
 Magnetic Chip Conveyors Market | 2026-2036
Magnetic Chip Conveyors Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Chip Conveyors Market Insights
Market Context
Aerospace machining demand is decoupling from general manufacturing trends as titanium and Inconel chip volumes surge. Eriez leverages permanent magnet technology leadership to anchor North American foundry relationships. MAYFRAN International sustains European automotive OEM contracts through application engineering depth. Storch Magnetics competes on quick-turn custom configurations for mid-tier job shops.
Technical Definition and Segment Structure
Magnetic chip conveyors are material handling systems that use magnetic force to transport ferrous metal chips, sludge, and scrap from machine tools to collection containers, typically operating with conveyor speeds of 5-30 meters per minute and magnetic field strengths calibrated to chip size and coolant viscosity. Drag chain conveyors dominate heavy-chip metalworking installations where cast iron and steel volumes stress belt alternatives. Permanent magnet technology leads installed base economics, though hybrid systems are gaining share where variable ferrous loads require active field modulation. Belt conveyors occupy the replacement-intensive food processing niche, where sanitary standards and magnet-compatible stainless specifications create distinct margin pools.
Regulatory Frame and Outlook
OSHA metalworking fluid exposure limits and EU machinery directive CE marking requirements shape conveyor guarding and coolant containment specifications. EPA hazardous waste generator rules and REACH substance restrictions influence chip disposal pathway design, pushing integrated filtration-conveyor bundling. Stakeholders must monitor how dual carbon goals in China's MIIT planning and Germany's KBA automotive production standards redirect capital toward energy-efficient electromagnetic drive retrofits versus full system replacement.
Market Dynamics
OSHA metalworking fluid exposure limits and EU machinery directive CE marking requirements are forcing capital-intensive retrofits of legacy chip handling infrastructure across precision manufacturing facilities.
Growth Catalysts
- Aerospace Production Expansion:Titanium and Inconel machining volumes in commercial aviation supply chains are pulling automated chip removal systems into high-value production lines where manual handling creates unacceptable contamination risk.
- REACH Substance Restrictions:ECHA regulations on hazardous metalworking fluid constituents are bundling filtration and conveyor investments as integrated compliance solutions rather than standalone equipment purchases.
- Germany's Precision Manufacturing Belt:Automotive OEMs and tool shops in Baden-Württemberg and Bavaria are specifying premium conveyor configurations that exceed baseline CE requirements, creating specification uplift across European supply chains.
Market Restraints
- Neodymium Price Volatility:Permanent magnet conveyor manufacturers face margin compression from rare earth element supply concentration in Chinese processing facilities.
- Electromagnetic Drive Energy Costs:Variable field systems carry operating cost penalties that disadvantage them against mechanical alternatives in energy-intensive continuous-run environments.
- Stainless Steel Specification Conflicts:Food processing belt conveyors require magnet-compatible grades that trade off corrosion resistance, limiting service life in aggressive washdown regimes.
Strategic Opportunities
- India's PLI Manufacturing Incentives:Production-linked incentive schemes for machine tools and auto components are creating first-mover advantage for conveyor suppliers establishing local assembly presence.
- Dual Carbon Goals in China:MIIT planning directives are redirecting state-owned enterprise capital toward energy-efficient electromagnetic retrofits versus full system replacement, opening upgrade service markets.
- Hybrid Magnetic-Mechanical Convergence:Systems combining permanent magnet base fields with active modulation for variable ferrous loads are capturing mid-market customers between pure permanent and full electromagnetic price points.
Industry Challenges
- Mechatronics Skill Scarcity:Conveyor maintenance organizations lack technicians trained in both magnetic field calibration and PLC-driven conveyor control integration.
- CE Marking Documentation Burden:EU machinery directive conformity assessment timelines extend 8-14 months for custom-engineered configurations, compressing project delivery windows.
- Legacy Coolant System Interface Complexity:Retrofit installations must reconcile modern conveyor controls with existing machine tool PLC architectures from multiple generations.
Report Scope
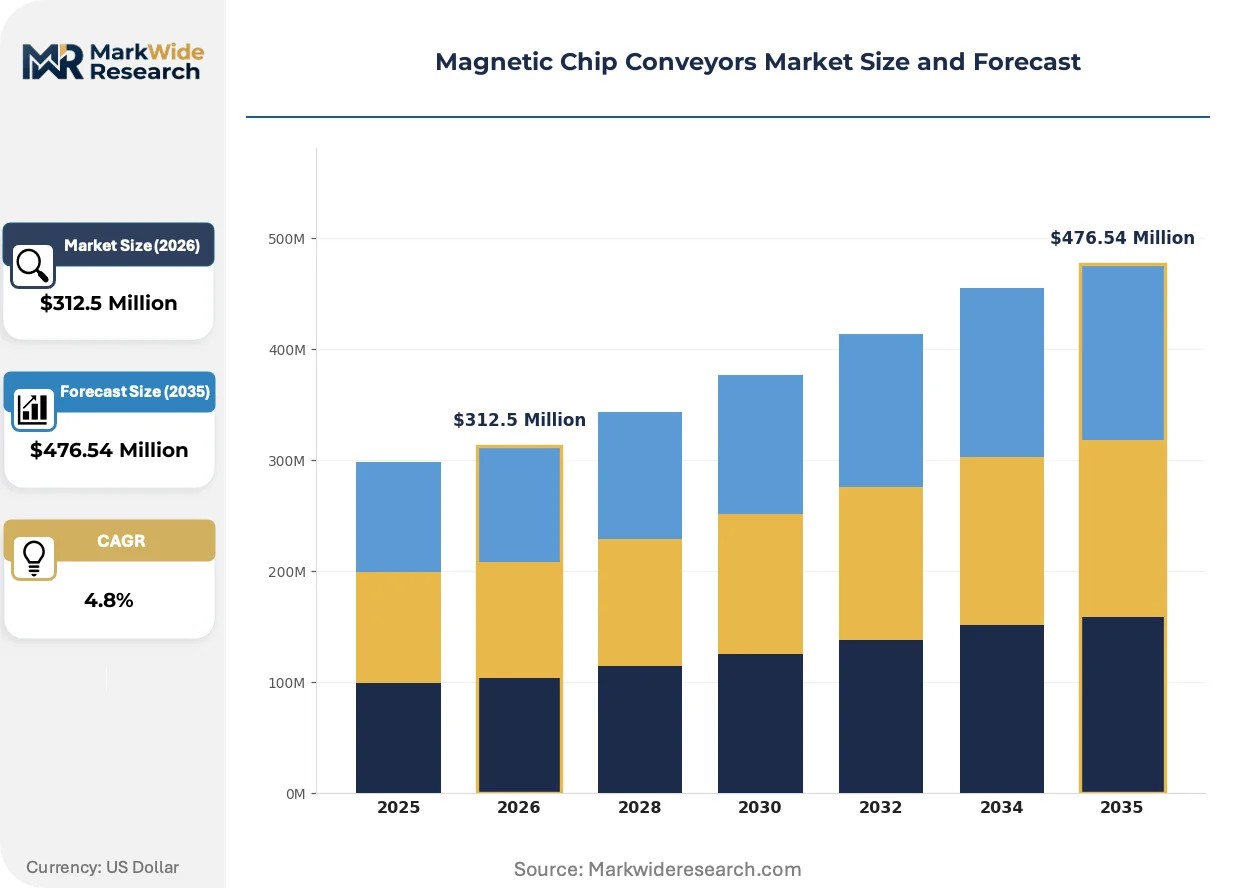
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Chip Conveyors Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Overhead Conveyors, Drag Chain Conveyors, Belt Conveyors, Roller Conveyors Application: Metalworking, Plastic Processing, Recycling, Food Processing End User: Aerospace, Automotive OEMs, Electronics, Manufacturing Technology: Electromagnetic, Permanent Magnet, Hybrid Systems, Automation |
| Companies Covered | Sollau, Tyler Machine & Foundry, Eriez, Schrage Conveying Systems, MAYFRAN International, Storch Magnetics, Bunting Magnetics, Magnetic Transfer Systems, PRAB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Chip Conveyors Market Trends and Innovations
Active field modulation technology is consolidating competitive position in applications where chip load variability previously forced oversizing of permanent magnet systems.
Permanent magnet arrays with embedded Hall-effect sensors are consolidating real-time flux density monitoring into standard conveyor configurations. German automotive tier-one suppliers are specifying these systems for lights-out machining cells where field degradation would trigger unplanned downtime. The technology is consolidating maintenance intervals from calendar-based to condition-based regimes, compressing total cost of ownership calculations against electromagnetic alternatives.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-based coolant system replacements that alter chip temperature profiles and magnetic susceptibility. Metalworking facilities must recalibrate conveyor magnetic field strength specifications to accommodate higher-temperature synthetic coolants. European precision component manufacturers are responding by bundling thermal management and chip handling specifications in single vendor procurement packages.
Buyer consolidation among contract manufacturers is compressing specification diversity and favoring suppliers with configurable platform architectures. Large-scale machining job shops in the US Midwest are standardizing on single conveyor families across multiple machine tool brands to simplify spare parts logistics and technician training. This concentration is visible most acutely in Illinois and Ohio metalworking clusters where private equity roll-ups have created multi-facility procurement leverage.
Magnetic Chip Conveyors Market Segmentation
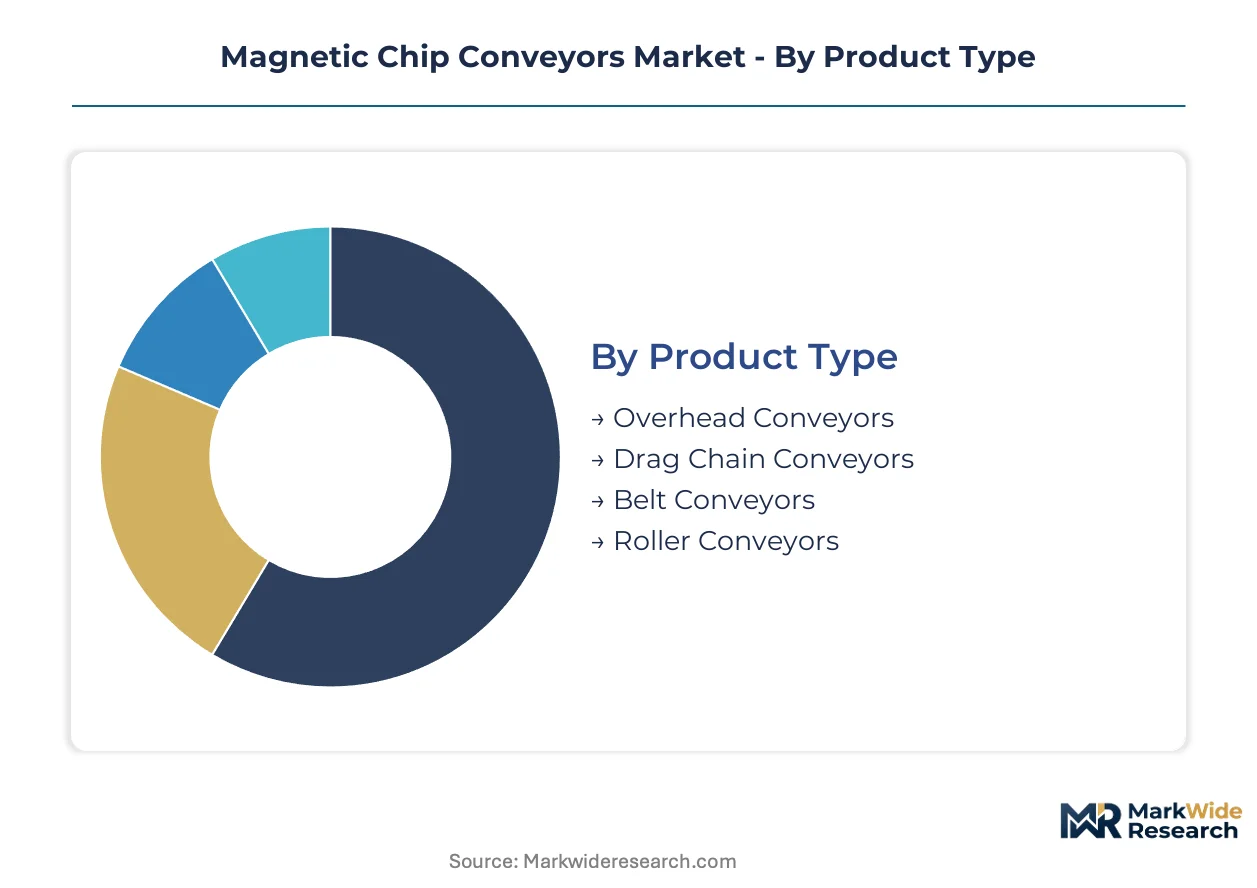
Segmentation in magnetic chip conveyors reveals how upgrade cycles diverge across equipment types and end-use environments. Replacement timing varies dramatically between heavy-chip metalworking installations and precision aerospace cells, reshaping vendor account management priorities.
Product Type:
Upgrade cycles for magnetic chip conveyors stretch from 8 years in standard metalworking to 15 years in precision installations, creating staggered replacement windows that favor suppliers with broad product portfolios.
- Drag Chain Conveyors:Heavy-duty chain-and-flight mechanisms handle cast iron and steel chip volumes that destroy belt alternatives. German automotive OEMs in Baden-Württemberg specify these for transfer line applications where coolant immersion and abrasive loads demand hardened construction.
- Belt Conveyors:Continuous magnetic belts transport ferrous chips across horizontal runs with minimal elevation change. Food processing facilities in Illinois and Ohio metalworking clusters favor stainless steel specifications that trade corrosion resistance for magnet compatibility under aggressive washdown regimes.
- Overhead Conveyors:Ceiling-mounted systems free floor space in congested machine shops.
- Roller Conveyors:Powered roller beds handle palletized chip containers in high-volume foundry operations.
Drag Chain Conveyors sits at the top of the volume ranking, with Belt Conveyors climbing the fastest.
Application:
Application-driven segmentation exposes how coolant chemistry and chip morphology dictate magnetic field calibration requirements across process environments.
- Metalworking:Ferrous chip removal from CNC machining centers, grinding operations, and turning cells dominates installed base economics. REACH substance restrictions on metalworking fluid constituents are bundling filtration and conveyor investments as integrated compliance solutions in European precision component manufacturing.
- Recycling:Scrap metal sorting and shredder feed applications recover ferrous fractions from mixed waste streams. China's MIIT dual carbon goals are redirecting state-owned enterprise capital toward energy-efficient electromagnetic retrofits in scrap processing yards.
- Plastic Processing:Magnetic metal detection protects injection molding equipment from tramp ferrous contamination.
- Food Processing:Sanitary-grade magnetic conveyors remove metal fragments from product streams.
Metalworking commands the largest installed base, while Recycling gains share fastest as circular economy mandates intensify.
End User:
End-user concentration determines specification complexity, with aerospace and automotive OEMs driving premium configurations that exceed baseline compliance requirements.
- Automotive OEMs:High-volume production lines demand continuous-duty conveyors with redundant drive systems. Tier-one suppliers in Bavaria specify permanent magnet arrays with embedded Hall-effect sensors for lights-out machining cells where field degradation would trigger unplanned downtime.
- Aerospace:Titanium and Inconel machining generates chips with distinct magnetic susceptibility profiles. Commercial aviation supply chains in the US Midwest are pulling automated chip removal systems into high-value production lines where manual handling creates unacceptable contamination risk.
- Manufacturing:General industrial machine shops represent the price-sensitive mid-market.
- Electronics:Precision component fabrication requires miniature chip handling with minimal particle generation.
Automotive OEMs anchor volume demand, with Aerospace expanding most quickly on commercial aviation production ramp-ups.
Technology:
Technology segmentation tracks the shift from fixed-field permanent magnet systems toward active modulation architectures that adapt to variable ferrous loads.
- Permanent Magnet:Fixed-field systems using neodymium or ferrite arrays dominate installed base economics. OSHA metalworking fluid exposure limits are forcing capital-intensive retrofits of legacy permanent magnet infrastructure across US precision manufacturing facilities.
- Hybrid Systems:Combined permanent magnet base fields with active modulation capture mid-market customers between pure permanent and full electromagnetic price points. These configurations are consolidating competitive position in applications where chip load variability previously forced oversizing of permanent magnet systems.
- Electromagnetic:Variable field strength systems accommodate non-ferrous and mixed-metal chip streams.
- Automation:PLC-integrated conveyors with remote monitoring and predictive maintenance capabilities.
Permanent Magnet retains the largest installed base, while Hybrid Systems show the steepest expansion trajectory as mechatronics costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between OSHA-mandated retrofits in the United States and baseline CE requirements in Eastern Europe are redirecting precision manufacturing investment toward Poland and Czechia. Germany's KBA automotive standards and China's MIIT dual carbon directives create additional arbitrage opportunities for conveyor suppliers with modular certification packages.
United States
Aerospace machining clusters in Illinois and Ohio are automating chip removal for titanium and Inconel production lines. OSHA metalworking fluid exposure limits are forcing capital-intensive retrofits across legacy permanent magnet infrastructure. Tier-one suppliers in the US Midwest are standardizing on single conveyor families to simplify spare parts logistics after private equity roll-ups.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria specify premium conveyor configurations exceeding baseline CE machinery directive requirements. ECHA REACH substance restrictions on hazardous metalworking fluid constituents are bundling filtration and conveyor investments as integrated compliance solutions. KBA production standards for energy-efficient manufacturing are accelerating electromagnetic drive retrofits in precision component facilities.
China
State-owned enterprise capital is redirecting toward energy-efficient electromagnetic retrofits under MIIT dual carbon planning directives. Scrap processing yards in the Yangtze River Delta are upgrading magnetic separation infrastructure to meet circular economy mandates. GB standards for machine tool safety are tightening guarding and coolant containment specifications for new installations.
India
Production-linked incentive schemes for machine tools and auto components are creating first-mover advantage for conveyor suppliers establishing local assembly presence. BIS certification requirements for industrial machinery are extending conformity assessment timelines for imported equipment. Tamil Nadu and Maharashtra automotive clusters are specifying automated chip handling for new CNC machining investments.
Japan
Precision component manufacturers in the Chubu region around Nagoya are adopting Hall-effect sensor arrays for lights-out machining cells. METI energy efficiency standards are favoring permanent magnet systems over electromagnetic alternatives in continuous-run environments. JIS machinery safety standards are harmonizing with EU machinery directives for export-oriented tier-one suppliers.
Magnetic Chip Conveyors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium aerospace applications favoring application-engineered solutions while mid-tier job shops prioritize quick-turn customization. The vendor base organizes around three archetypes: permanent magnet technology leaders, hybrid system integrators, and electromagnetic retrofit specialists. Strategic moves concentrate on geographic expansion through local assembly partnerships and technology licensing agreements that bypass lengthy CE conformity assessments.
Among North American magnetic technology specialists, Eriez and Storch Magnetics exemplify contrasting positioning archetypes. Eriez occupies a position anchored in foundry and heavy metalworking relationships through permanent magnet technology depth. Storch Magnetics sits within the quick-turn customization tier serving mid-tier job shops with configurable platform architectures. MAYFRAN International represents the European application engineering model, sustaining automotive OEM contracts through specification leadership in high-volume production environments.
| Leading Market Players |
|---|
| Sollau |
| Tyler Machine & Foundry |
| Eriez |
| Schrage Conveying Systems |
| MAYFRAN International |
| Storch Magnetics |
| Bunting Magnetics |
| Magnetic Transfer Systems |
| PRAB |
| Others |
Pricing and Supply Chain Analysis
Mechatronics technician scarcity in Germany's precision manufacturing belt widens labor-cost differentials that propagate into three-tier pricing spreads separating premium Hall-effect sensor configurations from economy permanent magnet systems.
Pricing Analysis
Distributor margins of 15-25% separate OEM direct pricing from job shop procurement through industrial supply houses. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—CE-plus-KBA compliance commands 30-40% uplifts over baseline machinery directive configurations. Pricing pressure stems from neodymium price volatility concentrated in Chinese processing facilities. Tier-one automotive suppliers show lowest price sensitivity; mid-tier job shops in Illinois and Ohio metalworking clusters negotiate aggressively on spare parts bundling.
Supply Chain Analysis
Neodymium magnet supply rests on Chinese rare earth element processing concentration, with secondary sourcing from Japanese and German specialty magnet producers. Permanent magnet arrays, Hall-effect sensors, and hardened drag chain assemblies constitute critical component dependencies. Single-source vulnerability in Chinese rare earth processing creates tariff exposure and supply interruption risk. Distribution runs through regional industrial equipment distributors with application engineering capabilities, supplemented by direct OEM relationships for high-volume automotive contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a late-cycle quality story as aerospace production lines demand premium automated chip removal systems that eliminate contamination risk in titanium and Inconel machining.
For Market Incumbents: To counter hybrid system integrators capturing mid-market share between permanent magnet and electromagnetic price points, deepen application engineering presence in Baden-Württemberg automotive clusters and accelerate Hall-effect sensor standardization across platform architectures. Certification investment in dual CE-KBA compliance creates specification lock-in against lower-tier competitors.
For New Entrants and Emerging Players: The 25-35% price-point gap between premium German-engineered systems and economy Chinese imports opens white-space targeting in India's PLI-funded Tamil Nadu and Maharashtra automotive clusters. Establish local assembly partnerships to bypass BIS certification delays on imported equipment. Pursue quick-turn customization for mid-tier job shops as the go-to-market angle.
For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, seeking conveyor specialists with embedded sensor IP and automotive OEM relationships. Long-term viability centers on hybrid magnetic-mechanical convergence as the dominant technology trajectory. Watch for MIIT dual carbon directive acceleration in China as the inflection signal indicating electromagnetic retrofit service market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Hall-Effect Sensor Integration | Embedded flux monitoring shifts maintenance from calendar-based to condition-based regimes in lights-out machining cells. |
| Local Assembly Partnerships | India PLI scheme compliance requires domestic manufacturing presence to capture auto component machining demand. |
| Dual Certification Bundling | Combined CE machinery directive and KBA automotive standards create specification barriers against unbundled competitors. |
| Hybrid System Development | Active modulation plus permanent magnet base fields capture mid-market customers with variable ferrous loads. |
| Electromagnetic Retrofit Services | MIIT dual carbon goals redirect Chinese SOE capital toward energy-efficient upgrades versus full replacement. |
Research Methodology
Bottom-up metalworking facility modeling reconciled against top-down magnetic equipment shipment tracking forms the analytical core of this study. Primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads combined with secondary validation against customs records, SEC machinery manufacturer filings, and automotive production databases. Triangulation across stakeholder inputs and trade data ensures cross-verification of installation counts and replacement timing.
Historical trendline analysis of upgrade cycles spanning standard metalworking to precision aerospace installations informs the projection framework. Segmentation dimensions include product type, application environment, technology architecture, and end-user concentration across the analysis window. CAGRs derive from equipment replacement velocity, regulatory compliance deadlines, and capital expenditure patterns in named manufacturing clusters. Aerospace production ramp-ups and REACH substance restriction implementation timelines serve as industry-specific forecast inputs.
Caveats apply where neodymium price volatility, CE marking documentation delays, or mechatronics skill scarcity could materially shift the outlook. Forecasts reflect assumptions regarding regulatory enforcement consistency and automotive OEM capital commitment continuity. A small set of named triggers—MIIT dual carbon acceleration, ECHA substance list expansion, and PLI scheme renewal—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Sorter Machines Market
Industrial Equipment
Precision Dispensing Accessories Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Europe Fusion Splicer Market
Industrial Equipment
Long-Range Acoustic Device Market
Industrial Equipment
Asia Pacific Industrial Embedded Systems Market
Industrial Equipment
Screw Air End Market
Industrial Equipment
PCB Punching Machine Market
Industrial Equipment
Laser Ablation Systems Market
Industrial Equipment
Roller Bearings Market
Industrial Equipment
Global Ultrasonic Cleaning Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
Press-Insertion Systems Market
Industrial Equipment
Ultrasonic Cleaning Equipment Market
Industrial Equipment
Femtosecond Fiber Lasers Market
Industrial Equipment
Automatic Laser Welding Machine Market