
 Asia-Pacific Utilities Asset Management Market | 2026-2036
Asia-Pacific Utilities Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Utilities Asset Management Market Insights
Enterprise-grade predictive analytics is bifurcating the Asia-Pacific utilities asset management landscape into premium platforms and modular point solutions. Siemens AG leverages its digital grid software stack to anchor large-scale transmission operator contracts across Australia and Japan. ABB Group competes through its Ability platform, which specializes in real-time asset health monitoring for hydroelectric and thermal generation fleets. IBM Corporation differentiates via Watson-based optimization engines that sustain multi-utility deployments across South Korea and Singapore.
Asia-Pacific utilities asset management encompasses integrated software platforms, sensor networks, and lifecycle services that monitor, diagnose, and optimize physical infrastructure across generation, transmission, and distribution systems. Core technical specifications include SCADA interoperability, MTBF modeling algorithms, and GIS-tagged asset registries that enable condition-based maintenance scheduling for transformers, pipelines, and turbine assemblies. Software Solutions and Cloud Solutions command the primary margin pools as utilities shift from perpetual licenses to subscription architectures, while Managed Services represents the fastest-expanding segment as operators outsource predictive analytics to vendors with dedicated data science teams. On-Premises deployments still dominate in Japan and China due to cybersecurity protocols, though Hybrid models are gaining share where regulators permit partitioned data residency.
Japan's METI enforces stringent grid resilience standards that mandate real-time asset monitoring for utilities above 1 GW capacity, while Australia's AEMO integrates NEM-wide asset performance benchmarks into network access agreements. India's CEA mandates centralized asset registries under its Smart Grid roadmap, creating compliance-driven demand for standardized data platforms. Stakeholders must weigh sovereign data requirements against cloud economics as ASEAN regulators draft cross-border energy data protocols.
Market Dynamics
Digital twin deployments are compressing maintenance cycles across Asia-Pacific transmission networks as utilities replace calendar-based inspections with continuous physics-based simulations. This shift demands real-time sensor integration and cloud-native analytics stacks that legacy SCADA architectures cannot support.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for power sector modernization accelerate procurement of predictive maintenance platforms by state transmission utilities replacing aging transformer fleets.
- Hydroelectric fleet monitoring:Real-time asset health systems for turbine assemblies and penstock infrastructure expand as operators face reservoir volatility from climate-driven precipitation shifts.
- Japan's METI resilience mandates:Grid operators above 1 GW capacity must deploy continuous asset monitoring, creating compliance-driven demand for integrated SCADA-interoperable platforms.
Market Restraints
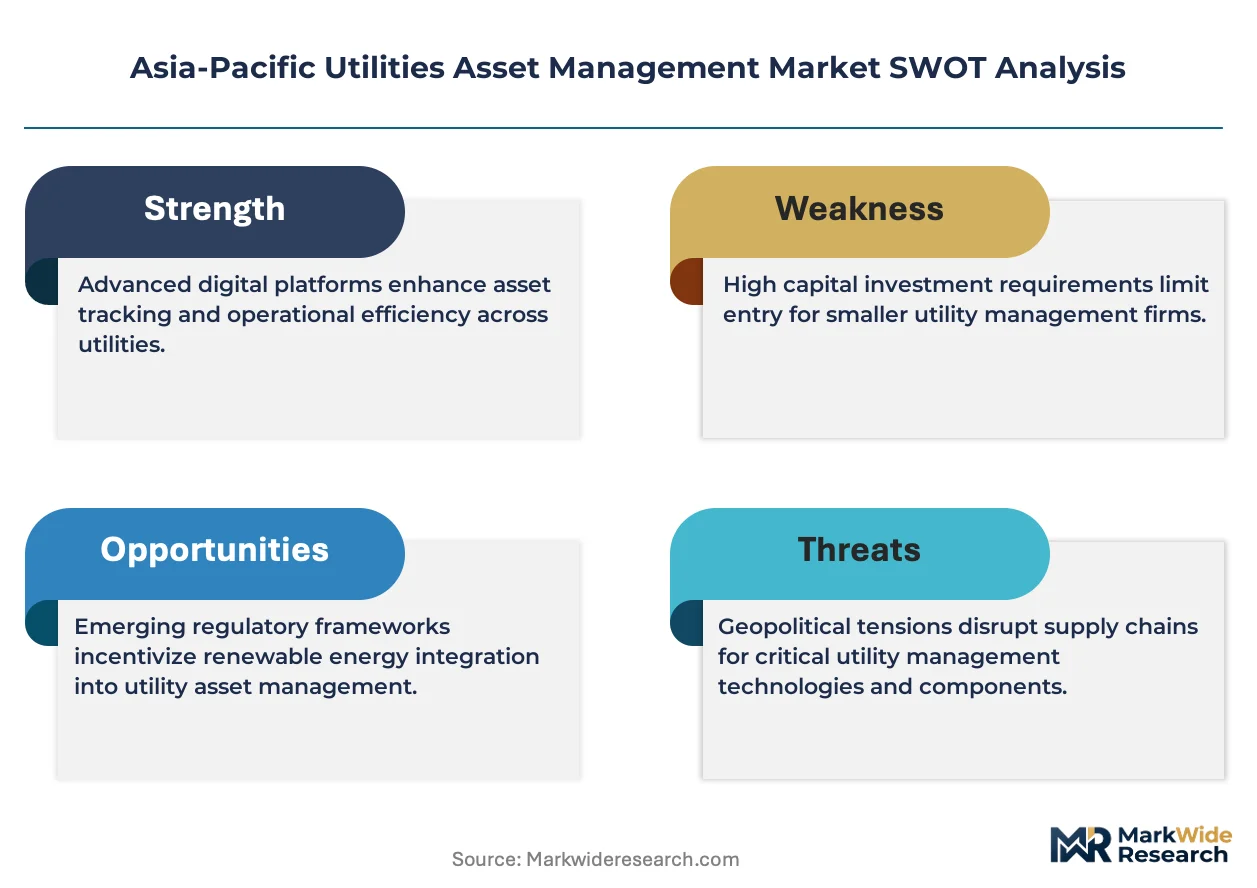
- Semiconductor supply concentration:Industrial-grade sensor chip procurement depends on concentrated East Asian foundry capacity, exposing deployment timelines to foundry allocation volatility.
- On-premises data residency requirements:China's cybersecurity protocols and Japan's critical infrastructure classifications block pure-cloud architectures, forcing costly hybrid infrastructure builds.
- Technical debt in legacy GIS systems:Decades-old asset registries lack standardized tagging schemas, requiring expensive data cleansing before predictive analytics deployment.
Strategic Opportunities
- ASEAN cross-border data protocols:Draft regional energy data sharing frameworks will enable centralized asset performance benchmarking across interconnected Southeast Asian grids.
- Offshore wind integration:Subsea cable monitoring and floating platform predictive maintenance represent white-space applications with limited incumbent vendor presence.
- Australia's renewable integration mandates:AEMO's network access agreements incorporating asset performance benchmarks create procurement pull for real-time condition monitoring systems.
Industry Challenges
- SCADA integration complexity:Multi-vendor protocol fragmentation forces custom middleware development for each deployment, extending implementation timelines.
- Data science talent scarcity:Utilities lack in-house capabilities for MTBF model calibration and anomaly detection algorithm tuning, creating dependency on vendor professional services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Utilities Asset Management Market |
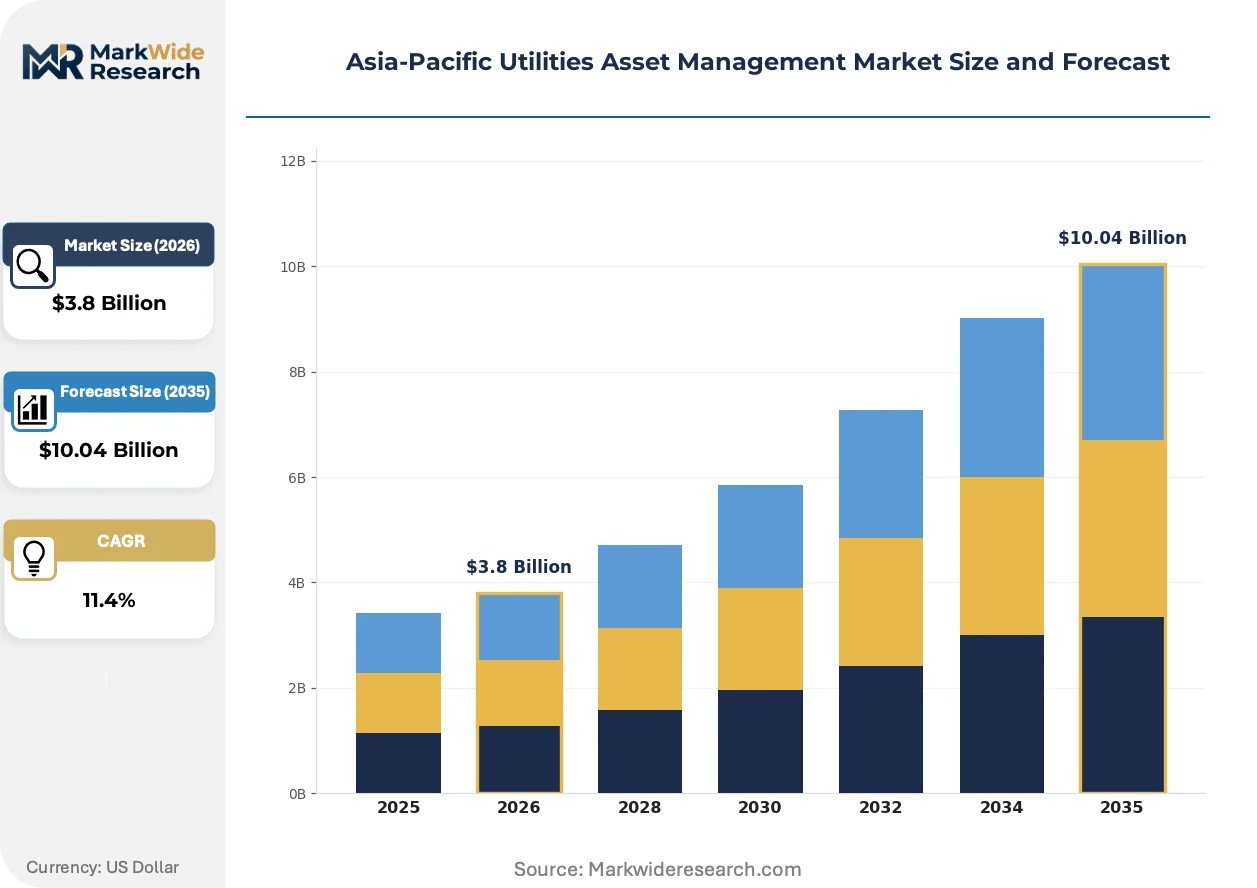
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Consulting Services, Managed Services, Cloud Solutions Deployment Model: On-Premises, Hybrid, Public Cloud, Private Cloud End User: Electric Utilities, Water Utilities, Gas Utilities, Renewable Energy Companies Service Type: Maintenance Services, Optimization Services, Risk Management Services, Performance Analytics |
| Companies Covered | Siemens AG, ABB Group, Schneider Electric SE, GE Vernova, Hitachi Energy, Eaton Corporation, IBM Corporation, Fujitsu Limited, IFS AB, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Utilities Asset Management Market Trends and Innovations
Physics-informed machine learning is merging first-principles engineering models with operational data streams, enabling failure prediction horizons that exceed purely statistical approaches. This convergence is reshaping how transmission operators prioritize capital replacement schedules.
Digital twin platforms are supplanting traditional asset management software by embedding finite element analysis directly into operational dashboards. Australian and Japanese transmission operators now require physics-based simulation layers for transformer thermal modeling and switchgear electromechanical stress analysis. This capability compression forces legacy CMMS vendors to acquire or partner for multiphysics simulation expertise.
Australia's AEMO has integrated NEM-wide asset performance benchmarks into network access agreements, binding generator and transmission reliability metrics to market participation rights. This regulatory architecture shifts procurement criteria from feature checklists to demonstrated predictive accuracy in live grid conditions. Hydroelectric and thermal fleet operators face the steepest compliance curves under these performance-linked access rules.
Subscription pricing for cloud-native asset platforms is displacing perpetual license models as utilities seek to convert capex commitments into operational expenditure streams aligned with regulatory rate-case cycles. Indian state utilities and Australian municipal distributors lead this shift, though Japanese operators remain constrained by capital structure preferences embedded in regional regulatory frameworks. The transition pressures on-premises dominant vendors to develop partitioned data residency architectures that satisfy cybersecurity requirements while capturing recurring revenue economics.
Asia-Pacific Utilities Asset Management Market Segmentation
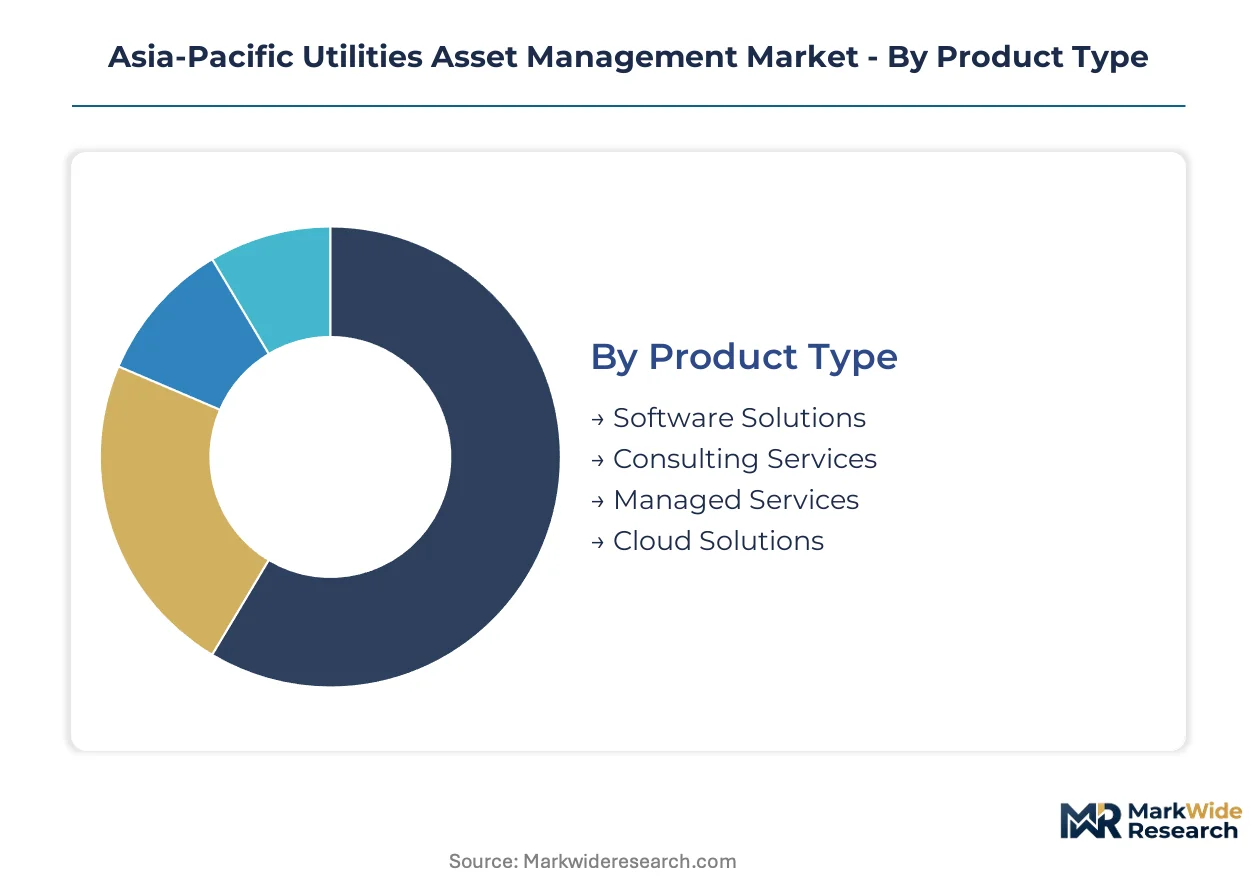
Segmentation in Asia-Pacific utilities asset management reveals how procurement patterns diverge between legacy infrastructure operators and digital-native entrants. Understanding these divides exposes where vendors must configure hybrid delivery models versus pure-cloud architectures.
Product Type:
Software Solutions and Cloud Solutions anchor procurement in Australia and Japan where transmission operators modernize at scale, while Consulting Services and Managed Services concentrate in India's state utility sector.
- Software Solutions:Integrated platforms embedding SCADA interoperability, MTBF modeling algorithms, and GIS-tagged asset registries enable condition-based maintenance scheduling for transformer fleets and turbine assemblies. Australian transmission operators and Japanese grid utilities above 1 GW capacity drive procurement through METI resilience mandates and AEMO performance benchmarks.
- Cloud Solutions:Subscription architectures convert capital expenditure into operational expenditure streams aligned with regulatory rate-case cycles. Indian state utilities and Australian municipal distributors lead adoption, though hybrid deployments prevail where data residency requirements block pure-cloud models.
- Consulting Services:Professional services for legacy GIS system migration and data cleansing precede predictive analytics deployment across Southeast Asian markets.
- Managed Services:Outsourced predictive analytics operations address data science talent scarcity, with dedicated vendor teams handling MTBF model calibration and anomaly detection tuning.
Software Solutions commands the established base. The steepest expansion runs through Managed Services.
Deployment Model:
Deployment preferences track regulatory posture: On-Premises and Private Cloud dominate where critical infrastructure classifications apply, while Hybrid and Public Cloud gain traction under permissive data governance frameworks.
- On-Premises:Air-gapped architectures satisfy Japan's critical infrastructure cybersecurity protocols and China's data sovereignty requirements. Operators accept higher capital intensity to maintain direct control over SCADA-interoperable asset registries and real-time monitoring systems.
- Hybrid:Partitioned data residency architectures separate sensitive operational technology data from analytics workloads, enabling recurring revenue economics for vendors while satisfying regulator-mandated data localization. ASEAN markets with draft cross-border energy data protocols show accelerating interest.
- Private Cloud:Single-tenant infrastructure delivers cloud scalability without multi-tenant security exposure, preferred by Japanese regional utilities and Australian transmission network service providers.
- Public Cloud:Native elasticity supports digital twin physics-based simulations requiring burst compute capacity, adopted where regulatory frameworks permit operational data offshore processing.
On-Premises retains the largest installed capacity. Hybrid deployments are climbing the fastest as regulators relax absolute data localization mandates.
End User:
Electric Utilities absorb the majority of platform investment, while Renewable Energy Companies represent the fastest-growing demand source as offshore wind and solar portfolios expand.
- Electric Utilities:Transmission and distribution operators deploy predictive maintenance platforms for aging transformer replacement, digital twin implementations for grid infrastructure, and real-time asset health monitoring mandated by capacity thresholds. India's state transmission utilities leverage PLI scheme incentives for fleet modernization.
- Renewable Energy Companies:Offshore wind developers require subsea cable monitoring and floating platform predictive maintenance capabilities with limited incumbent vendor presence. Solar and onshore wind operators integrate asset performance benchmarks into grid access negotiations.
- Water Utilities:Pipeline condition assessment and pump station optimization drive adoption of pressure transient monitoring and corrosion prediction algorithms.
- Gas Utilities:Compressor station reliability and distribution network integrity management utilize similar predictive analytics stacks adapted for pressure vessel and pipeline asset classes.
Electric Utilities commands the established base. Renewable Energy Companies shows the steepest expansion trajectory.
Service Type:
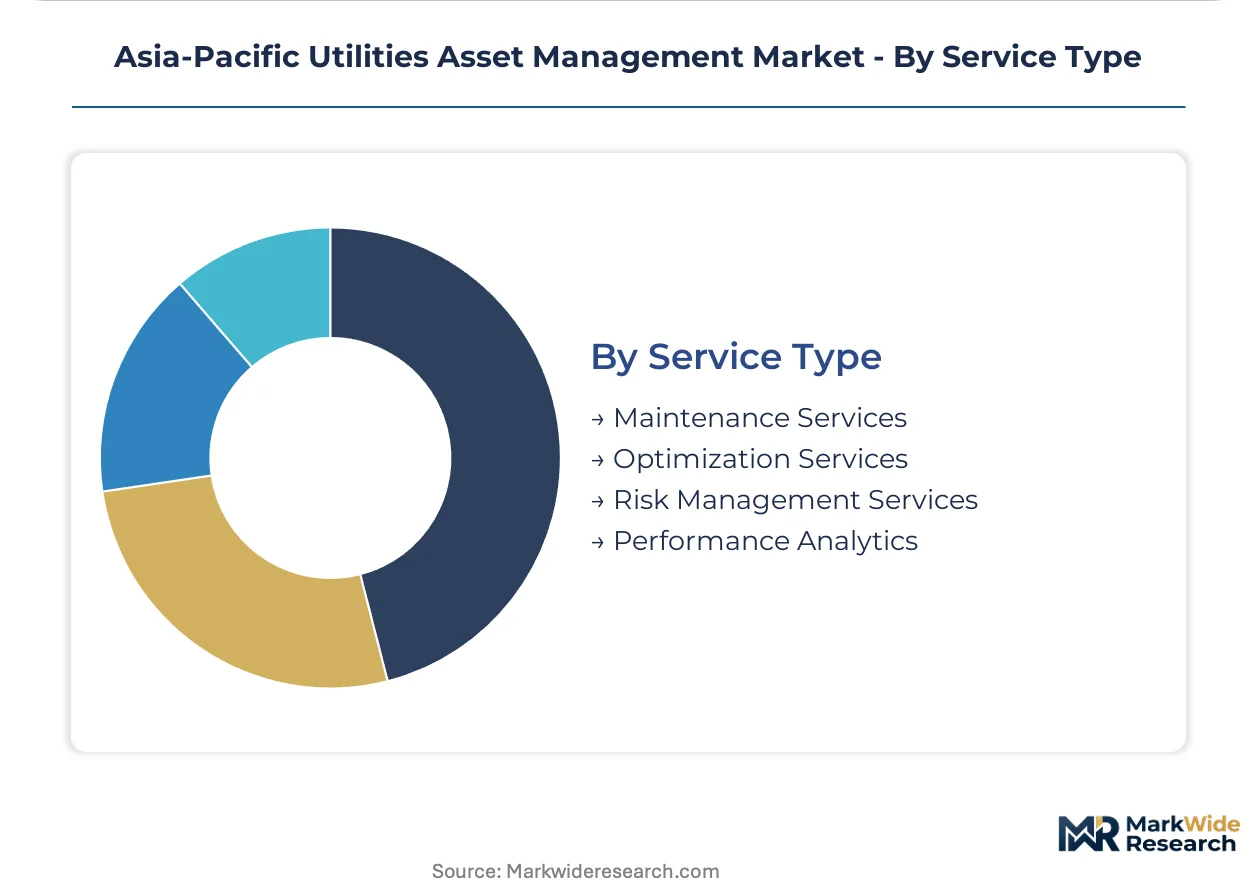
Service demand aligns with asset lifecycle stage: Maintenance Services dominate for aging infrastructure, while Performance Analytics accelerates for new digital twin deployments.
- Maintenance Services:Condition-based scheduling replaces calendar-based inspection regimes, requiring continuous sensor integration and physics-informed machine learning for failure prediction horizons exceeding statistical approaches. Australian and Japanese transmission operators mandate these capabilities for network access compliance.
- Performance Analytics:Real-time dashboards embedding finite element analysis for transformer thermal modeling and switchgear electromechanical stress analysis compress capital replacement decision cycles. This capability layer forces legacy CMMS vendors toward multiphysics simulation partnerships.
- Optimization Services:Capital prioritization algorithms balance reliability targets against budget constraints, deployed where regulatory frameworks permit outcome-based ratemaking.
- Risk Management Services:Climate-driven reservoir volatility and extreme weather exposure quantification supports hydroelectric and thermal fleet insurance and hedging strategies.
Maintenance Services commands the established base. Performance Analytics is gaining share fastest as physics-based simulation layers become procurement requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific utilities asset management trade flows reflect concentrated technology imports into India and Australia offset by Japan's domestic platform development. Regional procurement patterns diverge sharply between markets mandating data localization and those permitting cross-border cloud processing.
India
State transmission utilities drive procurement volumes through CEA-mandated centralized asset registries and PLI scheme incentives for transformer fleet modernization. The Smart Grid roadmap compels standardized data platform adoption across generation and distribution networks. Maharashtra and Gujarat host the densest deployment clusters where DISCOMs integrate predictive maintenance with renewable integration mandates.
Australia
AEMO's network access agreements binding asset performance benchmarks to market participation rights reshape procurement criteria for transmission operators. NEM-wide reliability metrics drive real-time condition monitoring adoption across New South Wales and Victoria. Sydney and Melbourne anchor the largest digital twin deployments for grid infrastructure physics-based simulation.
Japan
METI enforces stringent grid resilience standards mandating continuous asset monitoring for utilities above 1 GW capacity, creating compliance-driven demand for SCADA-interoperable platforms. Critical infrastructure cybersecurity protocols block pure-cloud architectures. The Kanto region around Tokyo concentrates the highest density of hybrid deployment infrastructure.
South Korea
Multi-utility predictive analytics deployments accelerate as operators seek optimization engines for generation fleet management. The country's national energy regulator mandates reliability reporting standards that favor integrated platform procurement. Seoul anchors concentrated demand for subscription-based cloud architectures where data residency requirements permit offshore processing.
Singapore
Urban grid digitization programs drive compact but high-value deployments of sensor-integrated asset management platforms. The city-state's permissive data governance framework enables public-cloud analytics stacks for regional utility headquarters operations. Singapore serves as a deployment testbed for ASEAN cross-border energy data protocol development.
Asia-Pacific Utilities Asset Management Market Competitive Landscape
Listed leaders compete with private specialists across platform architecture and delivery model dimensions. The vendor base organizes into three tiers: integrated industrial conglomerates with captive software stacks, pure-play asset management platform developers, and professional services firms with analytics capabilities. Strategic moves concentrate on hybrid cloud infrastructure partnerships and multiphysics simulation capability acquisition.
Within the integrated industrial tier, Siemens AG and ABB Group exemplify archetypes competing through end-to-end digital grid portfolios. IBM Corporation occupies a position representing analytics-first entrants competing via optimization engines rather than hardware-software integration. These three companies anchor competitive dynamics across the region's largest procurement markets.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Group |
| Schneider Electric SE |
| GE Vernova |
| Hitachi Energy |
| Eaton Corporation |
| IBM Corporation |
| Fujitsu Limited |
| IFS AB |
| Others |
Pricing and Supply Chain Analysis
Japan's METI critical infrastructure cybersecurity protocols gate both vendor qualification and price differentiation simultaneously, forcing hybrid architecture premiums while constraining pure-cloud discounting across Asia-Pacific procurement markets.
Pricing Analysis
Industrial OEM buyers anchor subscription-tiered pricing structures across Asia-Pacific utilities asset management platforms. Pricing stratifies across premium digital twin suites, standard predictive maintenance modules, and economy-tier point solutions differentiated by SCADA interoperability depth and physics-based simulation capability. Cost compression in standard tiers intensifies as Indian state utilities leverage PLI scheme procurement volumes for platform discounts. Municipal distributors in Australia exhibit highest price sensitivity due to rate-case cycle constraints, while Japanese transmission operators above 1 GW capacity show lowest sensitivity given METI compliance mandates.
Supply Chain Analysis
East Asian semiconductor foundry concentration creates chokepoint exposure for industrial-grade sensor chip procurement across predictive maintenance platform deployments. Manufacturing draws from Taiwan, South Korea, and Japan for MEMS sensors, FPGA processors, and edge computing modules essential to real-time asset monitoring systems. Single-source vulnerability in advanced node fabrication threatens deployment timelines for digital twin implementations requiring burst compute capacity. Distribution runs through authorized systems integrators with SCADA certification credentials, particularly concentrated in Sydney, Tokyo, and Singapore regional hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific utilities asset management functions as a service-attach opportunity where managed analytics subscriptions expand faster than perpetual software licenses across Indian and Australian procurement markets.
For Market Incumbents: Shield installed base relationships by embedding multiphysics simulation partnerships that close capability gaps against pure-play digital twin specialists. Accelerate hybrid cloud infrastructure certification to satisfy Japan's data residency requirements while capturing recurring revenue economics. Prioritize capacity addition in ASEAN regional hubs as cross-border energy data protocols mature.
For New Entrants and Emerging Players: IEC 61850 interoperability certification fast-tracks market access for SCADA-native platform entrants targeting Southeast Asian transmission operator procurement. White-space concentration sits with offshore wind subsea cable monitoring and floating platform predictive maintenance where incumbent vendor presence remains limited. Pursue direct engagement with Australian renewable developers facing AEMO asset performance benchmark compliance deadlines.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial software platforms lacking cloud-native architecture or physics-informed machine learning capabilities. Five-to-ten year viability hinges on recurring revenue mix and data science team depth rather than legacy license maintenance streams. Monitor PLI scheme disbursement velocity in India as inflection indicator for state utility procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Infrastructure Partnership | Enables METI-compliant data residency while capturing subscription economics for Japanese utilities. |
| Multiphysics Simulation Acquisition | Closes capability gaps against digital twin requirements in Australian AEMO benchmark compliance. |
| Managed Services Expansion | Addresses data science talent scarcity across Indian state transmission utility deployments. |
| ASEAN Regional Hub Establishment | Positions for cross-border energy data protocol ratification across Southeast Asian grids. |
| Offshore Wind Specialist Partnership | Captures subsea cable monitoring white space before incumbent platform vendors adapt. |
Research Methodology
Cross-validation between utility planning officer interviews and CEA Smart Grid roadmap documentation anchors the qualitative findings for Asia-Pacific market characterization. Primary fieldwork engaged transmission network service providers, state DISCOM procurement leads, renewable developer engineering heads, and systems integrator technical directors across India, Australia, Japan, and Singapore. Secondary validation drew from CEA centralized asset registry mandates, AEMO network access agreement filings, METI grid resilience standards publications, and ASEAN energy regulator draft protocol releases. Bottom-up deployment tracking and top-down infrastructure investment flow analysis triangulate market sizing.
Sensitivity analysis across deployment model adoption curves and PLI scheme incentive trajectories shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, deployment architecture, end-user category, and service layer complexity alongside regulatory framework cluster. CAGRs derive from installed base replacement cycles and greenfield digital twin penetration assumptions. Forecast inputs incorporate transformer fleet age profiles, hydroelectric reservoir volatility indices, and offshore wind pipeline development status.
Decision-makers should treat outputs as directional under sustained PLI scheme funding and METI mandate enforcement; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as ASEAN cross-border data protocol negotiations and semiconductor foundry allocation volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
India Mutual Fund Market
Asset Management
Canada Asset Management Market
Asset Management
Canada Pension Fund Market
Asset Management
Asset Management System Market
Asset Management
Equity Management Tool Market
Asset Management
Japan Asset Management Market
Asset Management
Asset and Wealth Management Market
Asset Management
Healthcare Asset Management Market
Asset Management
US Healthcare Assets Management Market
Asset Management
Global AI in Asset Management Market
Asset Management
Capital Expenditure Market
Asset Management
Fund Management Fee Market
Asset Management
Mutual Fund Assets Market
Asset Management
Global Infrastructure Asset Management Market
Asset Management
India Asset Management Market
Asset Management
Asset Optimization Solutions Market