
 UK Asset Management Market | 2026-2036
UK Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
UK Asset Management Market Analytics
Market Context
Wealth management firms as a distribution channel is reshaping how asset managers reach retail and high-net-worth clients across Britain. BlackRock Investment Management (UK) Limited leverages its scale in index investing to dominate institutional mandates. Legal & General Investment Management Limited anchors its competitive position through deep ties with UK pension funds. Schroders plc differentiates via active emerging market strategies that sustain premium fee structures.
Technical Definition and Segment Structure
Asset management encompasses the professional oversight of investment portfolios comprising equities, fixed income instruments, real estate holdings, and commodity exposures, governed by fiduciary standards and risk-return parameters tailored to client liabilities. The practice pools capital from disparate investors to achieve diversification, liquidity management, and targeted yield profiles that individual investors cannot replicate independently. Active management strategies command higher fee margins but face structural pressure from index investing, which captures the bulk of net inflows across British retail and institutional channels. Pension funds represent the most concentrated client type by assets under management, while online platforms represent the fastest-growing distribution channel as digital onboarding reduces intermediary costs.
Regulatory Framework and Outlook
The Financial Conduct Authority's Consumer Duty rules and the Bank of England's systemic risk oversight are tightening governance standards for product design, fee transparency, and suitability assessments across UK asset managers. FCA authorization requirements and the Senior Managers and Certification Regime shape market access by holding individual executives accountable for compliance failures. Stakeholders must monitor how evolving ESG disclosure rules and potential defined-benefit pension scheme consolidation will redistribute asset flows among active and passive strategies.
Market Dynamics
The UK Asset Management Market is experiencing structural pressure from the FCA's Consumer Duty rules, which mandate stricter product governance and fee transparency standards across all retail-facing strategies. This regulatory tightening is forcing active managers to justify premium pricing while passive vehicles capture accelerating inflows.
Growth Catalysts
- Defined-benefit pension consolidation:The UK Pensions Regulator's push for scheme mergers is concentrating assets into fewer, larger mandates that favor sophisticated liability-driven investment capabilities.
- ESG integration mandates:Institutional investors now require climate risk disclosure across portfolios, creating demand for carbon accounting infrastructure and transition-themed strategies.
- Wealth platform digitization:Online distribution channels are reducing onboarding friction and expanding retail access to previously institutional-only fund structures.
Market Restraints
- Fee compression mechanics:Index-tracking vehicles have driven management fees toward marginal cost, squeezing revenue per basis point of assets under management.
- London employment concentration:Talent and operational infrastructure cluster in the capital, creating geographic vulnerability and elevated compensation costs.
- Active performance drag:Persistent underperformance versus benchmarks across UK equity strategies has eroded credibility and client retention.
Strategic Opportunities
- Private market access vehicles:Regulatory reforms permitting long-term asset funds are opening retail distribution for private equity and infrastructure exposure.
- Scotland's fund servicing cluster:Edinburgh and Glasgow offer lower-cost operational bases with established custody and administration ecosystems.
- AI-driven personalization:Machine learning tools are enabling mass-customization of portfolio construction at unit economics previously reserved for ultra-high-net-worth segments.
Industry Challenges
- Legacy technology integration:Core banking systems from the 1990s resist API connectivity with modern portfolio management platforms, delaying real-time reporting.
- Suitability documentation burden:The Senior Managers and Certification Regime requires granular accountability trails for every investment recommendation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Asset Management Market |
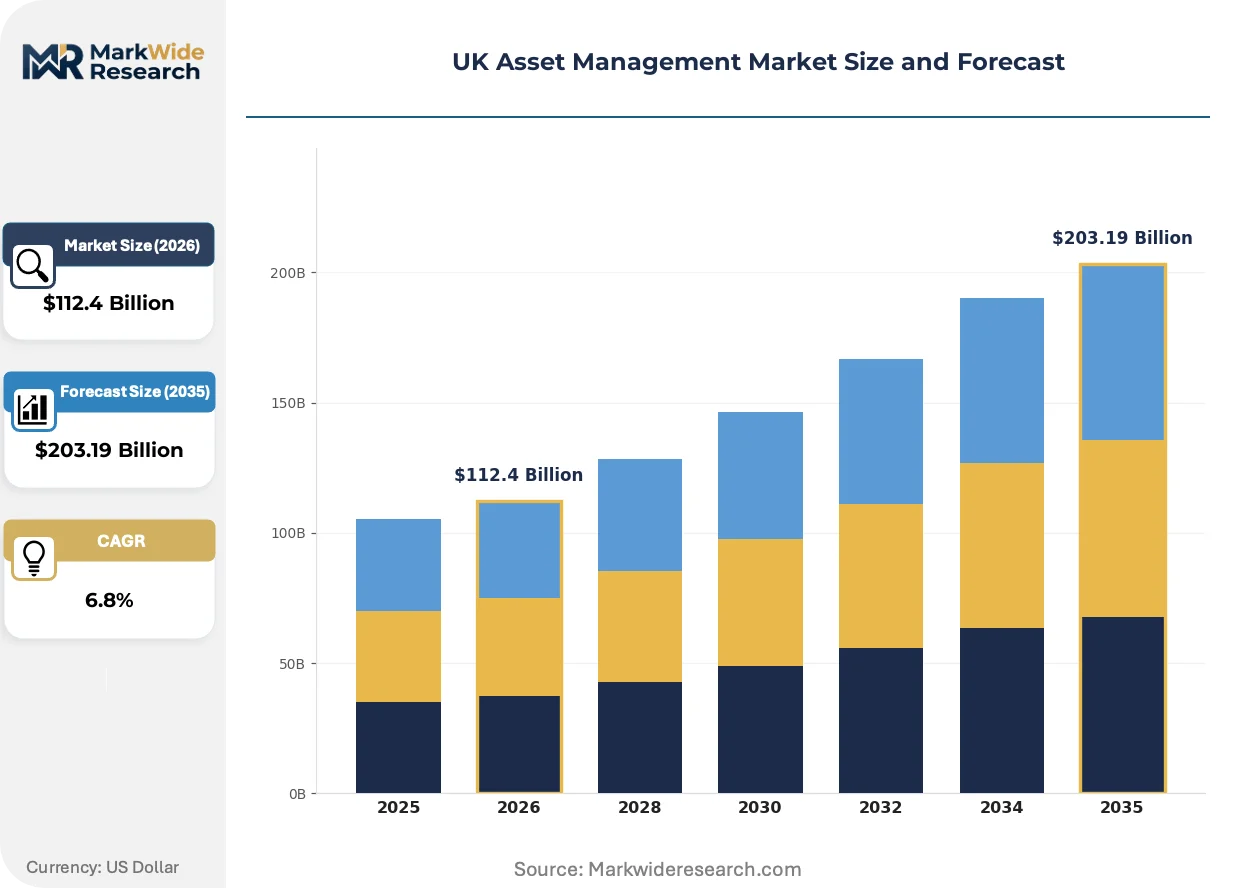
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $203.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Strategy: Value Investing, Growth Investing, Index Investing, Active Management Asset Class: Equities, Fixed Income, Real Estate, Commodities Client Type: Institutional Investors, High-Net-Worth Individuals, Retail Investors, Pension Funds Distribution Channel: Direct Sales, Third-Party Advisors, Online Platforms, Wealth Management Firms |
| Companies Covered | BlackRock Investment Management (UK) Limited, Legal & General Investment Management Limited, Schroders plc, Abrdn plc, M&G plc, St James's Place, Rathbones Group plc, Evelyn Partners, Quilter plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Asset Management Market Evolving Landscape
Digital infrastructure is virtualizing distribution relationships and compressing the traditional intermediary chain between asset managers and end investors. Three developments are reshaping competitive positioning.
Cloud-native portfolio accounting systems are virtualizing back-office functions that previously required on-premise mainframe installations. Mid-tier asset managers in Manchester and Birmingham are adopting these platforms faster than London incumbents, enabling operational parity without equivalent fixed-cost bases. The technology is virtualizing scale advantages that historically protected larger competitors.
The FCA's Consumer Duty implementation deadline has triggered wholesale redesign of product governance frameworks across UK-authorized firms. Disclosure requirements now mandate total cost quantification and value-for-money assessments that favor transparent, simple structures over complex, opaque vehicles. Defined-contribution pension schemes are responding by stripping out high-fee share classes and consolidating fund ranges.
Direct indexing platforms are fragmenting the traditional mutual fund wrapper by permitting customized benchmark replication at the individual security level. Wealth managers in the Southeast are deploying these tools to harvest tax losses and implement personalized exclusion screens. The behavior is most pronounced among inherited-wealth clients seeking granular control over environmental and ethical preferences.
UK Asset Management Market Segmentation
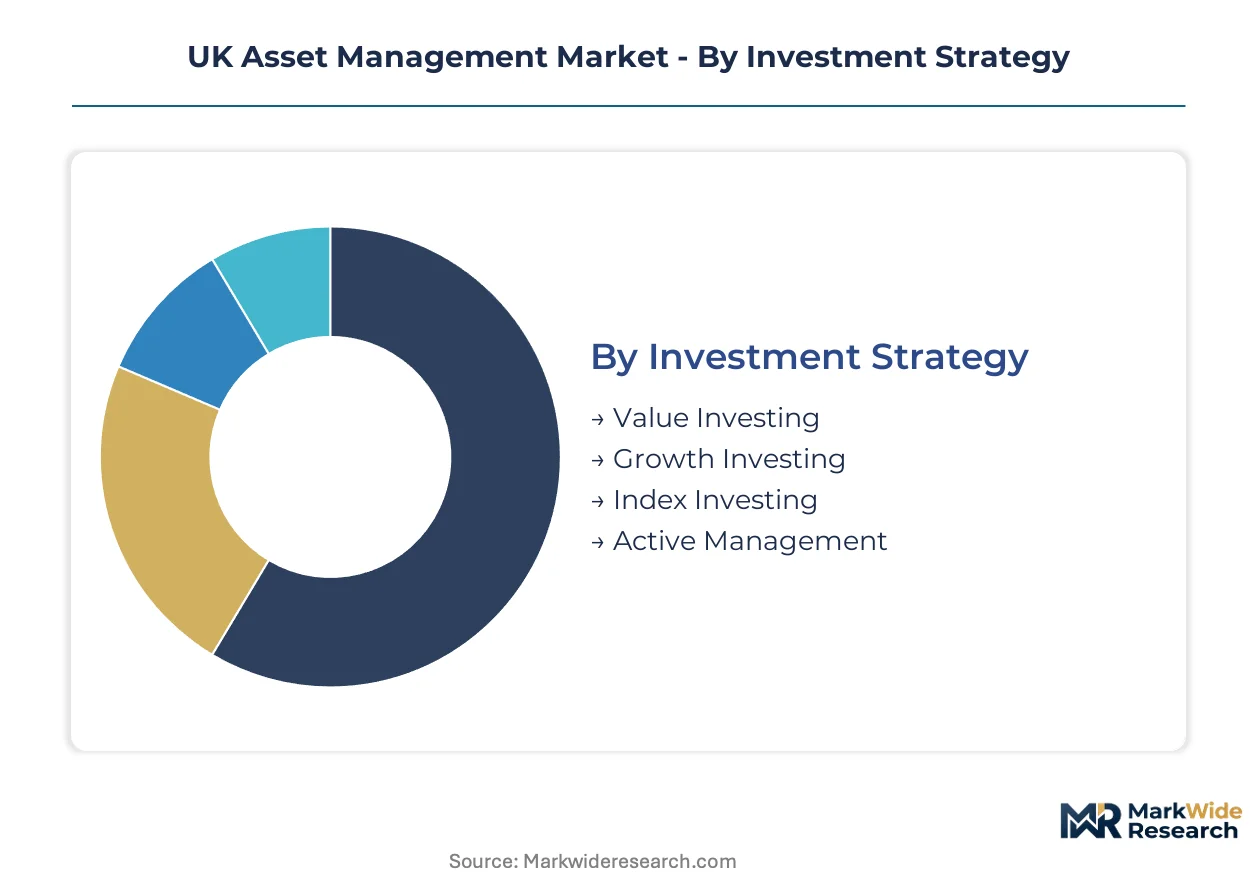
Asset management segmentation reveals how capital flows bifurcate between low-touch passive vehicles and high-touch advisory relationships. Understanding these divisions exposes where fee compression strikes hardest and where premium pricing endures.
Investment Strategy:
Cycle times vary dramatically across strategies, with index-tracking vehicles rebalancing continuously while concentrated value mandates hold positions for years.
- Index Investing:Rules-based replication of benchmark constituents minimizes trading costs and operational overhead. UK defined-contribution pension schemes in London and Birmingham are consolidating fund ranges around these vehicles, stripping out active share classes to satisfy FCA Consumer Duty cost transparency requirements.
- Active Management:Discretionary security selection commands higher fee margins but faces persistent outperformance challenges. Liability-driven investment mandates from consolidated pension schemes favor sophisticated active strategies that match duration and cash flow profiles.
- Value Investing:Bottom-up fundamental analysis targets undervalued securities with long holding periods.
- Growth Investing:Momentum-oriented positioning in expanding sectors attracts younger retail cohorts through digital platforms.
Index Investing anchors the volume base while Active Management retains the highest fee per dollar managed despite share erosion.
Asset Class:
Cost tiers separate liquid exchange-traded instruments from illiquid private holdings with multi-year lockups.
- Equities:Public company shares dominate AUM through both direct holdings and pooled vehicles. UK institutional allocations concentrate in FTSE-listed securities and developed market exposures, though emerging market sleeves are expanding.
- Fixed Income:Government and corporate debt instruments provide liability-matching cash flows for pension funds. The Bank of England's systemic risk oversight shapes duration and credit quality parameters across gilt-heavy portfolios.
- Real Estate:Physical property and REIT exposures offer inflation hedging with extended redemption timelines.
- Commodities:Raw material futures and physical holdings diversify portfolios against equity correlation.
Fixed Income commands the largest institutional commitment while Real Estate expands most quickly through long-term asset fund structures.
Client Type:
Volume concentration sits with fiduciary vehicles holding pooled retirement savings, while individual accounts fragment across service tiers.
- Pension Funds:Defined-benefit and defined-contribution schemes represent the most concentrated capital pools. The Pensions Regulator's consolidation push is concentrating assets into fewer, larger mandates that favor sophisticated LDI capabilities.
- Institutional Investors:Insurance companies, endowments, and sovereign wealth entities deploy capital with extended time horizons. These clients demand granular ESG disclosure and transition-themed strategies across their UK allocations.
- High-Net-Worth Individuals:Private banking relationships support customized portfolio construction with family governance overlays.
- Retail Investors:Mass-market participants access funds through platforms with reduced advisory overlays.
Pension Funds anchor the volume base while Retail Investors gain share at the steepest rate through platform digitization.
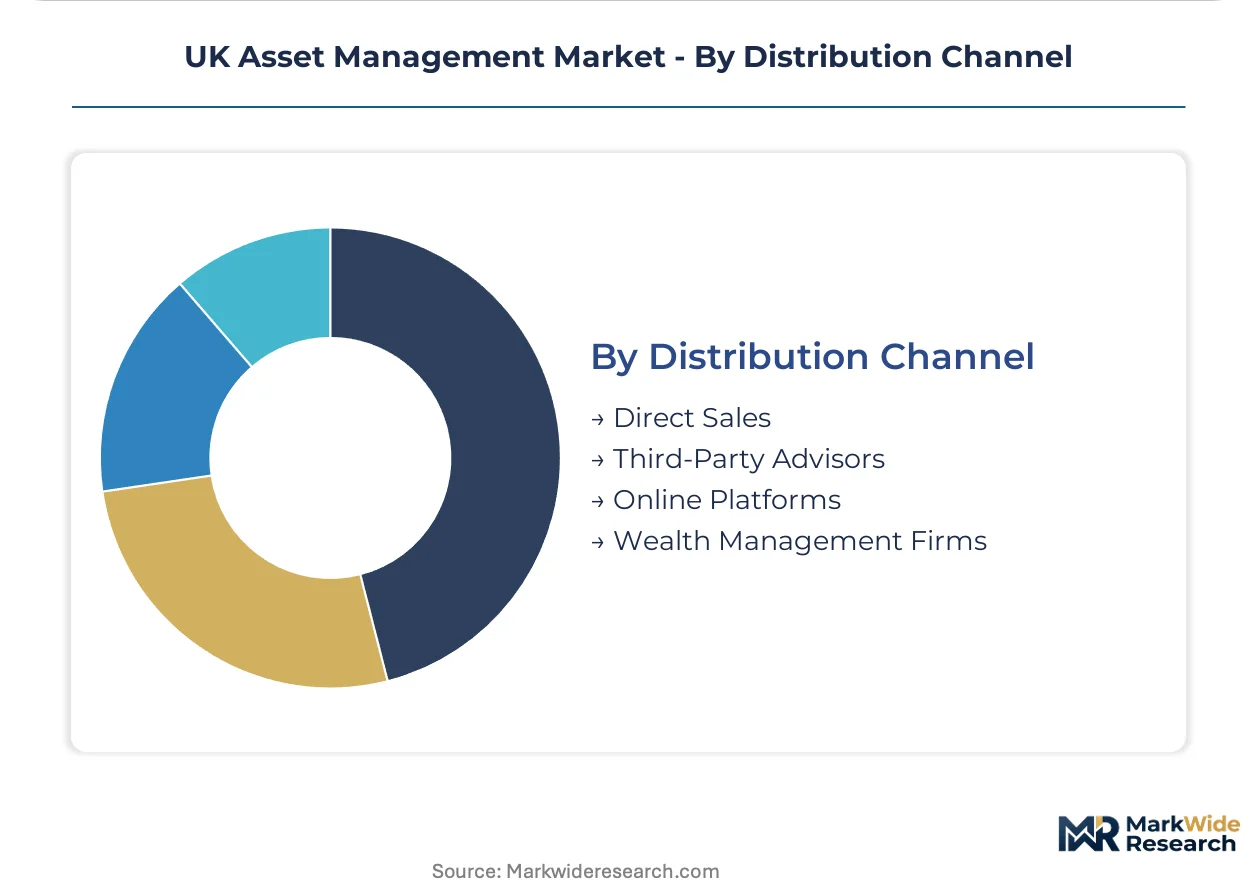
Distribution Channel:
Customer acquisition economics favor self-service onboarding over intermediary relationships with revenue-sharing obligations.
- Online Platforms:Digital distribution reduces onboarding friction and expands access to previously institutional-only structures. Hargreaves Lansdown and interactive investor are capturing flows from traditional advised channels through lower-cost execution.
- Wealth Management Firms:Holistic advisory relationships bundle asset management with tax and estate planning. Southeast England's inherited-wealth demographic sustains demand for personalized exclusion screens and direct indexing capabilities.
- Third-Party Advisors:Independent financial intermediaries select funds on behalf of advised clients.
- Direct Sales:Manager-to-client relationships bypass intermediaries for large institutional mandates.
Wealth Management Firms anchor the volume base while Online Platforms gain share at the steepest rate as digital onboarding compresses intermediary economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London commands premium fee structures that Edinburgh and Glasgow cannot replicate, creating a pricing-power asymmetry that shapes talent migration and operational location decisions across British asset management.
London and the Southeast
Institutional mandates from consolidated defined-benefit pension schemes and sovereign wealth allocations drive demand concentration in the capital. The Financial Conduct Authority's Consumer Duty rules enforce strict product governance and fee transparency standards. The City of London and Canary Wharf host BlackRock Investment Management (UK) Limited and Schroders plc headquarters, where liability-driven investment teams match duration profiles for pension fund clients.
Scotland
Fund administration and custody operations seek lower-cost bases without sacrificing regulatory credibility. The Senior Managers and Certification Regime applies uniformly across UK jurisdictions, preserving authorization value. Edinburgh anchors a servicing cluster where Abrdn plc maintains operational infrastructure, while Glasgow custody banks process trades for London-domiciled funds.
Midlands
Wealth management distribution networks expand through Birmingham and Manchester as digital platforms reduce dependency on London intermediaries. The Pensions Regulator's consolidation push concentrates assets into fewer mandates. Birmingham-based advisory firms are capturing retail flows that previously routed through Southeast wealth managers.
North England
Regional pension schemes and local authority funds sustain demand for investment advisory services outside the capital. ESG disclosure requirements from institutional investors reshape manager selection criteria. Leeds and Manchester house mid-tier asset managers adopting cloud-native portfolio accounting systems faster than London incumbents.
UK Asset Management Market Competitive Landscape
Index-heavy scale players and active specialty houses split the market into divergent margin structures. Consolidation pressure favors firms with liability-driven investment capabilities and ESG data infrastructure. Three archetypes dominate: global index providers with UK institutional dominance, domestic pension-anchored active managers, and wealth-platform-integrated advisory firms. Competitive moves concentrate on defined-benefit pension mandate consolidation and direct indexing technology licensing.
Among UK-domiciled institutions, Legal & General Investment Management Limited, Schroders plc, and Abrdn plc occupy positions across the active-passive spectrum. Legal & General Investment Management Limited exemplifies the pension-anchored archetype through deep ties with UK retirement schemes. Schroders plc represents active specialty positioning via emerging market strategies. Abrdn plc sits within the consolidating tier, navigating fee compression through platform integration and alternative asset expansion.
| Leading Market Players |
|---|
| BlackRock Investment Management (UK) Limited |
| Legal & General Investment Management Limited |
| Schroders plc |
| Abrdn plc |
| M&G plc |
| St James's Place |
| Rathbones Group plc |
| Evelyn Partners |
| Quilter plc |
| Others |
Value Network & Pricing Analysis
The London-Edinburgh rail freight corridor moves custody documentation and settlement instructions between Scotland's fund administration cluster and the capital's asset managers, with its cost dynamics amplifying the pricing-power asymmetry between London's premium fee structures and Edinburgh's lower-cost operational bases. This corridor's economics concentrate high-value advisory relationships in the Southeast while pushing back-office functions toward lower-cost jurisdictions, creating a bifurcated supply chain where downstream price differentiation reflects upstream geographic concentration.
Pricing Analysis
The customization-premium spread separates bespoke liability-driven investment mandates from standardized index-tracking vehicles, with active strategies commanding elevated fee margins that passive products cannot replicate. Three-tier pricing structure across premium, standard, and economy levels stratifies by advisory intensity, with wealth management firms bundling tax and estate planning into premium tiers while online platforms strip out overlays for economy positioning. Cost compression in standard-tier passive vehicles is intensifying because defined-contribution pension schemes are consolidating fund ranges to satisfy FCA Consumer Duty cost transparency requirements. Retail investors accessing funds through digital platforms exhibit the highest price sensitivity, while consolidated defined-benefit pension schemes retain tolerance for premium active management fees.
Supply Chain Analysis
Tariff exposure between the UK and EU dominates operational risk for cross-border fund distribution and delegated portfolio management arrangements post-Brexit. Technology infrastructure draws from Ireland's cloud hosting cluster, India's software development centers, and domestic UK data centers for regulatory-sensitive functions. Raw material dependencies center on proprietary data feeds from index providers, ESG rating agency licenses, and custody bank settlement systems. Single-source vulnerability concentrates in dominant index providers and clearing infrastructure. Distribution runs through wealth management firms for high-touch advisory relationships and online platforms for self-service retail access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Asset Management Market represents an early-cycle expansion story, with defined-benefit pension consolidation and ESG integration mandates driving adoption of sophisticated liability-driven investment and carbon accounting capabilities that remain underpenetrated across mid-tier managers.
For Market Incumbents: Entrench dominance in consolidated pension mandates by deepening liability-driven investment capabilities and acquiring ESG data infrastructure to meet institutional disclosure requirements. BlackRock Investment Management (UK) Limited and Legal & General Investment Management Limited anchor positions through scale in index investing and pension relationships respectively, but fee compression from passive vehicles threatens active management margins. Prioritize certification investment in the FCA's Consumer Duty compliance frameworks to differentiate on governance transparency. For New Entrants and Emerging Players: Build out direct indexing platforms and AI-driven personalization tools to capture inherited-wealth clients in Southeast England seeking granular control over environmental and ethical preferences. Scotland's fund servicing cluster offers lower-cost operational bases with established custody ecosystems, presenting the most penetrable geography for mid-tier asset managers. Pursue a go-to-market angle through wealth platform partnerships that bypass traditional intermediary economics. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate parent structures seeking to divest non-core asset management divisions amid industry consolidation pressure. Long-term viability over the next decade hinges on capturing flows from pension scheme mergers and ESG mandate expansion. Monitor the Pensions Regulator's consolidation timeline as the critical inflection indicator for mandate concentration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Indexing Platform Launch | Wealth managers in Southeast England deploy these tools to harvest tax losses for inherited-wealth clients. |
| ESG Data Infrastructure Acquisition | Institutional investors now require climate risk disclosure across portfolios from their UK asset managers. |
| Scotland Operational Expansion | Edinburgh and Glasgow custody banks process trades for London-domiciled funds at lower cost bases. |
| Consumer Duty Compliance Certification | FCA rules mandate total cost quantification that favors transparent fund structures over complex vehicles. |
| Long-Term Asset Fund Authorization | Regulatory reforms permitting these vehicles open retail distribution for private equity exposure. |
Research Methodology
Two parallel data streams informed the analysis: structured conversations with fund managers, pension trustees, platform executives, and regulatory compliance officers; and secondary validation through FCA authorization databases, Bank of England systemic risk reports, Pensions Regulator consolidation filings, and trade association flow statistics. Bottom-up triangulation across these sources cross-checked AUM figures and fee structure assumptions, while top-down verification against macroeconomic indicators anchored growth trajectory plausibility.
Forecast inputs considered investment strategy segmentation across active and passive vehicles, asset class concentration in fixed income and equities, client type evolution between pension funds and retail platforms, and distribution channel digitization rates. CAGRs were derived through compounding annual flow assumptions against baseline AUM positions across the modeling period. Industry-specific inputs incorporated the Pensions Regulator's consolidation push trajectory and FCA Consumer Duty implementation deadlines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by global index providers or platform consolidators would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
China Mutual Funds Market
Asset Management
Japan Asset Management Market
Asset Management
Asset Management System Market
Asset Management
Smart Asset Management Market
Asset Management
India Mutual Fund Market
Asset Management
US Pension Funds Market
Asset Management
India Asset Management Market
Asset Management
Fixed Income Asset Management Market
Asset Management
Global Investment Management Software Market
Asset Management
Asia-Pacific Utilities Asset Management Market
Asset Management
Mutual Fund Assets Market
Asset Management
Fund Management Fee Market
Asset Management
Global Remote Asset Management Market
Asset Management
Assets Under Management Market
Asset Management
Global Infrastructure Asset Management Market
Asset Management
Capital Expenditure Market