
 India Mutual Fund Market | 2026-2036
India Mutual Fund Market Size, Share, and Industry Trends Forecast 2026-2036
India Mutual Fund Market Insights
Urban salaried households is rebalancing the investor base away from traditional fixed-income instruments toward market-linked products. SBI Mutual Fund leverages its vast branch network to penetrate semi-urban geographies. ICICI Prudential Mutual Fund differentiates through quantitative active strategies and institutional mandates. HDFC Mutual Fund anchors the competitive landscape with its dominant equity franchise and advisor-driven distribution.
A mutual fund pools capital from multiple investors to purchase diversified portfolios of securities, operating through net asset value calculations with daily mark-to-market transparency and regulated expense ratios. The vehicle enables fractional ownership of equity, debt, or hybrid instruments while delegating portfolio decisions to professional fund managers. Equity Funds command the largest share of assets under management, reflecting retail risk appetite and long-term wealth accumulation goals. Hybrid Funds attract conservative investors seeking balanced exposure amid interest rate volatility. Direct Plans gain traction as digitally savvy investors bypass distributor commissions, compressing revenue per unit for asset management companies.
SEBI mandates strict disclosure norms, expense ratio ceilings, and risk classification frameworks that shape product design and distributor conduct. RBI's monetary policy stance influences Debt Fund returns and investor flows into fixed-income categories. The Pension Fund Regulatory and Development Authority's interoperability with mutual fund products expands retirement-oriented allocation. Stakeholders must monitor SEBI's evolving total expense ratio regulations and the competitive threat from passive Investment Strategy vehicles as fee compression accelerates.
Market Dynamics
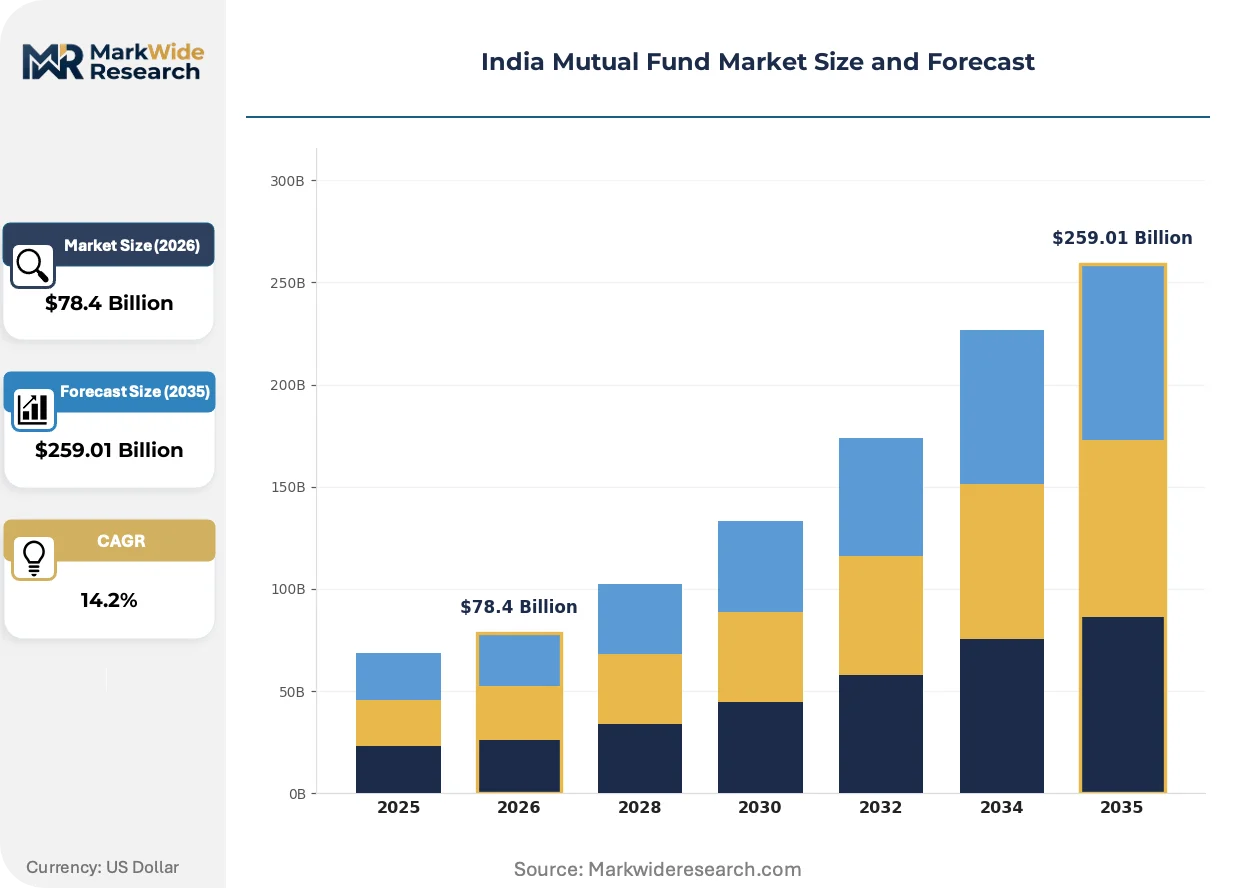
SEBI's total expense ratio compression mandates are restructuring distributor economics and accelerating direct plan adoption across India's mutual fund landscape. This regulatory pressure is forcing asset management companies to rebuild revenue models around scale rather than commission load.
Growth Catalysts
- Systematic Investment Plan penetration:Monthly SIP flows from tier-2 and tier-3 cities are deepening retail participation beyond traditional banking centers. Maharashtra, Gujarat, and Karnataka dominate contribution volumes.
- SEBI's risk classification framework:Standardized product labeling has simplified comparison shopping for retail investors. Transparency norms have reduced information asymmetry between distributors and end-investors.
- Pension Fund Regulatory and Development Authority interoperability:Retirement account portability with mutual fund products is expanding long-term allocation pools. National Pension System subscribers now rotate into equity-oriented schemes.
Market Restraints
- Debt Fund yield compression:RBI's prolonged accommodative stance has squeezed fixed-income category returns. Conservative investors are rotating toward bank deposits and small savings instruments.
- Distributor commission caps:SEBI's ceiling on upfront and trail commissions has compressed intermediary incentives. Advisor-driven distribution in semi-urban markets faces margin pressure.
- Passive vehicle substitution:Exchange-traded funds and index funds are capturing flows from actively managed equity schemes. Fee-sensitive institutional mandates favor benchmark-tracking products.
Strategic Opportunities
- Uttar Pradesh and Bihar penetration:These underpenetrated states exhibit rising per-capita income and limited banking density. Digital onboarding platforms can bypass physical branch constraints.
- Environmental, Social, and Governance thematic products:Regulatory tailwinds from SEBI's ESG disclosure requirements for listed companies enable dedicated fund launches. Corporate sustainability reporting creates investible universe expansion.
- Artificial intelligence-driven robo-advisory:Algorithmic portfolio construction is converging with regulatory sandbox approvals. Fintech partnerships offer scalable personalization without human advisor costs.
Industry Challenges
- Certified financial planner scarcity:SEBI's investment advisor regulations require specific qualifications for fee-based advisory. Talent pipelines from recognized institutions remain insufficient for geographic expansion.
- Legacy technology integration:Core banking system interoperability with modern API architectures creates operational friction. Real-time NAV dissemination demands infrastructure overhaul.
- Multi-channel reconciliation complexity:Distributor platforms, direct portals, and registrar systems generate fragmented investor data. Unified customer view implementation requires substantial capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Mutual Fund Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $259.01 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investor Type: Retail Investors, Institutional Investors, High Net Worth Individuals, Corporate Investors Fund Type: Equity Funds, Debt Funds, Hybrid Funds, Liquid Funds Investment Strategy: Active Management, Passive Management, Indexed Funds, Growth Strategy Distribution Channel: Direct Plans, Regular Plans, Online Platforms, Financial Advisors |
| Companies Covered | Nippon India Mutual Fund, Aditya Birla Sun Life Mutual Fund, SBI Mutual Fund, UTI Mutual Fund, Axis Mutual Fund, ICICI Prudential Mutual Fund, Kotak Mahindra Mutual Fund, Tata Mutual Fund, HDFC Mutual Fund, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Mutual Fund Market Trends and Innovations
Digital infrastructure and regulatory technology are converging to reshape how Indian investors discover, compare, and transact in mutual fund products. This transformation is compressing distribution layers while elevating data transparency.
Blockchain-based record-keeping is expanding into fund registry and transfer agency operations. Asset management companies are piloting distributed ledger technology for real-time unit ownership verification. This innovation is compressing settlement cycles from T+2 to T+0 while reducing reconciliation costs across registrar functions.
SEBI's enhanced total expense ratio disclosure norms now mandate granular breakdowns of distributor payouts and operational charges. Fund houses must publish itemized cost structures in standardized formats. Smaller asset management companies are responding by outsourcing back-office functions to shared service platforms.
Direct plan preference is accelerating among digitally native investors who bypass intermediary commissions entirely. Urban salaried professionals in Bangalore and Hyderabad are driving this channel shift through self-service platforms. This behavioral rotation is compressing revenue per unit for distributors while rewarding scale-focused fund houses with lower operational cost ratios.
India Mutual Fund Market Segmentation
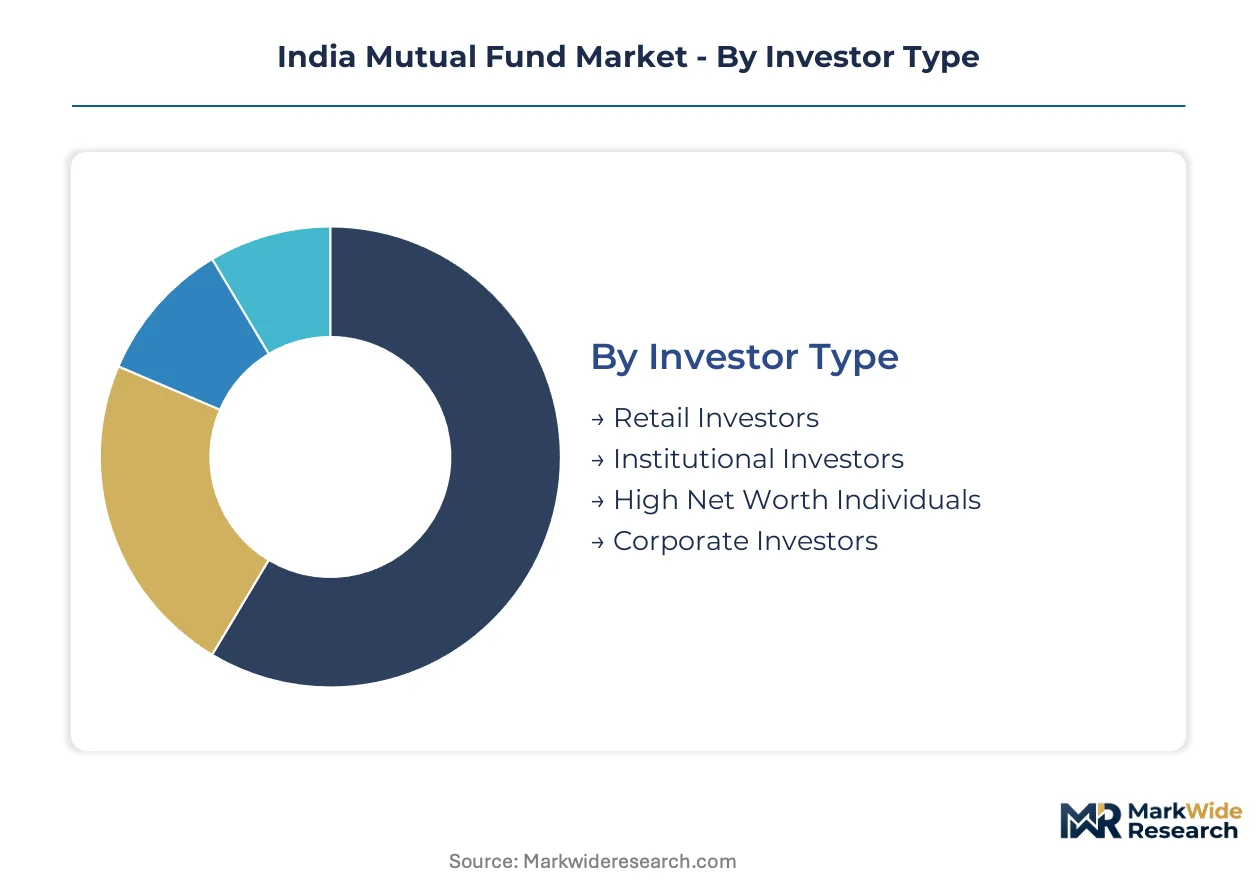
Segmentation in India's mutual fund market reveals how capital formation channels align with investor sophistication, risk tolerance, and access infrastructure. Understanding these partitions enables asset management companies to calibrate product design, distribution economics, and regulatory compliance across divergent participant profiles.
Investor Type:
Standardization dominates mass-market retail offerings while bespoke portfolio construction characterizes institutional mandates and ultra-high-net-worth relationships.
- Retail Investors:Comprise salaried professionals and small business owners deploying systematic investment plans through bank channels. SIP flows from Maharashtra, Gujarat, and Karnataka concentrate demand as tier-2 and tier-3 city participation deepens amid SEBI's financial literacy campaigns.
- Institutional Investors:Include pension funds, insurance companies, and corporate treasuries executing large-ticket mandates with customized liquidity terms. SEBI's risk classification framework governs their allocation limits while RBI's monetary policy stance shapes debt fund deployment timing.
- High Net Worth Individuals:Demand tailored portfolio management services with concentrated equity exposure and alternative investment access. Bespoke fee negotiations and dedicated relationship managers distinguish this segment from mass retail.
- Corporate Investors:Deploy surplus cash through liquid and ultra-short duration schemes for working capital optimization. Treasury policy constraints and auditor scrutiny limit tenor flexibility in fund selection.
Most installed capacity flows through Retail Investors. Expansion is steepest in High Net Worth Individuals as wealth creation accelerates in technology and manufacturing clusters.
Fund Type:
Cost tier separation aligns with risk-return hierarchy, where equity products command premium expense ratios against compressed yields in liquid and short-duration categories.
- Equity Funds:Deploy capital across market-cap segments and sectoral themes with active stock selection or index replication. Retail risk appetite and long-term wealth accumulation goals in urban centers drive sustained inflow momentum.
- Debt Funds:Navigate interest rate cycles through duration management and credit quality stratification. RBI's accommodative stance has compressed category returns, triggering rotation toward bank deposits among conservative investors.
- Hybrid Funds:Blend equity and debt exposure dynamically to balance capital appreciation with income stability. Conservative investors favor these vehicles amid interest rate volatility and equity market turbulence.
- Liquid Funds:Provide same-day redemption for institutional cash management with minimal mark-to-market risk. Corporate treasury deployment sustains asset base despite regulatory restrictions on exit loads.
Most installed capacity flows through Equity Funds. Expansion is steepest in Hybrid Funds as investors seek calibrated volatility exposure.
Investment Strategy:
Margin structure diverges sharply between high-fee active management and scale-dependent passive vehicles, reshaping revenue models across asset management companies.
- Active Management:Relies on fundamental research and portfolio manager discretion to outperform benchmarks. Fee-sensitive institutional mandates are migrating toward passive alternatives, compressing active management margins.
- Passive Management:Tracks defined indices with minimal turnover and transparent construction rules. Exchange-traded funds are capturing flows from actively managed equity schemes as institutional cost scrutiny intensifies.
- Indexed Funds:Offer mutual fund wrappers for index exposure with end-of-day NAV pricing. Direct plan adoption amplifies their appeal among digitally native investors bypassing distributor commissions.
- Growth Strategy:Targets capital appreciation through high-growth sector concentration and earnings momentum exposure. Technology and consumption themes dominate portfolio construction in this category.
Most installed capacity flows through Active Management. Expansion is steepest in Passive Management as fee compression accelerates across institutional mandates.
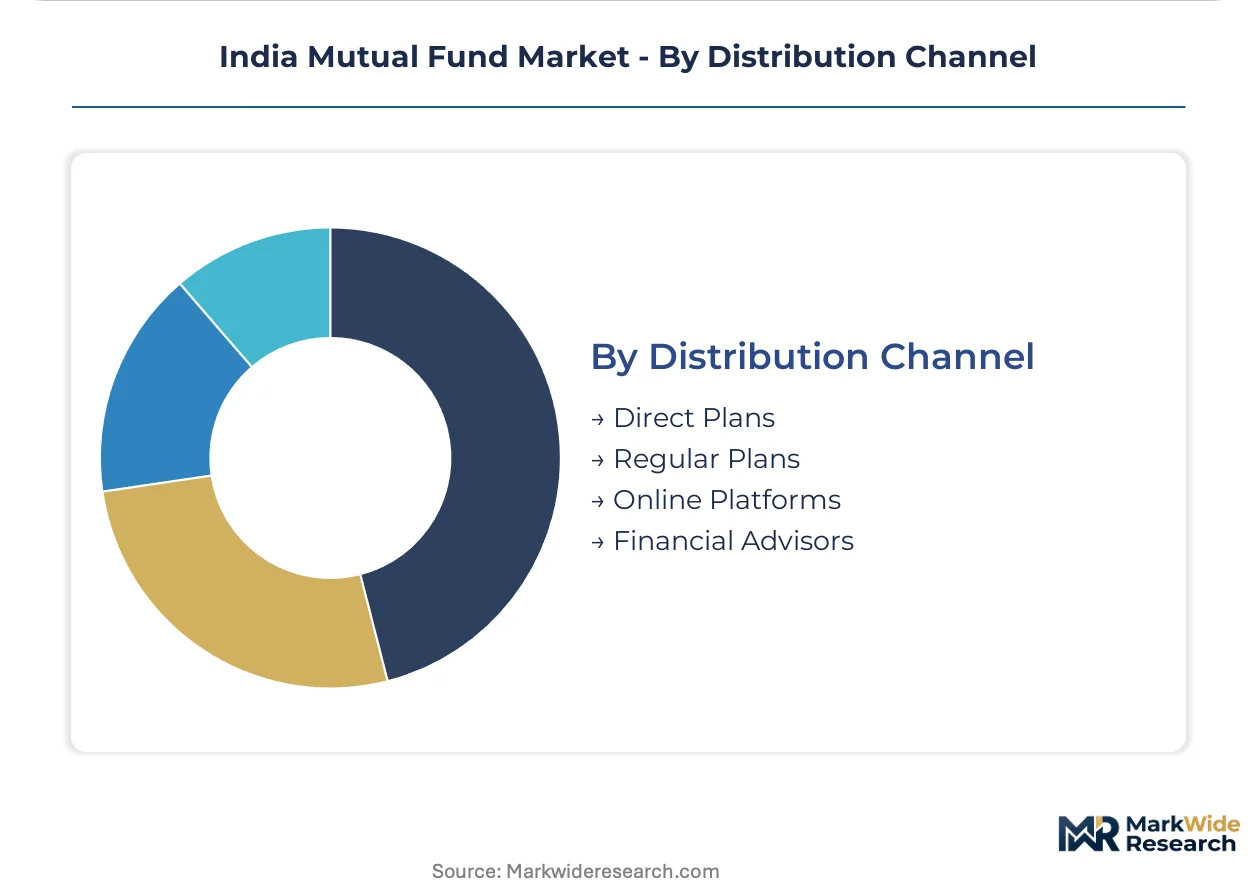
Distribution Channel:
Customer type and digital maturity determine channel selection, with self-directed investors gravitating toward zero-commission direct platforms while advised relationships sustain regular plan economics.
- Direct Plans:Eliminate distributor commissions through investor-initiated transactions via fund house portals or aggregators. Urban salaried professionals in Bangalore and Hyderabad drive this channel shift through self-service adoption.
- Regular Plans:Embed advisor compensation through upfront and trail commissions in product pricing. SEBI's commission ceiling mandates have compressed intermediary incentives in semi-urban markets.
- Online Platforms:Aggregate fund comparisons, analytics, and paperless onboarding through mobile-first interfaces. Fintech partnerships enable scalable distribution without physical branch infrastructure.
- Financial Advisors:Deliver personalized asset allocation and goal-based planning through certified professionals. SEBI's investment advisor regulations mandate specific qualifications that constrain talent pipeline expansion.
Most installed capacity flows through Regular Plans. Expansion is steepest in Online Platforms as digital onboarding penetrates underbanked geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra anchors India's mutual fund concentration through Mumbai's financial district infrastructure and SEBI's regulatory headquarters presence. Asset management companies cluster around the city's fund administration ecosystem. The state generates disproportionate SIP inflows relative to national totals.
Maharashtra
Salaried professionals in Mumbai and Pune drive systematic investment plan subscriptions through bank distribution networks. SEBI's investor protection mandates require standardized risk disclosure documentation for all product sales. The Mumbai-Pune corridor houses the headquarters of SBI Mutual Fund, ICICI Prudential Mutual Fund, and HDFC Mutual Fund, creating dense fund manager talent pools.
Gujarat
Small business owners and trading communities in Ahmedabad and Surat favor equity-oriented schemes for wealth accumulation. RBI's monetary policy transmission affects debt fund yields across the state's cooperative banking network. The Ahmedabad-Surat industrial belt exhibits deepening retail participation through distributor-led onboarding in tier-2 cities.
Karnataka
Technology sector employees in Bangalore demonstrate the highest direct plan adoption rates among Indian metros. SEBI's total expense ratio disclosure norms enable fee comparison across fund houses. The Bangalore-Hyderabad corridor drives digital platform transactions, compressing distributor commission dependencies.
Tamil Nadu
Manufacturing sector workforce in Chennai contributes to hybrid fund inflows seeking balanced volatility exposure. The Pension Fund Regulatory and Development Authority's interoperability with mutual funds expands National Pension System rotation into equity schemes. The Chennai-Coimbatore manufacturing belt shows emerging SIP penetration through employer-sponsored financial wellness programs.
Telangana
Pharmaceutical and IT professionals in Hyderabad exhibit rapid growth in self-directed online platform usage. SEBI's risk classification framework simplifies product comparison for first-time investors. The Hyderabad financial district hosts expanding registrar and transfer agency operations serving southern India.
India Mutual Fund Market Competitive Landscape
Portfolio diversification dominates the current landscape as asset management companies expand beyond core equity franchises into hybrid and passive vehicles. The market structure concentrates around ten major players with bank-affiliated entities commanding systemic distribution advantages. Three strategic archetypes define competitive positioning: bank-owned scale players, independent diversified houses, and specialist quantitative managers. M&A activity and direct plan technology investments represent the dominant competitive moves reshaping revenue models.
Among bank-affiliated asset managers, SBI Mutual Fund, ICICI Prudential Mutual Fund, and HDFC Mutual Fund occupy positions reflecting their parent banking networks' branch penetration. These entities exemplify the scale-driven archetype where vast distribution infrastructure compensates for fee compression pressures. SBI Mutual Fund represents public sector banking lineage with semi-urban reach, ICICI Prudential Mutual Fund anchors private sector quantitative capabilities, and HDFC Mutual Fund sits within the dominant equity franchise tier. Independent houses including Nippon India Mutual Fund and Aditya Birla Sun Life Mutual Fund compete through brand differentiation and thematic product innovation rather than captive distribution channels.
| Leading Market Players |
|---|
| Nippon India Mutual Fund |
| Aditya Birla Sun Life Mutual Fund |
| SBI Mutual Fund |
| UTI Mutual Fund |
| Axis Mutual Fund |
| ICICI Prudential Mutual Fund |
| Kotak Mahindra Mutual Fund |
| Tata Mutual Fund |
| HDFC Mutual Fund |
| Others |
Pricing and Supply Chain Analysis
Captive distribution through bank-owned asset management companies anchors both supply positioning and pricing power in India's mutual fund landscape. SBI Mutual Fund, ICICI Prudential Mutual Fund, and HDFC Mutual Fund leverage parent banking networks to control customer access while compressing competitor margins through scale economics.
Pricing Analysis
Input-cost pass-through from SEBI's total expense ratio compression mandates is restructuring fee structures across active and passive categories. Direct plans eliminate distributor commissions entirely, while regular plans embed advisor compensation through upfront and trail structures. Price differentiation rests on fund complexity and distribution channel, with equity schemes commanding premium expense ratios against compressed liquid fund yields. Urban salaried professionals in Bangalore and Hyderabad exhibit lowest price sensitivity through self-directed platform adoption, while tier-2 and tier-3 retail investors remain most sensitive to visible cost disclosures.
Supply Chain Analysis
Single-source vulnerability sits with registrar and transfer agency operations concentrated among CAMS and KFin Technologies. Fund administration draws from Mumbai's financial district infrastructure, with custody services resting on domestic banks and foreign custodians operating through Indian subsidiaries. Raw material dependencies include Bloomberg and Refinitiv data feeds, CRISIL and ICRA credit research, and proprietary algorithmic trading infrastructure. Supply chain risk centers on legacy technology integration friction between core banking systems and modern API architectures. Distribution runs through bank branches, independent financial advisors, and direct digital platforms in multi-channel configuration.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's mutual fund market functions as a regulatory compounder where SEBI's risk classification framework and total expense ratio mandates continuously reshape competitive economics and investor behavior.
For Market Incumbents: Extend defensive positioning through proprietary robo-advisory platform development and exclusive distributor lock-in agreements. Passive vehicle substitution threatens active management margins, requiring scale-focused fund houses to deepen vertical integration into direct-to-investor digital channels. Prioritize technology infrastructure that compresses operational cost ratios below SEBI-mandated ceilings. For New Entrants and Emerging Players: Begin with Uttar Pradesh and Bihar penetration through mobile-first onboarding platforms that bypass physical branch constraints. These underpenetrated states exhibit rising per-capita income with limited incumbent banking density. Target employer-sponsored financial wellness programs in manufacturing and IT corridors as the primary go-to-market angle for systematic investment plan acquisition. For Investors and Strategic Acquirers: Roll-up economics work for specialist quantitative managers because fee compression is accelerating institutional migration toward passive vehicles. Long-term viability favors asset management companies with scalable direct plan technology and captive distribution through parent banking networks. Monitor SEBI's evolving total expense ratio regulations as the critical inflection signal for margin structure stability.| Strategic Initiative | Industry Significance |
|---|---|
| Robo-Advisory Platform Launch | Algorithmic portfolio construction from SEBI's regulatory sandbox approvals enables scalable personalization without human advisor cost burdens. |
| Direct Plan Technology Investment | Self-service portal development captures digitally native investors in Bangalore and Hyderabad who bypass distributor commissions entirely. |
| ESG Thematic Product Introduction | SEBI's ESG disclosure requirements for listed companies expand investible universe for dedicated sustainability-focused fund launches. |
| Uttar Pradesh and Bihar Expansion | Digital onboarding platforms penetrate underbanked geographies where rising per-capita income meets limited physical branch infrastructure. |
| Blockchain Registry Pilot | Distributed ledger technology for real-time unit ownership verification compresses settlement cycles from T+2 to T+0 across registrar functions. |
Research Methodology
Coverage spans Maharashtra, Gujarat, Karnataka, Tamil Nadu, and Telangana, with primary inputs from each region's asset management company headquarters and distribution networks. The analysis combines primary interviews with fund managers, distributor relationship heads, SEBI regulatory affairs officers, and retail investor focus groups with secondary validation from AMFI industry statistics, SEBI circular archives, RBI monetary policy statements, and Pension Fund Regulatory and Development Authority interoperability guidelines. Bottom-up systematic investment plan flow analysis and top-down asset under management aggregation provide triangulation across data sources.
Rate-of-change decomposition separates volume growth from yield compression effects across the projection horizon. The analytical framework models investor type, fund category, investment strategy, and distribution channel dimensions alongside geographic penetration depth and digital adoption intensity. CAGRs derive from historical flow pattern analysis adjusted for regulatory milestone impacts and demographic shift projections. Forecast inputs include RBI policy stance trajectories, SEBI expense ratio evolution scenarios, and tier-2 and tier-3 city wealth creation indices.
Several conditions sit outside the modeled scope, including extreme equity market volatility episodes, systemic banking sector stress, and disruptive fintech platform entrants outside regulatory sandbox parameters. Forecasts reflect documented assumptions about SEBI regulatory continuity and demographic transition pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
India Asset Management Market
Asset Management
Japan Asset Management Market
Asset Management
Europe Asset Management Market
Asset Management
LAMEA Equity Management Software Market
Asset Management
Fund Management Fee Market
Asset Management
Pension Fund Management Software Market
Asset Management
Assets Under Management Market
Asset Management
Hardware Asset Management Market
Asset Management
Fund Management Software Market
Asset Management
Capital Expenditure Market
Asset Management
US Asset Management Market
Asset Management
Asset Management System Market
Asset Management
US Pension Funds Market
Asset Management
US Healthcare Assets Management Market
Asset Management
Smart Asset Management Market
Asset Management
Canada Asset Management Market