
 US Pension Funds Market | 2026-2036
US Pension Funds Market Size, Share, and Industry Trends Forecast 2026-2036
US Pension Funds Market Outlook
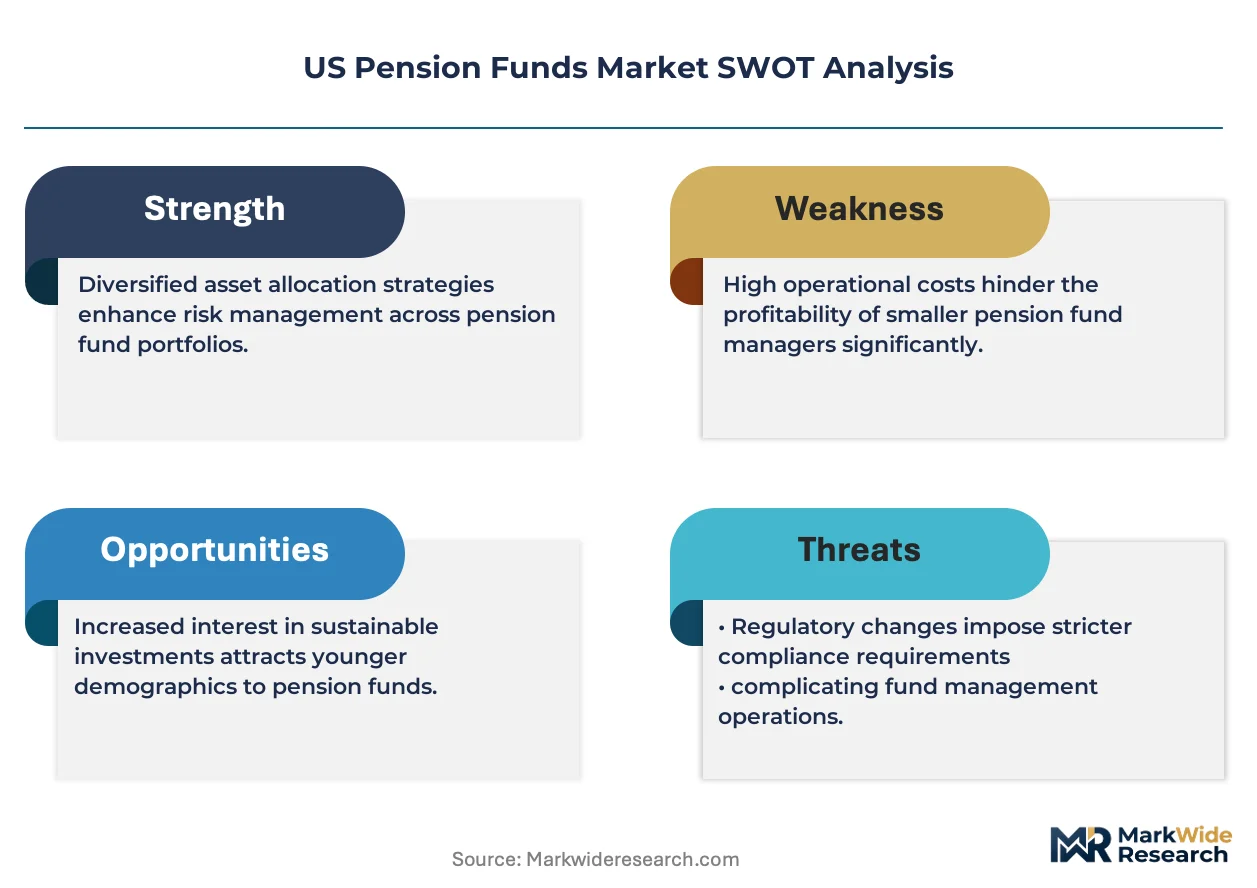
Fixed income instruments are hardening as the foundational risk-mitigation layer within pension liability-driven investment frameworks. BlackRock leverages its Aladdin risk analytics platform to dominate institutional portfolio construction. CalPERS anchors its strategic asset allocation with substantial private market commitments across infrastructure and real assets. Vanguard competes through ultra-low-cost passive equity vehicles that occupy the core holdings of most defined contribution plans.
US pension funds represent pooled retirement savings vehicles governed by ERISA fiduciary standards, with assets held in trust for beneficiaries and managed under strict prudence and diversification requirements. These institutions primarily exist to convert current contributions into inflation-adjusted income streams spanning multi-decade retirement horizons. The client type dimension reveals structural divergence: public plans face escalating unfunded liability pressures from demographic aging, while corporate plans continue de-risking through liability-driven investment shifts. Within investment strategy, alternatives allocations are deepening as sponsors pursue yield enhancement to close funding gaps in a persistently low-return environment.
The Department of Labor enforces ERISA fiduciary standards that directly shape investment menu design and fee disclosure practices across defined contribution platforms. The SEC's regulation of investment advisers under the Advisers Act imposes custody and reporting requirements that filter through to pension fund operational infrastructure. Plan sponsors must monitor evolving ESG disclosure mandates from federal regulators while calibrating glide path constructions for target-date funds against participant longevity risk.
Market Dynamics
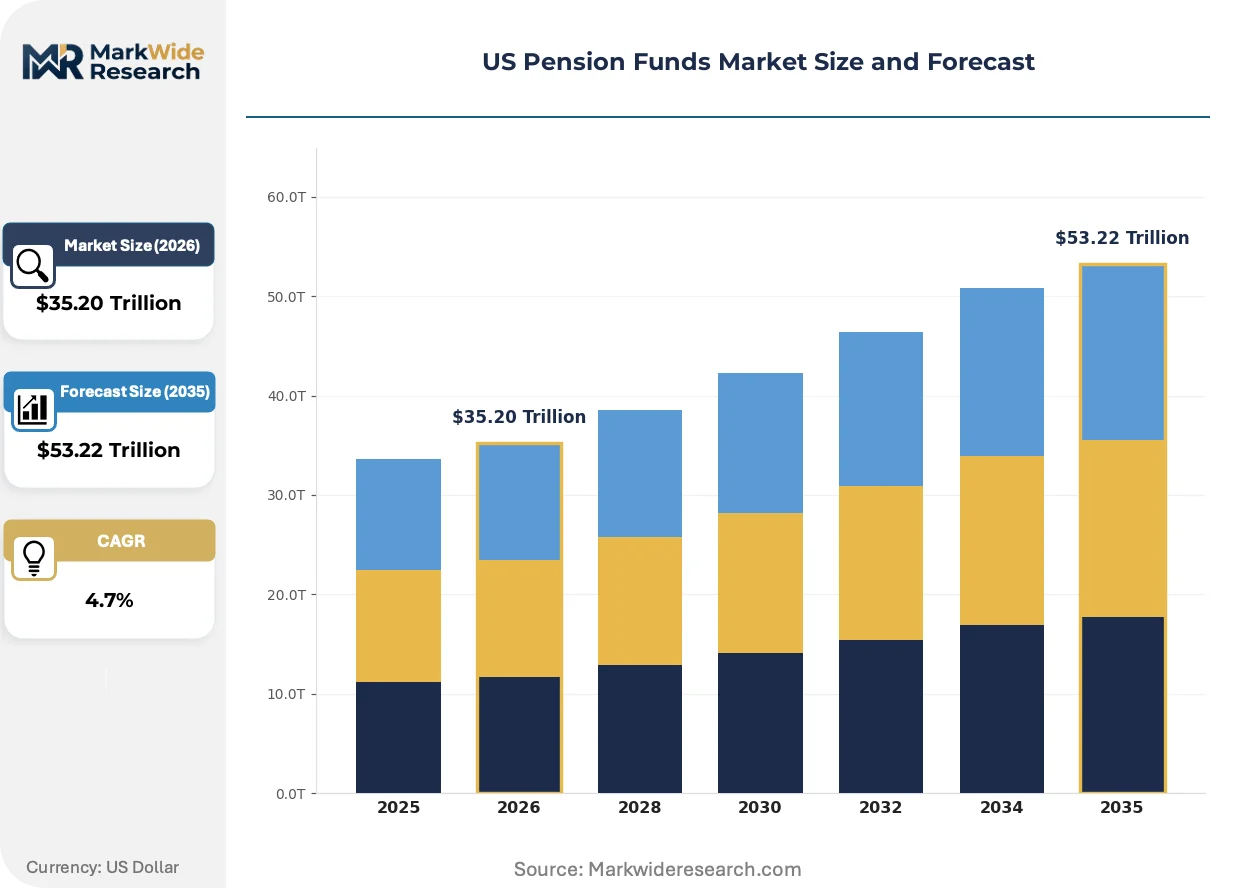
The US Pension Funds Market is undergoing fundamental reconfiguration as liability-driven investment frameworks force sponsors to reconcile stretched return assumptions against demographic headwinds. Plan fiduciaries face mounting pressure to generate yield without compromising solvency ratios.
Growth Catalysts
- Private Credit Expansion:Direct lending and mezzanine strategies offer yield pickup over public fixed income. Corporate pension sponsors allocate incrementally to fill duration gaps.
- SEC Enhanced Disclosure Mandates:The Investment Advisers Act amendments sharpen fee transparency. This compels advisers to demonstrate value through net-of-fee performance attribution.
- Infrastructure Real Assets:Toll roads, utilities, and digital infrastructure provide inflation-linked cash flows. Public plans in Texas and Florida deepen commitments to match long-dated liabilities.
Market Restraints
- Interest Rate Sensitivity:Rising discount rates compress reported liability values but increase fixed-income portfolio duration risk. Sponsors face convexity mismatches in their hedging programs.
- Valuation Opacity in Alts:Quarterly marks for private equity and venture holdings lag public market repricing. This creates pro-cyclical allocation drift during volatility episodes.
- Demographic Withdrawal Pressure:Maturing baby-boomer cohorts accelerate benefit distributions. Cash outflows force asset sales precisely when market liquidity contracts.
Strategic Opportunities
- Defined Contribution Glide Path Innovation:Target-date funds incorporating guaranteed income layers address participant longevity anxiety. Recordkeepers in Illinois and Ohio pilot hybrid accumulation-decumulation vehicles.
- Climate Risk Integration:The Department of Labor's ESG guidance permits consideration of material environmental factors. Trustees incorporate physical risk assessments into real estate and infrastructure due diligence.
- Healthcare Cost Liability Management:Retiree medical obligations represent unfunded exposures. Sponsors in Michigan and Pennsylvania explore captive insurance structures to prefund OPEB liabilities.
Industry Challenges
- Actuarial Talent Scarcity:Qualified pension actuaries with expertise in stochastic liability modeling command premium compensation. Smaller municipal plans struggle to retain specialized staff.
- Legacy System Integration:Core recordkeeping platforms built on COBOL architectures resist modernization. Data migration to cloud-native administration systems risks participant service disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pension Funds Market |
| Market Size in 2026 | $35.20 Trillion |
| Market Size in 2035 | $53.22 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Strategy: Equity, Fixed Income, Alternatives, Cash Fund Size: Small-cap, Mid-cap, Large-cap, Mega-cap Client Type: Corporate, Public, Multi-employer, Non-profit Asset Class: Equities, Bonds, Real Estate, Commodities |
| Companies Covered | Fidelity Investments, BlackRock, California Public Employees' Retirement System (CalPERS), Morgan Stanley, Charles Schwab, California Teachers' Retirement System (CalSTRS), Vanguard, UBS, Federal Retirement Thrift Investment Board (FRTIB), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pension Funds Market Strategic Shifts
Fiduciary technology and participant-facing digital infrastructure are converging to reshape how retirement assets are administered, governed, and accessed. Automation is compressing operational cost structures while elevating data security imperatives.
Artificial intelligence-driven participant engagement platforms are rewriting the economics of retirement readiness counseling. Plan sponsors deploy predictive analytics to identify employees at risk of inadequate savings rates. Large defined contribution recordkeepers in California and New York accelerate AI pilot programs. This capability is compressing the cost per meaningful participant touchpoint by an order of magnitude.
The SEC's custody rule amendments under the Investment Advisers Act impose stricter operational requirements on investment managers handling pension assets. Qualified custodians must maintain enhanced segregation and reporting protocols. Private fund advisers face particular compliance burden given partnership agreement complexity. Mid-sized investment managers in Massachusetts and Connecticut restructure operational infrastructure to satisfy attestation requirements.
Portability demands from mobile workforces are fragmenting traditional lifetime employment-based accumulation models. Participants accumulate multiple small-balance accounts across successive employers. State-facilitated auto-IRA programs in Oregon and Illinois create new accumulation channels outside employer sponsorship. This behavioral shift pressures recordkeepers to develop interoperable data exchange standards.
US Pension Funds Market Segmentation
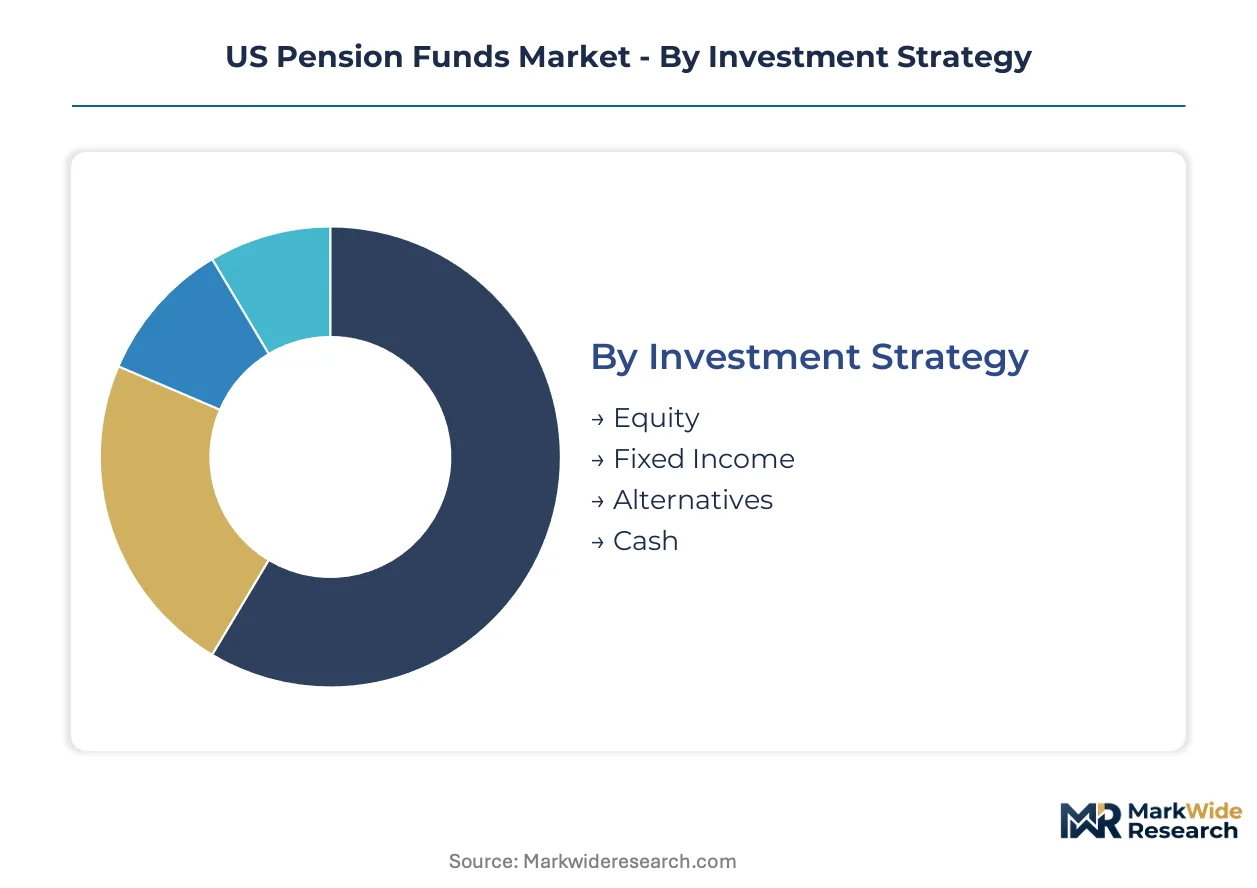
US pension fund segmentation reveals how liability duration, sponsor governance, and participant demographics reshape portfolio construction across distinct institutional profiles. Each dimension captures material differences in risk tolerance, liquidity needs, and regulatory constraints.
Investment Strategy:
Rebalancing cycles and glide-path recalibration drive replacement velocity across strategy buckets, with sponsors rotating between risk-seeking and liability-hedging postures.
- Equity:Domestic and international equity allocations provide growth exposure to offset long-duration liabilities. Demand concentrates among corporate sponsors in California and Texas seeking to close funding gaps through public market beta.
- Fixed Income:Investment-grade bonds and Treasury strips form the duration-matched hedging layer in liability-driven investment frameworks. Public plans in New York and Illinois weight heavily here to stabilize reported funded status against interest rate volatility.
- Alternatives:Private equity, hedge funds, and real assets deliver uncorrelated return streams with extended lock-up periods.
- Cash:Liquidity reserves cover benefit distributions and collateral requirements for derivatives overlays.
Volume placements concentrate in Fixed Income; the faster expansion belongs to Alternatives.
Fund Size:
Scale economies separate operational capabilities, with larger funds accessing direct deals and bespoke structures unavailable to smaller peers.
- Mega-cap:Plans exceeding $100 billion in assets under management command dedicated internal teams for private market co-investments and infrastructure direct deals. These sponsors in California and New York negotiate preferential fee terms and board representation rights.
- Large-cap:Assets between $10 billion and $100 billion rely on fund-of-funds and consultant-advised manager selection to access alternative asset classes.
- Mid-cap:Plans from $1 billion to $10 billion face pressure to consolidate through mergers or join investment pools to achieve diversification.
- Small-cap:Assets below $1 billion depend heavily on outsourced chief investment officer models and target-date fund defaults for defined contribution participants.
Mega-cap vehicles capture the largest allocation flows; mid-cap plans are consolidating fastest to survive.
Client Type:
Governance structure and benefit promise durability create fundamentally different investment horizons and political constraints.
- Public:State and municipal retirement systems operate under constitutional or statutory benefit protections with limited flexibility to reduce accrued liabilities. Plans in California, Texas, and Florida face escalating contribution demands from taxpayers.
- Corporate:Single-employer defined benefit plans governed by ERISA and PBGC insurance face de-risking pressures as sponsors seek to offload longevity and investment risk through annuity purchases or lump-sum windows.
- Multi-employer:Taft-Hartley plans serving unionized industries across construction, trucking, and entertainment confront severe underfunding in legacy pools.
- Non-profit:University endowments and hospital retirement plans blend pension and endowment management with donor-driven constraints.
Public plans dominate total assets under management; corporate plans are shrinking fastest through frozen accruals and risk transfers.
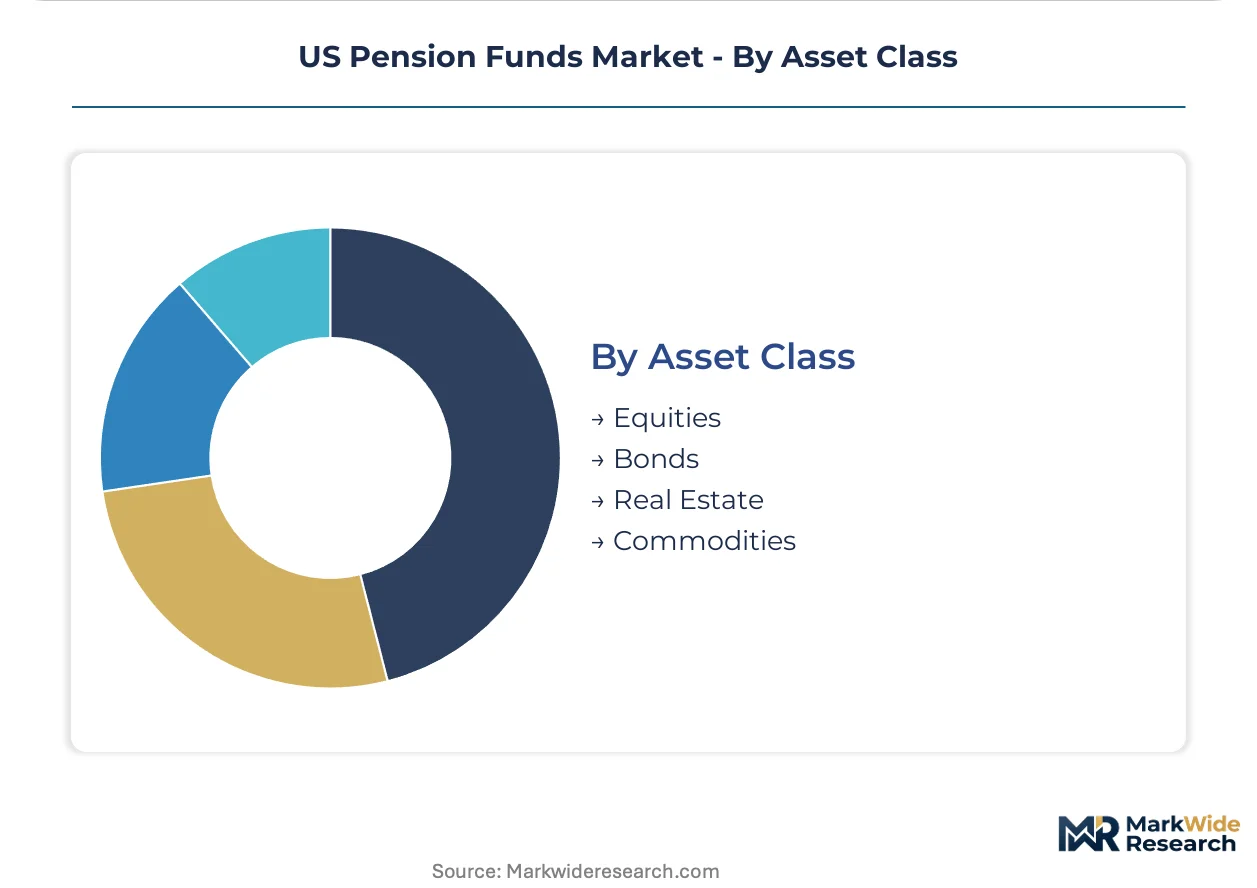
Asset Class:
Implementation vehicle selection separates passive beta replication from active management and illiquid private structures.
- Equities:Public equity exposure spans capitalization tiers and geographic markets through index funds, enhanced index, and concentrated active mandates. Recordkeepers in Ohio and Pennsylvania default participants into target-date equity glide paths.
- Bonds:Fixed income spans government, credit, and securitized sectors with duration targeting to match liability profiles. Liability-driven investment specialists in Massachusetts structure custom Treasury strips portfolios.
- Real Estate:Core property, value-add, and opportunistic strategies provide inflation sensitivity and income stability. Open-end core funds attract public plan commitments seeking quarterly liquidity.
- Commodities:Futures-based and physical commodity exposure offers inflation hedging and diversification from financial asset correlation.
Equities and Bonds together absorb the majority of flows; Real Estate is gaining share fastest among alternative allocations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates among mega-cap defined benefit plans exceeding $100 billion in assets, with California and New York public systems driving allocation flows into private equity and infrastructure. State-level regulatory variation shapes fiduciary transparency obligations across sponsor jurisdictions.
California
CalPERS and CalSTRS anchor the nation's largest public pension complex, with combined assets exceeding $750 billion. The state's Public Employees' Retirement Law mandates actuarial valuations every two years, tightening funding discipline. Sacramento-based investment teams negotiate direct infrastructure co-investments and private credit allocations unavailable to smaller sponsors.
New York
The New York State Common Retirement Fund and New York City Retirement Systems face escalating unfunded liability pressures from aging municipal workforces. State Comptroller oversight imposes strict proxy voting disclosure requirements on externally managed assets. Manhattan-based investment consultants structure liability-driven investment frameworks for corporate plan sponsors undergoing de-risking.
Texas
The Teacher Retirement System of Texas and Employees Retirement System of Texas command substantial capital deployment into energy infrastructure and real assets. State constitutional protections for accrued benefits limit sponsor flexibility to modify retirement formulas. Austin investment staff pursue direct lending opportunities in Permian Basin energy projects and southwestern logistics networks.
Florida
The State Board of Administration oversees retirement assets for public employees across the third-most populous state. Florida's absence of state income tax attracts retiree migration, accelerating benefit distribution timelines. Tampa-based recordkeepers pilot target-date fund innovations incorporating guaranteed income layers for decumulation-phase participants.
Illinois
Chicago-area public safety and municipal plans confront severe underfunding ratios among the nation's weakest. State legislation creating the Illinois Municipal Retirement Fund imposed consolidation mandates on smaller suburban systems. Springfield regulators enforce strict asset-liability matching requirements for plans seeking to issue pension obligation bonds.
US Pension Funds Market Competitive Environment
Consolidation through strategic partnerships dominates the current landscape as recordkeepers and asset managers combine capabilities to capture defined contribution platform mandates. The vendor base separates into three distinct tiers: mega-scale integrated providers with proprietary recordkeeping technology, specialized investment boutiques competing on net-of-fee performance, and regional advisory firms serving mid-market sponsors. Scale-driven players pursue vertical integration into data analytics and participant engagement tools. Niche specialists defend positioning through liability-driven investment customization and alternative asset access.
Among integrated asset management and recordkeeping platforms, Fidelity Investments, BlackRock, and Vanguard exemplify distinct competitive archetypes. Fidelity occupies the participant-service-centric position with proprietary recordkeeping infrastructure spanning employer-sponsored and retail retirement channels. BlackRock anchors the risk-analytics-driven tier, leveraging institutional portfolio construction tools across defined benefit and defined contribution mandates. Vanguard represents the ultra-low-cost passive specialist, capturing core equity allocations through index fund vehicles that dominate target-date fund glide paths.
| Leading Market Players |
|---|
| Fidelity Investments |
| BlackRock |
| California Public Employees' Retirement System (CalPERS) |
| Morgan Stanley |
| Charles Schwab |
| California Teachers' Retirement System (CalSTRS) |
| Vanguard |
| UBS |
| Federal Retirement Thrift Investment Board (FRTIB) |
| Others |
Value Chain & Pricing Dynamics
Captive in-house asset management infrastructure anchors both supply positioning and pricing power for the largest US pension funds, with mega-cap plans like CalPERS and CalSTRS leveraging internal teams to negotiate preferential fee terms unavailable to smaller sponsors dependent on external managers.
Pricing Analysis
Volume placements concentrate in mega-cap defined benefit plans exceeding $100 billion in assets, while margin compression runs through mid-cap and small-cap sponsors forced into fund-of-funds structures with layered fee loads. Pricing stratifies across direct mandate, commingled fund, and target-date vehicle tiers, with basis-point differentiation driven by scale and asset class complexity. Cost compression in alternatives access is intensifying because smaller plans lack bargaining leverage for co-investment rights. Public sector sponsors in California and Texas demonstrate lowest price sensitivity due to taxpayer-backed contribution flows, while corporate frozen plans exhibit highest sensitivity as sponsors prioritize de-risking cost minimization.
Supply Chain Analysis
Workforce availability constraints in Boston, New York, and Chicago financial centers limit the pipeline of qualified actuaries and liability-driven investment specialists, forcing sponsors into consultant-mediated manager selection. Supply concentrates in the United States for recordkeeping platforms and fiduciary technology, with secondary dependencies on Ireland and Luxembourg for UCITS-structured global equity vehicles. Raw material dependencies include Aladdin-style risk analytics licenses, cloud-native administration infrastructure, and proprietary target-date glide-path algorithms. Single-source vulnerability sits with legacy COBOL-based recordkeeping architectures resisting modernization. Distribution runs through bundled provider relationships linking asset management, recordkeeping, and participant engagement under unified contractual frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US pension fund capacity is supply-constrained by qualified actuarial talent scarcity, with stochastic liability modeling expertise propping pricing power for specialized consultants and in-house teams.
For Market Incumbents: Acquire direct infrastructure co-investment capabilities to defend against yield compression from rising discount rates and demographic withdrawal pressure. Consolidate through merger with mid-cap municipal plans in Illinois and Ohio to capture scale economies in alternative asset access. Channel control over proprietary recordkeeping technology represents the critical lever for participant data monetization. For New Entrants and Emerging Players: Capture state-facilitated auto-IRA administration mandates in Oregon and Illinois where employer-sponsored plan penetration remains incomplete. Target small-cap non-profit hospital and university retirement plans with outsourced CIO models addressing legacy system integration failures. Go-to-market positioning should emphasize AI-driven participant engagement platforms compressing counseling cost per touchpoint. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by mega-scale integrated providers seeking recordkeeping platform consolidation. Long-term viability favors sponsors with constitutional benefit protections and direct deal access. Watch for inflection in interest rate convexity mismatches forcing emergency de-risking transactions.| Strategic Initiative | Industry Significance |
|---|---|
| Private Credit Direct Lending Buildout | Corporate sponsors in Michigan and Pennsylvania allocate to fill duration gaps with yield pickup. |
| AI-Driven Participant Engagement Platform | Recordkeepers in California and New York deploy predictive analytics to identify at-risk savers. |
| State Auto-IRA Program Administration | Oregon and Illinois create accumulation channels outside traditional employer sponsorship structures. |
| Climate Risk Integration Framework | Department of Labor ESG guidance permits physical risk assessment in real estate due diligence. |
| Legacy System Cloud Migration | COBOL-based recordkeeping platforms in Massachusetts and Connecticut face modernization pressure. |
Study Parameters
SEC filings, ERISA plan disclosure documents, and state actuarial valuation reports formed the secondary backbone, supplemented by primary interviews with pension fund CIOs, ERISA fiduciary counsel, defined contribution recordkeeping executives, and investment consultant portfolio strategists. Bottom-up and top-down triangulation validated asset allocation flows across public, corporate, multi-employer, and non-profit sponsor categories.
Bottom-up modeling aggregated sponsor-level asset flows by investment strategy, fund size tier, and client type, while top-down reconciliation tracked aggregate market-level growth assumptions across the analysis window. Segmentation dimensions included investment strategy, fund size, client type, and asset class implementation vehicle. CAGRs derived from actuarial liability growth projections cross-referenced against contribution rate and benefit distribution assumptions. Forecast inputs incorporated demographic withdrawal timelines and interest rate sensitivity matrices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to discount rate volatility, alternative asset valuation opacity, and regulatory shifts in ESG disclosure mandates. Assumptions reflect current ERISA fiduciary standards and SEC custody rule frameworks. Material deviation in interest rate convexity mismatches or actuarial talent availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Asset Optimization Solutions Market
Asset Management
Global Investment Management Software Market
Asset Management
APAC Mutual Fund Market
Asset Management
Canada Asset Management Market
Asset Management
Global Remote Asset Management Market
Asset Management
Fixed Income Asset Management Market
Asset Management
Asset and Wealth Management Market
Asset Management
Europe Asset Management Market
Asset Management
Equity Management Tool Market
Asset Management
Fund Management Software Market
Asset Management
Pension Fund Management Software Market
Asset Management
India AMC Industry Market
Asset Management
Global Asset Performance Management Market
Asset Management
US Asset Management Market
Asset Management
China Mutual Funds Market
Asset Management
India Mutual Fund Market