
 Asset and Wealth Management Market | 2026-2036
Asset and Wealth Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asset and Wealth Management Market Analysis
Asset-light operating models and platform-based outsourcing is narrowing the capital barrier for mid-tier advisors to compete against integrated giants. BlackRock leverages its Aladdin technology infrastructure to sustain institutional scale across risk analytics and portfolio construction. Vanguard Group anchors retail market share through low-cost index fund dominance and direct-to-investor channel control. UBS differentiates by occupying the ultra-high-net-worth segment with integrated wealth planning and cross-border advisory capabilities.
Asset and wealth management encompasses the professional oversight of financial portfolios, combining securities selection, risk assessment, tax-efficient structuring, and fiduciary governance to preserve and compound capital across market cycles. The discipline applies modern portfolio theory, liability-driven investment frameworks, and regulatory compliance protocols to match assets with investor time horizons and return objectives. Investment advisory services lead revenue generation among service types, while ESG investing represents the fastest-expanding investment strategy as capital owners embed sustainability criteria into mandate structures. Retail investor participation through online platforms is accelerating channel migration, though institutional brokers still capture the largest margin pools from complex mandate negotiations.
The US Securities and Exchange Commission enforces fiduciary standards under the Investment Advisers Act, reshaping product recommendations and fee disclosure requirements for advisors serving American clients. The European Securities and Markets Authority coordinates MiFID II implementation across EU member states, mandating cost transparency and suitability assessments that alter distribution economics. The UK's Financial Conduct Authority applies consumer duty rules that force firms to demonstrate fair value in advisory relationships. Stakeholders must monitor how divergent national implementation of cross-border marketing rules affects platform scalability and client acquisition economics.
Market Dynamics
Fiduciary standard tightening under ERISA guidance is compressing fee structures while forcing institutional allocators toward transparent, outcome-based mandate structures across alternative asset classes.
Growth Catalysts
- Alternative asset allocation:Institutional pension funds are expanding exposure to private equity and infrastructure under liability-driven investment frameworks. This reallocation channels capital toward specialized managers with direct deal-sourcing capabilities.
- SEC's Investment Advisers Act enforcement:Stricter fiduciary standards reshape product recommendations and fee disclosure requirements. Advisors serving American clients must demonstrate suitability and eliminate conflicted compensation structures.
- Platform-based outsourcing:Asset-light operating models narrow capital barriers for mid-tier advisors. Technology infrastructure enables smaller firms to compete against integrated giants through risk analytics and portfolio construction tools.
Market Restraints
- Fee compression:Passive index fund dominance at Vanguard Group and similar providers squeezes active management margins. Retail investors migrate toward low-cost vehicles, eroding traditional advisory revenue pools.
- Talent concentration:Quantitative risk management and alternative asset expertise clusters in New York, London, and Singapore. Regional advisors face recruitment friction for specialized portfolio construction skills.
- MiFID II cost transparency:European Securities and Markets Authority mandates alter distribution economics across EU member states. Suitability assessments and explicit fee disclosure compress embedded commission structures.
Strategic Opportunities
- Family office outsourcing:North American single-family and multi-family offices seek external chief investment officer services. Direct private-market exposure and consolidated reporting represent unmet demand.
- ESG mandate integration:Capital owners embed sustainability criteria into investment structures. Asset managers developing verified ESG scoring frameworks capture institutional flows seeking alignment with environmental and governance objectives.
- Cross-border advisory:Ultra-high-net-worth individuals require integrated wealth planning across jurisdictions. Firms with multi-licensed advisor networks and tax-efficient structuring capabilities secure sticky relationships.
Industry Challenges
- Legacy system integration:Established wealth managers operate on fragmented technology stacks. Consolidating client data, portfolio accounting, and regulatory reporting across acquired platforms demands substantial capital and execution risk.
- Advisory talent pipeline:Certified financial planner and chartered financial analyst credential attainment lags demand growth. Succession planning for aging advisor populations compounds recruitment pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asset and Wealth Management Market |
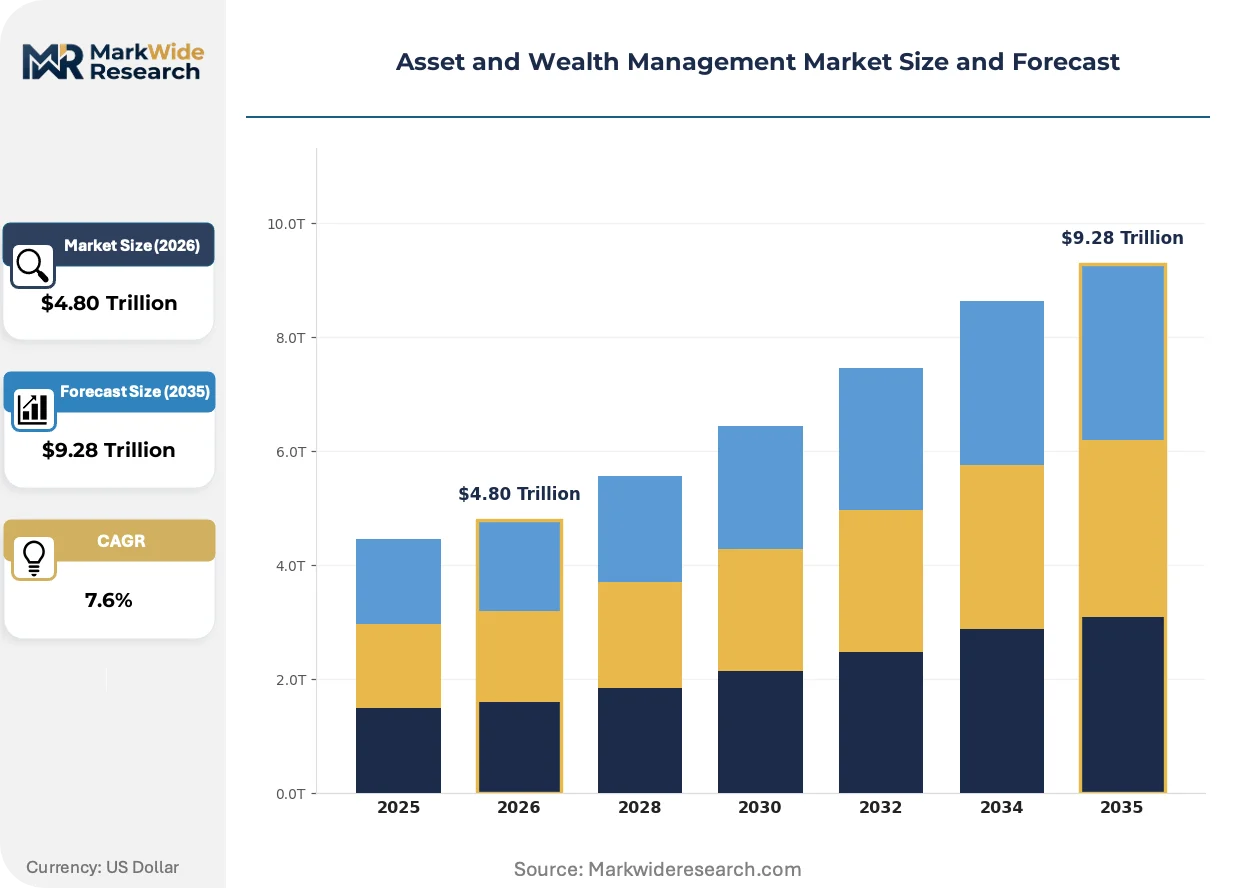
| Market Size in 2026 | $4.80 Trillion |
| Market Size in 2035 | $9.28 Trillion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Investment Advisory, Wealth Planning, Portfolio Management, Tax Optimization Client Type: High Net Worth Individuals, Institutions, Retail Investors, Family Offices Distribution Channel: Direct Sales, Online Platforms, Financial Advisors, Institutional Brokers Investment Strategy: Active Management, Passive Management, ESG Investing, Tactical Allocation |
| Companies Covered | BlackRock, Vanguard Group, Fidelity Investments, State Street Global Advisors, JPMorgan Chase, UBS, Invesco, Charles Schwab Corporation, Amundi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asset and Wealth Management Market Emerging Trajectories
Artificial intelligence and distributed ledger infrastructure are digitizing core operational workflows while regulatory fragmentation forces architecture investments that accommodate divergent national compliance requirements.
Portfolio management software incorporating machine learning algorithms is digitizing security selection and rebalancing processes. Mid-sized advisory firms adopt these tools to match institutional-grade analytics without proprietary technology development. The compression of manual research and trading workflows enables advisors to scale client relationships beyond traditional capacity limits.
The US Securities and Exchange Commission's enhanced custody rule proposals impose stricter requirements on how advisors safeguard client assets. Qualified custodians must demonstrate operational resilience and cybersecurity protocols that exceed historical standards. Smaller registered investment advisors face compliance cost burdens that accelerate consolidation toward platform-affiliated models.
Direct indexing strategies enable high-net-worth investors to customize benchmark replication with tax-loss harvesting and values-based exclusions. Separately managed account platforms displace commingled fund structures for taxable investors seeking granular control. This behavioral shift concentrates in the United States where tax alpha optimization and concentrated stock diversification drive adoption.
Asset and Wealth Management Market Segmentation
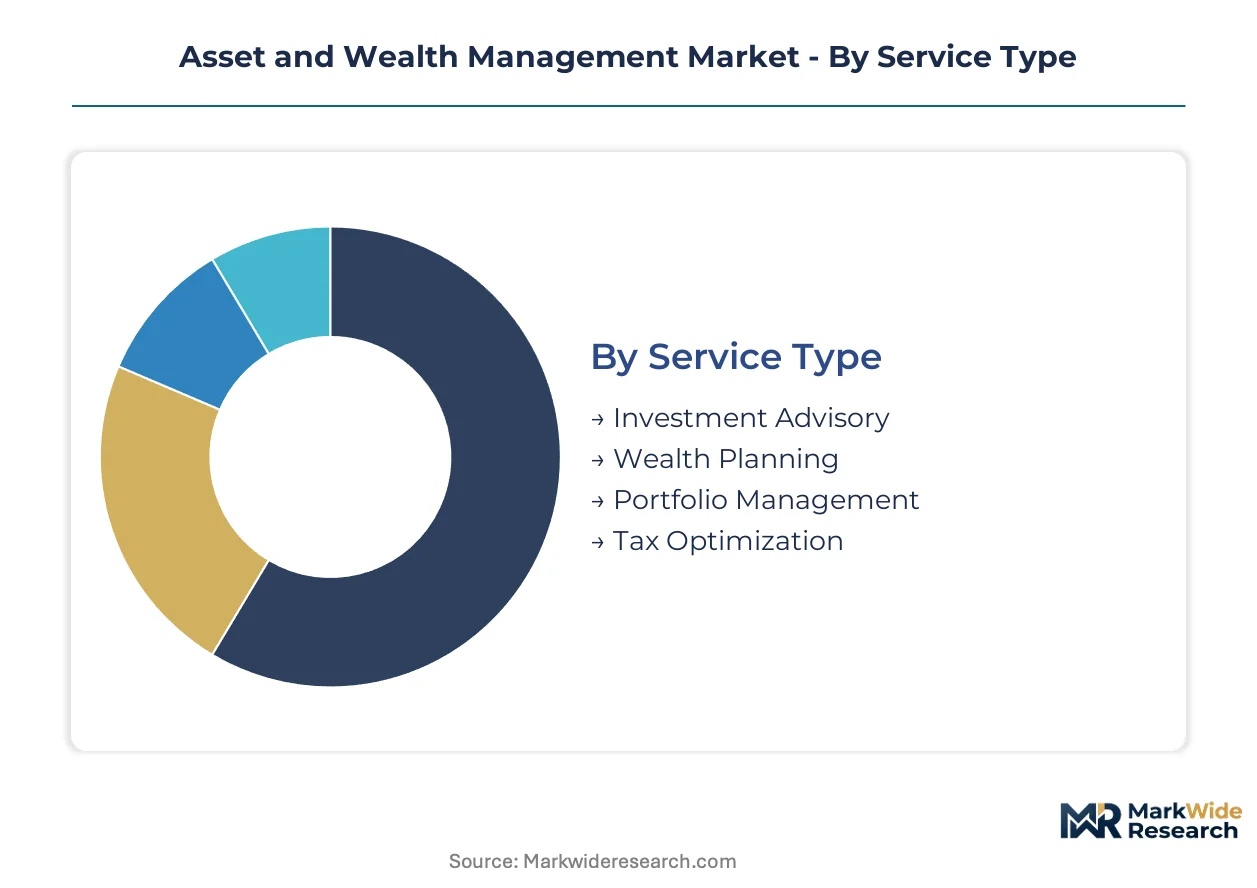
Asset and wealth management services fragment across client sophistication levels, regulatory complexity, and technology enablement. Understanding these divisions reveals where margin pools concentrate and which channels are capturing advisory relationship economics.
Service Type:
Cost tier determines how advisory firms structure compensation and where automation displaces labor-intensive delivery.
- Investment Advisory:Securities selection and suitability assessment delivered through fiduciary relationships. Demand concentrates among US institutional pension funds navigating ERISA guidance tightening, with fee compression forcing transparent outcome-based mandate structures.
- Wealth Planning:Integrated tax, estate, and intergenerational transfer strategies for complex balance sheets. North American family offices drive expansion as single-family and multi-family entities seek outsourced chief investment officer capabilities.
- Portfolio Management:Active rebalancing and risk-adjusted asset allocation across market cycles.
- Tax Optimization:Loss harvesting and jurisdictional structuring for after-return maximization.
Investment advisory holds installed capacity. Wealth planning is rotating up the share rankings.
Client Type:
Customer type maps directly to service customization depth and regulatory scrutiny intensity.
- High Net Worth Individuals:Personalized mandates requiring cross-border coordination and concentrated position management. UBS and comparable private banks capture sticky relationships through multi-licensed advisor networks spanning Switzerland, Singapore, and the United Kingdom.
- Institutions:Liability-driven investment frameworks governing pension and endowment allocations. US Department of Labor ERISA enforcement channels capital toward alternative asset classes with direct deal-sourcing capabilities.
- Retail Investors:Standardized products accessed through low-cost index vehicles and digital platforms.
- Family Offices:Consolidated reporting and direct private-market exposure for ultra-wealthy principals.
Institutions anchor current revenue. Family offices are climbing the fastest.
Distribution Channel:
Channel selection determines regulatory burden and client acquisition economics.
- Direct Sales:Proprietary relationship managers targeting ultra-high-net-worth segments. Vanguard Group leverages this channel for retail index fund dominance, bypassing intermediary cost layers.
- Online Platforms:Self-directed interfaces with algorithmic portfolio construction. BlackRock's Aladdin infrastructure enables mid-tier advisors to match institutional-grade risk analytics without proprietary development.
- Financial Advisors:Intermediary networks governed by SEC Investment Advisers Act suitability requirements.
- Institutional Brokers:Complex mandate negotiation for pension funds and sovereign wealth vehicles.
Institutional brokers command premium economics. Online platforms are gaining share fastest.
Investment Strategy:
Maturity and fee structure differentiate how capital owners deploy advisory relationships.
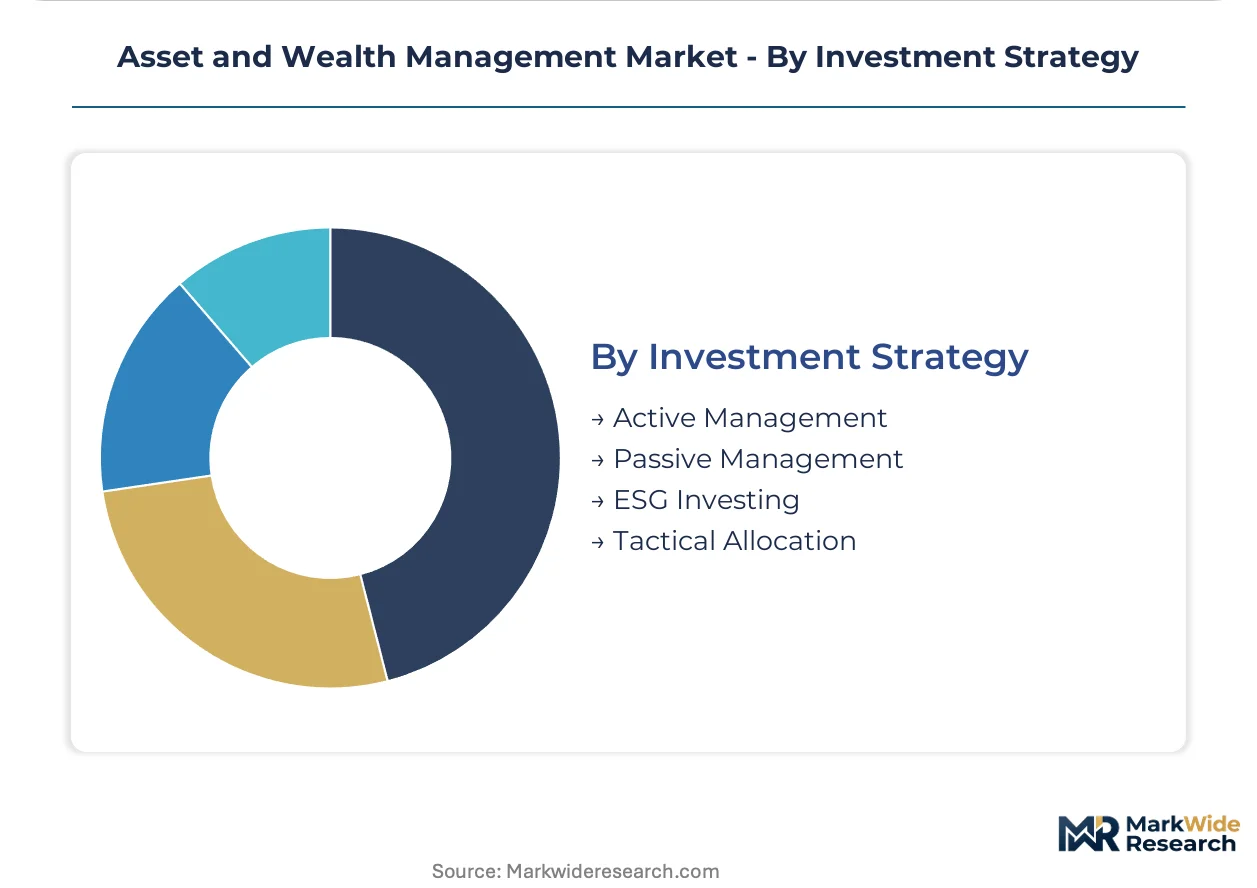
- Active Management:Security selection and tactical positioning seeking alpha generation. Fee compression at Vanguard Group and passive providers squeezes margins, though specialized alternative managers retain pricing power.
- Passive Management:Benchmark replication at minimal cost through index funds and ETFs. Retail migration toward these vehicles erodes traditional active advisory pools across North American and European markets.
- ESG Investing:Sustainability criteria embedded into mandate structures with verified scoring frameworks.
- Tactical Allocation:Short-term deviation from strategic benchmarks based on macro signals.
Passive management holds installed capacity. ESG investing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States exports portfolio construction expertise and risk analytics platforms while importing specialized alternative asset deal-sourcing capabilities from European and Asian centers. Switzerland and Singapore function as cross-border wealth planning hubs, channeling capital flows between jurisdictions. Germany and Japan anchor institutional asset management capacity within their respective regulatory spheres.
United States
Family offices in New York and California drive demand for outsourced chief investment officer services and direct private-market exposure. The SEC enforces fiduciary standards under the Investment Advisers Act, reshaping fee disclosure and product recommendation protocols for advisors serving American clients. Boston and Chicago clusters concentrate quantitative risk management talent serving institutional pension funds navigating ERISA guidance.
Switzerland
Ultra-high-net-worth individuals from emerging markets channel cross-border wealth planning demand through Geneva and Zurich private banking centers. FINMA applies prudential standards governing capital adequacy and risk management for systemically important institutions. The Zug crypto valley sub-cluster is attracting digital asset custody specialists expanding into tokenized securities infrastructure.
Singapore
Sovereign wealth funds and family offices headquartered in Southeast Asia expand allocations to infrastructure and private credit through Singapore-based managers. The Monetary Authority of Singapore licenses fund managers under variable capital company structures that optimize tax efficiency and regulatory flexibility. The Marina Bay financial district concentrates ESG scoring framework developers serving institutional mandates with sustainability criteria.
Germany
Insurance-linked asset managers and pension funds in Munich and Frankfurt seek liability-driven investment frameworks matching long-duration liabilities. BaFin implements MiFID II cost transparency requirements and suitability assessments that alter distribution economics across EU member states. The Frankfurt financial center hosts specialized infrastructure debt funds sourcing European green energy projects.
Japan
Government Pension Investment Fund reallocation drives demand for global equity and alternative asset specialists. The Financial Services Agency applies stewardship codes requiring institutional investors to engage actively with portfolio companies on governance and sustainability. Tokyo's Marunouchi district concentrates quantitative portfolio construction teams serving domestic insurers expanding overseas allocations.
Asset and Wealth Management Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in risk analytics and alternative asset deal-sourcing. The market structure concentrates around integrated giants with proprietary technology infrastructure, mid-tier advisors leveraging outsourced platforms, and boutique specialists in cross-border wealth planning. Three archetypes dominate: scale-driven index providers, technology-enabled platform operators, and relationship-centric private banks. Consolidation accelerates through technology acquisitions and advisor team lift-outs, while geographic expansion targets family office clusters in Singapore and Switzerland.
Among scale-driven asset managers, BlackRock and Vanguard Group exemplify divergent platform strategies—one leveraging institutional risk analytics infrastructure, the other dominating retail index fund distribution through direct channel control. UBS occupies a position within the ultra-high-net-worth tier, anchoring cross-border advisory relationships through multi-licensed networks spanning Switzerland, Singapore, and the United Kingdom.
| Leading Market Players |
|---|
| BlackRock |
| Vanguard Group |
| Fidelity Investments |
| State Street Global Advisors |
| JPMorgan Chase |
| UBS |
| Invesco |
| Charles Schwab Corporation |
| Amundi |
| Others |
Supply Flow & Price Mechanics
New York and London advisor clusters concentrate quantitative risk management talent and alternative asset deal-sourcing capabilities, creating tiered pricing power that separates institutional-grade mandates from retail-accessible products. Fee compression at scale-driven index providers feeds back into supply choices, forcing active managers toward specialized boutiques or platform-affiliated models.
Pricing Analysis
Institutional pension funds anchor pricing stratification across premium fiduciary advisory, standard wealth planning, and economy digital execution tiers. Price differentiation separates UBS-style cross-border wealth planning with multi-jurisdictional tax structuring from Vanguard's direct index fund distribution and BlackRock's Aladdin-powered risk analytics licensing. Cost compression in active management is intensifying because passive vehicle dominance erodes traditional advisory revenue pools. Retail investors through online platforms exhibit highest price sensitivity; ultra-high-net-worth family offices seeking outsourced chief investment officer services demonstrate lowest sensitivity.
Supply Chain Analysis
US Treasury and EU MiFID II regulatory restrictions on cross-border marketing limit how advisory services flow across jurisdictions. Supply concentrates in the United States, Switzerland, and Singapore as primary wealth management hubs. Raw material dependencies include certified financial analyst talent pipelines, proprietary risk analytics software licenses, and qualified custodian infrastructure. Single-source vulnerability sits with concentrated quantitative risk management expertise clustering in New York, London, and Singapore. Distribution runs through institutional brokers for complex mandates, direct sales for ultra-high-net-worth relationships, and online platforms for scalable retail access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asset and wealth management is approaching a platform-economics inflection where Aladdin-style risk analytics infrastructure and open-architecture outsourcing reshape competitive boundaries. Interoperability between proprietary technology stacks and third-party advisor tools determines which firms capture relationship economics.
For Market Incumbents: Pre-empt fee compression by consolidating advisor team lift-outs in Singapore and Switzerland family office clusters. Acquire specialized ESG scoring framework developers before institutional mandate flows harden around verified sustainability criteria. Platform-based outsourcing from BlackRock's Aladdin infrastructure represents the central threat; vertical integration into proprietary risk analytics preserves margin pools.
For New Entrants and Emerging Players: Establish a beachhead in North American multi-family office outsourcing where demand for direct private-market exposure and consolidated reporting exceeds incumbent capacity. Target mid-tier advisors seeking institutional-grade portfolio construction without proprietary technology development costs. Go-to-market through white-labeled risk analytics partnerships with established platform providers accelerates credibility.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among technology-enabled platform operators with sticky advisor relationships and multi-year Aladdin-style licensing contracts. Long-term viability across the analysis window favors firms with demonstrated cross-border regulatory navigation and multi-licensed advisor networks. Acquisition target archetype: boutique wealth planners with established ultra-high-net-worth relationships in Switzerland or Singapore. Watch for inflection when SEC custody rule proposals force smaller registered investment advisors toward platform affiliation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Aladdin infrastructure licensing enables mid-tier advisors to match institutional-grade risk analytics. |
| Acquisition of Specialist Firm | ESG scoring framework developers capture institutional flows embedding sustainability criteria. |
| Geographic Expansion | Singapore and Switzerland family office clusters concentrate outsourced chief investment officer demand. |
| Strategic Partnership | Multi-licensed advisor networks spanning Switzerland, Singapore, and the United Kingdom secure cross-border relationships. |
| Product Launch | Direct indexing platforms displace commingled funds for taxable investors seeking tax-loss harvesting. |
Methodological Framework
The analysis maps investment advisory, wealth planning, portfolio management, and tax optimization sub-sectors, each validated through chief investment officers at family offices, platform product managers at technology providers, and regulatory compliance leads at registered investment advisors. Primary interviews with these stakeholders combined with secondary validation from SEC Investment Advisers Act filings, FINMA prudential standards documentation, and Monetary Authority of Singapore licensing records. Bottom-up and top-down triangulation cross-checks advisor capacity estimates against platform-reported assets under administration.
Assumptions held fixed include prevailing SEC, FINMA, and Monetary Authority of Singapore regulatory frameworks; varied assumptions include alternative asset allocation rates and ESG mandate penetration curves. Segmentation dimensions modeled encompass service type, client sophistication tier, distribution channel, and investment strategy orientation across the projection horizon. CAGRs derive from reconciling historical advisor headcount growth with platform asset aggregation velocity, incorporating liability-driven investment framework adoption and direct indexing platform displacement effects.
Sensitivities concentrate around SEC custody rule implementation timelines and ERISA fiduciary guidance enforcement intensity. Forecasts reflect documented assumptions on regulatory stability and technology platform interoperability standards. Material shifts in cross-border marketing permissions or qualified custodian cybersecurity requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Capital Expenditure Market
Asset Management
India Mutual Fund Market
Asset Management
Fund Management Fee Market
Asset Management
Fund Management Software Market
Asset Management
APAC Mutual Fund Market
Asset Management
Global Infrastructure Asset Management Market
Asset Management
Asia-Pacific Utilities Asset Management Market
Asset Management
Japan Asset Management Market
Asset Management
India AMC Industry Market
Asset Management
Global Investment Management Software Market
Asset Management
Global Asset Performance Management Market
Asset Management
Pension Fund Management Software Market
Asset Management
UK Asset Management Market
Asset Management
Europe Asset Management Market
Asset Management
Mutual Fund Assets Market
Asset Management
Smart Asset Management Market