
 Fruit Beer Market | 2026-2036
Fruit Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Beer Market Analysis
Multi-pack variety bundling is expanding as the dominant packaging configuration, letting retailers and e-commerce platforms offer citrus, berry, and tropical assortments without committing to single-flavor case volumes. Founders Brewing Co. leverages its established barrel-aging infrastructure to anchor premium fruit-infused lines in Midwestern liquor stores. New Belgium Brewing Company competes through sustained investment in sour and wild-ale programs that occupy distinct shelf positions against mass-market alternatives. Lindemans Brewery differentiates by controlling traditional spontaneous fermentation methods that dominate Belgian-style fruit beer exports.
Fruit beer denotes an alcoholic beverage produced through fermentation of malted grains with fruit adjuncts, fruit purees, or whole fruit additions, typically yielding alcohol content between 2.5% and 8.0% ABV depending on base style and sugar conversion. The brewing process employs either kettle souring, mixed-culture fermentation, or traditional spontaneous inoculation to achieve tartness profiles that balance fruit sweetness against lactic or acetic acidity. Craft Fruit Beer and Hard Seltzer represent the most dynamic structural segments, with craft producers capturing margin pools through small-batch positioning while hard seltzer extends volume reach into convenience channels. Low Alcohol and Non-Alcoholic variants are gaining fastest within alcohol content tiers, reflecting formulation advances that preserve mouthfeel without ethanol contribution.
Regulatory frameworks from the FDA, TTB labeling requirements, and EU Food Information to Consumers Regulation shape ingredient disclosure, allergen declarations, and alcohol content accuracy standards that govern cross-border fruit beer commerce. REACH and FDA food-contact substance rules additionally constrain flavor additive sourcing and packaging material selection for imported fruit concentrates. Stakeholders must monitor evolving low-alcohol tax classifications and ingredient traceability mandates that determine which formulation paths preserve margin across multiple jurisdictions.
Market Dynamics
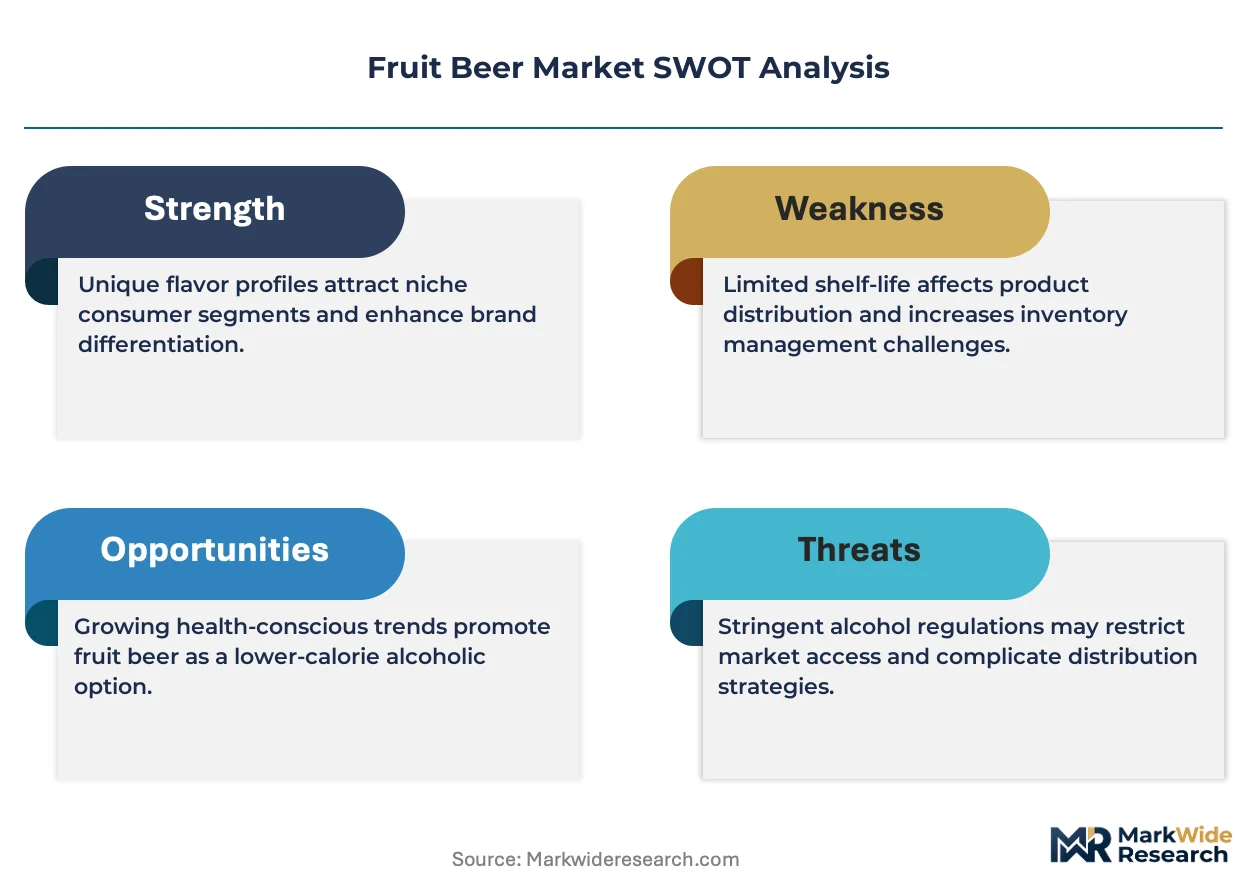
Reformulation pressures from evolving alcohol labeling mandates in the European Union and United States are forcing brewers to restructure ingredient sourcing and disclosure protocols, compressing margin structures while creating compliance-driven competitive separation between multinational and craft producers.
Growth Catalysts
- EU Food Information to Consumers Regulation:Mandatory ingredient disclosure requirements are accelerating transparency investments by Belgian lambic producers, converting compliance costs into premium positioning assets that justify sustained price premiums in export markets.
- Kettle souring adoption:Controlled lactic acid fermentation technology is enabling North American craft brewers to compress production cycles from months to weeks, expanding fruit beer capacity without traditional spontaneous fermentation infrastructure.
- Gastropub channel expansion:Premium draft rotation demand in United States, Germany, and Japan urban clusters is pulling fruit-forward lower-bitterness formulations into on-premise accounts previously dominated by conventional hop-forward styles.
Market Restraints
- Fruit concentrate supply concentration:Sourcing of tart cherry and raspberry purees concentrates in Eastern European processing hubs creates input cost volatility and seasonal availability constraints for kriek and framboise production lines.
- REACH compliance friction:Flavor additive and packaging material substance restrictions constrain cross-border formulation flexibility, requiring separate product variants for EU versus United States market access.
- Hard seltzer substitution:Flavored malt beverage alternatives in convenience channels capture volume-seeking consumers with lower price points and clearer calorie labeling, pressuring fruit beer trial conversion rates.
Strategic Opportunities
- Non-alcoholic formulation white space:Advances in arrested fermentation and dealcoholization processes are opening shelf-position opportunities in United States and German retail accounts where low-ABV tax classifications reduce price disadvantages.
- E-commerce variety bundling:Multi-pack citrus-berry-tropical assortments bypass single-flavor case commitments, unlocking direct-to-consumer channels previously inaccessible to small-batch regional producers.
- Spontaneous fermentation tourism:Belgian producers are converting traditional open-coolship facilities into experiential assets, capturing margin through on-site direct sales and subscription clubs that bypass wholesale distribution.
Industry Challenges
- Mixed-culture fermentation expertise scarcity:Brewers face extended training timelines for cellar operators managing Brettanomyces and Pediococcus populations, constraining quality consistency as production scales beyond pilot volumes.
- Barrel-aging capital intensity:Premium fruit-infused line expansion requires sustained investment in oak cooperage and climate-controlled warehouse capacity, compressing cash conversion cycles for mid-tier craft operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Beer Market |
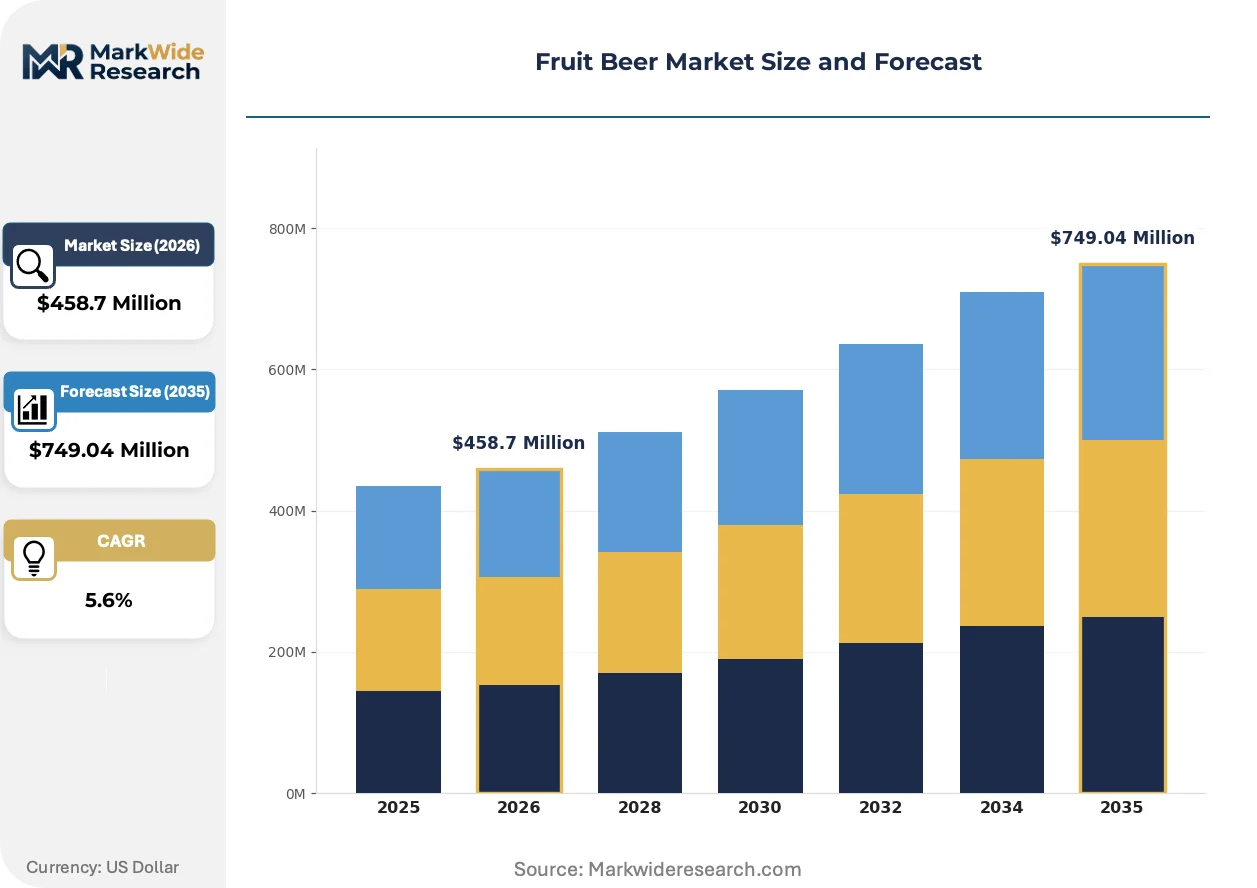
| Market Size in 2026 | $458.7 Million |
| Market Size in 2035 | $749.04 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Craft Fruit Beer, Cider, Malt Beverage, Hard Seltzer Flavor Profile: Citrus, Berry, Stone Fruit, Tropical Alcohol Content: Low Alcohol, Medium Alcohol, High Alcohol, Non-Alcoholic Distribution Channel: Supermarkets, Liquor Stores, Online Retail, Restaurants |
| Companies Covered | Jester King Brewery, Founders Brewing Co., The Boston Beer Company, Lindemans Brewery, New Belgium Brewing Company, New Glarus Brewing Company, Siren Craft Brew, Anchor Brewing, Allagash Brewing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Beer Market Emerging Trajectories
Active dry yeast strain development and precision fermentation controls are compressing traditional spontaneous production timelines while preserving flavor complexity, enabling craft producers to scale without sacrificing the tart-acid balance that defines category identity.
Precision fermentation technology is integrating DNA-sequenced yeast libraries with real-time metabolite monitoring to replicate spontaneous fermentation flavor profiles in controlled environments. Mid-sized craft breweries in Colorado and Oregon are adopting these systems to reduce batch-to-batch variation and accelerate new fruit variant prototyping. The technology is integrating quality assurance protocols previously exclusive to large-scale lager operations into sour and wild-ale production, narrowing the consistency gap between traditional and modern methods.
REACH substance restriction updates and FDA food-contact substance rule revisions are tightening flavor carrier and packaging liner compliance requirements for imported fruit concentrates. Brewers reformulating for dual-jurisdiction access are consolidating supplier relationships to reduce certification burden, favoring vertically integrated concentrate processors with established EU and United States regulatory documentation. Belgian and Dutch exporters face the most concentrated compliance timeline pressure as their traditional supply chains adapt to simultaneous disclosure mandates.
Multi-channel purchasing behavior is fragmenting fruit beer procurement across on-premise draft, specialty retail single-serve, and direct-to-consumer mixed-case subscriptions. Younger demographic cohorts in United States coastal cities and Tokyo metropolitan clusters are bypassing conventional liquor store discovery in favor of curated e-commerce platforms and brewery-managed membership programs. This rotation concentrates volume capture with producers investing in owned-channel data infrastructure rather than traditional wholesale distribution relationships.
Fruit Beer Market Segmentation
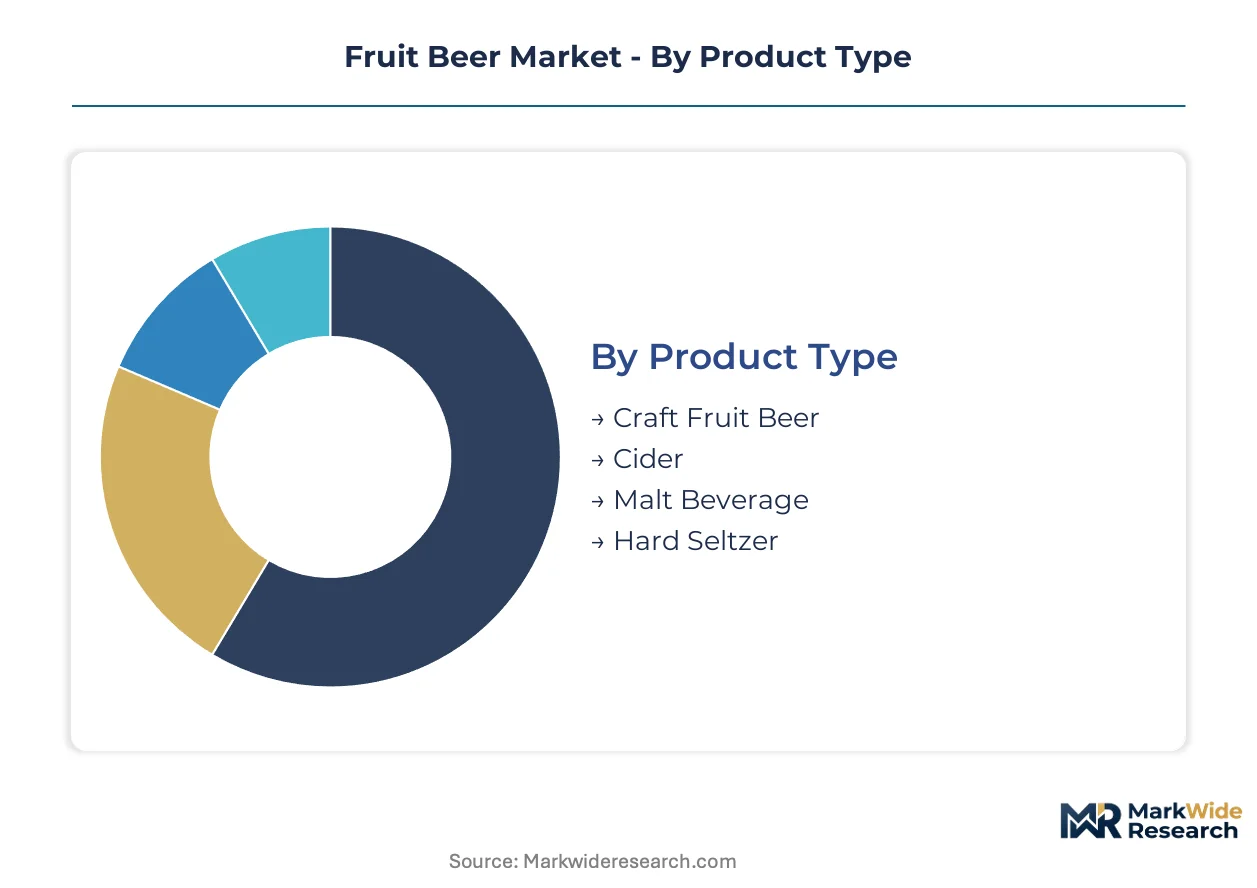
Fruit beer segmentation reflects divergent compliance burdens across formulation types and distribution pathways. Craft producers navigate stricter ingredient disclosure mandates than mass-market alternatives, while channel choice determines whether FDA food-contact rules or EU Food Information regulations dominate certification workflows.
Product Type:
Craft Fruit Beer carries the heaviest certification load through spontaneous fermentation documentation and barrel-aging facility inspections, while Hard Seltzer benefits from streamlined malt-beverage classifications in US TTB filings.
- Craft Fruit Beer:Small-batch production employing kettle souring or mixed-culture fermentation demands cellar-operator training protocols and Brettanomyces population monitoring. Demand concentrates in Belgian-style lambic exports and US Midwest barrel-aged programs where traditional methods justify price premiums.
- Hard Seltzer:Flavored malt beverage base simplifies regulatory pathway through existing TTB malt-beverage frameworks, though FDA food-contact substance rules still govern flavor carrier selection. Volume concentrates in US convenience channels where calorie transparency and lower price points capture trial-seeking consumers.
- Cider:Apple or pear-based fermentation falls under distinct tax classifications in EU member states and US federal codes, requiring separate compliance documentation from grain-based alternatives.
- Malt Beverage:Mass-market positioning leverages established supply chains for fruit concentrate sourcing, with REACH and FDA alignment determining cross-border formulation flexibility.
Hard Seltzer sits at the top of the volume ranking, with Craft Fruit Beer climbing the fastest.
Flavor Profile:
Raw material sourcing geography drives cost tier differentiation, with European tart cherry and raspberry concentrates commanding premium positioning against tropical fruit alternatives.
- Berry:Raspberry and blackberry purees anchor Belgian kriek and framboise traditions, with Eastern European processing hub concentration creating input volatility for craft producers.
- Citrus:Lemon, lime, and orange adjuncts integrate cleanly into kettle-soured bases, with US West Coast and Florida growing regions supplying concentrate processors with dual-jurisdiction certification documentation.
- Tropical:Mango, passionfruit, and pineapple purees expand fastest in e-commerce variety bundles targeting younger demographic cohorts in coastal cities.
- Stone Fruit:Peach and apricot formulations occupy mid-tier positioning between premium berry traditions and mass-market citrus accessibility.
Citrus dominates current volume share, with Tropical gaining share fastest among flavor investments.
Alcohol Content:
Tax classification thresholds reshape margin structures, with low-ABV designations in Germany and the United States reducing price disadvantages for arrested fermentation products.
- Low Alcohol:Dealcoholization and arrested fermentation advances preserve mouthfeel without ethanol contribution, opening shelf positions in German retail accounts where tax brackets favor sub-ABV thresholds.
- Non-Alcoholic:Precision fermentation controls and yeast strain development replicate tart-acid balance without alcohol generation, with US and German markets showing strongest retail acceptance.
- Medium Alcohol:Standard 4-6% ABV range captures gastropub draft rotation demand in urban clusters across the United States, Germany, and Japan.
- High Alcohol:Barrel-aged imperial variants target specialty retail and direct-to-consumer channels with extended aging timelines and oak cooperage capital requirements.
Medium Alcohol holds current volume leadership, with Non-Alcoholic showing steepest expansion trajectory.
Distribution Channel:
Channel selection determines data infrastructure investment requirements, with owned-channel membership programs capturing margin pools unavailable through wholesale relationships.
- Online Retail:Multi-pack variety bundling bypasses single-flavor case commitments, enabling direct-to-consumer reach for small-batch regional producers previously locked out of conventional distribution.
- Restaurants:Premium draft rotations in gastropubs and craft taprooms pull fruit-forward lower-bitterness formulations into on-premise accounts, with Belgian spontaneous fermentation tourism converting facilities into experiential assets.
- Supermarkets:Mass-market shelf placement demands compliance with EU Food Information to Consumers Regulation and FDA labeling mandates, favoring producers with consolidated supplier certification documentation.
- Liquor Stores:Single-serve and mixed-case configurations concentrate in specialty retail accounts where curated assortments compete against hard seltzer convenience channel substitution.
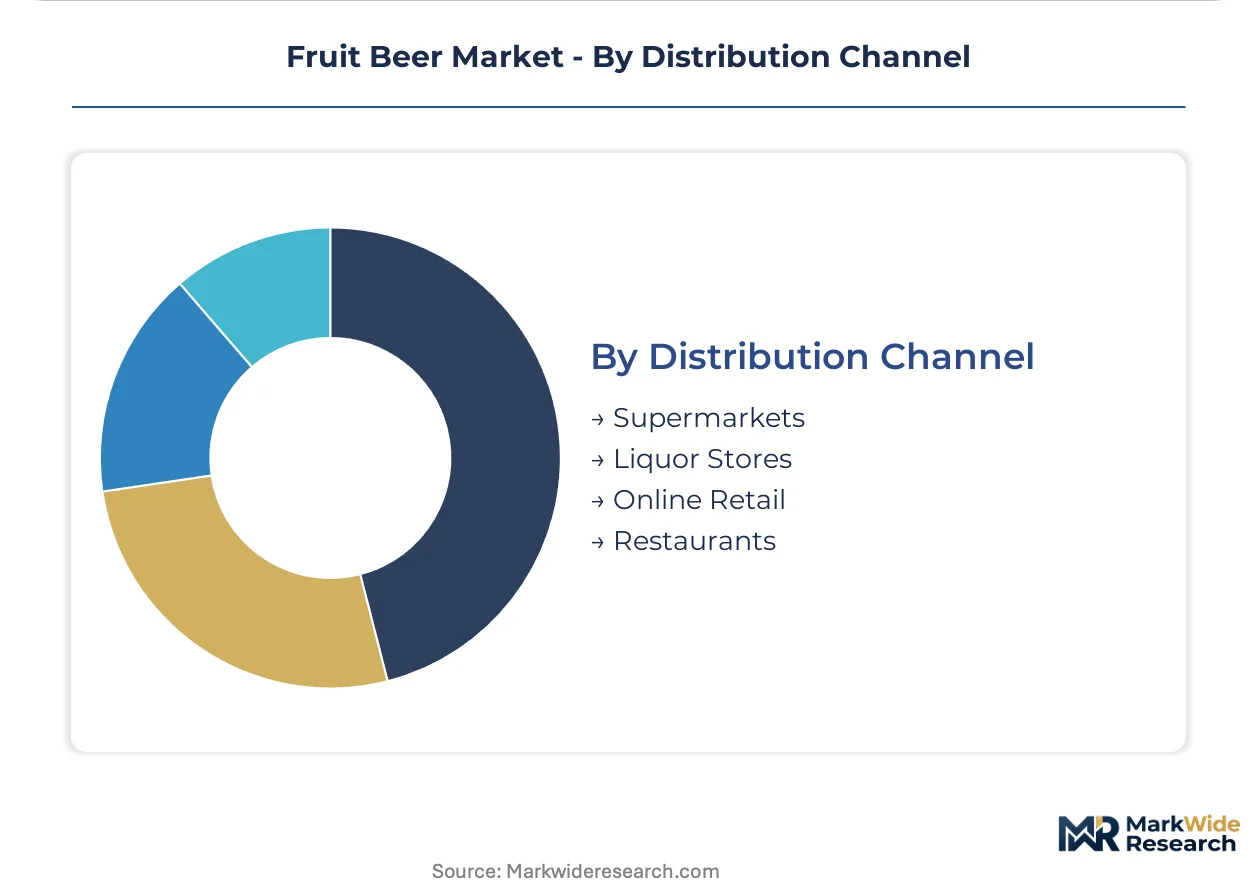
Supermarkets anchor current volume distribution, with Online Retail expanding most quickly through owned-channel data infrastructure investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium pioneered spontaneous fermentation methods that define premium fruit beer production, establishing brewing traditions that now anchor export demand across three continents. Contemporary market expansion concentrates in urban gastropub clusters where craft taprooms reinterpret these heritage techniques for local palates.
Belgium
Pajottenland's lambic producers command sustained export premiums through traditional open-coolship spontaneous fermentation. ECHA REACH substance restrictions on flavor carriers and packaging materials compress margin structures for concentrate-dependent brewers. Brussels and surrounding Flemish communes concentrate barrel-aging cooperage and direct-to-consumer tourism infrastructure.
United States
Midwestern liquor stores and coastal gastropub rotations pull kettle-soured fruit formulations into mainstream distribution. FDA food-contact substance rules and TTB malt-beverage labeling mandates shape reformulation investments for cross-state commerce. Michigan, Colorado, and Oregon cluster craft production capacity where precision fermentation technology adoption accelerates batch consistency.
Germany
Bavarian and North Rhine-Westphalia retail accounts favor low-alcohol variants where tax bracket thresholds reduce price disadvantages. EU Food Information to Consumers Regulation mandates accelerate transparency investments by importers of Belgian spontaneous fermentation products. Berlin and Munich urban taprooms expand draft rotations beyond Reinheitsgebot-traditional styles.
Japan
Tokyo metropolitan clusters concentrate gastropub demand for lower-bitterness fruit-forward formulations. METI standards alignment with EU disclosure protocols simplifies concentrate import certification for Flanders-origin producers. Osaka and Nagoya specialty retail channels curate Belgian import assortments alongside domestic craft kettle-soured alternatives.
United Kingdom
London and Southeast England gastropub networks drive premium draft rotation demand for berry-profiled kettle sours. Post-EU regulatory divergence on food-contact substance rules creates parallel certification tracks for concentrate processors serving UK versus continental accounts. Scottish craft producers leverage local fruit sourcing to differentiate against import-dependent competitors.
Fruit Beer Market Vendor Landscape
The competitive structure tilts toward heritage-method specialists and technology-enabled craft scale-ups rather than mass-market malt-beverage conglomerates. Belgian spontaneous fermentation houses occupy premium price tiers through controlled scarcity and export quota management. North American kettle-sour adopters compress production cycles to capture gastropub draft rotations. Strategic moves concentrate on barrel-aging capacity expansion and direct-to-consumer membership program development.
Among heritage-method specialists, Lindemans Brewery represents the archetype of spontaneous fermentation control that justifies sustained export premiums. Founders Brewing Co. and New Belgium Brewing Company exemplify North American craft scale-ups leveraging barrel-aging infrastructure and sour program investment to occupy distinct shelf positions. These three anchors illustrate the bifurcation between European tradition-preservation and New World technology-adoption competitive vectors.
| Leading Market Players |
|---|
| Jester King Brewery |
| Founders Brewing Co. |
| The Boston Beer Company |
| Lindemans Brewery |
| New Belgium Brewing Company |
| New Glarus Brewing Company |
| Siren Craft Brew |
| Anchor Brewing |
| Allagash Brewing Company |
| Others |
Supply Flow & Price Mechanics
Eastern European tart cherry and raspberry concentrate price indices cascade through Belgian lambic and kriek production tiers, compressing margins at craft scale while amplifying premium positioning power for spontaneous fermentation specialists with captive fruit sourcing contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates barrel-aged spontaneous fermentation releases from kettle-soured craft variants and mass-market malt beverage alternatives. Price differentiation hinges on certification documentation depth and traditional method provenance. Cost compression in mid-tier craft kettle sours is intensifying because hard seltzer alternatives capture trial-seeking consumers at lower price points. Mass-market malt beverage buyers exhibit highest price sensitivity; Belgian heritage-method collectors show least.
Supply Chain Analysis
Return flows of oak cooperage for refurbishment and remanufacturing anchor circular supply chain economics for barrel-aging programs. Fruit concentrate sourcing draws from Poland, Serbia, and Hungary for tart cherry and raspberry purees, with Florida and California supplying citrus adjuncts. Single-source vulnerability concentrates in Eastern European processing hubs exposed to seasonal harvest volatility. Distribution runs through wholesaler relationships for conventional retail, with direct-to-consumer membership programs bypassing traditional three-tier systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fruit beer has entered a late-cycle quality phase where consumer willingness-to-pay concentrates on heritage-method authenticity and transparent ingredient provenance rather than novelty flavor extensions.
For Market Incumbents: Anticipate hard seltzer substitution pressure by deepening barrel-aging infrastructure investments that create irreplicable flavor complexity. Secure captive supply contracts with Eastern European concentrate processors to defend input cost position against tariff exposure. Prioritize spontaneous fermentation tourism facility upgrades that convert production sites into experiential margin pools. For New Entrants and Emerging Players: Launch via e-commerce variety bundling platforms that bypass wholesaler gatekeeping and capture direct consumer relationship data. Target non-alcoholic formulation white space in German and United States retail accounts where tax bracket advantages reduce price disadvantages. Emphasize arrested fermentation technology partnerships as go-to-market differentiator against established craft scale-ups. For Investors and Strategic Acquirers: Consolidation pressure builds where barrel-aging capital intensity outstrips mid-tier craft cash conversion capacity. Five-to-ten year viability favors heritage-method specialists with export quota management discipline and owned-channel subscription infrastructure. Monitor Belgian spontaneous fermentation house succession planning and generational ownership transitions as inflection signal for premium asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Barrel-Aging Capacity Expansion | Founders Brewing Co. leverages existing cooperage infrastructure to anchor premium fruit-infused line positioning. |
| Direct-to-Consumer Membership Launch | New Belgium Brewing Company captures consumer data and margin pools unavailable through wholesale distribution relationships. |
| Spontaneous Fermentation Tourism Development | Lindemans Brewery converts Pajottenland production facilities into experiential assets with on-site direct sales. |
| Non-Alcoholic Formulation Investment | Arrested fermentation technology partnerships open German retail shelf positions with favorable tax classifications. |
| Concentrate Processor Backward Integration | Vertical control over Eastern European tart cherry sourcing defends against seasonal availability volatility. |
Methodological Framework
Multiple input streams — primary interviews with craft brewery cellar operators, regulatory affairs specialists at concentrate processors, and gastropub beverage directors; secondary validation through TTB labeling guidance documents, EU Food Information to Consumers Regulation filings, and customs trade data for fruit concentrate imports — were reconciled through bottom-up production volume modeling and top-down expenditure flow triangulation.
Historical volume trajectories were cross-referenced against panel input from brewery expansion planners and distributor category managers. The analytical framework segments across product type, flavor profile, alcohol content tier, and distribution channel throughout the forecast period. CAGRs were derived from elasticity-adjusted adoption curves incorporating kettle souring technology diffusion rates and spontaneous fermentation export quota constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under REACH substance restriction acceleration or hard seltzer formulation advances that replicate fruit beer flavor profiles at lower price points. Practitioners should monitor Belgian generational ownership transitions, FDA food-contact rule revision timelines, and arrested fermentation technology licensing activity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Germany Alcohol E-Commerce Market
Alcoholic Beverages
Rose Wine Market
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Hookah Charcoal Market
Alcoholic Beverages
Japanese Whisky Market
Alcoholic Beverages
Distillers Malt Market
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
Wine Fermentation Equipment Market
Alcoholic Beverages
Wine Cork Market
Alcoholic Beverages
Cannabis Drinks Market
Alcoholic Beverages
Australia Alcohol E-Commerce Market
Alcoholic Beverages
F-Style Jugs Market
Alcoholic Beverages
United States Beer Market
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
Pinot Noir Market
Alcoholic Beverages
North America Tequila Market