
 North America Tequila Market | 2026-2036
North America Tequila Market Size, Share, and Industry Trends Forecast 2026-2036
North America Tequila Market Insights
Jalisco's blue weber agave belt is expanding cultivation acreage to meet sustained North American demand. Diageo PLC leverages its vertical integration from agave fields to bottling facilities across the region. Constellation Brands Inc anchors its position through dedicated premium tequila portfolios in the United States. A. Becle S.A.B. de C.V. competes with heritage-driven positioning and distillery-controlled supply chains.
Tequila denotes a distilled spirit produced exclusively from blue weber agave in five designated Mexican states, with fermentation yielding alcohol content between 35% and 55% by volume. Blanco expressions lead volume throughput due to shorter production cycles and lower barrel inventory requirements. Reposado and añejo categories capture disproportionate margin pools as aged stock commands premium positioning in retail stores and on-premise bars. Extra añejo remains the smallest product type by volume but occupies the highest price tier across duty-free shops and specialized online platforms.
The Alcohol and Tobacco Tax and Trade Bureau (TTB) enforces labeling standards that govern "tequila" designation claims in United States commerce, while Mexico's Consejo Regulador del Tequila (CRT) oversees appellation compliance for export-bound production. These dual frameworks shape market access by restricting supply to certified distilleries and mandating geographic origin verification. Stakeholders must monitor agave harvest cycles and regulatory enforcement intensity as structural constraints on raw material availability intensify.
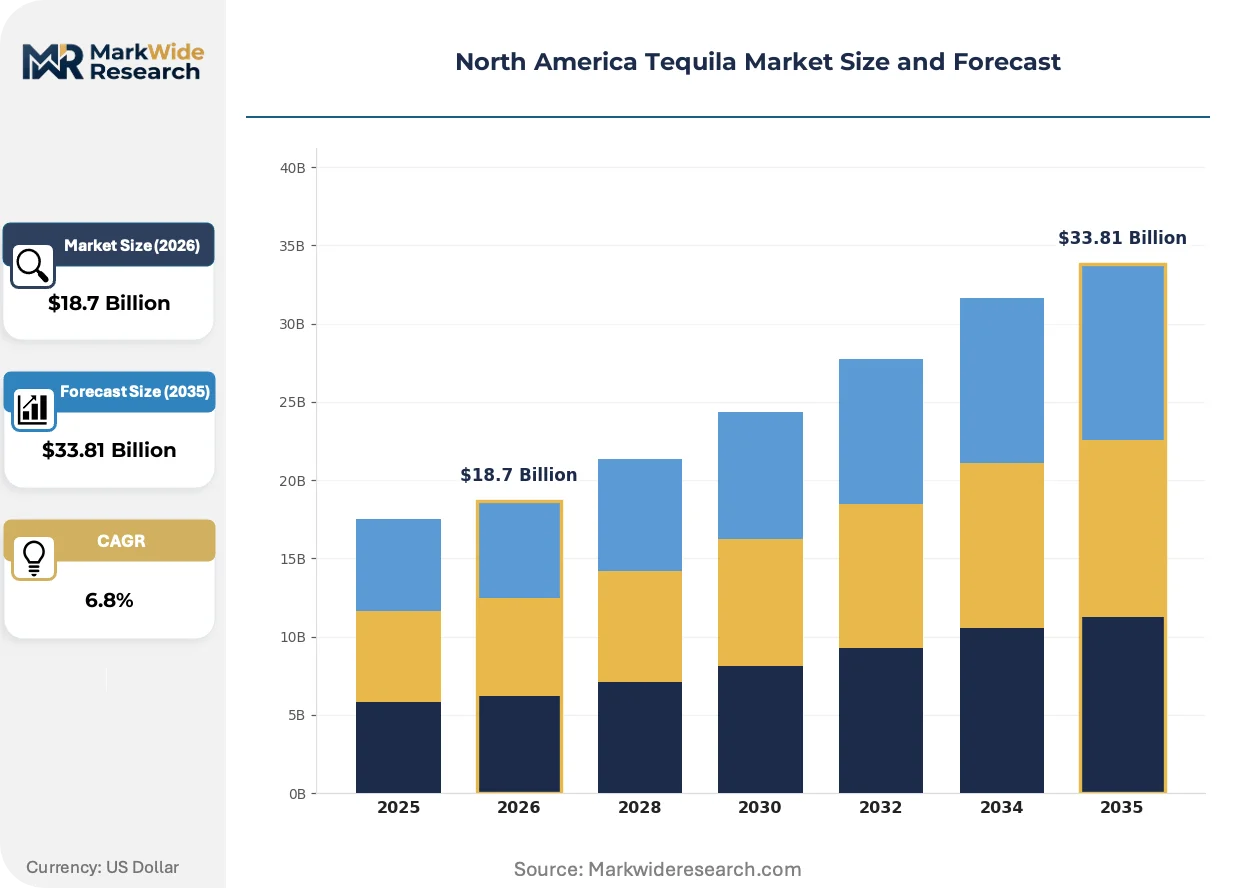
Market Dynamics
The North America tequila market is experiencing acute supply-side pressure as Jalisco's blue weber agave cultivation cycles create seven-to-ten-year inventory mismatches against millennial consumption surges in Texas and California metropolitan corridors.
Growth Catalysts
- CRT Export Certification:Mexico's Consejo Regulador del Tequila tightened geographic origin verification, channeling demand toward certified distilleries and locking out non-compliant suppliers from US distribution networks.
- On-Premise Premiumization:Texas and California cocktail bars expanded aged-tequila backbar allocations, pulling reposado and añejo volumes into higher-margin rotation.
- Agave Cultivation Technology:Drip irrigation and soil-monitoring systems in Jalisco's highlands are compressing plant maturation timelines and stabilizing raw material flow to bottling facilities.
Market Restraints
- Agave Price Volatility:Blue weber agave spot markets swing with harvest cycle timing, forcing distilleries to absorb margin compression or pass through cost spikes to wholesale buyers.
- Dual Regulatory Overlap:The TTB's spirits labeling standards and CRT's appellation rules create compliance friction for cross-border shipments, delaying product launches and increasing certification overhead.
- Substitute Spirit Competition:Mezcal and American whiskey producers target the same premium on-premise accounts, fragmenting bartender attention and backbar shelf space.
Strategic Opportunities
- Direct-to-Consumer Channels:Specialized online platforms bypass three-tier distribution constraints, enabling extra añejo producers to capture full retail margin from collectors in southwestern US states.
- TTB Label Modernization:Updated spirits labeling standards create openings for additive-free and terroir-specific claims that differentiate premium portfolios in retail stores.
- Metropolitan Mexico City Corridors:Underpenetrated high-income neighborhoods present volume expansion potential for heritage-positioned brands with distillery-controlled supply chains.
Industry Challenges
- Master Distiller Scarcity:Traditional tahona stone milling and wood-fired roasting expertise concentrates among aging specialists in Jalisco, constraining quality-scaled production expansion.
- Barrel Inventory Financing:Reposado and añejo categories require multi-year oak cask commitments that tie up working capital during agave cost spikes, squeezing mid-tier distilleries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Tequila Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blanco, Reposado, Añejo, Extra Añejo Packaging Type: Glass Bottle, Plastic Bottle, Cask, Can Distribution Channel: Retail Stores, Bars, Online Platforms, Duty-Free Shops Customer Type: Millennials, Gen X, Baby Boomers, Trendsetters |
| Companies Covered | Brown-Forman Corporation, Campari Group, Constellation Brands Inc, Heaven Hill Distilleries Inc, Sazerac Company Inc, Diageo PLC, Pernod Ricard, A. Becle S.A.B. de C.V., Bacardi and Company Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Tequila Market Trends and Innovations
Tequila production is rewiring around precision agriculture and regulatory data transparency, with distillery operators investing in traceability infrastructure to satisfy both certification bodies and premium buyer scrutiny.
Hyperspectral imaging and drone-mounted sensors deployed across Jalisco's blue weber agave belt are rewriting harvest prediction accuracy. Large distilleries with captive highland fields now model sugar content remotely, reducing manual jimador labor dependency and compressing decision-to-distillation timelines. This capability is enabling just-in-time agave procurement that buffers against spot market volatility.
The TTB's updated spirits labeling standards are forcing additive disclosure and production-method transparency across all US-bound shipments. Distilleries must now document diffuser versus tahona crushing, autoclave versus horno roasting, and glycerin or caramel coloring use. Small-batch producers with traditional methods are leveraging this friction to attack mass-market brands in Texas and California retail accounts.
Collector behavior in southwestern US states is rotating toward single-estate and vintage-dated expressions, displacing undifferentiated premium blanco volume. Duty-free shops and specialized online platforms are responding with allocated release calendars and blockchain-backed provenance verification. This preference shift is most visible in California's Bay Area and Austin's metropolitan corridor, where restaurant buyers now specify agave field coordinates on cocktail menus.
North America Tequila Market Segmentation
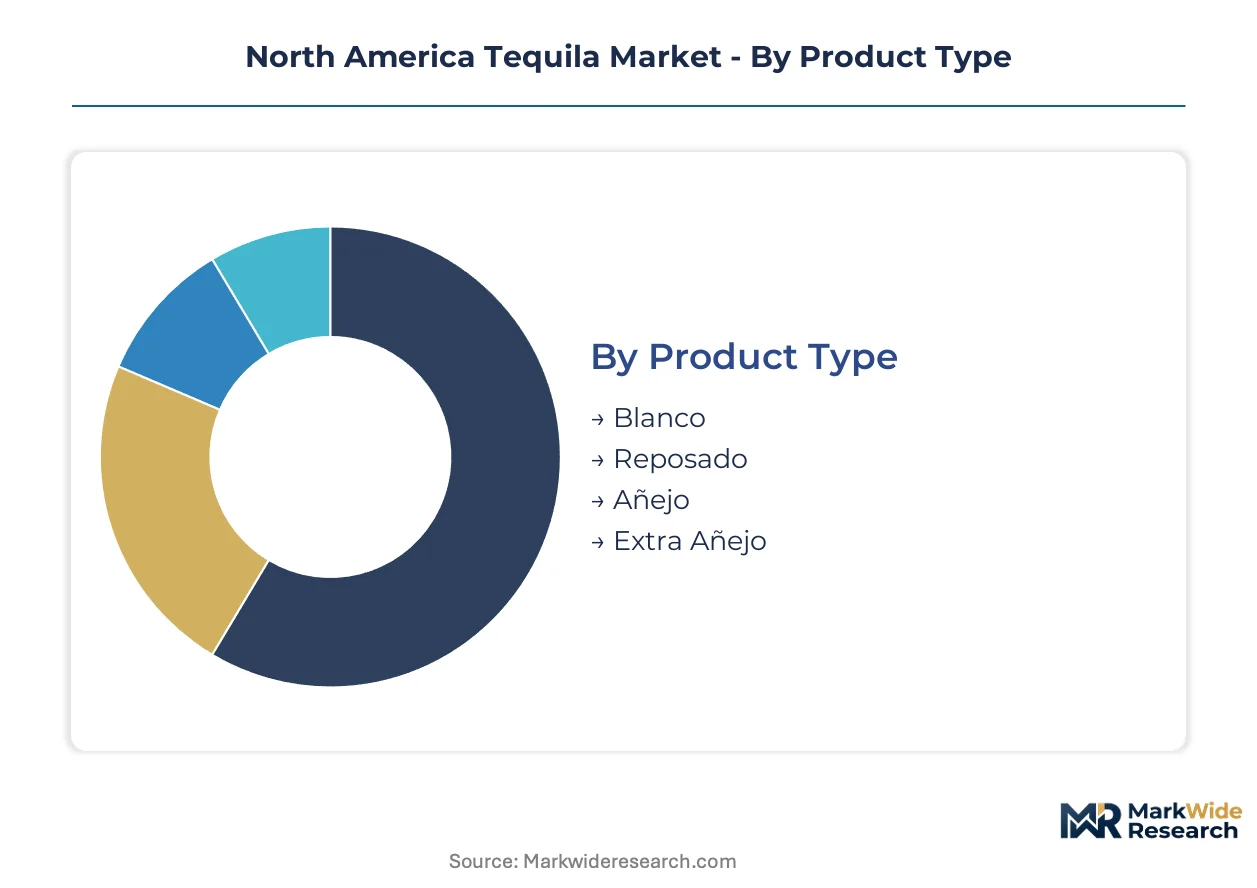
Tequila producers navigate four distinct segmentation dimensions that shape portfolio construction and margin capture. Product type determines production cycle length and barrel inventory requirements, while packaging and channel choices dictate access to premium buyer segments across Texas and California metropolitan corridors.
Product Type:
Volume throughput concentrates in unaged expressions, yet margin pools accumulate disproportionately in barrel-aged categories that command extended production timelines.
- Blanco:Unaged spirit bottled directly after distillation preserves the raw vegetal character of blue weber agave. Texas and California on-premise accounts rotate blanco heavily in cocktail programs where speed of service and ingredient cost control dominate purchasing decisions.
- Reposado:Two-to-twelve month oak rest mellows the spirit while retaining agave-forward brightness. California's Bay Area cocktail bars have expanded reposado backbar allocations, pulling this category into higher-margin rotation as bartenders specify field coordinates on menus.
- Añejo:One-to-three year cask maturation develops caramel and vanilla complexity through extended oak contact.
- Extra Añejo:Minimum three-year aging requirement creates the smallest volume tier but occupies peak price positioning in duty-free shops and specialized online platforms.
Today's leader: Blanco. Tomorrow's challenger: Reposado.
Packaging Type:
Material selection signals quality tier to buyers while constraining logistics flexibility and shelf-life performance.
- Glass Bottle:Dominant premium format across retail stores and on-premise accounts, with weight and closure design communicating heritage positioning. Southwestern US states show particular sensitivity to bottle aesthetics in gifting occasions.
- Plastic Bottle:Value-tier format enabling price penetration in high-volume Mexican retail channels and border-state convenience stores where breakage risk and transportation cost dominate procurement criteria.
- Cask:Bulk format for on-premise barrel programs and private label bottling, common in Texas steakhouse chains.
- Can:Emerging ready-to-drink format capturing trial among younger demographics in outdoor recreation settings.
Glass commands shelf presence. Cans are climbing the fastest as format experimentation accelerates.
Distribution Channel:
Channel selection determines margin retention, regulatory exposure, and buyer relationship depth across the three-tier system.
- Retail Stores:Primary volume channel for blanco and standard reposado, with shelf placement fees and promotional calendars shaping competitive outcomes in California and Texas liquor chains.
- Bars:On-premise accounts drive aged-tequila discovery through backbar visibility and cocktail menu integration, particularly in Austin's metropolitan corridor where agave spirits command dedicated program space.
- Online Platforms:Direct-to-consumer and specialized retailer sites bypass distribution tier constraints, enabling extra añejo producers to capture full retail margin from collectors.
- Duty-Free Shops:Allocated release calendars and limited editions target international travelers with compressed purchase decision windows.
Bars build brand equity. Online platforms are expanding most quickly as regulatory adaptation proceeds.
Customer Type:
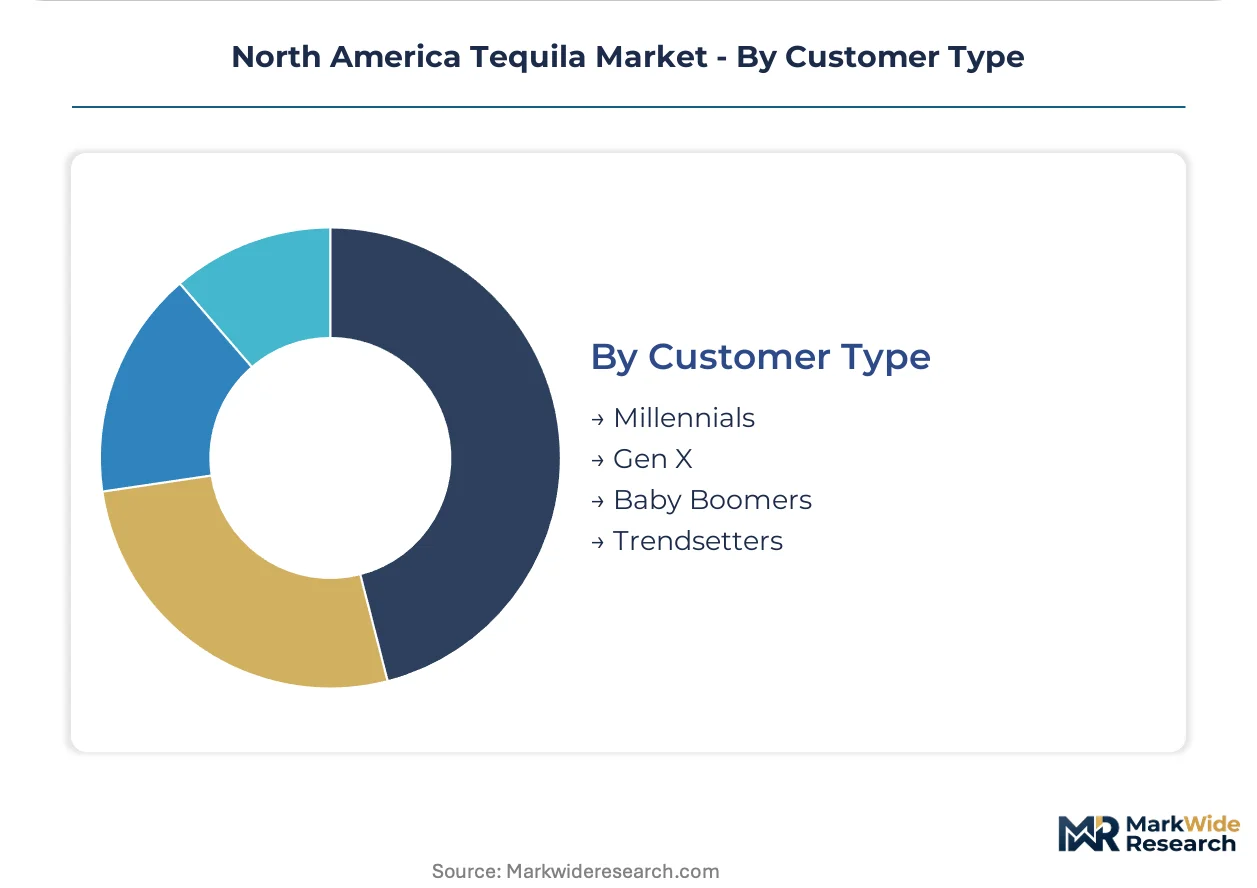
Generational cohorts exhibit divergent price elasticity, occasion patterns, and information-seeking behaviors that reshape marketing investment allocation.
- Millennials:Core volume driver concentrated in Texas and California metropolitan corridors, displaying high willingness to pay for additive-free claims and production-method transparency verified through QR-linked traceability.
- Gen X:Established premium buyers with stable brand loyalties and lower sensitivity to social media discovery, over-indexing in suburban retail purchases for home consumption.
- Baby Boomers:Heritage-focused segment favoring established distillery names and traditional production claims, with purchasing concentrated in gift-giving occasions.
- Trendsetters:Opinion-leading minority driving menu and social media conversation, demanding single-estate provenance and vintage dating as table stakes for engagement.
Millennials anchor volume growth. Trendsetters dictate tomorrow's premium specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics reshape production geography as distilleries migrate toward jurisdictions with favorable compliance-cost structures. The TTB's labeling standards and CRT's appellation rules create divergent cost burdens that influence facility siting decisions across the continent.
United States
Texas and California metropolitan corridors concentrate millennial consumption, with Austin and Los Angeles driving premium on-premise demand. The TTB enforces spirits labeling standards that mandate additive disclosure and production-method documentation for all US-bound tequila shipments. Jalisco-certified distilleries maintain dedicated bottling lines in Houston and San Diego to compress cross-border logistics timelines.
Mexico
Jalisco's blue weber agave belt anchors raw material supply, with highland cultivation expanding under drip irrigation and soil-monitoring systems. The CRT tightened geographic origin verification protocols, channeling export demand toward certified distilleries and locking out non-compliant suppliers. Mexico City corridors present underpenetrated volume expansion potential for heritage-positioned brands with distillery-controlled supply chains.
Canada
Ontario and British Columbia liquor boards govern provincial distribution through centralized procurement systems that favor established premium portfolios. Health Canada maintains additive disclosure requirements that align with TTB transparency mandates, reducing regulatory friction for US-compliant shipments. Toronto's metropolitan area exhibits concentrated demand for extra añejo expressions through specialized online platforms and duty-free channels.
North America Tequila Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue additive-free and single-estate positioning to differentiate. The market structures around heritage distillers with Jalisco appellation rights, multinational spirits conglomerates with captive distribution networks, and boutique operators leveraging direct-to-consumer channels. Three archetypes dominate: vertically integrated agave-field-to-bottle operators, portfolio-diversified beverage conglomerates, and terroir-focused craft specialists. Competitive moves concentrate on strategic partnerships with on-premise accounts and capacity expansion in highland Jalisco cultivation zones.
Within the multinational tier, Diageo PLC and Constellation Brands Inc exemplify scale-driven positioning through dedicated premium tequila portfolios and captive US distribution infrastructure. A. Becle S.A.B. de C.V. occupies a heritage-focused position with distillery-controlled supply chains and CRT-certified export capabilities. These three entities anchor competitive dynamics across retail stores, on-premise bars, and specialized online platforms throughout the southwestern United States and metropolitan Mexico City corridors.
| Leading Market Players |
|---|
| Brown-Forman Corporation |
| Campari Group |
| Constellation Brands Inc |
| Heaven Hill Distilleries Inc |
| Sazerac Company Inc |
| Diageo PLC |
| Pernod Ricard |
| A. Becle S.A.B. de C.V. |
| Bacardi and Company Ltd |
| Others |
Pricing and Supply Chain Analysis
Hyperspectral imaging and drone-mounted sensors deployed across Jalisco's blue weber agave belt are compressing decision-to-distillation timelines while simultaneously redistributing cost economics toward large distilleries with captive highland fields. This technological transition concentrates pricing power among vertically integrated operators capable of just-in-time agave procurement that buffers against spot market volatility.
Pricing Analysis
Distributor margin layers in the three-tier system absorb the steepest compression during agave cost spikes, forcing mid-tier distilleries to choose between margin sacrifice and wholesale price increases. Three-tier pricing structure across premium, standard, and economy levels stratifies around barrel inventory depth, with extra añejo commanding peak positioning through multi-year oak commitments. Price differentiation hinges on CRT certification status and additive-free production documentation, with millennial buyers in Texas and California metropolitan corridors showing lowest price sensitivity for heritage-positioned expressions. Pricing pressure stems from seven-to-ten-year agave harvest cycles that misalign raw material costs against consumption surges.
Supply Chain Analysis
Single-source vulnerability sits with Jalisco's blue weber agave belt, where highland cultivation zones supply the vast majority of North American demand. Raw material flows draw from Mexico's five designated tequila states, with oak cask sourcing tethered to American and Spanish cooperage networks. Supply chain risk centers on regulatory restriction from overlapping TTB and CRT compliance frameworks that delay cross-border shipments. Distribution runs through dedicated bottling facilities in Houston and San Diego that compress logistics timelines for US-bound volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
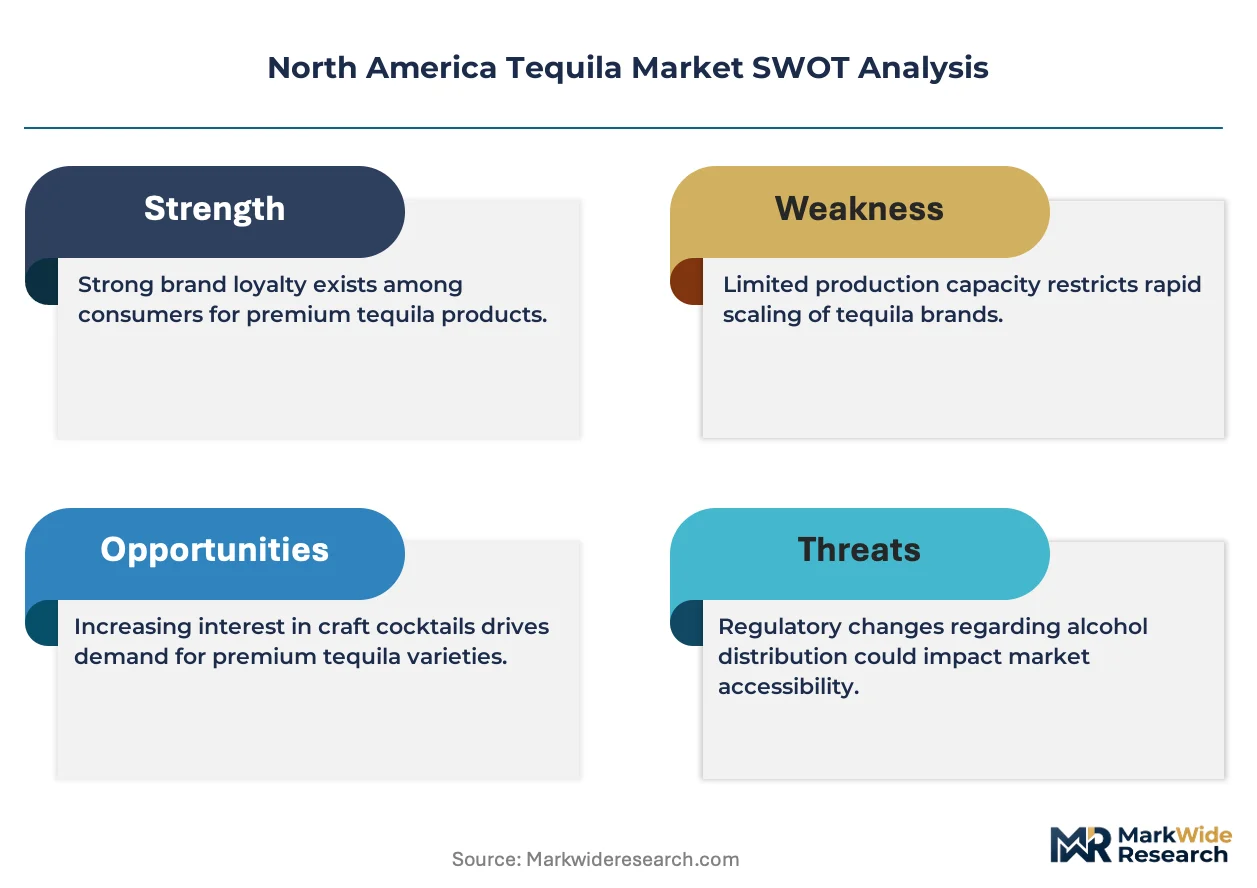
The North America tequila market functions as a regulatory compounder, where the TTB's updated spirits labeling standards and CRT's tightened geographic origin verification are accelerating demand concentration toward certified distilleries with full production-method transparency.
For Market Incumbents: Extend additive-free portfolio lines to capture millennial willingness-to-pay premium, while securing long-term oak cask commitments before interest rate pressure intensifies working capital demands. Lock in exclusive backbar allocations with Texas and California cocktail bars before mezcal producers fragment on-premise shelf space. Prioritize certification investment in CRT export credentials to maintain US distribution network access against tightening compliance thresholds. For New Entrants and Emerging Players: Enter via direct-to-consumer channels targeting extra añejo collectors in southwestern US states, where three-tier distribution constraints create margin capture opportunities for specialized online platforms. Mexico City corridors present underpenetrated volume expansion potential for heritage-positioned brands with distillery-controlled supply chains. Lead with single-estate provenance and vintage dating as table stakes for trendsetter engagement in Austin and Los Angeles metropolitan areas. For Investors and Strategic Acquirers: Roll-up economics work for boutique distilleries with CRT-certified export capabilities and captive highland agave fields because regulatory barriers are locking out non-compliant suppliers from US distribution networks. Target acquisition archetypes include terroir-focused craft specialists with established tahona stone milling expertise and existing direct-to-consumer infrastructure. Watch agave spot market volatility as the inflection indicator for distressed asset availability among working-capital-constrained mid-tier producers.| Strategic Initiative | Industry Significance |
|---|---|
| Additive-Free Certification Investment | TTB labeling standards reward transparency with millennial premium capture in Texas and California. |
| Direct-to-Consumer Channel Launch | Specialized online platforms bypass three-tier constraints for extra añejo margin retention. |
| Highland Agave Field Acquisition | Captive supply buffers against harvest cycle volatility and spot market price spikes. |
| Master Distiller Talent Retention | Traditional tahona expertise concentrates among aging specialists in Jalisco highlands. |
| On-Premise Backbar Partnership | Austin and Los Angeles cocktail bars drive aged-tequila discovery through menu integration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with distillery operators, CRT certification officers, Texas and California liquor chain category buyers, on-premise bar program directors, and agave cultivation specialists with secondary validation. Customs records, TTB spirits labeling filings, CRT export certification databases, and retail audit data from Nielsen and Circana anchored bottom-up volume estimation. Top-down triangulation against macroeconomic indicators ensured cross-method consistency.
Segment-weighting approaches modeled product type, packaging format, distribution channel, and customer cohort dimensions across the projection horizon. CAGRs derived from historical volume trajectories, regulatory enforcement intensity assumptions, and generational consumption pattern shifts. Agave harvest cycle timing, drip irrigation adoption curves, and master distiller labor availability fed industry-specific forecast inputs.
Inputs from CRT certification databases and TTB labeling filings were available through the study window; gaps in real-time agave spot market transaction data introduce uncertainty bands around cost pass-through assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Yorker Spouts Market
Alcoholic Beverages
Asia Pacific Beer Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Beer Keg System Market
Alcoholic Beverages
Isoamyl Alcohol Market
Alcoholic Beverages
South America Craft Beer Market
Alcoholic Beverages
South America Beer Market
Alcoholic Beverages
Fermented Beverages Market
Alcoholic Beverages
Ready to Serve Cocktails Market
Alcoholic Beverages
Global Red Wine Market
Alcoholic Beverages
Wine Bags Market
Alcoholic Beverages
Ethyl Alcohol (Ethanol) Market
Alcoholic Beverages
Hogshead Barrel Market
Alcoholic Beverages
Asia-Pacific Tequila Market
Alcoholic Beverages
Port Wine Market