
 Sake and Plum Wine Market | 2026-2036
Sake and Plum Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Sake and Plum Wine Market Analytics
Japanese artisanal brewer capacity is broadening across Kyushu and Kansai as traditional koji-making methods gain export certification. Takara Shuzo leverages its domestic yeast-banking infrastructure to supply overseas subsidiaries. Hakutsuru Sake Brewing anchors premium positioning through controlled-temperature aging cellars in Nada. Choya Umeshu specializes in multi-year ume maceration programs that command higher wholesale pricing in European markets.
Sake and plum wine comprise fermented rice beverages and ume fruit infusions, typically ranging from 8% to 20% alcohol by volume, produced through parallel multiple fermentation or steeping processes that convert starches and fruit sugars into ethanol. The category serves both ceremonial consumption and mixology applications in foodservice channels. Sake dominates volume through established brewery scale, while flavored sake variants capture faster velocity in North American retail. Online sales channels are expanding fastest among distribution pathways, though restaurants still hold the deepest margin pools through by-the-glass programs. Tetra packs remain marginal in premium positioning but gain traction in casual drinking segments across Southeast Asian markets.
Japan's National Tax Agency governs seishu labeling standards, while the FDA and TTB regulate import compliance and alcohol content disclosure in the United States. The EU's spirit drinks regulation and geographical indication framework shape market access terms for traditional producers entering European territories. Stakeholders must monitor evolving tariff classifications and organic certification reciprocity as export-dependent brewers diversify beyond established Asian consumer bases.
Market Dynamics
Japan's revised liquor tax framework is compressing margins for mid-tier brewers while redirecting production incentives toward small-batch certified operators, fundamentally reordering competitive positioning across export-oriented prefectures.
Growth Catalysts
- Junmai ginjo certification:Premium rice-polishing standards under Japan's National Tax Agency are unlocking foodservice placement in California and New York specialist venues.
- Aged umeshu programs:Multi-year maceration protocols command wholesale premiums in European markets, expanding addressable revenue pools for fruit-infusion specialists.
- Online direct-to-consumer channels:Specialist importers in British Columbia are building dedicated distribution networks that bypass traditional three-tier systems.
Market Restraints
- Rice input volatility:Yamada Nishiki and Gohyakumangoku varietal pricing fluctuates with Japanese agricultural subsidies, squeezing cost structures for premium-grade producers.
- Koji master scarcity:Traditional fermentation expertise concentrates in Nada and Fushimi brewing clusters, limiting scalable artisanal capacity expansion.
- Wine and craft beer substitution:Lower-price-point alternatives in North American retail are capturing casual drinking occasions from entry-level sake.
Strategic Opportunities
- Southeast Asian tetra-pack segments:Casual drinking formats are gaining traction in Thailand and Vietnam where ambient-stable distribution infrastructure remains underdeveloped.
- Mixology application expansion:Bartender education programs in Toronto and Vancouver izakaya chains are creating new on-premise velocity for flavored sake variants.
- Organic certification reciprocity:Evolving Japan-EU mutual recognition agreements are reducing compliance burdens for traditional producers entering German and French territories.
Industry Challenges
- Toji succession gaps:Master brewer apprenticeship pipelines in Kyushu face demographic contraction, threatening quality consistency at heritage houses.
- Temperature-controlled logistics capex:Controlled-aging cellar infrastructure requires capital deployment that small-batch operators struggle to finance.
- TTB label approval timelines:United States import compliance bottlenecks delay seasonal release windows, compressing effective selling periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sake and Plum Wine Market |
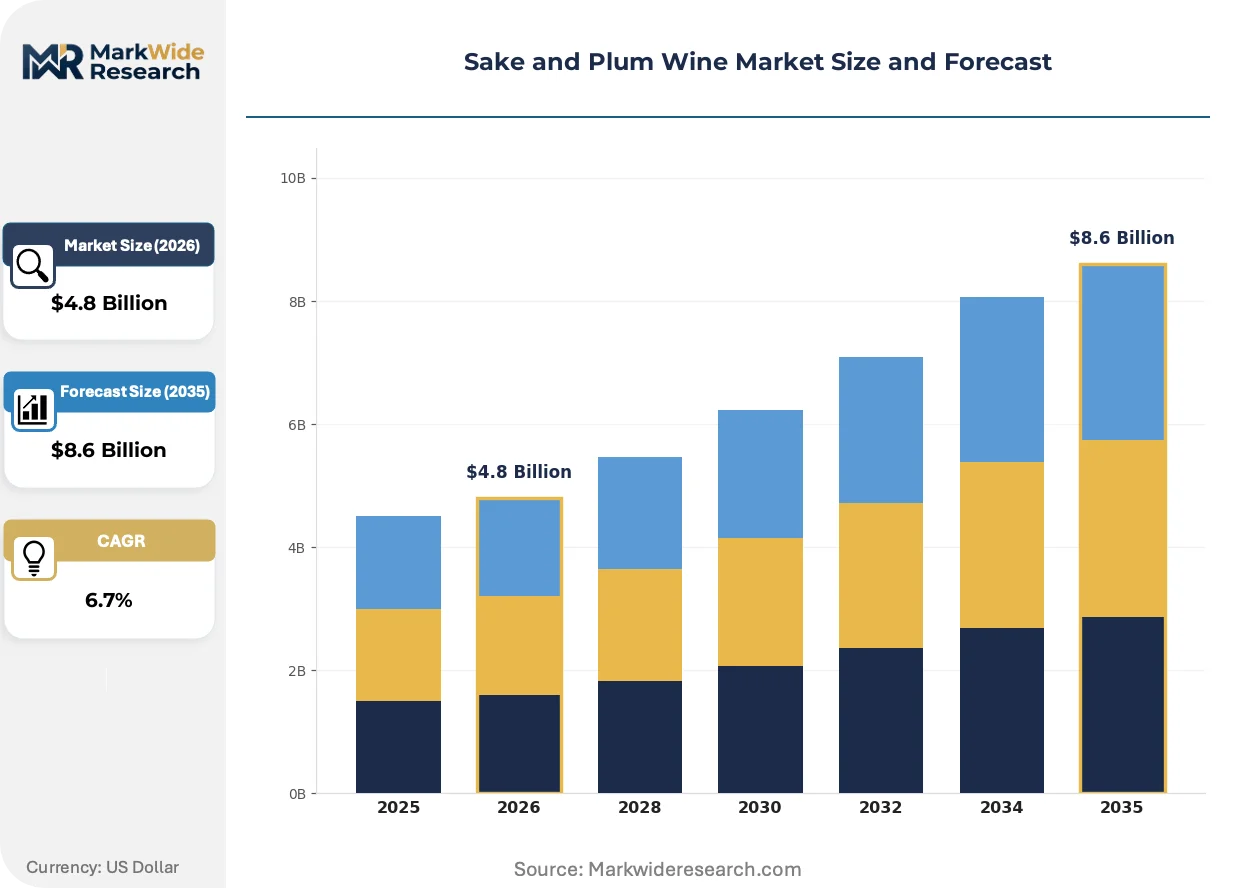
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sake, Umeshu, Fruit Wine, Flavored Sake Distribution Channel: Retail Stores, Online Sales, Bars, Restaurants Packaging Type: Bottles, Tetra Packs, Cans, Kegs Customer Type: Individuals, Businesses, Caterers, Importers |
| Companies Covered | Takara Shuzo Co., Ltd., Hakutsuru Sake Brewing Co., Ltd., Choya Umeshu Co., Ltd., Ozeki Corporation, Kikkoman Corporation, Asahi Shuzo Co., Ltd., Suntory Holdings Limited, Kishu Umeshu Co., Ltd., Gekkeikan Sake Company, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sake and Plum Wine Market Evolving Landscape
Parallel fermentation monitoring systems and precision koji cultivation are compressing production variability while new consumption occasions emerge through beverage-alcohol hybrid positioning.
Automated temperature and humidity sensors networked through IoT architecture are overtaking manual cellar management in premium breweries. Junmai daiginjo producers in Hyogo are deploying these systems to reduce batch-to-batch variation. The technology is enabling consistent export-grade output from facilities previously limited to domestic distribution.
Japan's National Tax Agency revised seishu labeling standards are tightening geographic indication enforcement for overseas-bound production. Small-batch brewers in Kansai must now document rice provenance and water source to maintain certified export status. European Union spirit drinks regulation alignment is forcing label redesigns for German and Dutch market entry.
By-the-glass program unbundling is fragmenting restaurant purchasing authority. Sommeliers in Manhattan and San Francisco are building direct relationships with specialist importers, bypassing traditional distributor consolidation. This pattern is most visible in California where izakaya chains operate captive beverage programs with dedicated junmai ginjo allocations.
Sake and Plum Wine Market Segmentation
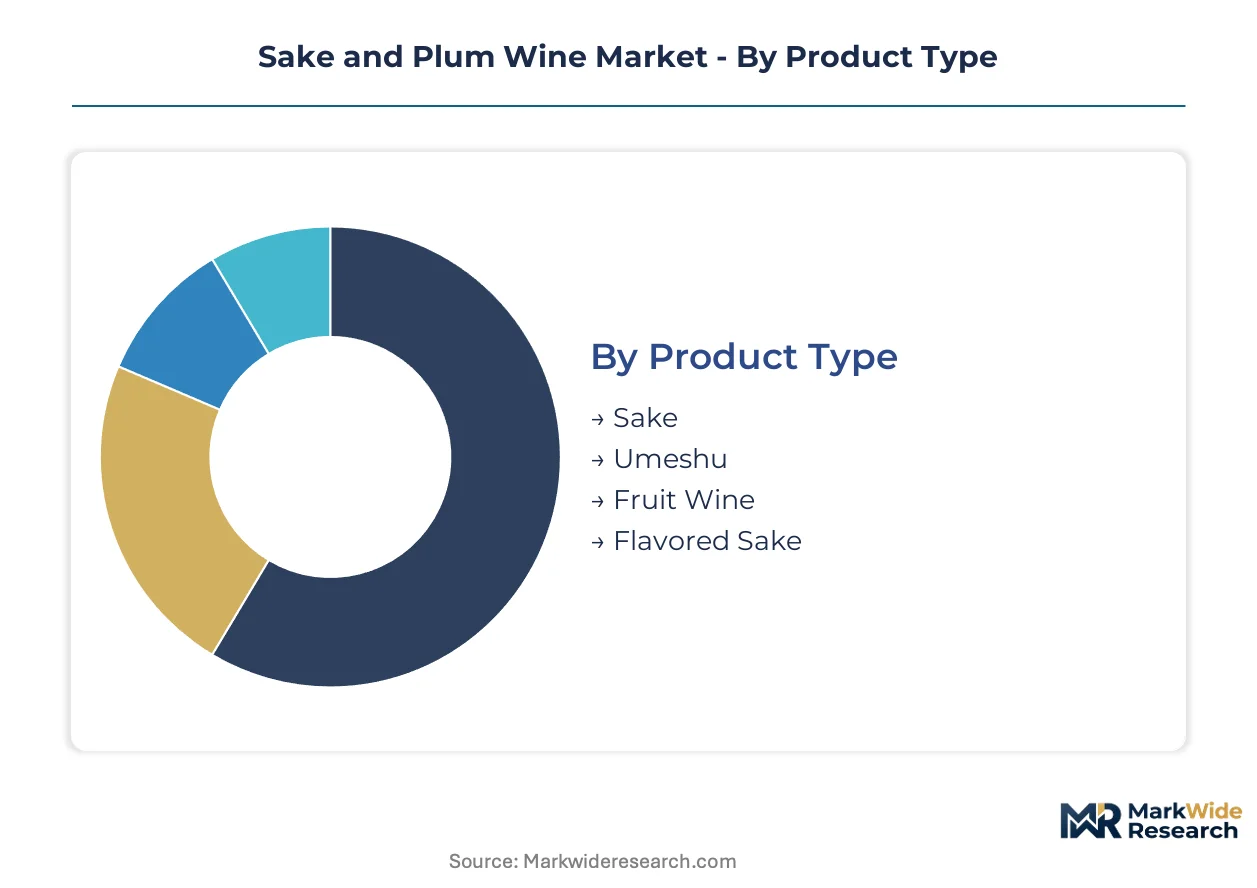
Sake and plum wine producers navigate distinct capital requirements across product categories, with fermentation infrastructure and aging protocols driving divergent investment profiles. Distribution and packaging choices further fragment resource deployment, creating tiered entry barriers for new market participants.
Product Type:
Capital intensity peaks with extended aging programs and certified rice-polishing facilities, while steeping-based production offers lower barrier entry.
- Sake:Parallel multiple fermentation of polished rice yields 15-20% ABV beverages requiring temperature-controlled cellars and toji oversight. California and New York izakaya chains drive junmai ginjo demand through dedicated by-the-glass allocations. Most installed capacity flows through Sake. Expansion is steepest in Flavored Sake.
- Umeshu:Multi-year ume fruit maceration in distilled spirits demands substantial working capital for inventory carrying costs. European wholesale premiums reward extended aging protocols, concentrating demand among specialist importers in Germany and France.
- Fruit Wine:Shorter production cycles and flexible fruit sourcing reduce fixed asset requirements compared to traditional categories.
- Flavored Sake:Infusion-based variants leverage existing brewery infrastructure with minimal incremental capex, capturing retail velocity in North American markets.
Flavor innovation cycles are compressing in this category, with seasonal releases requiring agile formulation capabilities.
Distribution Channel:
Margin capture varies sharply by channel control, with direct relationships outperforming consolidated intermediaries.
- Restaurants:By-the-glass programs generate the deepest margin pools through sommelier-curated placements. Manhattan and San Francisco venues build direct importer relationships, bypassing traditional three-tier markups.
- Online Sales:Direct-to-consumer channels in British Columbia circumvent distributor consolidation, though TTB label compliance creates approval bottlenecks for seasonal releases.
- Retail Stores:Three-tier system dependencies compress margins for entry-level positioning against wine and craft beer substitutes.
- Bars:Mixology education programs in Toronto and Vancouver izakaya chains create on-premise velocity for cocktail-application variants.
Channel diversification is accelerating as producers seek insulation from single-route concentration.
Packaging Type:
Cold chain requirements and shelf stability trade-offs dictate logistics infrastructure investments across formats.
- Bottles:Premium positioning standard for junmai daiginjo and aged umeshu, requiring controlled-temperature warehousing throughout distribution.
- Tetra Packs:Ambient-stable formats gain traction in Thailand and Vietnam where refrigeration infrastructure remains underdeveloped, enabling casual drinking segment penetration.
- Cans:Single-serve portability aligns with outdoor consumption occasions, though premium perception lags glass alternatives.
- Kegs:On-premise draft systems reduce packaging waste for high-volume izakaya accounts with captive beverage programs.
Format experimentation is expanding fastest in Southeast Asian markets with infrastructure constraints.
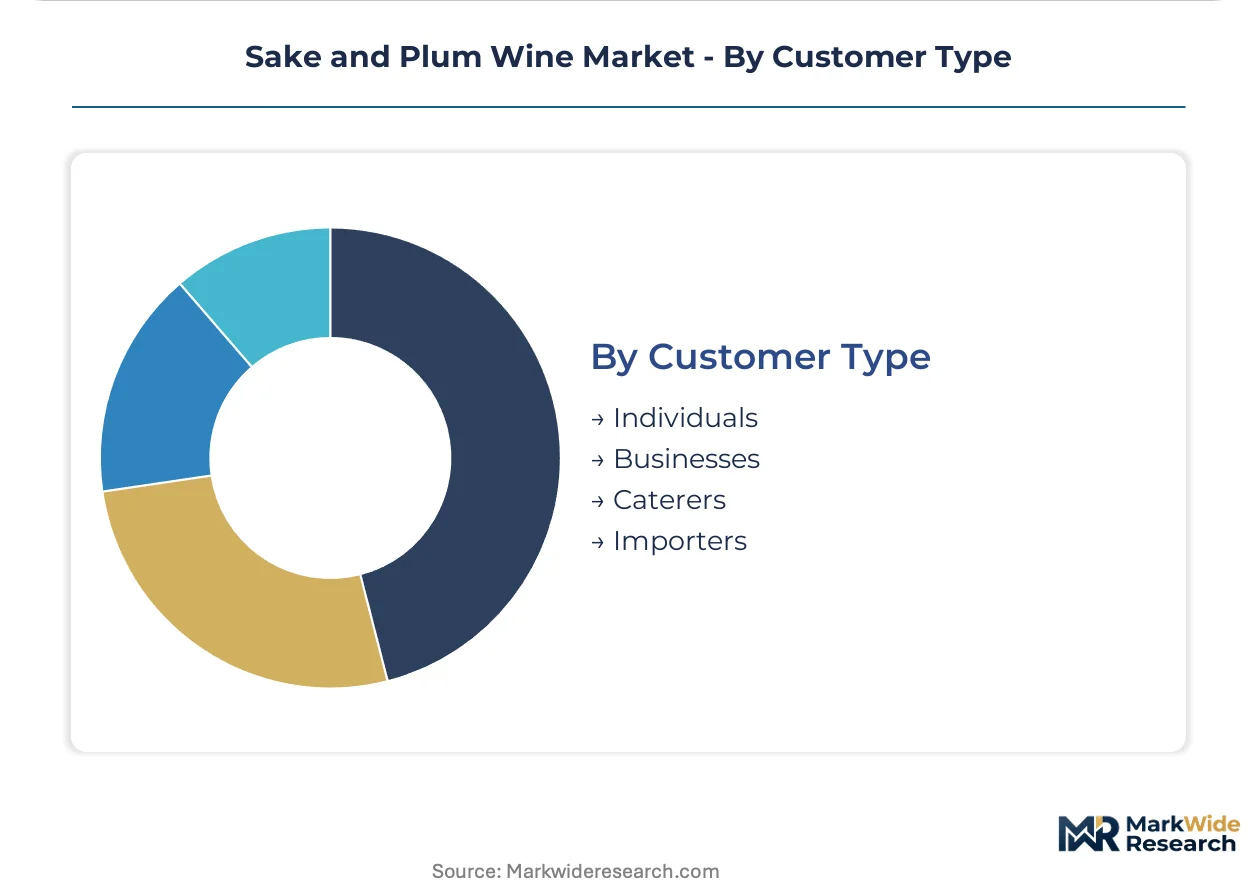
Customer Type:
Procurement scale and specification rigor separate commercial buyers from individual purchasers.
- Importers:Specialist distributors in California and New York build dedicated networks for certified export-grade production, absorbing compliance complexity for overseas breweries.
- Businesses:Izakaya chains operate captive beverage programs with direct allocations, consolidating purchasing authority previously fragmented across individual outlets.
- Caterers:Event-based demand concentrates in ceremonial consumption occasions with seasonal volume spikes.
- Individuals:Direct purchasing through online channels is climbing fastest among customer types, though average transaction values trail commercial accounts.
Account concentration risk is elevating as chain expansion consolidates foodservice procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's revised liquor tax framework is compressing margins for mid-tier brewers while redirecting production incentives toward small-batch certified operators, fundamentally reordering competitive positioning across export-oriented prefectures. Regulatory arbitrage is accelerating as producers migrate toward jurisdictions with favorable certification reciprocity and streamlined import compliance.
United States
California and New York izakaya chains are expanding beverage programs to include junmai ginjo and aged umeshu varieties. The TTB regulates import compliance and alcohol content disclosure, creating approval bottlenecks for seasonal release windows. Manhattan and San Francisco sommeliers are building direct relationships with specialist importers, bypassing traditional three-tier distribution markups.
Japan
Domestic demand concentrates in ceremonial consumption occasions while export certification drives production restructuring. The National Tax Agency governs seishu labeling standards and tightened geographic indication enforcement for overseas-bound production. Nada and Fushimi brewing clusters in Kansai maintain traditional koji-making expertise, though toji succession pipelines face demographic contraction.
Canada
British Columbia specialist importers are constructing dedicated distribution networks that circumvent traditional three-tier systems through direct-to-consumer channels. Health Canada and the PMRA regulate import compliance for alcohol beverages entering Canadian territories. Vancouver izakaya chains operate captive beverage programs with direct allocations, consolidating purchasing authority.
Germany
European wholesale premiums reward extended umeshu aging protocols, expanding addressable revenue pools for fruit-infusion specialists entering German and French markets. EU spirit drinks regulation and geographical indication frameworks shape market access terms for traditional producers. Evolving Japan-EU mutual recognition agreements are reducing compliance burdens for organic-certified breweries.
Thailand
Ambient-stable tetra-pack formats are gaining traction in casual drinking segments where refrigeration infrastructure remains underdeveloped. The country's national food and drug regulator oversees import compliance for alcoholic beverages. Bangkok and Chiang Mai distribution networks are expanding fastest among Southeast Asian markets, enabling volume penetration at lower price points.
Sake and Plum Wine Market Competitive Landscape
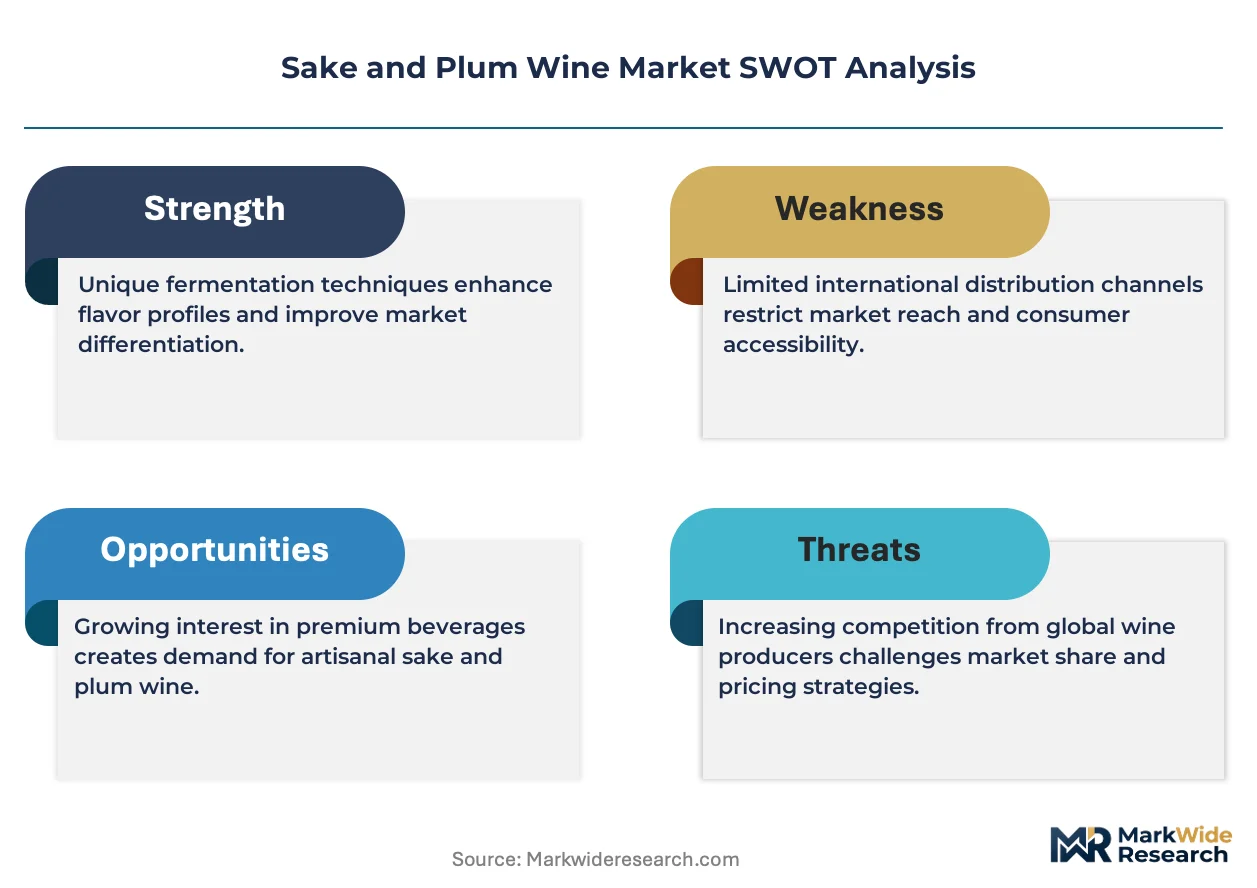
Japanese producers anchor the premium tier through heritage brewing credentials and certified export-grade infrastructure; North American and European specialists hold distribution and mixology application layers. Market structure fragments across three tiers: heritage houses with century-old koji lineages, mid-scale regional brewers, and commodity-oriented volume players. Strategic archetypes include certified small-batch artisans, tetra-pack format innovators, and direct-to-consumer channel specialists. Capacity expansion and strategic partnerships dominate competitive moves as players seek insulation from rice input volatility.
Within the heritage house tier, Takara Shuzo Co., Ltd. and Hakutsuru Sake Brewing Co., Ltd. occupy positions representing traditional Nada and Kansai brewing cluster concentration. Choya Umeshu Co., Ltd. exemplifies the fruit-infusion specialist archetype through multi-year ume maceration programs. These entities sit within a competitive set where geographic origin and fermentation expertise serve as primary differentiation vectors rather than scale economies.
| Leading Market Players |
|---|
| Takara Shuzo Co., Ltd. |
| Hakutsuru Sake Brewing Co., Ltd. |
| Choya Umeshu Co., Ltd. |
| Ozeki Corporation |
| Kikkoman Corporation |
| Asahi Shuzo Co., Ltd. |
| Suntory Holdings Limited |
| Kishu Umeshu Co., Ltd. |
| Gekkeikan Sake Company, Ltd. |
| Others |
Value Network & Pricing Analysis
California and New York izakaya chains consolidating purchasing authority through captive beverage programs are forcing supply-side reconfiguration toward direct allocation models, compressing traditional distributor margins while elevating price transparency for certified junmai ginjo grades.
Pricing Analysis
Direct-to-restaurant allocations bypassing three-tier markups command premium positioning for certified export-grade production. Three-tier pricing structure across junmai daiginjo, junmai ginjo, and futsushu levels stratifies by rice-polishing certification and aging protocol. Pricing pressure stems from wine and craft beer substitution in North American retail entry tiers. Casual drinking segments in Southeast Asian markets exhibit highest price sensitivity, while European specialist importers absorb premiums for extended umeshu aging programs.
Supply Chain Analysis
Dual-sourcing requirements for Yamada Nishiki and Gohyakumangoku rice varietals are mandated by heritage houses seeking insulation from Japanese agricultural subsidy volatility. Raw material procurement draws from Kyushu and Kansai brewing clusters, with koji master expertise concentrated in Nada and Fushimi. Single-source vulnerability concentrates in toji apprenticeship pipelines facing demographic contraction. Distribution runs through specialist importers in California, New York, and British Columbia building dedicated networks for temperature-controlled logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sake and plum wine market functions as a stable compounder anchored by ceremonial consumption continuity and mixology application expansion in North American foodservice channels.
For Market Incumbents: Hedge against rice input volatility through backward integration into controlled-temperature aging cellar infrastructure in Hyogo and Kyoto prefectures. Defensive consolidation of koji master apprenticeship pipelines in Kansai brewing clusters mitigates succession gap threats from demographic contraction. Certification investment in Japan-EU organic reciprocity agreements reduces compliance burdens for German and French market penetration. For New Entrants and Emerging Players: Specialist importers in British Columbia represent the most penetrable channel archetype, circumventing three-tier system dependencies through direct-to-consumer online infrastructure. White-space targets concentrate in Southeast Asian tetra-pack casual drinking segments where ambient-stable formats bypass underdeveloped refrigeration networks. Go-to-market execution should anchor in bartender education programs at Toronto and Vancouver izakaya chains driving mixology application velocity. For Investors and Strategic Acquirers: Asymmetric upside sits with small-batch certified operators holding export-grade infrastructure and documented rice provenance under Japan's National Tax Agency geographic indication enforcement. Long-term viability frames around heritage brewing credentials and captive yeast-banking capabilities. The signal to watch is TTB label approval timeline compression indicating regulatory pathway efficiency for seasonal release windows.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | British Columbia specialist importers bypass three-tier markups through dedicated online distribution networks. |
| Certified Export-Grade Infrastructure Investment | Controlled-temperature aging cellars in Nada enable consistent junmai daiginjo output for California izakaya chains. |
| Koji Master Apprenticeship Pipeline Development | Kyushu and Kansai brewing clusters address toji succession gaps threatening quality consistency at heritage houses. |
| Organic Certification Reciprocity Pursuit | Japan-EU mutual recognition agreements reduce compliance burdens for traditional producers entering German territories. |
| Ambient-Stable Format Innovation | Tetra-pack production lines capture casual drinking segments in Thailand and Vietnam where cold chain infrastructure remains limited. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with toji master brewers, specialist import distributors, izakaya beverage program directors, and National Tax Agency certification officers with secondary validation from Japan Sake and Shochu Makers Association export data, TTB import compliance filings, EU spirit drinks regulation documentation, and prefectural brewing cluster production statistics. Bottom-up volume builds across product categories triangulated against top-down market sizing.
Segment-weighting approaches modeled sake, umeshu, and flavored sake variants across distribution channels including restaurants, online sales, retail stores, and bars, with packaging format and customer type dimensions integrated throughout the projection horizon. CAGRs derived from historical trajectory analysis and category-specific growth drivers including junmai ginjo certification expansion and aged umeshu premiumization in European wholesale markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Japan's liquor tax framework revisions, rice agricultural subsidy fluctuations, and TTB label approval timeline variability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
Dark Spirits Market
Alcoholic Beverages
High-End Baijiu Market
Alcoholic Beverages
Tea Beer Market
Alcoholic Beverages
Premixed Margarita Market
Alcoholic Beverages
Global Brewery Filtration Market
Alcoholic Beverages
Smart Wine Cellar Market
Alcoholic Beverages
Single Serve Wine Market
Alcoholic Beverages
Europe Wine Coolers Market
Alcoholic Beverages
Vermouth Market
Alcoholic Beverages
Beer Mug Market
Alcoholic Beverages
Canned Cocktails Market
Alcoholic Beverages
Organic Wine Market
Alcoholic Beverages
Pinot Meunier Market
Alcoholic Beverages
Wine Chocolate Market
Alcoholic Beverages
Herbal Distillates Market