
 Rubus Fructicosus (Blackberry) Seed Market | 2026-2036
Rubus Fructicosus (Blackberry) Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Rubus Fructicosus (Blackberry) Seed Market Analytics
Modular packaging configurations across pouch-and-bottle bundles is rebalancing buyer choice toward trial-sized formats in specialty retail channels. Gracefruit Limited leverages its UK-based botanical supply chain to sustain consistent seed oil grades for cosmetic compounders. Lotioncrafter LLC anchors its position through technical documentation and formulation support that differentiates its wholesale platform from commodity traders. E.W. King & Co. Ltd competes on heritage sourcing relationships with British fruit growers.
Rubus fructicosus seed comprises the embryonic plant material recovered from blackberry drupelets, typically containing 13-20% oil by weight with a fatty acid profile dominated by linoleic (60-70%), oleic (15-20%), and alpha-linolenic acids, extracted through cold-press or supercritical CO2 methods for use in nutraceutical capsules, topical formulations, and functional food enrichment. The oil segment leads value generation due to its concentration threshold and shelf-stability requirements, while powder applications gain traction in protein-fortified food matrices where emulsification properties matter. Extract forms occupy the premium tier in pharmaceutical adjuvant applications where standardized polyphenol content commands quality premiums.
REACH registration requirements in Europe govern cosmetic ingredient safety dossiers, while FDA oversight in the United States shapes GRAS self-affirmation pathways for food-grade oil applications. The USDA organic certification framework creates market access differentiation for North American suppliers meeting handler standards. Stakeholders must monitor evolving Novel Food approvals in the European Union and pending state-level hemp-cosmetic regulatory harmonization that could reshape ingredient positioning claims.
Market Dynamics
Cold-press extraction technology upgrades in European processing facilities are compressing production timelines while elevating oil yield quality, forcing smaller operators to consolidate or exit as capital requirements for certification-compliant equipment escalate.
Growth Catalysts
- Cosmetic Ingredient Certification:Germany's natural cosmetic ingredient certification standards drive premium procurement patterns across formulator networks. Brands seeking BDIH or NaTrue labels now mandate documented seed oil provenance.
- Linoleic Acid Positioning:Skincare formulators exploit the 60-70% linoleic acid profile in anti-inflammatory and barrier-repair formulations. This biochemical signature differentiates blackberry seed oil from commodity carrier oils.
- Supercritical CO2 Methods:Adoption of supercritical CO2 extraction preserves heat-sensitive polyphenols for pharmaceutical adjuvant applications. Equipment suppliers in Italy and Spain report order backlogs from nutraceutical compounders.
Market Restraints
- Raw Material Volatility:Weather-dependent drupelet harvests in Eastern European growing regions create input cost instability. Polish and Romanian fruit processors dominate seed supply, concentrating sourcing risk.
- REACH Dossier Burden:ECHA registration requirements for cosmetic ingredient safety impose documentation costs that exclude micro-scale producers. Full dossier preparation exceeds six-figure euro investments.
- Shelf-Stability Limitations:Alpha-linolenic acid oxidation sensitivity restricts oil formulation in mass-market products lacking nitrogen-flush packaging. This technical ceiling contains addressable market expansion.
Strategic Opportunities
- Protein-Fortified Matrices:Powder applications in functional foods remain underdeveloped relative to oil segments. Emulsification properties of defatted seed meal suit plant-based meat analog developers.
- Novel Food Pathways:Pending EU Novel Food approvals for Rubus fructicosus seed extracts create first-mover advantages for dossier submitters. Early entrants secure 18-24 month regulatory moats.
- Modular Packaging Bundles:Trial-sized pouch-and-bottle configurations in specialty retail channels reduce buyer experimentation costs. This format innovation opens direct-to-consumer pathways previously blocked by minimum order quantities.
Industry Challenges
- Organic Handler Compliance:USDA organic certification demands segregated supply chains from farm to extraction. Multi-site operators struggle with audit trail documentation across contracted growers.
- GRAS Self-Affirmation Complexity:FDA food-grade pathway construction requires toxicological expertise scarce among botanical suppliers. Legal consultation costs strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubus Fructicosus (Blackberry) Seed Market |
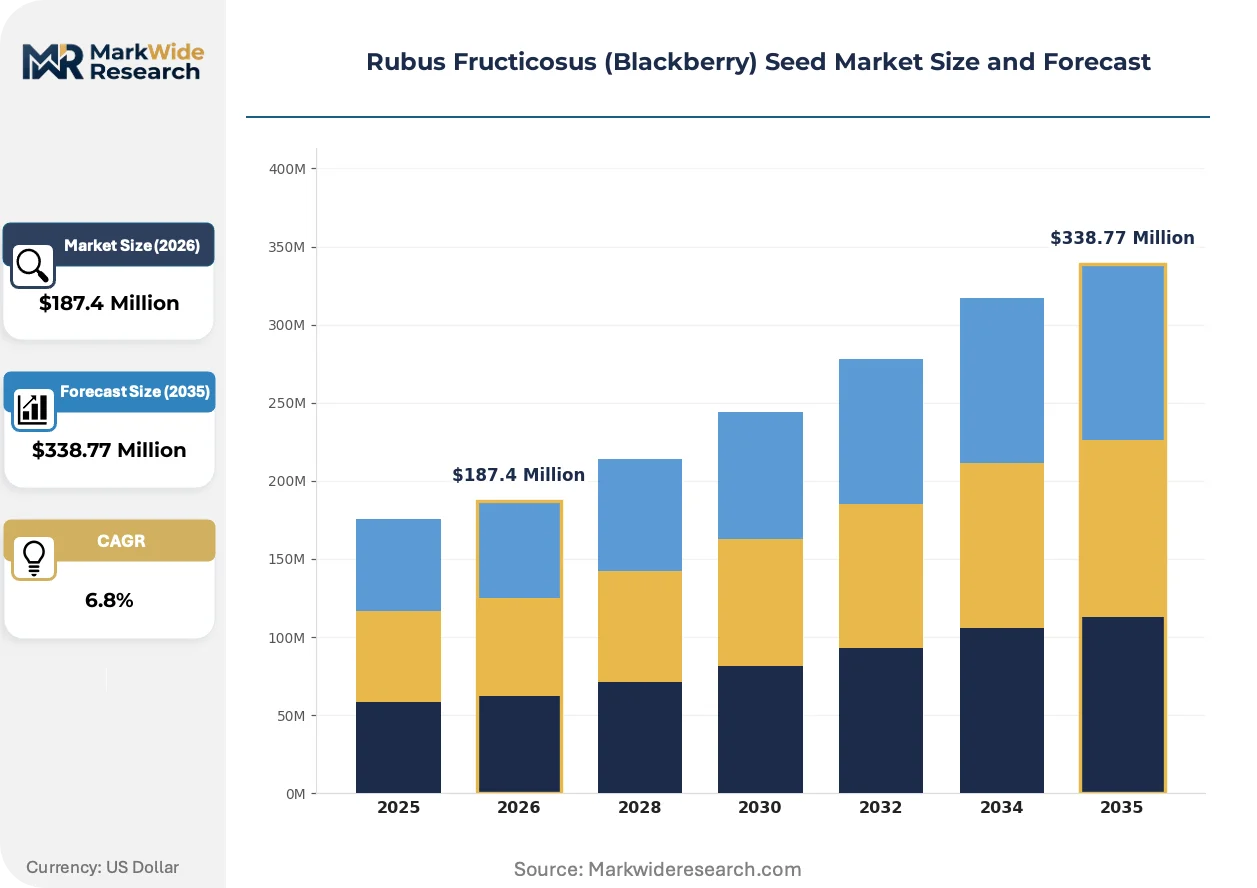
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil, Powder, Extract, Whole Seeds End Use Industry: Food & Beverage, Cosmetics, Pharmaceuticals, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Packaging Type: Bulk Bags, Bottles, Pouches, Custom Containers |
| Companies Covered | Gracefruit Limited, Lotioncrafter LLC, E.W King & Co. Ltd, Abonna Fruits and Plants Co. Pvt Ltd, Harris Seeds, Rhoads Farm, Wish Farms, Hortifrut SA, Sun Belle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubus Fructicosus (Blackberry) Seed Market Evolving Landscape
Extraction technology convergence with cosmetic formulation science is compressing the traditional supplier-compounder boundary, while regulatory documentation requirements are professionalizing a historically fragmented vendor base.
Supercritical CO2 extraction systems with integrated fractionation modules are modularizing production economics for mid-scale processors. German and Italian equipment manufacturers now lease turnkey units with output guarantees. Cosmetic compounders in France and Switzerland accelerate adoption to secure polyphenol-standardized supply chains. This technology is modularizing capital deployment, enabling processors to scale capacity in 500-liter increments rather than committing to industrial-scale infrastructure.
REACH registration deadlines for existing cosmetic ingredients are compressing supplier consolidation timelines. ECHA's 2026 dossier submission requirements for substances above 100 tons annually force micro-producers into toll-manufacturing arrangements. German formulators now demand Safety Data Sheet completeness as a procurement prerequisite. The premium oil segment responds by concentrating among three to four vertically integrated processors with in-house toxicology departments.
Certification-driven procurement now dominates buyer decision frameworks in natural cosmetics. Formulators in Germany and Austria require BDIH, NaTrue, or COSMOS documentation before contract negotiation. This behavioral shift displaces price-first sourcing in specialty retail channels. The pattern concentrates demand among handlers with multi-certification capabilities, compressing margins for single-standard operators.
Rubus Fructicosus (Blackberry) Seed Market Segmentation
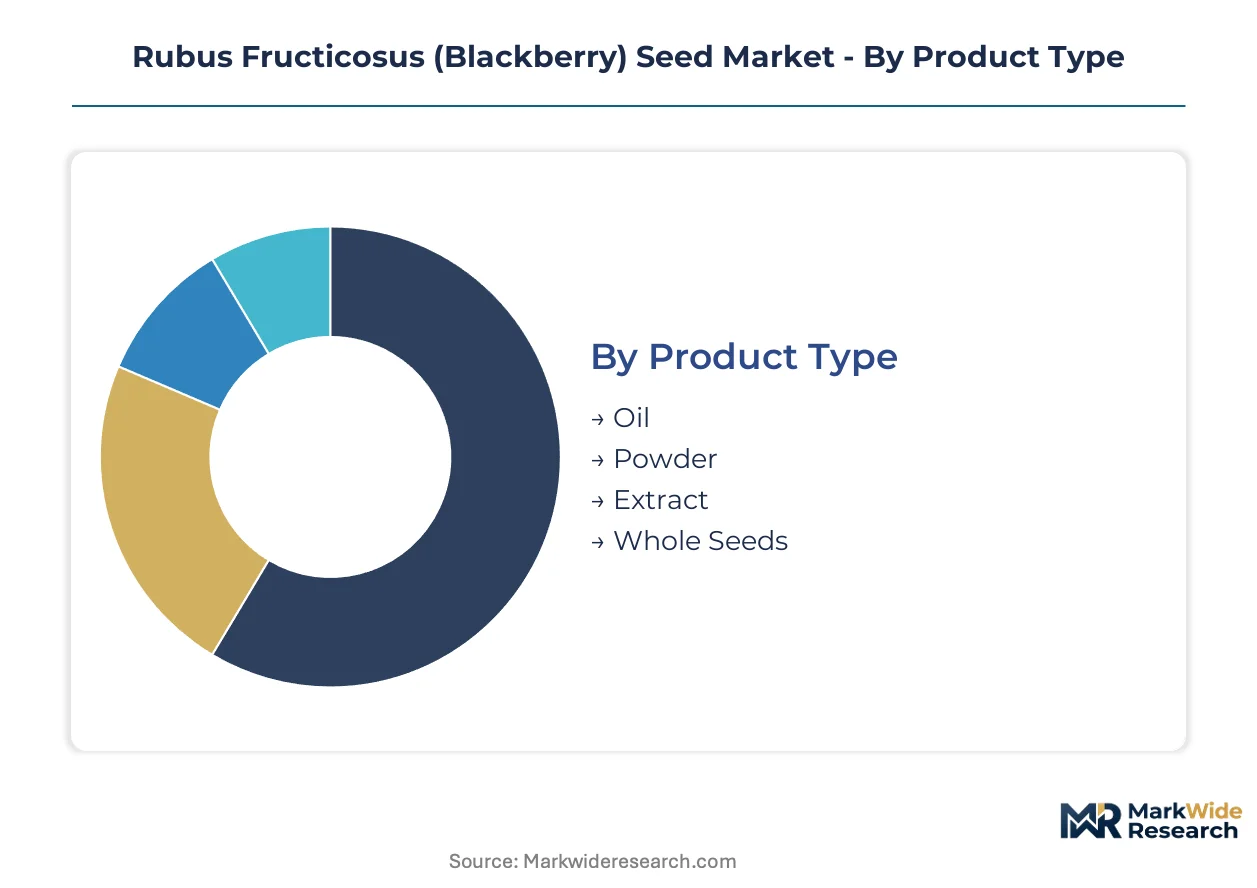
Segmentation in the Rubus fructicosus seed market reveals how certification requirements, extraction complexity, and shelf-stability demands create distinct commercial tiers. Each category carries divergent regulatory burdens that reshape supplier capabilities and buyer procurement patterns.
Product Type:
Certification intensity varies sharply across forms: oil demands REACH cosmetic dossiers and USDA organic handler compliance, powder navigates GRAS self-affirmation for food matrices, extract requires Novel Food submissions, while whole seeds face minimal processing oversight.
- Oil:Cold-press or supercritical CO2 extraction yields 13-20% oil by weight with linoleic acid dominance (60-70%). German and Austrian formulators drive premium procurement through BDIH and NaTrue certification mandates. Shelf-stability requirements constrain mass-market penetration.
- Extract:Supercritical CO2 methods preserve heat-sensitive polyphenols for pharmaceutical adjuvant applications. Standardized polyphenol content commands quality premiums in Swiss and French compounder networks. ECHA registration deadlines compress supplier consolidation timelines.
- Powder:Defatted seed meal offers emulsification properties for protein-fortified food matrices and plant-based meat analogs.
- Whole Seeds:Minimal processing preserves germination capacity for agricultural propagation and limited nutraceutical encapsulation.
Leading the category by volume: Oil. Growing fastest: Extract.
End Use Industry:
Margin structures diverge across applications: cosmetics tolerate premium pricing for certified grades, pharmaceuticals demand batch consistency documentation, food applications face cost compression, nutraceuticals balance standardization with scale.
- Cosmetics:Skincare formulators exploit anti-inflammatory and barrier-repair positioning in premium lines. Germany's natural cosmetic certification standards displace price-first sourcing. BDIH and COSMOS documentation now gates contract negotiation.
- Pharmaceuticals:Adjuvant applications require standardized polyphenol content with full Safety Data Sheet completeness. ECHA's dossier submission requirements force toll-manufacturing arrangements for micro-producers.
- Nutraceuticals:Capsule formulations leverage fatty acid profiles with GRAS self-affirmation pathways shaping US market access.
- Food & Beverage:Functional enrichment applications face oxidation sensitivity constraints and nitrogen-flush packaging cost barriers.
Highest margin capture: Cosmetics. Steepest expansion trajectory: Pharmaceuticals.
Distribution Channel:
Channel selection determines minimum order thresholds and technical support depth: direct sales sustain formulation partnerships, specialty stores enable trial-sized experimentation, online retail fragments price transparency.
- Direct Sales:Technical documentation and formulation support differentiate wholesale platforms from commodity traders. Gracefruit Limited leverages UK-based botanical supply chains for consistent seed oil grades.
- Specialty Stores:Modular pouch-and-bottle bundles reduce buyer experimentation costs and open direct-to-consumer pathways.
- Online Retail:Price transparency pressures single-standard operators lacking multi-certification capabilities.
- Supermarkets:Mass-market shelf-stability limitations restrict oil placement to nitrogen-flush packaged SKUs.
Deepest technical engagement: Direct Sales. Fastest format innovation: Specialty Stores.
Packaging Type:
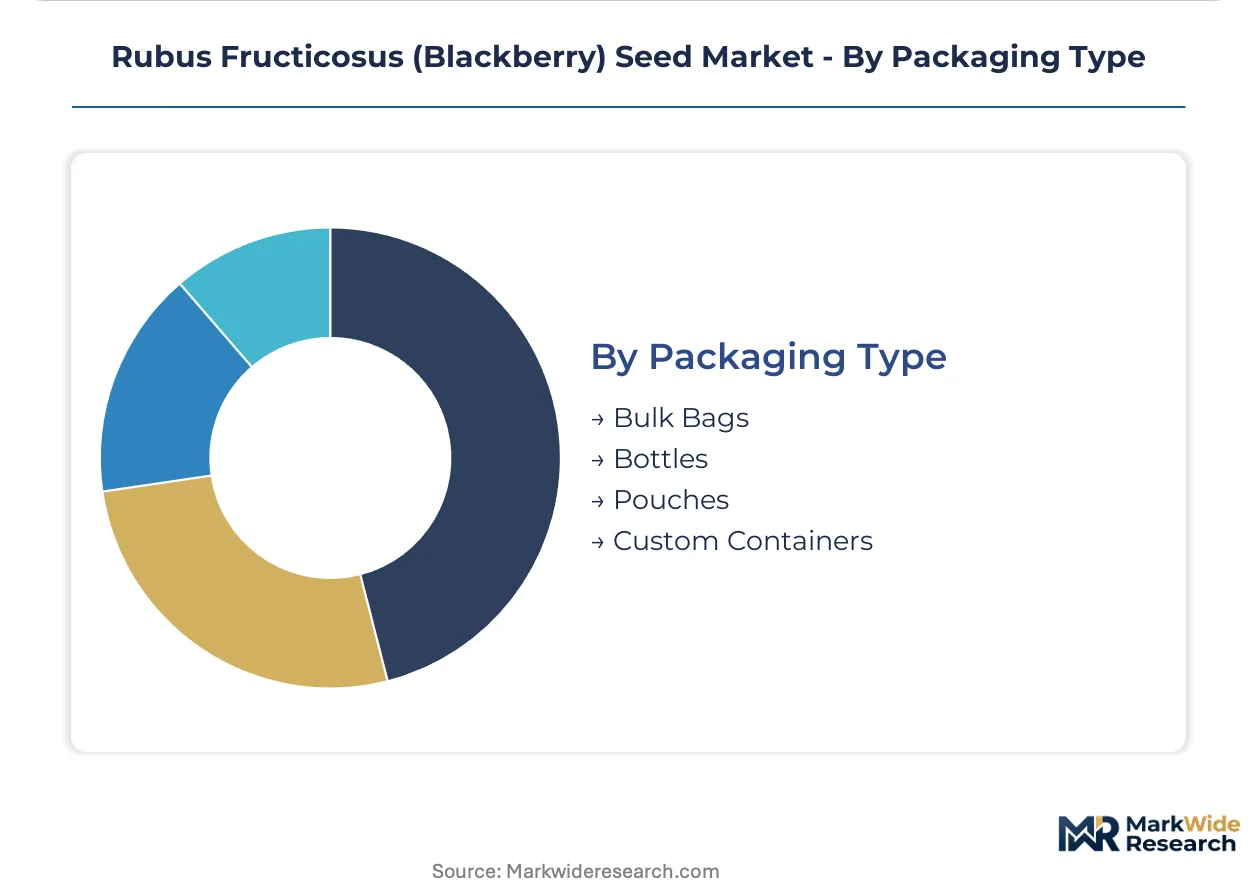
Packaging economics scale with volume commitment and shelf-life requirements: bulk bags serve integrated processors, bottles and pouches fragment toward trial formats, custom containers capture pharmaceutical specification premiums.
- Bottles:Standard packaging for cosmetic and nutraceutical oil applications with nitrogen-flush options for alpha-linolenic acid oxidation protection.
- Pouches:Trial-sized configurations in specialty retail channels rebalance buyer choice toward experimentation-friendly formats.
- Bulk Bags:Integrated extraction facilities in Poland and Romania deploy bulk handling for downstream oil processing.
- Custom Containers:Pharmaceutical-grade specifications with full audit trail documentation for segregated organic supply chains.
Dominant volume format: Bulk Bags. Gaining share fastest: Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish and Romanian processors dominate raw seed supply, while German and Austrian formulators consume premium oil volumes. Certification requirements fragment procurement patterns across production and consumption zones.
Germany
BDIH and NaTrue certification mandates drive premium oil procurement from cosmetic compounders in Hamburg and Berlin-Brandenburg. REACH dossier completeness gates supplier qualification, compressing vendor lists to vertically integrated handlers. Munich-based extraction facilities deploy supercritical CO2 systems for polyphenol-standardized output.
Poland
Weather-dependent drupelet harvests in Mazovia and Greater Poland regions concentrate seed supply risk. Polish fruit processors supply raw material to downstream oil extractors across the EU. Warsaw-area handling facilities struggle with segregated organic supply chain documentation for USDA export compliance.
United States
GRAS self-affirmation pathways for food-grade applications shape market access through FDA oversight. Pacific Northwest berry growers in Oregon and Washington supply seed to domestic oil processors. California cosmetic formulators demand nitrogen-flush packaging for alpha-linolenic acid stability in mass-market SKUs.
United Kingdom
Heritage sourcing relationships with British fruit growers anchor seed procurement for specialty oil producers. UK-based botanical supply chains sustain consistent grades for cosmetic compounders in London and the Southeast. Post-BREXIT regulatory divergence complicates EU market access for certified organic handlers.
Switzerland
Swissmedic pharmaceutical standards command batch consistency documentation for adjuvant applications. Basel-area compounders secure polyphenol-standardized extracts through toll-manufacturing arrangements. Zurich cosmetic laboratories exploit Switzerland's neutrality to bridge EU and non-EU certification requirements.
Rubus Fructicosus (Blackberry) Seed Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across extraction, formulation, and distribution tiers. Market structure concentrates among three to four vertically integrated processors with in-house toxicology departments, while micro-producers exit or consolidate into toll-manufacturing networks. Strategic archetypes include certification-heavy European handlers, UK-based botanical suppliers, and North American seed-to-oil integrators. Dominant competitive moves span backward integration into fruit grower contracts and technology licensing for modular supercritical CO2 deployment.
Among UK-based botanical specialists, Gracefruit Limited occupies a position exemplifying consistent supply chain management for cosmetic compounders. Lotioncrafter LLC represents the technical documentation archetype, anchoring wholesale platform differentiation through formulation support capabilities. E.W. King & Co. Ltd sits within the heritage sourcing tier, leveraging long-standing grower relationships that typify British seed procurement patterns.
| Leading Market Players |
|---|
| Gracefruit Limited |
| Lotioncrafter LLC |
| E.W King & Co. Ltd |
| Abonna Fruits and Plants Co. Pvt Ltd |
| Harris Seeds |
| Rhoads Farm |
| Wish Farms |
| Hortifrut SA |
| Sun Belle |
| Others |
Value Network & Pricing Analysis
Polish and Romanian drupelet harvest volatility feeds directly into three-tier pricing structure across premium, standard, and economy levels, with certified organic handlers commanding spreads that commodity traders cannot match. Weather-induced raw material instability compresses margins at the seed processing tier while concentrating pricing power among vertically integrated extractors with captive grower contracts.
Pricing Analysis
Margin tightening in standard-grade oil reflects REACH dossier cost absorption by mid-scale processors lacking in-house toxicology departments. Three-tier pricing structure across premium, standard, and economy levels separates BDIH-certified supply from NaTrue grades and uncertified commodity lots. Price differentiation hinges on certification completeness and volume scale, with specialty cosmetic compounders showing lowest price sensitivity and mass-market food formulators most responsive to cost fluctuations. Cost-down pressure on economy-tier powder accelerates because GRAS self-affirmation complexity excludes smaller botanical suppliers from food-grade positioning.
Supply Chain Analysis
Direct-to-compounder channels handle technical documentation demands from German and Austrian formulators requiring batch consistency guarantees. Raw seed supply concentrates in Poland, Romania, and the United Kingdom, with extraction capacity clustering in Germany and Italy. The chain draws from weather-dependent Eastern European drupelet harvests, supercritical CO2 equipment modules, and nitrogen-flush packaging materials. Single-source vulnerability in Polish fruit processor networks creates systemic input risk. Distribution runs through toll-manufacturing arrangements that consolidate micro-producers under REACH-compliant handlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polish harvest volatility and ECHA registration deadlines compress effective supply capacity, propping premium tier pricing through the analysis window. Segregated organic certification requirements further constrain handler availability.
For Market Incumbents: Lock in backward integration into Mazovia and Greater Poland grower contracts before 2026 dossier deadlines force competitor consolidation. Defend margin position by deploying modular supercritical CO2 fractionation modules that preserve polyphenol profiles for Swiss pharmaceutical compounders. Channel control through direct technical documentation relationships with Hamburg and Berlin-Brandenburg formulators resists price erosion from UK-based botanical traders. For New Entrants and Emerging Players: Supercritical CO2 extraction with integrated fractionation offers entry path into pharmaceutical adjuvant applications where standardized polyphenol content commands quality premiums. White-space targets include protein-fortified food matrices using defatted seed meal emulsification properties and trial-sized pouch configurations for specialty retail channels. The most penetrable segment sits in plant-based meat analog developers seeking functional ingredients outside established oil markets. Go-to-market leverage rests on Novel Food dossier submission timing that secures 18-24 month regulatory moats. For Investors and Strategic Acquirers: Distressed-cycle entries favor UK-based botanical specialists with heritage grower relationships and NaTrue multi-certification capabilities in London and Southeast clusters. Long-term viability centers on handlers with segregated organic supply chains from farm to extraction, capturing structural margin premiums as ECHA deadlines eliminate micro-producers. Acquisition target archetype: mid-cap processors with in-house toxicology departments and toll-manufacturing networks. Watch Italian equipment manufacturer order backlogs as inflection signal for supercritical CO2 adoption velocity among nutraceutical compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grower Contracts | Captive supply of Polish and Romanian drupelet harvests insulates processors from weather-driven input cost spikes. |
| Supercritical CO2 Technology Licensing | Modular deployment from German and Italian equipment manufacturers compresses capital requirements for mid-scale processors. |
| Novel Food Dossier Submission | Early EU regulatory approval for Rubus fructicosus seed extracts secures exclusive positioning in pharmaceutical adjuvant applications. |
| Multi-Certification Handler Investment | BDIH, NaTrue, and COSMOS capabilities gate contract negotiations with Hamburg and Berlin-Brandenburg cosmetic formulators. |
| Toll-Manufacturing Network Consolidation | REACH-compliant processing arrangements absorb micro-producers excluded by six-figure euro dossier preparation costs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across extraction facility managers, cosmetic formulation chemists, pharmaceutical compounder procurement leads, and fruit processor supply chain directors. ECHA registration databases, USDA organic handler audit reports, FDA GRAS notification filings, and EU Novel Food application records provided regulatory validation. Bottom-up seed supply estimates from Polish and Romanian agricultural statistics combined with top-down oil demand projections from German and Austrian cosmetic industry associations.
Segmentation granularity operated at product type, end-use industry, distribution channel, and packaging format levels, with extraction technology modality modeled as an additional dimension. CAGRs derived from trend extrapolation of certification-driven procurement patterns and technology adoption curves across the projection horizon. Industry-specific forecast inputs included supercritical CO2 equipment order backlogs from Italian manufacturers and nitrogen-flush packaging cost trajectories for alpha-linolenic acid stabilization.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged Polish drought conditions or accelerated ECHA registration deadline enforcement. Periodic stress-testing of base assumptions is recommended, particularly regarding Novel Food approval timelines and organic handler compliance audit failure rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Breadnut Market
Nuts and Seeds
Germany Cashew Market
Nuts and Seeds
Almond Extract Market
Nuts and Seeds
Nuts and Nutmeals Market
Nuts and Seeds
Baru Nuts Market
Nuts and Seeds
Walnut-Based Spreads Market
Nuts and Seeds
Almond Butter Market
Nuts and Seeds
India Cashew Market
Nuts and Seeds
Almond Market
Nuts and Seeds
Betel Nuts Market
Nuts and Seeds
Maca Market
Nuts and Seeds
Carob Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
Almond Oil Market
Nuts and Seeds
Almond with Shell Snack Market
Nuts and Seeds
Almond Protein Market