
 Distillers Malt Market | 2026-2036
Distillers Malt Market Size, Share, and Industry Trends Forecast 2026-2036
Distillers Malt Market Outlook
Specialty malt specification revenue is tilting toward distillers demanding higher diastatic power and lower nitrogen content for premium spirit yields. Cargill, Inc. leverages its North American grain origination network to secure consistent two-row barley supply for distilling clients. Simpsons Malt Limited sustains long-term contracts with Scotch whisky producers through its Scottish malting facilities. Malteurop Group competes across Europe with flexible batch sizes tailored to craft distillery volumes.
Distillers malt is germinated cereal grain, typically kilned at lower temperatures than brewing malt to preserve enzyme activity and minimize color development, with specifications targeting fermentable extract above 80% and fine grind coarse grind difference below 2%. Its primary commercial purpose is converting starch to fermentable sugars for subsequent yeast fermentation into distilled spirits. Single malt commands the deepest margin pools as aged whisky stocks appreciate in bonded warehouses, while peated malt occupies a defensible niche among Islay-style producers. Organic malt leads volume growth as clean-label spirits capture shelf space in European and North American retail channels.
EFSA enforces maximum levels for ochratoxin A and deoxynivalenol in cereals destined for distilling, pushing maltsters toward certified grain programs and in-house testing laboratories. REACH compliance governs chemical inputs in European malting operations, while FDA regulations under the Food Safety Modernization Act shape import requirements for malt entering American distilleries. Stakeholders must monitor how carbon accounting rules from the EU Green Deal reshape barley sourcing decisions and kiln energy specifications across the supply base.
Market Dynamics
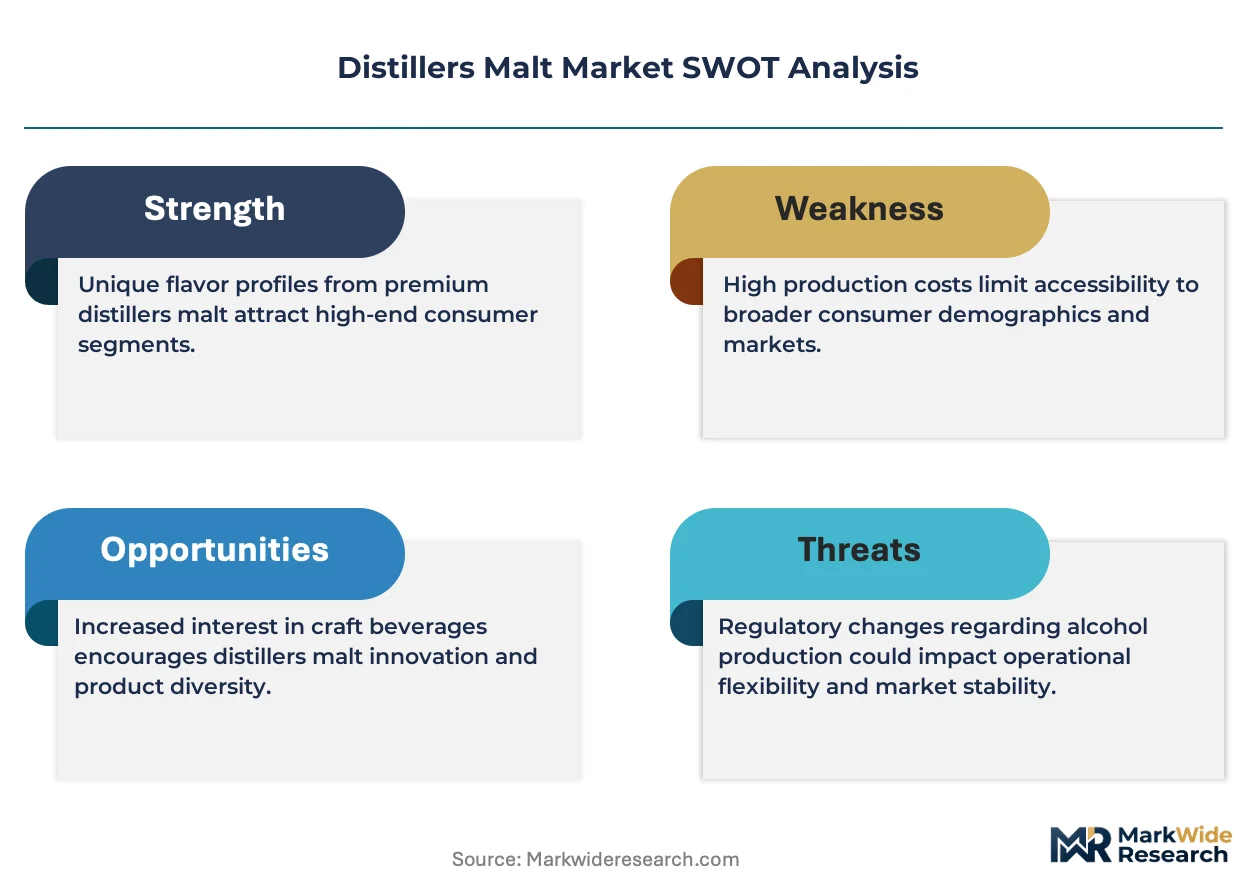
EFSA's tightening mycotoxin thresholds and diastatic power specifications for food-contact materials are compressing margins for maltsters serving European spirits supply chains, while Scotland's Speyside and Highland distillery clusters concentrate purchasing power among fewer buyers.
Growth Catalysts
- Clean-label spirits retail expansion:Organic malt specifications are capturing shelf space across European and North American premium whisky segments as consumer ingredient scrutiny intensifies.
- REACH compliance infrastructure:Maltsters investing in certified grain programs and in-house testing laboratories are securing preferential supply positions with bonded warehouse operators.
- Peated malt niche deepening:Islay-style producers are locking in long-term kilning contracts with Scottish malting facilities, creating defensible supply relationships.
Market Restraints
- Barley input cost volatility:Weather-driven two-row barley harvest variability in North American grain belts is squeezing margin predictability for distilling malt contracts.
- Supply concentration risk:Scotland's malting facility clustering around Speyside and Highland regions creates geographic vulnerability to climate-related production disruptions.
- Diastatic power technical ceiling:Kiln temperature trade-offs between enzyme preservation and color development limit extract yield optimization for premium spirit production.
Strategic Opportunities
- Craft distillery volume flexibility:Batch-size customization for smaller-scale whisky producers is opening service revenue streams beyond commodity malt supply.
- EU Green Deal carbon accounting:Early adopters of kiln energy specification optimization are positioning for preferential barley sourcing relationships with sustainability-mandated buyers.
- Peated malt geographic extension:Non-Islay Scottish regions and emerging North American distilleries are developing smoke-character malt programs to differentiate aged stock portfolios.
Industry Challenges
- Mycotoxin testing skill scarcity:Laboratory technicians capable of ochratoxin A and deoxynivalenol detection at EFSA threshold levels command premium compensation in tight labor markets.
- Bonded warehouse integration complexity:Maltsters must synchronize batch documentation with distillery fermentation scheduling and warehouse aging protocols across multi-year production cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distillers Malt Market |
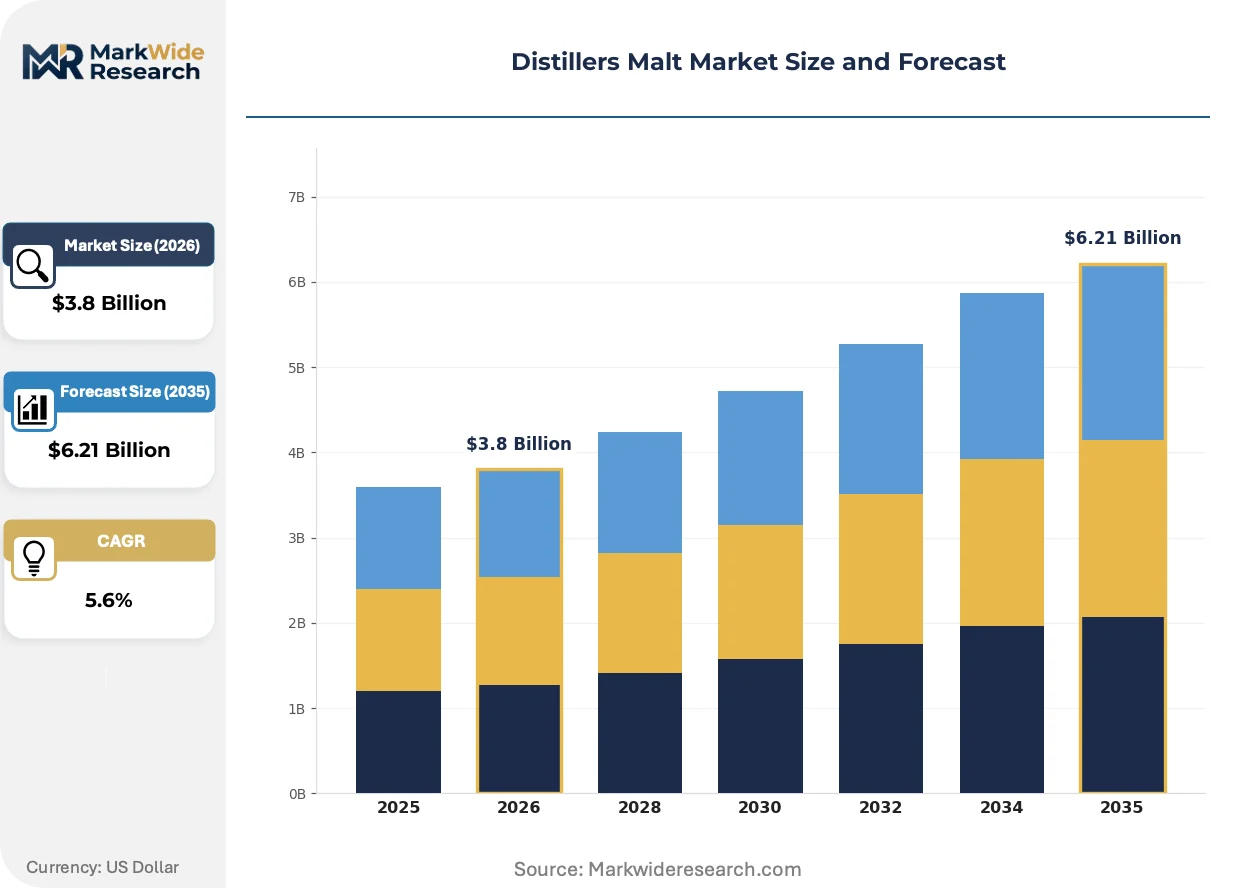
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Malt, Blended Malt, Organic Malt, Peated Malt Source Type: Barley, Wheat, Rye, Corn End Use: Spirits Production, Brewing, Food Flavoring, Culinary Uses Distribution Channel: Direct Sales, Retail, Online, wholesalers |
| Companies Covered | Cargill, Inc., Simpsons Malt Limited, Malteurop Group, Muntons Malt, Great Western Malting, Bairds Malt Limited, Crisp Malting Group, Viking Malt, Boortmalt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distillers Malt Market Strategic Shifts
Kiln technology, enzyme preservation science, and buyer procurement models are converging to reshape how distillers malt specifications are negotiated, tested, and delivered across premium spirits supply chains.
Controlled-atmosphere kilning systems is hybridizing traditional low-temperature drying with precision humidity management to maximize diastatic power retention while minimizing color development. Highland and Speyside distilleries are retrofitting existing facilities with these hybrid systems to meet tightening EFSA extract specifications. The technology is hybridizing competitive positioning among maltsters, separating those with capital-intensive kiln upgrades from commodity suppliers.
EFSA's evolving food-contact material standards are extending mycotoxin testing requirements from finished spirits back to raw malt inputs. Maltsters are deploying in-house chromatography laboratories to pre-certify batches before distillery delivery. Scottish malting facilities face the steepest compliance cost escalation given their concentration of premium single malt buyers with zero-tolerance quality thresholds.
Distilleries are consolidating supplier relationships around fewer maltsters capable of multi-year contract pricing with embedded carbon accounting documentation. Long-term agreements with fixed diastatic power and nitrogen content bands are displacing spot-market purchasing for aged whisky production programs. This consolidation pattern is most visible across Scotland's bonded warehouse operators managing multi-decade maturation inventories.
Distillers Malt Market Segmentation
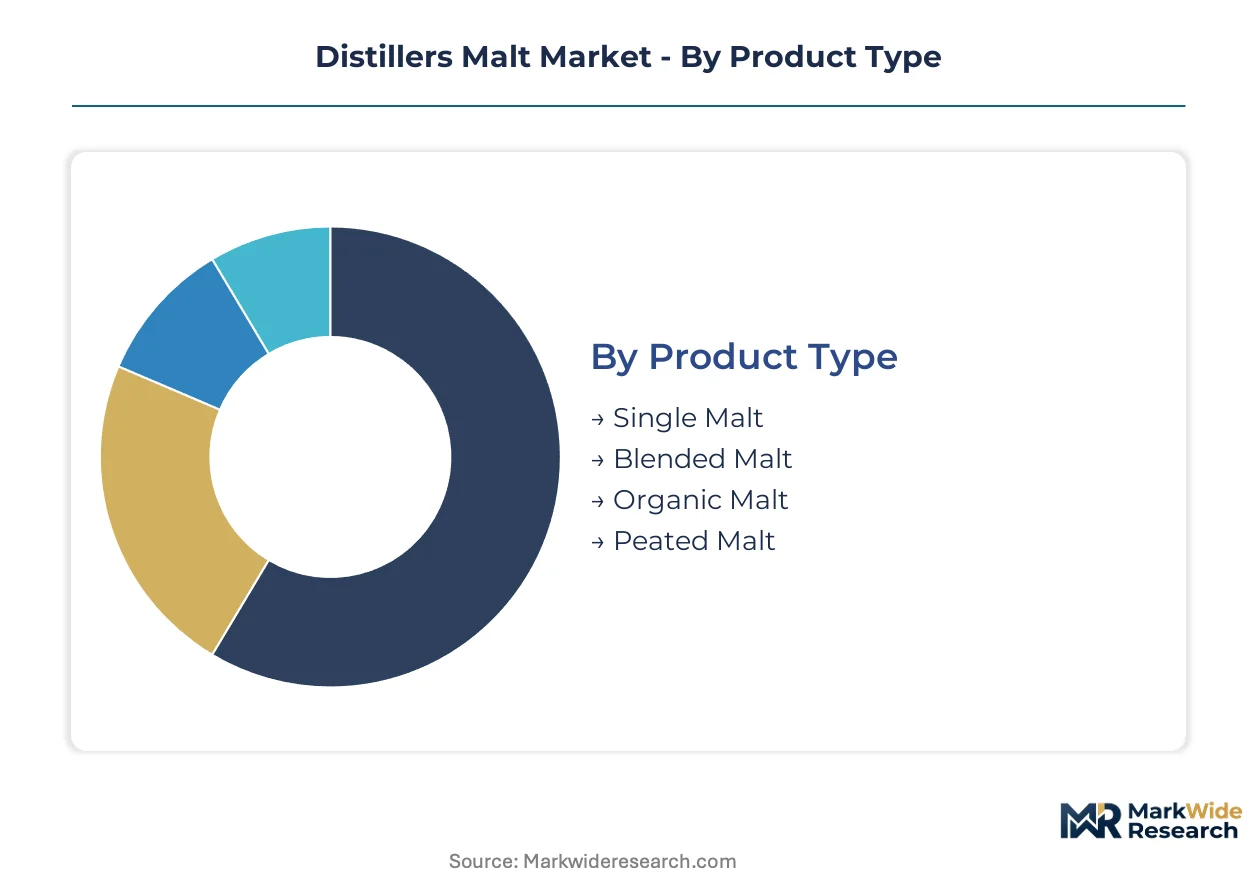
Distillers malt specifications diverge sharply across end-use applications, with spirit producers demanding precise enzyme preservation while food flavoring buyers prioritize aromatic intensity. Maltsters configure kilning profiles, grain sourcing, and batch documentation around these distinct performance requirements rather than selling undifferentiated commodity product.
Product Type:
Use-case spectrum spans premium aged whisky stock to clean-label organic spirits, with each specification tier commanding distinct margin pools and contract structures.
- Single Malt:Kilned at low temperatures to preserve diastatic power above 120°Lintner while minimizing color development below 5 EBC units. Scotland's bonded warehouse operators concentrate purchasing here, locking multi-year contracts with fixed nitrogen content bands to secure predictable fermentation yields for aged inventory.
- Organic Malt:Certified grain programs with full provenance documentation and zero synthetic input traces. European and North American retail channels are expanding shelf space for clean-label spirits, pushing distilleries toward certified organic specifications despite 15-25% raw material premiums.
- Blended Malt:Standardized enzyme profiles for volume spirit production with less stringent color constraints. Maltsters achieve scale economies through longer kiln runs.
- Peated Malt:Smoke-character kilning using Islay-sourced peat or regional alternatives. Islay-style producers outside Scotland are developing geographic extension programs.
The dominant share belongs to Single Malt, while Organic Malt is closing the gap fastest.
Source Type:
Grain selection determines extract potential, protein content, and regional supply security for maltsters serving distillery clusters.
- Barley:Two-row spring barley delivers fermentable extract above 80% with fine grind coarse grind difference below 2%. North American grain belts and Scottish lowlands concentrate supply, though weather-driven harvest variability squeezes margin predictability.
- Wheat:Lower enzyme content requires supplementation but produces lighter spirit character. German and French distilleries favor wheat malt for specific vodka and grain whisky specifications.
- Rye:Spicy flavor profile with higher beta-glucan content demanding modified mashing protocols. North American craft distilleries are expanding rye whisky programs.
- Corn:Highest starch content but minimal diastatic power, typically requiring enzymatic addition. Bourbon producers in Kentucky and Tennessee specify corn-dominant mash bills with malted barley as minority enzyme source.
Barley retains volume leadership by a wide margin, though Rye is expanding most quickly among craft distilleries seeking flavor differentiation.
End Use:
Application intensity varies from multi-year maturation cycles to immediate consumption, reshaping batch documentation and quality assurance requirements.
- Spirits Production:Primary commercial purpose with fermentable sugar conversion as core functional requirement. EFSA mycotoxin thresholds and REACH compliance govern European supply chains, while FDA Food Safety Modernization Act shapes American import protocols.
- Brewing:Adjacent demand from specialty beer producers seeking distilling-grade enzyme intensity for high-gravity worts. Smaller batch sizes and flexible specifications create service revenue opportunities.
- Food Flavoring:Malt extract and syrup applications prioritizing Maillard reaction products over enzyme activity. Kilning at higher temperatures develops color and aroma compounds.
- Culinary Uses:Niche applications in baking and confectionery with minimal specification rigor. Spot-market purchasing dominates.
Spirits Production commands the deepest contract value, while Food Flavoring offers the steadiest volume baseline.
Distribution Channel:
Procurement patterns stratify by buyer scale, with bonded warehouse operators consolidating around direct relationships and craft producers fragmenting across intermediaries.
- Direct Sales:Long-term agreements with fixed diastatic power and nitrogen content bands, embedded carbon accounting documentation, and synchronized batch delivery to distillery fermentation schedules. Scotland's Speyside and Highland clusters concentrate here.
- Wholesalers:Inventory aggregation for mid-scale distilleries lacking volume to justify direct maltster contracts. Regional grain merchants in Germany and France serve this tier.
- Retail:Bagged malt for home distillers and micro-producers, typically lower specification grades with minimal testing documentation.
- Online:Emerging channel for specialty peated and organic malts, enabling geographic reach beyond traditional malting facility catchment areas.
Direct Sales captures the premium contract value, while Online is gaining share fastest among craft producers outside established distillery clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scotland consumes distillers malt for premium single malt maturation cycles spanning decades, while American bourbon producers burn through enzyme inputs in weeks; this temporal differential shapes procurement contract structures across consuming geographies.
United States
Kentucky and Tennessee bonded warehouses drive demand for corn-dominant mash bills with minority barley malt enzyme sources. FDA Food Safety Modernization Act import protocols govern malt entering American distilleries from European suppliers. The Kentucky Bourbon Trail cluster concentrates purchasing power among heritage producers with multi-decade aging programs.
United Kingdom
Scotch whisky producers in Speyside and Highland regions specify low-temperature kilned malt with diastatic power above 120°Lintner. EFSA mycotoxin thresholds and REACH compliance shape maltster investments in certified grain programs. Islay distilleries maintain defensible peated malt supply relationships with Scottish malting facilities using island-sourced peat.
Germany
Wheat malt specifications for vodka and grain whisky production dominate distilling demand in Bavaria and North Rhine-Westphalia. ECHA chemical input regulations under REACH govern malting operation compliance costs. Hamburg and Berlin-Brandenburg regions host specialty maltsters serving craft distillery volume flexibility requirements.
France
Cognac and calvados producers utilize distillers malt for fruit brandy fermentation support in Normandy and Brittany. ANSM food-contact material standards align with EFSA evolving thresholds for ochratoxin A detection. The Île-de-France region concentrates spirits trading and warehousing infrastructure driving malt procurement consolidation.
Japan
Whisky distilleries in Yamazaki and Yoichi pursue premium single malt specifications matching Scottish diastatic power benchmarks. METI industrial standards and PMDA quality frameworks shape import malt acceptance protocols. The Chubu and Hokkaido regions host maltsters developing regional peat characterization programs for flavor differentiation.
Distillers Malt Market Competitive Environment
Capability concentration sits with specialty maltsters preserving enzyme activity through precision kilning; scale advantage sits with agricultural conglomerates securing North American two-row barley supply. The vendor base stratifies across three tiers: heritage Scottish malting facilities with bonded warehouse relationships, North American grain originators with captive barley networks, and European specialists offering flexible batch sizes for craft producers. Dominant competitive moves include kiln technology upgrades for diastatic power optimization and long-term contract consolidation with distillery fermentation scheduling integration.
Within the heritage facility tier, Simpsons Malt Limited and Bairds Malt Limited represent Scottish malting specialists with Speyside and Highland distillery cluster proximity. Cargill, Inc. exemplifies the agricultural-integrated archetype leveraging North American grain origination networks for consistent distilling barley supply. Malteurop Group occupies a position bridging flexible European batch production with multi-market distribution reach.
| Leading Market Players |
|---|
| Cargill, Inc. |
| Simpsons Malt Limited |
| Malteurop Group |
| Muntons Malt |
| Great Western Malting |
| Bairds Malt Limited |
| Crisp Malting Group |
| Viking Malt |
| Boortmalt |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Scottish malting facilities for premium single malt specifications determines both pricing tier spreads and supply chain shape, compressing margin buffers when EFSA mycotoxin thresholds tighten and Speyside distillery clusters consolidate purchasing power around fewer approved suppliers.
Pricing Analysis
Long-term offtake contracts with fixed diastatic power and nitrogen content bands dominate premium tier procurement, displacing spot-market purchasing for aged whisky production programs. Price differentiation rests on certification grade for organic specifications and volume scale for blended malt standard grades. Cost compression in the craft distillery tier is intensifying because Malteurop Group and regional specialists compete on batch-size flexibility. Bonded warehouse operators managing multi-decade maturation inventories exhibit the lowest price sensitivity, while emerging North American distilleries without established supplier relationships face the highest.
Supply Chain Analysis
Tariff exposure between the United Kingdom and European Union member states dominates supply chain risk calculus for maltsters serving cross-border distillery clients. Geographic supply concentration centers on Scotland, North American grain belts, and Germany for wheat malt specifications. Raw material dependencies draw from two-row spring barley, Islay-sourced peat, and certified organic grain programs. Single-source vulnerability pervades the peated malt segment where island-sourced peat lacks ready substitutes. Distribution runs through direct sales relationships for volume buyers and regional wholesalers serving mid-scale German and French distilleries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades the distillers malt landscape as craft distillery volume flexibility demands create service niches that agricultural conglomerates with rigid batch configurations cannot efficiently fill.
For Market Incumbents: Entrench bonded warehouse relationships through synchronized batch documentation integration with distillery fermentation scheduling and warehouse aging protocols across multi-year production cycles. Invest in controlled-atmosphere kilning upgrades to preserve diastatic power above competitor commodity supply. Certification investment in EFSA-aligned in-house chromatography laboratories defends against emerging entrants lacking mycotoxin testing infrastructure. For New Entrants and Emerging Players: North American craft distillery clusters outside Kentucky and Tennessee present the most penetrable white-space target, particularly rye whisky programs seeking flavor differentiation through specialty malt specifications. Peated malt geographic extension programs in non-Islay Scottish regions and emerging Japanese distilleries offer second-tier entry points. A flexible batch-size service model with embedded carbon accounting documentation provides the essential go-to-market angle against scale-focused incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialty maltsters with kiln technology differentiation and established distillery cluster proximity. Long-term viability over the next decade hinges on carbon accounting compliance infrastructure and REACH-aligned chemical input governance. Acquisition targets should display certified grain program maturity and in-house testing laboratory capability. The signal to watch is EU Green Deal carbon accounting rule finalization reshaping barley sourcing decisions and kiln energy specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Kilning Upgrade | Precision humidity management separates premium maltsters from commodity suppliers in Speyside and Highland clusters. |
| Certified Organic Grain Program Expansion | Full provenance documentation captures clean-label spirits shelf space in European and North American retail channels. |
| In-House Mycotoxin Testing Laboratory | Pre-certification capability at EFSA threshold levels secures preferential supply positions with bonded warehouse operators. |
| Flexible Batch-Size Service Model | Craft distillery volume customization opens revenue streams beyond commodity malt supply for mid-scale producers. |
| Carbon Accounting Documentation Integration | Embedded emissions tracking positions maltsters for sustainability-mandated buyer procurement consolidation. |
Study Parameters
A spread of perspectives from malting facility operations managers, distillery procurement leads, bonded warehouse inventory controllers, and EFSA regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary interviews with Scottish malting specialists and North American grain originators combined with secondary validation from customs and trade data, EFSA guidance documents, and SEC filings from agricultural conglomerates. Bottom-up volume modeling across product type, source grain, and end-use segments triangulated against top-down market sizing from industry association statistics.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling capacity utilization at Scottish malting facilities against Speyside and Highland distillery cluster expansion plans. Segmentation dimensions included product type tier, source grain variety, end-use application intensity, and distribution channel structure. CAGRs were derived from trend extrapolation of contract volume growth and price trajectory analysis. Industry-specific forecast inputs incorporated kiln technology adoption curves and EFSA regulatory implementation timelines.
Practitioners should monitor barley harvest variability in North American grain belts and EU Green Deal carbon accounting rule finalization for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Hopped Malt Extract Market
Alcoholic Beverages
Single Serve Wine Market
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
Tequila Market
Alcoholic Beverages
Cider Market
Alcoholic Beverages
Rice Wine Market
Alcoholic Beverages
Malt Whiskey Market
Alcoholic Beverages
France Alcohol E-Commerce Market
Alcoholic Beverages
Europe Wine Coolers Market
Alcoholic Beverages
Champagne Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Isoamyl Alcohol Market
Alcoholic Beverages
Organic Alcoholic Beverages Market
Alcoholic Beverages
China Tequila Market
Alcoholic Beverages
Alcoholic Tea Market
Alcoholic Beverages
Canned Cocktails Market