
 Pinot Noir Market | 2026-2036
Pinot Noir Market Size, Share, and Industry Trends Forecast 2026-2036
Pinot Noir Market Analytics
EU Green Deal soil health mandates and the California Sustainable Winegrowing Alliance certification program is hardening requirements for vineyard water use and chemical inputs. Domaine de la Romanée-Conti anchors its position through monopole control of Grand Cru sites in Vosne-Romanée. Gallo leverages massive distribution infrastructure to push Pinot Noir volume through retail and hospitality chains. Kosta Browne differentiates via single-vineyard Sonoma Coast and Russian River Valley bottlings with allocated scarcity.
Pinot Noir denotes a thin-skinned Vitis vinifera cultivar requiring cool-climate diurnal temperature shifts and calcareous or volcanic soils to achieve phenolic ripeness without excessive sugar accumulation; winemakers typically employ partial whole-cluster fermentation and restrained oak regimes to preserve terroir expression. Red Pinot Noir occupies the core volume and value pool across fine-wine auctions and restaurant lists. Sparkling Pinot Noir, including Blanc de Noir methods, captures expanding share in English sparkling wine and Tasmanian production. Old Vine Pinot Noir commands scarcity premiums in pockets of Martinborough and the Santa Lucia Highlands.
France's INAO appellation rules, the USDA National Organic Program, and New Zealand's Winegrowers sustainability certification collectively govern labeling integrity, pesticide residue thresholds, and export market access. These frameworks elevate compliance costs for smaller producers while rewarding certified estates with tariff advantages and retail listing priority. Stakeholders must track evolving carbon border adjustments and water-right allocations that will reshape where new Pinot Noir hectares prove economically viable.
Market Dynamics
EU Green Deal soil health mandates and California Sustainable Winegrowing Alliance certification are forcing vineyard operators to absorb higher compliance costs while repositioning plantings toward lower-intervention farming methods.
Growth Catalysts
- Sommelier-driven on-trade expansion:Premium restaurant lists in France and the United States are absorbing more vineyard-designate bottlings, creating pull-through for terroir-specific expressions.
- EU Green Deal subsidies:Vineyard operators accessing the EU's Common Agricultural Policy funds are redirecting hectares toward regenerative practices that command retail listing priority.
- Cool-climate diurnal shifts:Oregon's Willamette Valley and Central Otago in New Zealand are experiencing favorable temperature patterns that extend hang time without sugar accumulation.
Market Restraints
- Calcareous soil scarcity:Suitable vineyard land in Burgundy's Côte de Nuits commands extreme acquisition premiums, concentrating new plantings among capital-heavy estates.
- Thin-skin viticultural risk:Pinot Noir's inherent susceptibility to botrytis and sunburn elevates crop insurance costs and vintage variability for growers.
- Whole-cluster fermentation expertise gap:Skilled labor capable of executing partial stem-inclusion protocols without vegetal extraction remains concentrated in Old World regions.
Strategic Opportunities
- English sparkling expansion:Blanc de Noir production in Kent and Sussex is capturing shelf space previously held by Champagne, creating new outlet demand for Pinot Noir base wine.
- Tasmanian cool-climate development:Underutilized vineyard capacity on Australia's island state offers diurnal conditions comparable to Central Otago with lower land costs.
- Old vine scarcity marketing:Martinborough and Santa Lucia Highlands producers with 30-plus-year plantings can command auction premiums through verified vine-age documentation.
Industry Challenges
- Water-right allocation compression:California's Sustainable Groundwater Management Act is restricting irrigation access in Russian River Valley, forcing dry-farm conversion or hectare abandonment.
- INAO appellation compliance timelines:French producers seeking Grand Cru elevation face multi-year administrative review cycles that delay price-tier repositioning.
- Oak regime standardization gaps:Absence of unified cooperage certification creates batch-to-batch variation that undermines allocated scarcity positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pinot Noir Market |
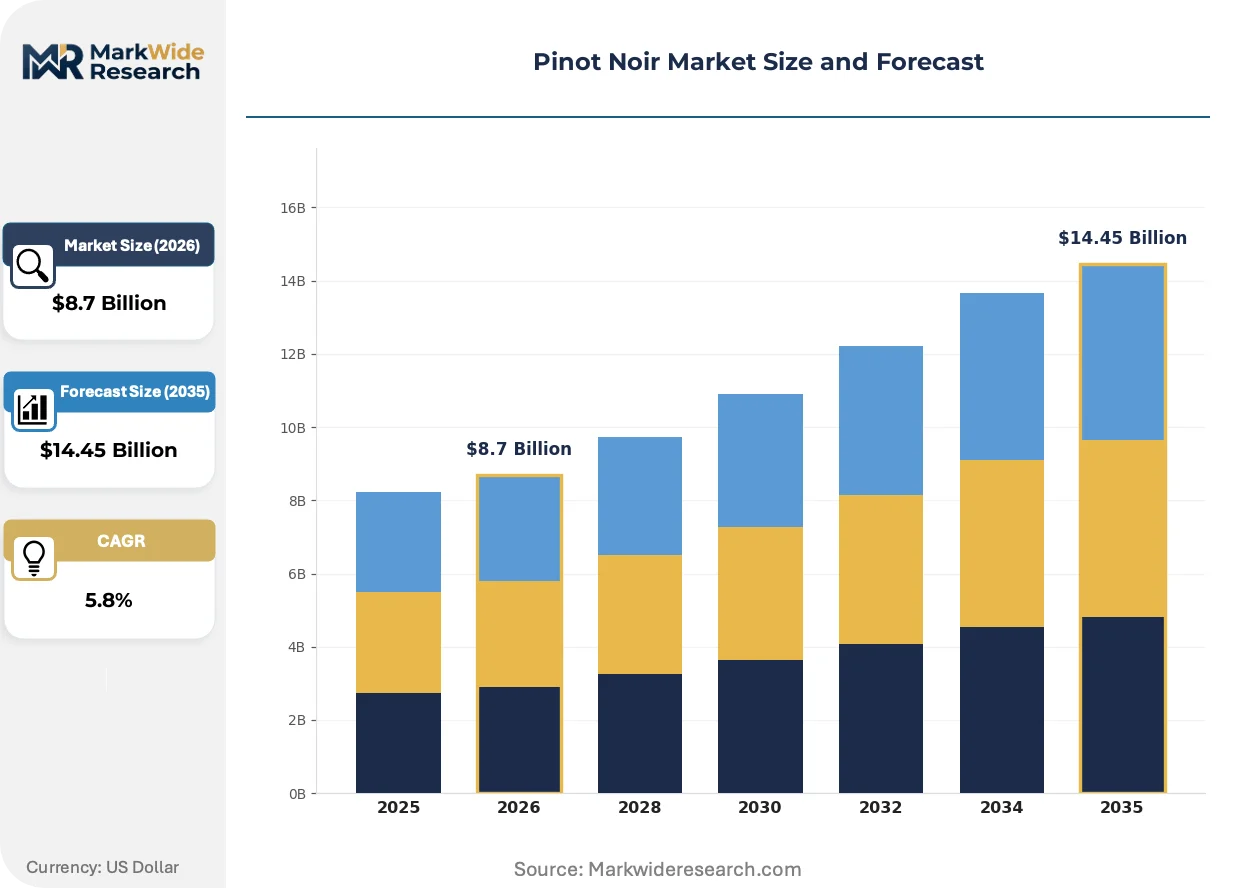
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Varietal Type: Red Pinot Noir, Blanc de Noir, Sparkling Pinot Noir, Old Vine Pinot Noir Flavor Profile: Cherry, Raspberry, Earthy, Floral Packaging Type: Bottle, Tetra Pak, Keg, Can Distribution Channel: Online Retail, Wine Shops, Restaurants, Supermarkets |
| Companies Covered | Felton Road, Domaine Drouhin, Gallo, La Crema, Carmel Road, Kosta Browne, Ata Rangi, Meiomi, Domaine de la Romanée-Conti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pinot Noir Market Evolving Landscape
Precision viticulture and regenerative farming protocols are compressing the gap between estate-scale and négociant production quality, while certification-driven retail access is hardening channel requirements.
Optical grape sorting technology is consolidating quality control at the winery level. High-resolution camera systems now remove sub-par berries before destemming, enabling larger-scale producers to achieve consistency previously associated with hand-sorting estates. Burgundy's négociant houses are adopting these systems fastest, compressing the traditional quality hierarchy between domaine-bottled and merchant-labeled offerings.
EU Green Deal carbon border adjustment mechanisms are reshaping export compliance burdens. The phased implementation of embedded carbon reporting for agricultural goods entering the European Union is forcing non-EU producers to document vineyard fuel and fertilizer inputs. New Zealand Winegrowers sustainability certification is adapting its audit protocols to satisfy this incoming requirement, positioning certified estates for tariff advantage.
Direct-to-consumer allocation models are displacing traditional three-tier distribution for scarcity-tier bottlings. Sonoma Coast and Willamette Valley producers with mailing list waitlists are unbundling restaurant and retail placement, capturing margin previously absorbed by wholesale channels. This channel shift concentrates in the United States, where regulatory fragmentation between states complicates compliance but rewards scale with consumer relationship data.
Pinot Noir Market Segmentation
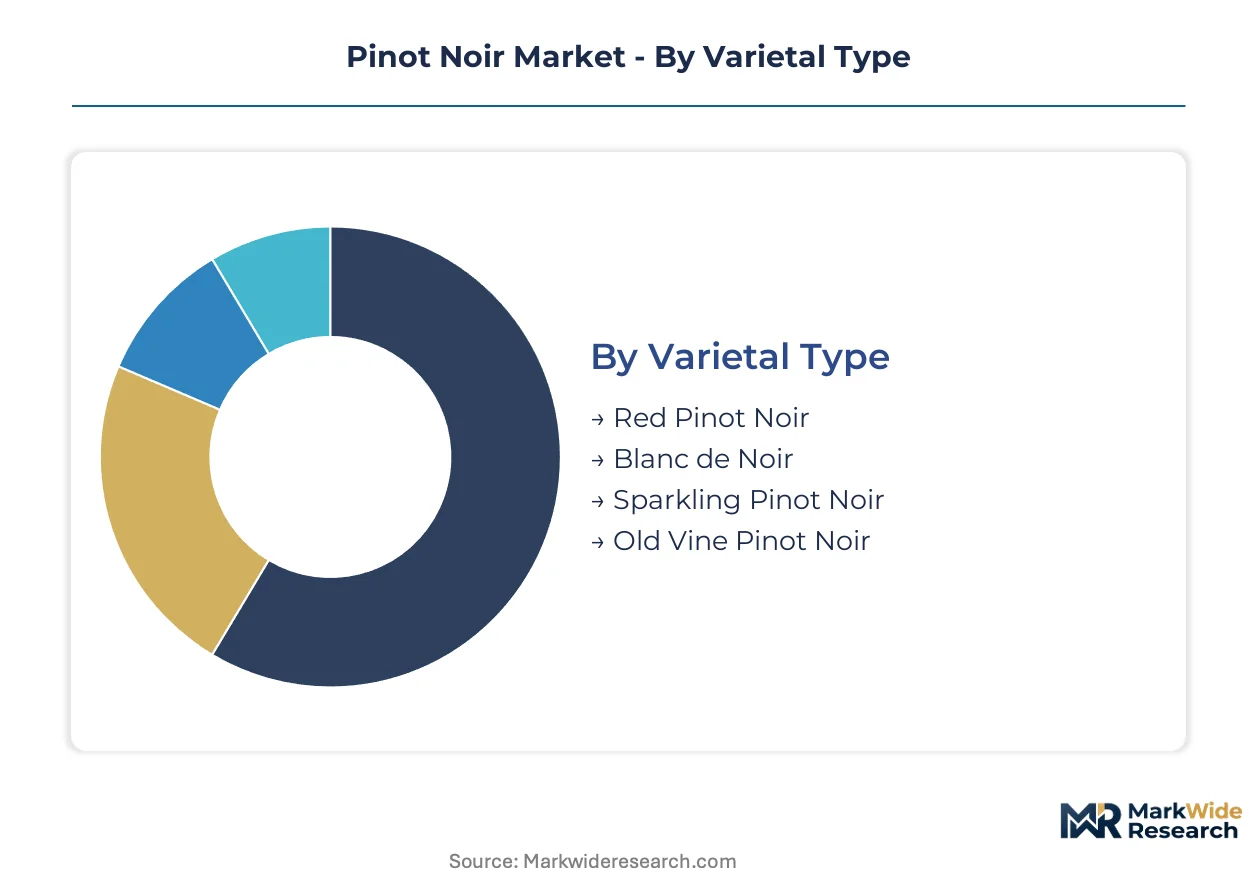
Pinot Noir's thin-skinned viticulture and terroir sensitivity fragment commercial opportunity across varietal expressions, flavor archetypes, and channel formats. Buyers navigate trade-offs between provenance authenticity, packaging convenience, and sommelier endorsement that reshape where value concentrates.
Varietal Type:
Winemaking intention—still versus sparkling, young vine versus old vine—determines price-tier access and allocation scarcity.
- Red Pinot Noir:The core still-wine expression dominates fine-wine auctions and restaurant list placements through vineyard-designate bottlings from Burgundy's Côte de Nuits and Oregon's Willamette Valley. Demand concentrates in premium on-trade channels where sommelier-driven lists absorb limited-production estate bottlings; EU Green Deal vineyard subsidies are redirecting hectares toward lower-intervention farming that commands retail listing priority.
- Old Vine Pinot Noir:Plantings exceeding thirty years deliver concentrated fruit with naturally lower yields that scarcity marketers leverage for auction premiums. Verified vine-age documentation from Martinborough and California's Santa Lucia Highlands unlocks price-tier repositioning unavailable to younger vineyard sources.
- Blanc de Noir:White wine produced from red Pinot Noir grapes via minimal skin contact, capturing expanding share in English sparkling wine from Kent and Sussex.
- Sparkling Pinot Noir:Base wine for traditional method production, with Tasmanian and Central Otago volumes climbing as Champagne alternatives capture shelf space.
Red Pinot Noir leads on scale; Old Vine Pinot Noir leads on momentum.
Flavor Profile:
Consumer recognition of signature aromatics drives retail placement and restaurant pairing decisions.
- Cherry:The dominant primary fruit marker across cool-climate expressions from Oregon and New Zealand, recognizable to entry-level buyers and sommeliers alike. Supermarket and online retail channels prioritize cherry-forward bottlings for volume turnover; California Sustainable Winegrowing Alliance certification adds shelf-talk credibility in US markets.
- Earthy:Forest floor and mushroom notes signal Burgundian terroir authenticity that commands restaurant list placement at premium price points. Sommelier-driven on-trade expansion in France and the United States absorbs more vineyard-designate bottlings with pronounced earthy character; INAO appellation rules govern labeling integrity for these expressions.
- Raspberry:Brighter red fruit expression typical of warmer vintage conditions or specific clonal selections.
- Floral:Violet and rose petal aromatics associated with whole-cluster fermentation protocols.
Cherry dominates volume placement; earthy expressions capture margin concentration.
Packaging Type:
Consumption occasion—cellar aging versus immediate consumption—shapes format selection and margin structure.
- Bottle:Traditional 750ml glass with cork closure remains mandatory for fine-wine positioning and cellar aging programs. Restaurant and wine shop channels require bottle format for vineyard-designate offerings; optical grape sorting technology enables larger-scale producers to achieve consistency previously associated with hand-sorting estates.
- Can:Single-serve aluminum formats penetrate outdoor and casual dining occasions where portability outweighs provenance signaling. Direct-to-consumer allocation models are displacing traditional three-tier distribution for scarcity-tier bottlings in the United States.
- Keg:On-premise draft format for by-the-glass programs in high-volume hospitality settings.
- Tetra Pak:Aseptic carton for value-tier retail in markets prioritizing shipping efficiency over cellar aging.
Bottle commands premium positioning; can formats expand occasion access fastest.
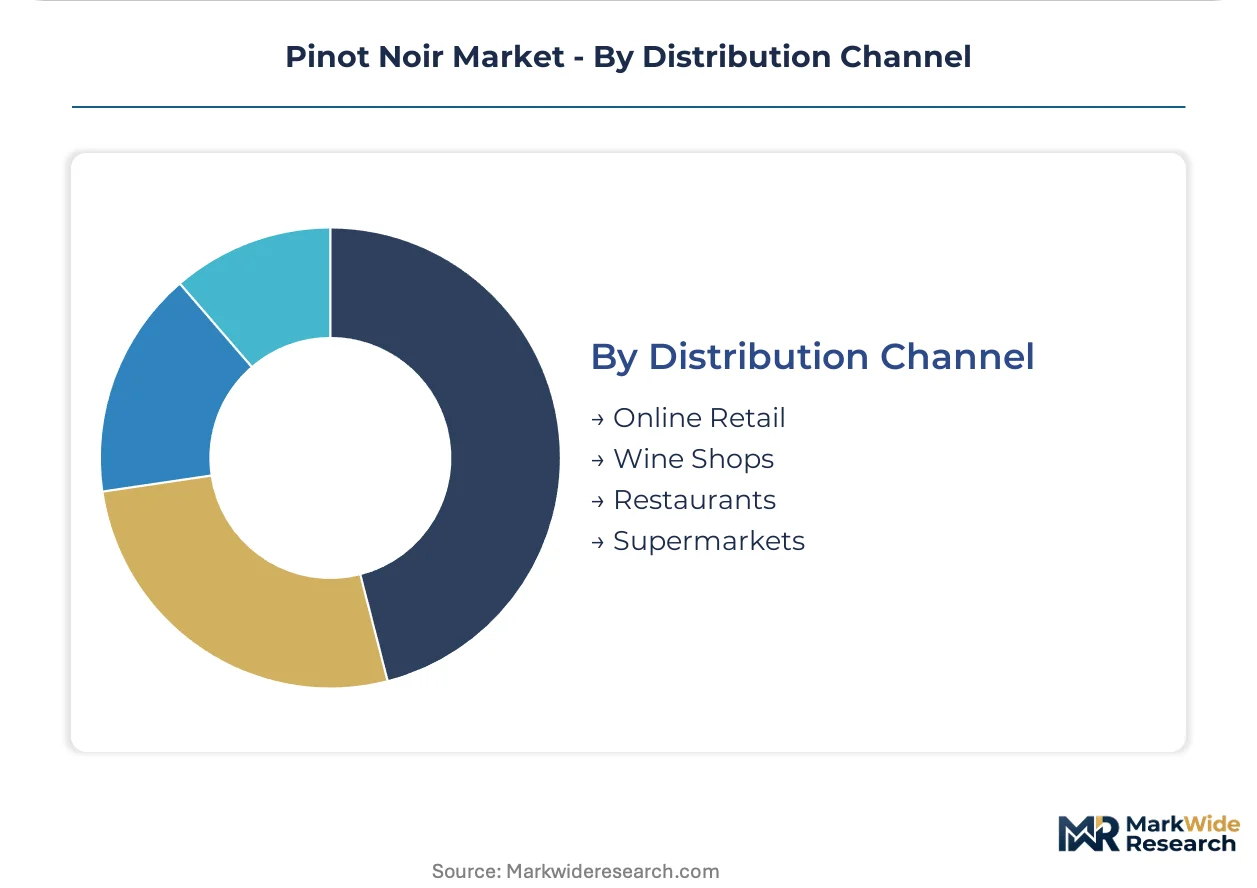
Distribution Channel:
Channel selection determines margin capture and consumer relationship depth.
- Restaurants:On-trade placement validates quality perception through sommelier curation and food pairing context. Premium restaurant lists in France and the United States are absorbing more vineyard-designate bottlings; direct-to-consumer allocation models unbundle restaurant placement from retail to capture margin previously absorbed by wholesale channels.
- Online Retail:E-commerce platforms enable mailing list allocation and scarcity-tier access without distributor markup. Sonoma Coast and Willamette Valley producers with waitlists are capturing consumer relationship data that rewards scale; regulatory fragmentation between US states complicates compliance but enables margin retention.
- Wine Shops:Specialist retail provides education and discovery for enthusiast buyers seeking terroir-specific expressions.
- Supermarkets:Mass retail concentrates volume for cherry-forward, price-accessible bottlings with recognizable labeling.
Restaurants anchor prestige positioning; online retail climbs fastest on margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pinot Noir viticulture traces its commercial lineage to Burgundy's Côte de Nuits, where monastic cultivation established the varietal's terroir-driven reputation centuries before New World plantings emerged.
France
INAO appellation rules govern Grand Cru elevation in Vosne-Romanée and Gevrey-Chambertin, where vineyard land scarcity concentrates ownership among capital-heavy estates. EU Green Deal subsidies redirect hectares toward regenerative practices. Domaine de la Romanée-Conti anchors production through monopole control of La Tâche and Romanée-Conti sites.
United States
Sommelier-driven restaurant lists in New York and San Francisco absorb vineyard-designate bottlings from Oregon's Willamette Valley and California's Russian River Valley. California's Sustainable Groundwater Management Act restricts irrigation access, forcing dry-farm conversion. Kosta Browne occupies the allocated scarcity tier through single-vineyard Sonoma Coast production.
New Zealand
New Zealand Winegrowers sustainability certification adapts audit protocols for EU carbon border adjustment compliance, positioning Central Otago exporters for tariff advantage. Cool-climate diurnal shifts extend hang time without excessive sugar accumulation. Felton Road and Ata Rangi anchor Martinborough and Central Otago clusters respectively.
Germany
Baden and Pfalz regions cultivate Spätburgung clones with increasing estate-bottled ambition, though Ahr Valley flooding disrupted established vineyard patterns. German wine law modernizations under the 2021 Öko-Weinbau standards elevate organic labeling integrity. Small-scale producers in the Ahr are replanting on steeper, less flood-prone slopes.
Australia
Tasmanian vineyard development offers diurnal conditions comparable to Central Otago with lower land acquisition costs for sparkling base wine production. The country's national agricultural regulator enforces export certification for residue thresholds. Yarra Valley producers face water allocation pressure while Tasmania's underutilized capacity attracts investment.
Pinot Noir Market Competitive Landscape
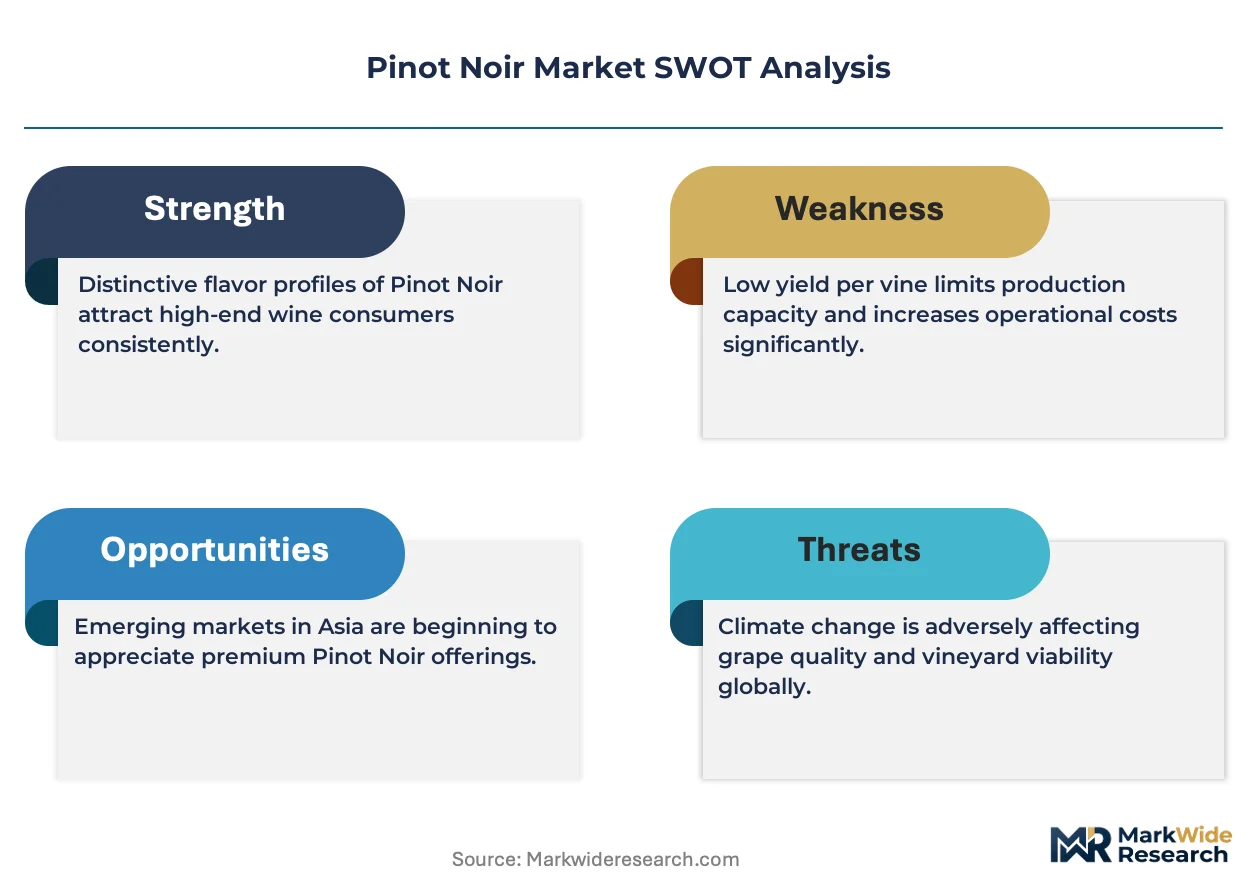
Premium-margin players sit above commodity-margin players across scarcity allocation and terroir authentication dimensions. The market structures into three tiers: monopole estates commanding auction premiums, allocated single-vineyard specialists, and volume-scale négociant-distributed labels. Consolidation concentrates in distribution infrastructure rather than vineyard ownership. Dominant competitive moves include direct-to-consumer allocation model expansion and sustainability certification acquisition for retail listing priority.
Within the monopole and allocated scarcity tier, Domaine de la Romanée-Conti and Kosta Browne exemplify divergent geographic strategies—Old World appellation control versus New World mailing list cultivation. Gallo occupies the scale-driven infrastructure position, leveraging distribution breadth across retail and hospitality channels. Among New Zealand-based producers, Felton Road and Ata Rangi represent the sustainability-certified export archetype, positioning for EU carbon border adjustment compliance.
| Leading Market Players |
|---|
| Felton Road |
| Domaine Drouhin |
| Gallo |
| La Crema |
| Carmel Road |
| Kosta Browne |
| Ata Rangi |
| Meiomi |
| Domaine de la Romanée-Conti |
| Others |
Value Network & Pricing Analysis
Optical grape sorting technology is compressing quality-control costs at scale while concentrating supply power among estates that can justify capital deployment. This shift simultaneously erodes the traditional quality premium of hand-sorting domaines and rewards négociant houses with volume throughput, restructuring where margin pools form across Burgundy's hierarchy.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates vineyard-designate auction tiers from allocated mailing-list bottlings and mass-market retail labels. Price differentiation rests on INAO appellation tier and California Sustainable Winegrowing Alliance certification status. Cost compression in the standard tier is intensifying because optical sorting enables négociant quality parity. Supermarket buyers exhibit highest price sensitivity; restaurant sommeliers and auction collectors demonstrate lowest.
Supply Chain Analysis
Freight cost volatility for temperature-controlled container shipping from New Zealand and Tasmania is compressing export margins for Central Otago producers. Geographic supply concentrates in France, the United States, and New Zealand. Raw material dependencies include French oak cooperage, diatomaceous earth filtration media, and sulfur dioxide inputs. Single-source vulnerability runs through Grand Cru vineyard land scarcity in Vosne-Romanée. Distribution runs through three-tier wholesale networks in the United States and direct-to-consumer allocation for scarcity-tier estates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Pinot Noir hinges on sustainability certification cost absorption being offset by retail listing priority and tariff advantage in EU export markets. Estates that front-loaded regenerative farming compliance are capturing price-tier repositioning unavailable to laggards.
For Market Incumbents: To counter négociant quality compression from optical sorting technology, domaine-bottled estates should deepen vine-age documentation for scarcity marketing and secure grandfathered water rights in Russian River Valley before California's Sustainable Groundwater Management Act triggers allocation cuts. Certification investment in EU Green Deal alignment offers tariff insulation.
For New Entrants and Emerging Players: Launch via direct-to-consumer allocation models in English sparkling wine base wine supply, where Kent and Sussex producers face capacity constraints for Blanc de Noir expansion. Tasmania's underutilized vineyard land offers the most penetrable geography with Central Otago-comparable diurnal conditions and lower land acquisition costs.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Willamette Valley estates lacking mailing list infrastructure but holding certified sustainable vineyard hectares. Long-term viability favors producers with locked-in water rights and documented old vine inventory. The signal to watch is EU carbon border adjustment implementation timing for non-certified New World exporters.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainability Certification Acquisition | EU Green Deal alignment unlocks tariff advantages and retail listing priority for certified estates. |
| Direct-to-Consumer Channel Expansion | Mailing list cultivation in Sonoma Coast and Willamette Valley captures margin from wholesale displacement. |
| Old Vine Documentation Program | Verified vine-age records from Martinborough and Santa Lucia Highlands enable auction premium positioning. |
| English Sparkling Base Wine Supply Agreement | Blanc de Noir contracts with Kent and Sussex producers tap Champagne-alternative shelf space growth. |
| Tasmanian Vineyard Development | Underutilized capacity with Central Otago-comparable diurnal conditions offers cost-advantaged expansion. |
Research Methodology
Direct dialogue with vineyard operators, winemaking directors, restaurant sommeliers, and export compliance officers grounded qualitative findings in operational reality. Secondary validation drew from INAO appellation filings, USDA National Organic Program registrations, New Zealand Winegrowers sustainability audit reports, and EU Common Agricultural Policy subsidy disclosures. Bottom-up hectare and yield estimates triangulated against top-down export volume data.
Segment-level value outputs across the projection horizon reflect varietal type, flavor profile archetype, packaging format, and distribution channel dimensions. CAGRs derived from historical price trajectory analysis and planted hectare expansion rates. Forecast inputs incorporated climate model projections for diurnal shift patterns in Oregon and Central Otago, plus EU carbon border adjustment phase-in assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme vintage conditions from botrytis pressure or drought-induced yield collapse. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Malt Whiskey Market
Alcoholic Beverages
Craft Beer Market
Alcoholic Beverages
Sparkling Wine Market
Alcoholic Beverages
Liquor Flavored Ice Cream Market
Alcoholic Beverages
Beer Mug Market
Alcoholic Beverages
Brewing Enzymes Market
Alcoholic Beverages
Hogshead Barrel Market
Alcoholic Beverages
Global Malted Barley Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
White Wine Market
Alcoholic Beverages
Barrel Liner Market
Alcoholic Beverages
Home Brew Boiler Market
Alcoholic Beverages
Luxury Wines and Spirits Market
Alcoholic Beverages
China Tequila Market
Alcoholic Beverages
Lager Market
Alcoholic Beverages
Malaysia Alcohol E-Commerce Market