
 Beverage Cooler Market | 2026-2036
Beverage Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Cooler Market Outlook
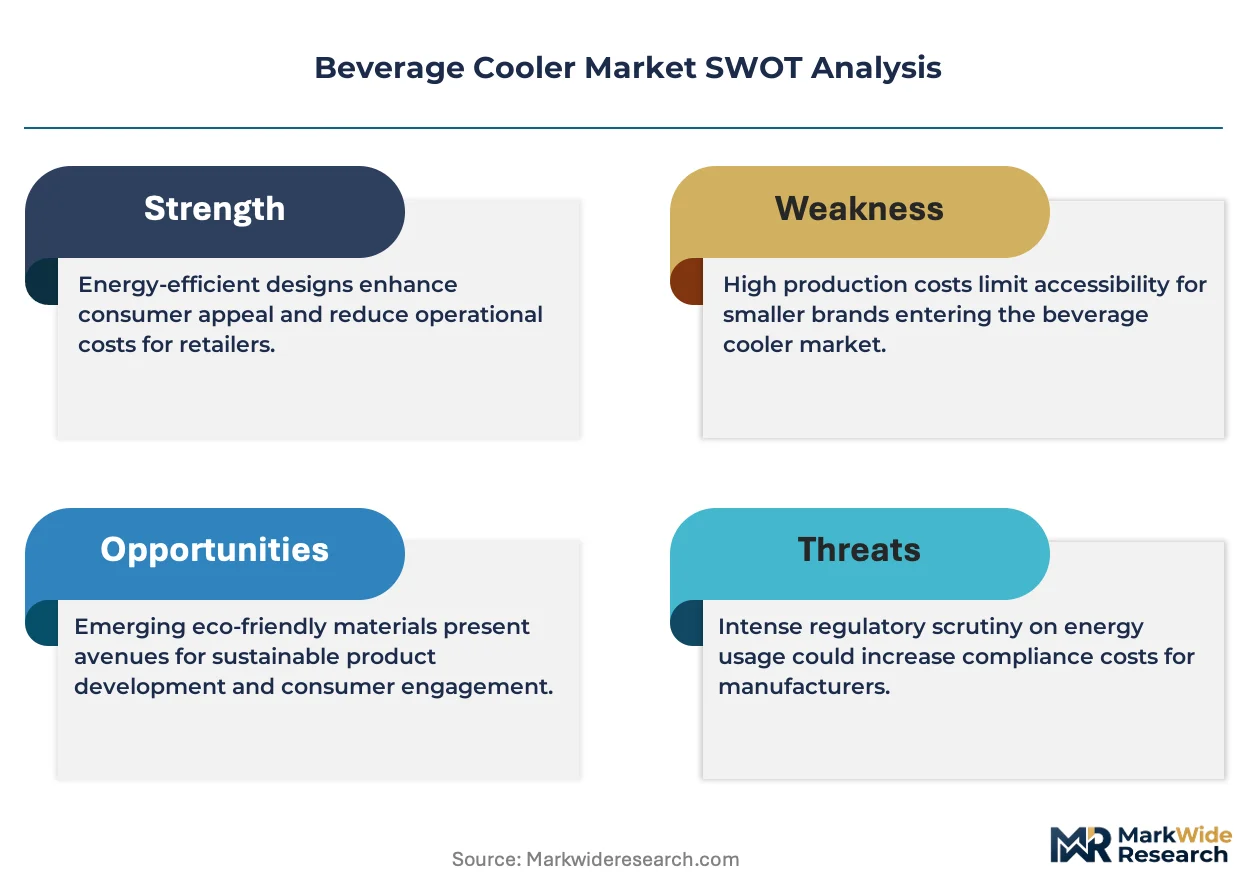
Foodservice operators are bifurcating from household buyers as the dominant demand archetype for premium cold-storage equipment. Haier Group Corporation leverages its manufacturing scale across multiple cooling technology platforms to serve this shift. Perlick Corporation specializes in undercounter systems for bars and restaurants, anchoring its position in commercial specification channels. Electrolux AB competes through brand strength in European foodservice markets while extending its distribution into North American retail chains.
A beverage cooler is a thermally insulated cabinet employing compressor, thermoelectric, or absorption mechanisms to maintain temperatures between 34°F and 64°F for stored drinks, typically constructed with polyurethane foam insulation, tempered glass doors, and LED interior lighting for commercial display visibility. Free-standing units dominate household and retail installations where floor placement flexibility matters, while undercounter formats capture margin pools in commercial kitchen renovations where space optimization governs specification. Compressor cooling technology leads volume shipments due to superior efficiency in high-ambient conditions, though thermoelectric segments gain traction in portable applications where noise suppression and vibration elimination prioritize battery or low-wattage operation.
EPA energy conservation standards and DOE test procedures shape minimum efficiency thresholds for electrically operated refrigeration equipment sold in the United States, directly influencing compressor selection and insulation specifications for manufacturers targeting this market. Ecodesign requirements and CE marking obligations under EU regulation mandate refrigerant containment and energy labeling for units distributed across European member states, creating compliance cost differentials between regional product lines. Stakeholders must monitor refrigerant phase-down schedules and emerging state-level building electrification codes that will redefine viable cooling architectures before the next replacement cycle peaks.
Market Dynamics
Foodservice cold-chain expansion collides with refrigerant phase-down mandates to restructure compressor sourcing and insulation specifications across commercial beverage cooler manufacturing.
Growth Catalysts
- EPA Energy Conservation Standards:Tightened DOE test procedures for electrically operated refrigeration equipment accelerate replacement cycles in United States convenience stores and quick-service restaurants.
- Quick-service restaurant buildouts:Cold-drink display capacity expansion across franchise networks drives specification volume for undercounter and free-standing units.
- Thermoelectric cooling modules:Solid-state refrigeration advances enable portable beverage cooler segments where vibration elimination and noise suppression prioritize battery operation.
Market Restraints
- Refrigerant input cost volatility:Hydrofluorocarbon phase-down schedules under EPA mandates and EU F-Gas Regulation create procurement uncertainty for compressor manufacturers.
- Supply concentration in compressor motors:High-efficiency variable-speed compressor production clusters in East Asian manufacturing bases, exposing North American and European OEMs to logistics disruption.
- Technical limitation of thermoelectric efficiency:Peltier coefficient of performance constraints restrict thermoelectric beverage coolers to low-capacity portable applications below 50 liters.
Strategic Opportunities
- Underpenetrated India foodservice:Organized retail and quick-service restaurant penetration below 10% in tier-2 and tier-3 cities creates whitespace for commercial beverage cooler deployment.
- EU Ecodesign energy labeling:Mandatory efficiency disclosure requirements create competitive differentiation for manufacturers achieving A+++ ratings on European product lines.
- IoT-enabled predictive maintenance:Sensor integration with compressor diagnostics enables outcome-based service contracts displacing traditional break-fix aftermarket models.
Industry Challenges
- Refrigerant handling certification timelines:EPA Section 608 technician certification requirements and EU F-Gas company certification create installation bottlenecks for service networks.
- Integration complexity with building electrification codes:Emerging state-level mandates for all-electric new construction in California, New York, and Washington require refrigeration system redesigns for grid-responsive operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Cooler Market |
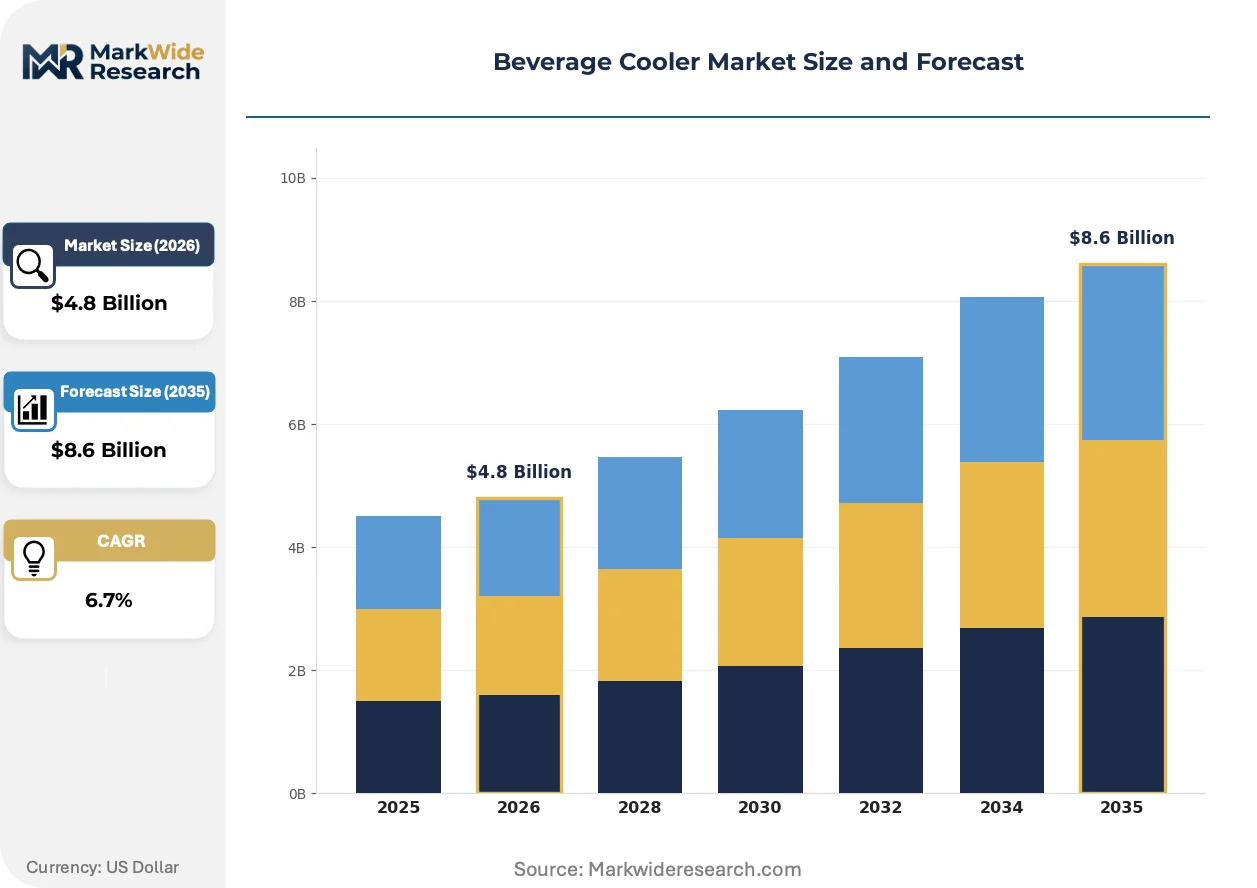
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Undercounter, Portable, Beverage Merchandiser, Free-Standing End User: Households, Restaurants, Bars, Retail Stores Cooling Technology: Thermoelectric, Compressor, Absorption, Hybrid Size: Compact, Medium, Large, Extra Large |
| Companies Covered | Electrolux AB, Haier Group Corporation, Danby Appliances Inc., LG Electronics Inc., Whirlpool Corporation, Perlick Corporation, Siemens AG, Viking Range Corporation, NewAir, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Cooler Market Strategic Shifts
Refrigeration architectures are fragmenting across three vectors: solid-state cooling advances, refrigerant chemistry transitions, and digital integration of fleet management systems.
Variable-speed compressor technology is displacing fixed-speed reciprocating units in mid-capacity commercial beverage coolers. Convenience store chains and cinema concessionaires adopt inverter-driven systems to reduce energy consumption during low-traffic periods. The shift compresses aftermarket parts demand while elevating electronic control module replacement rates.
EPA SNAP program approvals for hydrofluoroolefin blends and hydrocarbon alternatives reshape refrigerant selection protocols. Equipment manufacturers requalify compressor seals and pressure vessels for A2L mildly flammable chemistries. United States commercial specification channels lag European adoption curves due to divergent fire-safety code interpretations.
Buyers in United States foodservice increasingly specify fleet-wide remote monitoring capabilities. Cloud-connected temperature logging and door-open sensors displace clipboard-based HACCP documentation. Large casino and stadium operators deploy these systems first, with regional restaurant chains following as subscription pricing models mature.
Beverage Cooler Market Segmentation
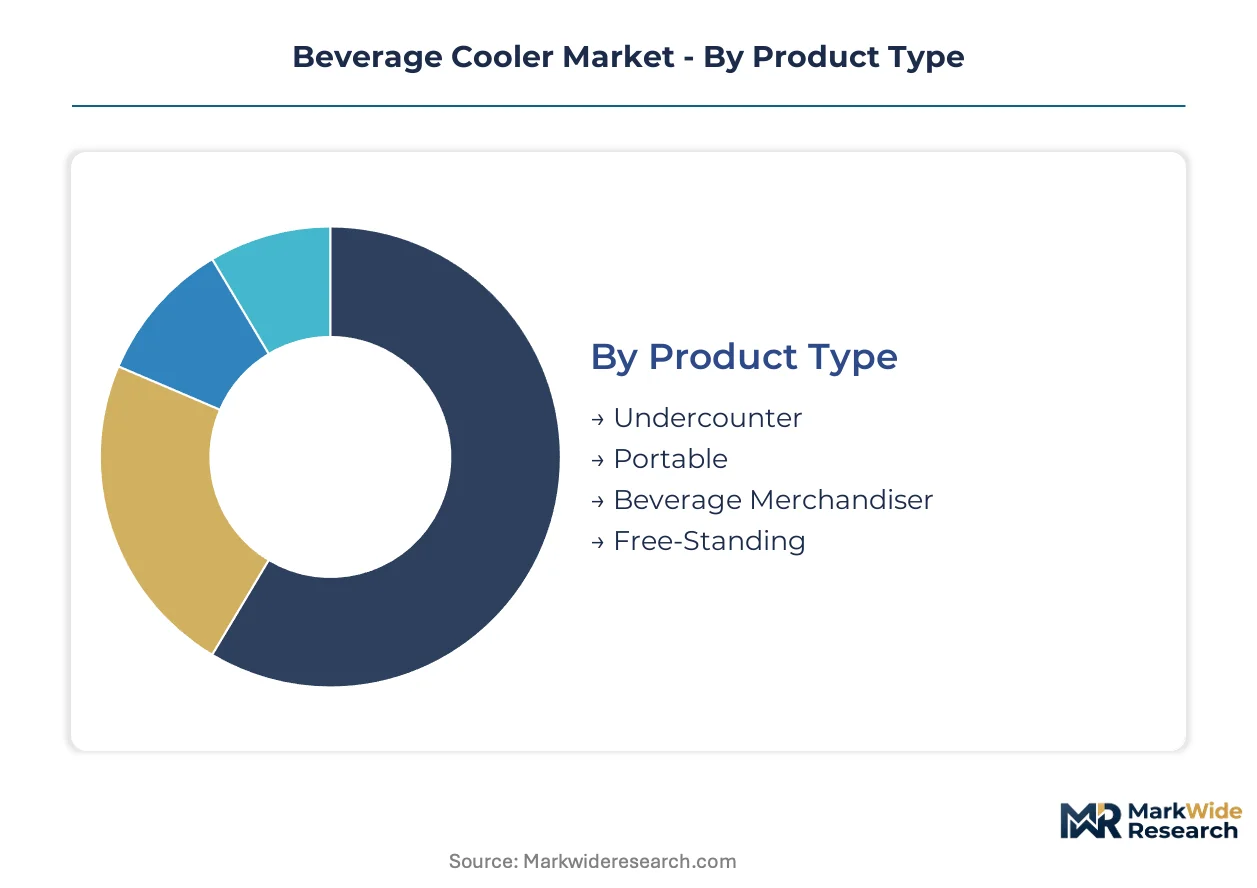
Beverage cooler segmentation reveals divergent margin structures across installation formats and cooling architectures. Specification requirements in commercial foodservice create premium pricing tiers absent in residential channels. Understanding segment boundaries clarifies where technology investments yield competitive differentiation versus commodity positioning.
Product Type:
Margin pools concentrate in undercounter formats where space constraints and aesthetic integration justify specification premiums. Free-standing units dominate volume shipments but compress margins through retail channel price competition.
- Undercounter:Built-in refrigeration systems designed for seamless integration beneath countertops in commercial bars and residential kitchens. Demand concentrates in United States restaurant renovation cycles where floor space optimization governs specification decisions. EPA energy-efficiency mandates accelerate replacement of legacy units with inverter-driven compressor models.
- Free-Standing:Self-supporting cabinets with finished exteriors requiring no built-in installation. Household buyers in suburban United States markets drive volume, though convenience store chains specify commercial-grade variants for cold-drink display. Price competition from mass-market retailers limits margin expansion.
- Portable:Battery-capable units employing thermoelectric or small compressor systems for mobile cooling. Camping and recreational vehicle end-uses in California and Florida generate seasonal demand spikes.
- Beverage Merchandiser:Glass-door display cabinets optimized for retail product visibility and impulse purchase conversion. Quick-service restaurant franchise buildouts in Texas and Florida specify these for front-of-house placement.
Undercounter holds installed capacity in commercial channels. Beverage Merchandiser is rotating up the share rankings as quick-service restaurant cold-drink display expansion accelerates.
End User:
Application context determines specification intensity and service contract attach rates. Foodservice operators demand predictive maintenance capabilities that household buyers disregard.
- Restaurants:Full-service and quick-service operators requiring HACCP-compliant temperature logging and rapid recovery after door openings. United States franchise networks specify fleet-standard units to simplify service relationships.
- Bars:High-turnover establishments prioritizing undercounter space efficiency and bottle orientation flexibility. Perlick Corporation anchors specification channels here through specialized dispensing integration.
- Retail Stores:Convenience stores and supermarkets deploying merchandiser formats for beverage category management. California and New York energy codes drive efficiency tier differentiation.
- Households:Residential buyers selecting free-standing units through big-box retail and e-commerce channels. Price sensitivity limits feature penetration beyond basic temperature control.
Restaurants command specification authority. Bars are rotating up the share rankings as craft cocktail venue expansion outpaces full-service restaurant growth.
Cooling Technology:
Cost tier stratification separates mature compressor architectures from emerging solid-state alternatives. Refrigerant chemistry transitions reshape total cost of ownership calculations.
- Compressor:Vapor-compression systems using reciprocating or rotary compressors with hydrofluorocarbon or hydrofluoroolefin refrigerants. High-ambient performance superiority maintains dominance in United States commercial installations despite refrigerant phase-down compliance costs.
- Thermoelectric:Solid-state Peltier modules eliminating moving parts for noise-sensitive applications. Portable segment demand in recreational boating and camping constrains capacity expansion due to coefficient of performance limitations.
- Absorption:Heat-driven cooling using ammonia-water or lithium bromide solutions for off-grid or waste-heat recovery scenarios. Remote commercial installations without reliable electrical infrastructure generate niche demand.
- Hybrid:Combined thermoelectric and compressor architectures optimizing efficiency across load conditions. Emerging configurations target premium residential wine storage applications.
Compressor holds installed capacity across commercial channels. Thermoelectric is rotating up the share rankings as solid-state reliability improvements expand portable application viability.
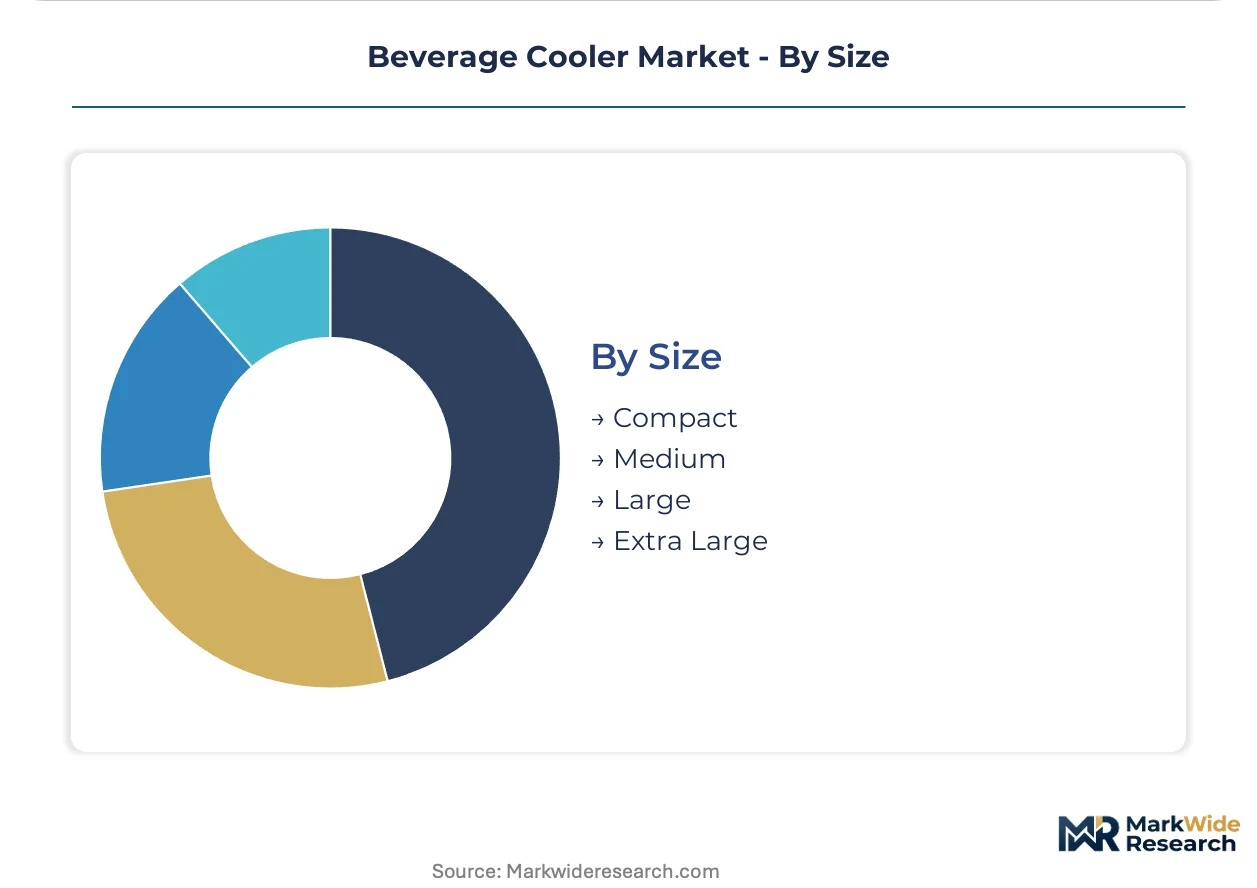
Size:
Customer type alignment separates compact personal units from extra-large commercial installations. Distribution channel configuration varies dramatically across size tiers.
- Large:200-400 liter capacity cabinets serving high-volume commercial and institutional settings. United States cinema concessionaires and stadium operators specify these for peak-event beverage throughput.
- Medium:100-200 liter formats balancing capacity with footprint constraints. Household kitchens and small restaurants represent the core demand concentration.
- Compact:Under-100 liter units for personal offices, dormitories, and recreational vehicles. Thermoelectric technology penetration is highest in this tier due to low capacity requirements.
- Extra Large:400+ liter walk-in and reach-in systems for beverage distribution centers and large-format retail backrooms. Custom engineering requirements limit manufacturer participation.
Medium holds installed capacity across residential and light commercial channels. Large is rotating up the share rankings as entertainment venue cold-drink display capacity expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers supply compressor systems and finished units to North American and European foodservice operators, establishing the dominant trade-flow corridor in commercial beverage cooling equipment.
United States
Convenience store chains and quick-service restaurant franchises drive replacement cycles for undercounter and merchandiser formats. EPA energy conservation standards and DOE test procedures mandate efficiency thresholds that accelerate obsolescence of pre-2020 installations. California's Title 24 building electrification codes and New York's emerging all-electric construction mandates reshape specification requirements in coastal metropolitan markets.
Germany
Commercial foodservice operators prioritize Ecodesign-compliant equipment with A+++ energy ratings for new construction and renovation projects. EU F-Gas Regulation mandates refrigerant phase-down schedules that constrain hydrofluorocarbon availability and elevate compliance costs. Industrial concentration in North Rhine-Westphalia and Bavaria supports domestic manufacturing of high-efficiency compressor systems for export throughout the European Union.
China
Domestic quick-service restaurant expansion and organized retail penetration generate volume demand for beverage merchandisers and free-standing units. GB standards for energy efficiency and refrigerant containment establish minimum performance thresholds for domestically sold equipment. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta supply compressor motors and finished cabinets to export markets across Southeast Asia and North America.
India
Organized foodservice penetration below 10 percent in tier-2 and tier-3 cities creates deployment whitespace for commercial-grade undercounter and merchandiser units. BIS certification requirements and FSSAI food safety protocols establish equipment standards for hospitality sector procurement. Industrial corridors in Maharashtra and Gujarat host assembly operations serving domestic demand and re-export to Middle Eastern markets.
Japan
Compact urban retail formats and high-turnover convenience store networks sustain demand for space-efficient undercounter systems. METI energy efficiency labeling programs and JIS standards govern minimum performance for commercial refrigeration equipment sold domestically. Manufacturing concentration in the Chubu region around Nagoya supplies precision compressor components to domestic OEMs and regional export markets.
Beverage Cooler Market Competitive Environment
Player mix skews toward diversified appliance conglomerates with captive compressor manufacturing, supplemented by specialized commercial foodservice fabricators. Market structure concentrates volume among three to four integrated manufacturers while fragmentation persists in premium undercounter segments. Strategic archetypes include scale-driven full-line suppliers, specification-focused commercial specialists, and regionally anchored premium brands. Competitive dynamics center on backward integration into compressor sourcing and geographic expansion through distribution partnerships.
Among diversified appliance conglomerates, Haier Group Corporation and Electrolux AB exemplify scale-driven archetypes with multi-platform cooling technology portfolios. Perlick Corporation occupies a position within the commercial specification specialist tier, anchoring undercounter system demand in bar and restaurant channels. LG Electronics Inc. and Whirlpool Corporation represent integrated manufacturers leveraging brand strength and distribution density across North American retail and foodservice segments.
| Leading Market Players |
|---|
| Electrolux AB |
| Haier Group Corporation |
| Danby Appliances Inc. |
| LG Electronics Inc. |
| Whirlpool Corporation |
| Perlick Corporation |
| Siemens AG |
| Viking Range Corporation |
| NewAir |
| Others |
Value Chain & Pricing Dynamics
EPA Section 608 certification requirements and EU F-Gas company certification simultaneously gate supplier qualification and create price differentiation between compliant and non-compliant equipment tiers. These regulatory barriers compress margin pools for manufacturers lacking certified service networks while rewarding incumbents with established technician training infrastructure.
Pricing Analysis
Next-generation inverter-driven compressor systems command 25-40% price premiums over fixed-speed reciprocating units, while prior-generation absorption cooling architectures retreat to niche off-grid applications. Three-tier pricing structure across premium, standard, and economy levels stratifies by energy efficiency certification grade and IoT connectivity bundling. Pricing pressure stems from refrigerant input cost volatility as hydrofluorocarbon phase-down schedules constrain supply availability. Household buyers through big-box retail channels exhibit highest price sensitivity, while United States quick-service restaurant franchise networks prioritize fleet standardization over unit cost minimization.
Supply Chain Analysis
Yangtze River Delta port congestion and Panama Canal transit limitations expose compressor motor procurement timelines to logistics disruption. Manufacturing concentration clusters in China, South Korea, and Japan for high-efficiency variable-speed compressors, while polyurethane foam insulation materials source from petrochemical complexes in the United States and Germany. Supply chain risk centers on single-source vulnerability for A2L refrigerant-compatible compressor seals. Distribution runs through foodservice equipment distributors in North America, captive retail networks in Europe, and e-commerce marketplaces for residential portable segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quick-service restaurant cold-drink display expansion in tier-2 and tier-3 Indian cities signals early-cycle penetration growth with decade-long runway potential.
For Market Incumbents: Fortify specification channel control through captive compressor manufacturing and EPA-certified service network density. Backward integration into refrigerant reclamation infrastructure defends margin position against input cost volatility. Invest in IoT-enabled predictive maintenance platforms to displace break-fix aftermarket competitors. For New Entrants and Emerging Players: Lead with thermoelectric portable applications where solid-state reliability improvements expand addressable market beyond traditional camping segments. Target India's underpenetrated foodservice corridors through distributor partnerships with organized retail chains. Emphasize battery-operation compatibility for recreational vehicle and marine applications. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed commercial foodservice fabricators lacking variable-speed compressor technology portfolios. Five-to-ten year viability favors manufacturers with in-house refrigerant handling certification and grid-responsive system architectures. Monitor California Title 24 electrification code adoption velocity as inflection indicator for all-electric refrigeration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Compressor Platform Migration | Variable-speed technology captures EPA energy conservation compliance premiums in United States convenience store retrofit cycles. |
| A2L Refrigerant System Requalification | Hydrofluoroolefin seal compatibility opens specification channels in EU member states with accelerated F-Gas phase-down timelines. |
| IoT Fleet Management Integration | Cloud-connected temperature logging displaces clipboard-based HACCP documentation in large casino and stadium operator accounts. |
| India Distribution Partnership Expansion | Organized retail penetration in tier-2 cities creates whitespace for commercial-grade undercounter deployment. |
| Technician Certification Program Buildout | EPA Section 608 training infrastructure locks in aftermarket service revenue and specification channel access. |
Study Parameters
A spread of perspectives from foodservice equipment procurement managers, convenience store chain facility directors, compressor manufacturing engineers, and refrigeration service contractors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EPA regulatory filings, DOE test procedure documentation, EU Ecodesign energy labeling databases, and customs trade data for compressor motor imports. Bottom-up unit shipment estimates triangulated against top-down foodservice construction spending and retail cold-drink display capacity expansion metrics.
Segmentation dimensions modeled span installation format, cooling technology architecture, end-user application context, and capacity tier across the projection horizon. CAGRs were derived from replacement cycle analysis, new construction penetration assumptions, and technology substitution elasticity parameters. Refrigerant phase-down schedule compliance costs and state-level building electrification code adoption curves informed scenario-weighted outcomes.
Forecasts assume regulatory continuity in EPA energy conservation standards and EU F-Gas Regulation enforcement; material policy shifts would require re-modeling compressor sourcing and insulation specifications. Practitioners should keep alternative scenarios live as California, New York, and Washington all-electric construction mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Oat Based Beverages Market
Beverages
Caffeinated Beverage Market
Beverages
Juice Concentrates Market
Beverages
GCC Fruit Juice Market
Beverages
Aloe Vera-Based Drink Market
Beverages
Bubble Food and Beverages Market
Beverages
Semillon Market
Beverages
Global Fruit Juice Concentrate Market
Beverages
Enzyme-Enabled Cold-Brew Concentrates Market
Beverages
Fruit Beverages Market
Beverages
India Soy Beverages Market
Beverages
Fruit Juice Market
Beverages
Vegetable Juice Market
Beverages
Middle East and Africa Fruits and Vegetable Juice Market
Beverages
Morocco Bottled Water Market
Beverages
US Bubble Tea Market