
 US Wine Cooler Market | 2026-2036
US Wine Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
US Wine Cooler Market Intelligence
The UL certification requirement for electrical safety is unwinding the historical separation between high-end custom and mass-market appliance segments. Specialist brands like Wine Guardian sustain their position through advanced climate control technologies for serious collectors. Allavino competes on design flexibility and broad distribution through online retail channels. KingsBottle differentiates with a focus on commercial-grade units tailored for the restaurant and hospitality industries.
A US wine cooler is a specialized refrigeration appliance designed to store wine at optimal, consistent temperatures, typically between 45°F and 65°F. Unlike standard refrigerators, these units control humidity and minimize vibration to preserve wine quality. Compressor-based systems dominate the market for their cooling power and capacity, while thermoelectric models find a niche in smaller, quieter applications. The residential end-user segment represents the largest volume, though the commercial hospitality space offers higher margin potential.
The EPA's Energy Star program sets efficiency benchmarks that manufacturers must meet to gain an advantage with environmentally conscious consumers. Concurrently, the FTC enforces truth-in-advertising and labeling rules, ensuring claims about bottle capacity and energy use are accurate. Stakeholders must therefore balance investments in energy-efficient compressor technology against evolving consumer preferences for smart features and aesthetic design integration.
Market Dynamics
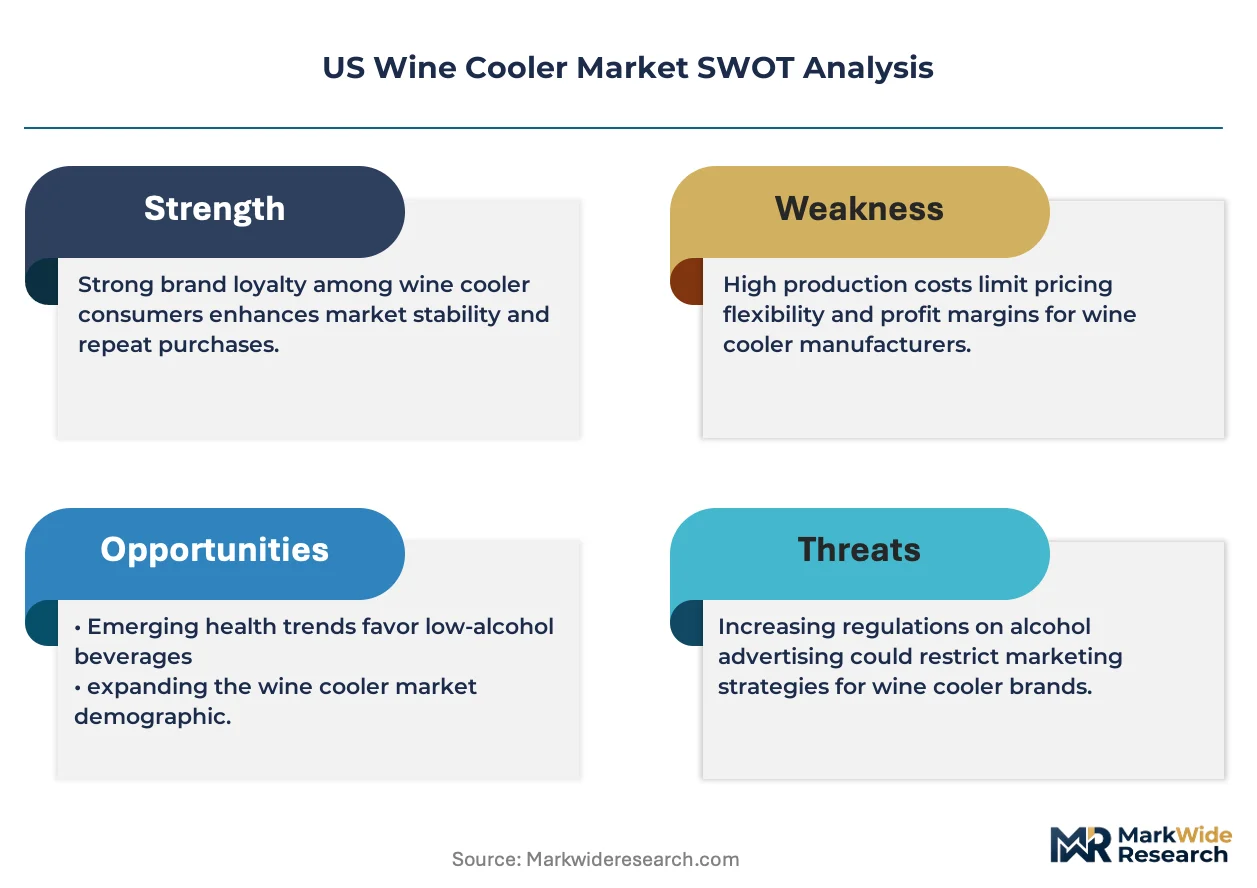
The central force shaping the US wine cooler market is the convergence of regulatory mandates and consumer expectations. Stricter EPA energy standards and non-negotiable UL safety certifications are forcing a design synthesis between commercial-grade performance and residential aesthetic appeal.
Growth Catalysts
- Smart Home Integration:Demand from the residential sector for IoT-enabled appliances that integrate into connected home ecosystems allows for remote temperature monitoring and control, creating a new value proposition beyond basic storage.
- Luxury Residential Construction:A concentration of high-end home building and renovation projects in states with prominent wine cultures, particularly California, drives installations of premium, built-in wine cooler units as a standard feature.
- Commercial Sector Efficiency:The hospitality industry's focus on reducing operational costs creates sustained demand for commercial-grade units that meet EPA Energy Star criteria, providing a clear return on investment through lower energy bills.
Market Restraints
- Component Cost Pressure:The use of high-efficiency, variable-speed compressors and advanced insulation materials required to meet energy standards significantly increases bill-of-materials costs, which translates to higher retail prices for consumers.
- Threat of Substitution:The growing availability of multi-zone beverage centers and high-end refrigerators with dedicated, temperature-controlled wine drawers presents a viable substitute, potentially cannibalizing sales from dedicated wine cooler units.
- Compressor System Noise:Despite technological advancements, the inherent noise and vibration from compressor-based systems remain a significant deterrent for some residential customers, especially for units intended for quiet living spaces or bedrooms.
Strategic Opportunities
- Emerging US Wine Regions:Targeting markets in developing wine culture zones like Oregon, Washington, and Texas provides an opportunity to build brand loyalty in areas with lower market penetration compared to established regions like California.
- Wellness and Preservation Technology:Integrating adjacent technologies such as UV-C light for sterilization or advanced charcoal filtration systems for odor control can create a new tier of products focused on active preservation and air quality.
- Customization via D2C Channels:A direct-to-consumer sales model allows for greater customization of finishes, door styles, and shelving configurations, catering to the specific design demands of architects and interior designers for bespoke projects.
Industry Challenges
- Evolving Energy Standards:The continuous updates to the EPA's Energy Star program requirements necessitate ongoing research and development investment to ensure compliance, effectively shortening the viable lifecycle of existing product designs.
- Component Supply Chain Vulnerability:Reliance on a globalized supply chain for critical components like electronic control boards and specialized compressors exposes manufacturers to significant risks from geopolitical instability and shipping disruptions.
- Certification Lead Times:The lengthy and costly process of obtaining UL certification for new electrical designs can create significant delays in bringing innovative products to market, acting as a drag on rapid development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Wine Cooler Market |
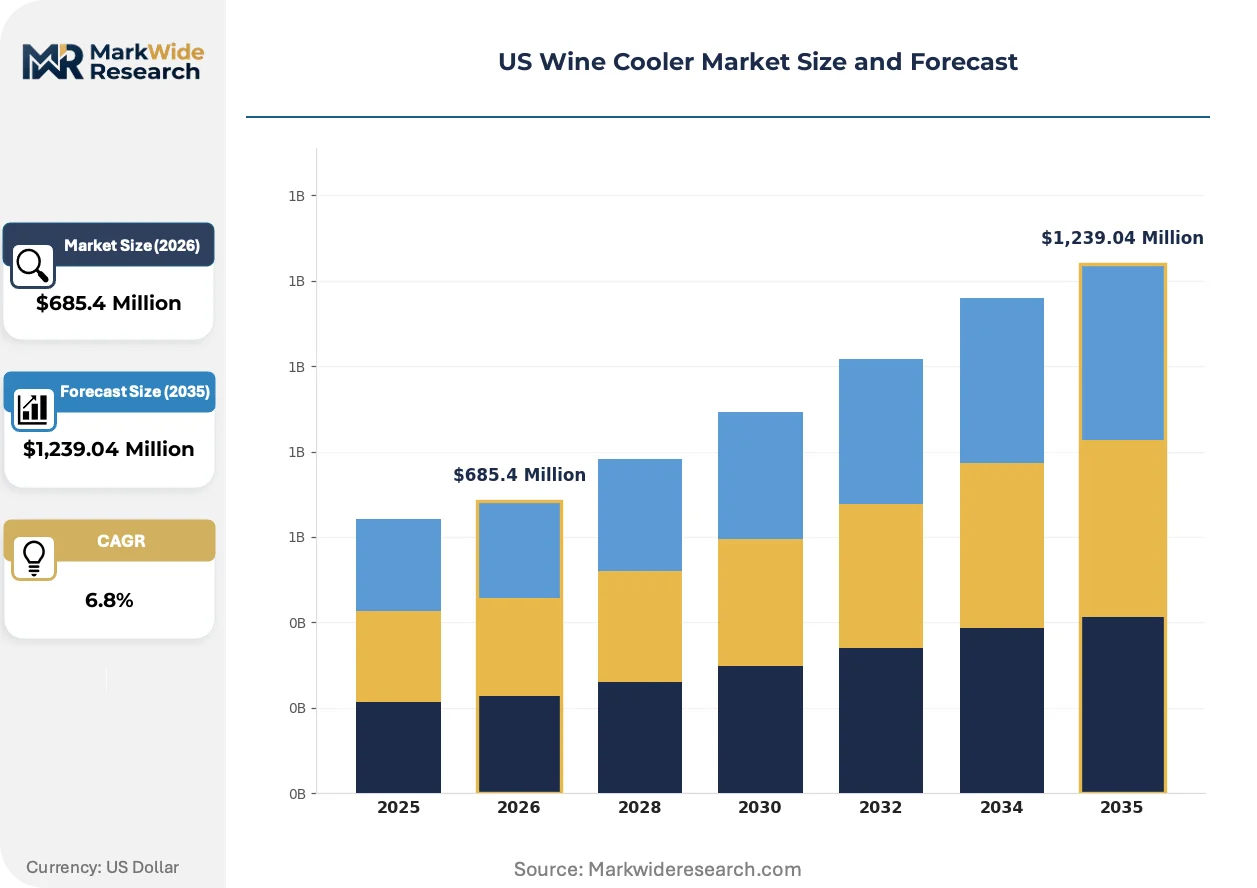
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoelectric, Compressor-Based, Dual Zone, Single Zone Size: Small Capacity, Medium Capacity, Large Capacity, Mini Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Wholesalers End User: Residential, Commercial, Hospitality, Restaurants |
| Companies Covered | CellarPro, KingsBottle, Wine Guardian, Le Cache, Transtherm, WhisperKOOL, Allavino, KoolR, Breezaire, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Wine Cooler Market Strategic Shifts & Innovations
Aesthetic integration and smart functionality are defining the next generation of wine coolers. Manufacturers are competing less on pure cooling power and more on how seamlessly a unit blends into a high-design kitchen while offering connected, user-friendly features.
Variable-speed inverter compressors provide precise temperature management by modulating cooling power based on real-time needs. This technology is seeing rapid adoption in both the premium residential and light commercial segments. Ultimately, the superior energy efficiency and quieter operation of these systems means this technology is supplanting legacy single-speed compressors that operate on a simple on-off cycle.
The FTC’s strict enforcement of truth-in-advertising rules governs claims about bottle capacity and energy usage. This regulatory oversight compels manufacturers to provide accurate, verifiable data, preventing misleading marketing and fostering greater consumer trust. The mass-market segment, where bottle count is a primary competitive metric, is most affected, as brands must now ensure their advertised capacities reflect realistic, mixed-bottle-shape storage.
Consumer preference is shifting decisively toward panel-ready and integrated wine coolers that disappear into custom cabinetry. This demand for seamless integration is disrupting the market for traditional freestanding stainless steel models, especially within new construction and kitchen renovations. The trend is most pronounced in high-density urban markets where architects and interior designers specify appliances for luxury residential projects.
US Wine Cooler Market Segmentation
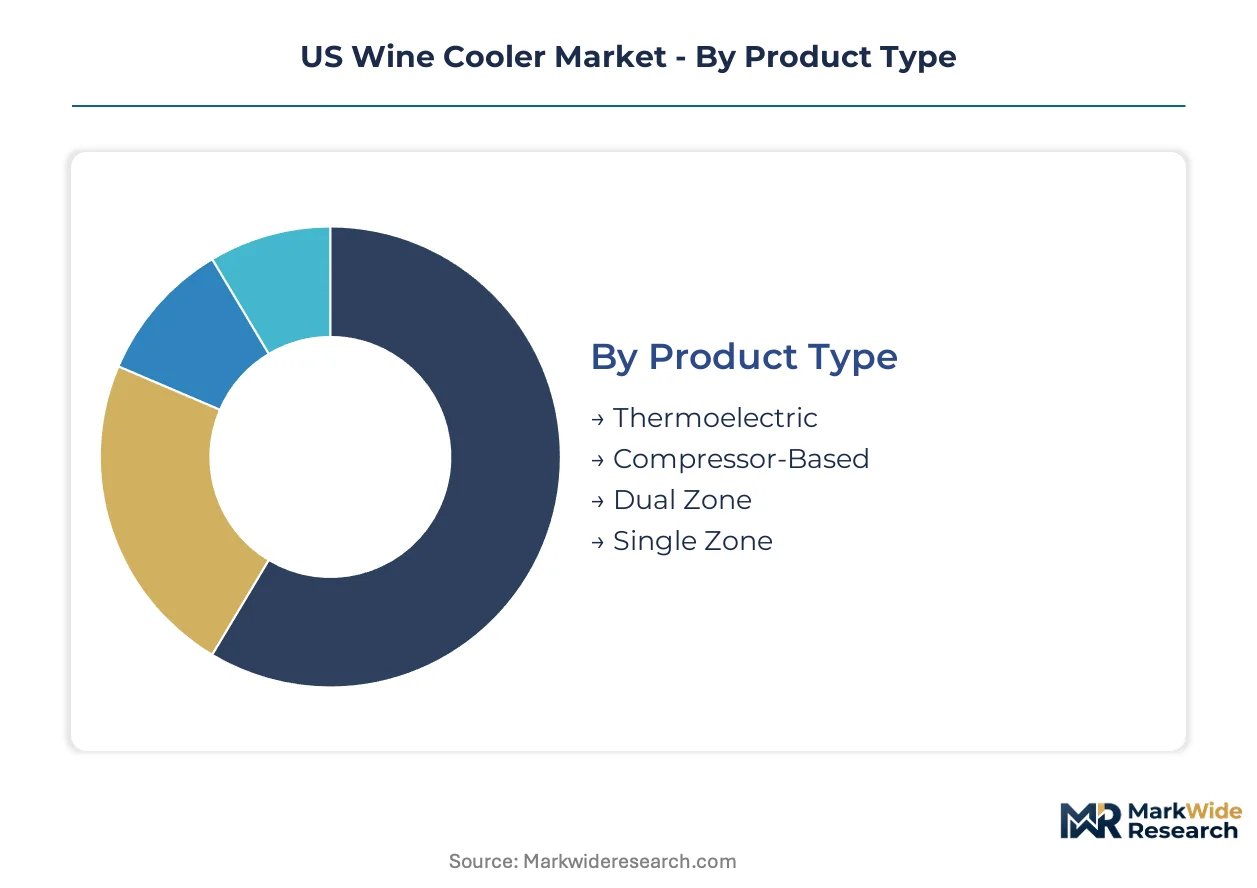
Understanding the segmentation of the US wine cooler market reveals how different product attributes and sales channels cater to specific consumer needs. This detailed breakdown highlights the varying demands across residential and commercial applications, influencing product design and distribution strategies within the United States.
Distribution Channel:
The distribution landscape for US wine coolers reflects varied consumer purchasing habits, with different channels catering to distinct customer segments seeking convenience or specialized service.
- Online Retail:This channel encompasses direct-to-consumer sales via brand websites and third-party e-commerce platforms, offering broad product selections and competitive pricing. Demand concentrates heavily in urban and suburban areas where consumers prioritize convenience and product comparison for residential installations.
- Specialty Stores:Dedicated appliance retailers and wine accessory shops provide expert advice, installation services, and a curated selection of premium and niche wine cooler brands. High-end residential construction projects in states like California frequently source units through these specialized outlets, valuing personalized service.
- Hypermarkets:Large retail chains offer a limited selection of mass-market wine coolers, typically focusing on entry-level or mid-range freestanding models. These outlets serve a broad consumer base seeking accessible and readily available units.
- Wholesalers:These distributors supply wine coolers in bulk to commercial clients, including hospitality groups and large-scale residential developers. Wholesalers facilitate large-volume procurement for new hotels or multi-unit housing projects.
By volume, Online Retail leads. By growth pace, Specialty Stores is ahead.
Product Type:
Product type segmentation highlights the technical solutions addressing diverse preservation needs and installation environments, balancing cooling efficiency with operational characteristics.
- Compressor-Based:These systems utilize a vapor compression cycle with a refrigerant, providing powerful and consistent cooling suitable for larger capacities and fluctuating ambient temperatures. This technology dominates the market due to its efficiency and ability to maintain precise temperatures in residential and commercial settings.
- Dual Zone:Units featuring two independently controlled temperature compartments allow for simultaneous storage of different wine types, such as reds and whites, at their optimal serving or aging temperatures. Demand for dual-zone functionality is particularly strong in the high-end residential segment, where wine collectors seek versatile storage solutions.
- Thermoelectric:Utilizing the Peltier effect, these models offer quieter operation and are generally smaller in capacity, making them suitable for compact spaces. Thermoelectric units often appeal to residential customers prioritizing minimal noise.
- Single Zone:These wine coolers maintain a uniform temperature throughout the entire storage compartment, ideal for either short-term serving or long-term aging of a single wine type. Single-zone models represent a cost-effective solution for many residential users.
Performance differences define this category's competitive landscape.
End User:
End-user categories delineate distinct application environments, each with specific requirements for capacity, aesthetics, and operational durability.
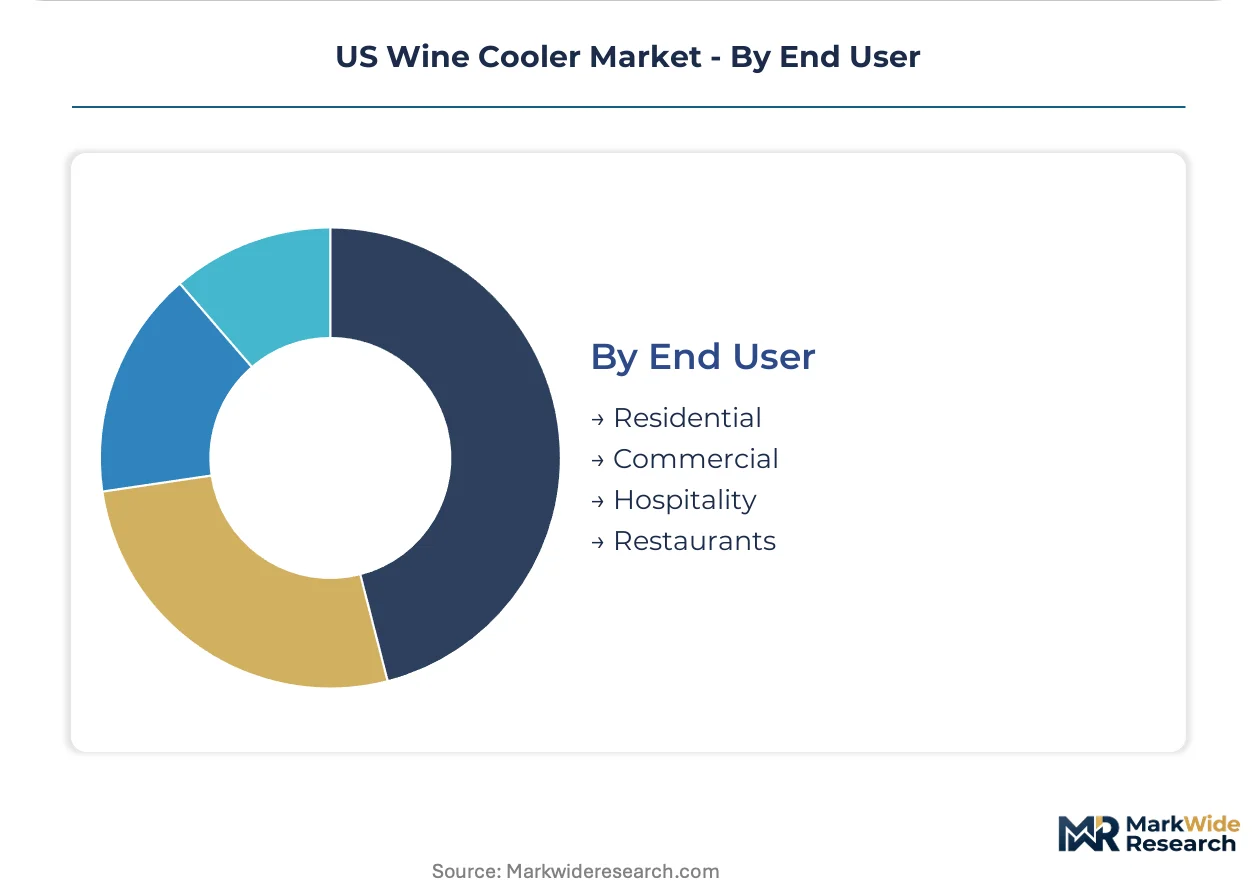
- Residential:Individual homeowners purchase wine coolers for personal use, ranging from small countertop units to integrated, multi-zone appliances within custom kitchens. This segment represents the largest volume of wine cooler sales in the US market.
- Hospitality:Hotels, resorts, and cruise lines integrate wine coolers into guest rooms, bars, and restaurants to enhance guest experience and manage beverage inventory. The hospitality sector prioritizes commercial-grade durability and energy efficiency, often driven by EPA Energy Star compliance.
- Commercial:Businesses such as wine shops, tasting rooms, and corporate offices utilize wine coolers for display, storage, and client entertainment purposes. Commercial end-users require robust units capable of continuous operation and often seek specific aesthetic integration for retail environments.
- Restaurants:Eateries and fine dining establishments employ wine coolers to store and display their wine lists at optimal serving temperatures. Restaurants often demand units with specific bottle capacities and aesthetic appeal to complement their dining ambiance.
This end-user segmentation demonstrates diverse functional priorities.
Size:
The size classification addresses the physical footprint and bottle capacity requirements, from compact personal units to extensive storage solutions.
- Medium Capacity:These units typically hold between 30 and 80 standard wine bottles, balancing storage volume with a manageable footprint for many residential kitchens or small commercial spaces. Demand for medium-capacity units is robust across a wide range of US residential consumers.
- Large Capacity:Designed for serious collectors or commercial establishments, large capacity wine coolers store 80 or more bottles, often featuring multiple zones and advanced climate control. High-end residential construction in states like California frequently incorporates these larger, built-in models.
- Small Capacity:These compact wine coolers typically accommodate fewer than 30 bottles, suitable for countertop placement or limited spaces in residential settings. Small capacity units appeal to casual wine drinkers or those with restricted kitchen space.
- Mini:Extremely compact units designed for a few bottles, often used for immediate serving or in personal offices. Mini wine coolers offer maximum portability and minimal space requirements.
The market exhibits a clear preference for mid-range and larger capacities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US wine cooler market exhibits strong buyer-archetype concentration in affluent residential areas and growing commercial hospitality zones. Demand for premium units correlates directly with high-end home construction and renovation activity. Regulatory frameworks from the EPA and FTC shape product development and consumer choice across these regions.
California
High-end residential construction and a robust wine culture drive significant demand for large-capacity, integrated wine coolers. EPA Energy Star standards influence purchasing decisions for energy-efficient models in this environmentally conscious state. The Napa Valley and Sonoma regions, with their numerous wineries and luxury estates, represent a core market for specialized wine preservation units.
New York Metro
Luxury apartment developments and upscale restaurant expansions in the New York metropolitan area fuel demand for compact, design-integrated, and commercial-grade wine coolers. The FTC's truth-in-advertising rules ensure accurate bottle capacity claims, critical for space-constrained urban installations. Manhattan's fine dining scene and high-net-worth residential projects create a concentrated hub for premium appliance sales.
Texas
Rapid population growth and an expanding luxury housing market in Texas generate substantial demand for both residential and commercial wine cooler installations. State-level energy efficiency incentives complement federal EPA guidelines, encouraging adoption of advanced cooling technologies. Major metropolitan areas like Dallas and Houston are experiencing a boom in high-end residential and hospitality developments, driving cooler sales.
Pacific Northwest
Emerging wine regions in Oregon and Washington, coupled with a focus on sustainable living, create demand for energy-efficient and specialized wine storage. UL certification for electrical safety remains a critical benchmark for all appliances sold in this region, ensuring product reliability. Seattle and Portland's vibrant culinary scenes and growing wine appreciation contribute to a steady market for both single and dual-zone units.
US Wine Cooler Market Key Industry Players
Player mix skews toward specialized manufacturers offering distinct value propositions in the US wine cooler market. The market structure exhibits a tiered consolidation, with some brands focusing on premium, custom solutions and others competing on broad distribution and design flexibility. Strategic archetypes include high-end preservation specialists, design-centric mass-market providers, and commercial-grade unit fabricators serving diverse end-user needs. Portfolio diversification into adjacent appliance categories and strategic partnerships with kitchen designers represent dominant competitive moves.
Specialists like Wine Guardian exemplify the high-end preservation archetype, providing advanced climate control systems crucial for serious wine collectors and long-term aging. KingsBottle anchors the commercial-grade segment, offering robust units specifically tailored for the demanding environments of the restaurant and hospitality industries, prioritizing durability and continuous operation. Allavino represents a design-flexible provider, emphasizing broad distribution through online retail channels and aesthetic appeal for modern residential users seeking integrated solutions that blend seamlessly into custom cabinetry.
| Leading Market Players |
|---|
| CellarPro |
| KingsBottle |
| Wine Guardian |
| Le Cache |
| Transtherm |
| WhisperKOOL |
| Allavino |
| KoolR |
| Breezaire |
| Others |
Cost & Logistics Intelligence
Scale economies in compressor manufacturing and insulation material procurement drive cost efficiencies, which in turn influence the competitive pricing floor for mass-market wine cooler units. This scale also encourages consolidation among component suppliers.
Pricing Analysis
Cost-plus contract patterns, often indexed to raw material prices like copper and steel, determine pricing for specialized wine cooler components. Price differentiation stems from UL certification levels, ensuring electrical safety, and the degree of aesthetic customization for integrated models. Pricing softness in the mass-market segment arises from intense online retail competition for entry-level units. Commercial hospitality clients, prioritizing durability and energy efficiency, exhibit the least price sensitivity.
Supply Chain Analysis
Geopolitical instability in key manufacturing hubs, particularly in Southeast Asia for electronic control boards, creates a logistics chokepoint for US wine cooler production. The market draws from specialized compressor manufacturers in China and Europe, alongside advanced insulation material suppliers globally. Single-source vulnerability for high-efficiency variable-speed compressors poses a structural risk. Distribution runs through a hybrid model, combining direct-to-consumer online channels with wholesale networks for commercial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US wine cooler market presents a fragmentation opportunity, driven by the demand-side shift towards highly integrated, bespoke appliance solutions in luxury residential construction. This shift creates distinct niches for specialized providers.
For Market Incumbents: Shield core market share by deepening vertical integration into advanced climate control technology R&D, specifically for quieter, more energy-efficient compressor systems. This defends against the threat of substitution from multi-zone beverage centers. Invest in a robust D2C channel to offer customization options, securing brand loyalty with high-end residential customers.
For New Entrants and Emerging Players: Lead with innovative preservation technology, such as integrated UV-C light sterilization or advanced charcoal filtration systems, targeting wellness-conscious consumers. The most penetrable segment lies within emerging US wine regions like Texas, where brand loyalty is still forming. A direct-to-consumer go-to-market angle allows for rapid iteration and tailored product offerings.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialist brands providing long-term service contracts or subscription-based maintenance for advanced climate control units. The acquisition target archetype comprises mid-cap manufacturers with strong intellectual property in energy-efficient compressor technology or established D2C customization platforms. A key signal to watch is the sustained increase in luxury residential building permits in non-traditional wine states.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Compressor R&D | Developing quieter, more efficient variable-speed compressors enhances product differentiation and meets EPA standards. |
| D2C Customization Platform | Enabling direct-to-consumer design flexibility caters to architects and interior designers for bespoke projects. |
| Wellness Tech Integration | Adding UV-C sterilization or air filtration creates a premium product tier focused on active wine preservation. |
| Supply Chain Diversification | Reducing reliance on single-source component suppliers mitigates geopolitical and logistics risks for manufacturers. |
| Regional Market Penetration | Targeting developing US wine regions like Texas builds early brand loyalty in underserved, growing markets. |
Research Approach
A spread of perspectives from appliance manufacturers, hospitality procurement managers, luxury home builders, and online retail executives converged on the working assumptions for this US wine cooler market analysis. Primary interviews were triangulated with secondary validation from EPA Energy Star databases, FTC consumer protection reports, and luxury residential construction permits data. This dual approach ensured both bottom-up and top-down insights informed the market sizing.
The segmentation dimensions modeled include distribution channel, product type, end user, size, and regional outlook across the projection horizon. This analytical framework integrates historical sales data with forward-looking indicators to derive compound annual growth rates. Key industry-specific forecast inputs include luxury residential construction starts and hospitality sector capital expenditure.
Forecasts assume regulatory continuity in US federal and state energy efficiency regimes; material policy shifts would require re-modeling. The analysis reflects current market dynamics, but global component supply chain volatility and rapid shifts in consumer aesthetic preferences represent specific risk factors. Practitioners should keep alternative scenarios live as economic conditions and technological advancements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
Distilled Spirits Market
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
Alcohol Gummies Market
Alcoholic Beverages
US Frozen Cocktail Popsicles Market
Alcoholic Beverages
South Korea Tequila Market
Alcoholic Beverages
Spirit-Based RTD Mixes Market
Alcoholic Beverages
Beer Brewing Machine Market
Alcoholic Beverages
Global Premium Alcoholic Beverage Market
Alcoholic Beverages
Flavored Whiskey Market
Alcoholic Beverages
South America Alcoholic Beverages Market
Alcoholic Beverages
Cigar Market
Alcoholic Beverages
Specialty Beer Market
Alcoholic Beverages
Japan Alcohol E-Commerce Market
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
Beer Adjuncts Market