
 Japan Ready-To-Drink (RTD) Coffee Market | 2026-2036
Japan Ready-To-Drink (RTD) Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Ready-To-Drink (RTD) Coffee Market Foresight
JIS S 2060 certification for beverage container integrity and label accuracy is redrawing competitive boundaries for shelf-stable coffee entrants. Asahi Group Holdings leverages its vertically integrated canning network to sustain cost advantages across Honshu distribution corridors. Suntory Holdings dominates the premium bottled segment through refrigerated supply chain control in Kanto and Kansai. UCC Ueshima Coffee anchors market presence with deep convenience store partnerships and heritage brand equity in regional Japan.
Japan Ready-To-Drink Coffee comprises commercially prepared, thermally processed or cold-brewed coffee formulations packaged in shelf-stable or refrigerated containers, typically formulated to deliver standardized caffeine content between 60-200mg per serving for immediate consumption without brewing equipment. The product serves Japan's dense commuter economy, where consumption occasions cluster around transit, workplace entry, and afternoon refreshment cycles. Canned formats occupy the mature volume core, while bottled variants capture expanding margin pools through premium positioning and refrigeration-dependent freshness claims. High Protein and Low Sugar ingredient segments attract health-oriented urban consumers, though Original flavor profiles still command the largest absolute volume through vending machine channels.
Japan's Food Labeling Standards Act, enforced by the Consumer Affairs Agency, mandates precise caffeine and allergen disclosure that elevates formulation compliance costs for new entrants. METI's Sustainable Food Systems Strategy and container recycling ordinances under the Containers and Packaging Recycling Law pressure producers toward lighter-weight aluminum and PET innovations. Stakeholders must monitor evolving F-Gas regulations affecting cold-chain refrigeration assets, as carbon footprint disclosure requirements tighten across retail procurement standards.
Market Dynamics
METI's container recycling mandates and tightening F-Gas standards for cold-chain equipment are forcing producers to reconfigure aluminum sourcing and refrigeration asset portfolios, compressing margin structures while elevating compliance as a competitive differentiator.
Growth Catalysts
- Convenience store expansion:Chains like Lawson and 7-Eleven Japan are extending grab-and-go coffee sections in Greater Tokyo and Osaka-Kobe corridors, capturing commuter foot traffic through high-vending-density placement.
- Containers and Packaging Recycling Law:METI's mandates for lighter-weight aluminum and PET innovations push producers toward circular material flows that reduce per-unit input costs over compliance cycles.
- Cold-brew processing:Ambient-stable extraction methods lower energy intensity versus thermal processing, enabling shelf-stable premium positioning without refrigerated distribution infrastructure.
Market Restraints
- Aluminum price volatility:Global smelter capacity constraints and energy cost spikes transmit directly to canning cost structures, squeezing margin on volume-core canned formats.
- Refrigerated supply chain concentration:Premium bottled segments depend on cold-chain density that clusters in Kanto and Kansai, locking out cost-effective national distribution for regional entrants.
- Caffeine disclosure rigidity:Consumer Affairs Agency enforcement of Food Labeling Standards Act precision requirements elevates formulation compliance costs and slows new product cycles.
Strategic Opportunities
- Hokkaido and Tohoku underpenetration:Lower vending machine density and aging demographics in northern prefectures create whitespace for functional coffee positioning around protein and low-sugar variants.
- Workplace direct delivery:Corporate pantry services and subscription models bypass convenience store intermediaries, capturing afternoon refreshment occasions in dense office districts.
- F-Gas transition incentives:METI's phasedown schedules for hydrofluorocarbon refrigeration reward early adopters of natural refrigerant systems with carbon footprint certification advantages.
Industry Challenges
- JIS S 2060 certification timelines:Beverage container integrity testing and label accuracy verification create 6-12 month product launch delays that disadvantage smaller entrants against established canning networks.
- Cold-chain technician scarcity:Specialized refrigeration maintenance skills for natural refrigerant systems concentrate with legacy equipment vendors, limiting in-house fleet management capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Ready-To-Drink (RTD) Coffee Market |
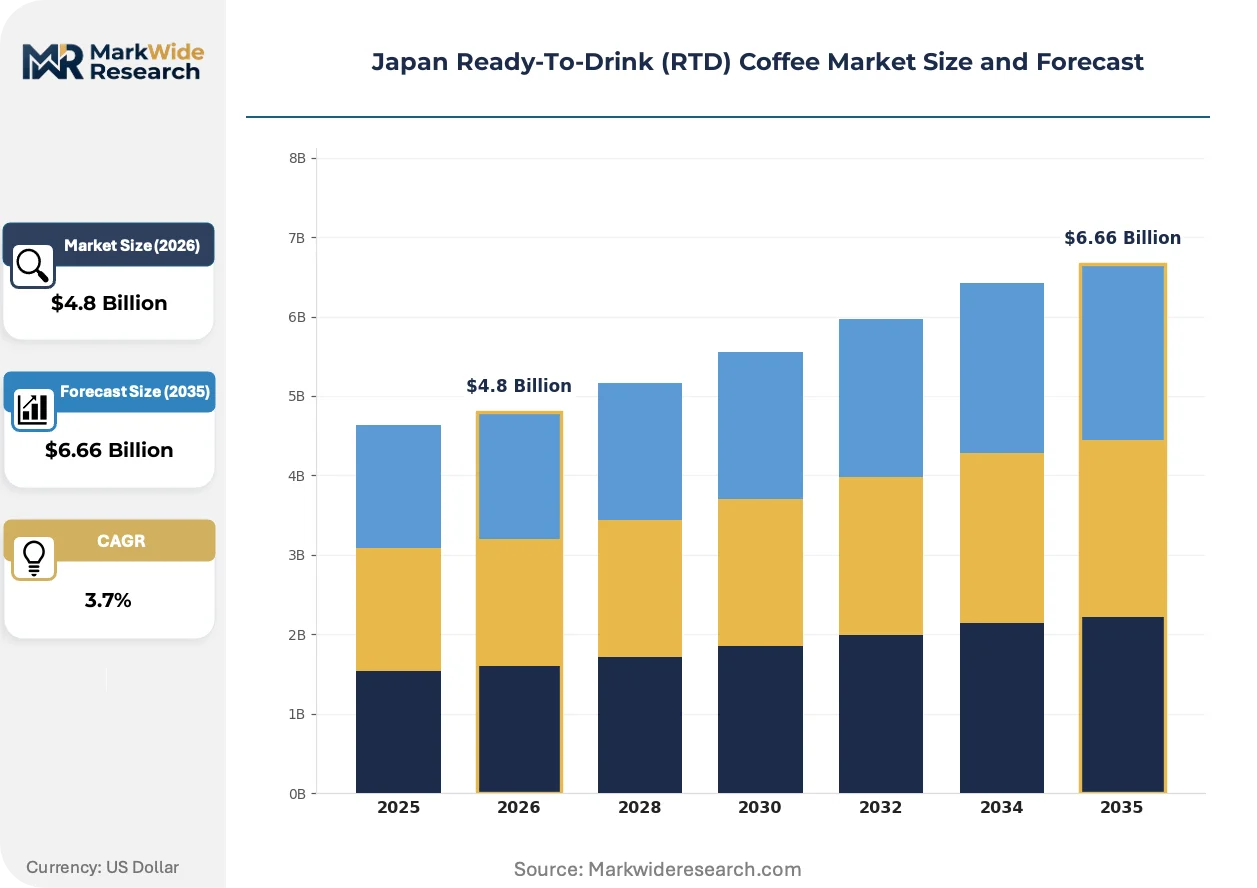
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned, Bottled, Pouch, Tetra Pak Flavor Profile: Original, Mocha, Vanilla, Caramel Ingredient Type: Organic, Non-Dairy, Low Sugar, High Protein Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Cafés |
| Companies Covered | Asahi Group Holdings, The Coca-Cola Company, Suntory Holdings, UCC Ueshima Coffee, Nestlé, Kirin Holdings, Coca-Cola Bottlers Japan, Starbucks Coffee Company, PepsiCo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Ready-To-Drink (RTD) Coffee Market Shifts & Advancements
Processing technology and packaging material science are diverging toward dual-track futures, while regulatory pressure on carbon disclosure and container circularity accelerates capital redeployment across the value chain.
Retort pouch formats for ambient-stable coffee is bifurcating the shelf-stable segment from aluminum-can dominance. Convenience store chains in commuter corridors are trialing flexible packaging for seasonal limited editions, enabling faster flavor rotation without canning line changeover costs. This format shift compresses minimum viable production runs while opening margin pools previously captured by bottled refrigerated variants.
METI's evolving F-Gas standards under the Act on Rational Use and Proper Management of Fluorocarbons are forcing cold-chain equipment replacement cycles. Producers with captive refrigerated distribution in Kanto and Kansai face accelerated depreciation schedules, while those dependent on third-party logistics confront procurement renegotiation. Premium bottled segments bear disproportionate impact as refrigeration-dependent freshness claims become costlier to sustain.
Health-oriented urban consumers are rotating toward functional ingredient claims that displace original-flavor vending machine defaults. High-protein and low-sugar variants capture afternoon refreshment occasions previously served by standard black coffee, particularly among white-collar commuters in Greater Tokyo. This behavioral pivot pressures heritage brands to reformulate without alienating core vending channel volume.
Japan Ready-To-Drink (RTD) Coffee Market Segmentation
Channel dynamics in Japan's RTD coffee market diverge sharply between ambient-stable formats suited to vending infrastructure and refrigerated variants demanding cold-chain density. Understanding how each segment maps to distribution corridors reveals where margin pools concentrate versus where volume scales.
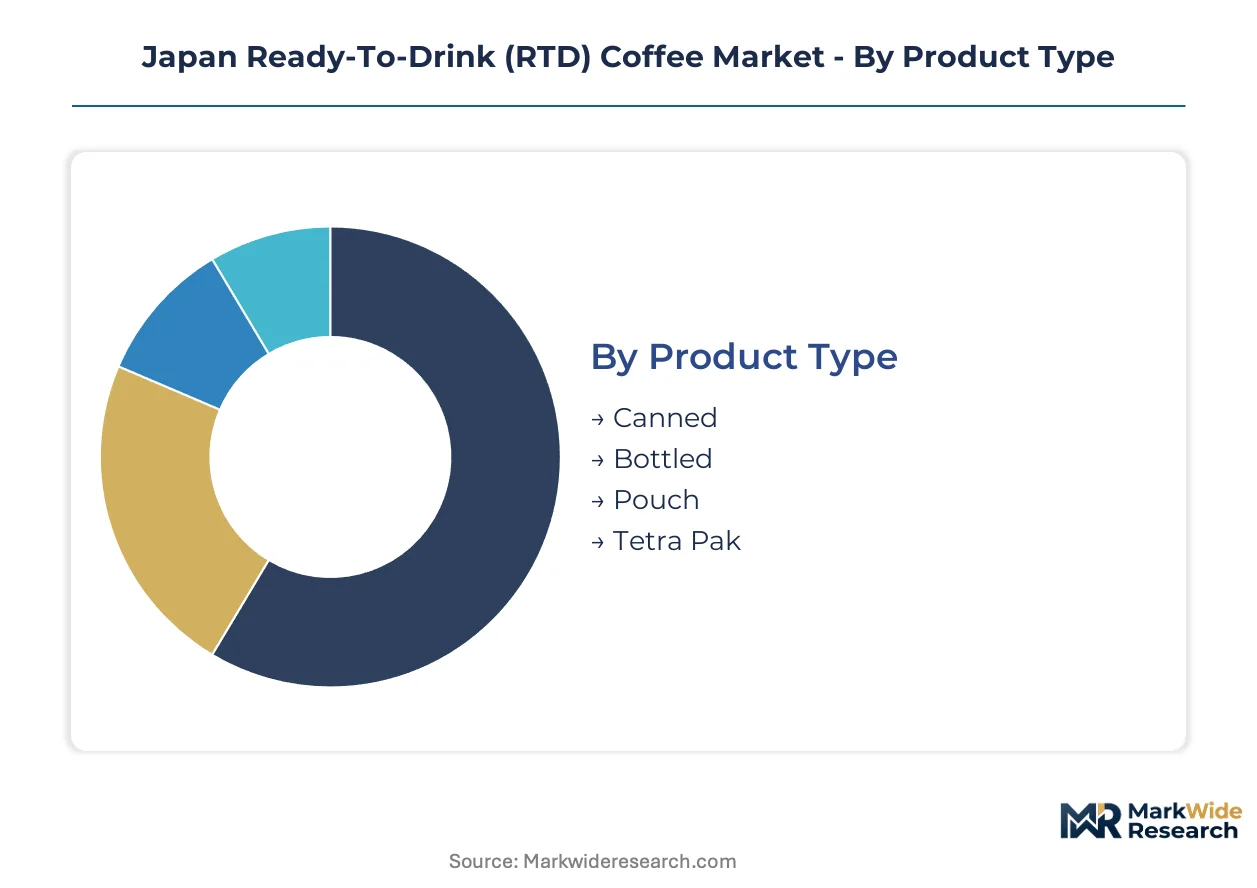
Product Type:
Canned formats flow through vending machine networks and convenience store ambient shelves, while bottled variants concentrate in refrigerated convenience store sections and supermarket cold cases.
- Canned:Aluminum-can construction delivers shelf stability across 12-24 month horizons without refrigeration. Demand concentrates in Greater Tokyo and Osaka-Kobe commuter corridors where vending machine density exceeds 23 units per square kilometer.
- Bottled:PET or glass containers carry refrigeration-dependent freshness claims and premium positioning. Expansion concentrates in convenience store cold cases along suburban rail lines where grab-and-go afternoon refreshment occasions cluster.
- Pouch:Flexible retort packaging enables seasonal limited editions with faster flavor rotation and lower minimum production runs.
- Tetra Pak:Aseptic carton formats occupy institutional channels and workplace pantry services seeking portion control and reduced packaging waste.
Canned dominates installed base. Bottled is where expansion concentrates.
Flavor Profile:
Flavor preferences stratify by consumption occasion, with morning transit favoring intensity and afternoon refreshment accepting sweetness.
- Original:Unsweetened black coffee formulations deliver standardized caffeine content between 60-200mg per serving. Volume concentrates in vending machine channels serving morning commuter entry into office districts.
- Mocha:Chocolate-coffee hybrid formulations balance bitterness with approachable sweetness. Demand clusters in convenience store grab-and-go sections targeting afternoon energy restoration without harsh taste profiles.
- Vanilla:Sweetened dairy-forward variants capture younger demographics and occasional coffee drinkers.
- Caramel:Dessert-positioned formulations occupy seasonal promotional cycles and gift packaging segments.
Original commands absolute volume through heritage positioning. Mocha is climbing the fastest as afternoon occasion expansion reshapes consumption timing.
Ingredient Type:
Ingredient claims increasingly determine shelf placement priority and procurement standards across retail banners.
- Low Sugar:Reduced-carbohydrate formulations align with metabolic health positioning and workplace wellness program procurement criteria. Demand concentrates among white-collar commuters in dense office districts where afternoon refreshment occasions previously defaulted to standard formulations.
- High Protein:Protein-fortified variants target fitness-oriented consumers and meal-replacement occasions. Expansion concentrates in convenience store chains extending functional beverage sections in Greater Tokyo.
- Organic:Certified cultivation claims attract premium positioning in supermarket natural food aisles.
- Non-Dairy:Plant-based milk alternatives capture lactose-intolerant demographics and sustainability-conscious urban consumers.
Low Sugar dominates functional claim penetration. High Protein is gaining share fastest as protein fortification crosses from sports nutrition into mainstream refreshment.
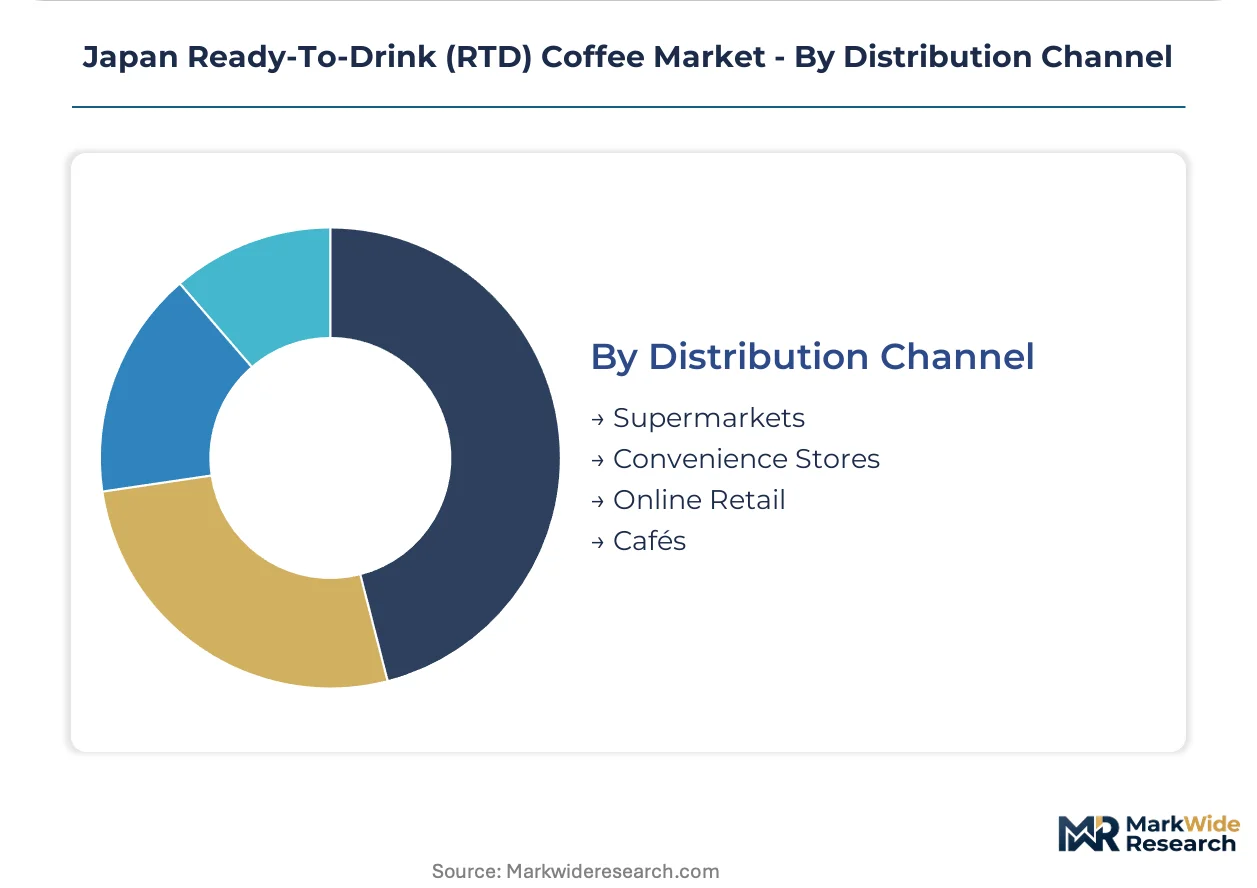
Distribution Channel:
Channel control determines pricing power and brand visibility, with convenience store chains extracting slotting fees that reshape margin structures.
- Convenience Stores:Lawson, 7-Eleven Japan and FamilyMart operate refrigerated and ambient shelf networks with highest foot traffic density. Volume concentrates in Greater Tokyo and Osaka-Kobe corridors where commuter patterns sustain multiple daily purchase occasions.
- Supermarkets:Multi-format retail banners carry broader SKU ranges including premium bottled variants and multipack configurations. Demand clusters in suburban household stock-up trips and weekend promotional cycles.
- Online Retail:E-commerce platforms and subscription services bypass slotting fee structures while capturing workplace direct delivery and bulk pantry replenishment.
- Cafés:Coffee shop chains and independent operators serve immediate consumption with premium positioning and customization options.
Convenience Stores anchor volume throughput. Online Retail is where margin expansion concentrates as subscription models capture recurring pantry replenishment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban commuters in Greater Tokyo and Osaka-Kobe corridors drive the bulk of grab-and-go RTD coffee purchases, with vending machine density and convenience store placement determining competitive access.
Kanto/Tokyo
White-collar office workers in Shibuya and Marunouchi districts sustain premium bottled demand through afternoon refreshment occasions. METI's F-Gas phasedown schedules pressure cold-chain equipment replacement in refrigerated distribution networks. Suntory Holdings anchors Kanto supply through captive refrigerated logistics serving Lawson and 7-Eleven Japan cold cases.
Kansai/Osaka
Osaka-Kobe commuter rail corridors concentrate vending machine installations exceeding 20 units per square kilometer in Umeda and Namba transit hubs. The Consumer Affairs Agency enforces Food Labeling Standards Act precision requirements on caffeine disclosure across all retail channels. UCC Ueshima Coffee leverages heritage brand equity in regional Kansai convenience store partnerships.
Chubu/Nagoya
Automotive sector shift workers in Toyota and Nagoya industrial zones generate off-peak consumption outside standard commuter windows. JIS S 2060 certification timelines for container integrity testing slow new product launches from regional entrants. Asahi Group Holdings extends vertically integrated canning networks through Honshu distribution corridors serving Chubu markets.
Hokkaido
Aging demographics and lower vending machine density create whitespace for functional coffee positioning around protein-fortified and low-sugar variants. METI's Sustainable Food Systems Strategy pressures lighter-weight packaging innovations in remote distribution logistics. Sapporo-based retail banners trial seasonal limited editions through flexible retort pouch formats.
Tohoku
Sendai metropolitan recovery and reconstruction investment has rebuilt convenience store density following earlier disruptions. The Containers and Packaging Recycling Law mandates aluminum and PET circular material flows that elevate compliance costs for smaller regional distributors. Local bottlers face margin compression from aluminum price volatility transmitted through global smelter capacity constraints.
Japan Ready-To-Drink (RTD) Coffee Market Competitive Landscape
Player mix skews toward diversified beverage conglomerates with captive canning infrastructure and heritage coffee specialists with deep convenience store relationships. Market structure concentrates around three strategic archetypes: vertically integrated aluminum canning networks controlling Honshu distribution corridors, refrigerated supply chain operators dominating Kanto and Kansai premium bottled segments, and functional ingredient specialists capturing health-oriented urban rotations. Dominant competitive moves include backward integration into aluminum sourcing and strategic partnerships with convenience store chains for refrigerated shelf placement.
Among diversified beverage conglomerates, Asahi Group Holdings, Suntory Holdings, and Kirin Holdings occupy positions defined by infrastructure control rather than brand differentiation alone. Asahi exemplifies the vertically integrated archetype through captive canning networks. Suntory represents refrigerated supply chain concentration in premium positioning. Kirin sits within the diversified portfolio tier leveraging cross-category distribution scale.
| Leading Market Players |
|---|
| Asahi Group Holdings |
| The Coca-Cola Company |
| Suntory Holdings |
| UCC Ueshima Coffee |
| Nestlé |
| Kirin Holdings |
| Coca-Cola Bottlers Japan |
| Starbucks Coffee Company |
| PepsiCo |
| Others |
Supply & Pricing Matrix
Captive canning network utilization rates above 85 percent in Honshu distribution corridors create scale economies that compress per-unit aluminum sourcing costs while establishing price floors regional entrants cannot match. This concentration of production capacity in vertically integrated beverage conglomerates feeds directly into margin structures across canned and bottled format tiers.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate aluminum can procurement, transmitting global smelter energy cost spikes directly into input cost structures. Pricing stratifies across premium refrigerated bottled, standard ambient canned, and economy private-label tiers, with differentiation driven by cold-chain certification status and convenience store slotting fee absorption. Cost compression in the canned volume core is intensifying because METI container recycling mandates force lighter-weight material investments without immediate volume offset. Heritage brand buyers in Greater Tokyo commuter corridors show lowest price sensitivity, while aging demographic segments in Tohoku and Hokkaido exhibit highest elasticity.
Supply Chain Analysis
Inbound logistics costs through Yokohama and Osaka port congestion, combined with Asia-Pacific container availability constraints on the Shanghai-Osaka trade lane, elevate working capital requirements for PET resin and flavor additive imports. Aluminum ingot supply concentrates in Australia, Indonesia, and domestic Japanese smelters, while cold-chain equipment draws from German and South Korean refrigeration technology providers. Single-source vulnerability in natural refrigerant compressor technology creates fleet replacement risk as F-Gas phasedown accelerates. Distribution runs through Lawson, 7-Eleven Japan, and FamilyMart refrigerated and ambient shelf networks, with third-party logistics consolidation in Kanto and Kansai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power in Japan's RTD coffee market is concentrating through convenience store chain consolidation, with Lawson, 7-Eleven Japan, and FamilyMart extracting slotting fees that reshape margin structures and elevate compliance as a competitive barrier.
For Market Incumbents: Secure backward integration into aluminum canning capacity to defend against regional entrant cost advantages and raw material volatility. Prioritize JIS S 2060 certification maintenance as a lever to extend product launch timelines that disadvantage smaller competitors. Lock in refrigerated shelf placement agreements with FamilyMart and Lawson before F-Gas equipment replacement cycles elevate third-party logistics renegotiation risk. For New Entrants and Emerging Players: JIS S 2060 certification fast-track through partnership with established canning networks offers the most viable entry path around 6-12 month testing delays. Target Hokkaido and Tohoku functional coffee whitespace, where protein-fortified and low-sugar variants face lower vending machine density competition. Pursue workplace direct delivery subscription models in Sendai and Sapporo office districts to bypass convenience store slotting fee structures entirely. For Investors and Strategic Acquirers: Regional bottlers with captive convenience store relationships in Kansai and Chubu represent the most defensible acquisition target archetype, given heritage brand equity and distribution density that national players cannot replicate quickly. Long-term viability over a 5-10 year window hinges on cold-chain refrigeration asset compliance with evolving METI F-Gas standards. Watch for natural refrigerant technician certification scarcity as the inflection signal for in-house fleet management capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Canning | Captive aluminum sourcing insulates margin from LME volatility and METI recycling compliance costs. |
| Natural Refrigerant Fleet Conversion | Early F-Gas phasedown adoption secures carbon footprint certification advantages with Lawson and 7-Eleven Japan procurement. |
| Functional Ingredient R&D Partnership | Protein fortification and low-sugar formulation capabilities capture health-oriented rotations in Greater Tokyo office districts. |
| Workplace Direct Delivery Launch | Subscription models bypass convenience store intermediaries and slotting fees in dense commuter corridors. |
| Retort Pouch Format Expansion | Flexible packaging enables seasonal limited editions with faster flavor rotation and lower minimum production runs. |
Research Methodology
The analysis maps canned ambient-stable, bottled refrigerated, retort pouch, and Tetra Pak institutional sub-sectors, each validated through convenience store category buyers, beverage supply chain planners, cold-chain logistics operators, and METI regulatory affairs specialists. Primary interviews with these stakeholders combined with secondary validation from Japan Customs trade statistics, Consumer Affairs Agency Food Labeling Standards enforcement records, and Containers and Packaging Recycling Law compliance filings. Bottom-up SKU-level volume modeling and top-down macroeconomic triangulation anchored market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, flavor profile, ingredient claim, and distribution channel segmentation dimensions. CAGRs were derived from trend extrapolation of commuter foot traffic patterns, vending machine installation rates, and convenience store expansion capex disclosures. Industry-specific forecast inputs included METI F-Gas phasedown schedules and aluminum smelter capacity utilization projections.
Underlying assumptions cover sustained convenience store grab-and-go consumption growth and stable aluminum price indexation mechanisms, with deviation risk concentrated in regulatory acceleration of container recycling mandates and cold-chain technician availability constraints. Forecasts reflect these conditions with acknowledgment that outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Middle East and Africa Fruits and Vegetable Juice Market
Beverages
Low Fat Drinks Market
Beverages
Aloe Vera-Based Drink Market
Beverages
Reconstituted Juice Market
Beverages
Europe Yerba Mate Market
Beverages
Germany Probiotic Drinks Market
Beverages
Collagen Drinks Market
Beverages
Ginger Ale Market
Beverages
Latin America Sports and Energy Drinks Market
Beverages
Italy Probiotic Drinks Market
Beverages
Maple Water Market
Beverages
Fusion Beverages Market
Beverages
North America Yerba Mate Market
Beverages
Beverage Multipacks Market
Beverages
Smart Home-Based Beverage Machine Market
Beverages
Europe Probiotic Drinks Market