
 Packaged Coconut Water Market | 2026-2036
Packaged Coconut Water Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Coconut Water Market Analysis
USDA organic certification is hardening the cost-of-entry calculus for new packaged coconut water brands, forcing capital investment in traceable supply chains and third-party audit infrastructure. Vita Coco Company leverages its multi-country sourcing network to sustain year-round availability across North American retail channels. Harmless Harvest anchors premium positioning through High Pressure Processing technology that extends refrigerated shelf life without thermal degradation. PepsiCo competes on manufacturing scale and beverage system distribution density, while Goya Foods occupies ethnic grocery and mainstream supermarket overlap with bilingual packaging and heritage brand recognition.
Packaged coconut water is the sterile extraction, filtration, and hermetic packaging of liquid endosperm from mature or young Cocos nucifera fruits, typically processed to achieve pH 4.6–5.2 and packaged in materials ranging from aseptic Tetra Pak cartons to aluminum cans with nitrogen-flush headspace. Pure coconut water commands the largest volume share but faces margin compression from commodity-grade imports, while coconut water blend variants with tropical fruit juices capture faster velocity in convenience channels seeking flavor differentiation. Carbonated coconut water remains nascent in North America but shows structural promise in European markets where sparkling functional beverages carry premium price elasticity.
FDA food labeling rules, USDA National Organic Program standards, and EU REACH chemical safety frameworks collectively shape permissible processing aids, packaging migration limits, and import documentation burdens for coconut water crossing into regulated markets. Health Canada and ANVISA impose parallel microbial and heavy-metal testing regimes that filter out small-scale exporters lacking laboratory partnerships. Stakeholders must monitor evolving extended producer responsibility mandates for beverage packaging and decide whether to front-run circular-economy compliance or absorb retrofit costs when enforcement tightens.
Market Dynamics
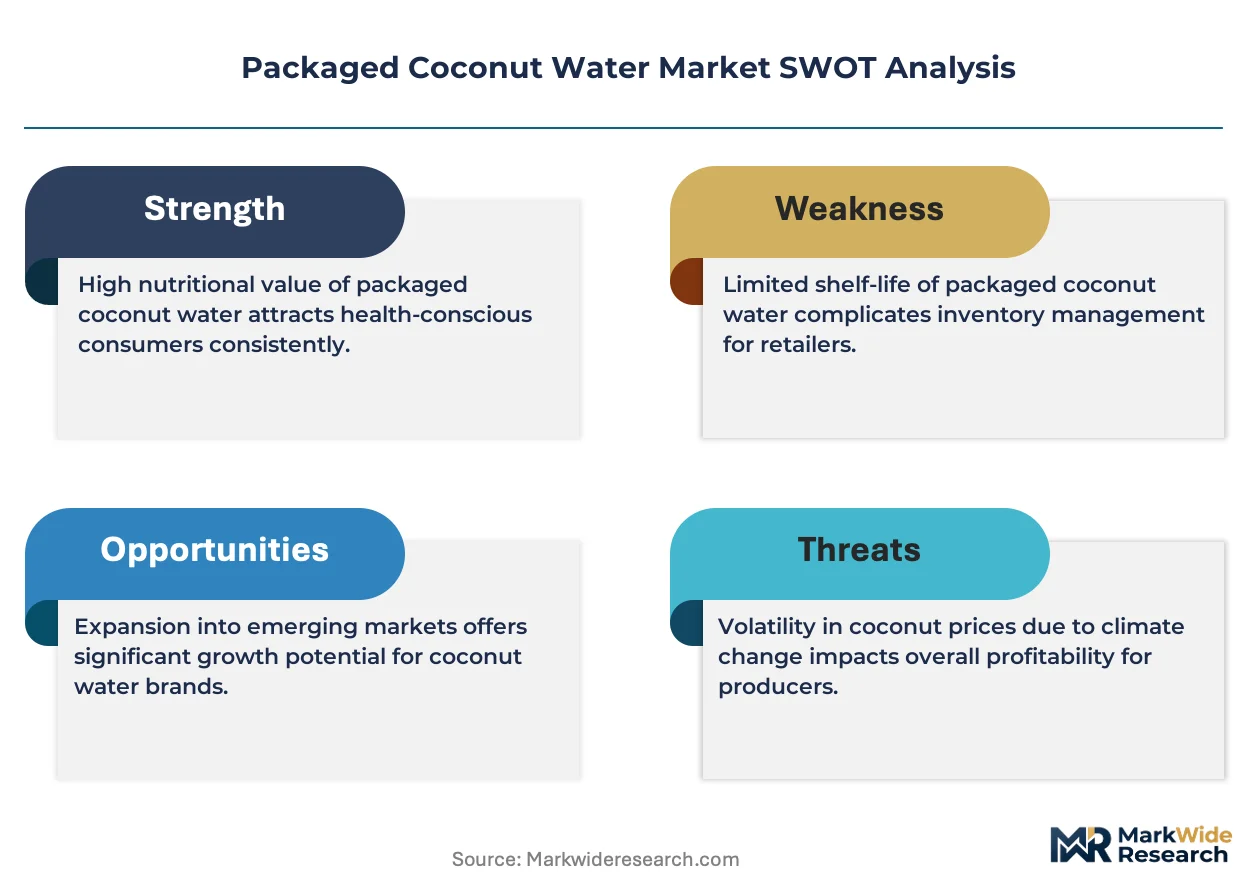
USDA organic certification requirements are hardening cost-of-entry calculus for new packaged coconut water brands, forcing capital investment in traceable supply chains and third-party audit infrastructure across sourcing regions.
Growth Catalysts
- High Pressure Processing:Cold pasteurization technology preserves heat-sensitive electrolytes and enzymes, extending refrigerated shelf life without thermal degradation and opening premium channel access.
- Sports nutrition application pull:Post-workout recovery positioning shifts volume from conventional sports drinks into functional hydration, with athletic clubs and fitness centers expanding refrigerated facings.
- EU REACH chemical safety frameworks:Migration-tested packaging materials compliant with European chemical safety standards unlock cross-border retail placement in regulated Western European markets.
Market Restraints
- Young coconut supply concentration:Thailand, Indonesia, and the Philippines dominate fresh nut availability, exposing processors to monsoon-driven crop volatility and freight rate spikes.
- FDA food labeling enforcement:Nutrient content claim substantiation requirements increase legal review costs and delay label revisions for blend variants with added juices.
- Tap water and enhanced bottled water substitution:Low-cost hydration alternatives in foodservice and institutional channels compress price elasticity for commodity-grade coconut water.
Strategic Opportunities
- Carbonated format penetration in Germany and France:Sparkling functional beverage acceptance in European markets supports premium price positioning for nitrogen-chilled effervescent variants.
- Extended producer responsibility mandates:Front-running circular-economy compliance for aseptic carton and aluminum can recovery systems builds retailer preference ahead of enforcement tightening.
- Direct-to-subscription channel development:Cold-chain subscription boxes bypass traditional distributor markups while capturing recurring revenue from wellness-focused households.
Industry Challenges
- Organic certification timeline compression:USDA National Organic Program transition period requirements and inspector availability bottlenecks delay product launches by 8-14 months.
- Cold-chain capex intensity:Refrigerated transport fleet expansion and warehouse temperature monitoring systems demand upfront capital that strains emerging brand balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Coconut Water Market |
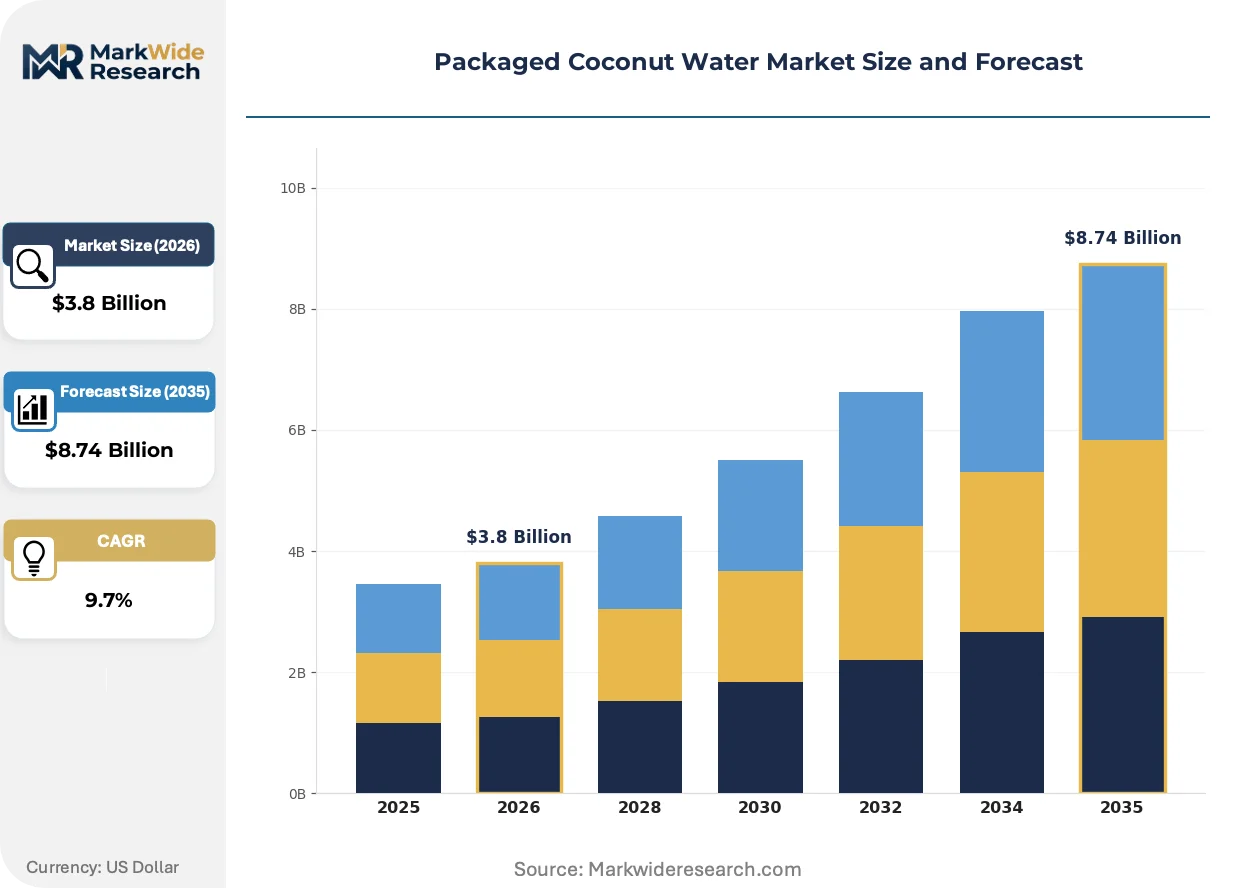
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Coconut Water, Coconut Water Blend, Sweetened Coconut Water, Carbonated Coconut Water Packaging Type: Tetra Pack, Glass Bottle, Plastic Bottle, Can Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Food Shops End User: Health Conscious Consumers, Fitness Enthusiasts, Young Adults, Families |
| Companies Covered | Harmless Harvest, Goya Foods, Vita Coco Company, Celebes Coconut Corporation, Taste Nirvana International, PepsiCo, C2O Pure Coconut Water, ZICO Rising, The Coca-Cola Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Coconut Water Market Emerging Trajectories
Processing technology and packaging format evolution are compressing traditional trade-offs between shelf stability and nutrient retention, while regulatory chemical safety standards and procurement model shifts reshape competitive positioning.
Aseptic filling systems paired with nitrogen-flush headspace technology are modularizing the production economics of ambient-stable coconut water. Mid-size processors in Brazil and Vietnam are adopting these systems to bypass refrigerated distribution constraints and access convenience store channels previously dominated by thermal pasteurized imports. This technology convergence is collapsing the traditional premium-commodity price spread for shelf-stable formats.
EU REACH chemical safety frameworks are tightening migration limits for bisphenol and phthalate residues in beverage contact materials. Packaging suppliers must submit extended safety dossiers for novel barrier films, extending qualification timelines for coconut water exporters seeking European retail placement. Aseptic carton and aluminum can formats with established migration testing histories are gaining share against newer flexible pouch entrants.
Buyer concentration among wellness-focused e-commerce aggregators is displacing conventional distributor relationships for emerging coconut water brands. Subscription box curators and direct-to-consumer platforms in the United States are capturing household pantry share through bundled functional beverage assortments. This channel shift concentrates volume with fewer gatekeepers and compresses slotting fee structures compared to mainstream retail.
Packaged Coconut Water Market Segmentation
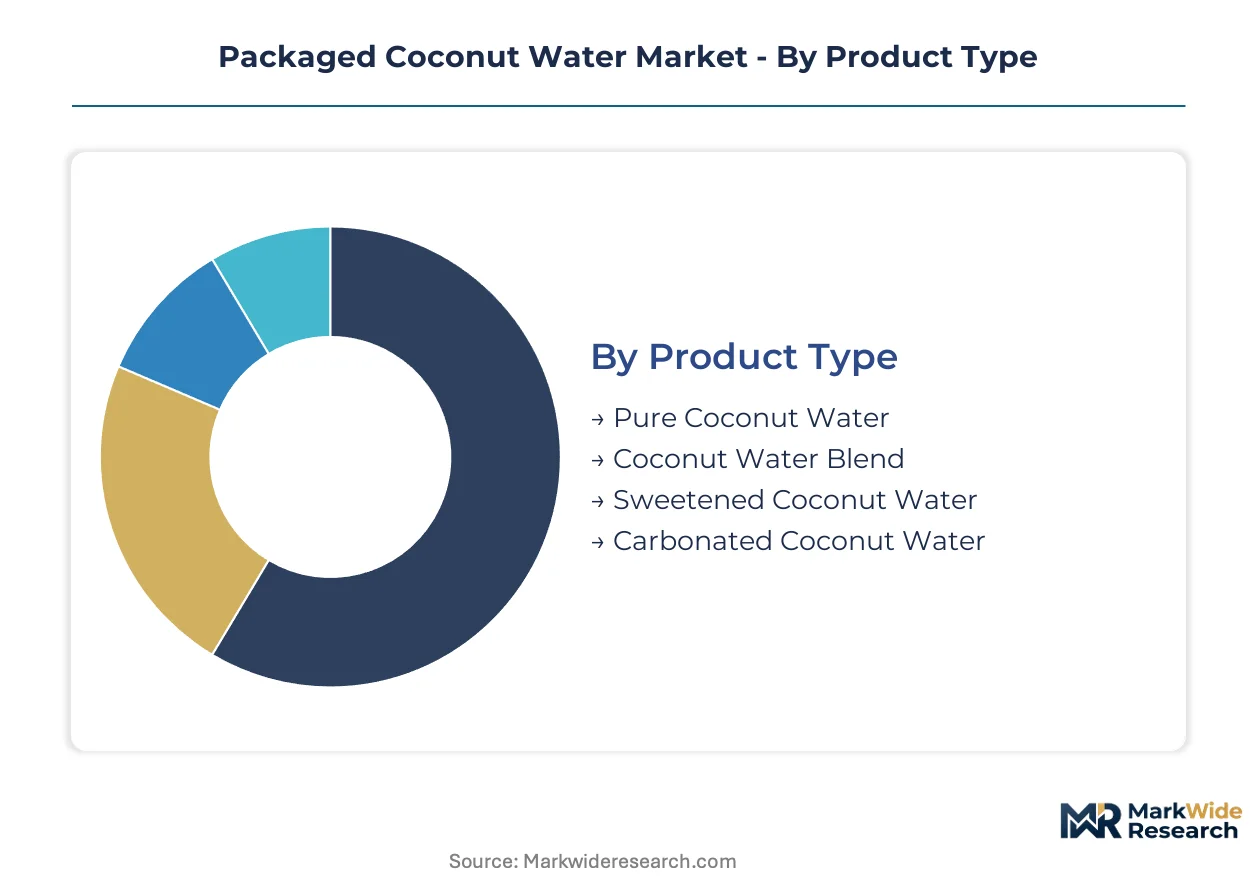
Segmentation in packaged coconut water reveals how processing choices and channel access determine margin capture. Product purity, packaging material costs, and retail format each create distinct competitive battlegrounds with divergent capital requirements.
Product Type:
Volume concentrates in commodity-grade pure formats while premium pricing accrues to differentiated blends and carbonated variants.
- Pure Coconut Water:Single-source extraction without additives or dilution, typically achieving pH 4.6–5.2 through cold pasteurization. Demand clusters in United States mainstream retail and Brazilian supermarkets where price elasticity limits premium positioning. FDA nutrient content claim enforcement raises compliance costs for label revisions.
- Coconut Water Blend:Formulations combining coconut water with tropical fruit juices or functional additives like electrolytes. Velocity accelerates in convenience channels seeking flavor differentiation; post-workout recovery positioning in athletic clubs drives refrigerated facings.
- Sweetened Coconut Water:Added cane sugar or alternative sweeteners targeting palatability-focused consumers in Southeast Asian markets and ethnic grocery overlap in North America.
- Carbonated Coconut Water:Nitrogen-chilled effervescent variants with structural promise in German and French markets where sparkling functional beverages command premium price elasticity.
Mature deployment sits with Pure Coconut Water. Newer deployment is concentrated in Carbonated Coconut Water.
Packaging Type:
Cost tier separates ambient-stable formats from cold-chain-dependent alternatives with divergent distribution economics.
- Tetra Pack:Aseptic carton systems with nitrogen-flush headspace enable ambient shelf stability and modular production economics. Mid-size Brazilian and Vietnamese processors adopt these to bypass refrigerated constraints and access convenience channels.
- Can:Aluminum formats with established EU REACH migration testing histories gain share against flexible pouch entrants in European retail placement. Recycling infrastructure and extended producer responsibility mandates favor established barrier materials.
- Glass Bottle:Premium positioning vehicle in health food shops and direct-to-subscription channels where perceived purity justifies weight and fragility costs.
- Plastic Bottle:Cost-minimizing format dominating commodity-grade imports and foodservice institutional channels where tap water substitution compresses price elasticity.
High-volume deployment sits with Tetra Pack. Premium positioning deployment is concentrated in Glass Bottle.
Distribution Channel:
Customer type stratification separates recurring wellness subscribers from impulse convenience purchasers.
- Supermarkets:Mainstream retail with bilingual packaging requirements and slotting fee structures that favor PepsiCo and Goya Foods manufacturing scale. Refrigerated facings expand in United States and Brazilian stores.
- Online Retail:Wellness-focused e-commerce aggregators and subscription box curators capture household pantry share through bundled functional beverage assortments, concentrating volume with fewer gatekeepers.
- Convenience Stores:Ambient-stable Tetra Pack and can formats dominate grab-and-go hydration with flavor-differentiated blends driving velocity.
- Health Food Shops:Cold-chain premium positioning with High Pressure Processing technology and organic certification commanding shelf space in United States coastal markets.
Scale deployment sits with Supermarkets. Expanding most quickly is Online Retail.
End User:
Application focus separates sports nutrition positioning from family-oriented hydration occasions.
- Fitness Enthusiasts:Post-workout recovery consumption shifting volume from conventional sports drinks into functional hydration, with athletic clubs expanding refrigerated facings for electrolyte-focused pure formats.
- Health Conscious Consumers:USDA organic certification and High Pressure Processing technology drive purchasing decisions; direct-to-subscription channel development captures recurring revenue.
- Young Adults:Flavor-differentiated blends and carbonated variants in convenience and online channels; social media discovery patterns favor emerging brand aesthetics.
- Families:Volume purchasing in supermarkets with price sensitivity toward commodity-grade Tetra Pack formats and sweetened variants for children's palatability.
Established deployment sits with Health Conscious Consumers. Steepest expansion trajectory is Fitness Enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Thailand's Samut Sakhon and Indonesia's Batam drive processing concentration for young coconut extraction. FDA import documentation requirements and USDA organic certification timelines filter small-scale exporters from regulated markets.
United States
Fitness enthusiasts in coastal metropolitan areas pull volume into refrigerated premium channels. FDA food labeling enforcement raises compliance costs for nutrient content claims on blend variants. Brooklyn and Los Angeles anchor cold-chain subscription box fulfillment networks serving wellness-focused households.
Brazil
Mid-size processors in São Paulo state adopt aseptic Tetra Pack systems to bypass refrigerated distribution constraints. ANVISA microbial testing regimes filter exporters lacking laboratory partnerships. The coastal cluster from Santos to Rio de Janeiro concentrates ambient-stable production for convenience store channels.
Germany
Sparkling functional beverage acceptance creates structural promise for carbonated coconut water variants. EU REACH chemical safety frameworks tighten migration limits for packaging materials. Berlin and Hamburg health food shops command premium shelf space for High Pressure Processing technology products.
Thailand
Young coconut supply concentration exposes processors to monsoon-driven crop volatility in the Central Plains. The country's national food safety regulator imposes parallel heavy-metal testing that shapes export qualification timelines. Samut Sakhon province anchors sterile extraction and filtration infrastructure for North American retail placement.
France
Nitrogen-chilled effervescent variants capture premium price elasticity in Parisian convenience channels. Extended producer responsibility mandates for beverage packaging recovery systems build retailer preference. The Île-de-France region concentrates direct-to-subscription platform distribution for bundled functional beverage assortments.
Packaged Coconut Water Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price positioning. The market structure consolidates around manufacturing scale advantages and cold-chain infrastructure density. Three archetypes dominate: beverage system conglomerates leveraging distribution density, heritage ethnic brands occupying bilingual grocery overlap, and premium specialists anchoring refrigerated health channels. Capacity expansion in aseptic filling systems and strategic partnerships for traceable supply chains constitute the dominant competitive moves.
Within the premium specialist tier, Harmless Harvest and Taste Nirvana International exemplify technology-driven positioning through High Pressure Processing and organic certification. Among diversified beverage conglomerates, PepsiCo and The Coca-Cola Company occupy scale-driven positions leveraging manufacturing density and retail system access. Heritage-focused Goya Foods anchors ethnic grocery and mainstream supermarket overlap through bilingual packaging recognition.
| Leading Market Players |
|---|
| Harmless Harvest |
| Goya Foods |
| Vita Coco Company |
| Celebes Coconut Corporation |
| Taste Nirvana International |
| PepsiCo |
| C2O Pure Coconut Water |
| ZICO Rising |
| The Coca-Cola Company |
| Others |
Supply Flow & Price Mechanics
Captive sourcing networks spanning Thailand's Central Plains and Indonesia's Batam anchor both supply security and margin capture for packaged coconut water processors, with vertical integration into sterile extraction infrastructure insulating premium brands from spot-market volatility while commodity traders absorb freight-rate shocks.
Pricing Analysis
Short lead-time premiums command shelf space in refrigerated health channels, while extended-payment spot inventory discounts dominate ambient-stable Tetra Pack procurement. Three-tier pricing structure across premium, standard, and economy levels separates High Pressure Processing-certified organic formats from aseptic thermal pasteurized mid-tier and commodity-grade imports. Pricing pressure stems from tap water and enhanced bottled water substitution in foodservice channels. Fitness enthusiasts show lowest price sensitivity; families purchasing supermarket volumes exhibit highest elasticity.
Supply Chain Analysis
Young coconut supply rests on Thailand, Indonesia, and the Philippines for fresh nut availability, with Brazilian mid-size processors drawing from domestic mature coconut feedstocks. Sterile extraction equipment, nitrogen-flush aseptic filling systems, and EU REACH-compliant barrier films constitute critical input dependencies. Monsoon-driven crop volatility in Southeast Asia creates single-source vulnerability for premium cold-chain brands. Distribution runs through beverage system conglomerates, wellness-focused e-commerce aggregators, and ethnic grocery channels with divergent slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Packaged coconut water sits in a processing technology transition, with High Pressure Processing displacing thermal pasteurization as the anchor for premium positioning and refrigerated channel access.
For Market Incumbents: Acquire cold-chain logistics assets in coastal metropolitan fulfillment networks to defend against subscription-box aggregators capturing wellness household pantry share. Secure multi-country sourcing contracts across Thailand, Indonesia, and Brazil to buffer monsoon-driven crop volatility. Invest in USDA National Organic Program certification infrastructure ahead of inspector availability bottlenecks tightening transition timelines. For New Entrants and Emerging Players: Launch via direct-to-subscription channel development bypassing traditional distributor markups, targeting carbonated format penetration in German and French markets where sparkling functional beverage acceptance supports premium positioning. Capture athletic club refrigerated facings with post-workout recovery positioning against conventional sports drinks. Anchor initial volume through wellness-focused e-commerce curators before mainstream retail slotting fee negotiation. For Investors and Strategic Acquirers: Exit pathways concentrate in beverage system conglomerate acquisition of premium specialist brands with High Pressure Processing technology and organic certification infrastructure. Long-term viability hinges on cold-chain capex intensity and traceable supply chain audit capabilities as USDA requirements harden. Watch extended producer responsibility mandate enforcement tightening as the inflection signal for packaging recovery system valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| High Pressure Processing Capacity Expansion | Extends refrigerated shelf life without thermal degradation, opening premium channel placement. |
| Multi-Country Sourcing Network Development | Insures year-round availability against monsoon-driven crop volatility in Thailand and Indonesia. |
| USDA Organic Certification Investment | Hardens cost-of-entry barriers against commodity-grade imports in regulated North American markets. |
| Direct-to-Subscription Channel Launch | Bypasses distributor markups while capturing recurring revenue from wellness-focused households. |
| EU REACH-Compliant Packaging Qualification | Unlocks cross-border retail placement in German and French markets with tightened migration limits. |
Methodological Framework
Independent corroboration across brand managers at beverage conglomerates, category buyers at supermarket chains, cold-chain logistics operators, and sterile extraction equipment suppliers underwrites the qualitative findings. Primary interviews with supply planners at coconut water processors and channel sales heads at ethnic grocery distributors combined with secondary validation from FDA food labeling guidance documents, USDA National Organic Program standards, EU REACH chemical safety dossiers, and customs trade data for young coconut imports. Bottom-up volume modeling from processor capacity and top-down market sizing from retail audit data triangulate to the figures presented.
Historical reference periods spanning pre-pandemic baseline, supply disruption interval, and normalization phase anchor the forecast window across the projection horizon. Segmentation dimensions modeled include product purity tier, packaging material cost structure, distribution channel type, and end-user application focus. CAGRs derive from processor capacity expansion pipelines, refrigerated facing expansion rates at athletic clubs, and e-commerce aggregator growth trajectories. Forecast inputs incorporate monsoon pattern variability, inspector availability for organic certification, and extended producer responsibility mandate implementation schedules.
The model assumes a particular technology adoption path; alternative pathways for aseptic thermal pasteurization would alter the outlook if High Pressure Processing capex intensity proves prohibitive for mid-tier brands. Forecasts reflect assumptions about cold-chain infrastructure buildout, wellness consumer retention post-subscription trial, and EU migration limit enforcement consistency. Regulatory timeline compression, freight rate volatility, and tap water substitution acceleration in foodservice constitute specific risk factors. A small set of triggers—organic certification inspector strikes, major monsoon crop failure, or abrupt extended producer responsibility enforcement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Soft Serve Premix Market
Beverages
North America Dairy Beverages Market
Beverages
Nitro-Infused Cola Market
Beverages
South East Asia Bottled Water Market
Beverages
Aloe Vera-Based Drink Market
Beverages
Breakfast Drink Market
Beverages
Smoothies Market
Beverages
Grab and Go Bottles Market
Beverages
South America Bottled Water Market
Beverages
Ready to Drink Premixes Market
Beverages
North America Cold Pressed Juices Market
Beverages
Europe Ready-To-Drink Beverages Market
Beverages
Apple Juice Concentrate Market
Beverages
Orange Juice Market
Beverages
Powdered Beverages Market
Beverages
South America Dairy Based Beverages Market