
 BBQ Charcoal Market | 2026-2036
BBQ Charcoal Market Size, Share, and Industry Trends Forecast 2026-2036
BBQ Charcoal Market Analysis
The EU Deforestation Regulation is restructuring compliance requirements for charcoal entering European ports, forcing suppliers to demonstrate traceable, sustainable wood sourcing. Kingsford Products Company leverages its domestic hardwood supply chains to sustain volume leadership across North American retail channels. Royal Oak Enterprises LLC anchors its position through vertical integration from timberlands to bagging facilities. Fogo Charcoal differentiates via premium hardwood lump positioning in specialty barbecue retail.
BBQ charcoal comprises carbonized biomass—typically hardwood, fruitwood, or compressed agricultural residues—produced through controlled pyrolysis at 400–700°C to create a low-moisture, high-fixed-carbon fuel optimized for sustained heat output and minimal ash residue. Lump charcoal retains natural wood structure and ignites faster with higher peak temperatures, while briquettes deliver uniform burn duration through compressed binders and additives. The material dimension reveals hardwood charcoal dominating premium segments, with coconut shell charcoal gaining traction in specialty applications due to its low ash and neutral flavor profile. Distribution through supermarkets still occupies the largest volume channel, though online retail is capturing enthusiast segments seeking niche hardwood varieties.
The USDA enforces plant health inspection standards on imported charcoal under APHIS protocols, while the EPA regulates particulate emissions from charcoal manufacturing facilities under Clean Air Act provisions. In Europe, ECHA's REACH framework governs chemical safety in charcoal binders and ignition additives, with the EU Green Deal's deforestation-free requirements now mandating geolocation traceability for all wood-based fuel imports. Stakeholders must monitor evolving carbon border adjustment mechanisms and deforestation due diligence laws that will determine which sourcing regions retain market access.
Market Dynamics
The EU Deforestation Regulation's geolocation traceability mandate is forcing wholesale restructuring of charcoal import protocols, compressing supplier margins while favoring vertically integrated hardwood producers with documented timberland ownership.
Growth Catalysts
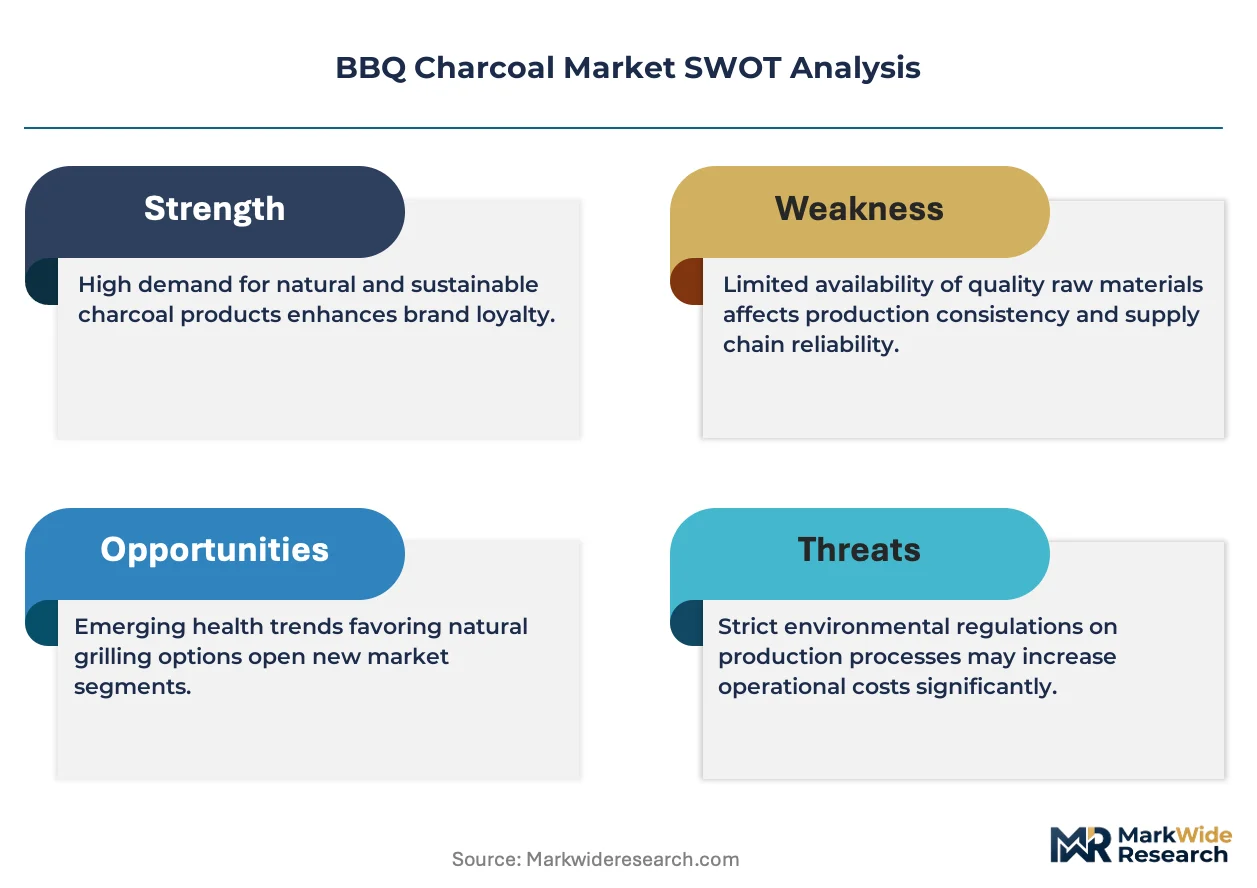
- Outdoor Dining Permanence:Restaurants and catering services have institutionalized open-air seating formats, locking in recurring bulk charcoal procurement cycles that stabilize demand volatility for suppliers.
- EU Green Deal Compliance Infrastructure:The deforestation-free supply chain framework is creating competitive moats for early-adopting importers who built traceable sourcing networks ahead of enforcement deadlines.
- Brazilian Churrasco Export Cluster:Hardwood charcoal production hubs in Minas Gerais and São Paulo states serve dual domestic consumption and international premium markets simultaneously.
Market Restraints
- Hardwood Input Cost Volatility:Oak and hickory timber prices fluctuate with construction sector competition for lumber, squeezing lump charcoal margins without corresponding pricing power.
- South American Supply Concentration:Brazil's dominance in global hardwood charcoal exports creates single-source vulnerability for European and North American buyers during harvest disruptions or currency shocks.
- Briquette Performance Ceiling:Compressed binder-dependent formulations cannot match lump charcoal's peak temperature output, limiting penetration in enthusiast segments despite superior burn consistency.
Strategic Opportunities
- Indonesian Coconut Shell Scale-Up:Abundant agricultural residue from palm and coconut processing offers low-ash, neutral-flavor charcoal feedstock for specialty barbecue and shisha markets.
- Direct-to-Consumer Channel Expansion:Online retail platforms enable enthusiast access to single-origin hardwood varieties bypassing supermarket assortment constraints.
- USDA APHIS Certification Alignment:Plant health inspection standardization creates export pathway advantages for suppliers achieving pre-clearance status versus inspection-backlogged competitors.
Industry Challenges
- Pyrolysis Engineering Talent Scarcity:Controlled carbonization facility operations require specialized knowledge of temperature curve management and emissions control that outpaces vocational training pipeline output.
- REACH Binder Compliance Timeline:ECHA's chemical safety framework demands extensive additive disclosure and testing cycles that delay product reformulation launches by 12-18 months.
- Legacy Kiln Emissions Retrofit Burden:Traditional earth-mound and brick kiln operations face EPA Clean Air Act particulate enforcement requiring capital-intensive afterburner or filtration installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BBQ Charcoal Market |
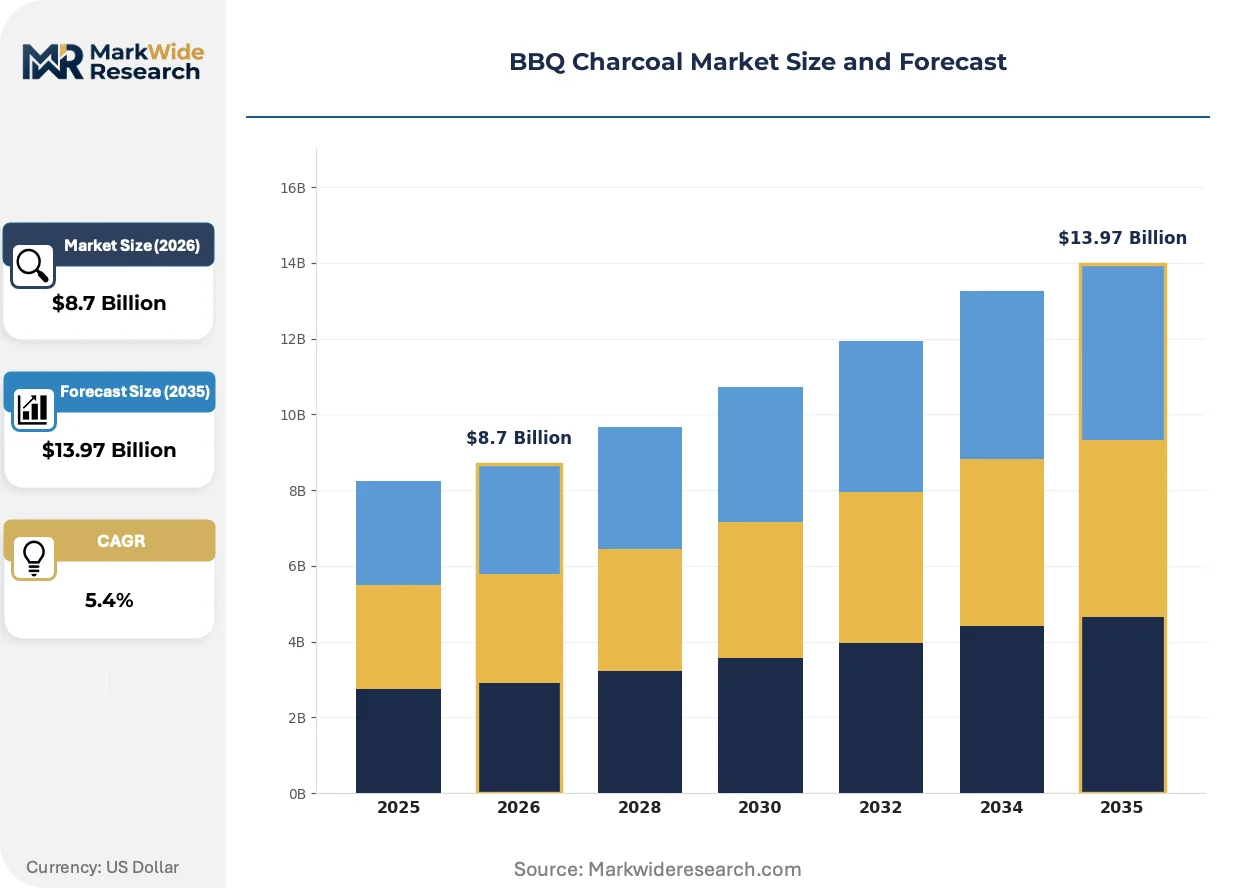
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Charcoal, Briquettes, Lump Charcoal, Activated Charcoal Material: Wood, Bamboo, Coconut Shell, Peat Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale End User: Households, Restaurants, Catering Services, Outdoor Events |
| Companies Covered | Ignite Products, Big Green Egg Charcoal, Royal Oak Enterprises LLC, Fogo Charcoal, Jealous Devil Charcoal, Kingsford Products Company, Paraguay Charcoal, Kamado Joe Charcoal, Duraflame Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BBQ Charcoal Market Emerging Trajectories
Carbonization technology and sourcing transparency protocols are converging to reshape product differentiation and procurement qualification standards across barbecue fuel supply chains.
Smart temperature-monitoring kiln controls are integrating pyrolysis automation with real-time emissions tracking. Premium hardwood producers in Kentucky and Tennessee deploy these systems to guarantee fixed-carbon consistency for competition barbecue teams. The technology is integrating quality assurance documentation directly into batch-level traceability records required by EU import authorities.
ECHA's REACH framework governing chemical safety in charcoal binders and ignition additives tightened disclosure thresholds for polycyclic aromatic hydrocarbons. Manufacturers reformulating briquette compositions face extended testing protocols that advantage established laboratories with existing substance dossiers. European importers now require third-party additive certificates as standard purchase order terms, filtering out unverified Asian suppliers.
Enthusiast buyers increasingly prioritize single-origin hardwood provenance over price in specialty retail channels. Independent barbecue retailers curate regional oak, mesquite, and fruitwood assortments that supermarkets cannot replicate. This preference shift concentrates margin capture in direct-import relationships and away from mass-market brand intermediaries, most visible in Texas, California, and Pacific Northwest metropolitan markets.
BBQ Charcoal Market Segmentation
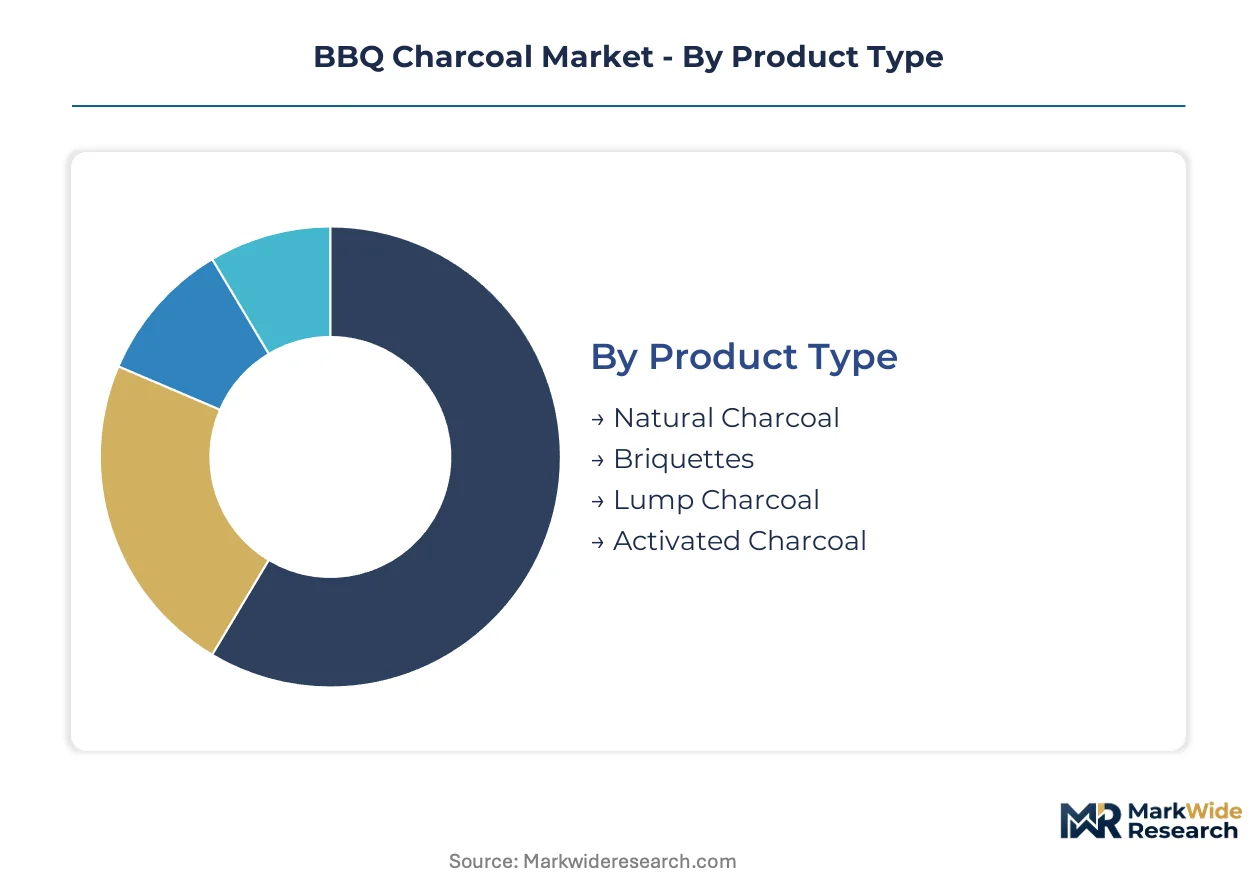
Product differentiation in BBQ charcoal determines heat output profiles, ignition speed, and flavor neutrality that separate enthusiast-grade fuels from commodity alternatives. Segmentation reveals how material sourcing and distribution channel selection create tiered margin structures across the supply chain.
Product Type:
Replacement cycles vary dramatically across product formats, with competition barbecue teams upgrading fuel stocks seasonally while casual consumers replenish annually.
- Lump Charcoal:Retains natural wood cellular structure through pyrolysis, delivering peak temperatures above 700°C with minimal ash residue. Demand concentrates in Texas barbecue competitions and California outdoor cooking clusters where heat intensity outweighs burn duration concerns.
- Briquettes:Compressed biomass with starch binders and mineral additives ensures uniform burn duration across 4-6 hour cycles. European patio grilling and US suburban backyard segments prioritize this consistency for low-supervision cooking sessions.
- Natural Charcoal:Traditional earth-mound carbonization without chemical additives serves purist segments in Brazil's churrasco culture and Japanese yakitori establishments seeking unadulterated wood smoke profiles.
- Activated Charcoal:Extended pyrolysis with steam activation creates high-surface-area carbon for filtration applications rather than combustion, serving water purification and air treatment adjacent markets.
Briquettes sit at the top of the volume ranking, with lump charcoal climbing the fastest.
Material:
Cost tiers separate feedstocks by raw material scarcity and processing energy intensity, with agricultural residues commanding lower input costs than mature hardwoods.
- Wood:Oak, hickory, and mesquite hardwoods dominate premium segments through dense carbon structures that prolong heat release. Kentucky and Tennessee timberlands supply competition-grade lump to US domestic and export markets.
- Coconut Shell:Agricultural residue from Indonesian and Philippine palm oil processing yields low-ash, neutral-flavor carbon preferred for shisha and specialty barbecue applications in Middle Eastern and European urban centers.
- Bamboo:Rapid-growth grass species from China's Fujian and Zhejiang provinces offer renewable feedstock with faster harvest cycles than hardwoods, though lower fixed-carbon content limits penetration in high-heat segments.
- Peat:Partially decomposed organic matter from Irish and Baltic bogs produces slower-burning fuel with distinctive aroma profiles, retaining niche demand in traditional smoking applications despite sustainability scrutiny.
Wood occupies the largest volume position, with coconut shell expanding most quickly.
Distribution Channel:
Customer type dictates channel preference, with enthusiast segments bypassing mass retail for curated single-origin assortments unavailable in supermarket sets.
- Supermarkets:Mass-market retail chains stock standardized briquette SKUs with seasonal promotional cycles tied to Memorial Day and July 4th grilling peaks in the US.
- Online Retail:E-commerce platforms enable direct access to regional hardwood varieties and subscription replenishment models for recurring barbecue enthusiasts.
- Specialty Stores:Independent barbecue retailers curate premium lump assortments with provenance documentation required by EU deforestation regulations.
- Wholesale:Bulk procurement channels serve restaurant chains and catering operations with palletized delivery schedules synchronized to outdoor dining seasonality.
Supermarkets maintain volume leadership, with online retail gaining share fastest.
End User:
Application context determines performance specifications, with commercial operations prioritizing burn consistency over peak temperature metrics valued by enthusiast segments.
- Restaurants:Open-fire steakhouse concepts and Brazilian churrascarias in São Paulo and Dallas deploy hardwood lump for visual flame presentation and flavor transfer.
- Households:Residential patio grilling in suburban US markets and European apartment balconies drives seasonal replenishment of standard briquette formats.
- Catering Services:Mobile barbecue operations for weddings and corporate events require rapid-ignition fuels with predictable burn windows to synchronize service timing.
- Outdoor Events:Festival food vendors and campground operators prioritize compressed briquette formats for transport efficiency and storage stability.
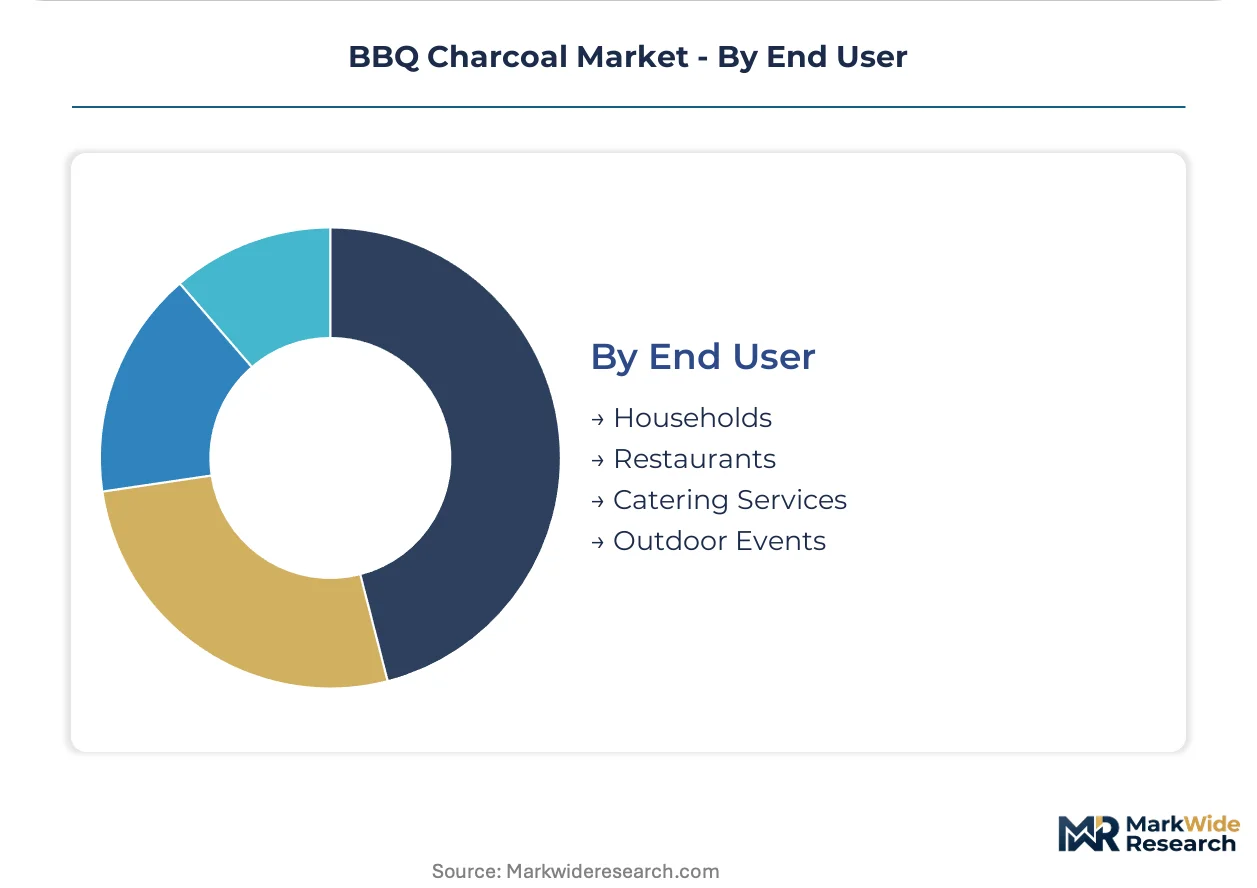
Households dominate volume rankings, with restaurants expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Charcoal carbonization emerged as an industrial practice in nineteenth-century North American hardwood forests, where controlled pyrolysis techniques developed to supply fuel for iron forges before transitioning to culinary applications. Contemporary production clusters now span timber-rich and agricultural-residue regions across multiple continents.
United States
Competition barbecue culture in Texas and Kansas City drives premium lump charcoal consumption for high-heat searing applications. The EPA enforces Clean Air Act particulate standards on pyrolysis facilities, particularly in Kentucky and Tennessee where hardwood carbonization plants cluster. Kingsford Products Company maintains production presence in these Appalachian timber regions, supplying retail channels nationwide.
Brazil
Churrasco tradition sustains massive domestic hardwood charcoal demand while Minas Gerais and São Paulo states export premium grades to European and North American markets. ANVISA regulates food-contact carbon materials for restaurant applications. Production cooperatives in the Cerrado biome face mounting pressure to document deforestation-free sourcing under emerging EU import requirements.
Germany
Grilling culture concentrates in Bavaria and North Rhine-Westphalia, where patio barbecue equipment penetration exceeds European averages. ECHA's REACH framework governs chemical binders in imported briquette formulations, with recent disclosure threshold tightening for polycyclic aromatic hydrocarbons. Hamburg serves as the primary European entry port for South American hardwood charcoal, with customs authorities now enforcing geolocation traceability documentation.
Indonesia
Coconut shell charcoal production scales rapidly in Sulawesi and Sumatra, leveraging abundant agricultural residue from palm oil processing operations. The country's national trade regulator coordinates export certification alignment with EU deforestation regulations. Surabaya and Makassar function as consolidation hubs for low-ash, neutral-flavor carbon grades targeting Middle Eastern shisha and European specialty barbecue segments.
China
Bamboo charcoal manufacturing clusters in Fujian and Zhejiang provinces exploit rapid-growth grass harvest cycles for renewable feedstock supply. MEE enforces emissions controls on carbonization kilns through dual carbon policy implementation. Xiamen port handles bulk export shipments to Japan and South Korea, where barbecue culture absorbs consistent volumes of compressed bamboo fuel grades.
BBQ Charcoal Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent manufacturing models in the BBQ charcoal sector. Vertically integrated timberland owners operate pyrolysis kilns and bagging facilities under single ownership, while trading houses source finished product through contract manufacturing arrangements. Three archetypes dominate: hardwood estate operators with captive carbonization capacity, agricultural residue processors exploiting byproduct feedstocks, and brand marketers outsourcing production to third-party kilns. Capacity expansion and documented sustainability certification represent the primary competitive moves as import regulations tighten.
Among US-based hardwood specialists, Kingsford Products Company and Royal Oak Enterprises LLC exemplify the estate-integrated archetype with documented timberland supply chains. Fogo Charcoal occupies a position within the premium-lump tier, representing Brazilian sourcing differentiation in specialty retail channels. These three companies anchor distinct strategic positions without overlapping segment focus, enabling parallel market presence rather than direct confrontation.
| Leading Market Players |
|---|
| Ignite Products |
| Big Green Egg Charcoal |
| Royal Oak Enterprises LLC |
| Fogo Charcoal |
| Jealous Devil Charcoal |
| Kingsford Products Company |
| Paraguay Charcoal |
| Kamado Joe Charcoal |
| Duraflame Inc |
| Others |
Supply Flow & Price Mechanics
Hardwood certification tiers create a three-tier pricing structure across premium, standard, and economy levels that simultaneously segments buyer archetypes and concentrates supply chain control among documented timberland owners in Brazil and Kentucky. EU deforestation-free import requirements now embed compliance costs into landed pricing, compressing margins for traders while rewarding vertically integrated producers with captive hardwood supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates transaction structures, with single-origin hardwood provenance and EU traceability certification commanding substantial premiums over commodity briquette alternatives. Price differentiation stems from hardwood density grades and deforestation-free documentation status, with certified lump charcoal from Minas Gerais timberlands priced at multiples of standard supermarket briquettes. Cost compression in the economy tier is intensifying because construction sector competition for oak and hickory lumber elevates raw material input costs without corresponding pricing power in mass retail channels. Casual suburban households exhibit highest price sensitivity, while competition barbecue teams and Brazilian churrascarias demonstrate inelastic demand for documented provenance.
Supply Chain Analysis
Container freight cost volatility from Santos to Hamburg and Surabaya to Rotterdam directly shapes procurement economics for European importers dependent on Brazilian hardwood and Indonesian coconut shell feedstocks. Geographic supply concentration centers on Brazil for premium lump, Indonesia for low-ash coconut grades, and China's Fujian province for bamboo alternatives. Raw material dependencies rest on mature oak and hickory timber cycles, palm oil processing residue streams, and rapid-growth grass harvests. Single-source vulnerability from Brazil's export dominance creates structural risk during harvest disruptions or currency shocks. Distribution runs through supermarket retail chains for volume, specialty barbecue retailers for premium tiers, and direct-to-consumer platforms for enthusiast segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories favor producers achieving backward integration into documented timberlands and those capturing premium-tier shifts toward single-origin hardwood provenance. Input cost stabilization through captive supply and certification-driven pricing power represent the primary value-creation levers.
For Market Incumbents: Deepen timberland ownership documentation to satisfy EU Deforestation Regulation geolocation traceability mandates ahead of enforcement deadlines. Expand pyrolysis capacity in Kentucky and Tennessee to secure competition barbecue segment loyalty against Brazilian import alternatives. Invest in smart kiln automation to guarantee fixed-carbon consistency and batch-level quality documentation that filters unverified Asian competitors from European procurement channels. For New Entrants and Emerging Players: The mid-tier price gap between premium Brazilian hardwood lump and economy briquettes offers white-space entry through Indonesian coconut shell scale-up for European specialty barbecue and Middle Eastern shisha markets. Target direct-to-consumer subscription models in Texas, California, and Pacific Northwest metropolitan clusters where enthusiast buyers bypass supermarket assortment constraints. Pursue USDA APHIS pre-clearance certification to accelerate export pathways versus inspection-backlogged competitors. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented trading houses lack documented timberland supply chains and face margin compression from compliance cost inflation. Long-term viability favors vertically integrated hardwood estate operators with captive carbonization capacity and established EU import documentation systems. Acquisition target archetypes include Brazilian production cooperatives in Minas Gerais with deforestation-free certification potential and Indonesian coconut shell processors with export consolidation hub positioning. Watch EU carbon border adjustment mechanism implementation timing as inflection indicator for sourcing region market access.| Strategic Initiative | Industry Significance |
|---|---|
| Timberland Documentation Investment | EU Deforestation Regulation geolocation traceability mandates now determine European port entry eligibility for hardwood charcoal shipments. |
| Smart Kiln Automation Deployment | Real-time pyrolysis temperature monitoring integrates quality assurance directly into batch-level import documentation required by Hamburg customs authorities. |
| Direct-to-Consumer Channel Expansion | Online retail platforms enable enthusiast access to single-origin hardwood varieties bypassing supermarket assortment constraints in Texas and California. |
| Coconut Shell Processing Scale-Up | Indonesian agricultural residue from Sulawesi palm operations yields low-ash carbon grades for European specialty barbecue and Middle Eastern shisha segments. |
| USDA APHIS Certification Alignment | Plant health inspection standardization creates export pathway advantages versus competitors facing inspection backlogs at US entry ports. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with charcoal plant managers, procurement leads at restaurant chains, specialty retail buyers, and distribution channel partners with secondary validation. Secondary sources include customs and trade data from Brazilian and Indonesian export authorities, EPA Clean Air Act enforcement records, ECHA REACH substance dossiers, and SEC filings from publicly traded fuel products companies. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity.
Historical trendline analysis of hardwood timber pricing, pyrolysis capacity utilization, and import volume patterns informs projection frameworks across the analysis window. Segmentation dimensions modeled include product type, material feedstock, distribution channel, and end-user application context. CAGRs derive from regression analysis of volume and value trajectories, incorporating competition barbecue culture expansion, outdoor dining permanence in restaurant procurement, and EU regulatory compliance infrastructure buildout as industry-specific forecast inputs.
Caveats apply where Brazilian harvest disruptions, EU carbon border adjustment implementation, or REACH binder compliance timeline extensions could materially shift the outlook. Forecasts reflect assumptions regarding deforestation-free certification adoption rates and hardwood input cost stabilization. A model refresh is warranted upon material change in EU import enforcement protocols or South American supply concentration dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Hydrogen Water Dispenser Market
Beverages
Ready to Drink Shakes Market
Beverages
Double Valve Moka Pots Market
Beverages
North America Cold Pressed Juices Market
Beverages
Recovery Drinks Market
Beverages
Fermented Drinks Market
Beverages
Direct Piping Water Dispenser Market
Beverages
Cold Pressed Juice Market
Beverages
GCC Sports and Energy Drinks Market
Beverages
Europe Coconut Water Market
Beverages
South America Dairy Based Beverages Market
Beverages
Ready to Drink Premixes Market
Beverages
Coconut Milk Beverages Market
Beverages
China Soy Beverages Market
Beverages
North America Energy Drink Market
Beverages
Apple Juice Concentrate Market