
 Freeze-Drying Equipment Market | 2026-2036
Freeze-Drying Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Freeze-Drying Equipment Market Intelligence
Biopharmaceutical contract manufacturers are unwinding legacy batch workflows as personalized medicine and mRNA therapies reshape capacity planning. GEA Group Aktiengesellschaft leverages its pharmaceutical-grade lyophilizer portfolio to dominate European validation protocols. Tofflon Science and Technology Group Co., Ltd. anchors Asia-Pacific supply through integrated freeze-dry and fill-finish lines. SP Industries, Inc. specializes in laboratory-to-production scale transitions that sustain R&D-to-commercial pathways for emerging biotechs.
Freeze-drying equipment removes water from heat-sensitive materials by freezing the product, reducing chamber pressure below the triple point, then supplying latent heat to drive sublimation—typically operating at shelf temperatures between -50°C and +60°C with vacuum levels below 0.1 mbar to preserve protein structure and bioactivity. Tray dryers occupy the mature core of installed base renewal, while continuous dryers represent the fastest-growing technology segment as manufacturers seek to eliminate batch-to-batch variability. Pharmaceutical manufacturing commands the deepest margin pools due to stringent FDA and EMA validation requirements that extend equipment lifecycle value through aftermarket service contracts.
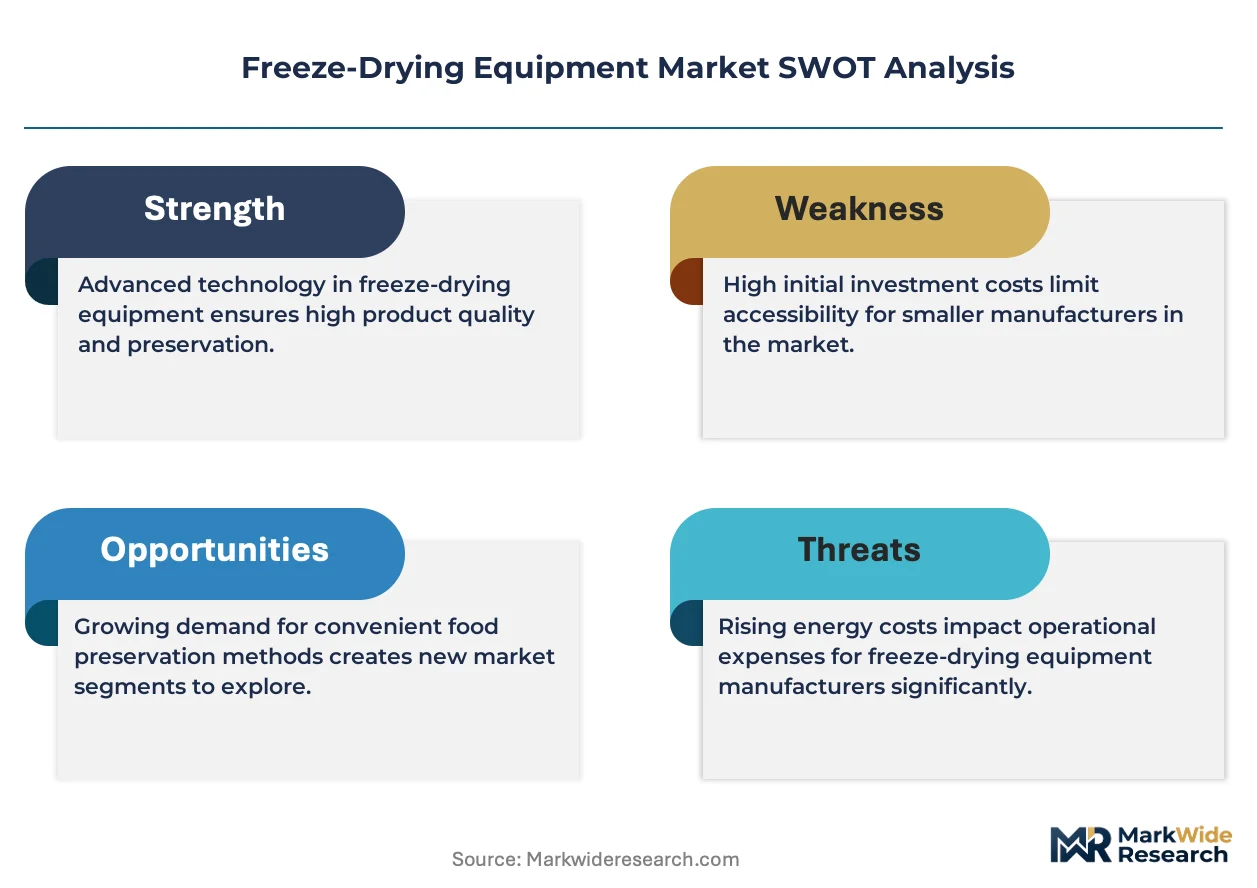
FDA current good manufacturing practice enforcement and EMA Annex 1 revisions on sterile manufacturing compel equipment vendors to integrate isolator technology and real-time release testing capabilities. The EU Green Deal's energy efficiency directives are reshaping refrigeration system specifications, pushing adoption of natural refrigerants and heat recovery architectures. Stakeholders must monitor how regulatory divergence between FDA process analytical technology guidance and China's NMPA digital validation standards fragments equipment qualification protocols across multi-site manufacturing networks.
Market Dynamics
Biologics manufacturers are consolidating lyophilization capacity around continuous processing architectures as batch-to-batch variability becomes economically unsustainable for temperature-sensitive therapeutics.
Growth Catalysts
- FDA Sterile Drug Guidance:The agency's updated manufacturing enforcement compels North American facilities to replace legacy tray dryers with validated isolator-integrated systems.
- mRNA Platform Expansion:Vaccine and gene therapy developers are scaling dedicated freeze-dry capacity to stabilize lipid nanoparticle formulations for ambient distribution.
- Precision Engineering Clusters:German CDMO hubs are attracting equipment investment through integrated validation protocols that compress qualification timelines.
Market Restraints
- Refrigerant Supply Concentration:EU F-Gas Regulation phase-downs have tightened availability of hydrofluorocarbon working fluids, forcing redesign of compressor architectures.
- Validation Cost Burden:FDA process analytical technology requirements extend commissioning cycles by 8-14 months for multi-chamber production trains.
- Skilled Technician Scarcity:Vacuum system specialists and thermal validation engineers command premium wages in Boston-Cambridge and Basel biotech corridors.
Strategic Opportunities
- Cell and Gene Therapy CDMOs:Autologous therapy manufacturers in the US and Germany lack captive lyophilization, creating third-party service demand.
- Natural Refrigerant Transition:EU Green Deal efficiency mandates are accelerating heat recovery system adoption as a competitive differentiator.
- Real-Time Release Testing Integration:EMA Annex 1 revisions on sterile manufacturing reward vendors embedding PAT sensors for parametric release.
Industry Challenges
- Legacy Control System Migration:Pharmaceutical facilities face integration friction when connecting 1990s-era freeze-dryers to modern distributed control architectures.
- Multi-Site Qualification Divergence:FDA digital validation standards and China's NMPA data integrity requirements fragment equipment protocols across transnational manufacturing networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freeze-Drying Equipment Market |
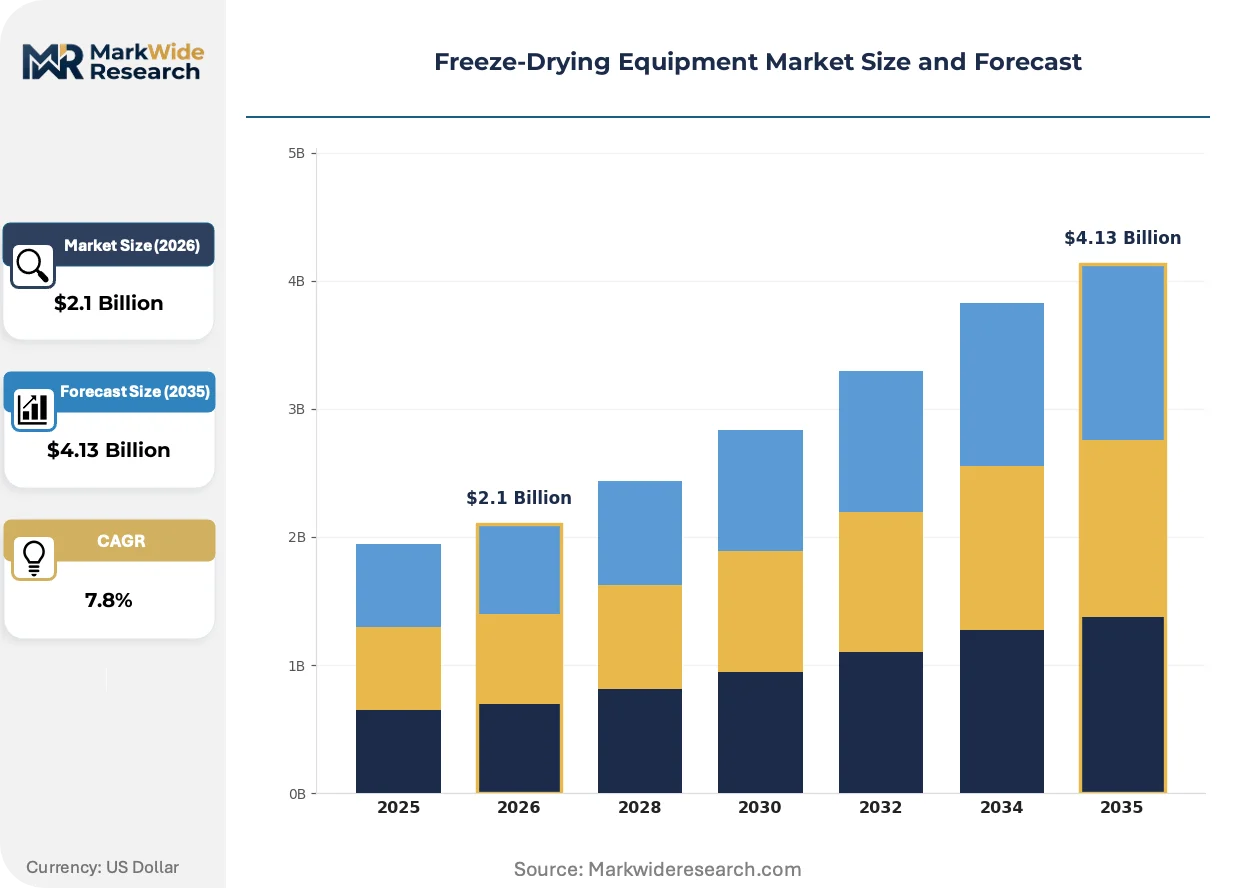
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tray Dryers, Batch Dryers, Continuous Dryers, Pilot Scale Dryers Technology: Freeze-Drying, Vacuum Drying, Sublimation, Direct Sublimation End User: Pharmaceuticals, Food & Beverages, Biotechnology, Research Institutions Application: Food Preservation, Pharmaceutical Manufacturing, Chemical Processing, Biological Samples |
| Companies Covered | GEA Group Aktiengesellschaft, Martin Christ Gefriertrocknungsanlagen GmbH, Azbil Corporation, Tofflon Science and Technology Group Co., Ltd., Labconco, Millrock Technology Inc., Cuddon Freeze Dry, SP Industries, Inc., Optima Packaging Group GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freeze-Drying Equipment Market Strategic Shifts & Innovations
Equipment architectures are splitting between high-throughput continuous systems for commercial biologics and flexible single-chamber units for clinical-stage programs. This divergence is compressing the middle tier of standardized batch equipment.
Continuous freeze-drying technology is bifurcating the installed base. Rotary and linear continuous dryers sublimate product in motion rather than static trays, cutting cycle times by half. Large molecule manufacturers in Denmark and Switzerland are piloting these systems for blockbuster biologics. The technology is bifurcating vendor portfolios into batch-legacy service lines and continuous-native development programs.
EMA Annex 1 revisions on sterile manufacturing are mandating isolator-barrier integration for all new lyophilizer installations. The regulation requires closed systems for aseptic processing, effectively banning open-manipulation tray loading. German and Irish CDMO facilities are retrofitting existing chambers with restricted access barrier systems to avoid complete replacement.
Service contract unbundling is altering vendor-customer relationships. Biopharmaceutical procurement teams are separating equipment purchase from validation, maintenance, and spare parts agreements. This pattern is most pronounced among emerging biotechs in the San Francisco Bay Area and Cambridge, Massachusetts, where capital constraints favor operational expenditure models over full lifecycle commitments.
Freeze-Drying Equipment Market Segmentation
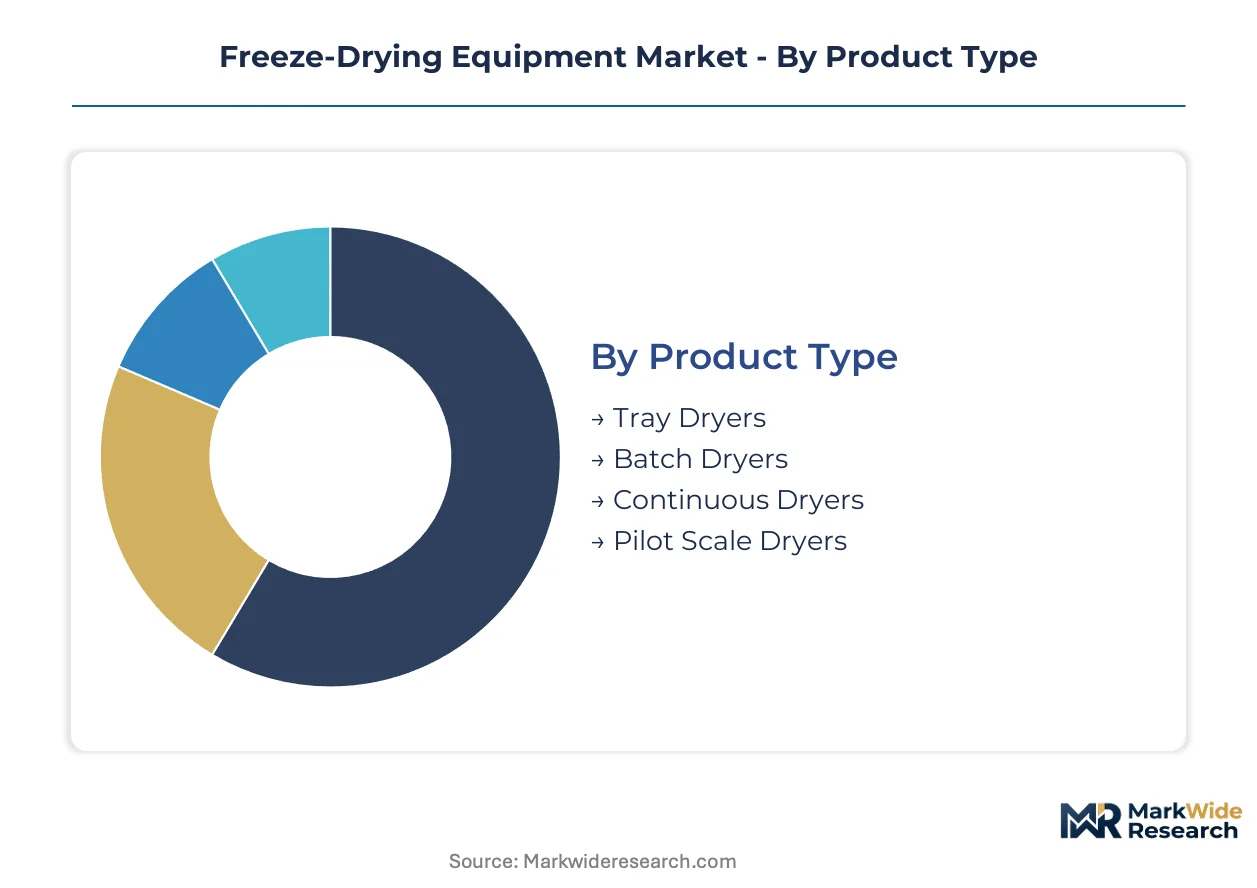
Freeze-drying equipment purchasing splits sharply between validated pharmaceutical systems and cost-optimized industrial units. Equipment specification divergences create distinct margin pools that vendors must navigate through separate sales channels and service architectures.
Product Type:
Continuous processing architectures are displacing legacy batch formats as biologics manufacturers eliminate cycle-time variability from temperature-sensitive production.
- Tray Dryers:Static shelf configurations freeze product in place before applying vacuum and controlled heat for sublimation. German precision engineering clusters in Bavaria and Baden-Württemberg sustain replacement demand as FDA sterile drug guidance forces isolator retrofits on existing installations.
- Continuous Dryers:Rotary and linear configurations move product through temperature and pressure zones without batch boundaries. Danish and Swiss large-molecule manufacturers pilot these systems for blockbuster biologics where halving cycle time justifies capital intensity.
- Batch Dryers:Chamber-based systems process discrete loads with complete environmental isolation between cycles.
- Pilot Scale Dryers:Single-chamber units bridge laboratory development and commercial validation.
Tray dryers retain volume leadership; continuous dryers hold the steepest expansion curve.
Technology:
Cost tiers separate premium lyophilization from commodity vacuum drying as end-users match thermal protection requirements to product value.
- Freeze-Drying:Triple-point manipulation preserves protein structure through controlled ice crystal formation and sublimation at shelf temperatures between -50°C and +60°C. Pharmaceutical manufacturing commands the deepest margin pools due to FDA and EMA validation requirements that extend equipment lifecycle value through aftermarket service contracts.
- Vacuum Drying:Pressure reduction accelerates moisture removal without freezing, sacrificing bioactivity preservation for throughput economics.
- Sublimation:Solid-to-gas phase transition eliminates liquid water contact with heat-sensitive materials.
- Direct Sublimation:Surface freezing enables rapid processing of thin-layer formulations.
Freeze-drying dominates value capture; vacuum drying serves volume applications where thermal damage tolerance permits.
End User:
Customer type determines procurement patterns, with contract manufacturers separating equipment purchase from validation agreements while captive biopharma favors bundled lifecycle contracts.
- Pharmaceuticals:Sterile drug manufacturers deploy isolator-integrated systems under FDA current good manufacturing practice enforcement. Boston-Cambridge and Basel biotech corridors concentrate skilled technician demand for vacuum system specialists and thermal validation engineers.
- Biotechnology:Cell and gene therapy developers lack captive lyophilization capacity, creating third-party service demand.
- Food & Beverages:Nutraceutical and prepared meal producers optimize for energy efficiency under EU Green Deal directives.
- Research Institutions:Academic and government laboratories prioritize flexible single-chamber units for diverse sample portfolios.
Pharmaceuticals anchor revenue concentration; biotechnology is climbing the fastest as autologous therapy manufacturing scales.
Application:
Application maturity splits between established food preservation and emerging pharmaceutical manufacturing where regulatory validation creates sustainable competitive moats.
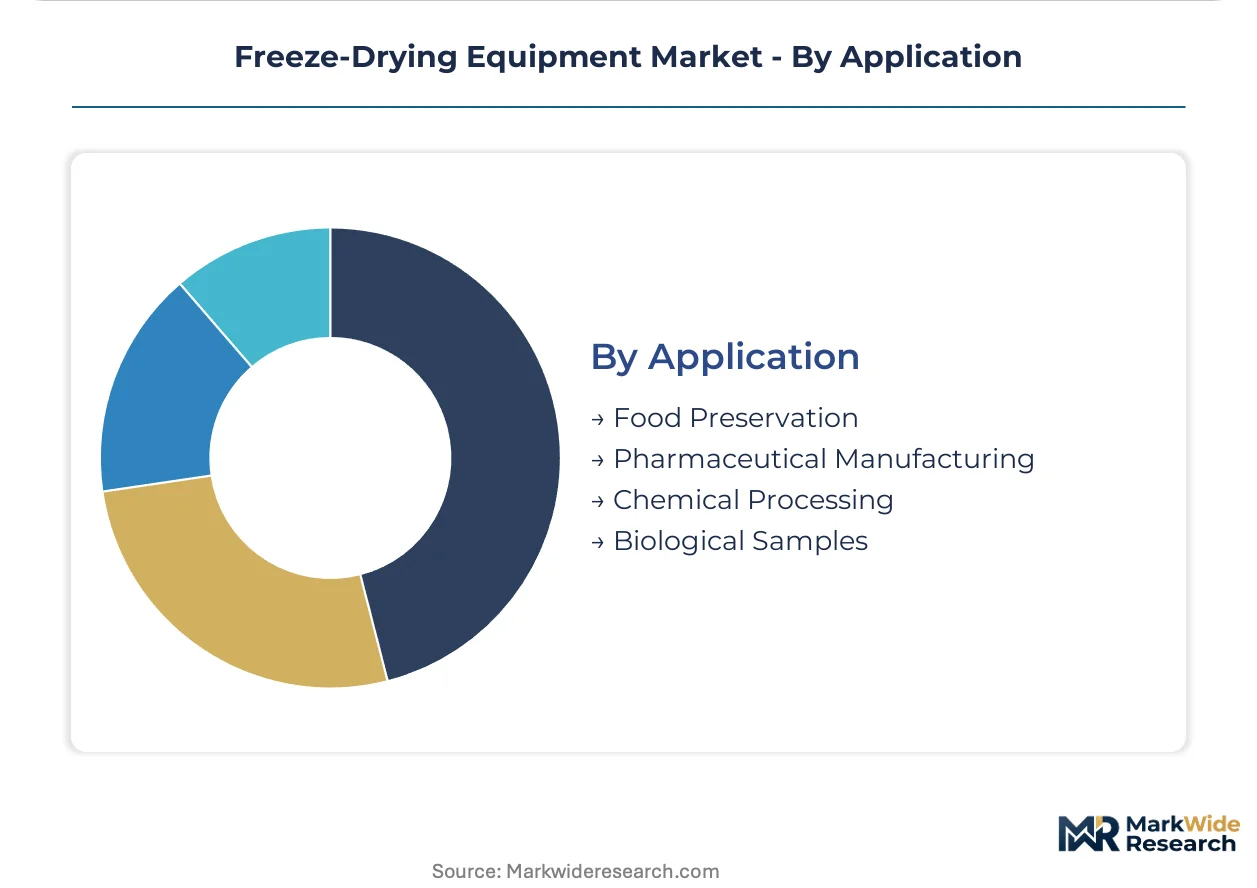
- Pharmaceutical Manufacturing:Sterile processing of parenteral biologics requires closed-system isolator integration under EMA Annex 1 revisions. mRNA vaccine and gene therapy developers scale dedicated freeze-dry capacity to stabilize lipid nanoparticle formulations for ambient distribution.
- Food Preservation:Coffee, fruits, and emergency rations drive installed base renewal with less stringent qualification protocols.
- Biological Samples:Cell banks, tissue archives, and diagnostic reagents require ultra-low temperature protocols.
- Chemical Processing:Catalyst and intermediate drying tolerates wider process parameter variation.
Food preservation retains installed base scale; pharmaceutical manufacturing commands expanding share of new equipment value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters export isolator-integrated lyophilizers to North American biopharma facilities, while Chinese equipment manufacturers supply cost-optimized batch systems across Southeast Asian contract manufacturing networks.
United States
FDA sterile drug guidance and mRNA vaccine stabilization needs drive equipment replacement cycles. The agency's current good manufacturing practice enforcement compels Boston-Cambridge biotechs to retrofit legacy tray dryers with barrier isolation systems. Greater Boston anchors skilled technician demand for vacuum system specialists and thermal validation engineers.
Germany
Precision engineering clusters in Bavaria and Baden-Württemberg dominate European validation protocol development. EU F-Gas Regulation phase-downs force compressor architecture redesigns while Green Deal efficiency mandates accelerate heat recovery system adoption. Bavarian CDMO hubs attract investment through integrated qualification timelines that compress commissioning cycles.
China
Domestic biopharma expansion and NMPA digital validation standards reshape procurement patterns. The national medical products regulator's data integrity requirements fragment equipment protocols across transnational manufacturing networks. Yangtze River Delta contract manufacturers source integrated freeze-dry and fill-finish lines from local equipment fabricators.
Switzerland
Large-molecule manufacturers pilot continuous processing architectures for blockbuster biologics. Swissmedic oversight of sterile manufacturing aligns with EMA Annex 1 isolator-barrier mandates. Basel biotech corridors concentrate demand for thermal validation engineers commanding premium wages.
India
CDMO capacity expansion for export-oriented biologics creates third-party lyophilization service demand. CDSCO oversight of sterile drug manufacturing compels facility upgrades among domestic manufacturers. Maharashtra and Gujarat pharmaceutical clusters invest in pilot-scale dryers to bridge laboratory development and commercial validation.
Freeze-Drying Equipment Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with pharmaceutical-grade portfolios alongside specialized freeze-drying equipment fabricators. Market structure concentrates around three strategic archetypes: precision engineering specialists with integrated validation capabilities, scale-driven manufacturers of cost-optimized batch systems, and laboratory-to-production transition specialists serving emerging biotechs. Dominant competitive moves include geographic expansion through regional sales offices and technology licensing partnerships for continuous processing architectures.
Among Germany-based precision engineering groups, GEA Group Aktiengesellschaft and Martin Christ Gefriertrocknungsanlagen GmbH exemplify the validation-integrated tier, while Tofflon Science and Technology Group Co., Ltd. anchors Chinese supply of integrated production lines. SP Industries, Inc. occupies a position within the laboratory-scale and pilot-system specialist segment that sustains R&D-to-commercial pathways.
| Leading Market Players |
|---|
| GEA Group Aktiengesellschaft |
| Martin Christ Gefriertrocknungsanlagen GmbH |
| Azbil Corporation |
| Tofflon Science and Technology Group Co., Ltd. |
| Labconco |
| Millrock Technology Inc. |
| Cuddon Freeze Dry |
| SP Industries, Inc. |
| Optima Packaging Group GmbH |
| Others |
Cost & Logistics Intelligence
Eighteen-month lead times for isolator-integrated lyophilizers concentrate pricing power with German precision engineering clusters, while compressed commissioning cycles at Bavarian CDMOs feed back into premium service bundling that sustains margin pools against Asian cost competition.
Pricing Analysis
Batch-legacy versus continuous-native equipment generations command a three-tier pricing structure across premium isolator-integrated, standard validated batch, and economy non-pharmaceutical tiers. Price differentiation hinges on FDA 21 CFR Part 11 compliance tier and aftermarket service contract depth, with Boston-Cambridge biotechs showing highest sensitivity to capital expenditure timing. Pricing pressure stems from Chinese manufacturers penetrating Southeast Asian contract manufacturing networks with cost-optimized tray configurations. Pharmaceutical-grade systems resist erosion through validation protocol stickiness that locks buyers into lifecycle service relationships.
Supply Chain Analysis
Inventory compression to ninety-day cycles for vacuum pump assemblies reflects refrigerant supply tightening under EU F-Gas Regulation phase-downs. Manufacturing concentrates in Germany, China, and Switzerland, with compressor architectures drawing from Japanese precision component suppliers and Italian isolator fabrication specialists. Single-source vulnerability sits with hydrofluorocarbon working fluid availability as regulatory restrictions tighten import pathways. Distribution runs through regional validation-integrated service hubs rather than direct equipment-only transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freeze-drying equipment markets approach a platform-economics inflection where continuous processing architectures and real-time release testing interoperability reshape vendor-customer lock-in dynamics around data integration rather than hardware specification alone.
For Market Incumbents: Compound isolator-integrated validation capabilities through backward integration into PAT sensor development, defending against modular continuous dryer entrants from Danish and Swiss large-molecule manufacturing ecosystems. Add captive service capacity in Boston-Cambridge and Basel corridors where skilled technician scarcity extends commissioning premiums. For New Entrants and Emerging Players: Anchor in cell and gene therapy CDMO white space where autologous therapy manufacturers lack captive lyophilization capacity, targeting third-party service demand with flexible single-chamber pilot units. Pursue regulatory-fast-track positioning through FDA digital validation guidance alignment. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because sterile manufacturing enforcement intensifies equipment lifecycle value through aftermarket service contracts that compound recurring revenue visibility. Target acquisition profiles center on validation-integrated regional specialists with isolator retrofit capabilities. Monitor EMA Annex 1 enforcement variance across German and Irish CDMO facilities as inflection signal for isolator-barrier retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Retrofit Program | EMA Annex 1 compliance mandates closed-system upgrades across existing tray dryer installations in European CDMO facilities. |
| Continuous Processing Scale-Up | Rotary and linear dryer pilots at Danish biologics manufacturers validate cycle-time compression for blockbuster production. |
| PAT Sensor Integration | FDA process analytical technology guidance rewards embedded sensors enabling parametric release for sterile drug manufacturing. |
| Natural Refrigerant Transition | EU Green Deal efficiency directives accelerate heat recovery system adoption as competitive differentiation in compressor architectures. |
| Service Contract Unbundling | San Francisco Bay Area biotech procurement teams separate equipment purchase from validation agreements favoring operational expenditure models. |
Research Approach
Initial hypotheses were tested against primary input from lyophilization engineering directors, pharmaceutical manufacturing executives, regulatory affairs specialists, and CDMO procurement leads, and refined through secondary validation against FDA guidance documents, EMA Annex 1 revisions, EU F-Gas Regulation filings, and trade customs data for refrigeration compressor imports. Bottom-up equipment shipment analysis triangulated with top-down pharmaceutical capital expenditure disclosures.
Variance decomposition across product type, technology tier, end-user segment, and application maturity shaped the analytical framework over the projection horizon. Modeled dimensions included isolator integration level, continuous versus batch architecture, and regional regulatory cluster stringency. CAGRs derived from segmented growth rate reconciliation against aggregate market expansion validated through cross-reference to biologics manufacturing capacity announcements and sterile drug pipeline databases.
Decision-makers should treat outputs as directional under assumptions of sustained FDA sterile drug guidance enforcement and EU Green Deal refrigerant phase-down adherence; material deviation in regulatory implementation timelines or mRNA platform demand would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Glass Processing Equipment Market
Food Processing Equipment
Cereal Rolling Machine Market
Food Processing Equipment
Global Food Blenders and Mixers Market
Food Processing Equipment
Granular Ice Machine Market
Food Processing Equipment
Portioning Machines Market
Food Processing Equipment
Brewery Equipment Market
Food Processing Equipment
Potato Processing Market
Food Processing Equipment
Steam Blanching Equipment Market
Food Processing Equipment
Global Shawarma Machines Market
Food Processing Equipment
Industrial Planetary Mixers Market
Food Processing Equipment
Dehydrators Market
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Micro Winery Equipment Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
Food Disinfection Equipment Market
Food Processing Equipment
Global Food Processing Market