
 Nutraceutical Supplements Market | 2026-2036
Nutraceutical Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Nutraceutical Supplements Market Analytics
Multi-source raw material procurement is broadening across the nutraceutical supplements industry as brands reduce dependency on single-origin botanical suppliers. Nestlé leverages captive ingredient networks spanning multiple continents to secure supply continuity. BASF anchors its position through in-house synthesis of vitamins and carotenoids at scale. Glanbia PLC specializes in dairy-derived protein isolates for the sports nutrition channel, competing against commodity-grade alternatives.
Nutraceutical supplements encompass bioactive compounds, vitamins, minerals, probiotics, and botanical extracts formulated for physiological benefit beyond basic nutrition, typically manufactured via spray-drying, microencapsulation, or fermentation to preserve potency through shelf life. These products serve preventive health, performance optimization, and condition-specific therapeutic support across consumer and clinical channels. Probiotics and herbal extracts command premium margin pools as clinical validation deepens prescriber confidence in non-pharmaceutical interventions. The adult end-user segment dominates volume, while athlete-targeted powders and liquids capture disproportionate value per unit through performance-positioning. Immune support applications sustain baseline demand cyclicality, whereas digestive health formulations build recurring purchase patterns through gut microbiome education.
The FDA's NDI notification requirements and cGMP enforcement shape product development timelines and capital barriers for US market entrants, while the EFSA health claims framework constrains permissible marketing language across European jurisdictions. FSSAI fortification standards and BIS quality benchmarks in India create compliance complexity for multinational portfolios seeking emerging-market penetration. Stakeholders must monitor evolving substantiation thresholds as regulators tighten the evidentiary burden for structure-function claims.
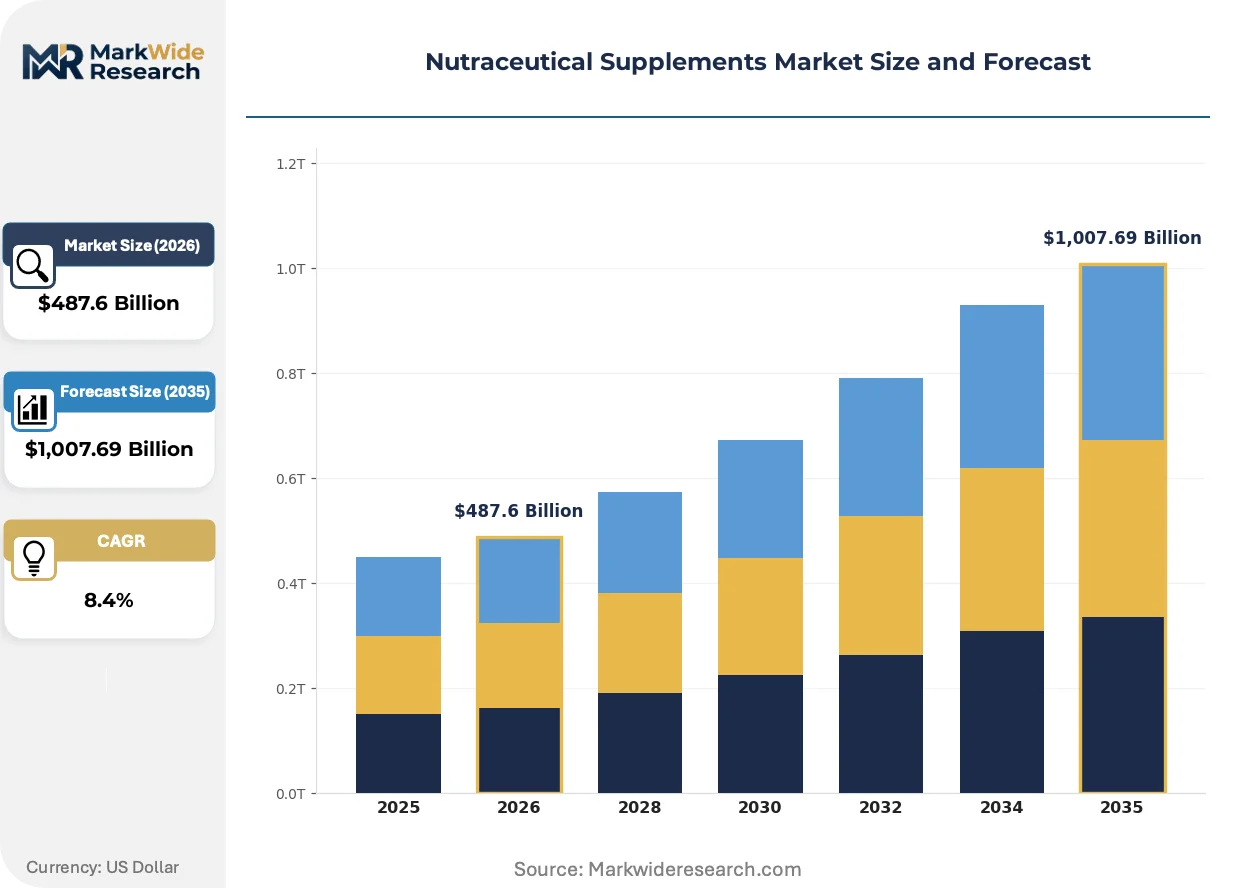
Market Dynamics
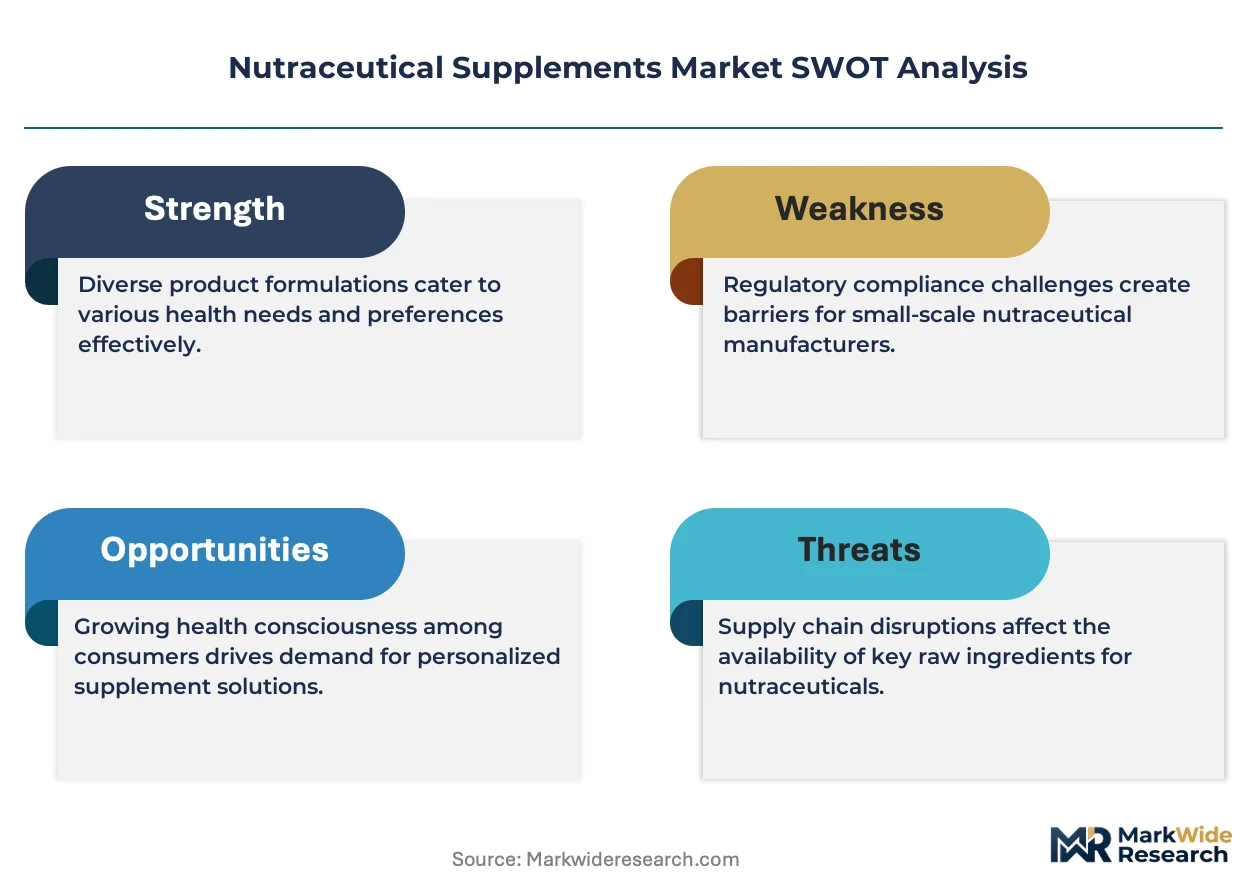
Regulatory fragmentation across FDA NDI notifications, EFSA health claims frameworks, and FSSAI fortification standards is forcing brands to maintain parallel compliance infrastructures, raising capital barriers and extending formulation-to-shelf timelines by 18-24 months for multinational entrants.
Growth Catalysts
- EFSA Article 13.1 health claims:Approved probiotic and botanical substantiations enable prescriber-channel penetration in European markets, shifting clinical confidence toward non-pharmaceutical interventions.
- Sports nutrition end-use expansion:Athlete-targeted powders and liquids capture premium value per unit through performance positioning, with protein isolates and nootropics driving repeat purchase velocity.
- China TCM-informed consumption:Traditional Chinese Medicine heritage anchors premium positioning for herbal extracts, with domestic brands leveraging cultural authenticity against Western entrants.
Market Restraints
- FDA NDI notification timelines:New Dietary Ingredient pre-market submissions extend development cycles and freeze capital in pending approvals, disadvantaging smaller formulators against established players with dedicated regulatory affairs teams.
- Single-origin botanical concentration:Dependency on Indian and Chinese raw material clusters exposes supply continuity to climate volatility, geopolitical friction, and export restriction risk.
- Structure-function claim substantiation costs:Randomized controlled trial requirements for immune and digestive health positioning compress margins for clinical-grade formulations.
Strategic Opportunities
- India FSSAI fortification mandates:Government-mandated micronutrient enrichment in staple foods creates institutional procurement channels for vitamin premix suppliers.
- Personalized nutrition convergence:At-home microbiome testing combined with AI-driven supplement matching enables subscription-based recurring revenue models.
- Direct-to-clinic distribution:Bypassing retail pharmacy shelves through practitioner-exclusive lines captures higher margins and builds prescriber loyalty.
Industry Challenges
- Phytochemical standardization expertise:Scarcity of analytical chemists capable of validating marker compound consistency across harvest batches constrains scale-up of botanical-heavy portfolios.
- cGMP facility capex intensity:Spray-drying and microencapsulation equipment for moisture-sensitive actives demands seven-figure capital deployment with 4-6 year payback horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutraceutical Supplements Market |
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,007.69 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Probiotics, Herbal Extracts Delivery Mode: Tablets, Capsules, Powders, Liquid End User: Adults, Athletes, Seniors, Pregnant Women Application: Weight Management, Immune Support, Digestive Health, Skin Care |
| Companies Covered | Nestlé, Amway Corp., Herbalife Nutrition Ltd., BASF, ADM, Glanbia PLC, Danone, General Mills Inc., Yakult Honsha Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutraceutical Supplements Market Evolving Landscape
Microbiome science and fermentation-derived actives are compressing the boundary between food and pharmaceutical-grade efficacy, while digital health integration enables real-time biomarker feedback loops that reshape dosing protocols and subscription retention.
Fermentation-based synthesis of rare bioactives is decentralizing production economics for cannabinoids, astaxanthin, and specialized omega-3s. Biotech entrants in Singapore and the Netherlands are commissioning contract manufacturing capacity at 40% lower capital intensity than extraction-based alternatives. This technology is decentralizing supply away from agricultural harvest cycles and geographic climate dependency toward controlled bioreactor environments.
EFSA's tightening evidentiary standards for Article 13.5 proprietary health claims are compressing permissible marketing language for novel ingredients. Brands now commission human intervention studies costing €500K-€2M per claim, shifting competitive advantage toward firms with captive clinical research infrastructure. Probiotic strains with published trial data command 35-60% price premiums over commodity alternatives in German and French pharmacy channels.
Practitioner-channel purchasing is displacing retail self-selection for condition-specific formulations. Functional medicine clinics in the US and integrative health centers in Germany now source 60-70% of supplement volumes through professional-exclusive lines with dosing protocols, compressing mass-market brand relevance. This behavioral pivot is most visible in autoimmune and metabolic health categories where prescriber guidance overrides consumer price sensitivity.
Nutraceutical Supplements Market Segmentation
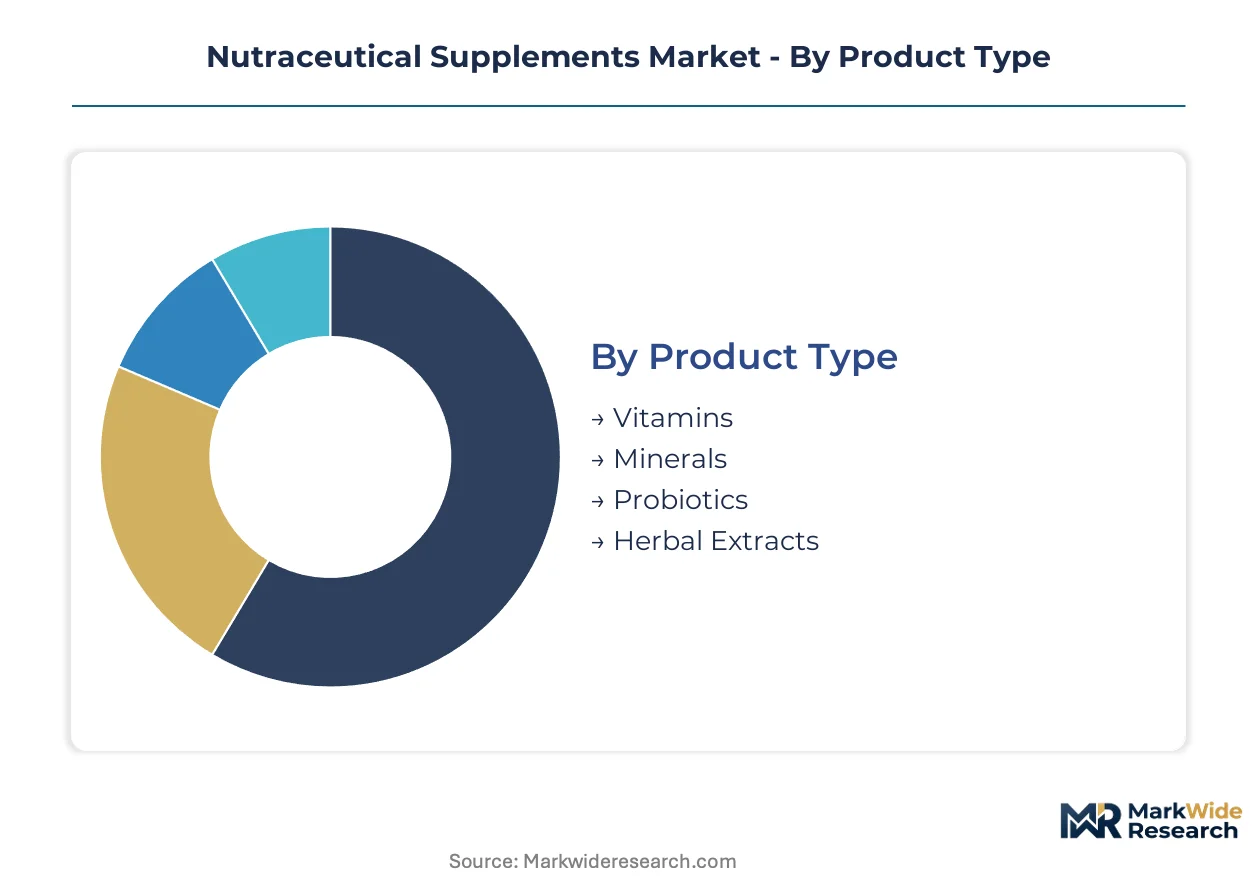
Nutraceutical formulations diverge sharply across consumption contexts, with delivery mechanics and end-user physiology dictating ingredient selection, bioavailability engineering, and regulatory pathway. Segmentation discipline separates commodity vitamin premixes from condition-specific clinical formulations commanding prescriber-channel premiums.
Product Type:
Volume concentrates in foundational micronutrients, while probiotics and botanicals capture margin through clinical substantiation and supply scarcity.
- Vitamins:Synthetic and nature-identical compounds manufactured via chemical synthesis or fermentation, standardized to USP or EP monographs. Demand clusters in India FSSAI fortification mandates and institutional procurement channels for staple food enrichment.
- Probiotics:Live microbial cultures delivered in CFU-counted doses, requiring cold-chain integrity and strain-specific clinical validation. German and French pharmacy channels reward published trial data with 35-60% price premiums over commodity alternatives.
- Minerals:Chelated and inorganic salt forms addressing bioavailability constraints in aging populations and geographies with soil depletion.
- Herbal Extracts:Phytochemical concentrates standardized to marker compounds, sourced predominantly from Indian and Chinese botanical clusters with climate-dependent harvest cycles.
Today's leader: Vitamins. Tomorrow's challenger: Probiotics.
Delivery Mode:
Format selection hinges on actives stability, patient compliance economics, and prescriber-channel protocol requirements.
- Capsules:Gelatin and HPMC shells accommodating moisture-sensitive powders and lipid-based actives, dominant in practitioner-exclusive lines with dosing precision requirements.
- Powders:Bulk formats enabling flexible dosing and flavor masking for sports nutrition applications, with protein isolates and nootropics driving repeat purchase velocity in athlete segments.
- Tablets:Compressed formulations offering cost efficiency at scale, constrained by disintegration time requirements for elderly consumers with reduced gastric acid.
- Liquid:Emulsion and suspension formats for pediatric and geriatric populations with swallowing difficulties, demanding preservative systems and shorter shelf-life management.
Capsules dominate prescriber loyalty. Powders are climbing the fastest through sports nutrition expansion.
End User:
Age and activity level segment demand across preventive, performance, and therapeutic positioning.
- Adults:Working-age consumers seeking preventive maintenance and stress-adaptation support, representing baseline volume across mass-market retail channels.
- Athletes:Performance-optimized consumers prioritizing protein synthesis, recovery acceleration, and cognitive enhancement, accepting premium per-unit pricing for clinical-grade formulations.
- Seniors:Aging populations with malabsorption concerns and polypharmacy interactions, driving demand for bioavailable mineral chelates and condition-specific combinations.
- Pregnant Women:Preconception through lactation consumers requiring folate, DHA, and iron formulations with teratogenic safety documentation and prescriber oversight.
Adults anchor current volume. Athletes show the steepest expansion trajectory through performance-positioning premiums.
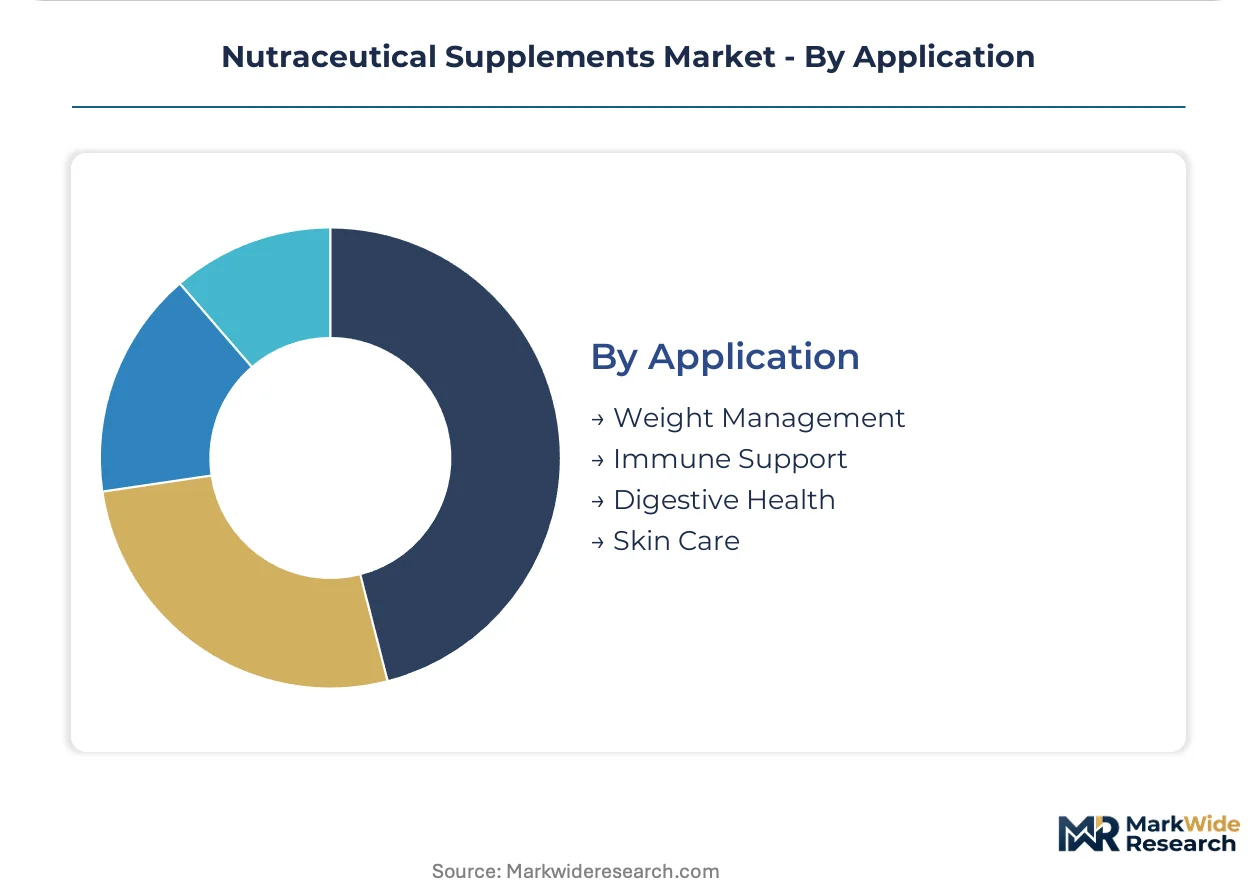
Application:
Condition-specific targeting separates clinical-grade formulations from general wellness commodities.
- Immune Support:Zinc, vitamin C, and elderberry formulations sustaining baseline demand cyclicality, constrained by structure-function claim substantiation costs for premium positioning.
- Digestive Health:Probiotic and prebiotic combinations building recurring purchase patterns through gut microbiome education and subscription model compatibility.
- Weight Management:Thermogenic and satiety-modulating actives facing regulatory scrutiny for efficacy claims and cardiovascular safety profiles.
- Skin Care:Collagen peptides, carotenoids, and polyphenols bridging ingestible and topical beauty categories, with EFSA Article 13.1 substantiations enabling prescriber-channel penetration.
Immune support defends baseline revenue. Digestive health is gaining share fastest through subscription retention mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta anchors nutraceutical manufacturing capacity, with fermentation-derived actives and botanical extraction facilities clustering around Shanghai and Suzhou. Domestic TCM-informed brands leverage cultural authenticity to command premium positioning against Western entrants.
United States
Sports nutrition powders and practitioner-exclusive capsules drive demand in the US, with athlete-targeted formulations capturing premium per-unit pricing. FDA NDI notification requirements and cGMP enforcement extend development timelines for new entrants. Manufacturing concentrates in Utah's Wasatch Front and California's Orange County corridor.
Germany
German pharmacy channels reward clinical substantiation with 35-60% price premiums for validated probiotic strains. EFSA Article 13.1 health claims frameworks constrain permissible marketing language for novel ingredients. Production clusters in Bavaria and Baden-Württemberg serve as European distribution hubs.
India
FSSAI fortification mandates for staple foods create institutional procurement channels for vitamin premix suppliers. BIS quality benchmarks and CDSCO oversight create compliance complexity for multinational portfolios. Manufacturing concentrates in Maharashtra's Mumbai-Pune belt and Gujarat's pharmaceutical corridor.
Japan
Aging demographics drive demand for bioavailable mineral chelates and condition-specific combinations for senior populations. PMDA and METI frameworks govern functional food and supplement claims with stringent substantiation requirements. Production clusters in the Kanto region around Tokyo and Saitama.
Brazil
Rising preventive health consciousness expands mass-market vitamin and probiotic consumption. ANVISA registration pathways for novel ingredients require local clinical data, favoring established players with dedicated regulatory affairs teams. Manufacturing concentrates in São Paulo state's pharmaceutical belt.
Nutraceutical Supplements Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and channel access. The vendor base spans multinational conglomerates with captive ingredient networks, mid-cap specialists in dairy-derived or fermentation-based actives, and domestic TCM-rooted brands in China. Three archetypes dominate: integrated nutrition conglomerates with backward control over supply chains, ingredient specialists commanding premium through clinical validation, and direct-selling operators with embedded consumer education infrastructure. Competitive moves concentrate on M&A for microbiome capabilities and strategic partnerships for biotech-derived actives.
Among integrated nutrition conglomerates, Nestlé and BASF exemplify archetypes of supply chain control and in-house synthesis scale respectively. Glanbia PLC occupies a position within the ingredient specialist tier, with its company name signaling focus on dairy-derived protein isolates. These three entities represent contrasting strategic postures: conglomerate diversification, chemical manufacturing scale, and category-specific depth.
| Leading Market Players |
|---|
| Nestlé |
| Amway Corp. |
| Herbalife Nutrition Ltd. |
| BASF |
| ADM |
| Glanbia PLC |
| Danone |
| General Mills Inc. |
| Yakult Honsha Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Botanical raw material costs from Indian and Chinese extraction clusters cascade through three distinct pricing tiers before reaching end consumers, with climate-driven harvest volatility compressing margins at the standard grade while premium strains with clinical validation capture insulation through prescriber-channel loyalty.
Pricing Analysis
Input-cost pass-through from fermentation-derived actives and cold-chain probiotic logistics drives pricing stratification across premium, standard, and economy tiers. Price differentiation rests on EFSA Article 13.1 substantiation status and cGMP certification tier, with validated strains commanding prescriber-channel premiums. Pricing pressure intensifies in commodity vitamin premixes as FSSAI fortification mandates standardize institutional procurement. Athlete-targeted formulations show least price sensitivity; mass-market tablet buyers exhibit highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive probiotics and expired botanical returns remain underdeveloped, creating working capital drag for direct-to-consumer operators. Raw material extraction concentrates in India and China, with fermentation capacity expanding in Singapore and the Netherlands. Supply chains draw from specialized omega-3 biomass, strain-culture banks, and phytochemical marker compounds. Single-origin botanical dependency exposes continuity to export restriction risk. Distribution runs through practitioner-exclusive lines, pharmacy channels, and athletic specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where fermentation-based manufacturing in Singapore and the Netherlands undercuts extraction-dependent production in climate-vulnerable botanical clusters by 40% on capital intensity.
For Market Incumbents: Cement supply continuity through backward integration into strain-culture banks and captive fermentation capacity, insulating against Indian and Chinese export friction. Fortify prescriber-channel relationships with dosing protocol services to defend against biotech entrants with AI-driven personalization platforms.
For New Entrants and Emerging Players: Begin with microbiome testing subscription models that lock in recurring revenue before expanding into formulated products. White-space concentrates in at-home gut health diagnostics and practitioner-exclusive autoimmune formulations. Go-to-market leverage: direct-to-clinic distribution bypassing retail pharmacy margin stacking.
For Investors and Strategic Acquirers: Consolidation pressure builds where clinical validation infrastructure separates scalable players from commodity formulators unable to fund EFSA Article 13.5 study costs. Long-term viability favors firms with captive trial data and strain IP. Target acquisition archetype: mid-cap probiotics specialists with published human studies. Signal to watch: ANVISA registration pathway simplification in Brazil triggering emerging-market entry waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain-Culture Banks | Captive probiotic IP reduces dependency on external culture suppliers and accelerates NDI timelines. |
| EFSA Article 13.5 Health Claim Investment | Published human trials unlock 35-60% pharmacy channel premiums in German and French markets. |
| Direct-to-Clinic Distribution Launch | Bypassing retail shelves captures prescriber loyalty and protects margin from mass-market erosion. |
| AI-Driven Personalization Platform | Microbiome test-to-supplement matching enables subscription retention and displaces generic formulations. |
| Fermentation Capacity Expansion | Controlled bioreactor environments decentralize supply from agricultural harvest cycles and climate risk. |
Research Methodology
Direct dialogue with regulatory affairs directors, fermentation facility operators, pharmacy procurement managers, and functional medicine practitioners grounded qualitative findings, cross-referenced against FDA NDI notification databases, EFSA health claim registers, FSSAI fortification circulars, and customs trade flows for botanical extracts. Bottom-up strain-level volume estimates and top-down category spend analysis were triangulated to reconcile discrepancies.
Segment-level outputs across product type, delivery mode, end user, and application dimensions were generated through the projection horizon, with CAGRs derived from historical growth patterning and regulatory inflection timing. Model inputs incorporated NDI approval velocity, EFSA substantiation success rates, and prescriber-channel penetration curves by geography.
Several conditions sit outside the modeled scope, including abrupt FDA cGMP enforcement escalations, Chinese export license suspensions for botanicals, and breakthrough synthetic biology alternatives displacing fermentation economics. Forecasts reflect documented assumptions about regulatory stability and climate patterns. Practitioners should monitor NDI backlog clearance rates and EFSA Article 13.5 rejection trends for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
Food Grade Beta-Alanine Market
Nutritional Supplements
Tea Tree Oil Market
Nutritional Supplements
GLP-1 Diet Food Market
Nutritional Supplements
Postbiotic Supplements Market
Nutritional Supplements
Red Ginseng Market
Nutritional Supplements
Japan Whey Protein Market
Nutritional Supplements
Direct Fed Microbials Market
Nutritional Supplements
Europe Collagen Supplements Market
Nutritional Supplements
Europe Nutrition and Supplements Market
Nutritional Supplements
Folate Market
Nutritional Supplements
Feed Prebiotics Market
Nutritional Supplements
Middle East Protein Market
Nutritional Supplements
Throat Lozenges Market
Nutritional Supplements
North America Insoluble Dietary Fibers Market
Nutritional Supplements
Krill Oil Market