
 Steam Blanching Equipment Market | 2026-2036
Steam Blanching Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Blanching Equipment Market Insights
Frozen vegetable processing is realigning capital allocation toward high-throughput steam blanching systems that reduce water usage and thermal degradation. Laitram Machinery leverages its seafood and vegetable processing heritage to anchor North American installed base renewal cycles. OctoFrost AB competes on thermal efficiency metrics and energy recovery architecture in European greenfield projects.
Steam blanching equipment applies saturated steam at temperatures between 85°C and 100°C to inactivate enzymes, reduce microbial load, and fix color prior to freezing or dehydration, with retention times typically spanning 30 to 180 seconds depending on product density and geometry. Continuous systems command the largest share of replacement demand among food processors running multi-shift operations, while countertop units occupy the catering and restaurant channel where space constraints and batch flexibility outweigh throughput requirements. Automatic operating modes are displacing manual and semi-automatic configurations in new industrial installations as labor availability tightens and consistency specifications harden.
Food safety frameworks including FDA regulations for low-acid canned foods, EU hygiene package directives enforced by EFSA-aligned national agencies, and China's GB standards for food machinery shape equipment design, material certification, and export market access documentation. REACH compliance for belt coatings and stainless steel grade specifications add compliance cost layers that favor established suppliers with in-house metallurgy and chemical certification capabilities. Buyers must weigh total cost of ownership against throughput guarantees when specifying hybrid operating modes that promise labor savings without full automation premiums.
Market Dynamics
Capital allocation among frozen food processors is pivoting toward waterless thermal processing as clean-label mandates harden and energy costs reset operational benchmarks across European and North American installed bases.
Growth Catalysts
- EU Green Deal decarbonization targets:Food processors in Germany and the Netherlands face binding Scope 3 reduction deadlines that favor steam blanching over water-intensive alternatives for vegetable preservation lines.
- Enzyme inactivation precision:Peroxidase and lipoxygenase deactivation thresholds below 95°C preserve carotenoid retention in spinach and green beans, driving specification upgrades at premium frozen vegetable packers.
- China's GB standards alignment:Export-oriented processors in Shandong and Zhejiang provinces are retrofitting lines to meet dual certification for domestic SAMR compliance and EU import requirements.
Market Restraints
- Austenitic stainless steel price volatility:Grade 316L sheet and coil inputs for chamber construction fluctuate with nickel futures, compressing margin buffers for mid-tier equipment fabricators.
- Belt coating supply concentration:PTFE-impregnated fiberglass conveyor belts for high-temperature steam environments source from a narrow base of European chemical compounders, creating single-source vulnerability.
- Water recirculation infrastructure lock-in:Existing hydro-blanching installations in legacy vegetable processing plants carry sunk costs that delay steam system conversion cycles despite operational savings.
Strategic Opportunities
- India FSSAI modernization mandates:Cold chain infrastructure investments under the PLI scheme for food processing create first-mover positioning for steam blanching suppliers targeting frozen pea and corn operations in Punjab and Haryana.
- Heat recovery integration:Condensate return and flash steam capture systems are converging with blanching line architecture to deliver energy intensity metrics that differentiate bids for ESG-linked procurement.
- Contract manufacturing channel expansion:Co-manufacturing networks serving private-label frozen vegetable brands represent an underserved specification pathway distinct from direct OEM sales.
Industry Challenges
- ASME pressure vessel certification timelines:Saturated steam systems operating above 15 psi require third-party inspection cycles that extend delivery schedules by 8-14 weeks for North American deployments.
- Legacy control system integration:Proprietary PLC architectures from 1990s-era hydro-blanching lines resist seamless handshaking with modern IoT-enabled steam temperature and dwell-time monitoring modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Blanching Equipment Market |
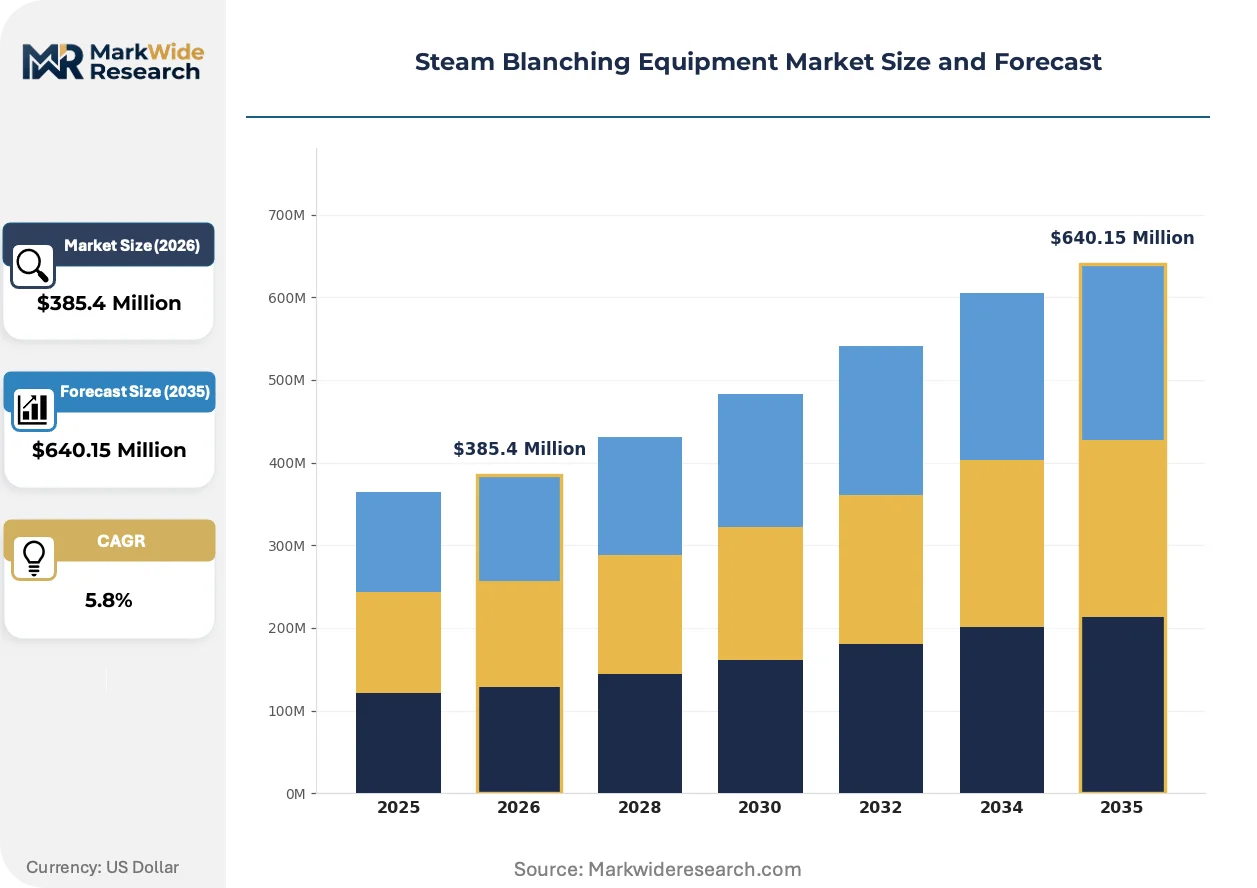
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Systems, Continuous Systems, Countertop Units, Industrial Installations End User: Food Processors, Catering Services, Restaurants, Household Users Operating Mode: Manual, Automatic, Semi-Automatic, Hybrid Application: Vegetable Processing, Fruit Processing, Seafood, Other Foods |
| Companies Covered | Laitram Machinery, OctoFrost AB, Henan Huafood Machinery Technology, Lyco Manufacturing, Cabinplant A/S, JBT Corporation, Heat and Control Inc., Bühler Group, Turatti Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Blanching Equipment Market Trends and Innovations
Thermal processing architecture is reconfiguring around closed-loop energy systems and predictive maintenance protocols that compress total cost of ownership calculations for multi-shift vegetable freezing operations.
Electromagnetic steam injection manifolds are converging with variable-frequency drive blower controls to enable real-time temperature profiling across product bed depths. Frozen broccoli and cauliflower processors in the United States are piloting these configurations to reduce over-blanching losses. The technology is converging with legacy continuous belt designs to retrofit existing footprints without greenfield construction.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of belt coating chemistries for high-temperature steam exposure. Equipment suppliers with in-house polymer certification capabilities are capturing specification advantages in EU tender processes. Frozen vegetable packers in Belgium and Denmark are prioritizing suppliers with ECHA pre-registered coating alternatives.
Specification authority is migrating from plant engineering departments to centralized procurement functions with standardized total cost of ownership models. Multi-site frozen food operators are consolidating vendor panels and demanding throughput guarantees with energy consumption ceilings. This concentration is most pronounced among North American and European processors running integrated vegetable and potato product lines.
Steam Blanching Equipment Market Segmentation
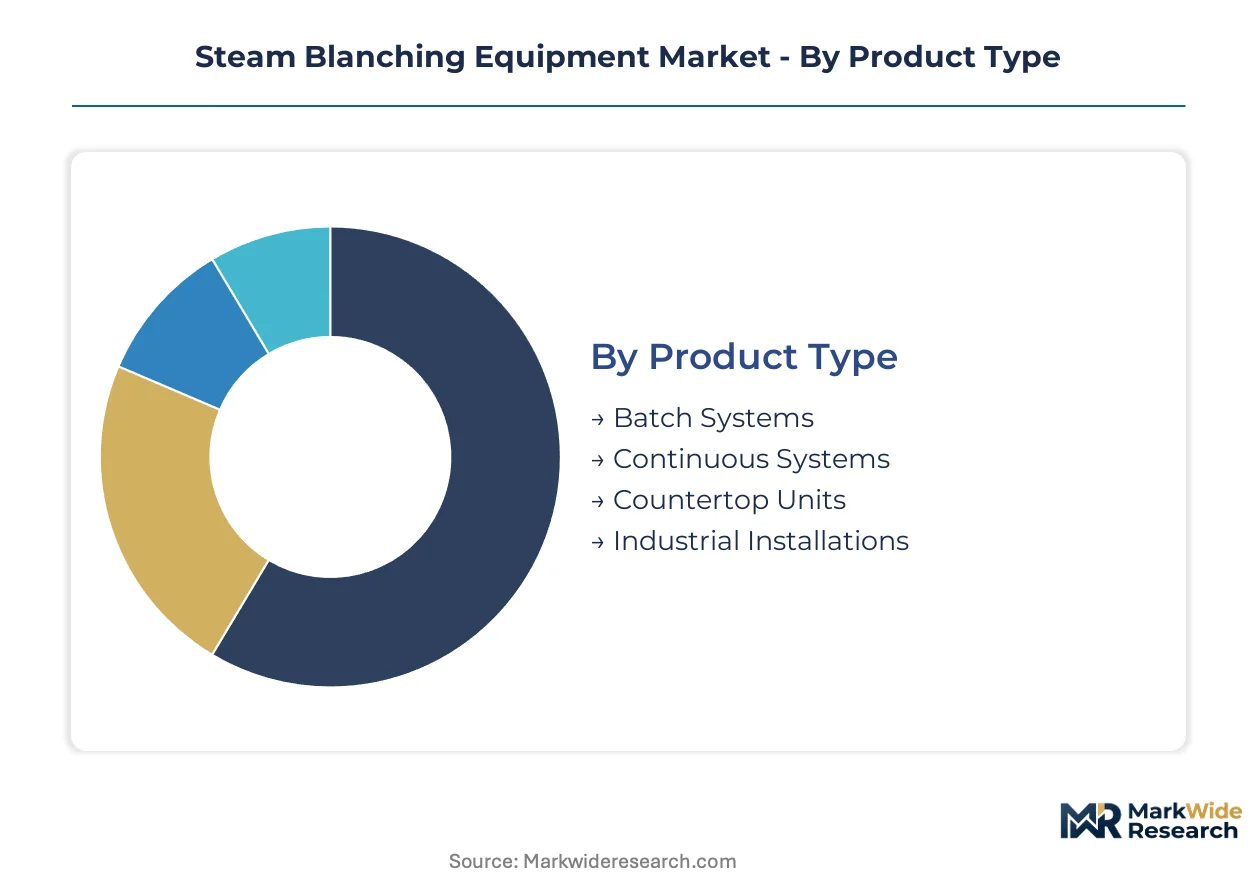
Steam blanching equipment procurement splits sharply between capital-intensive industrial lines and flexible batch units. Specification authority migrates toward total cost of ownership models that weight energy recovery, throughput guarantees, and compliance documentation across operating modes.
Product Type:
Capital intensity escalates dramatically with system scale and automation depth, separating industrial continuous lines from compact batch alternatives.
- Continuous Systems:Saturated steam tunnels with variable-frequency drive blowers and electromagnetic injection manifolds dominate multi-shift frozen vegetable operations. German and Chinese processors specify these for Scope 3 compliance under EU Green Deal timelines and domestic dual carbon goals.
- Batch Systems:Chamber-style configurations with programmable dwell-time controls serve mid-volume processors and specialty product runs. Indian frozen pea operations in Punjab deploy these under FSSAI modernization mandates where capital constraints limit continuous line adoption.
- Countertop Units:Compact steam generators with manual loading trays occupy restaurant and catering channels where floor space constraints override throughput targets.
- Industrial Installations:Integrated lines with condensate return and flash steam capture systems command premium specification for ESG-linked procurement at North American frozen food operators.
Most installed capacity flows through Continuous Systems. Expansion is steepest in Industrial Installations.
End User:
Procurement sophistication diverges between regulatory-driven food processors and price-sensitive foodservice operators.
- Food Processors:Frozen vegetable packers in Belgium and Denmark specify REACH-compliant belt coatings and ASME-certified pressure vessels for export market access. These buyers consolidate vendor panels and demand throughput guarantees with energy consumption ceilings.
- Catering Services:Contract foodservice operators prioritize batch flexibility and rapid changeover between vegetable SKUs. Space constraints and variable daily volumes favor countertop and small-batch configurations.
- Restaurants:Independent operators and regional chains source entry-level steam blanching for in-house vegetable prep, with specification authority resting with kitchen equipment distributors rather than central procurement.
- Household Users:Consumer-grade steam blanching appliances occupy a narrow niche for home preservation enthusiasts, with minimal overlap with commercial equipment supply chains.
Food Processors account for the dominant share of equipment revenue. Catering Services are climbing the fastest as co-manufacturing networks expand.
Operating Mode:
Labor availability and consistency specifications reshape automation architecture across installation scales.
- Automatic:PLC-controlled systems with IoT-enabled temperature and dwell-time monitoring displace manual configurations in new industrial builds. US broccoli and cauliflower processors pilot these for over-blanching reduction.
- Hybrid:Semi-automated loading with automated steam injection and manual unloading offers labor savings without full automation premiums. Mid-tier fabricators target this segment for margin protection.
- Manual:Operator-dependent steam valve control persists in legacy installations and developing markets where skilled technician availability limits electronic system adoption.
- Semi-Automatic:Programmable timers with manual product handling occupy intermediate positions, primarily in retrofit scenarios where legacy control system integration resists full automation upgrades.
Automatic systems carry the heaviest upfront investment. Hybrid configurations are expanding most quickly among budget-constrained processors.
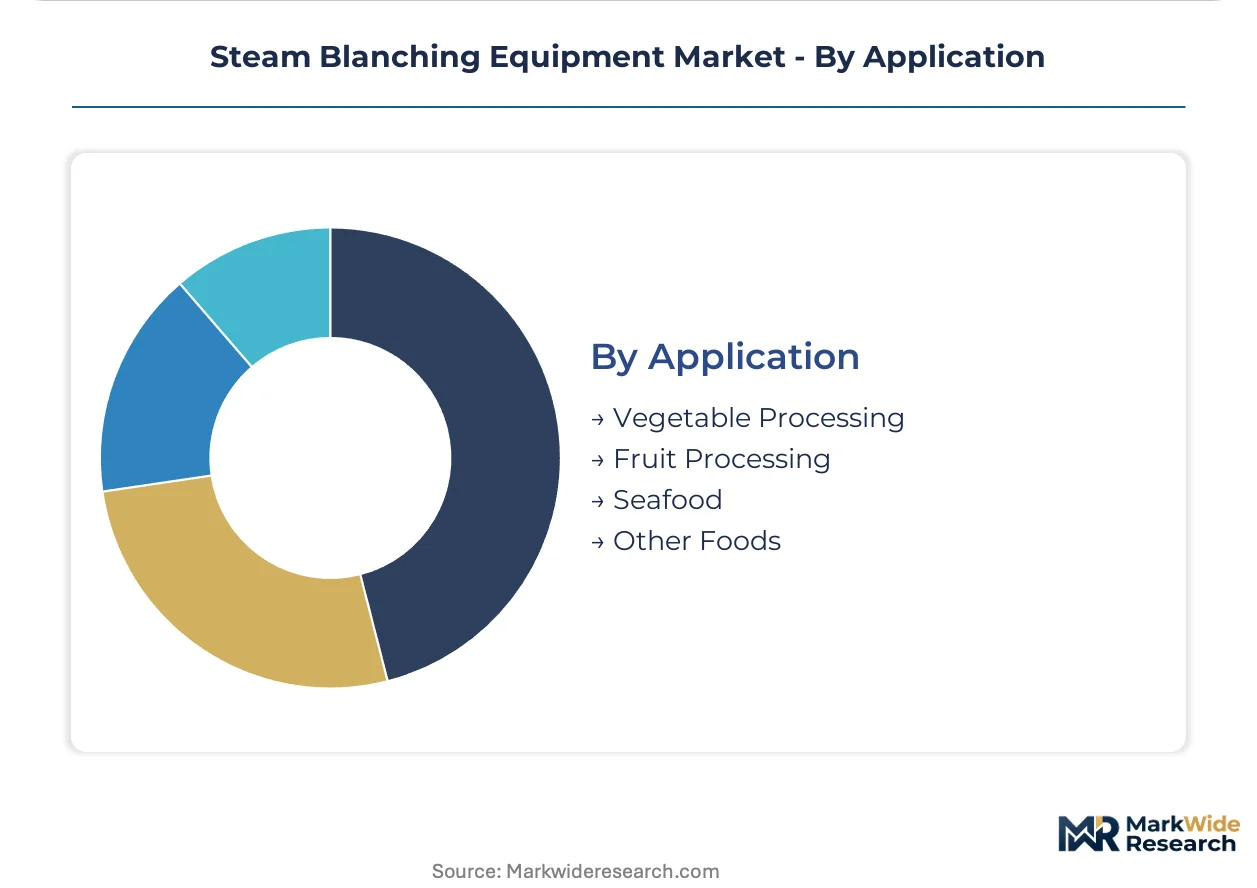
Application:
Enzyme inactivation requirements and thermal sensitivity vary substantially across product categories.
- Vegetable Processing:Peroxidase and lipoxygenase deactivation thresholds below 95°C preserve carotenoid retention in spinach and green beans. Premium frozen vegetable packers in the Netherlands and Germany drive specification upgrades for color fixation.
- Seafood:Delicate protein structures require precise temperature profiling to prevent texture degradation. Laitram Machinery leverages seafood processing heritage for cross-selling into vegetable lines.
- Fruit Processing:Pectin stability and sugar retention demands shorter dwell times than vegetables, favoring electromagnetic injection manifolds for rapid heat transfer.
- Other Foods:Niche applications including pasta and grain processing occupy limited specification bandwidth, typically served by adapted vegetable processing equipment.
Vegetable Processing anchors the installed base. Seafood applications are gaining share fastest as thermal efficiency metrics penetrate protein processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping equipment procurement as processors relocate capacity to jurisdictions with converging food safety standards but diverging carbon compliance costs. Capital flows toward countries where dual certification for export markets minimizes redundant engineering.
United States
Frozen broccoli and cauliflower processors in California's Central Valley drive specification upgrades for electromagnetic injection manifolds. FDA low-acid canned food regulations govern pressure vessel design for systems operating above 15 psi. Midwest vegetable packers in Wisconsin and Minnesota anchor replacement demand for continuous belt systems with IoT-enabled monitoring.
Germany
EU Green Deal Scope 3 reduction deadlines compress procurement timelines for steam-based preservation lines. EFSA-aligned hygiene package directives enforce stainless steel grade specifications for chamber construction. The Lower Saxony vegetable processing cluster around Hanover specifies energy recovery architecture for condensate return systems.
China
Export-oriented processors in Shandong and Zhejiang provinces retrofit lines for dual SAMR domestic compliance and EU import certification. GB standards for food machinery shape belt coating material selection and documentation protocols. Yangtze River Delta frozen vegetable operations prioritize throughput guarantees with energy consumption ceilings.
India
FSSAI modernization mandates under the PLI scheme for food processing create specification pathways for frozen pea and corn operations. Punjab and Haryana cold chain infrastructure investments favor batch systems where capital constraints limit continuous line adoption. DGFT export promotion schemes accelerate certification alignment for European market access.
Netherlands
Premium frozen vegetable packers specify REACH-compliant belt coatings and peroxidase deactivation thresholds below 95°C for carotenoid retention. ECHA pre-registered coating alternatives differentiate supplier selection in Belgian and Danish tender processes. The Flevoland agricultural cluster drives greenfield project demand for closed-loop thermal processing architecture.
Steam Blanching Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated food processors consolidating vendor panels while co-manufacturing networks fragment procurement authority. The vendor base organizes around three archetypes: heritage seafood-to-vegetable cross-sellers, thermal efficiency specialists with energy recovery portfolios, and diversified industrial conglomerates with in-house metallurgy capabilities. Dominant competitive moves include backward integration into belt coating polymer certification and strategic partnerships for IoT-enabled control system integration.
Within the heritage cross-selling tier, Laitram Machinery anchors North American installed base renewal cycles through seafood processing lineage. OctoFrost AB exemplifies the thermal efficiency specialist archetype in European greenfield specifications. Among diversified industrial fabricators, Bühler Group occupies a position spanning multiple food processing equipment categories. JBT Corporation and Heat and Control Inc. represent the integrated systems provider archetype with broad protein and vegetable processing exposure.
| Leading Market Players |
|---|
| Laitram Machinery |
| OctoFrost AB |
| Henan Huafood Machinery Technology |
| Lyco Manufacturing |
| Cabinplant A/S |
| JBT Corporation |
| Heat and Control Inc. |
| Bühler Group |
| Turatti Group |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up equipment specialists anchor pricing discipline across European and North American procurement channels, compressing distributor margins while consolidating vendor panels around throughput-guaranteed contracts. Their ownership structures favor long-term service bundling over transactional equipment sales, reshaping how mid-tier fabricators compete on total cost of ownership metrics.
Pricing Analysis
Distributor margin layers in the 15-25% range separate OEM floor pricing from landed equipment costs at frozen vegetable processors in Germany and the United States. Three-tier pricing structure across premium, standard, and economy levels stratifies by automation depth and energy recovery architecture, with ASME-certified pressure vessels commanding tier-one positioning. Cost compression in standard-tier batch systems is intensifying because mid-tier fabricators absorb stainless steel volatility rather than pass through nickel futures exposure. Contract foodservice operators exhibit highest price sensitivity due to capital constraints, while integrated frozen food multinationals prioritize energy consumption ceilings over upfront equipment cost.
Supply Chain Analysis
Workforce availability constraints in Danish and German fabrication hubs are pushing chamber construction toward Polish and Czech manufacturing satellites with skilled welder pools. Geographic supply concentrates in Germany, China, and the United States for pressure vessel fabrication, with belt coating polymer compounding anchored in Belgium and the Netherlands. Raw material dependencies center on grade 316L stainless steel sheet, PTFE-impregnated fiberglass conveyor substrates, and electromagnetic injection manifold assemblies. Single-source vulnerability in European belt coating supply creates structural risk for lead-time reliability. Distribution runs through direct OEM specification for industrial continuous lines, while batch and countertop units channel through kitchen equipment distributors and foodservice supply houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal compliance costs in Germany and the Netherlands exceed India's FSSAI modernization expenditure by multiples, creating first-mover positioning for suppliers targeting Punjab and Haryana frozen pea operations.
For Market Incumbents: Anticipate margin compression from Chinese fabricators achieving dual SAMR and EU certification alignment, and respond by deepening captive supply of REACH-compliant belt coating polymers to defend specification authority in Belgian and Danish tender processes. Backward integration into in-house metallurgy capabilities protects against grade 316L price volatility while accelerating ASME pressure vessel certification timelines. For New Entrants and Emerging Players: Begin with India's PLI scheme for food processing, where FSSAI modernization mandates and DGFT export promotion create specification pathways without entrenched incumbent relationships. Target batch system configurations for Punjab frozen pea operations where capital constraints limit continuous line adoption. Pursue contract manufacturing channel partnerships with private-label frozen vegetable brands as the primary go-to-market angle. For Investors and Strategic Acquirers: Diversified industrial conglomerates with food processing equipment portfolios are the most active acquirer in this space, seeking thermal efficiency specialists with energy recovery architecture. Long-term viability hinges on IoT-enabled control system integration capabilities and ESG-linked procurement positioning. Monitor EU ECHA pre-registration status for PFAS-free belt coating alternatives as the critical inflection signal for supplier differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Certification | In-house REACH compliance capabilities capture specification advantages in EU tender processes. |
| Heat Recovery Architecture Deployment | Condensate return systems differentiate bids for ESG-linked procurement at North American operators. |
| IoT Control System Integration | PLC-enabled temperature monitoring reduces over-blanching losses in US broccoli processing lines. |
| Dual Certification Alignment | GB standards and EU hygiene package convergence unlocks Shandong export-oriented processor demand. |
| Contract Manufacturing Channel Expansion | Co-manufacturing networks serving private-label brands fragment procurement authority away from direct OEM sales. |
Research Methodology
Coverage spans Germany, the United States, China, India, and the Netherlands, with primary inputs from each market cluster through structured interviews with plant engineers at frozen vegetable processors, procurement leads at integrated food operators, aftermarket service heads at equipment distributors, and regulatory affairs specialists at OEMs. Secondary validation draws from EU EFSA hygiene package directives, FDA low-acid canned food regulations, China's GB standards documentation, FSSAI modernization circulars, and customs trade data for stainless steel equipment imports. Bottom-up equipment shipment tallies triangulate against top-down frozen vegetable processing capacity expansion estimates.
Granularity-level modeling disaggregates volume and value outputs by product type (continuous, batch, countertop, industrial installation), operating mode (automatic, hybrid, manual, semi-automatic), and end user (food processors, catering services, restaurants, household users) across the analysis window. CAGRs derive from regression analysis of historical capital expenditure patterns and projected replacement cycles. Industry-specific forecast inputs include EU Green Deal Scope 3 reduction deadline compliance timelines and India's PLI scheme disbursement trajectories for cold chain infrastructure.
Several conditions sit outside the modeled scope, including abrupt nickel futures dislocations affecting grade 316L input costs, unilateral REACH Annex XVII restrictions on fluoropolymer chemistries, and geopolitical trade barrier impositions between EU and Chinese certification regimes. Forecasts reflect assumptions about regulatory stability and energy cost trajectories that material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Food and Beverages Air Filters Market
Food Processing Equipment
Clean in Place Market
Food Processing Equipment
Spiral Cooler Market
Food Processing Equipment
Planetary Mixer Market
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
Ice Cream Processing Equipment Market
Food Processing Equipment
Pea Protein Processing Equipment Market
Food Processing Equipment
Small Brewery Equipment Market
Food Processing Equipment
Sous Vide Cooking Appliances Market
Food Processing Equipment
Coconut Crushers Market
Food Processing Equipment
Global Shawarma Machines Market
Food Processing Equipment
Middle East and Africa Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Ice Maker Machines Market
Food Processing Equipment
Continuous Fryer Machine Market
Food Processing Equipment
Philippines Cold Storage Warehouse Market
Food Processing Equipment
Global Food Dehydrators Market