
 Dehydrators Market | 2026-2036
Dehydrators Market Size, Share, and Industry Trends Forecast 2026-2036
Dehydrators Market Insights
Aftermarket service revenue for industrial dehydration systems is reshaping margin pools across the value chain, pulling profitability away from pure equipment sales toward maintenance contracts and spare parts fulfillment. Excalibur Dehydrator leverages its established dealer network to sustain recurring revenue streams in North American commercial kitchens. COSORI competes aggressively on smart-home connectivity, while LEM Products Holding LLC anchors its position in hunting and outdoor preservation segments through specialized chamber designs.
A dehydrator is an electromechanical or thermal device that removes moisture from organic materials through controlled heat and airflow, typically operating between 95°F and 165°F depending on substrate sensitivity, to inhibit microbial growth and extend shelf stability. The equipment serves commercial food processors, agricultural cooperatives, and household consumers seeking to preserve nutritional density while reducing water activity to safe thresholds. Tray dehydrators occupy the broadest household penetration, whereas industrial dehydrators command the highest unit margins and are deepening integration with programmable logic controllers for batch consistency. Convective drying technology leads installed capacity globally, though microwave drying is gaining traction in premium snack manufacturing for its speed and energy precision.
The U.S. FDA enforces preventive controls for low-moisture foods under FSMA, compelling dehydrator manufacturers to validate kill-step parameters and sanitary design standards. The EU's REACH regulation and EFSA material safety assessments constrain polymer and coating selections for food-contact surfaces, elevating compliance costs for European-bound equipment. China's SAMR implements GB standards for food machinery hygiene that foreign suppliers must certify before market entry. Stakeholders must monitor how energy-efficiency mandates and carbon-border adjustments will reshape equipment specification criteria and sourcing geography.
Market Dynamics
Snack manufacturers are scaling automated drying capacity to meet clean-label demand, while FSMA kill-step validation requirements force equipment redesigns across North American and European supply chains. This dual pressure compresses procurement cycles and elevates total cost of ownership calculations.
Growth Catalysts
- Clean-label snack expansion:Dried fruit and vegetable processors in China's Shandong province are installing PLC-integrated systems to achieve batch consistency for export markets.
- FSMA preventive controls:The U.S. FDA mandates validated kill-step parameters for low-moisture foods, compelling processor upgrades to compliant thermal systems.
- Energy-efficiency retrofit mandates:EU Green Deal carbon-border adjustments are accelerating replacement of legacy convective dryers with heat-pump and microwave technologies.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 price swings compress fabrication margins for European and North American equipment builders.
- Control system supplier concentration:Programmable logic controller modules for industrial dehydrators concentrate among German and Japanese automation vendors, creating single-source risk.
- Freeze-drying substitution:Premium pet food and nutraceutical processors are migrating to lyophilization for superior nutrient retention, constraining high-end thermal dryer demand.
Strategic Opportunities
- India food processing corridors:The PLI scheme for food processing machinery offers 20-35% capital subsidy for automated drying lines in Uttar Pradesh and Maharashtra.
- Smart-home channel expansion:Connected dehydrators with app-controlled temperature profiling are penetrating direct-to-consumer channels previously dominated by offline retail.
- Precision fermentation feedstock drying:Novel protein producers require specialized low-temperature dehydration for mycelium and biomass preservation.
Industry Challenges
- Thermal process engineering talent scarcity:Food safety validation and heat-transfer modeling expertise concentrates among aging specialists in Midwestern U.S. and Northern European equipment firms.
- Legacy system integration friction:Brownfield food plants face protocol mismatches when retrofitting IoT-enabled monitoring onto 1990s-era dryer control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dehydrators Market |
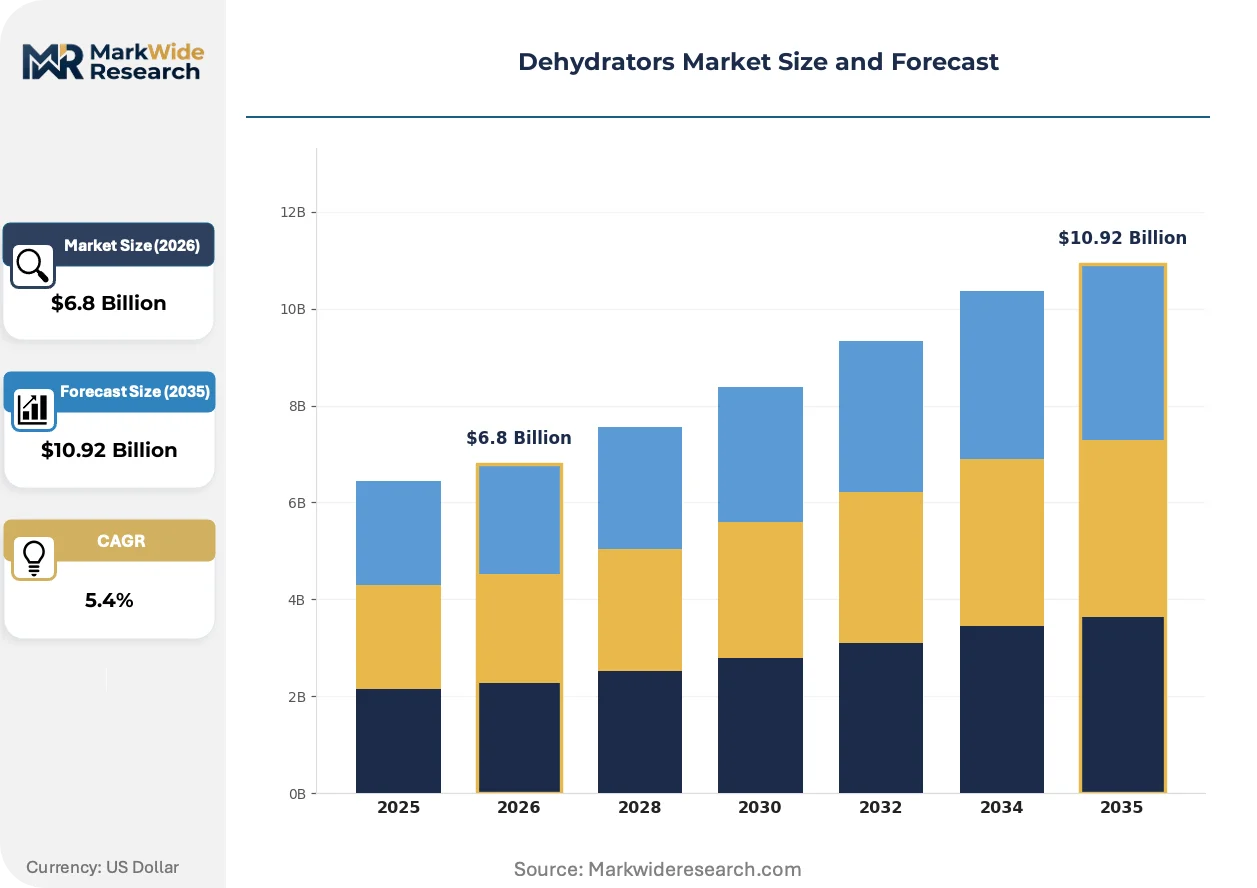
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tray Dehydrators, Industrial Dehydrators, Food Dehydrators, Portable Dehydrators Application: Food Preservation, Herbal Drying, Fruit Drying, Vegetable Drying End User: Restaurants, Home Users, Food Processing Industry, Snack Manufacturers Technology: Solar Drying, Convective Drying, Microwave Drying, Hybrid Drying |
| Companies Covered | Tribest Corporation, Hamilton Beach Brands, Inc., Excalibur Dehydrator, National Presto Industries, Inc., Koolatron Corporation, LEM Products Holding LLC, Aroma Housewares Company, STX International, COSORI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dehydrators Market Trends and Innovations
Equipment intelligence and energy recovery systems are displacing conventional thermal designs, while regulatory material restrictions and buyer consolidation reshape competitive requirements.
Programmable logic controllers with embedded food safety algorithms are digitizing batch documentation and kill-step verification for mid-scale commercial processors. Regional cooperatives in France and California are adopting these systems to reduce manual HACCP logging. The technology is digitizing compliance workflows and compressing audit preparation timelines from weeks to hours.
REACH substance restrictions on chromium coatings and certain polymer additives are constraining food-contact surface specifications for European-bound equipment. Manufacturers are shifting to ceramic and glass-bead blast finishes to maintain sanitary ratings without restricted compounds. Premium snack producers in the Netherlands and Germany are demanding third-party EFSA compliance certification before contract award.
Aftermarket service unbundling is fragmenting traditional equipment-procurement relationships. Large agricultural cooperatives in Brazil and Australia are negotiating separate maintenance contracts and spare parts agreements rather than bundled purchase packages. This shift concentrates purchasing power among procurement teams and compresses vendor margins on initial equipment sales.
Dehydrators Market Segmentation
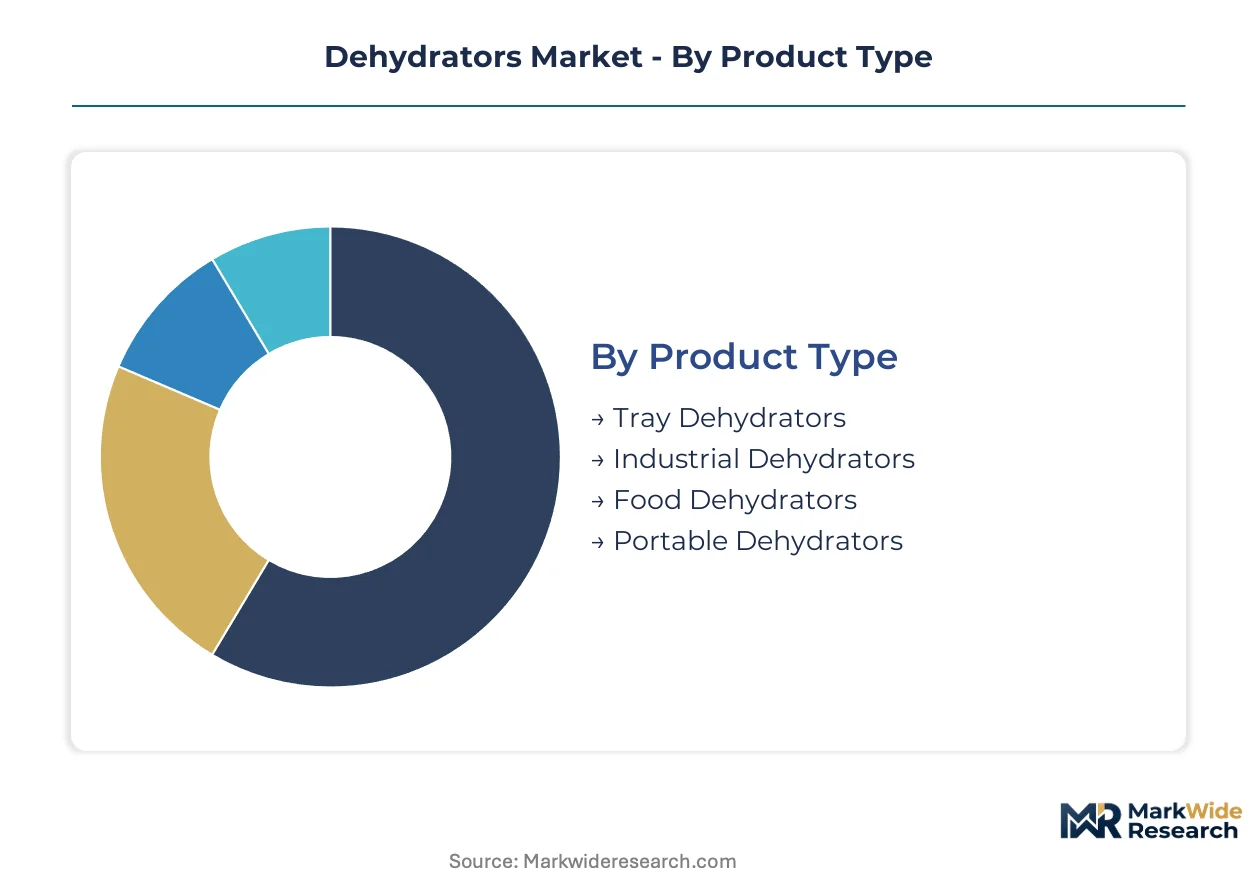
Dehydrator procurement patterns diverge sharply across use cases, with industrial buyers prioritizing throughput validation and compliance documentation while household consumers trade automation for countertop footprint. Segment boundaries are blurring as commercial kitchen operators adopt scaled-down industrial controls and snack manufacturers demand residential-scale flexibility for R&D lines.
Product Type:
Cost tier separates equipment procurement strategies, with capital intensity determining whether buyers lease, finance, or purchase outright.
- Tray Dehydrators:Stackable horizontal or vertical chamber designs with perforated polymer or stainless steel trays, typically 4-10 tier configurations rated for 95°F to 165°F operation. Demand concentrates among home users in North American suburban markets where clean-label meal prep trends drive countertop appliance turnover.
- Industrial Dehydrators:Continuous belt or batch chamber systems with programmable logic controllers, heat recovery modules, and sanitary welded construction for HACCP-validated operations. Snack manufacturers in China's Shandong and Henan provinces are scaling automated installations to meet export certification requirements.
- Food Dehydrators:Mid-capacity units bridging commercial and prosumer segments, often featuring digital temperature controls and transparent door panels for visual batch monitoring. Agricultural cooperatives in France and California deploy these for seasonal fruit processing with lower capital barriers.
- Portable Dehydrators:Collapsible or lightweight designs powered by 12V automotive or solar inputs, targeting outdoor recreation and emergency preparedness channels. Hunting and camping retailers in the U.S. Midwest stock these for game meat preservation during seasonal peaks.
Tray dehydrators command the established base. The steepest expansion runs through industrial dehydrators.
Application:
Application focus determines equipment specification priorities, with moisture content targets and substrate fragility driving thermal profile requirements.
- Food Preservation:Broad-spectrum moisture reduction for long-term storage of proteins, grains, and prepared meals, typically targeting water activity below 0.6 for shelf-stable outcomes. Preppers and homesteading communities in rural U.S. markets sustain steady demand for robust, repairable units.
- Herbal Drying:Low-temperature dehydration preserving volatile aromatic compounds and active phytochemicals, requiring precise airflow control below 115°F. Small-scale cultivators in Oregon and Northern California invest in dedicated chambers to protect terpene profiles for medicinal and culinary markets.
- Fruit Drying:High-sugar substrate processing with sticky surface management and uniform heat distribution to prevent case hardening. Export-oriented processors in Turkey and Chile deploy tunnel dryers for mango, apricot, and grape production destined for European retail.
- Vegetable Drying:Blanching-integrated workflows for enzymatic deactivation prior to moisture removal, preserving color and rehydration capacity. Soup and ready-meal manufacturers in the Netherlands specify custom belt configurations for onion, tomato, and leafy green processing.
Food preservation anchors volume throughput. Fruit drying gains share fastest.
End User:
Customer type dictates purchasing authority structures, with procurement teams, owner-operators, and individual consumers applying divergent evaluation criteria.
- Restaurants:High-turnover commercial kitchens requiring compact footprint equipment for house-made garnishes, powders, and preserved components. Farm-to-table establishments in Copenhagen and Melbourne feature dehydration programs as menu differentiation tools.
- Home Users:Individual consumers prioritizing ease of cleaning, noise levels, and recipe app integration over throughput metrics. Direct-to-consumer brands are capturing this segment through social media content demonstrating jerky and fruit leather preparation.
- Food Processing Industry:Mid-scale manufacturers with dedicated engineering staff capable of validating kill-step parameters and maintaining sanitary design standards. Brazilian agricultural cooperatives are unbundling maintenance contracts from initial equipment purchases to optimize lifecycle costs.
- Snack Manufacturers:Large-scale operators with automated packaging integration and real-time quality monitoring requirements. Clean-label processors in Germany and the Netherlands demand third-party EFSA compliance certification before contract award.
Home users represent the broadest installed base. Snack manufacturers drive premium equipment upgrades.
Technology:
Maturity level and energy efficiency separate technology adoption curves, with legacy thermal methods competing against precision alternatives.
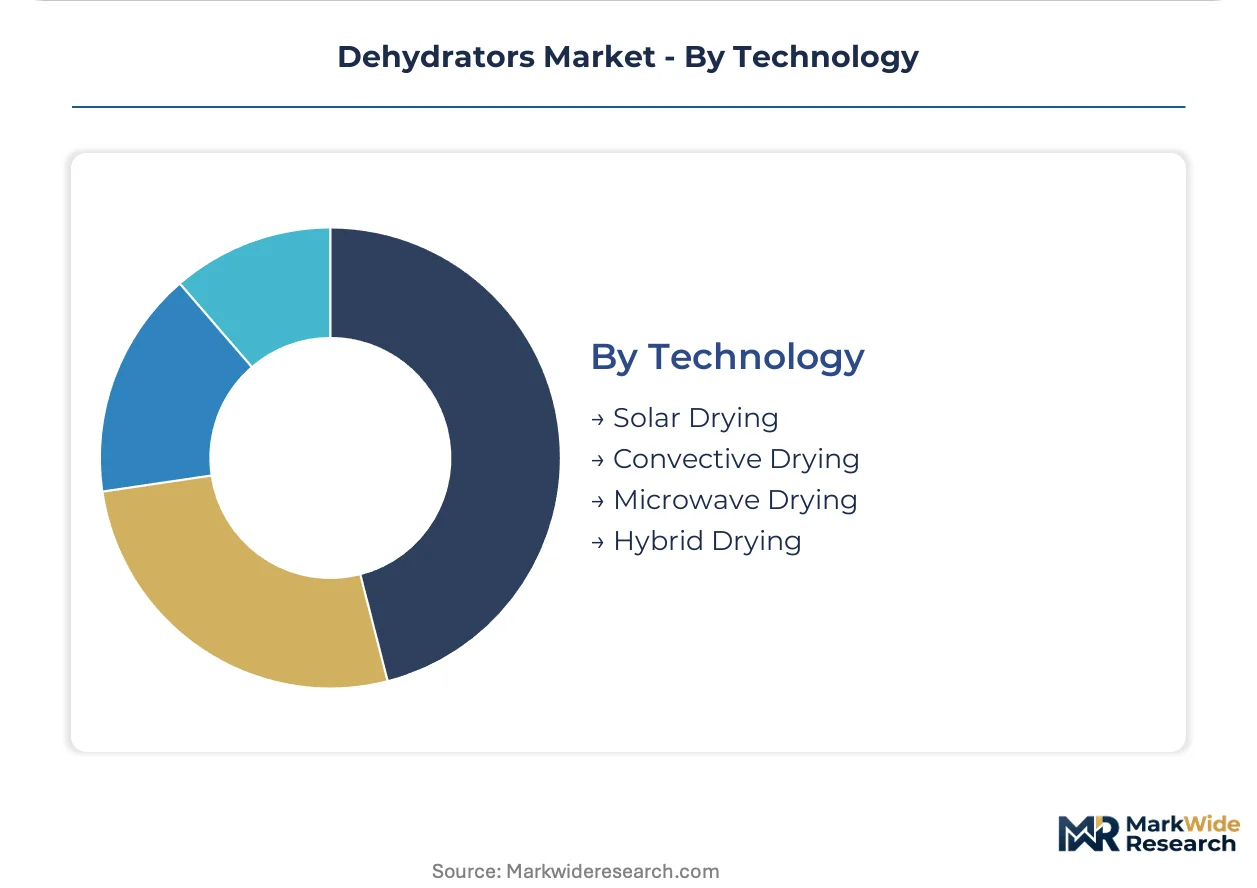
- Solar Drying:Passive or active solar-thermal collection with natural or forced convection, eliminating electrical input but dependent on ambient conditions and diurnal cycles. Off-grid communities in sub-Saharan Africa and South Asia deploy these for post-harvest loss reduction with minimal capital outlay.
- Convective Drying:Heated air circulation through electric or gas-fired heat exchangers, the dominant installed base globally due to capital efficiency and operational simplicity. EU Green Deal carbon-border adjustments are accelerating replacement of legacy convective systems with heat-pump alternatives.
- Microwave Drying:Dielectric heating penetrating substrate volume for rapid, uniform moisture removal with reduced thermal degradation. Premium snack producers in Japan and South Korea are adopting microwave tunnels for high-value fruit and vegetable crisp production.
- Hybrid Drying:Sequential or simultaneous combination of thermal methods, such as convective pre-drying followed by microwave finish, optimizing energy use and product quality. Precision fermentation feedstock processors are piloting hybrid configurations for mycelium biomass preservation.
Convective drying holds the dominant position. Hybrid systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's agricultural cooperatives exhibit the highest price elasticity, deferring equipment upgrades until subsidy windows open. German snack manufacturers show the lowest sensitivity, prioritizing EFSA-validated systems regardless of capital cost. China's Shandong processors occupy the middle ground, balancing automation mandates against export certification timelines.
United States
Commercial kitchen operators and homesteading communities drive divergent demand streams. The FDA's FSMA preventive controls mandate validated kill-step documentation for low-moisture food processors. Equipment validation services concentrate in Midwestern states where thermal engineering expertise clusters around legacy food machinery corridors.
China
Export-oriented fruit processors in Shandong and Henan provinces scale automated drying capacity for European retail compliance. SAMR's GB standards for food machinery hygiene require foreign suppliers to certify sanitary design before market entry. Qingdao and Zhengzhou industrial zones host the densest concentration of PLC-integrated dehydration line installations.
Germany
Premium snack manufacturers demand third-party EFSA compliance certification prior to contract award. EU Green Deal carbon-border adjustments accelerate heat-pump dryer adoption against legacy convective systems. The Netherlands and western German processing clusters lead hybrid technology pilot programs for energy recovery integration.
India
Food processing machinery investment concentrates in Uttar Pradesh and Maharashtra under PLI scheme subsidies reaching 35% capital support. FSSAI hygiene standards for dried fruit exports compel processor upgrades to stainless steel construction. Mumbai and Lucknow corridors attract automated line deployments for mango and spice dehydration.
Brazil
Agricultural cooperatives unbundle maintenance contracts from initial equipment purchases to optimize lifecycle cost structures. ANVISA sanitary regulations for dried meat products elevate documentation requirements for jerky processors. São Paulo state food parks integrate dehydration lines with automated packaging for domestic retail distribution.
Dehydrators Market Competitive Landscape
Capability concentration sits with specialized thermal engineering firms; scale advantage sits with diversified appliance manufacturers. The vendor base separates into three functional tiers: industrial system integrators with PLC validation expertise, mid-cap commercial equipment builders, and consumer appliance brands competing on connectivity features. Consolidation pressure runs through maintenance contract unbundling and aftermarket service fragmentation.
Among North American specialists, Excalibur Dehydrator and LEM Products Holding LLC exemplify divergent archetype strategies. Excalibur occupies a position anchored to dealer-network recurring revenue in commercial kitchen channels. LEM Products Holding LLC sits within the outdoor preservation equipment tier, serving hunting and game meat processing segments through specialized chamber configurations. COSORI represents the connected-appliance vector, competing on smart-home integration and direct-to-consumer app ecosystems rather than thermal engineering depth.
| Leading Market Players |
|---|
| Tribest Corporation |
| Hamilton Beach Brands, Inc. |
| Excalibur Dehydrator |
| National Presto Industries, Inc. |
| Koolatron Corporation |
| LEM Products Holding LLC |
| Aroma Housewares Company |
| STX International |
| COSORI |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's Shandong drying equipment manufacturing corridor compresses pricing power for mid-cap industrial dehydrator builders while simultaneously incentivizing aggressive aftermarket service bundling to defend margins. This utilization dynamic forces European and North American fabricators to differentiate through validated kill-step documentation and energy-recovery integration rather than competing on capital cost alone.
Pricing Analysis
Long-term offtake contracts dominate procurement for snack manufacturers scaling automated capacity, while spot purchasing persists among agricultural cooperatives with seasonal processing windows. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-validated systems with embedded PLC safety algorithms from basic convective units without documentation packages. Pricing pressure stems from stainless steel input volatility eroding fabrication margins for Grade 304 and 316 construction. Brazilian agricultural cooperatives exhibit the highest price sensitivity through unbundled maintenance negotiations, whereas German clean-label processors show minimal elasticity when third-party compliance certification is demanded.
Supply Chain Analysis
Export-control regimes on precision microwave generator components limit technology transfer from Japanese and German automation vendors to Chinese system integrators, constraining hybrid drying line proliferation. Component fabrication concentrates in China, Germany, and Japan, with programmable logic controller modules drawing from concentrated German and Japanese supplier bases. Raw material dependencies center on stainless steel sheet stock, ceramic coating formulations, and heat-pump compressor assemblies. Single-source vulnerability runs through PLC module supply concentration. Distribution runs through dealer networks for commercial kitchen channels and direct OEM relationships for snack manufacturing scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freeze-drying substitution in premium pet food and nutraceutical segments threatens thermal dehydrator incumbents, demanding active defense of mid-scale commercial processing strongholds where capital efficiency still favors convective and microwave technologies.
For Market Incumbents: Build aftermarket service moats through unbundled maintenance contracts and spare parts fulfillment networks that lock agricultural cooperatives into recurring revenue streams. Anchor defensive positioning by deepening PLC-integrated validation expertise for FSMA-compliant kill-step documentation, neutralizing emerging automation entrants lacking thermal engineering depth. Prioritize backward integration into heat-pump compressor sourcing to offset carbon-border adjustment exposure in EU-bound equipment sales. For New Entrants and Emerging Players: Mid-market food processing corridors in India's Uttar Pradesh and Maharashtra represent the most penetrable entry point given PLI scheme subsidies reaching substantial capital support levels for automated drying lines. Precision fermentation feedstock drying for mycelium biomass preservation offers uncaptured white-space demand from novel protein producers requiring specialized low-temperature configurations. Go-to-market execution should target direct engagement with Mumbai and Lucknow equipment procurement committees rather than competing through established dealer networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across industrial dehydrator segments as heat-pump and microwave technology adoption demands higher upfront equipment investment against legacy convective alternatives. Acquisition targeting should prioritize mid-cap commercial equipment builders with established FSSAI or EFSA certification pathways and embedded PLC programming capabilities. Monitor carbon-border adjustment implementation timelines as the critical inflection signal for accelerated replacement demand in European processing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Aftermarket Service Unbundling | Separate maintenance contracts from equipment sales to capture Brazilian cooperative lifecycle spending. |
| Heat-Pump Technology Transition | Replace legacy convective systems ahead of EU Green Deal carbon-border adjustment enforcement. |
| PLC Safety Algorithm Development | Embed kill-step verification to meet FDA FSMA preventive controls for low-moisture food processors. |
| Precision Fermentation Partnership | Develop specialized low-temperature configurations for mycelium biomass preservation demand. |
| Regional Certification Investment | Secure EFSA and FSSAI validation pathways to unlock German snack manufacturer and Indian export procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC equipment manufacturer filings, customs trade data for drying machinery imports, and SAMR GB standard certification records. Interviews with plant engineers at snack manufacturing facilities, aftermarket service heads at dealer networks, and procurement leads at agricultural cooperatives informed demand-side validation. Technical discussions with thermal engineering specialists and PLC automation vendors supplied supply-side perspective. Bottom-up equipment shipment analysis triangulates against top-down food processing capacity expansion tracking.
Forecast inputs span product type segmentation across tray, industrial, and portable configurations; technology adoption curves for convective, microwave, and hybrid systems; and end-user differentiation between home users, restaurants, and large-scale snack manufacturers. CAGRs derive from modeled replacement cycles for legacy convective capacity against energy-efficiency retrofit mandates and clean-label snack production expansion. Industry-specific inputs incorporate FSMA validation timeline assumptions and PLI scheme subsidy window durations.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity pricing, carbon-border adjustment implementation pace, or precision fermentation investment flows would shift the trajectory. Material shifts in freeze-drying cost curves or REACH substance restriction expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Electric Kebab Machine Market
Food Processing Equipment
Glass Processing Equipment Market
Food Processing Equipment
Mixer Settler Market
Food Processing Equipment
Global Automatic Mask Production Equipment Market
Food Processing Equipment
Automatic Deboner Market
Food Processing Equipment
Wine Bottling Machine Market
Food Processing Equipment
Electric Brewing System Market
Food Processing Equipment
Pasta Machine Market
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
Cake Cutting Machines Market
Food Processing Equipment
Commercial Kettles and Braising Pans Market
Food Processing Equipment
Granular Ice Machine Market
Food Processing Equipment
Food Processing Equipment Market
Food Processing Equipment
Small Brewery Equipment Market
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Walk-In Refrigerator Market