
 Micro Winery Equipment Market | 2026-2036
Micro Winery Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Winery Equipment Market Foresight
The EU Green Deal is pivoting European micro winery procurement toward energy-efficient fermentation and bottling lines. Bucher Vaslin SA leverages its French manufacturing heritage to dominate European press and tank supply. Alfa Laval AB anchors its position through advanced heat exchanger technology for temperature-controlled fermentation. GEA Group AG competes on automation integration, extending its dairy processing expertise into small-batch wine systems.
Micro winery equipment encompasses scaled-down vinification machinery—typically stainless steel fermentation tanks under 5,000 liters, pneumatic presses with membrane bladder systems, gravity-fed bottling lines, and oak or alternative-material aging vessels—engineered for batch volumes between 100 and 10,000 cases annually. Fermentation tanks command the largest product share due to their universal necessity across all production scales, while eco-friendly solutions represent the fastest-expanding technology category as water recycling and energy recovery systems gain traction among sustainability-focused vintners. Craft winemaking applications generate the highest absolute demand, though commercial production segments retain stronger pricing power through repeat equipment refresh cycles.
EMA guidelines on food contact materials and REACH chemical safety standards govern equipment composition and cleaning protocol chemistry across European markets, while FDA food safety regulations and TTB labeling requirements shape product specifications for US-bound winery equipment. The USDA's National Organic Program influences material selection for tanks and barrels serving certified organic vineyards. Stakeholders must weigh regulatory divergence between EU and North American standards when designing modular equipment platforms for cross-border micro winery customers.
Market Dynamics
The EU Green Deal is compressing equipment refresh cycles across European micro wineries, forcing vintners to replace legacy fermentation systems with water-recycling and energy-recovery configurations ahead of import compliance deadlines.
Growth Catalysts
- REACH chemical safety standards:Equipment manufacturers are redesigning tank coatings and cleaning protocols to eliminate restricted substances, opening upgrade revenue from compliance-driven replacements.
- Biodynamic certification expansion:France's Burgundy region is modernizing cellars with precision fermentation controls to meet Demeter and Biodyvin process documentation requirements.
- Membrane press technology:Pneumatic presses with bladder systems are displacing traditional basket presses in California's Sonoma County, reducing oxidation and labor intensity for craft producers.
Market Restraints
- Stainless steel price volatility:Fermentation tank fabrication costs fluctuate with nickel and chromium input markets, squeezing margins for European fabricators dependent on Asian metal supply.
- Specialized component concentration:Precision temperature control systems rely on German and Italian sensor suppliers, creating single-source vulnerability for North American equipment assemblers.
- Scale ceiling in gravity-fed bottling:Manual bottling lines cap throughput at approximately 1,200 bottles per hour, blocking micro wineries from contract production opportunities without capital-intensive automation jumps.
Strategic Opportunities
- India's nascent wine regions:Maharashtra and Karnataka state governments are subsidizing winery infrastructure under agricultural diversification schemes, creating first-mover equipment installation potential.
- Hybrid oak-alternative aging:Converging demand for cost control and sustainability is driving trials of toasted oak chips in stainless steel tanks among Australia's Margaret River producers.
- Direct-to-consumer channel maturation:US micro wineries are investing in on-premise bottling lines to support tasting-room sales, bypassing mobile bottling services and capturing margin.
Industry Challenges
- Cross-border certification complexity:Equipment serving both EU and US markets must simultaneously satisfy EMA food contact material rules and FDA food safety regulations, extending design validation timelines.
- Legacy cellar integration:Pre-digital temperature monitoring systems in established European wineries require costly retrofitting to interface with automated fermentation control platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Winery Equipment Market |
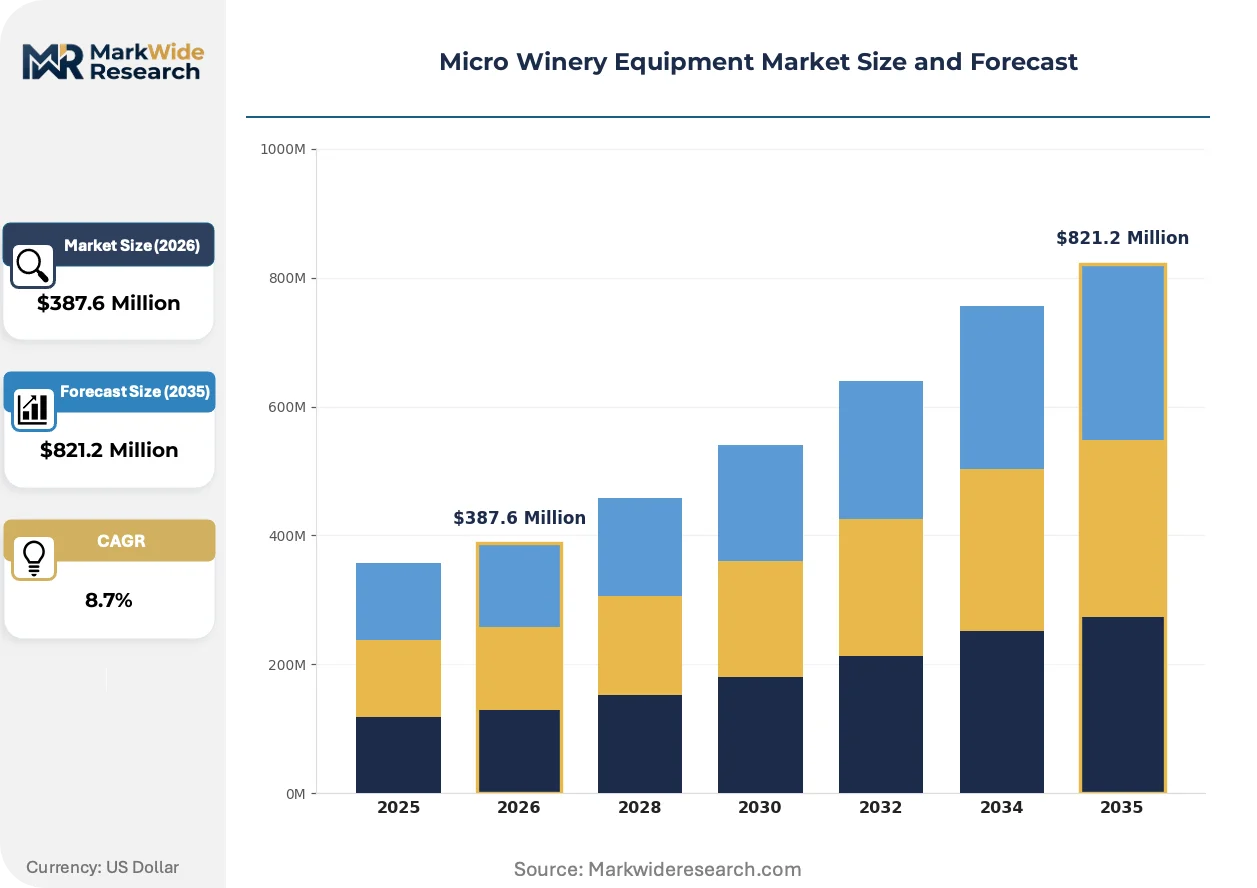
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fermentation Tanks, Presses, Bottling Equipment, Aging Barrels Application: Craft Winemaking, Home Production, Commercial Production, Wine Tasting Rooms Technology: Traditional Methods, Modern Techniques, Automation Systems, Eco-Friendly Solutions End User: Small Wineries, Independent Vintners, Hobbyists, Enterprises |
| Companies Covered | Criveller Group, AEB Group, Bucher Vaslin SA, Prospero Equipment Corp., Mori-Tem, GEA Group AG, Alfa Laval AB, Grapeworks Pty Ltd, Krones AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Winery Equipment Market Shifts & Advancements
Digital fermentation monitoring is displacing manual cellar management across premium micro winery segments, while sustainability mandates are rewriting equipment specification criteria. Three developments are restructuring competitive positioning.
Precision temperature control systems is converging with IoT-enabled predictive analytics, allowing vintners to anticipate fermentation deviations before sensory detection. Biodynamic producers in France's Loire Valley are deploying these platforms most aggressively, compressing the skill gap between apprentice and master winemakers while reducing spoilage losses.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in cooling systems, forcing equipment manufacturers to specify propane or CO2-based alternatives for new tank installations. German and Italian fabricators are retooling production lines fastest, while Spanish and Portuguese suppliers face compliance lag that is reshaping intra-European sourcing patterns.
Service unbundling is fragmenting traditional equipment procurement. California's Napa Valley micro wineries are separating capital purchases from maintenance contracts, instead sourcing predictive maintenance through third-party viticultural technology platforms. This compresses vendor margins on initial sales while extending customer lifetime value for specialized service providers.
Micro Winery Equipment Market Segmentation
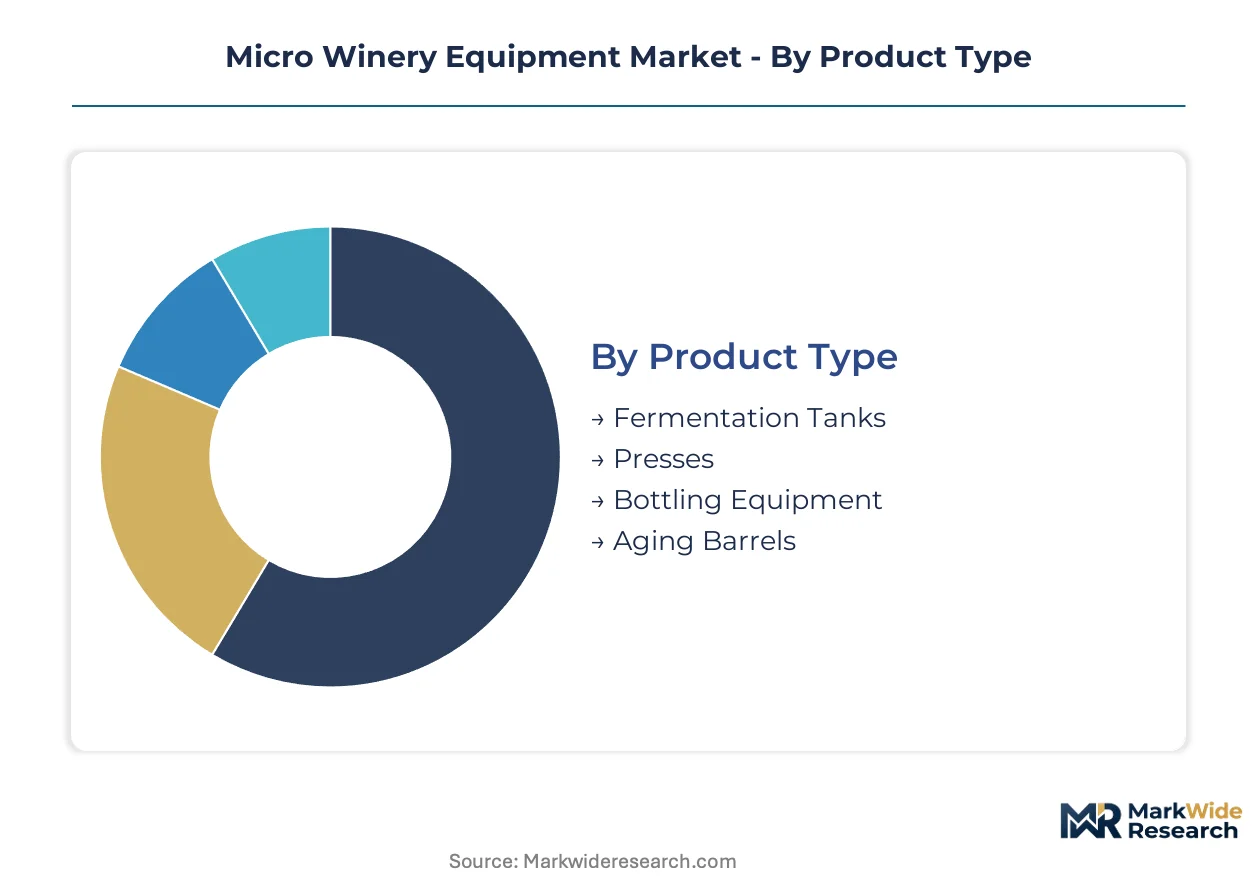
Equipment segmentation in micro wineries determines capital deployment priorities, with fermentation infrastructure commanding universal placement while bottling and aging systems vary by channel strategy and scale ceiling.
Product Type:
Fermentation tanks function as standalone anchor investments, whereas presses and bottling lines often embed into integrated production workflows.
- Fermentation Tanks:Stainless steel vessels under 5,000 liters with temperature control jackets form the core production asset for every micro winery. California's Napa Valley operators are prioritizing water-recycling jacket systems ahead of EU Green Deal import compliance deadlines for European-bound exports.
- Presses:Pneumatic membrane presses with bladder systems are displacing traditional basket configurations in Sonoma County craft operations, cutting oxidation exposure and labor hours per crush cycle.
- Bottling Equipment:Gravity-fed manual lines dominate sub-1,000 case producers; automated fillers penetrate tasting-room direct-to-consumer channels.
- Aging Barrels:Oak alternatives and hybrid chip-in-tank systems are gaining trial among Australia's Margaret River sustainability-focused vintners.
Volume placements concentrate in fermentation tanks; the faster expansion belongs to eco-optimized press and tank configurations.
Application:
Application segmentation tracks margin capture potential, with craft and commercial production diverging on automation depth and refresh cycle frequency.
- Craft Winemaking:Small-batch producers in France's Burgundy region are modernizing cellars with precision fermentation controls to satisfy Demeter biodynamic certification documentation requirements.
- Commercial Production:Repeat equipment refresh cycles sustain vendor relationships, though scale ceilings limit micro winery participation in contract bottling services.
- Home Production:Hobby-scale systems emphasize manual operation and compact footprint over throughput metrics.
- Wine Tasting Rooms:On-premise bottling investments are climbing among US micro wineries seeking margin capture from direct-to-consumer sales channels.
Commercial production absorbs the highest equipment volume annually; tasting-room applications are climbing the fastest as channel maturation accelerates.
Technology:
Technology tiers separate legacy cellar retrofits from greenfield installations, with regulatory pressure compressing adoption timelines for sustainable configurations.
- Traditional Methods:Gravity flow and manual temperature monitoring persist in established European cellars where legacy infrastructure resists digital retrofit costs.
- Modern Techniques:IoT-enabled predictive analytics platforms are compressing skill gaps between apprentice and master winemakers in France's Loire Valley biodynamic operations.
- Automation Systems:Precision temperature control with sensor networks depends on concentrated German and Italian component suppliers, creating sourcing vulnerability for North American assemblers.
- Eco-Friendly Solutions:Propane and CO2-based cooling alternatives are displacing hydrofluorocarbon refrigerants under EU F-Gas Regulation phase-down mandates, with German fabricators retooling fastest.
Traditional methods still anchor installed base volume; eco-friendly solutions are gaining share fastest as compliance deadlines approach.
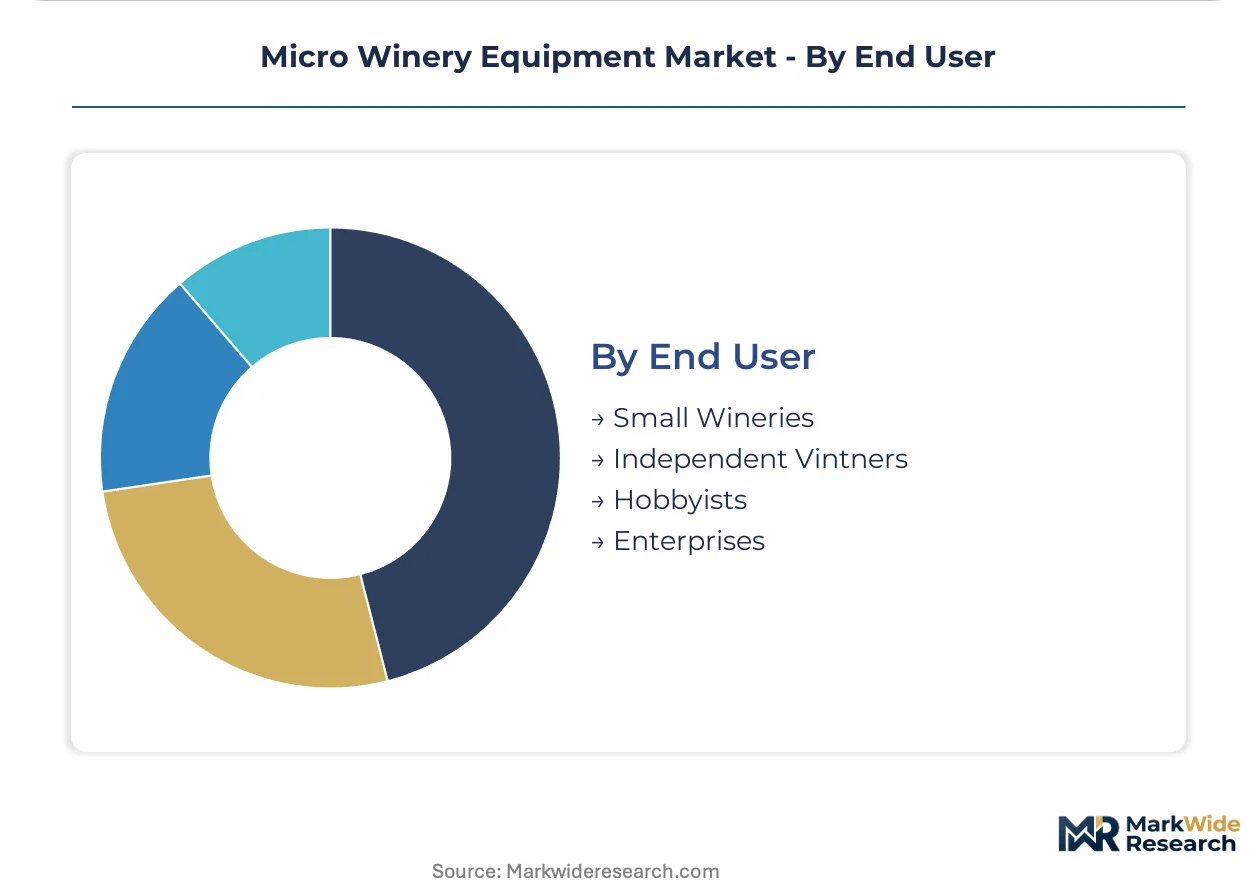
End User:
End user categories align equipment specification with operational sophistication, from enterprise procurement teams to individual hobbyist decision-makers.
- Small Wineries:India's Maharashtra and Karnataka state subsidies are attracting first-mover equipment installations under agricultural diversification schemes.
- Independent Vintners:Burgundy's biodynamic producers are driving demand for precision fermentation documentation systems to satisfy certification audit trails.
- Hobbyists:Entry-level manual presses and small-volume tanks prioritize capital accessibility over production efficiency.
- Enterprises:Large-scale procurement leverages maintenance contract unbundling, separating capital purchases from third-party predictive service platforms.
Small wineries absorb the highest absolute unit volume; independent vintners are expanding fastest as biodynamic certification spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in established European wine regions while consumption-driven equipment procurement accelerates in emerging markets. The EU Green Deal is compressing refresh cycles across French and Italian cellars. India's state-level subsidies are unlocking first-mover installations in nascent viticulture zones.
United States
California's Napa Valley and Sonoma County craft producers are expanding equipment purchases ahead of tightening sustainability requirements for wine exports to Europe. The FDA and TTB regulate food safety and labeling specifications for domestic equipment. Precision fermentation controls are displacing manual cellar management in premium micro winery clusters across these coastal regions.
France
Biodynamic certification expansion in Burgundy and the Loire Valley is driving demand for precision fermentation documentation systems. The EU Green Deal and F-Gas Regulation are forcing refrigerant transitions in cooling jacket systems. Small-scale vintners in these regions are modernizing cellars with IoT-enabled predictive analytics platforms.
Italy
Traditional gravity-flow cellars in Piedmont and Tuscany are retrofitting with automated temperature monitoring to satisfy export compliance documentation. EMA food contact material rules and REACH chemical safety standards govern tank coatings and cleaning protocols. German and Italian sensor suppliers are concentrating supply for these precision control systems.
India
Maharashtra and Karnataka state governments are subsidizing winery infrastructure under agricultural diversification schemes. The country's national food safety regulator and BIS standards shape equipment import specifications. First-mover equipment installations are concentrating in these western and southern states as domestic wine consumption climbs.
Australia
Sustainability-focused vintners in Margaret River are trialing hybrid oak-alternative aging systems combining toasted chips with stainless steel tanks. The country's national agricultural and environmental regulators influence material selection for certified organic production. Water recycling and energy recovery configurations are gaining traction among export-oriented producers in this premium region.
Micro Winery Equipment Market Competitive Landscape
The competitive structure tilts toward specialized European fabricators with deep regional wine heritage. Consolidation around fermentation tank and press specialists persists alongside fragmentation in bottling line assembly. Two archetypes dominate: heritage European manufacturers leveraging proximity to premium wine regions, and diversified industrial conglomerates extending dairy or beverage processing expertise into small-batch systems. Capacity expansion in cooling jacket fabrication and strategic partnerships for sensor technology sourcing represent the primary competitive moves.
Among heritage European specialists, Bucher Vaslin SA and Alfa Laval AB exemplify the regional fabrication archetype, while GEA Group AG occupies a position as the diversified industrial entrant extending automation expertise. These three entities anchor the competitive landscape through distinct positioning: French manufacturing heritage, advanced heat exchange specialization, and cross-sector automation integration respectively. Each represents a viable strategic template for market participation without overlapping directly on capability vectors.
| Leading Market Players |
|---|
| Criveller Group |
| AEB Group |
| Bucher Vaslin SA |
| Prospero Equipment Corp. |
| Mori-Tem |
| GEA Group AG |
| Alfa Laval AB |
| Grapeworks Pty Ltd |
| Krones AG |
| Others |
Supply & Pricing Matrix
Membrane press technology adoption across California's Sonoma County is compressing equipment lifecycle economics while concentrating procurement leverage among German and Italian sensor suppliers. This dual squeeze elevates capital costs for temperature-controlled fermentation systems even as water-recycling jacket configurations become mandatory under EU Green Deal timelines.
Pricing Analysis
Margin tightening in fermentation tank fabrication reflects nickel and chromium input volatility from Asian metal markets. Three-tier pricing structure across premium, standard, and economy levels separates IoT-enabled predictive systems from manual gravity-flow alternatives. Cost-down pressure on European fabricators accelerates because REACH compliance mandates coating redesigns. Hobby-scale buyers exhibit highest price sensitivity; enterprise procurement teams with unbundled maintenance contracts show lowest.
Supply Chain Analysis
Regional distribution centers in Germany, Italy, and France anchor hub-and-spoke patterns for precision temperature control components. Stainless steel feedstock draws from Chinese and Indonesian nickel processing. German and Italian sensor suppliers create single-source vulnerability for North American equipment assemblers. Distribution runs through specialized viticultural technology platforms rather than traditional OEM dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation tank fabrication capacity concentrates in heritage European fabricators, propping pricing power as EU F-Gas Regulation compliance deadlines compress refresh cycles.
For Market Incumbents: Extend sensor technology sourcing partnerships to neutralize single-source vulnerability from German and Italian component suppliers. Build captive cooling jacket fabrication capacity in France or Italy to capture margin from refrigerant transition mandates. Biodynamic certification documentation requirements in Burgundy represent a lever for premium-tier pricing separation. For New Entrants and Emerging Players: Begin with India's Maharashtra and Karnataka state subsidy windows for first-mover winery infrastructure installations. Target hybrid oak-alternative aging systems for Australia's Margaret River sustainability-focused vintners. A direct-to-consumer channel equipment bundling approach bypasses entrenched OEM service relationships. For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation control specialists given IoT-enabled predictive analytics convergence. Long-term viability over a five-to-ten year horizon favors fabricators with EU Green Deal compliance certification depth. Watch for F-Gas Regulation enforcement intensity as inflection indicator for refrigerant transition equipment replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Technology Partnership | Secures supply chain resilience against German and Italian component concentration. |
| Cooling Jacket Capacity Expansion | Captures margin from EU F-Gas Regulation refrigerant transition mandates. |
| Biodynamic Certification Investment | Unlocks premium pricing tier among Burgundy precision fermentation documentation buyers. |
| Direct-to-Consumer Channel Launch | Bypasses mobile bottling service intermediaries for US tasting-room margin capture. |
| India First-Mover Installation | Exploits Maharashtra and Karnataka agricultural diversification subsidy windows. |
Research Methodology
Independent corroboration across equipment manufacturer sales directors, winery operations managers, and viticultural technology platform executives underwrites the qualitative findings. Secondary validation draws from EU ECHA substance restriction databases, USDA National Organic Program material guidelines, and customs trade records for stainless steel fermentation tank imports. Bottom-up unit economics from individual winery capital expenditure patterns triangulate against top-down market sizing from regional equipment shipment aggregates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include equipment product type, application tier, technology generation, and end-user sophistication level. CAGRs derive from logistic diffusion curves fitted to regulatory compliance deadline clustering. Forecast inputs incorporate EU Green Deal implementation pacing and India's state-level subsidy renewal probability.
Underlying measurement precision varies by segment; fermentation tank volume placements carry tighter precision than emerging hybrid aging system adoptions. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and raw material price regime stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Food Recycling Machines Market
Food Processing Equipment
Dehydrators Market
Food Processing Equipment
Global Wine Tanks Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Industrial Food Milling Machine Market
Food Processing Equipment
North America Multi Cooker Market
Food Processing Equipment
Freshwater Flake Ice Machine Market
Food Processing Equipment
India Household Flour Milling Machines Market
Food Processing Equipment
Non-Thermal Food Processing Market
Food Processing Equipment
Alternative Protein Processing Equipment Market
Food Processing Equipment
Pet Food Extrusion Market
Food Processing Equipment
Wine Crusher Market
Food Processing Equipment
Food Disinfection Equipment Market
Food Processing Equipment
Filleting Machines Market
Food Processing Equipment
Food Waste Shredder Market
Food Processing Equipment
Destemmer Market