
 Freeze-Drying Market | 2026-2036
Freeze-Drying Market Size, Share, and Industry Trends Forecast 2026-2036
Freeze-Drying Market Intelligence
Direct equipment sales channels for freeze-drying systems is narrowing as pharmaceutical and food processors consolidate vendor relationships around full-service lifecycle contracts. GEA Group AG leverages its integrated containment and aseptic processing portfolio to anchor multi-year service agreements with European biologics manufacturers. Telstar S.A.U. competes through specialized isolator-integrated lyophilizers designed for potent compound handling. Millrock Technology Inc. differentiates in the laboratory and pilot-scale segment where R&D flexibility commands premium positioning.
Freeze-drying, or lyophilization, removes water from heat-sensitive materials by sublimation under vacuum at temperatures typically below −40°C, preserving structural integrity and bioactivity for extended periods without refrigeration. The process operates at chamber pressures between 0.1 and 0.3 mbar with shelf temperatures cycling through freezing, primary drying, and secondary drying phases to achieve final moisture content below 3%. Tray freeze-drying technology dominates commercial pharmaceutical production where batch sizes exceed 100,000 vials and equipment utilization rates determine manufacturing economics. Lyophilized powders in the product type category command the widest margin pools due to stringent cGMP validation requirements and limited qualified supplier bases.
FDA current good manufacturing practice regulations and EMA Annex 1 sterile manufacturing guidelines shape equipment qualification protocols, driving replacement cycles for non-compliant legacy lyophilizers. ISO 9001 and ISO 13485 quality management standards further constrain market access for equipment suppliers lacking certified quality systems. Stakeholders must monitor evolving regulatory expectations for continuous process verification and real-time release testing as agencies integrate lyophilization into broader pharmaceutical quality paradigms.
Market Dynamics
Pharmaceutical cold-chain logistics are deepening lyophilization adoption for biologics preservation, with FDA and EMA stability guidelines now mandating validated freeze-drying protocols for parenteral drugs. This regulatory convergence is compressing equipment replacement cycles and consolidating buyer-vendor relationships around full-service lifecycle contracts.
Growth Catalysts
- EMA Annex 1 sterile manufacturing guidelines:These updated protocols require continuous process verification for lyophilization, forcing pharmaceutical manufacturers to upgrade legacy equipment and validate new installations against stricter contamination control standards.
- Biologics preservation demand:Monoclonal antibodies and cell therapies require sublimation-based stabilization to maintain bioactivity across extended distribution networks without continuous refrigeration infrastructure.
- Contract manufacturing expansion:CDMOs in Germany, the United States, and China are scaling commercial lyophilization capacity to capture outsourced production from originator pharmaceutical companies.
Market Restraints
- Stainless steel and vacuum pump supply concentration:Critical lyophilizer components depend on specialized European and Japanese suppliers, creating lead time vulnerability and input cost volatility for equipment manufacturers.
- Technical limitation in continuous processing:Batch-based tray lyophilization remains the only validated approach for commercial pharmaceutical production, constraining throughput scalability versus alternative drying technologies.
- Substitution threat from spray-drying:Protein formulations with lower thermal sensitivity increasingly adopt spray-drying for cost efficiency, narrowing the addressable market for freeze-drying in select therapeutic categories.
Strategic Opportunities
- Underpenetrated food preservation applications:Specialty coffee, probiotics, and pet nutrition segments in South Korea and Australia represent white space where pharmaceutical-grade lyophilization expertise commands premium positioning.
- Technology convergence with isolator systems:Integration of containment technology with lyophilizers for potent compound handling opens high-margin segments in oncology and hormone manufacturing.
- India PLI scheme for pharmaceuticals:Production-linked incentives for active pharmaceutical ingredient and formulation manufacturing are driving domestic lyophilization capacity investment by multinational and local producers.
Industry Challenges
- Process analytical technology integration:Implementing real-time release testing for lyophilization requires rare expertise in both pharmaceutical process engineering and data science, creating talent scarcity.
- Legacy equipment qualification burden:Retrospective validation of aging lyophilizers against revised FDA cGMP and EMA Annex 1 standards consumes technical resources without generating new revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freeze-Drying Market |
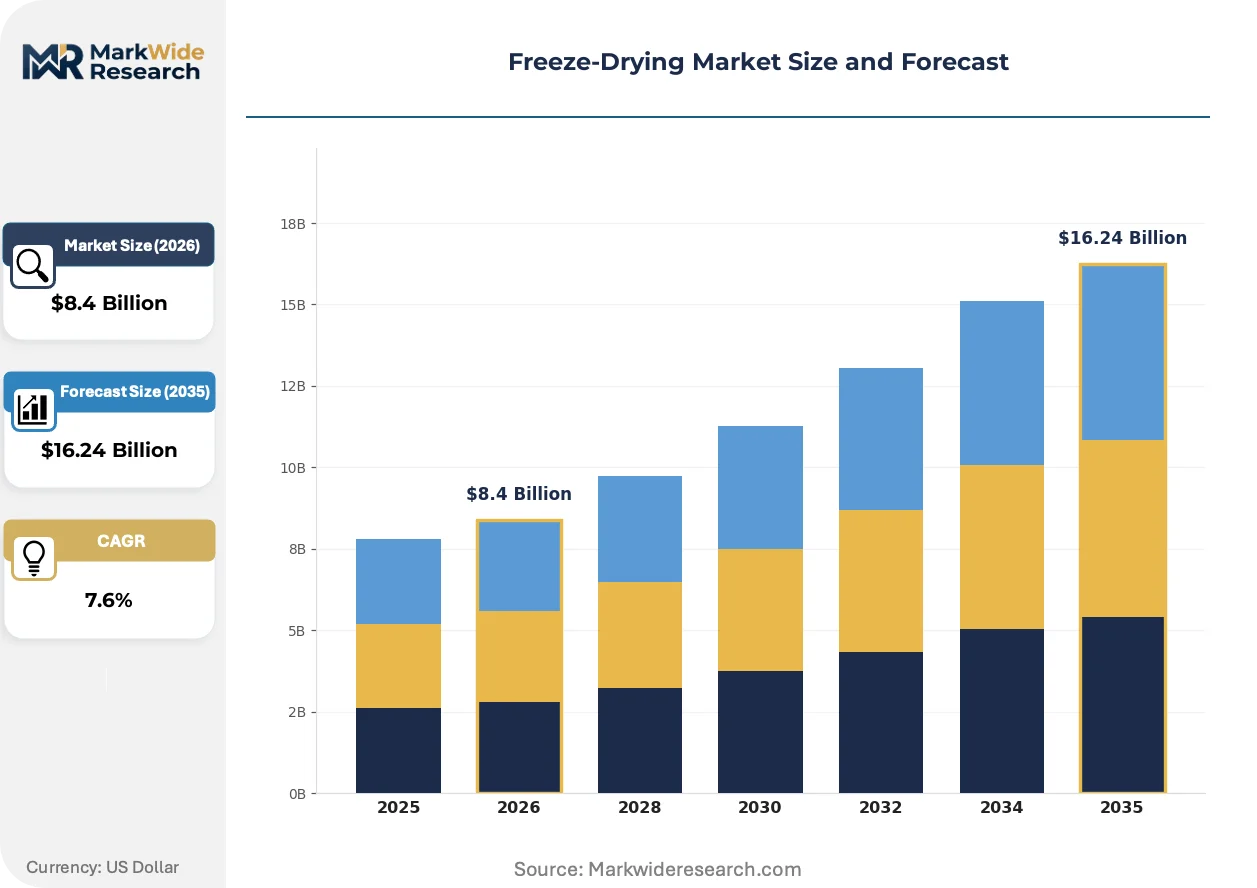
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.24 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lyophilized Powders, Freeze-Dried Fruits, Freeze-Dried Vegetables, Freeze-Dried Meats End User: Food & Beverage Industry, Pharmaceuticals, Biotechnology, Snack Manufacturers Technology: Tray Freeze-Drying, Rotary Freeze-Drying, Vacuum Freeze-Drying, Batch Freeze-Drying Application: Long-Term Storage, Instant Food, Nutraceuticals, Laboratory Use |
| Companies Covered | Millrock Technology Inc., HOF Sonderanlagenbau GmbH, GEA Group AG, Martin Christ Gefriertrocknungsanlagen GmbH, Shanghai Tofflon Science Technology Co. Ltd., Telstar S.A.U., SP Industries Inc., IMA S.p.A., Cuddon Freeze Dry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freeze-Drying Market Strategic Shifts & Innovations
Digital twin technology is virtualizing lyophilization process development, compressing cycle optimization timelines and reducing material waste during scale-up. Equipment manufacturers and pharmaceutical producers are converging on predictive modeling platforms that simulate sublimation behavior before physical batch execution.
Digital twin platforms are virtualizing freeze-drying process development by simulating heat and mass transfer dynamics across shelf configurations. Biologics manufacturers in Switzerland and Massachusetts are adopting these tools to reduce cycle development time by half. The technology is virtualizing traditional empirical optimization approaches, enabling first-principles design of lyophilization protocols without extensive laboratory screening.
EU F-Gas Regulation phase-down schedules are accelerating adoption of alternative refrigerants in lyophilizer cooling systems. Equipment suppliers must redesign condenser architectures to accommodate lower-global-warming-potential fluids while maintaining −80°C performance thresholds. German and Swiss pharmaceutical manufacturers are prioritizing compliant systems in procurement specifications to avoid operational disruption from refrigerant availability constraints.
Service contract unbundling is fragmenting traditional equipment-vendor relationships as pharmaceutical buyers separate hardware procurement from validation and maintenance services. Large biologics producers in Denmark and California are establishing captive lyophilization engineering teams, reducing reliance on original equipment manufacturer service networks. This pattern is most pronounced among companies operating multiple manufacturing sites with standardized equipment platforms.
Freeze-Drying Market Segmentation
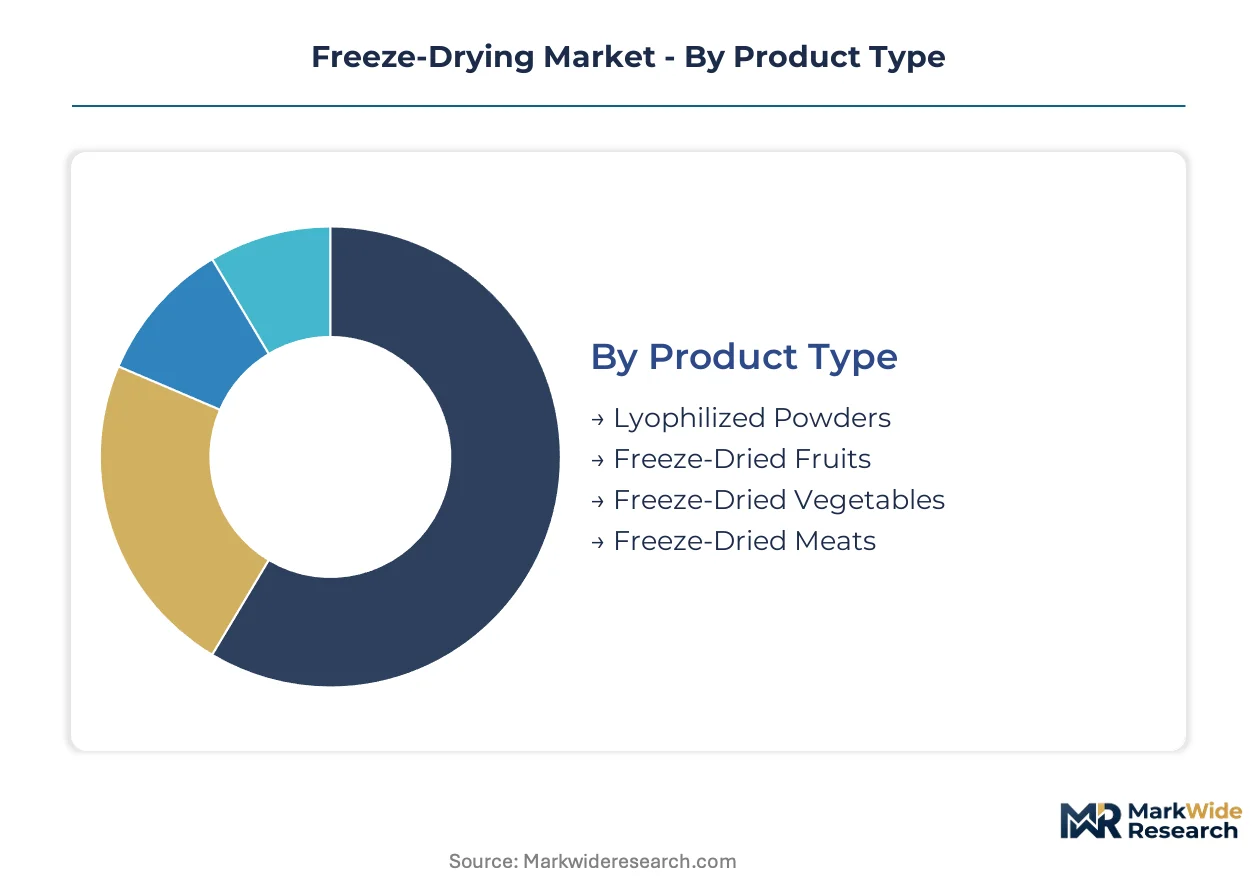
Freeze-drying market segmentation reveals divergent equipment utilization patterns across pharmaceutical validation cycles and food processing seasons. Understanding segment-specific replacement frequencies and capacity expansion timelines enables suppliers to align service contract structures with actual customer operating rhythms.
Product Type:
Cycle times vary dramatically—pharmaceutical powders demand decade-long validation protocols while food products turn over annually with minimal regulatory burden.
- Lyophilized Powders:These sterile pharmaceutical formulations require sub-3% residual moisture and extensive cGMP documentation. Demand clusters in Switzerland and Massachusetts where monoclonal antibody manufacturers operate multi-ton freeze-drying suites under FDA and EMA scrutiny. Equipment runs 24/7 with qualification periods spanning 18-24 months.
- Freeze-Dried Fruits:Breakfast cereal and snack bar manufacturers in California and Germany drive procurement of stainless steel tray systems with faster batch turnaround. Seasonal harvest windows compress installation schedules, creating Q3-Q4 equipment delivery surges.
- Freeze-Dried Vegetables:Soup and ready-meal processors value color retention and rapid rehydration properties.
- Freeze-Dried Meats:Pet nutrition and military ration suppliers in Australia and South Korea represent emerging volume.
Lyophilized powders dominate installed base. Freeze-dried fruits are where expansion concentrates.
End User:
Customer scale determines procurement modality—multinational biologics producers negotiate enterprise frameworks while regional snack makers purchase through equipment distributors.
- Food & Beverage Industry:Coffee processors and specialty ingredient suppliers in Italy and Colombia deploy pilot-scale systems for product development before commercial scale-up. Capital expenditure cycles align with harvest financing and private equity ownership changes.
- Pharmaceuticals:Parenteral drug manufacturers face mandatory lyophilization under FDA stability guidelines for biologics distribution. CDMOs in Germany and the United States are adding commercial capacity to capture outsourced production from originator companies.
- Biotechnology:Cell therapy developers require isolator-integrated containment for potent compound handling.
- Snack Manufacturers:Asian convenience food producers are adopting freeze-drying for premium texture differentiation.
Pharmaceuticals anchor the revenue base. Biotechnology is climbing the fastest as cell therapy manufacturing scales.
Technology:
Equipment architecture selection hinges on batch size requirements and contamination control needs, with pharmaceutical applications demanding stainless steel construction and isolator integration.
- Tray Freeze-Drying:The commercial pharmaceutical standard processes 100,000+ vials per batch with shelf temperatures cycling through −40°C freezing and 20°C secondary drying. German and Swiss manufacturers specify these systems for monoclonal antibody production under EMA Annex 1 guidelines.
- Rotary Freeze-Drying:Granular and powder products benefit from continuous agitation during sublimation, reducing cycle time by 15-20% for certain food applications. Coffee processors in Brazil and Vietnam favor this approach for soluble product manufacturing.
- Vacuum Freeze-Drying:Laboratory and pilot-scale operations utilize lower-capacity systems for R&D flexibility.
- Batch Freeze-Drying:Small-volume pharmaceutical and nutraceutical producers value equipment mobility and rapid changeover.
Tray freeze-drying commands the majority of installed pharmaceutical capacity. Rotary freeze-drying is gaining share fastest in food applications.
Application:
Use case determines moisture specification stringency—laboratory applications tolerate wider variance than commercial pharmaceutical release.
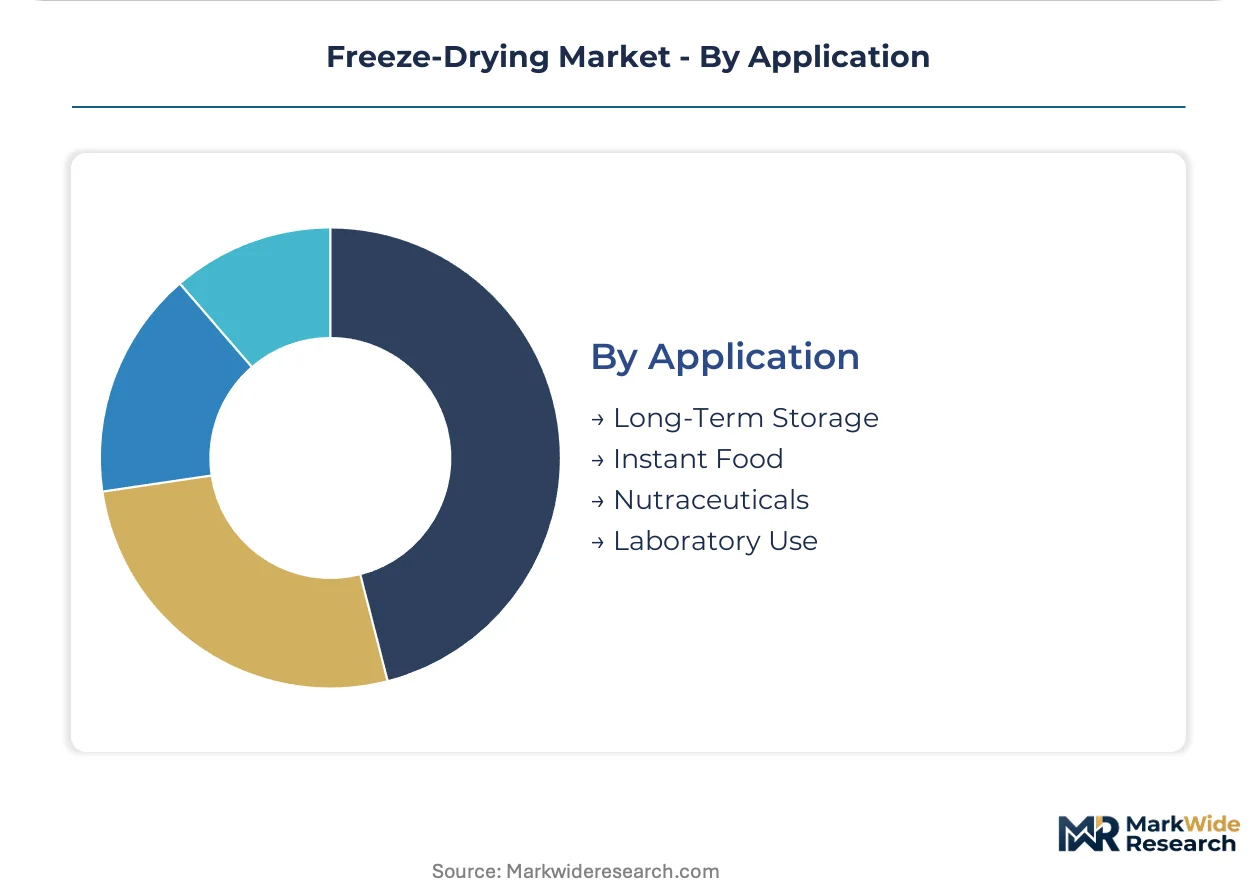
- Long-Term Storage:Vaccine stockpiling and strategic medical reserves require validated 25-year stability data under WHO temperature excursion protocols. National health authorities in Saudi Arabia and the United States maintain dedicated lyophilization capacity for emergency preparedness.
- Instant Food:Backpacking meals and military rations prioritize weight reduction and rapid reconstitution without cooking infrastructure. Manufacturers in France and Japan supply NATO and domestic defense procurement channels.
- Nutraceuticals:Probiotic and enzyme preservation demands precise thermal control to maintain bioactivity.
- Laboratory Use:Academic and contract research organizations require flexible pilot systems for method development.
Long-term storage dominates capital deployment in government and institutional channels. Instant food is where commercial volume expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA stability guidelines for parenteral biologics anchor United States demand, while EMA Annex 1 protocols and China's NMPA reforms are compressing equipment replacement cycles across three distinct regulatory zones. National health authorities and contract manufacturing expansion are reshaping capacity deployment.
United States
Monoclonal antibody manufacturers in Massachusetts and California operate multi-ton freeze-drying suites under FDA cGMP scrutiny. The agency's 2023 stability guideline updates mandate validated lyophilization protocols for biologics distribution. CDMOs in North Carolina and New Jersey are adding commercial capacity to capture outsourced production from originator pharmaceutical companies.
Germany
EMA Annex 1 sterile manufacturing guidelines force pharmaceutical manufacturers to upgrade legacy equipment against stricter contamination control standards. The country's national pharmaceutical regulator enforces continuous process verification requirements. Industrial clusters in Bavaria and Baden-Württemberg host specialized containment-integrated lyophilizer production for European biologics manufacturers.
China
NMPA reforms align domestic pharmaceutical manufacturing standards with FDA and EMA precedents, accelerating lyophilization adoption for parenteral drugs. The country's national pharmaceutical regulator mandates validated freeze-drying protocols under revised biologics guidelines. Contract manufacturing organizations in Jiangsu and Zhejiang provinces are scaling commercial capacity to serve domestic and export markets.
Switzerland
Swissmedic oversees monoclonal antibody production requiring sub-3% residual moisture and extensive documentation. The national pharmaceutical regulator maintains alignment with EMA standards while preserving independent inspection protocols. Basel and Zurich host biologics manufacturers deploying digital twin platforms to reduce lyophilization cycle development time.
India
CDSCO pharmaceutical manufacturing standards are tightening under production-linked incentive schemes for active pharmaceutical ingredient and formulation manufacturing. The national pharmaceutical regulator is harmonizing lyophilization validation requirements with FDA precedents. Maharashtra and Gujarat are driving domestic capacity investment by multinational and local producers seeking import substitution.
Freeze-Drying Market Key Industry Players
Full-service lifecycle contractors and specialized equipment fabricators split the market between integrated containment portfolios and isolator-integrated designs for potent compound handling. European and Asian suppliers dominate commercial pharmaceutical production systems, while North American vendors anchor laboratory and pilot-scale segments. Strategic consolidation centers on multi-year service agreements and technology convergence with isolator systems. Capacity expansion and geographic licensing arrangements represent the dominant competitive moves.
Within the integrated solutions tier, GEA Group AG and Telstar S.A.U. exemplify European full-service positioning, while Millrock Technology Inc. occupies the North American laboratory-specialist vector. Shanghai Tofflon Science Technology Co. Ltd. represents Chinese scale-driven fabrication. HOF Sonderanlagenbau GmbH and Martin Christ Gefriertrocknungsanlagen GmbH anchor German precision-engineering archetypes. These six named entities collectively span the geographic and technological breadth of installed pharmaceutical capacity.
| Leading Market Players |
|---|
| Millrock Technology Inc. |
| HOF Sonderanlagenbau GmbH |
| GEA Group AG |
| Martin Christ Gefriertrocknungsanlagen GmbH |
| Shanghai Tofflon Science Technology Co. Ltd. |
| Telstar S.A.U. |
| SP Industries Inc. |
| IMA S.p.A. |
| Cuddon Freeze Dry |
| Others |
Cost & Logistics Intelligence
Undercapacity in German commercial lyophilization suites drives both equipment vendor pricing power and pharmaceutical buyer willingness to accept multi-year service contracts. CDMOs competing for monoclonal antibody manufacturing slots absorb premium positioning from European equipment suppliers while food processors in California and Brazil negotiate harder on stainless steel tray systems with shorter replacement cycles.
Pricing Analysis
Geographic price spreads of 30-40% separate German and Swiss pharmaceutical-grade installations from Southeast Asian food-processing configurations. Three-tier pricing structure across premium containment-integrated, standard cGMP-compliant, and economy pilot-scale levels dominates equipment procurement. Price differentiation rests on EMA Annex 1 certification status and isolator integration depth. Cost compression in standard-tier tray systems is intensifying because Chinese fabricators are scaling stainless steel production capacity. Regional snack manufacturers in Vietnam and Indonesia exhibit highest price sensitivity, while Massachusetts biologics producers prioritize validation documentation over capital expenditure minimization.
Supply Chain Analysis
Tariff exposure between Germany and China dominates strategic sourcing discussions for vacuum pump assemblies and precision refrigeration components. Equipment fabrication draws from specialized stainless steel suppliers in Germany, vacuum technology specialists in Japan, and control system integrators in the United States. Critical dependencies include medical-grade 316L stainless steel, oil-free vacuum pumps, and ultra-low-temperature refrigerants subject to EU F-Gas Regulation phase-down schedules. Single-source vulnerability concentrates in Japanese scroll compressor technology for −80°C condenser performance. Distribution runs through direct OEM sales forces for pharmaceutical accounts and regional equipment distributors serving food processing buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spray-drying substitution for protein formulations with moderate thermal tolerance threatens freeze-drying's addressable market in select therapeutic categories, forcing incumbents to defend through validation depth and bioactivity preservation guarantees.
For Market Incumbents: Pre-empt spray-drying substitution by anchoring long-term service contracts around continuous process verification capabilities that alternative drying technologies cannot replicate. Invest in isolator-integrated containment systems for oncology and hormone manufacturing where potency handling requirements create defensible moats. Backward integration into stainless steel fabrication secures supply continuity against German and Japanese component concentration.
For New Entrants and Emerging Players: Establish a beachhead in South Korean specialty coffee and Australian pet nutrition segments where pharmaceutical-grade lyophilization expertise commands premium positioning against commodity freeze-drying suppliers. Target probiotic and enzyme preservation applications requiring precise thermal control that food-grade equipment cannot achieve. Lead with digital twin-enabled cycle development services that compress customer time-to-market versus incumbent empirical optimization approaches.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across isolator-integrated containment systems as EMA Annex 1 guidelines mandate continuous process verification infrastructure. Mid-scale CDMOs with validated multi-product lyophilization suites represent acquisition targets with defensive revenue visibility. Monitor NMPA reform implementation velocity in China as the signal indicating whether domestic capacity investment will absorb multinational fabrication output or trigger regional price competition.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Integration | Opens high-margin oncology manufacturing segments under EMA Annex 1 containment requirements. |
| Digital Twin Platform Deployment | Reduces Massachusetts biologics manufacturers' cycle development timelines by half. |
| Alternative Refrigerant Transition | Ensures German pharmaceutical manufacturers avoid operational disruption from EU F-Gas phase-down. |
| Captive Service Engineering Teams | Reduces Danish multi-site producers' reliance on OEM maintenance networks. |
| India PLI-Aligned Capacity Investment | Captures production-linked incentive flows for API and formulation manufacturing. |
Research Approach
A spread of perspectives from pharmaceutical manufacturing executives, regulatory affairs leads at biologics firms, CDMO procurement directors, and aftermarket service heads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA cGMP guidance documents, EMA Annex 1 sterile manufacturing guidelines, and ISO 13485 quality management certifications. Trade data from German and Japanese vacuum technology exports, SEC filings from listed equipment suppliers, and pharmaceutical manufacturing capacity announcements triangulated bottom-up unit economics with top-down market sizing.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation by product type, end-user industry, technology architecture, and application use case. Pharmaceutical validation cycle duration, food processing harvest seasonality, and equipment utilization rate assumptions informed replacement frequency and capacity expansion timelines. CAGRs derived from regression analysis of historical equipment shipment data against biologics pipeline expansion and CDMO contract award patterns.
Sensitivities concentrate around NMPA reform implementation pace, EU F-Gas refrigerant availability constraints, and spray-drying technology advancement in protein formulation stability. Forecasts reflect documented assumptions about regulatory convergence timelines and contract manufacturing outsourcing velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Commercial Kettles and Braising Pans Market
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Food Waste Shredder Market
Food Processing Equipment
Europe Commercial Sous Vide Machine Market
Food Processing Equipment
Tunnel Oven Market
Food Processing Equipment
Defrosting & Thawing Equipment for Food Market
Food Processing Equipment
Electric Chicken Scalder Market
Food Processing Equipment
Coffee Processing Machine Market
Food Processing Equipment
Dehydrators Market
Food Processing Equipment
Food Ultrasound Market
Food Processing Equipment
Gas Convection Oven Market
Food Processing Equipment
Craft Beer Saccharification Equipment Market
Food Processing Equipment
Commercial Wood Fired Pizza Oven Market
Food Processing Equipment
Commercial Oven Market
Food Processing Equipment
Food and Beverages Air Filters Market
Food Processing Equipment
Pasteuriser Market