
 Brewery Equipment Market | 2026-2036
Brewery Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Brewery Equipment Market Intelligence
The unbundling of large-scale systems into modular, scalable components for smaller producers is shifting buyer preferences away from monolithic installations. This trend favors suppliers with diverse portfolios. GEA Group leverages its engineering depth in thermal processing and separation. Krones AG dominates the high-capacity packaging and filling segment for large-scale production, while Alfa Laval specializes in efficient fluid handling solutions like wort coolers.
Brewery equipment encompasses the integrated system of vessels, machinery, and controls used to process raw ingredients into finished beer. This includes stainless steel Fermentation Tanks, often grade 304, designed for precise temperature control and sanitation via Clean-in-Place (CIP) systems. Automated Control systems are becoming standard, moving beyond large-scale production to enhance consistency in the Microbreweries segment. While Brewing Kettles and Filtration Systems are mature categories, demand for advanced Energy Recovery technology is creating new value.
Equipment design and market access are governed by stringent food contact and safety standards. The FDA's rules in the United States and Europe's CE marking directives mandate specific material traceability and hygienic design. Compliance with ISO manufacturing standards is also a key differentiator for suppliers. Future purchasing decisions will prioritize vendors whose systems can meet evolving energy efficiency rules and demonstrate clear compliance pathways.
Market Dynamics
The central dynamic shaping the brewery equipment market is the bifurcation of demand. Large-scale brewers prioritize throughput and efficiency, while the expanding craft segment demands modularity, scalability, and automation to ensure product consistency across smaller, more varied batches.
Growth Catalysts
- Craft Brewing Expansion:The proliferation of microbreweries and brewpubs globally creates sustained demand for smaller-footprint, flexible systems capable of producing diverse beer styles without requiring the scale of macro-brewery installations.
- Automation for Consistency:The integration of automated control systems is moving downstream to smaller producers who seek to replicate product quality and optimize processes, reducing reliance on manual intervention and enhancing batch-to-batch consistency.
- Energy Efficiency Focus:Mandates associated with initiatives like the EU Green Deal are driving investment in equipment with advanced energy recovery systems, creating a value-add proposition for suppliers who can demonstrate lower operational costs.
Market Restraints
- High Capital Investment:The significant upfront cost of complete brewing systems, particularly stainless steel fermentation tanks and automated packaging lines, acts as a major barrier to entry for startups and small-scale breweries.
- Raw Material Price Volatility:The market is sensitive to price fluctuations in key commodities, especially food-grade 304 stainless steel, which can directly impact equipment manufacturing costs and final pricing for customers.
- Complex Regulatory Compliance:Adhering to stringent food safety standards, such as the FDA's rules in the United States and CE marking in Europe, requires significant investment in hygienic design, material traceability, and validation.
Strategic Opportunities
- Water Management Solutions:Growing environmental concerns and water scarcity in key brewing regions create an opportunity for equipment suppliers to integrate advanced water treatment and reclamation technologies into their systems. -
- Digital Twin and Simulation:Offering software for process modeling allows brewers to optimize recipes, train staff, and predict outcomes without consuming raw materials, opening a new high-margin service revenue stream.
- Turnkey Systems for Emerging Markets:Demand for complete, ready-to-install microbrewery packages is rising in developing regions, particularly in parts of Latin America and Southeast Asia, offering new geographic growth avenues.
Industry Challenges
- Skilled Labor Shortages:A deficit of technicians and brewers with the expertise to operate, maintain, and troubleshoot increasingly complex automated brewing systems can limit the operational efficiency gains promised by new technology.
- Integration with Legacy Systems:Established breweries face significant technical challenges and downtime when integrating modern, modular components with older, pre-existing infrastructure, delaying modernization projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brewery Equipment Market |
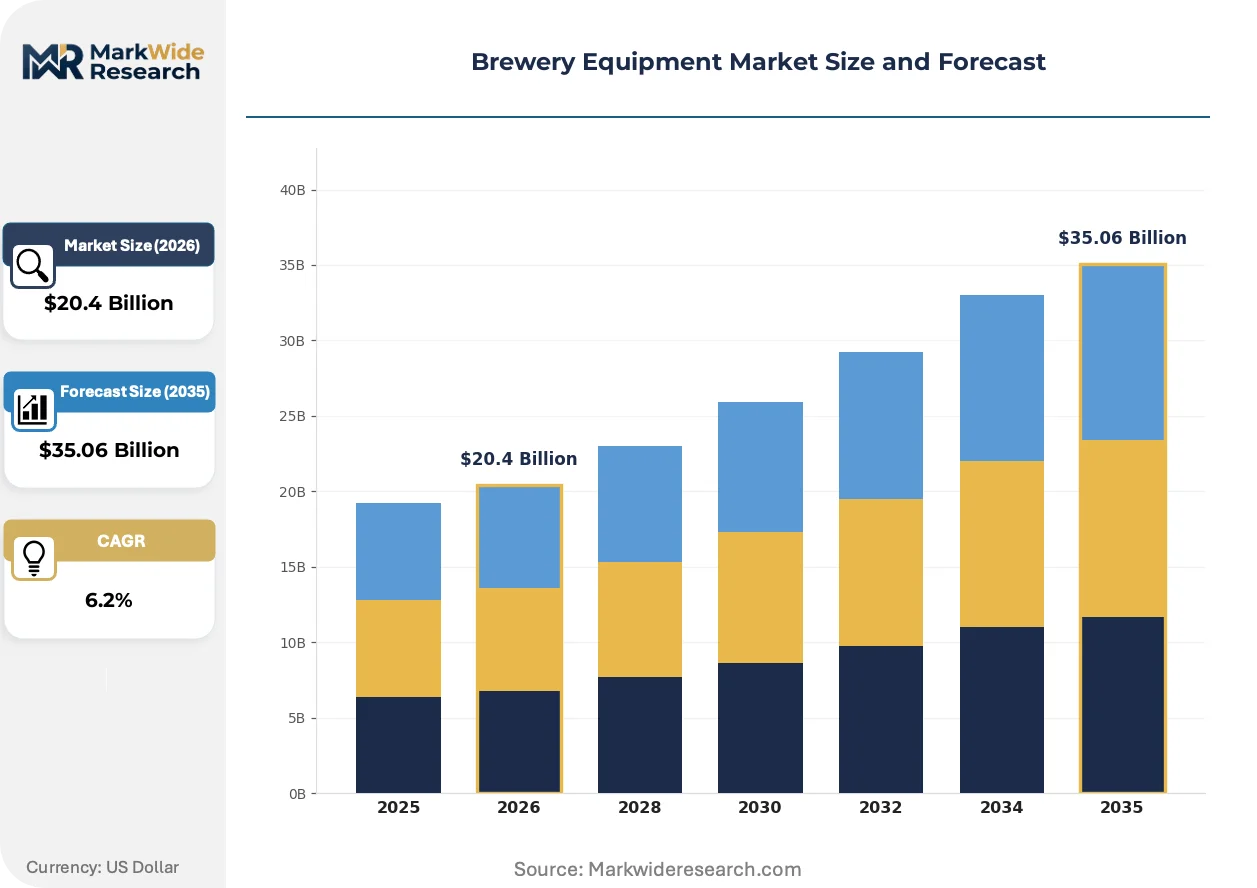
| Market Size in 2026 | $20.4 Billion |
| Market Size in 2035 | $35.06 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fermentation Tanks, Filtration Systems, Brewing Kettles, Wort Coolers, Grain Handling Equipment, Packaging Machines Technology: Automated Control, Sensor Integration, Thermal Processing, Liquid Handling, CIP Systems, Energy Recovery Application: Microbreweries, Craft Brewers, Large-scale Production, Brewpubs, Contract Brewing, Home Brewing End User: Brewing Companies, Beverage Manufacturers, Hospitality Sector, Research Institutions, Distributors, Equipment Suppliers |
| Companies Covered | Paul Mueller Company, Della Toffola USA, GEA Group, Hypro, Kaspar Schulz, Krones AG, Criveller Group, Meura, Alfa Laval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brewery Equipment Market Strategic Shifts & Innovations
Digitalization and sustainability are reshaping equipment design and function. The push for greater process control is driving the adoption of sensor technology, while resource efficiency is becoming a core competitive differentiator mandated by both regulation and operational cost pressures.
Advanced sensor technology for real-time monitoring of parameters like dissolved oxygen and specific gravity is becoming more accessible. Mid-sized and craft breweries are the primary adopters, seeking to emulate the process consistency of larger industrial operations. This use of continuous data feedback is consolidating multiple quality control steps into a single automated loop, reducing the need for manual sampling and shortening production timelines.
Heightened regulatory scrutiny over food contact materials is a defining trend. Rules like the FDA's Food Safety Modernization Act (FSMA) and Europe's CE directives require verifiable material traceability and hygienic design principles. This forces equipment manufacturers to secure their supply chains and provide extensive compliance documentation. Component suppliers for items like gaskets and valves are most affected, facing increased costs to meet certification demands.
A preference for flexible financing models is altering purchasing behavior, especially among new market entrants. The traditional capital expenditure purchase is being supplemented by leasing options and service-based contracts that lower the initial investment barrier. This shift is most visible within the craft brewery segment in North America and Europe, where it enables startups to access sophisticated technology sooner.
Brewery Equipment Market Segmentation
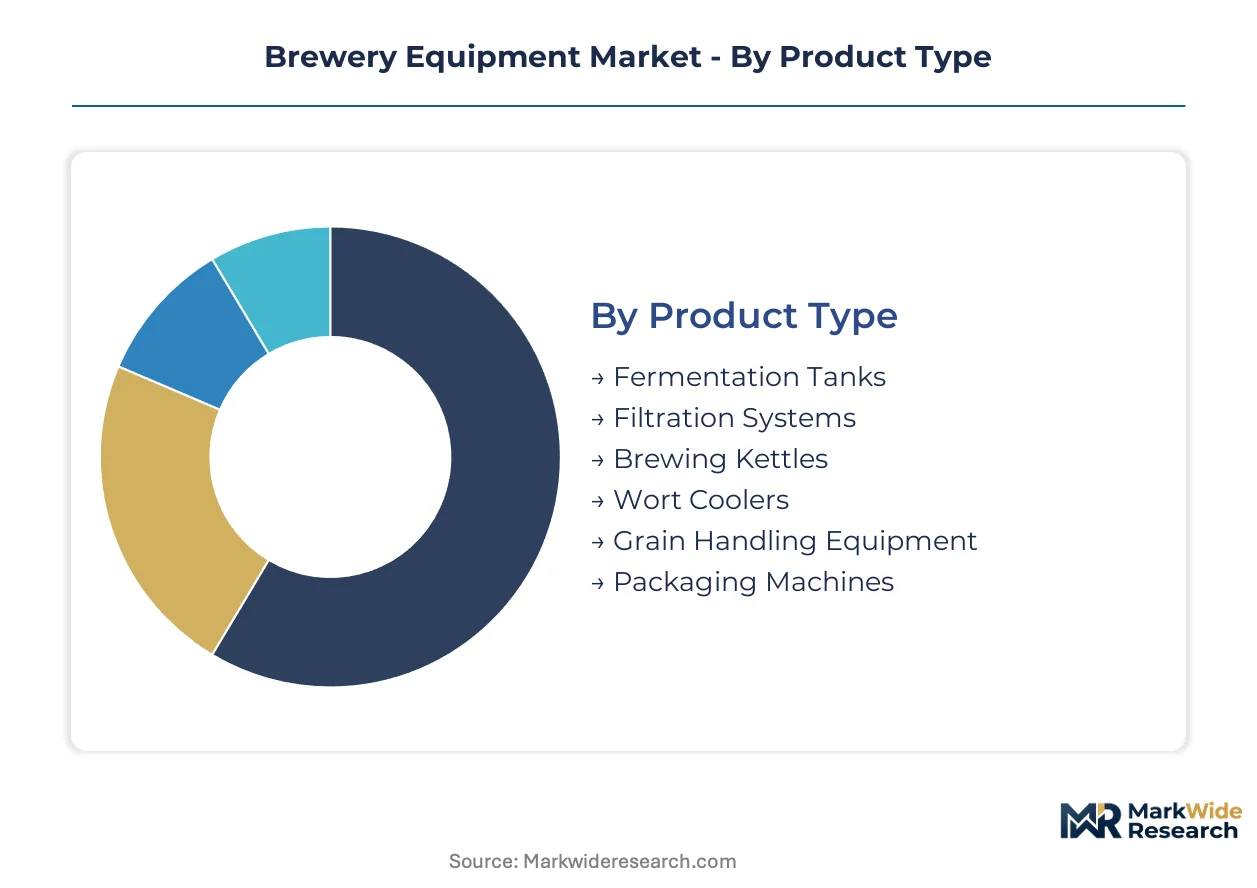
Understanding the brewery equipment market requires a granular view of its diverse components and applications. Segmentation illuminates the varying capital requirements, technological advancements, and end-user demands shaping purchasing decisions. This detailed breakdown highlights areas of concentrated investment and emerging growth across the brewing industry.
Product Type:
Segments within product type exhibit widely varying capital investment requirements, directly influencing market entry and expansion strategies for brewers.
- Fermentation Tanks:Stainless steel vessels, often grade 304, designed for precise temperature control and sanitation via Clean-in-Place (CIP) systems. Demand concentrates in craft breweries in Germany and the United States, driven by the need for consistent batch quality.
- Packaging Machines:Automated systems for bottling, canning, or kegging finished beer, ensuring product integrity and shelf-life. Investment is significant for large-scale production facilities in countries like Brazil and China, prioritizing high throughput and reduced labor costs.
- Filtration Systems:Equipment for clarifying beer, removing yeast and particulates for desired product clarity.
- Brewing Kettles:Vessels for boiling wort, facilitating hop isomerization and sterilization.
- Wort Coolers:Heat exchangers rapidly reducing wort temperature, crucial for yeast health.
- Grain Handling Equipment:Systems for milling, conveying, and storing malt, optimizing raw material preparation.
Most installed capacity flows through Brewing Kettles. Expansion is steepest in Packaging Machines.
Technology:
Technological advancements are primarily driven by the pursuit of operational efficiency and product consistency across diverse brewing scales.
- Automated Control:Advanced programmable logic controllers (PLCs) and software manage brewing parameters, standardizing production processes. This technology sees concentrated adoption in microbreweries across Europe, aiming to reduce human error and enhance batch reproducibility.
- Energy Recovery:Systems designed to capture and reuse heat or cooling energy, significantly reducing utility consumption and operational expenditure. Demand is pronounced in established markets like Canada and Australia, driven by stringent environmental regulations and rising energy costs.
- Sensor Integration:Real-time monitoring for critical parameters like dissolved oxygen, improving process control.
- Thermal Processing:Equipment for heating and cooling, vital for sanitation and product stability.
- Liquid Handling:Pumps, valves, and piping for efficient, hygienic transfer of liquids.
- CIP Systems:Automated cleaning units ensuring hygienic conditions within vessels and pipework.
Efficiency gains are central to CIP Systems. Innovation focuses on Energy Recovery.
Application:
Application segments reflect the varied operational scales and business models within the brewing industry, from artisanal producers to industrial giants.
- Large-scale Production:Industrial brewing operations characterized by high volume, continuous processes, and extensive automation for global distribution. Investment concentrates in emerging markets like India and Mexico, driven by increasing domestic beer consumption.
- Craft Brewers:Independent breweries focusing on diverse beer styles, often with smaller batch sizes and a strong emphasis on product innovation. Demand is robust in the United States and the United Kingdom, where consumer preference for local and specialty beers is high.
- Microbreweries:Small-scale commercial breweries producing limited quantities, often for local markets.
- Brewpubs:Establishments combining a brewery with a pub, producing beer for on-premise consumption.
- Contract Brewing:Production of beer by one brewery for another brand, requiring flexible solutions.
- Home Brewing:Non-commercial production by individuals, using smaller, less complex equipment.
The largest installed base resides within Large-scale Production. New market entrants favor Microbreweries.
End User:
End-user categories delineate where brewery equipment is deployed within the broader beverage and hospitality value chain, impacting purchasing motivations.
- Brewing Companies:Dedicated enterprises focused solely on beer production, ranging from global conglomerates to regional craft operations. Their purchasing decisions prioritize efficiency, scalability, and compliance with food safety regulations in markets like Japan and Australia.
- Hospitality Sector:Hotels, restaurants, and specialized brewpubs that integrate brewing operations to enhance customer experience and diversify revenue streams. Demand for compact, aesthetically pleasing systems is visible in urban centers across France and Italy.
- Beverage Manufacturers:Companies producing varied beverages, integrating brewing lines for specific products.
- Research Institutions:Labs using small-scale equipment for studies, product development, and quality control.
- Distributors:Supply chain entities investing in equipment for demonstration or rental.
- Equipment Suppliers:Manufacturers using equipment for testing, prototyping, or internal R&D.
Primary purchasing power resides with Brewing Companies. Growth in ancillary services is driven by Equipment Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The brewery equipment industry traces its foundational engineering to Europe, particularly Germany, where ancient traditions met industrial innovation. This historical depth now converges with modern demand patterns, driving equipment deployment across diverse global markets.
Germany
Germany maintains strong demand for complete brewing systems, driven by established traditions and stringent quality standards. Manufacturers adhere to CE marking directives, ensuring high product safety and material traceability. Bavaria concentrates equipment suppliers specializing in precision engineering for traditional and craft breweries.
United States
Craft brewing expansion drives significant demand for flexible, scalable systems across the United States. Suppliers comply with the FDA's stringent rules for food contact materials and hygienic design. The Pacific Northwest showcases a high concentration of microbreweries adopting advanced automation technologies.
China
China's expanding domestic beer consumption fuels robust demand for high-capacity packaging machines and large-scale production systems. Equipment must meet rigorous GB standards for safety and quality. The Yangtze River Delta region features numerous industrial zones supporting large-scale brewery operations and specialized equipment fabrication.
Canada
Canadian brewers prioritize energy recovery systems and automated control technologies to optimize operational costs and sustainability. Health Canada regulations guide hygienic design and material selection for all food-contact equipment. Ontario exhibits a growing cluster of craft breweries investing in advanced, energy-efficient brewing solutions.
Brazil
Brazil experiences investment in large-scale production facilities alongside rising demand for complete microbrewery packages. ANVISA sanitary regulations dictate equipment specifications and operational hygiene. São Paulo concentrates major brewing companies and a burgeoning craft beer scene, driving diverse equipment procurement.
Brewery Equipment Market Key Industry Players
The competitive structure tilts toward a blend of established industrial engineering conglomerates and specialized equipment manufacturers. The market exhibits a tiered consolidation, with a few large players dominating high-capacity segments and a broader base of smaller firms serving niche craft brewery needs. Three strategic archetypes emerge: comprehensive solution providers, specialized component manufacturers, and regional turnkey system integrators. Competitive moves focus on portfolio diversification into automation and energy recovery, alongside strategic partnerships to offer complete brewing solutions.
Scale-driven industrial players like Germany-based GEA Group and Krones AG exemplify comprehensive engineering capabilities across the brewing equipment spectrum. GEA Group, an AG, represents a broad portfolio in thermal processing and separation technologies. Krones AG, also an AG based in Germany, anchors the high-capacity packaging and filling segment for large-scale production facilities. Sweden-based Alfa Laval, another AG, occupies a distinct position specializing in efficient fluid handling solutions such as wort coolers. These entities collectively underscore the market's reliance on robust engineering and specialized component expertise.
| Leading Market Players |
|---|
| Paul Mueller Company |
| Della Toffola USA |
| GEA Group |
| Hypro |
| Kaspar Schulz |
| Krones AG |
| Criveller Group |
| Meura |
| Alfa Laval |
| Others |
Cost & Logistics Intelligence
Craft brewers' preference for modular, scalable components forces suppliers to diversify portfolios, impacting equipment pricing structures by emphasizing value-added flexibility over sheer throughput. This shift creates distinct pricing tiers for customized solutions versus standardized offerings.
Pricing Analysis
A value-based, project-oriented pricing model dominates the brewery equipment market for complete systems. Price differentiation stems from stringent compliance standards like CE marking and FDA regulations, alongside the level of customization for specific brewing processes. Pricing pressure on upfront capital expenditure intensifies due to high entry barriers for new market participants. Startups and microbreweries demonstrate the highest price sensitivity, often seeking flexible financing solutions.
Supply Chain Analysis
Refurbishment programs for brewery equipment extend asset lifespans, integrating circular economy principles into the supply chain. Geographic supply concentration for core manufacturing resides in Germany, known for precision engineering, and China, for high-volume fabrication. The market relies heavily on food-grade 304 stainless steel and specialized components like gaskets and valves. Raw material price volatility, particularly for stainless steel, presents a significant structural risk. Distribution runs primarily through direct sales channels and specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The brewery equipment market presents a clear margin-expansion story, driven by the increasing adoption of energy recovery systems that reduce operational costs for brewers.
For Market Incumbents:Anticipate continued demand for integrated solutions by actively diversifying portfolios into advanced automation and energy recovery technologies. Form strategic partnerships with specialized component manufacturers to offer complete brewing systems. This approach counters threats from niche players and addresses integration challenges with legacy systems. Invest in engineering depth and R&D for next-generation automated controls.
For New Entrants and Emerging Players:Underserved microbreweries in emerging markets represent a significant white-space opportunity. Focus on providing turnkey microbrewery packages for regions like Latin America and Southeast Asia. Integrate advanced water management solutions as a core offering to differentiate. A go-to-market strategy leveraging flexible financing models, such as leasing and service-based contracts, lowers initial investment barriers for these segments.
For Investors and Strategic Acquirers:Asymmetric upside sits with specialized component manufacturers offering advanced digitalization and sustainability solutions. Long-term viability hinges on companies that can deliver energy-efficient and highly automated systems across diverse scales. Target firms specializing in sensor technology, process controls, or water reclamation for strategic acquisitions. The adoption rate of advanced sensor technology in craft breweries serves as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Advanced Energy Recovery Systems | Reduces operational costs for brewers, enhancing profitability and sustainability. |
| Platform Integration: Digital Twin Software | Optimizes brewing processes and staff training, minimizing raw material waste. |
| Strategic Partnership: Water Treatment Technology Providers | Addresses water scarcity concerns, creating value-added systems for brewers. |
| Geographic Expansion: Turnkey Microbrewery Packages in Emerging Markets | Captures new demand in developing regions with growing beer consumption. |
| Certification Investment: Enhanced Hygienic Design Standards | Ensures compliance with evolving food safety regulations like FDA and CE marking. |
Research Approach
Bottom-up microbrewery application modeling reconciled against top-down large-scale production tracking forms the analytical core for this report. This approach integrates extensive primary interviews with brewing company executives, equipment engineers, microbrewery owners, and regulatory compliance officers. Secondary validation draws from FDA rules, CE marking directives, ISO manufacturing standards, and various industry association reports.
Historical trendline analysis informs the forecast framework across the analysis window. The market is segmented by product type, technology, application, end-user, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical data and projected market dynamics. Key industry-specific forecast inputs include craft brewing expansion rates and 304 stainless steel commodity prices.
Underlying measurement precision varies by segment; fermentation tanks and packaging machines carry tighter precision than others. Forecasts reflect assumptions concerning technological advancements and market adoption rates. Practitioners should monitor raw material price volatility and evolving energy efficiency rules for early signals of market shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Spray Dryer Market
Food Processing Equipment
Food and Beverages Air Filters Market
Food Processing Equipment
Philippines Cold Storage Warehouse Market
Food Processing Equipment
Global Automatic Mask Production Equipment Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market
Food Processing Equipment
North America Commercial Sous Vide Machine Market
Food Processing Equipment
Freezers Market
Food Processing Equipment
Soda Production Machine Market
Food Processing Equipment
Homogenizers Market
Food Processing Equipment
Nut Processing Machine Market
Food Processing Equipment
Global Carbonated Beverage Processing Equipment Market
Food Processing Equipment
Ice Flaking Machine Market
Food Processing Equipment
Tunnel Oven Market
Food Processing Equipment
Food Ingredients Sterilization Market
Food Processing Equipment
Countertop Blast Chiller Market
Food Processing Equipment
Global Food Processing Market