
 Glass Processing Equipment Market | 2026-2036
Glass Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Processing Equipment Market Analysis
Equipment leasing and project finance models are reshaping competitive entry in glass processing machinery, lowering capital barriers for mid-size fabricators. Glaston Corporation leverages its vertical integration into tempering furnace technology to sustain premium positioning. Bavelloni S.p.A. anchors its competitiveness through deep specialization in grinding and polishing systems. Lisec Austria GmbH dominates automated insulating glass lines across European architectural supply chains.
Glass processing equipment encompasses machinery for cutting, edging, tempering, laminating, and inspecting flat or hollow glass, operating at temperatures exceeding 600°C for thermal strengthening and achieving optical tolerances within 0.1 mm for display-grade substrates. Its primary purpose is transforming raw glass sheets into value-added components for construction, transportation, and electronics. Cutting machines occupy the largest installed base among product types, though automated systems integrating robotics and CNC technology command the highest margin pools due to labor substitution and yield improvements. Display glass applications represent the fastest-growing demand segment, driven by OLED substrate expansion and foldable device manufacturing requirements.
The EPA enforces emissions standards on glass melting furnaces under the National Emission Standards for Hazardous Air Pollutants, compelling equipment upgrades with regenerative thermal oxidizers. REACH and RoHS in Europe restrict heavy metals in glass coatings, redirecting R&D toward lead-free formulations and compatible processing methods. China's MEE implements dual carbon compliance audits that disqualify outdated soda-lime production lines. Stakeholders must monitor how fragmented national efficiency standards fragment equipment certification requirements and shape regional supplier qualification.
Market Dynamics
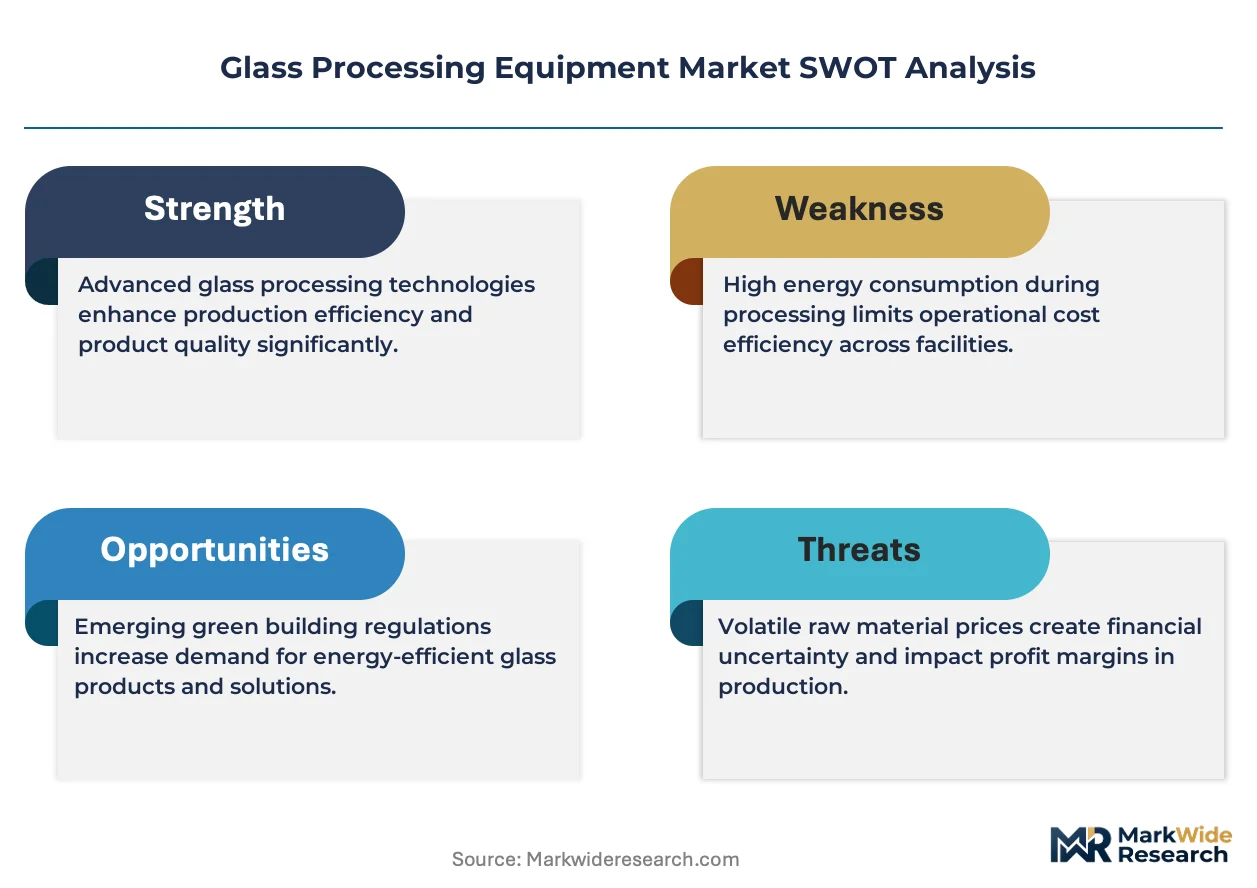
China's dual carbon compliance audits are forcing furnace upgrades across soda-lime production lines, compressing replacement cycles and concentrating demand among certified equipment suppliers.
Growth Catalysts
- Building energy codes:Germany's EnEV and China's GB 50189 mandate high-performance glazing, accelerating insulating glass line investments.
- Solar panel expansion:Tempered glass capacity additions by photovoltaic manufacturers are pulling tempering furnace orders.
- REACH and RoHS:Heavy metal restrictions in European coatings redirect R&D toward lead-free processing methods.
Market Restraints
- Natural gas price volatility:Thermal processing costs fluctuate with European energy markets, squeezing furnace operator margins.
- Supplier concentration:Germany's Baden-Württemberg cluster controls critical tempering technology, creating single-source risk.
- Optical tolerances:Display-grade substrate requirements at 0.1 mm precision limit viable machine suppliers.
Strategic Opportunities
- Equipment leasing models:Project finance structures lower capital barriers for mid-size fabricators in India.
- Foldable device manufacturing:Ultra-thin glass processing for OLED substrates opens premium equipment segments.
- Regenerative thermal oxidizers:EPA NESHAP compliance creates aftermarket retrofit demand across US glass melting operations.
Industry Challenges
- CNC programming expertise:Automated cutting and edging systems require specialized technicians scarce in emerging manufacturing bases.
- Legacy system integration:Brownfield facilities struggle to synchronize new robotic handling with existing conveyor architectures.
- Multi-jurisdiction certification:Fragmented national efficiency standards force redundant testing for equipment exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Processing Equipment Market |
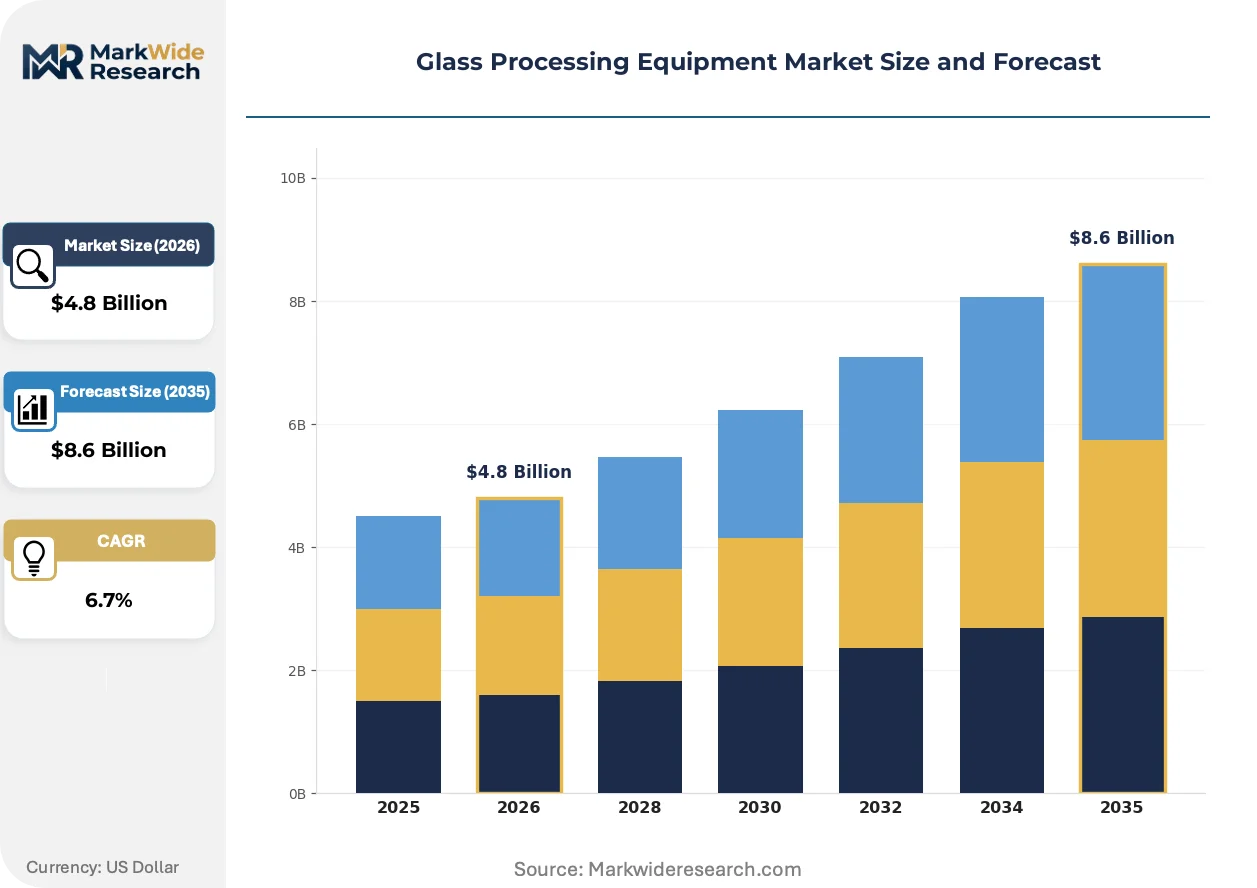
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cutting Machines, Grinding Machines, Washing Systems, Inspection Equipment Technology: Laser Technology, CNC Technology, Robotics, Automated Systems Application: Automotive Glass, Architectural Glass, Consumer Glass, Display Glass End User: Manufacturers, Fabricators, Retailers, Contractors |
| Companies Covered | Glaston Corporation, Bavelloni S.p.A., Lisec Austria GmbH, Qingdao North Glass Automation Co., Ltd., Intermac S.p.A., Bottero S.p.A., Hegla GmbH & Co. KG, Gentex Corp., Bystronic Glass AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Processing Equipment Market Emerging Trajectories
Digital control systems and thermal efficiency technologies are compressing equipment replacement cycles while redefining supplier qualification criteria across architectural and electronics supply chains.
Electromagnetic stirring in glass melting furnaces is rendering obsolete conventional gas-fired homogenization methods. Display glass manufacturers in South Korea and Japan are adopting these systems to reduce bubble defects in thin substrates. The technology is rendering obsolete legacy furnace designs that cannot achieve the thermal uniformity required for foldable device substrates.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants compels regenerative thermal oxidizer installations on existing melting furnaces. Glass container producers in Ohio and Pennsylvania face retrofit deadlines that compress capital deployment timelines. The regulatory pressure is fragmenting equipment certification requirements as state-level air quality boards impose supplemental testing protocols.
Outcome-based service contracts are displacing traditional equipment purchase models among European insulating glass fabricators. Lisec Austria GmbH and competitors now bundle performance guarantees with automated line installations, transferring operational risk from buyers to suppliers. This restructuring concentrates most visibly in Germany's architectural glass supply chains where labor substitution yields dominate investment decisions.
Glass Processing Equipment Market Segmentation
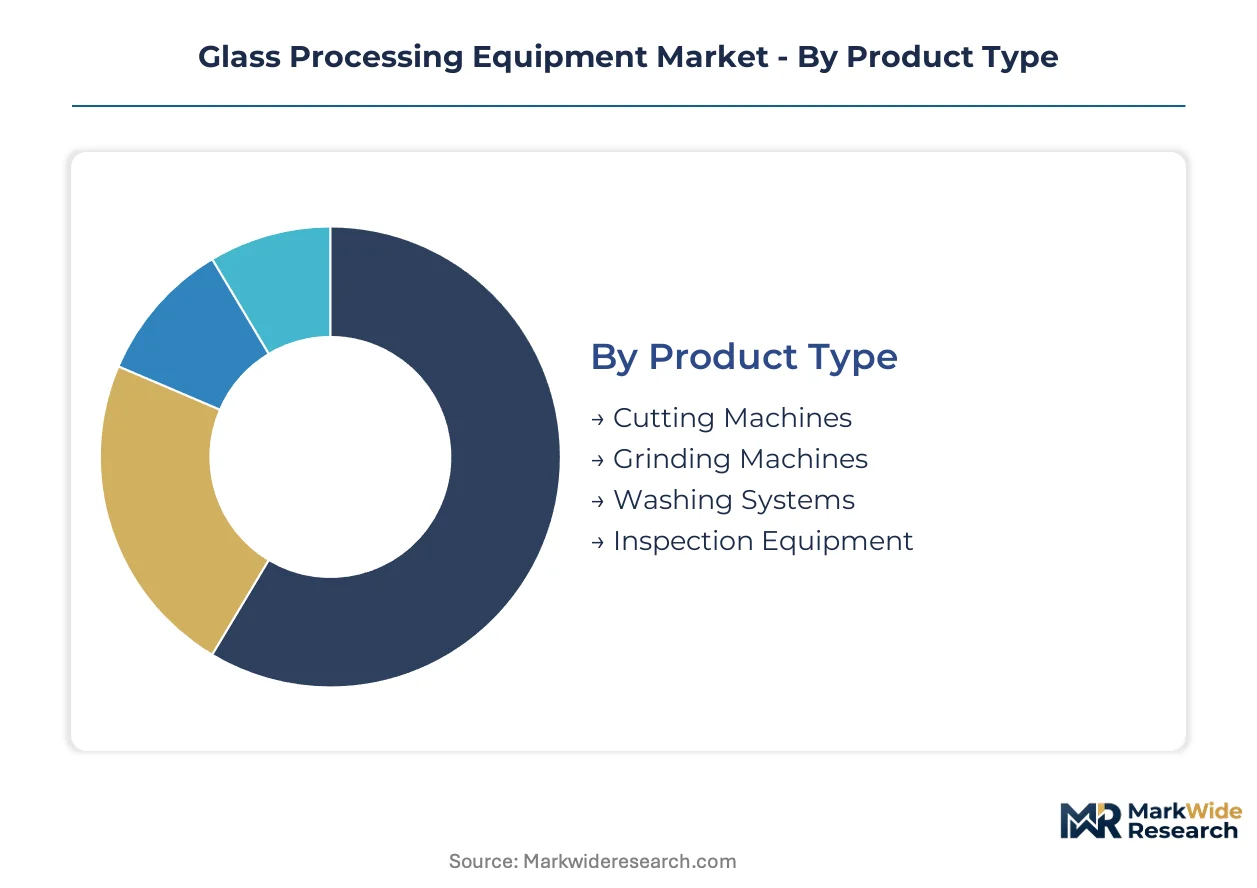
Equipment segmentation in glass processing reveals distinct replacement rhythms and margin profiles across machinery categories. Cycle times range from rapid consumable-driven inspection systems to decade-long furnace investments, shaping supplier revenue predictability and aftermarket service attach rates.
Product Type:
Cutting machines turn over fastest due to blade wear and software obsolescence, while washing systems operate on extended depreciation schedules tied to water treatment infrastructure.
- Cutting Machines:Mechanical scoring and waterjet systems process raw glass sheets with tolerances down to 0.5 mm for architectural panels. Demand concentrates among German fabricators supplying high-performance glazing to meet EnEV energy codes, with replacement cycles compressing as CNC retrofits displace manual scoring tables.
- Grinding Machines:Diamond abrasive systems remove edge defects and shape bevels for automotive windshields. South Korean automotive glass suppliers anchor procurement volumes, driven by OEM requirements for optical clarity in head-up display compatibility.
- Washing Systems:Deionized water rinsing and air-knife drying equipment removes particulate contamination before tempering or coating operations.
- Inspection Equipment:Automated optical and laser scanning systems detect bubble inclusions, thickness variation, and surface defects in real-time production flows.
Cutting machines dominate installed base across fabrication facilities globally. Grinding machines are where expansion concentrates as automotive OEMs tighten optical specifications.
Technology:
Technology tiers stratify by capital intensity and technician scarcity, with automated systems commanding premium pricing against standalone CNC units.
- Laser Technology:CO2 and fiber laser systems enable contact-free cutting of chemically strengthened glass for foldable device substrates. Japanese display glass manufacturers anchor demand, constrained by beam stability requirements at sub-100-micron thicknesses.
- CNC Technology:Computer numerical control drives multi-axis edging and drilling with programmable repeatability for custom architectural shapes. Italian machinery specialists sustain competitive positioning through proprietary motion control software.
- Robotics:Articulated arm systems handle sheet loading, transfer, and stacking in continuous production flows.
- Automated Systems:Integrated lines combining cutting, edging, tempering, and inspection with centralized process control.
CNC technology commands the broadest installed footprint. Automated systems are climbing the fastest as labor costs rise in Indian and Southeast Asian fabrication bases.
Application:
Application segments diverge sharply in thermal processing requirements and optical tolerance thresholds, with display glass imposing the most stringent equipment specifications.
- Display Glass:Ultra-thin substrate processing for OLED and foldable devices requires ion-exchange strengthening and laser separation at 0.1 mm precision. South Korean and Japanese panel manufacturers anchor equipment demand, with substrate thinning trends forcing furnace redesigns for thermal uniformity.
- Automotive Glass:Tempered and laminated windshields, side lites, and sunroofs meet ECE R43 and FMVSS 205 safety standards. German and Czech automotive glass fabricators concentrate procurement of bending furnaces for complex curvature windshields.
- Architectural Glass:Insulating, tempered, and coated products for commercial and residential building envelopes.
- Consumer Glass:Tableware, appliance panels, and decorative items with lower precision requirements.
Architectural glass sustains the largest equipment installed base. Display glass is gaining share fastest as foldable device manufacturing scales.
End User:
End user categories reflect vertical integration depth, with manufacturers capturing captive equipment demand that fabricators must source externally.
- Manufacturers:Primary glass producers operating integrated float lines and downstream processing for captive supply chains. Chinese soda-lime producers anchor furnace orders as MEE dual carbon audits force efficiency upgrades.
- Fabricators:Independent processors purchasing raw glass for custom cutting, tempering, and laminating services. Indian mid-size fabricators increasingly adopt equipment leasing to bypass capital constraints.
- Retailers:Glass merchants and distributors with limited processing capabilities.
- Contractors:Installation-focused entities with minimal in-house fabrication.
Fabricators represent the broadest equipment user base. Manufacturers are where technology upgrade cycles concentrate under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment trade flows concentrate where glass fabrication clusters sit closest to end-use demand, with Germany and China running structural surpluses in specialized machinery while India and Southeast Asia remain net importers of automated processing lines.
Germany
Baden-Württemberg's machinery corridor supplies tempering furnaces and insulating glass lines across European architectural supply chains. The country's EnEV building energy codes mandate high-performance glazing, pulling investment into automated edging and coating equipment. Stuttgart and Mannheim host dense concentrations of CNC grinding specialists serving automotive OEMs.
China
Dual carbon compliance audits from MEE are compressing replacement cycles for soda-lime production furnaces, concentrating demand among certified domestic and European suppliers. GB 50189 energy efficiency standards for commercial buildings accelerate insulating glass adoption in tier-one cities. The Yangtze River Delta and Pearl River Delta clusters anchor tempered glass capacity expansions for solar panel manufacturers.
United States
EPA enforcement of National Emission Standards for Hazardous Air Pollutants compels regenerative thermal oxidizer retrofits on glass melting operations in Ohio and Pennsylvania. Natural gas price volatility in Texas and Louisiana squeezes furnace operator margins, slowing greenfield investments. The Southeast's automotive glass fabrication base sources bending furnaces primarily from German and Italian suppliers.
India
Equipment leasing models are lowering capital barriers for mid-size fabricators in Gujarat and Maharashtra, expanding the addressable market for second-tier machinery suppliers. BIS certification requirements for safety glass in construction create compliance-driven upgrade cycles. The Delhi-Mumbai Industrial Corridor concentrates new insulating glass line installations serving commercial real estate development.
South Korea
Display glass manufacturers in Gyeonggi Province anchor demand for ultra-thin substrate processing equipment at 0.1 mm precision. METI-coordinated technology programs in neighboring Japan indirectly shape equipment specifications through cross-border supply chain integration. The Busan-Ulsan corridor specializes in ion-exchange strengthening systems for foldable device substrates.
Glass Processing Equipment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in grinding, cutting, and thermal processing subsystems. The vendor base stratifies between full-line automation suppliers and single-technology pure-plays, with premium positioning accruing to firms controlling proprietary thermal uniformity IP. Three archetypes dominate: furnace technology specialists, CNC motion control developers, and automated line integrators. Competitive moves concentrate on geographic expansion through distribution partnerships and backward integration into critical consumables.
Within the European specialist tier, Glaston Corporation and Lisec Austria GmbH exemplify divergent strategic positions—one anchored in thermal processing technology, the other in automated insulating glass line integration. Bavelloni S.p.A. occupies a position among Italian machinery developers with deep specialization in grinding and polishing systems. These firms represent how geographic clustering around Baden-Württemberg and Northern Italy shapes competitive differentiation through proximity to automotive and architectural glass demand centers.
| Leading Market Players |
|---|
| Glaston Corporation |
| Bavelloni S.p.A. |
| Lisec Austria GmbH |
| Qingdao North Glass Automation Co., Ltd. |
| Intermac S.p.A. |
| Bottero S.p.A. |
| Hegla GmbH & Co. KG |
| Gentex Corp. |
| Bystronic Glass AG |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European tempering furnace manufacturing is compressing lead times and amplifying pricing power for Baden-Württemberg specialists serving German and Czech automotive glass fabricators. This utilization squeeze simultaneously rewards suppliers with certified thermal uniformity IP and pressures buyers into longer-term offtake commitments.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across automated insulating glass lines and tempering furnaces. Price differentiation centers on CE certification tier and after-sales service bundling, with premium tiers commanding substantial uplifts for regenerative thermal oxidizer compliance. Cost compression in standard-grade CNC grinding systems is intensifying because Italian machinery specialists are absorbing margin erosion to defend share against Chinese competitors. Mid-size Indian fabricators exhibit highest price sensitivity, while South Korean display glass manufacturers prioritize optical tolerance guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from 90 to 180 days are becoming standard for German furnace suppliers serving Indian and Southeast Asian fabricators, with supply-chain finance facilities emerging as competitive differentiators. Manufacturing concentration rests on Germany, Italy, and China for core thermal processing and motion control systems. Critical inputs include precision ceramic rollers, diamond abrasive tooling, and regenerative burner assemblies. Single-source vulnerability concentrates in electromagnetic stirring technology for display glass melting. Distribution runs through direct sales forces for large integrated lines and specialized distributors for standalone cutting and grinding equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where EPA NESHAP compliance and China's MEE dual carbon audits create certification barriers that lock out unqualified suppliers and cement incumbent positions.
For Market Incumbents: Build switching-cost moats through outcome-based service contracts that transfer operational risk from fabricators to equipment suppliers. Deepen captive supply of precision ceramic rollers and diamond tooling to capture aftermarket revenue streams. Defend against emerging Chinese automation specialists by accelerating regenerative thermal oxidizer retrofit certifications for US glass container producers facing EPA enforcement deadlines. For New Entrants and Emerging Players: India's equipment leasing white-space offers the most penetrable entry point, where project finance structures bypass capital constraints among Gujarat and Maharashtra fabricators. Target second-tier CNC grinding and washing systems where Italian and German incumbents have ceded share on price. Pursue distribution partnerships with regional machinery financiers rather than direct sales force buildout. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated insulating glass lines as robotics integration and centralized process control expand system complexity. Acquisition targets should prioritize furnace technology specialists with proprietary thermal uniformity IP and established MEE certification relationships. Monitor EPA enforcement intensity in Ohio and Pennsylvania as the signal for aftermarket retrofit demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Components | Captures precision roller and hearth plate supply chains that German furnace specialists currently outsource. |
| Regenerative Thermal Oxidizer Retrofit Certification | Unlocks EPA NESHAP compliance revenue from Ohio and Pennsylvania glass container producers facing enforcement deadlines. |
| Equipment Leasing Partnership Expansion | Lowers capital barriers for Indian mid-size fabricators in Gujarat and Maharashtra without direct balance sheet exposure. |
| Laser Cutting Technology Licensing | Addresses Japanese and South Korean demand for sub-100-micron display glass processing without full R&D burden. |
| Outcome-Based Service Contract Rollout | Transfers operational risk from German architectural fabricators to suppliers, locking in multi-year revenue predictability. |
Methodological Framework
Desk research of trade association filings, customs records, and equipment certification databases preceded structured interviews with furnace engineering directors, glass fabricator procurement leads, aftermarket service managers, and regulatory compliance officers. Primary fieldwork across Germany's Baden-Württemberg machinery corridor, China's Yangtze River Delta glass clusters, and India's Gujarat fabrication bases validated secondary indicators. Bottom-up equipment shipment tallies were triangulated against top-down glass production capacity estimates.
Forecast assumptions held regulatory enforcement timelines and natural gas price bands within observed ranges across the projection horizon. Segmentation dimensions modeled include product type, technology tier, application precision requirements, and end-user vertical integration depth. CAGRs were derived from replacement cycle compression analysis and regulatory-driven upgrade elasticity. Industry-specific inputs incorporated MEE dual carbon audit schedules and EPA NESHAP compliance deadlines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese automation specialists or accelerated electromagnetic stirring adoption by South Korean display manufacturers would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Hot Food Processing Equipment Market
Food Processing Equipment
Batter Mixer Machines Market
Food Processing Equipment
Plastic Processing Equipment Market
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
Spiral Cooler Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
Countertop Food Blenders Market
Food Processing Equipment
Freshwater Flake Ice Machine Market
Food Processing Equipment
High Speed Oven Market
Food Processing Equipment
Coffee Processing Machine Market
Food Processing Equipment
Mooncake Production Line Market
Food Processing Equipment
Asia-Pacific Commercial Sous Vide Machine Market
Food Processing Equipment
Spray Drying Equipment Market
Food Processing Equipment
Food Waste Shredder Market
Food Processing Equipment
Holding and Proofing Cabinet Market
Food Processing Equipment
Fish Feed Pellet Making Machine Market