
 Global Food Processing Market | 2026-2036
Global Food Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Processing Market Analysis
Subscription-based maintenance contracts for processing line uptime is hardening into a core revenue stream for equipment vendors and integrated food companies alike. Nestlé leverages its global service network to lock in long-term facility management partnerships across emerging markets. JBS anchors its North American protein operations through captive rendering and packaging infrastructure that reduces third-party dependency. PepsiCo differentiates by embedding predictive analytics into fountain and filling equipment, converting capital sales into recurring revenue streams.
Food processing encompasses the mechanical, thermal, and biological transformation of raw agricultural commodities into shelf-stable, palatable, and safe consumable products through unit operations such as pasteurization, extrusion, fermentation, and aseptic packaging. The sector serves industrial buyers, retail channels, and foodservice operators by extending product longevity, standardizing quality, and enabling mass distribution of perishable inputs. Beverages and dairy segments command the deepest margin pools due to high throughput velocity and brand premiumization potential, while bioprocessing technology represents the fastest-growing capability area as enzymatic and microbial conversion methods displace energy-intensive thermal alternatives. Meat processing retains the largest absolute value footprint but faces margin compression from labor scarcity and energy costs.
FDA enforcement of the Food Safety Modernization Act intensifies traceability requirements for US-based manufacturers, while EU Green Deal carbon accounting rules and REACH chemical safety standards constrain ingredient formulations and packaging materials across European supply chains. India's FSSAI and PLI scheme for food processing infrastructure jointly accelerate capital deployment into integrated cold chain and irradiation facilities. Stakeholders must monitor how divergent regulatory timelines for clean-label definitions and Scope 3 emissions disclosure reshape sourcing geographies and capital allocation priorities.
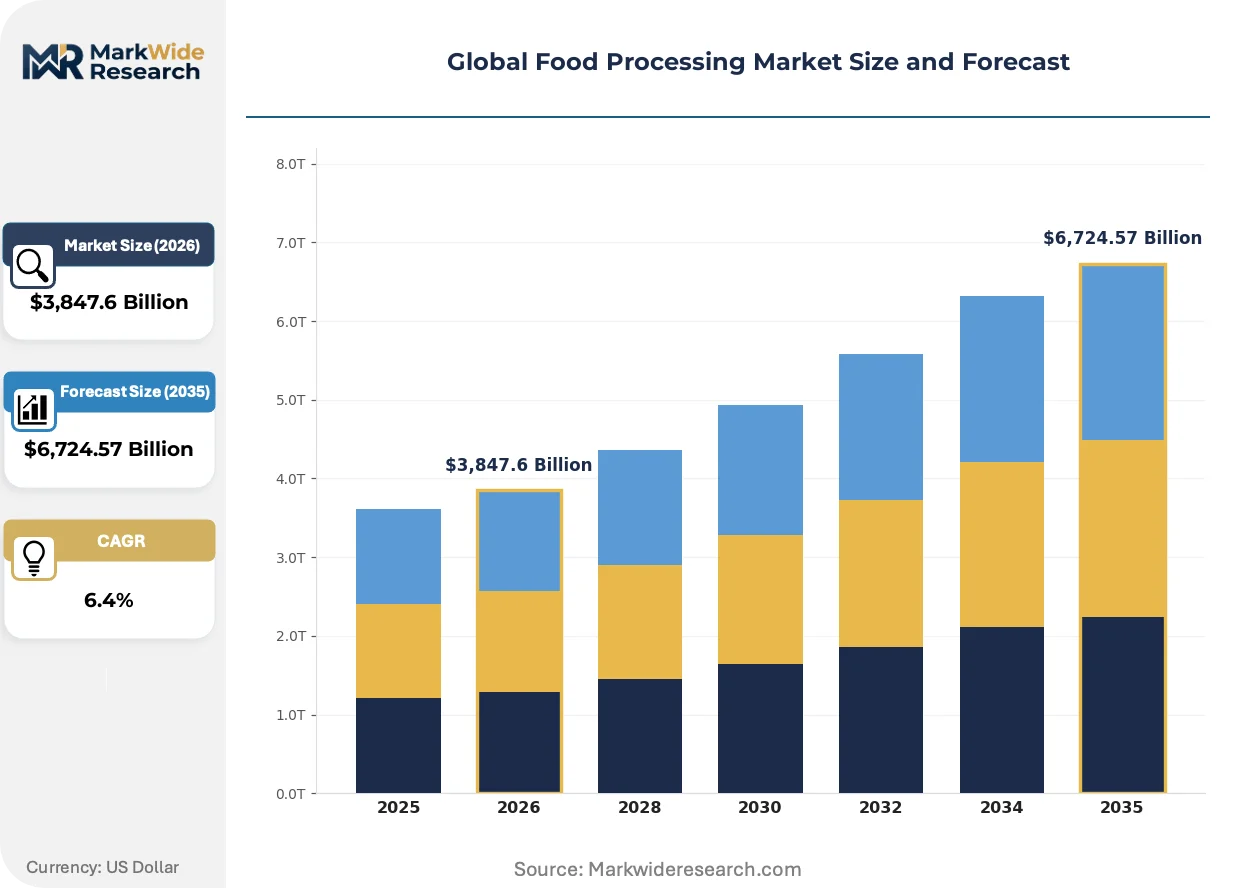
Market Dynamics
Bioprocessing technology is absorbing capital allocation previously directed toward thermal processing infrastructure, as enzymatic conversion methods demonstrate superior yield efficiency and Scope 3 emissions reduction across protein and carbohydrate transformation operations.
Growth Catalysts
- EU Green Deal carbon accounting:REACH chemical safety standards and packaging material constraints are forcing reformulation investments that unlock premium positioning in European retail channels.
- India PLI scheme for food processing infrastructure:Capital deployment into integrated cold chain and irradiation facilities accelerates processed dairy distribution into tier-two cities.
- High-pressure processing (HPP):Cold pasteurization technology extends shelf life without thermal degradation, enabling clean-label positioning in ready-to-eat meal segments.
Market Restraints
- Natural gas price volatility:Thermal processing operations in Germany and Italy face margin compression from energy input cost spikes that sterilization and drying stages cannot fully pass through.
- Labor scarcity in meat processing:Slaughterhouse and butchery automation lags behind other segments due to irregular carcass geometry, concentrating operational risk in Poland and Brazil processing clusters.
- FDA Food Safety Modernization Act traceability:Lot-level digital tracking requirements impose compliance costs that disadvantage smaller US manufacturers lacking integrated ERP systems.
Strategic Opportunities
- Precision fermentation capacity:Microbial protein production creates white space in alternative dairy and egg replacement formulations, with Singapore and Denmark establishing regulatory sandboxes for novel food approval.
- Blockchain-enabled provenance verification:Retail and foodservice buyers in Japan and South Korea are mandating immutable supply chain records for premium seafood and wagyu beef categories.
- Aseptic carton packaging:Shelf-stable beverage distribution without refrigeration opens penetration in Nigerian and Indonesian markets with underdeveloped cold chain infrastructure.
Industry Challenges
- Automation engineering talent gap:Food-grade robotics programming and hygienic design expertise concentrates in German and Swiss industrial clusters, creating recruitment bottlenecks for expansion projects elsewhere.
- Legacy MES integration:Brownfield facilities struggle to retrofit predictive analytics modules onto decades-old SCADA architectures without production line shutdowns.
- Dual certification timelines:Organic and halal accreditation processes in Indonesia and Malaysia extend product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Processing Market |
| Market Size in 2026 | $3,847.6 Billion |
| Market Size in 2035 | $6,724.57 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat, Dairy, Grain, Beverages Technology: Thermal Processing, Bioprocessing, Packaging, Preservation End User: Restaurants, Food Retailers, Catering Services, Food Manufacturing Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | Mars, Kraft Heinz, Nestlé, Unilever, General Mills, PepsiCo, Mondelēz International, The Coca-Cola Company, JBS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Processing Market Emerging Trajectories
Processing equipment architecture is pivoting from batch-oriented flexibility toward continuous-flow precision, driven by throughput demands and real-time quality control capabilities that reduce giveaway and rework rates.
Electrochemical oxidation water treatment is absorbing capital from conventional biological effluent systems in beverage and dairy plants. Nestlé and Danone facilities in France and Mexico are deploying boron-doped diamond electrodes to eliminate chemical oxygen demand without chlorine byproducts. The technology is compressing wastewater discharge compliance costs while recovering process water for reuse.
China's GB standards for food contact materials are tightening migration limits for plastics and coatings used in aseptic packaging. Manufacturers exporting to the Chinese market must reformulate barrier layers or face port-of-entry rejection. Japanese and South Korean packaging suppliers are accelerating fluoropolymer-free alternatives to maintain market access.
Foodservice operators are consolidating procurement through integrated platform distributors that bundle proteins, produce, and value-added processing under single-source contracts. Sysco and US Foods are capturing volume previously fragmented across specialty meat purveyors and regional dairy processors. This concentration is most visible in US institutional catering and European contract foodservice, where specification compliance and traceability documentation are becoming non-negotiable bid requirements.
Global Food Processing Market Segmentation
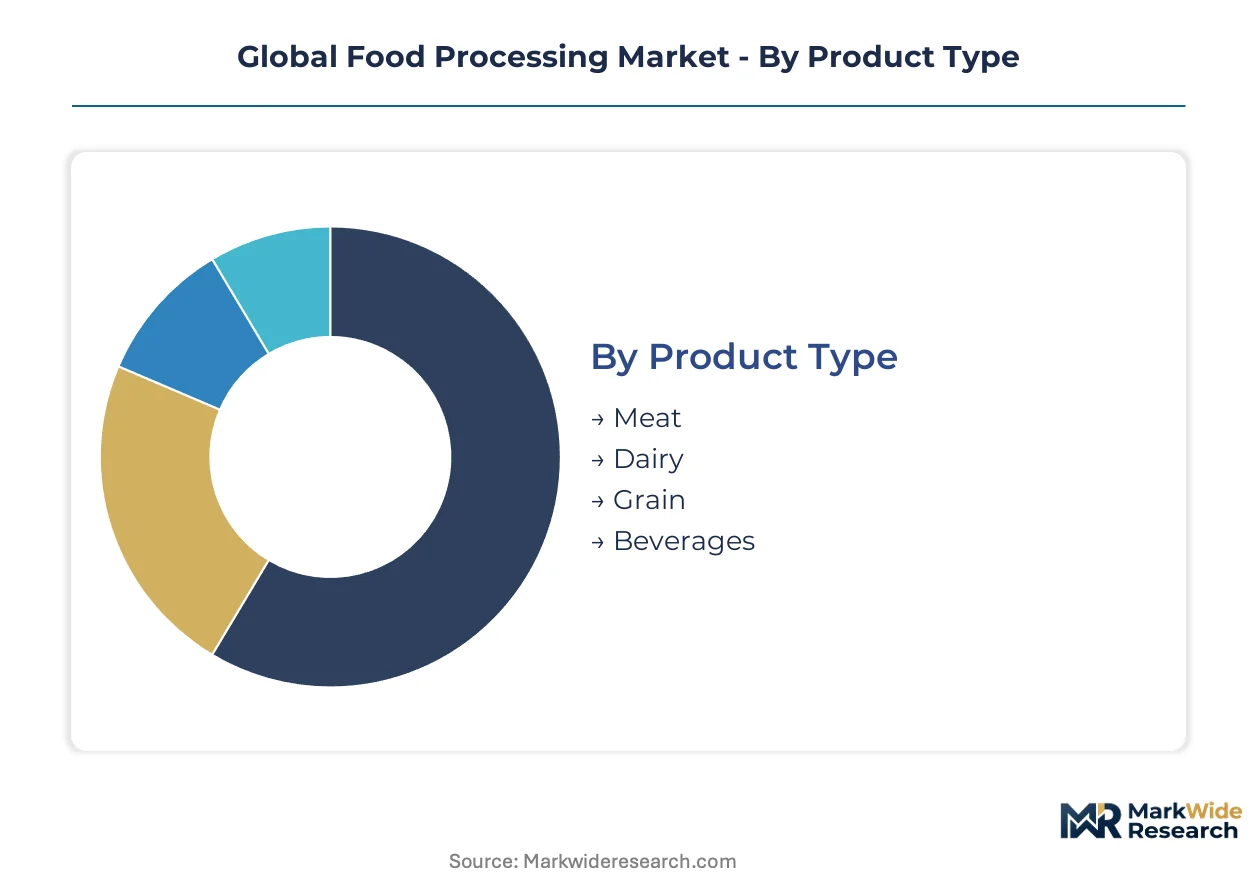
Segmentation in food processing reveals how capital allocation, regulatory exposure, and margin structures vary dramatically across input types and customer interfaces. Buyers prioritize shelf-life extension, traceability compliance, and throughput velocity differently depending on their downstream channel position and geographic market access.
Product Type:
Margin concentration and energy intensity separate buyers in this category, with protein processors facing labor scarcity while beverage operators capture premiumization upside.
- Meat:Slaughterhouse and butchery operations absorb the highest absolute capital deployment in processing infrastructure. Poland and Brazil clusters face acute automation gaps due to irregular carcass geometry, concentrating operational risk in these geographies.
- Dairy:Ultra-high-temperature sterilization and aseptic filling lines enable ambient distribution without cold chain dependency. India's tier-two city expansion is accelerating demand for processed dairy with extended shelf stability.
- Grain:Extrusion and milling operations serve industrial bakeries and breakfast cereal manufacturers with standardized throughput economics.
- Beverages:High-velocity filling lines and brand premiumization potential command the deepest margin pools in the sector.
Meat leads volumes today; beverages are gaining share fastest.
Technology:
Capital deployment velocity distinguishes technology adopters, with sustainability mandates and yield efficiency driving substitution patterns between thermal and biological conversion methods.
- Thermal Processing:Pasteurization, sterilization, and drying stages remain the workhorse of shelf-life extension despite energy cost volatility. German and Italian operators face margin compression from natural gas price spikes that cannot be fully passed through.
- Bioprocessing:Enzymatic and microbial conversion methods demonstrate superior yield efficiency and Scope 3 emissions reduction. Singapore and Denmark regulatory sandboxes are accelerating novel protein approval timelines.
- Packaging:Aseptic carton and barrier film technologies determine distribution reach into cold chain-constrained markets.
- Preservation:High-pressure processing extends shelf life without thermal degradation, enabling clean-label positioning in ready-to-eat segments.
Thermal processing retains installed base dominance; bioprocessing shows the steepest expansion trajectory.
End User:
Traceability documentation requirements and procurement consolidation patterns differentiate buyers, with institutional operators demanding integrated supply contracts that smaller processors cannot fulfill.
- Restaurants:Quick-service and casual dining chains specification-engineer processed ingredients for consistency and labor reduction. US foodservice distributors are consolidating procurement through platform contracts that bundle proteins and value-added processing.
- Food Retailers:Private-label ready-to-eat meal adoption is accelerating among urban consumers seeking convenience without cooking.
- Catering Services:Institutional and contract foodservice in Europe are mandating traceability documentation as non-negotiable bid requirements.
- Food Manufacturing:Industrial buyers extend product longevity and standardize quality for mass distribution of perishable inputs.
Food manufacturing anchors volume absorption; restaurants are climbing the fastest as procurement consolidation concentrates share.
Distribution Channel:
Cold chain infrastructure maturity and customer acquisition economics determine channel viability, with direct relationships capturing margin that intermediaries erode.
- Online:Direct-to-consumer processed food platforms require last-mile refrigeration capabilities that limit geographic reach. Urban density and subscription models are proving viable in developed markets with reliable logistics networks.
- Retail:Supermarket and hypermarket shelf space allocation favors established brands with trade promotion budgets and category management relationships.
- Direct Sales:Equipment vendors and integrated food companies are hardening subscription-based maintenance contracts into core revenue streams for processing line uptime.
- Wholesale:Broadline distributors capture volume previously fragmented across specialty meat purveyors and regional dairy processors.
Retail maintains channel dominance; direct sales are expanding most quickly as recurring revenue models displace transactional equipment sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting capital toward jurisdictions where carbon accounting rules and cold chain subsidies lower the cost of compliance. Production clusters migrate to markets offering integrated infrastructure support and streamlined novel food approval pathways.
United States
Quick-service chains and institutional foodservice operators specification-engineer processed ingredients for labor reduction and consistency. FDA enforcement of Food Safety Modernization Act traceability rules imposes lot-level digital tracking requirements that favor integrated ERP systems. Midwest protein processing clusters around Nebraska and Iowa face margin pressure from slaughterhouse automation gaps and natural gas price volatility in thermal sterilization stages.
Germany
Beverage and dairy manufacturers prioritize energy-efficient bioprocessing to offset natural gas cost spikes in pasteurization operations. EU Green Deal carbon accounting and REACH chemical safety standards constrain packaging material formulations and ingredient sourcing decisions. Bavarian industrial clusters concentrate electrochemical oxidation water treatment deployments that eliminate chemical oxygen demand without chlorine byproducts.
India
Tier-two city expansion accelerates demand for ambient-stable processed dairy and ready-to-eat meals among urban consumers. FSSAI safety standards and PLI scheme incentives jointly drive capital deployment into integrated cold chain and irradiation facilities. Gujarat and Maharashtra processing corridors absorb the bulk of foreign direct investment in aseptic filling and high-pressure processing capacity.
China
Domestic beverage brands and export-oriented seafood processors confront tightening GB standards for food contact material migration limits. NMPA and SAMR oversight of novel food ingredients extends approval timelines for precision fermentation-derived proteins. Yangtze River Delta packaging suppliers accelerate fluoropolymer-free barrier layer development to maintain port-of-entry compliance.
Brazil
Beef and poultry exporters navigate labor scarcity in slaughterhouse operations while capturing Asian market share through traceability documentation. ANVISA regulatory frameworks for processed meat exports align with Japanese and South Korean blockchain-enabled provenance mandates. São Paulo and Paraná processing clusters anchor JBS captive rendering infrastructure that reduces third-party logistics dependency.
Global Food Processing Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated multinationals commanding premium positioning in beverages and dairy while regional processors capture protein volume through cost leadership. Market structure tilts toward consolidation at the top tier, where scale economies in procurement and regulatory compliance create defensive moats. Three archetypes dominate: global brand houses with captive R&D pipelines, vertically integrated protein processors with captive rendering assets, and precision fermentation startups accessing regulatory sandboxes. Competitive moves center on subscription-based maintenance contract expansion and predictive analytics embedding that converts capital equipment sales into recurring revenue streams.
Among Swiss and Dutch brand houses, Nestlé and Unilever occupy positions that exemplify global service network leverage for long-term facility management partnerships across emerging markets. JBS anchors the vertically integrated protein processor archetype through its Brazilian and North American rendering and packaging infrastructure. PepsiCo sits within the predictive analytics tier, embedding fountain and filling equipment intelligence to differentiate beyond commodity processing. These three represent divergent strategic vectors: service monetization, upstream supply control, and technology-enabled recurring revenue.
| Leading Market Players |
|---|
| Mars |
| Kraft Heinz |
| Nestlé |
| Unilever |
| General Mills |
| PepsiCo |
| Mondelēz International |
| The Coca-Cola Company |
| JBS |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon accounting mandates gate qualified supply and premium-tier pricing access, as REACH-compliant ingredient sourcing and Scope 3 disclosure requirements concentrate procurement relationships with certified processors while excluding uncertified competitors from European retail channels.
Pricing Analysis
Capacity additions in India are reshaping price floors for ambient-stable dairy and ready-to-eat segments as PLI-subsidized cold chain infrastructure enables tier-two city distribution. Three-tier pricing structure across premium clean-label, standard fortified, and economy bulk tiers differentiates on certification grade and after-sales service bundling. Pricing pressure stems from natural gas volatility in German and Italian thermal sterilization operations. Quick-service chains show highest price sensitivity; institutional foodservice buyers prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-retail channels handle hyperscale beverage and dairy demand while equipment vendors deploy subscription-based maintenance contracts for processing line uptime. Raw material flows concentrate in Brazil for protein rendering, Germany for precision engineering components, and India for dairy feedstock. Electrochemical oxidation water treatment systems and aseptic barrier films represent critical component dependencies. Single-source vulnerability concentrates in German and Swiss automation engineering clusters. Distribution runs through integrated platform distributors consolidating US foodservice procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where urban consumer demand shifts toward premium clean-label specifications justify sustained margin capture for certified processors.
For Market Incumbents: Anticipate bioprocessing substitution threats by accelerating enzymatic conversion capacity in Singapore and Denmark regulatory sandboxes. Lock in long-term facility management partnerships across emerging markets to convert capital equipment sales into recurring revenue streams. Prioritize predictive analytics embedding in filling and packaging lines to defend service-based differentiation. For New Entrants and Emerging Players: The mid-tier price-point gap between premium clean-label and economy bulk segments offers white-space entry through precision fermentation-derived alternative proteins. Target India's tier-two city expansion where cold chain infrastructure gaps favor ambient-stable formulations. Pursue regulatory sandbox approvals in novel food categories as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for precision fermentation specialists because regulatory sandbox access creates scarce approval assets that large brand houses cannot replicate internally. Five-to-ten year viability hinges on bioprocessing yield efficiency displacing thermal alternatives. Monitor FDA enforcement intensity on Food Safety Modernization Act traceability as the inflection signal for ERP-integrated processors versus fragmented competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Singapore and Denmark regulatory sandboxes accelerate novel protein approval timelines beyond traditional jurisdictions. |
| Subscription-Based Maintenance Contracts | Nestlé's global service network converts capital equipment sales into recurring revenue across emerging markets. |
| Predictive Analytics Embedding | PepsiCo's fountain and filling equipment intelligence differentiates beyond commodity processing capabilities. |
| Backward Integration into Rendering | JBS captive infrastructure reduces third-party logistics dependency in Brazilian and North American protein operations. |
| Electrochemical Oxidation Water Treatment | Nestlé and Danone deployments in France and Mexico recover process water while eliminating chlorine byproducts. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at protein and dairy processing facilities, procurement leads at quick-service chains, channel partners in foodservice distribution, and technical R&D directors in packaging innovation. Secondary validation drew from FDA enforcement actions, EU ECHA REACH substance registrations, FSSAI compliance bulletins, and customs trade data on processing equipment imports. Bottom-up capacity installation tracking and top-down market sizing triangulated volume estimates.
Segment-weighting approaches modeled product type, technology adoption stage, end-user channel position, and geographic regulatory cluster across the analysis window. CAGRs derived from installed base expansion rates, substitution elasticity between thermal and bioprocessing methods, and cold chain infrastructure investment trajectories. Yield efficiency improvements in enzymatic conversion and Scope 3 emissions reduction targets served as industry-specific forecast inputs.
Caveats apply where FDA traceability enforcement intensity, EU Green Deal carbon accounting timeline acceleration, or natural gas price volatility could materially shift the outlook. Forecasts reflect assumptions on regulatory sandbox approval velocities and cold chain subsidy continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Spray Drying Equipment Market
Food Processing Equipment
Reach-In Freezers Market
Food Processing Equipment
Water Cooled Cube Ice Machines Market
Food Processing Equipment
Global Wine Tanks Market
Food Processing Equipment
Global Food Dehydrators Market
Food Processing Equipment
Cake Cutting Machines Market
Food Processing Equipment
Micro Winery Equipment Market
Food Processing Equipment
Pet Food Processing Market
Food Processing Equipment
Multiple Unit Pellet Systems Market
Food Processing Equipment
Ice Flaking Machine Market
Food Processing Equipment
Deaeration Machine Market
Food Processing Equipment
French Fries Cutter Market
Food Processing Equipment
Food-Grade Mixing Tank Market
Food Processing Equipment
Global Commercial Food Dehydrators Market
Food Processing Equipment
Fish Deboning Machine Market
Food Processing Equipment
Small Brewery Equipment Market