
 Multi Ovens Market | 2026-2036
Multi Ovens Market Size, Share, and Industry Trends Forecast 2026-2036
Multi Ovens Market Foresight
Commercial foodservice buyer concentration is consolidating as multinational restaurant chains and institutional catering operators centralize procurement through national supply agreements. Whirlpool leverages its North American manufacturing footprint to anchor contracts with large hospitality groups. Bosch competes through precision engineering capabilities that sustain premium positioning in European commercial kitchens.
Multi ovens integrate multiple cooking modalities—convection, steam, microwave, and infrared—within a single enclosure, typically achieving temperatures from 90°F to 550°F with programmable humidity control for precise food texture management. Combination ovens and steam ovens command the strongest margin pools as commercial operators prioritize water-based cooking methods that reduce energy consumption and improve yield consistency. Electric technology dominates new installations in regions with aggressive decarbonization targets, while gas configurations retain share where utility infrastructure lags.
The U.S. Department of Energy sets minimum efficiency standards that shape product development cycles, while the EU Ecodesign Directive and CE marking requirements govern market access across European member states. The EU F-Gas Regulation additionally constrains refrigerant choices in combination oven designs that incorporate blast chilling functions. Stakeholders must monitor evolving efficiency tier thresholds and refrigerant phase-down schedules to align R&D roadmaps with compliance timelines.
Market Dynamics
The EU Ecodesign Directive and U.S. Department of Energy standards are compressing product development cycles, forcing manufacturers to prioritize energy efficiency certifications before feature differentiation in commercial kitchen procurement decisions.
Growth Catalysts
- EU Ecodesign Directive:The directive mandates minimum energy efficiency thresholds for commercial cooking equipment, compelling foodservice operators to accelerate replacement schedules with compliant multi oven systems.
- Steam cooking modality:Water-based cooking methods reduce energy consumption and improve yield consistency, driving adoption across institutional catering and restaurant chains prioritizing operational cost control.
- Germany:Commercial hospitality operators in this market lead upgrade spending, concentrating demand visibility for combination and steam oven configurations with programmable humidity control.
Market Restraints
- Stainless steel input volatility:Multi oven enclosures rely heavily on grade 304 stainless steel, exposing manufacturers to commodity price swings that compress margin buffers on standard configurations.
- EU F-Gas Regulation:The refrigerant phase-down schedule constrains blast chilling integration in combination oven designs, limiting product versatility for operators requiring rapid cooling workflows.
- Gas infrastructure dependency:Regions with lagging utility electrification retain gas configuration demand, fragmenting R&D investment across incompatible heating technologies.
Strategic Opportunities
- Electric technology convergence:Aggressive decarbonization targets in advanced economies are displacing gas installations, creating first-mover advantage for manufacturers with mature electric heating platforms.
- Infrared modality integration:The convergence of infrared with convection and steam capabilities enables premium positioning through accelerated cooking speeds and enhanced surface browning control.
- National supply agreements:Centralized procurement by multinational restaurant chains favors vendors with continental manufacturing footprints capable of volume consistency and service network density.
Industry Challenges
- CE marking complexity:Multi oven manufacturers face extended certification timelines as combination units must satisfy overlapping safety, electromagnetic compatibility, and energy efficiency frameworks before EU market entry.
- Legacy kitchen integration:Foodservice operators with existing ventilation and power infrastructure struggle to accommodate next-generation multi oven specifications without facility retrofit costs.
- Humidity control calibration:Precision engineering talent scarcity complicates programmable moisture management system development, slowing feature parity among mid-tier competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi Ovens Market |
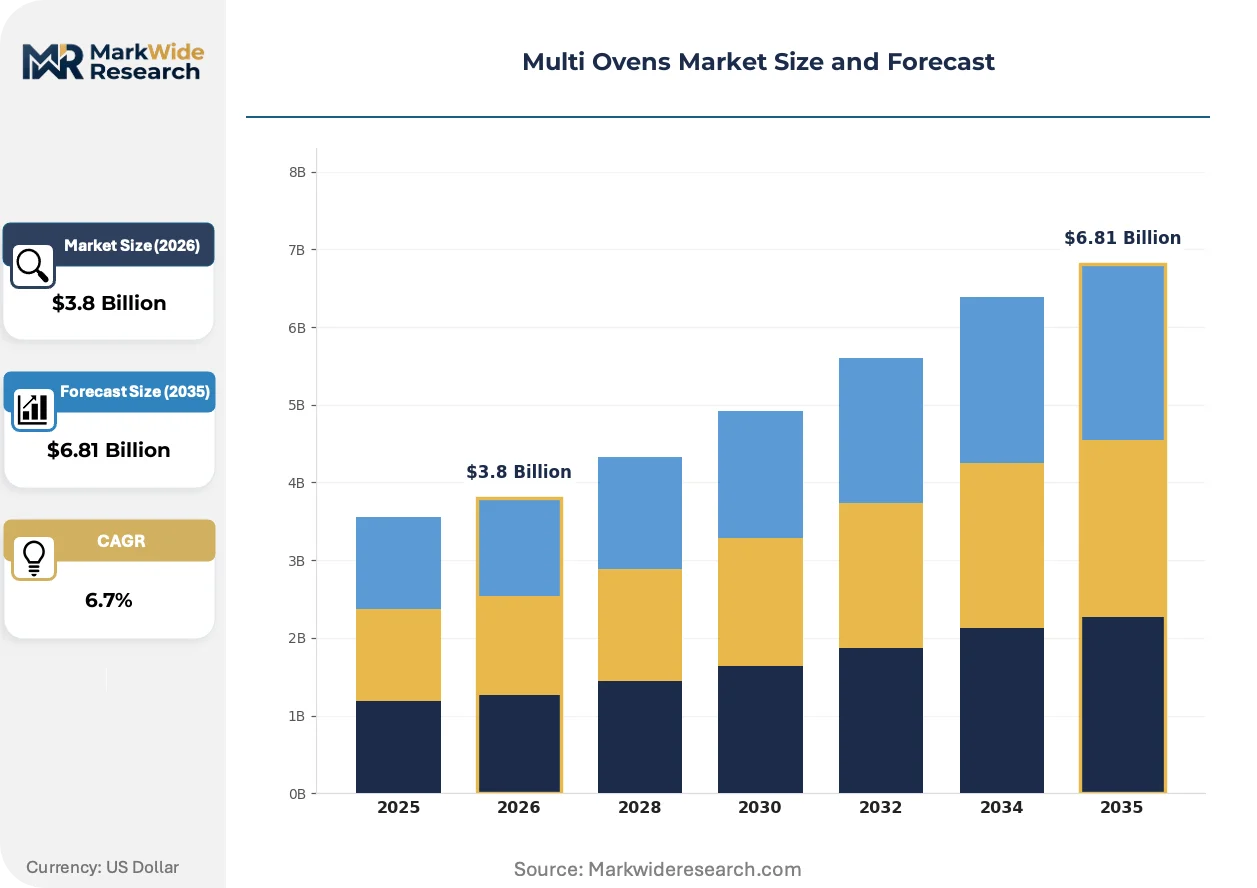
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convection Ovens, Microwave Ovens, Combination Ovens, Steam Ovens End User: Residential, Commercial, Industrial, Hospitality Technology: Infrared, Induction, Electric, Gas Capacity: Compact, Medium, Large, Extra Large |
| Companies Covered | Whirlpool, Bosch, Samsung, LG Electronics, Electrolux, Panasonic, Miele, GE Appliances, Frigidaire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi Ovens Market Shifts & Advancements
Active rewiring of product architecture is occurring as connectivity layers, refrigerant constraints, and procurement centralization simultaneously reshape how commercial kitchens specify and operate multi oven equipment.
Programmable humidity management is rewriting competitive differentiation in the combination oven segment. The technology enables precise texture control across proteins, baked goods, and reheated items without dedicated equipment. High-volume institutional caterers in Germany and France are specifying these systems at replacement cycle acceleration. The capability is compressing demand for standalone steam ovens and forcing margin erosion in single-function product lines.
The EU F-Gas Regulation is tightening refrigerant choices for combination ovens with integrated blast chilling. Manufacturers must redesign thermal systems around lower-global-warming-potential alternatives or remove rapid-cooling functionality entirely. Commercial bakery and prepared-meal segments face the steepest compliance costs, with several operators delaying fleet upgrades pending clarity on alternative refrigerant availability and service infrastructure.
Consolidated procurement through national supply agreements is concentrating buyer power among multinational restaurant chains and institutional operators. Traditional distribution through independent foodservice dealers is losing share to direct manufacturer relationships with centralized technical support and standardized training protocols. This pattern is most visible in North American quick-service and contract catering verticals, where procurement teams prioritize total cost of ownership metrics over upfront equipment pricing.
Multi Ovens Market Segmentation
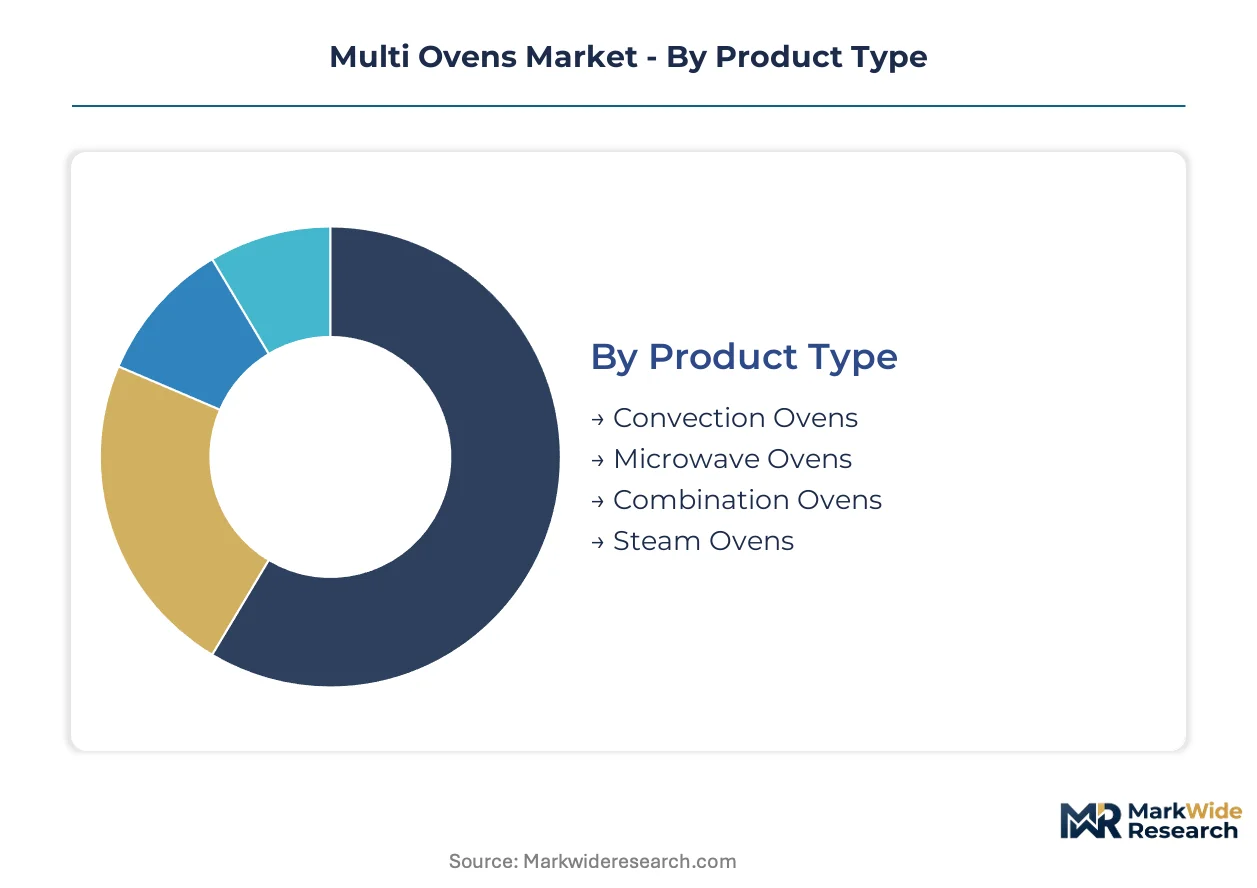
Multi oven segmentation reveals how cooking modality, operator scale, and energy infrastructure interact to determine specification requirements. Procurement patterns diverge sharply between residential replacement cycles and commercial fleet upgrades driven by regulatory compliance timelines.
Product Type:
Standardized platforms dominate high-volume production, while configurable multi-function units command premium positioning through humidity programmability and modality stacking.
- Combination Ovens:These units integrate convection, steam, and microwave capabilities within a single chamber, enabling sequential or simultaneous modality deployment. Commercial hospitality operators in Germany specify these systems most intensively as they consolidate equipment footprints while satisfying EU Ecodesign Directive efficiency thresholds. Programmable humidity control drives replacement demand among institutional caterers seeking yield consistency across protein and baked goods production.
- Steam Ovens:Water-based cooking systems achieve temperature precision through saturated vapor injection, reducing energy consumption versus dry-heat alternatives. Restaurant chains prioritize these configurations where operational cost control outweighs speed requirements, particularly in markets with aggressive utility decarbonization mandates. The segment faces margin pressure as combination ovens absorb standalone steam functionality.
- Convection Ovens:Forced-air circulation systems remain the baseline specification for standard baking and roasting applications.
- Microwave Ovens:Rapid reheating units concentrate in quick-service and convenience retail formats.
Most installed capacity flows through Combination Ovens. Expansion is steepest in Steam Ovens.
End User:
Volume concentration tilts toward centralized procurement by multinational operators, while fragmented residential demand sustains distribution through retail channels.
- Commercial:Restaurant chains and contract caterers drive fleet standardization through national supply agreements, prioritizing total cost of ownership metrics over upfront capital expenditure. These operators specify electric configurations where utility infrastructure supports decarbonization targets, while gas retention persists in regions with lagging grid capacity. Replacement cycles compress where EU Ecodesign Directive compliance deadlines approach.
- Hospitality:Hotels and event venues demand configurable equipment supporting menu breadth without dedicated station proliferation. German commercial hospitality operators lead upgrade spending, concentrating demand visibility for premium combination configurations with infrared integration. Procurement centralization among international hotel groups favors vendors with continental service network density.
- Residential:Individual households purchase through retail and e-commerce channels with replacement-driven demand patterns.
- Industrial:Centralized production facilities for prepared meals and bakery components require high-throughput continuous systems.
Procurement volume concentrates in Commercial. Hospitality is gaining share fastest.
Technology:
Energy source selection tracks regional electrification progress and utility pricing structures, fragmenting R&D investment across incompatible heating architectures.
- Electric:Resistance and induction heating platforms dominate new installations in markets with aggressive decarbonization targets and grid infrastructure investment. The U.S. Department of Energy efficiency standards accelerate displacement of legacy gas configurations in North American commercial kitchens. Manufacturers with mature electric platforms capture first-mover advantage as procurement specifications harden around emissions metrics.
- Gas:Open-burner and infrared gas systems retain share where utility electrification lags or energy costs favor hydrocarbon combustion. These configurations persist in regions with established gas distribution infrastructure and operator preference for rapid temperature response. Product development investment fragments as regulatory timelines diverge across jurisdictions.
- Induction:Electromagnetic heating delivers precise temperature control with minimal thermal loss to ambient kitchen environments.
- Infrared:Radiant heat transfer enables accelerated surface browning and reduced cooking times for specific protein applications.
Current fleet composition favors Gas. Electric is climbing the fastest.
Capacity:
Footprint constraints and throughput requirements determine specification, with kitchen real estate costs driving demand toward space-efficient configurations.
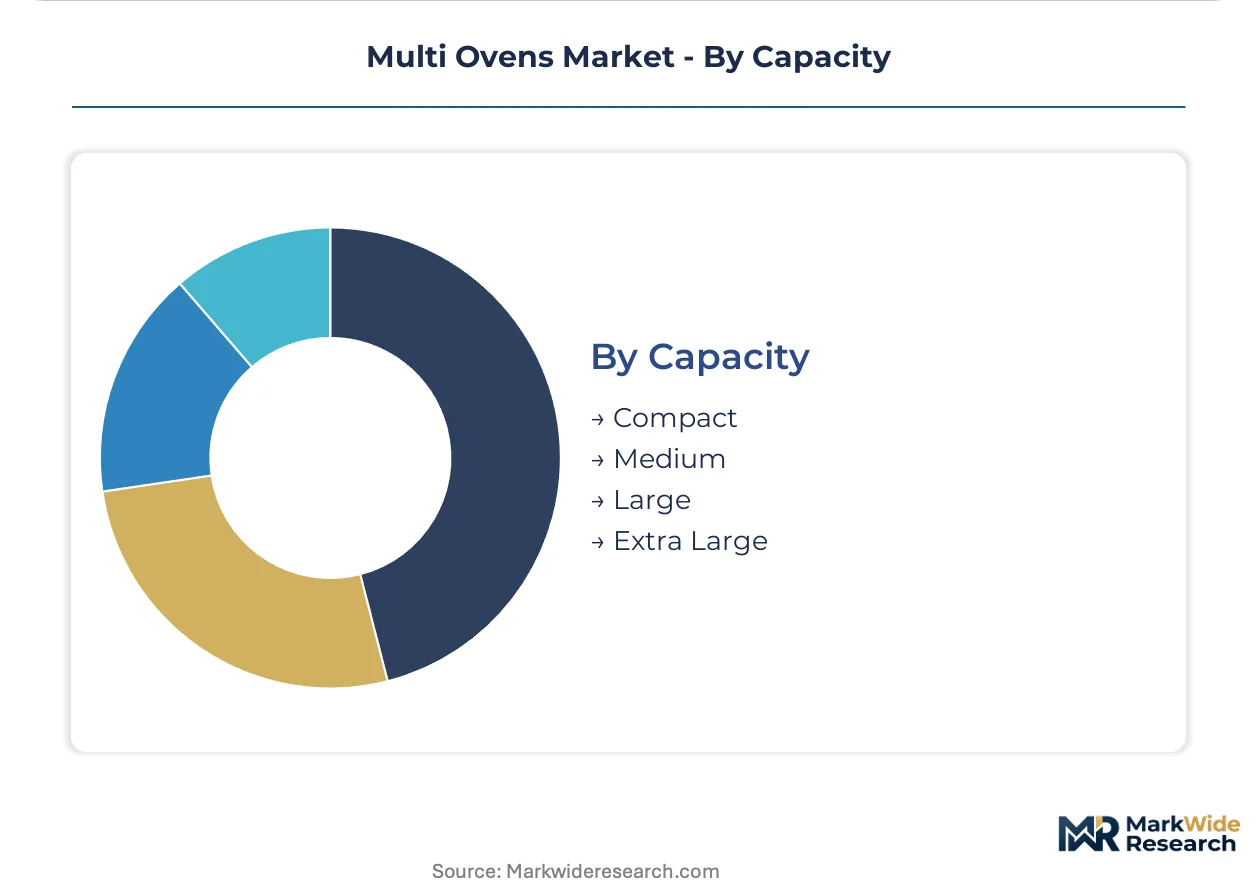
- Large:Full-size units accommodate standard gastronorm containers and high-volume production schedules for institutional catering and central commissary operations. These systems command premium positioning through multi-rack capability and programmable recipe management. Operators prioritize energy efficiency certifications as operational cost components dominate total cost of ownership calculations.
- Medium:Mid-capacity configurations balance throughput flexibility with kitchen footprint constraints for independent restaurants and regional chain operations. Demand concentrates where facility retrofit costs limit accommodation of larger equipment specifications. CE marking complexity extends procurement timelines as combination units must satisfy overlapping safety and efficiency frameworks.
- Compact:Countertop and undercounter units serve space-constrained operations and front-of-house display cooking.
- Extra Large:Tunnel and rack configurations support industrial-scale continuous production for bakery and prepared meal segments.
Medium capacity holds the largest installed base. Large capacity shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates commercial hospitality upgrade spending while the United States drives electric platform displacement through federal efficiency mandates. Utility decarbonization timelines diverge sharply across these markets, fragmenting manufacturer R&D investment between incompatible heating architectures.
Germany
Commercial hospitality operators in Bavaria and North Rhine-Westphalia accelerate replacement cycles for combination ovens with programmable humidity control. The EU Ecodesign Directive mandates minimum efficiency thresholds that compress procurement timelines for institutional caterers. Munich's hotel and event venue clusters specify premium configurations with infrared integration as international groups centralize procurement.
United States
Multinational restaurant chains consolidate procurement through national supply agreements prioritizing total cost of ownership metrics. The U.S. Department of Energy efficiency standards reshape product development cycles ahead of feature differentiation. Chicago and Dallas-Fort Worth quick-service operators drive electric configuration adoption where grid infrastructure supports decarbonization targets.
France
Institutional caterers in Île-de-France specify steam-capable systems for yield consistency across protein and baked goods production. The EU F-Gas Regulation constrains blast chilling integration in combination oven designs for commercial bakery segments. Lyon and Paris prepared-meal producers delay fleet upgrades pending clarity on alternative refrigerant service infrastructure.
China
Restaurant chains in the Yangtze River Delta and Pearl River Delta balance throughput flexibility with kitchen footprint constraints for mid-capacity configurations. National efficiency standards under MIIT guidance accelerate displacement of legacy gas configurations in coastal commercial kitchens. Shanghai's contract catering operators prioritize electric platforms where utility pricing structures favor grid-connected heating.
United Kingdom
Independent restaurants and regional chain operators in London and the Midlands face extended procurement timelines due to CE marking complexity for combination units. The UK's post-EU regulatory alignment with Ecodesign thresholds maintains efficiency pressure on replacement schedules. Birmingham's foodservice dealers lose share to direct manufacturer relationships as procurement centralizes among hospitality groups.
Multi Ovens Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: diversified appliance conglomerates with continental manufacturing footprints, precision-engineering specialists with premium positioning capabilities, and scale-driven fabricators serving centralized procurement channels. Competitive moves concentrate on strategic partnerships for refrigerant compliance and portfolio diversification into connectivity-enabled platforms.
Among diversified conglomerates, Whirlpool and Electrolux occupy positions anchored by North American and European manufacturing scale respectively. Bosch exemplifies the precision-engineering archetype through German GmbH-structured operations. These three entities represent distinct competitive vectors: continental service network density, premium-tier feature differentiation, and volume consistency for multinational contract capture.
| Leading Market Players |
|---|
| Whirlpool |
| Bosch |
| Samsung |
| LG Electronics |
| Electrolux |
| Panasonic |
| Miele |
| GE Appliances |
| Frigidaire |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap fabricators in Northern Italy and Southern Germany anchor specialty stainless steel component supply, linking generational ownership discipline to stable input contracting and premium-tier pricing power for precision-engineered multi oven enclosures.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard convection configurations, compressing margins on commodity-grade units while European producers defend premium positioning through CE-marked efficiency certifications. Three-tier pricing structure across premium, standard, and economy levels separates programmable humidity systems from basic convection units from compact countertop models. Price differentiation hinges on certification grade and after-sales service bundling, with institutional caterers least sensitive and independent restaurants most responsive to upfront capital expenditure.
Supply Chain Analysis
Freight cost volatility from Asia-Europe lanes is forcing inventory repositioning, with manufacturers absorbing higher carrying costs to buffer grade 304 stainless steel supply. Production concentrates in Germany, China, and the United States, drawing from Taiwanese control systems, Italian heating elements, and domestic stainless steel rolling. Single-source vulnerability around semiconductor-based controller chips creates exposure, while distribution runs through direct manufacturer relationships with multinational chains alongside legacy foodservice dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: electric platform R&D costs in Germany run substantially above comparable investment thresholds in China's coastal manufacturing zones, creating cost-structure divergence for entrants with modular technology sourcing.
For Market Incumbents: Extend service network density in North American quick-service corridors to defend against centralized procurement consolidation, while accelerating backward integration into stainless steel component forging to buffer commodity volatility. Prioritize EU F-Gas Regulation compliance roadmaps before refrigerant phase-down deadlines harden competitive exclusion. For New Entrants and Emerging Players: Launch via direct-to-operator digital channels targeting mid-capacity electric configurations for independent restaurant clusters in secondary US metros, where national supply agreement coverage remains thin and total cost of ownership messaging resonates against legacy gas replacement cycles. For Investors and Strategic Acquirers: Diversified appliance conglomerates seeking European precision-engineering capabilities represent the most active acquirer category in this space, with five-to-ten year viability contingent on electrification platform maturity. Target mid-tier manufacturers with programmable humidity control IP and established CE marking pathways. Monitor EU Ecodesign Directive tier threshold announcements as the critical inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Platform Migration | Aligns product portfolios with US Department of Energy efficiency mandates and EU decarbonization timelines. |
| Programmable Humidity Control Development | Captures institutional catering demand in Germany and France seeking yield consistency across protein production. |
| Refrigerant System Redesign | Addresses EU F-Gas Regulation constraints on blast chilling integration in combination oven configurations. |
| Direct Manufacturer Relationships | Bypasses independent dealer networks to capture centralized procurement from multinational restaurant chains. |
| Continental Service Network Expansion | Supports hospitality group procurement centralization requiring standardized training and rapid technical response. |
Research Methodology
Bottom-up commercial operator modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with foodservice procurement directors, commercial kitchen design consultants, OEM product development engineers, and aftermarket service heads combined with secondary validation from US Department of Energy efficiency filings, EU Ecodesign Directive compliance databases, customs trade records for stainless steel components, and SEC 10-K disclosures from diversified appliance manufacturers.
Historical trendline analysis across installed base replacement cycles and energy efficiency adoption curves informed projection frameworks. Segmentation dimensions span cooking modality, operator scale, technology architecture, and capacity tier, with CAGRs derived from regression against regulatory compliance deadlines and utility electrification timelines. Forecast inputs incorporate EU F-Gas Regulation phase-down schedules and MIIT efficiency guidance trajectory for Chinese commercial kitchens.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated refrigerant transition costs or prolonged stainless steel price volatility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Electrodialysis Equipment Market
Food Processing Equipment
Industrial Food Milling Machine Market
Food Processing Equipment
Countertop Blast Chiller Market
Food Processing Equipment
Yogurt Makers Market
Food Processing Equipment
Bread Maker Market
Food Processing Equipment
Sorbitol Production Equipment Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Global High Pressure Processing (HPP) Market
Food Processing Equipment
Freeze-Drying Market
Food Processing Equipment
Spray Dried Food Market
Food Processing Equipment
Butcher Equipment Market
Food Processing Equipment
Granular Ice Machine Market
Food Processing Equipment
High Speed Oven Market
Food Processing Equipment
USA Commercial Walk-In Refrigeration Market
Food Processing Equipment
Europe Household Food Waste Composting Machine Market
Food Processing Equipment
Plastic Processing Machinery Market