
 Global Food Blenders and Mixers Market | 2026-2036
Global Food Blenders and Mixers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Blenders and Mixers Market Analysis
Foodservice equipment distribution is tilting toward integrated direct-sales teams with embedded technical service. GEA Group leverages its process engineering heritage to anchor large-scale dairy and beverage installations. Tetra Laval sustains cross-category bundling advantages that link processing equipment to packaging lines. SPX Flow competes through specialized hygienic designs that reduce clean-in-place downtime.
Food blenders and mixers are motorized appliances with stainless-steel contact surfaces, variable-speed drives, and sealed bearing housings designed to homogenize, emulsify, or aerate food matrices under controlled shear conditions. Stand mixers dominate commercial bakery and confectionery operations where planetary action and bowl-lift mechanisms handle dense dough formulations. Hand blenders and immersion units are gaining traction in catering and central kitchen settings where portability and reduced footprint offset lower throughput capacity. Mixing and blending functionalities command the widest installed base, while chopping and pureeing configurations attract premium positioning in prepared-meal and infant-nutrition processing.
FDA sanitary equipment standards and 3-A Sanitary Standards in the United States, CE marking and EU Machinery Directive requirements in Europe, and China's GB standards enforced by SAMR collectively dictate material specifications, guarding geometries, and validation protocols. These frameworks elevate compliance costs for new entrants while rewarding incumbents with certified product portfolios and established testing relationships. Stakeholders must monitor evolving energy-labeling thresholds and allergen-control mandates that will determine which equipment platforms remain viable across major commercial kitchens.
Market Dynamics
Quick-service restaurant chains are consolidating kitchen footprints while demanding higher throughput per square meter, forcing equipment suppliers to engineer compact multi-function platforms that replace standalone units.
Growth Catalysts
- Energy-efficiency mandates:Europe's Ecodesign Directive and escalating EU Machinery Directive thresholds compel manufacturers to redesign motor systems and thermal management, creating replacement cycles in installed bases.
- Food processing infrastructure modernization:China's domestic food processing sector is upgrading from manual batch operations to automated continuous processing, driving demand for industrial-scale homogenization equipment.
- Clean-label formulation complexity:Beverage and dairy processors require precision shear control to stabilize plant-based emulsions without synthetic additives, expanding the addressable market for variable-speed drive systems.
Market Restraints
- Stainless steel price volatility:Fluctuations in nickel and chromium input costs compress margins for equipment fabricators locked into fixed-price contracts with foodservice distributors.
- Supply concentration in precision motors:High-torque variable-frequency drive motors for industrial mixers concentrate among German and Japanese suppliers, exposing lead time risks.
- Technical ceiling in shear-sensitive applications:Current impeller geometries damage protein structures in cultured meat and precision fermentation broths, limiting penetration in alternative protein processing.
Strategic Opportunities
- Southeast Asia central kitchen buildout:Indonesia and Vietnam are constructing regional food preparation hubs to serve chain restaurant expansion, creating demand for high-capacity batch mixers with remote monitoring.
- Regulatory tailwind from allergen control:FDA Food Safety Modernization Act traceability mandates incentivize equipment with sealed bearing housings and tool-free disassembly for validated cleaning protocols.
- Technology convergence of IoT and predictive maintenance:Embedded vibration sensors and cloud-based analytics enable service revenue models that shift customer relationships from transactional to subscription-based.
Industry Challenges
- Certification timeline compression:3-A Sanitary Standards and EU Machinery Directive conformity assessments now require simultaneous documentation across multiple notified bodies, extending product launch schedules.
- Integration friction with legacy MES systems:Food manufacturers operate heterogeneous control architectures that resist standardized data exchange with new blending equipment, complicating automation upgrades.
- Specialized technician scarcity:Servicing sealed bearing housings and variable-frequency drives demands electromechanical expertise that outpaces vocational training pipeline output in key manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Blenders and Mixers Market |
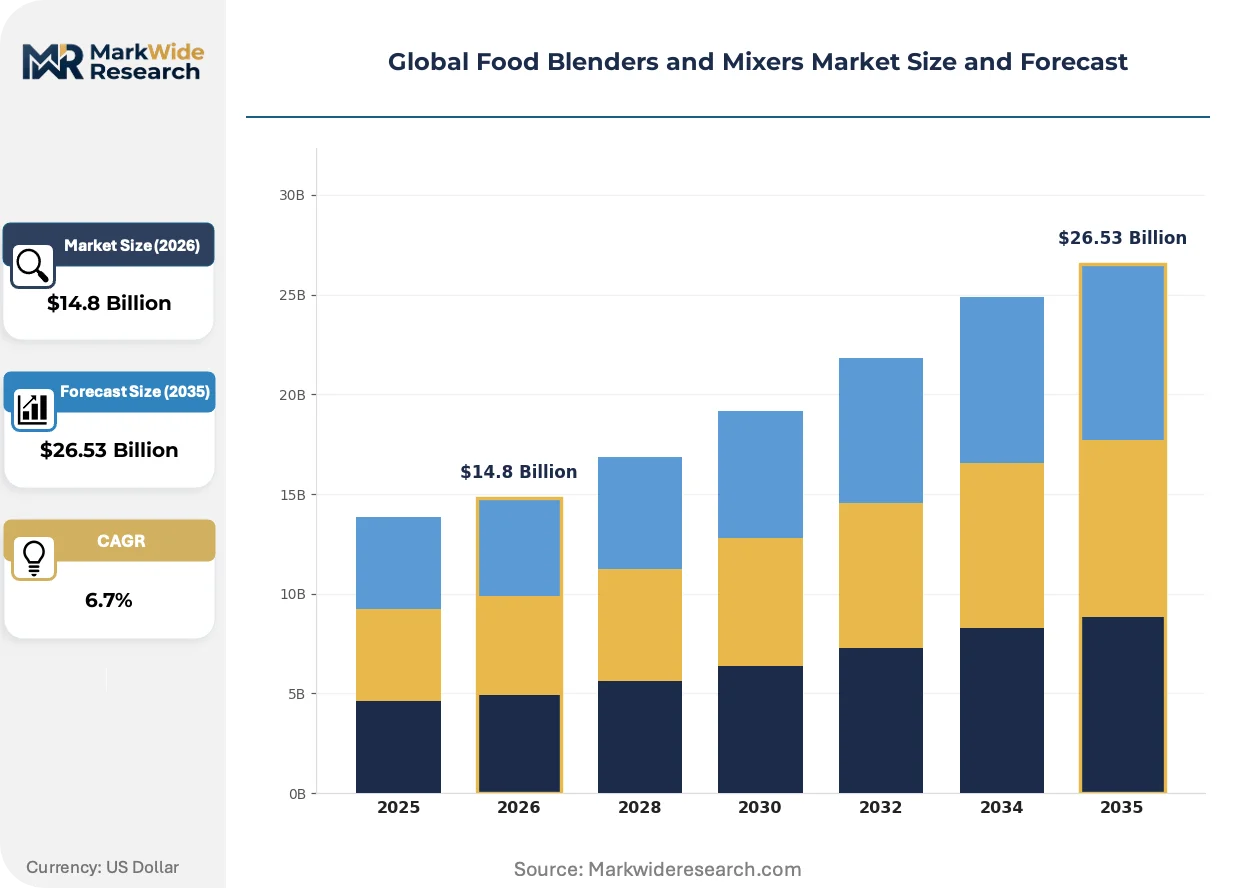
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Blenders, Stand Mixers, Food Processors, Immersion Blenders End User: Restaurants, Cafes, Households, Catering Services Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Direct Sales Functionality: Mixing, Blending, Chopping, Pureeing |
| Companies Covered | GEA Group, Tetra Laval, SPX Flow, Alfa Laval, Marel, Vitamix, KitchenAid, Buhler, Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Blenders and Mixers Market Emerging Trajectories
Equipment architecture is converging around modular platforms that swap tool heads and bowl configurations without hardware changeovers, compressing capital deployment timelines for multi-product facilities.
Magnetic drive coupling technology is collapsing the mechanical seal maintenance burden that historically dominated total cost of ownership calculations for sanitary processing equipment. Dairy and beverage processors in the Netherlands and Denmark are specifying magnetically coupled mixers for new installations. This shift is collapsing the service revenue streams that incumbent suppliers built around scheduled seal replacement programs.
REACH restrictions on per- and polyfluoroalkyl substances are compelling manufacturers to eliminate PTFE-based bearing seals and coatings from food-contact equipment designs. The industrial consequence is accelerated qualification of ceramic and graphite dry-running seal alternatives. European OEMs are most affected, with several German suppliers redesigning entire hygienic mixer lines to maintain CE marking compliance.
Central procurement teams at multinational food manufacturers are consolidating vendor panels and demanding outcome-based performance guarantees rather than equipment specifications. Distributor networks are losing ground to direct technical sales teams with embedded service capabilities. This pattern is most visible in North American quick-service restaurant supply chains, where equipment standardization across franchise networks overrides local distributor relationships.
Global Food Blenders and Mixers Market Segmentation
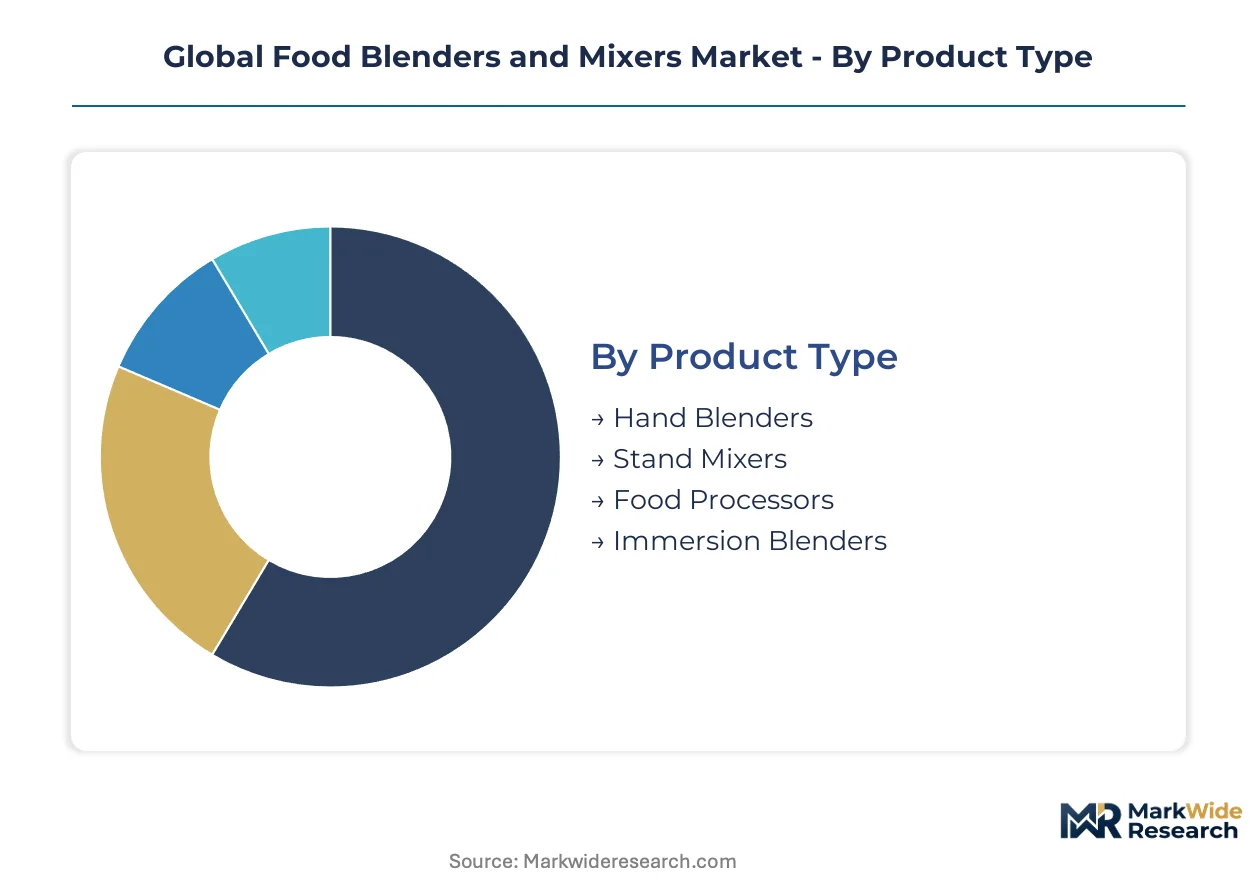
Segmentation in food blenders and mixers separates volume-driven commodity purchases from precision-engineered industrial platforms. Equipment specification diverges sharply between household convenience features and commercial-grade sanitary designs. Understanding these fault lines clarifies where margin compression versus technology premiumization occurs across the supply base.
Product Type:
Cost tier stratification in this category spans disposable small appliances through capital-intensive industrial platforms with decade-long depreciation schedules.
- Hand Blenders:Portable motorized units with detachable stainless-steel shafts enable single-operator processing in confined kitchen footprints. Demand concentrates in European catering operations where labor mobility and reduced equipment redundancy offset lower throughput versus fixed installations. REACH compliance on bearing seals has accelerated ceramic dry-running alternatives in German and Danish specifications.
- Stand Mixers:Planetary-action machines with bowl-lift mechanisms and variable-speed drives handle dense dough formulations in commercial bakery operations. Chinese quick-service restaurant chains are standardizing these units across franchise networks, driving procurement consolidation toward direct manufacturer relationships with embedded technical service.
- Food Processors:Multi-function platforms with interchangeable tool heads perform slicing, shredding, and emulsification in central kitchen configurations.
- Immersion Blenders:Submersible shaft designs with sealed bearing housings target high-volume liquid processing in beverage manufacturing.
Stand mixers hold installed capacity. Immersion blenders are rotating up the share rankings.
End User:
Application intensity varies from intermittent domestic use through continuous-duty industrial cycles exceeding 18 hours daily.
- Restaurants:Full-service establishments deploy compact multi-function platforms to maximize throughput per square meter as kitchen footprints shrink. Equipment specification prioritizes tool-free disassembly for validated cleaning under FDA Food Safety Modernization Act traceability mandates.
- Catering Services:Mobile and event-based operations demand portable equipment with rapid deployment capabilities. Southeast Asian central kitchen buildouts in Indonesia and Vietnam are sourcing high-capacity batch mixers with remote monitoring functionality for regional hub configurations.
- Cafes:Beverage-focused operations emphasize precision shear control for plant-based emulsion stabilization without synthetic additives.
- Households:Price-sensitive segment with replacement cycles driven by aesthetic obsolescence rather than functional degradation.
Restaurants anchor volume procurement. Catering services are climbing the fastest as chain restaurant consolidation accelerates hub-and-spoke food preparation models.
Distribution Channel:
Customer type determines whether procurement flows through transactional retail or technical sales relationships with outcome-based performance guarantees.
- Direct Sales:Integrated technical teams with embedded service capabilities dominate multinational food manufacturer and quick-service restaurant chain procurement. This channel captures premium positioning through specification consulting and lifecycle cost optimization rather than equipment list pricing.
- Online Retailers:E-commerce platforms serve price-transparent replacement part markets and small-batch commercial purchasers. The channel struggles with complex hygienic equipment where installation validation and commissioning support determine operational outcomes.
- Supermarkets:Mass-market channel for household-grade appliances with limited commercial penetration.
- Specialty Stores:Regional distributors maintaining local inventory for expedited delivery to independent foodservice operators.
Direct sales commands margin concentration. Online retailers are rotating up the share rankings as procurement standardization enables remote specification.
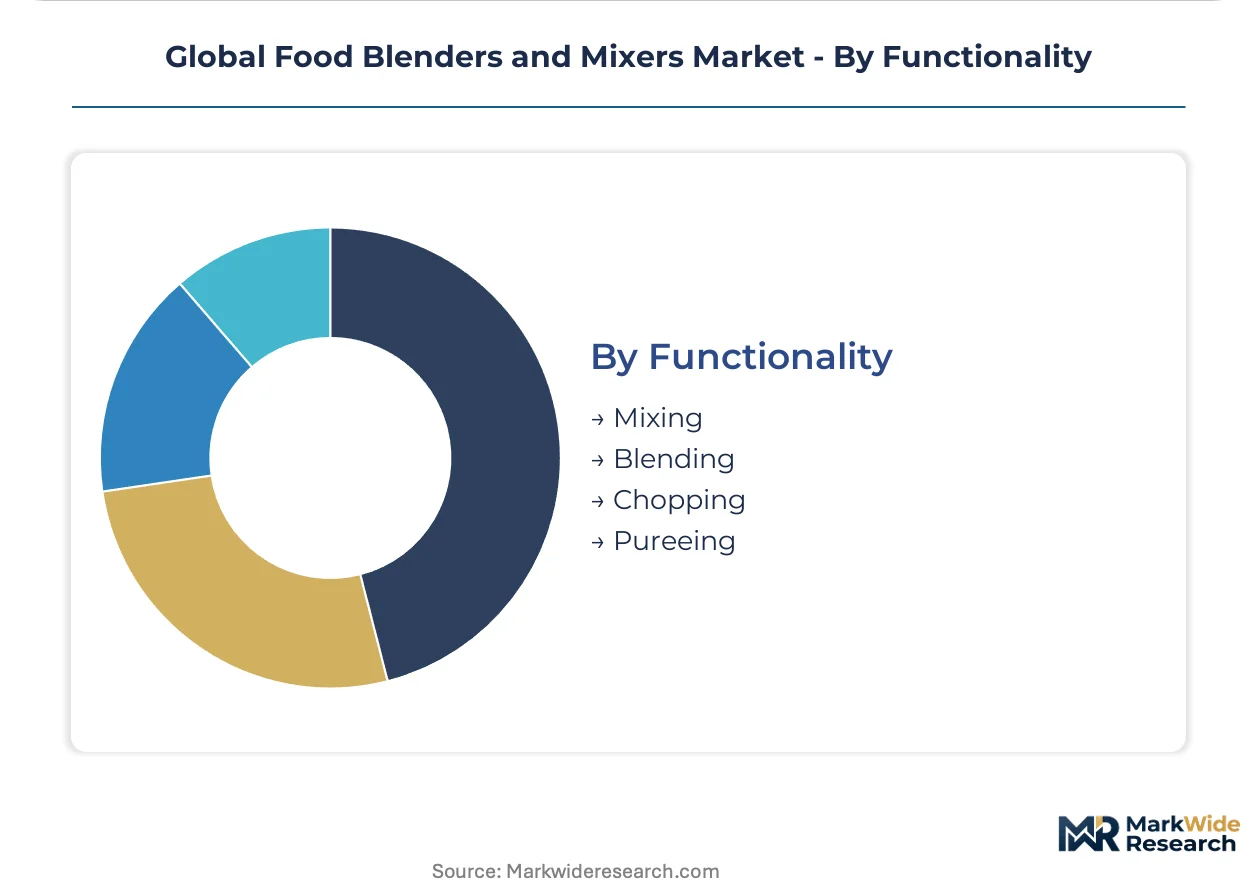
Functionality:
Volume throughput and shear precision requirements separate commodity mixing from premium-positioned emulsification and aeration applications.
- Mixing:Homogenization of discrete ingredients through controlled agitation represents the widest installed base across commercial and industrial segments. Variable-frequency drive systems enable energy-efficient operation under Europe's Ecodesign Directive thresholds.
- Blending:High-shear liquid processing for beverage and dairy applications demands precision impeller geometries. Current technical ceilings in protein structure preservation limit penetration in cultured meat and precision fermentation processing.
- Chopping:Solid reduction functionality with defined particle size distribution targets prepared-meal and infant-nutrition specifications.
- Pureeing:Fine matrix disruption for smooth-texture applications in clinical nutrition and premium foodservice positioning.
Mixing holds installed capacity. Blending is rotating up the share rankings as clean-label formulation complexity drives precision equipment specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites Europe's position in perishable food processing equipment trade, while China's high-speed rail network connects coastal manufacturing clusters to interior food processing zones.
United States
Quick-service restaurant chains are consolidating procurement through direct manufacturer relationships with embedded technical service teams. FDA Food Safety Modernization Act traceability mandates are accelerating equipment specification with sealed bearing housings and tool-free disassembly. Chicago's central kitchen corridor serves as the primary demand concentration for high-capacity batch mixers.
Germany
Industrial dairy and beverage processors are specifying magnetically coupled mixers to eliminate mechanical seal maintenance burdens. REACH restrictions on per- and polyfluoroalkyl substances are forcing redesign of PTFE-based bearing seals toward ceramic alternatives. Bavaria's food technology cluster anchors equipment engineering for hygienic processing applications.
China
Domestic food processing infrastructure is upgrading from manual batch operations to automated continuous processing systems. GB standards enforced by SAMR dictate material specifications and validation protocols for commercial kitchen equipment. Yangtze River Delta manufacturing zones are building regional service networks for industrial-scale homogenization equipment.
Netherlands
Dairy processors are deploying precision shear control systems for plant-based emulsion stabilization without synthetic additives. Ecodesign Directive energy-efficiency thresholds are compelling motor system redesigns and thermal management upgrades. Eindhoven's food technology corridor concentrates magnetically coupled mixer installations for new dairy facilities.
Indonesia
Central kitchen buildouts for chain restaurant expansion are creating demand for high-capacity batch mixers with remote monitoring functionality. National food safety infrastructure modernization is aligning equipment specifications with international sanitary standards. Jakarta's regional food preparation hubs are standardizing procurement across franchise networks.
Global Food Blenders and Mixers Market Vendor Landscape
On the supply side, the industry is consolidating around integrated process engineering groups with cross-category bundling capabilities. Equipment specification increasingly flows through direct technical sales relationships rather than distributor networks. Three archetypes dominate: diversified industrial conglomerates with hygienic processing heritage, specialized sanitary equipment fabricators, and precision motor system suppliers. Competitive moves center on magnetic drive coupling technology licensing and outcome-based performance guarantee contracting.
Within the diversified industrial tier, GEA Group and Tetra Laval occupy positions anchored by process engineering heritage and packaging line integration capabilities respectively. SPX Flow exemplifies the specialized sanitary fabricator archetype through its hygienic design focus. Buhler represents the Swiss precision engineering tradition in food processing equipment. These three entities collectively illustrate the competitive tension between integrated solution provision and specialized component excellence.
| Leading Market Players |
|---|
| GEA Group |
| Tetra Laval |
| SPX Flow |
| Alfa Laval |
| Marel |
| Vitamix |
| KitchenAid |
| Buhler |
| Philips |
| Others |
Supply Flow & Price Mechanics
The Port of Rotterdam's cold chain freight corridors transmit stainless steel input cost volatility directly into European equipment pricing, while simultaneously amplifying margin pressure on distributors serving quick-service restaurant chains with fixed-price contracts. This logistics chokepoint concentrates pricing power among German and Japanese motor suppliers who anchor tiered equipment cost structures across the analysis window.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified hygienic platforms from commercial kitchen workhorses and disposable household units. Price differentiation rests on CE marking tier and after-sales service bundling, with FDA-validated configurations commanding substantial premiums over baseline commercial specifications. Cost compression in the standard tier is intensifying because nickel and chromium spot market fluctuations compress fabricator margins on fixed-price distributor contracts. Quick-service restaurant procurement teams exhibit highest price sensitivity, while precision fermentation startups demonstrate lowest sensitivity due to protein structure preservation requirements.
Supply Chain Analysis
Stainless steel feedstock draws from Indonesian nickel smelters, Chinese chromium processors, and German specialty alloy foundries. High-torque variable-frequency drive motors hinge on Japanese precision manufacturing and German industrial automation clusters, creating single-source vulnerability for industrial mixer lead times. REACH restrictions on per- and polyfluoroalkyl substances compound regulatory friction across European supply nodes. Distribution runs through integrated direct-sales teams with embedded technical service capabilities rather than traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electromechanical technician training pipeline lag across Yangtze River Delta and Bavarian manufacturing zones constrains service capacity expansion, creating persistent capability scarcity that shapes competitive outcomes. Equipment specification increasingly demands hybrid skill sets spanning sealed bearing housing maintenance and cloud-based predictive analytics deployment.
For Market Incumbents: Insulate service revenue streams against magnetic drive coupling displacement by accelerating IoT-enabled predictive maintenance subscriptions. Secure captive supply of ceramic dry-running seal alternatives ahead of REACH enforcement timelines. Vertical integration into precision motor system sourcing mitigates lead time exposure from German and Japanese supplier concentration. For New Entrants and Emerging Players: Establish a beachhead in Indonesia's central kitchen buildout corridor where remote monitoring capabilities differentiate against legacy equipment incumbents. Target Vietnam's regional food preparation hub expansion with high-capacity batch mixer offerings priced below Tetra Laval bundled solutions. Pursue direct technical sales relationships with Southeast Asian chain restaurant procurement teams rather than distributor channel dependence. For Investors and Strategic Acquirers: Specialized sanitary equipment fabricators with hygienic design IP and established 3-A Sanitary Standards testing relationships represent the most defensible acquisition archetype. Long-term viability across the projection horizon depends on magnetic drive coupling technology licensing positions and outcome-based contracting capabilities. Monitor FDA Food Safety Modernization Act traceability mandate enforcement intensity as inflection indicator for sealed bearing housing specification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Drive Coupling Licensing | Eliminates mechanical seal maintenance burdens for Dutch dairy processors deploying new installations. |
| Ceramic Dry-Running Seal Qualification | Accelerates REACH compliance for German OEMs redesigning hygienic mixer lines. |
| IoT Predictive Maintenance Platform | Shifts customer relationships from transactional equipment sales to subscription-based service revenue. |
| Direct Technical Sales Team Expansion | Captures quick-service restaurant procurement consolidation away from traditional distributor networks. |
| Central Kitchen Remote Monitoring Integration | Addresses Indonesian and Vietnamese regional hub demand for high-capacity batch mixer oversight. |
Methodological Framework
Desk research of customs trade databases, SEC equipment manufacturer filings, and EU Ecodesign Directive regulatory precedents preceded structured interviews with food processing plant engineers, quick-service restaurant procurement directors, commercial kitchen equipment distributors, and aftermarket service technicians. Primary fieldwork across Yangtze River Delta manufacturing zones and Chicago's central kitchen corridor validated secondary demand indicators. Bottom-up equipment shipment data triangulated against top-down foodservice capital expenditure surveys to anchor volume estimates.
Assumptions held fixed include Europe's Ecodesign Directive energy-efficiency thresholds, FDA Food Safety Modernization Act traceability mandates, and China's GB standards enforcement intensity; variables stress-tested included nickel price volatility bands, precision motor supplier lead time scenarios, and alternative protein processing penetration rates. The analytical framework modeled product type, end user application intensity, distribution channel structure, and functionality precision requirements across the projection horizon. CAGRs derived from segment-level growth rate convergence analysis incorporating clean-label formulation complexity indices and central kitchen buildout pipeline data.
Stress conditions across stainless steel input costs, REACH regulatory enforcement timelines, and technician training pipeline output were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding equipment replacement cycle timing and multinational food manufacturer vendor panel consolidation trajectories. Cross-checking against EU industrial equipment production statistics and Chinese food processing machinery import data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Starch Recovery Systems Market
Food Processing Equipment
Food Automation Market
Food Processing Equipment
Industrial Steam Peeler Market
Food Processing Equipment
Blast Chillers Market
Food Processing Equipment
Smart Meat Thermometer Market
Food Processing Equipment
Ice Cream Equipment Market
Food Processing Equipment
Portioning Machines Market
Food Processing Equipment
Global Fermenters Market
Food Processing Equipment
Aseptic Processing Market
Food Processing Equipment
Global Commercial Food Dehydrators Market
Food Processing Equipment
Pizza Scissors Market
Food Processing Equipment
Nugget Ice Machines Market
Food Processing Equipment
Global Industrial Bakery Processing Equipment Market
Food Processing Equipment
Cook Processor Market
Food Processing Equipment
India Household Flour Milling Machines Market
Food Processing Equipment
Vacuum Cooling Equipment Market