
 Germany Seed Treatment Market | 2026-2036
Germany Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Seed Treatment Market Foresight
Biological active ingredients are expanding their share of formulation costs as synthetic chemistries face mounting regulatory pressure. BASF SE leverages its Ludwigshafen research infrastructure to sustain integrated development pipelines spanning chemical and biological platforms. Bayer AG anchors its German operations through seed treatment R&D co-located with crop science headquarters in Monheim. Syngenta AG competes through specialized biological seed treatment portfolios tailored to regional disease pressures.
Germany Seed Treatment encompasses the application of crop protection agents, biological stimulants, and physical coatings to seeds prior to planting, with formulations typically containing active concentrations between 50 and 600 grams per liter depending on target pest spectrum and crop sensitivity. The practice serves to protect germinating embryos from soil-borne pathogens and early-season insect pressure while improving stand establishment uniformity. Fungicides maintain the largest value share within product types as cereal growers prioritize control of Fusarium and bunt diseases that threaten yield stability across German bread wheat production. Biostimulants represent the fastest-expanding category as the EU Farm to Fork strategy accelerates farmer willingness to trial non-chemical alternatives. Seed coating dominates application method volumes due to its compatibility with high-speed drilling equipment standard on German arable farms.
The European Commission's Farm to Fork strategy and Germany's National Action Plan on Sustainable Use of Plant Protection Products jointly constrain synthetic pesticide availability while creating compliance obligations for treated seed disposal and buffer zone management. KBA and BVL enforcement of reduced-risk substance approvals shapes product registration timelines and determines which active ingredients remain accessible to German formulators. Stakeholders must monitor the pace of EU regulatory derogation renewals for neonicotinoid seed treatments and calibrate biological pipeline investments against the certainty of chemical withdrawal timelines.
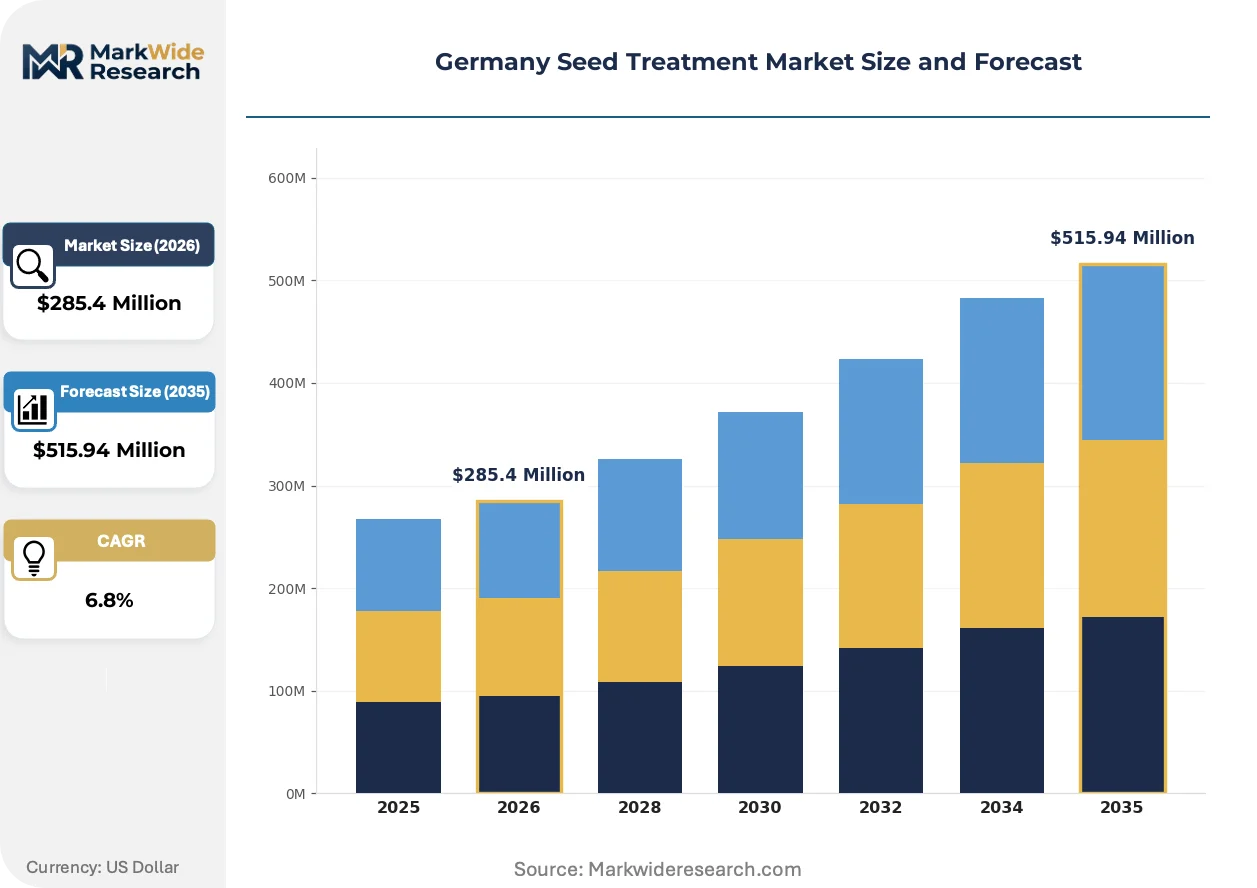
Market Dynamics
The EU Green Deal's chemical pesticide reduction targets are forcing German cereal farmers to reconstitute their seed protection strategies around biological alternatives, compressing formulation development cycles and redrawing competitive boundaries between synthetic and bio-based suppliers.
Growth Catalysts
- Farm to Fork Strategy:The European Commission's pesticide reduction mandates accelerate farmer willingness to trial biological seed treatments across German bread wheat operations.
- Fusarium pressure:Soil-borne pathogen severity in Bavaria's intensive cereal zones sustains fungicide demand while creating entry points for biocontrol integration.
- Seed coating standardization:Compatibility with high-speed drilling equipment on Lower Saxony arable farms drives uniform application method adoption.
Market Restraints
- Active ingredient volatility:KBA and BVL enforcement of reduced-risk substance approvals compresses accessible chemistries for German formulators.
- Biological efficacy gaps:Inconsistent performance of non-chemical alternatives against bunt diseases limits complete synthetic substitution in premium wheat segments.
- Disposal compliance costs:Germany's National Action Plan on Sustainable Use of Plant Protection Products imposes treated seed disposal obligations that inflate operational overhead.
Strategic Opportunities
- Neonicotinoid derogation windows:Uncertainty around EU regulatory renewal timelines creates temporary market space for biological pipeline investment calibration.
- Biostimulant convergence:Integration of microbial inoculants with physical coating technologies opens premium positioning in organic-transitioning cereal operations.
- Buffer zone innovation:Precision application technologies that reduce drift enable compliance with tightening aquatic protection standards in northern German watersheds.
Industry Challenges
- Formulation expertise scarcity:German agritech employers compete for biochemists capable of stabilizing live microbial cultures in seed coating matrices.
- Registration timeline compression:BVL's accelerated review schedules for biological actives strain dossier preparation capacity without guaranteed approval certainty.
- Equipment retrofit requirements:Legacy seed treatment machinery in Bavaria cooperatives demands capital outlay for biological-compatible temperature and humidity controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Seed Treatment Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungicides, Insecticides, Biostimulants, Nematicides, Herbicides Crop Type: Cereals, Oilseeds, Vegetables, Legumes, Fiber Crops Application Method: Seed Coating, Seed Dressing, Seed Pelleting, Film Coating, Powder Coating End User: Seed Producers, Contract Growers, Agricultural Cooperatives, Research Institutes |
| Companies Covered | BASF SE, Bayer AG, Syngenta AG, Corteva Agriscience, UPL Deutschland GmbH, Nufarm GmbH & Co KG, Certis Belchim, Humintech, KWS SAAT SE & Co. KGaA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Seed Treatment Market Shifts & Advancements
Biological active platforms are capturing formulation development investment as regulatory chemistry constraints harden, while precision application hardware and farmer data integration reshape how protection value is delivered and measured.
Microbial seed inoculants containing Trichoderma and Bacillus species are consolidating their position in German cereal protection protocols. Bavarian farm cooperatives now specify biological compatibility in new drilling equipment procurement. This consolidation is compressing the addressable market for single-mode synthetic fungicides while expanding service revenue for integrated pest management advisory.
Germany's National Action Plan on Sustainable Use of Plant Protection Products tightens treated seed disposal and buffer zone management obligations annually. Formulators must now design products for compliance with aquatic protection standards in northern watersheds. Cereal growers in Lower Saxony respond by prioritizing low-dust formulations that reduce surface water contamination risk.
Cooperative procurement consortia now aggregate seed treatment demand across multiple farm holdings to secure volume pricing and technical service access. Traditional agricultural merchant channels face margin compression as these buying groups negotiate direct supply relationships with BASF and Bayer field representatives. This concentration is most visible in eastern German arable regions where farm structure consolidation has proceeded fastest.
Germany Seed Treatment Market Segmentation
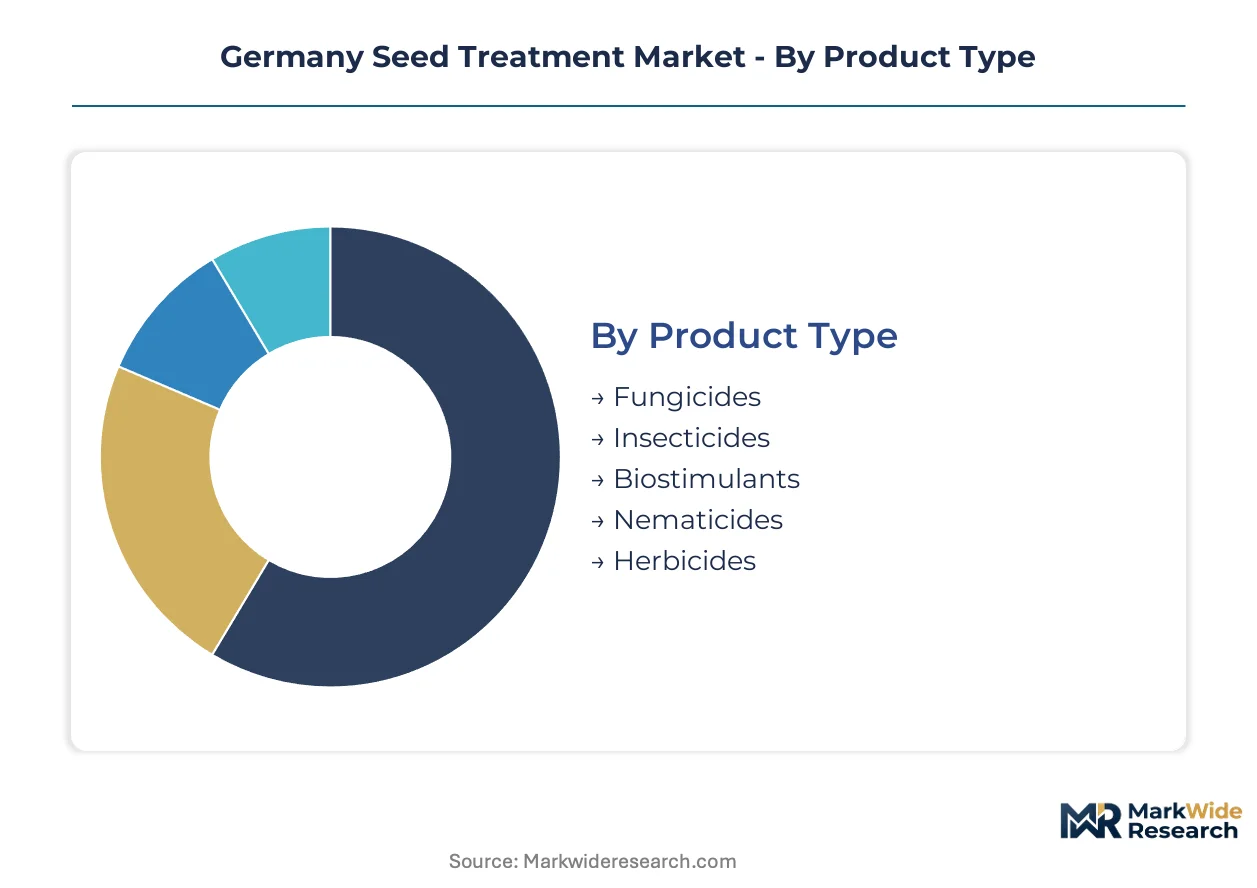
German seed treatment procurement fragments across four structural dimensions. Product chemistry, crop exposure, application hardware, and buyer configuration each create distinct commercial entry points and margin profiles for suppliers.
Product Type:
Fungicides dominate volume tonnage while biostimulants command premium positioning as regulatory pressure reshapes formulation economics.
- Fungicides:Formulations targeting Fusarium and bunt diseases in bread wheat contain active concentrations between 50 and 600 grams per liter. Bavarian cereal operations sustain the largest procurement volumes as soil-borne pathogen pressure intensifies in intensive arable zones.
- Biostimulants:Microbial inoculants containing Trichoderma and Bacillus species integrate with physical coating technologies. Lower Saxony organic-transitioning farms drive fastest category expansion under EU Farm to Fork compliance timelines.
- Insecticides:Neonicotinoid-based chemistries face KBA and BVL renewal uncertainty, compressing accessible actives for German formulators.
- Nematicides:Specialized protection for sugar beet and potato seed stocks addresses cyst nematode pressure in northern German loam soils.
- Herbicides:Pre-emergent weed control formulations remain niche, limited by crop phytotoxicity constraints in small-grain cereals.
Mature deployment sits with fungicides. Newer deployment is concentrated in biostimulants.
Crop Type:
Arable crop exposure determines treatment complexity and reapplication frequency across German agricultural regions.
- Cereals:Bread wheat, barley, and rye seed treatments account for the majority of hectare coverage. Fusarium pressure in Bavaria sustains multi-active fungicide demand while biocontrol integration accelerates.
- Oilseeds:Rapeseed protection prioritizes flea beetle and Phoma control. Eastern German farm structure consolidation drives cooperative procurement concentration for this segment.
- Vegetables:High-value specialty seed stocks command precision coating specifications. Research institutes in Baden-Württemberg trial biological alternatives for organic vegetable propagation.
- Legumes:Rhizobium inoculant compatibility shapes treatment formulation design for pea and faba bean operations.
- Fiber Crops:Limited hectarage restricts dedicated treatment development, with flax and hemp growers adapting cereal-derived chemistries.
Volume leadership resides with cereals. Margin expansion concentrates in vegetables.
Application Method:
Equipment compatibility and drift reduction requirements differentiate method selection across German farm scales.
- Seed Coating:Polymer-based film formations enable high-speed drilling compatibility standard on Lower Saxony arable equipment. Low-dust specifications address National Action Plan aquatic protection obligations in northern watersheds.
- Seed Dressing:Traditional powder and liquid applications persist in Bavarian cooperative facilities with legacy machinery infrastructure.
- Seed Pelleting:Bulking agents improve handling of small-seeded vegetable crops. Specialized equipment requirements limit adoption to research institutes and large-scale vegetable propagators.
- Film Coating:Ultra-thin polymer layers reduce active loading while maintaining protection efficacy. Precision application hardware investments concentrate in eastern German contract growing operations.
- Powder Coating:Dust formulations face tightening BVL occupational exposure limits, compressing accessible chemistries for on-farm treatment.
Equipment standardization favors seed coating. Regulatory pressure is displacing powder coating.
End User:
Buyer scale and technical capability determine service bundling and pricing power in German distribution channels.
- Seed Producers:Integrated breeding and treatment operations at Bayer Monheim and BASF Ludwigshafen facilities control proprietary formulation pipelines. Direct regulatory engagement with BVL accelerates registration timelines for captive actives.
- Contract Growers:Eastern German arable specialists aggregate hectarage under management, creating volume leverage for direct supplier negotiations bypassing traditional merchant channels.
- Agricultural Cooperatives:Bavarian and Lower Saxony buying groups specify biological compatibility in drilling equipment procurement and secure technical service access through consolidated demand.
- Research Institutes:Julius Kühn-Institut and regional university stations trial next-generation biological actives, generating efficacy data for BVL reduced-risk approval pathways.
Procurement concentration sits with seed producers. Cooperative consolidation is accelerating fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement volumes concentrate in Bavaria and Lower Saxony where large-scale arable farming dominates German seed treatment demand. The EU Green Deal's pesticide reduction targets are reshaping regional adoption patterns as biological alternatives gain traction across these intensive cereal zones.
Bavaria
Fusarium pressure in intensive cereal zones sustains multi-active fungicide demand while creating entry points for biocontrol integration. KBA enforcement of reduced-risk substance approvals shapes which actives remain accessible to Bavarian formulators. Farm cooperatives in the Munich-Augsburg corridor now specify biological compatibility in drilling equipment procurement.
Lower Saxony
High-speed drilling equipment standardization drives uniform seed coating adoption across Lower Saxony arable operations. The National Action Plan on Sustainable Use of Plant Protection Products imposes treated seed disposal obligations that inflate operational overhead. Cereal growers in the Hanover-Braunschweig region prioritize low-dust formulations to reduce surface water contamination risk.
Baden-Württemberg
Research institutes in Stuttgart and Freiburg trial next-generation biological actives for organic vegetable propagation. BVL's accelerated review schedules for biological actives strain dossier preparation capacity without guaranteed approval certainty. The Rhine-Neckar metropolitan region hosts specialized vegetable propagators adopting precision coating specifications.
North Rhine-Westphalia
Contract growing operations in the Münsterland district aggregate hectarage under management for direct supplier negotiations. Buffer zone management obligations under EU aquatic protection standards tighten annually in northern watersheds. Precision application hardware investments concentrate in eastern North Rhine-Westphalia to enable compliance with drift reduction mandates.
Brandenburg
Farm structure consolidation in eastern German arable regions accelerates cooperative procurement concentration. Legacy seed treatment machinery in regional cooperatives demands capital outlay for biological-compatible temperature and humidity controls. The Potsdam-Berlin corridor sees rising biostimulant trials as organic-transitioning operations expand.
Germany Seed Treatment Market Competitive Landscape
Portfolio diversification dominates the current landscape as synthetic chemistry constraints force biological pipeline investment. The vendor base consolidates around integrated crop science conglomerates with captive R&D infrastructure and specialized biological formulators with microbial stabilization expertise. Three strategic archetypes emerge: diversified agrichemical majors with seed treatment divisions, biological specialists with microbial formulation capabilities, and regional distributors with technical service bundling. M&A activity targets biological platform acquisitions while capacity expansion concentrates on coating facility upgrades for low-dust compliance.
Among Germany-based integrated majors, BASF SE anchors the diversified agrichemical archetype through its Ludwigshafen research infrastructure. Bayer AG occupies a position within the same tier, with Monheim operations co-locating seed treatment R&D with crop science headquarters. Syngenta AG exemplifies the biological specialization vector, competing through tailored microbial portfolios. These three represent distinct strategic responses to regulatory chemistry constraints reshaping competitive boundaries.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta AG |
| Corteva Agriscience |
| UPL Deutschland GmbH |
| Nufarm GmbH & Co KG |
| Certis Belchim |
| Humintech |
| KWS SAAT SE & Co. KGaA |
| Others |
Supply & Pricing Matrix
Captive integration of biological formulation R&D with coating facility operations anchors pricing power for German seed treatment suppliers, compressing margin exposure to raw material volatility while enabling premium positioning against merchant competitors dependent on outsourced active sourcing.
Pricing Analysis
Volume procurement through cooperative consortia concentrates in standard fungicide formulations while margin capture concentrates in biostimulant segments with microbial stabilization requirements. Price differentiation separates premium biological platforms certified under EU Green Deal compliance pathways from economy-tier synthetic chemistries facing KBA withdrawal timelines. Pricing pressure stems from biological efficacy gaps against bunt diseases that sustain residual synthetic demand in premium wheat segments. Contract growers demonstrate highest price sensitivity due to volume leverage in direct negotiations, while research institutes show lowest sensitivity given grant-funded procurement.
Supply Chain Analysis
Freight costs for temperature-sensitive microbial inoculants compress distribution radii from production facilities, favoring regional coating hubs over centralized manufacturing. Active ingredient supply concentrates in Germany, Switzerland, and the Netherlands for synthetic chemistries, with biological actives drawing from Danish and Dutch fermentation specialists. Raw material dependencies center on polymer coating substrates, live culture media, and specialized application equipment components. Single-source vulnerability sits with BVL-approved biological active suppliers where accelerated review timelines strain dossier preparation capacity. Distribution runs through agricultural cooperative channels bypassing traditional merchant intermediaries in eastern German arable regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German seed treatment is transitioning from synthetic chemistry dominance to biological platform integration, with microbial inoculants displacing legacy fungicide protocols under EU Farm to Fork mandates.
For Market Incumbents: Anchor biological pipeline investment against neonicotinoid derogation uncertainty, prioritizing Trichoderma and Bacillus formulation stability for Bavarian cooperative specifications. Defend position by securing captive coating facility capacity with temperature-controlled microbial handling, as legacy equipment retrofit costs strain regional cooperative budgets. Accelerate BVL pre-submission engagement for biological actives to compress approval timelines ahead of synthetic withdrawal windows. For New Entrants and Emerging Players: The premium-economy price-point gap in organic-transitioning cereal operations opens white-space positioning for mid-tier biological platforms with documented Fusarium suppression. Target Lower Saxony contract growing aggregations with precision coating compatibility specifications for high-speed drilling equipment. Pursue technical service bundling with equipment retrofit financing to bypass established cooperative supply relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in biological platform acquisitions by integrated agrichemical majors seeking microbial stabilization capabilities. Long-term viability favors formulators with captive BVL regulatory engagement and demonstrated coating matrix expertise over pure-play active suppliers. Monitor EU neonicotinoid derogation renewal announcements as inflection signals for biological pipeline valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Pipeline Investment | Microbial formulation capabilities secure positioning ahead of KBA synthetic withdrawals. |
| Coating Facility Upgrade | Low-dust compliance with National Action Plan aquatic standards enables northern watershed access. |
| Cooperative Procurement Consolidation | Volume aggregation across Bavarian and Lower Saxony holdings secures technical service access. |
| Precision Application Partnership | Drilling equipment compatibility specifications lock in biological platform adoption. |
| BVL Pre-Submission Engagement | Accelerated biological active review timelines compress competitive entry windows. |
Research Methodology
Independent corroboration across BASF and Bayer field representatives, Bavarian cooperative procurement managers, and Julius Kühn-Institut research directors underwrites the qualitative findings. Primary interviews with seed treatment formulators, agricultural equipment distributors, and BVL regulatory affairs specialists combined with secondary validation from EU pesticide registration databases, German customs trade records, and cooperative financial disclosures. Bottom-up hectarage coverage estimates triangulate against top-down supplier revenue allocations across product chemistry segments.
Comparable-period anchoring to historical cereal planting cycles and treatment penetration rates established the forecast baseline across the projection horizon. Segmentation dimensions modeled include product chemistry, crop exposure, application hardware, and buyer configuration, with regional regulatory cluster differentiation for EU Green Deal compliance timelines. CAGRs derived from volume-weighted average treatment intensity projections and biological substitution elasticity assumptions, incorporating KBA renewal probability distributions for restricted synthetics.
Inputs from BVL registration timelines and cooperative procurement records were available through the study window; gaps in confidential biological efficacy trial data introduce uncertainty bands around substitution rate assumptions. Forecasts reflect documented regulatory trajectories and documented farm structure consolidation patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
Seed Coating Materials Market
Seed Technology
Chitosan-based Seed Coatings Market
Seed Technology
Asia-Pacific Tomato Seed Market
Seed Technology
Seed Storage Systems Market
Seed Technology
North America Seed Coating Materials Market
Seed Technology
China Seed Treatment Market
Seed Technology
Mexico Seed Treatment Market
Seed Technology
Japan Seed Treatment Market
Seed Technology
Seed Quality Imaging and Germination Prediction Test Systems Market
Seed Technology
Asia-Pacific Seed Coating Materials Market
Seed Technology
Canada Seed Treatment Market
Seed Technology
Global Wheat Seed Treatment Market
Seed Technology
France Seed Treatment Market
Seed Technology
North America Cotton Seed Treatment Market
Seed Technology
Seed Additives Market
Seed Technology
India Seed Treatment Market