
 Automated People Mover Market | 2026-2036
Automated People Mover Market Size, Share, and Industry Trends Forecast 2026-2036
Automated People Mover Market Analysis
The EU Green Deal's decarbonization mandate for public transit is repositioning procurement criteria across European airport authorities and municipal operators. Alstom SA leverages its integrated signaling-platform portfolio to compete for turnkey APM installations in France and Belgium. CRRC Corporation Limited anchors volume production through captive rail manufacturing scale in Changzhou and Zhuzhou. Siemens AG extends its digital twin capabilities into predictive maintenance contracts for automated guideway systems.
Automated people movers are self-propelled, driverless transit vehicles operating on fixed guideways with automatic train control systems typically achieving headways of 90 to 120 seconds. These systems serve high-frequency passenger circulation in controlled environments such as airport terminals, urban centers, and entertainment districts. Monorail configurations dominate existing installed base owing to smaller footprint requirements in dense infrastructure corridors, while automated guided vehicle segments capture fastest expansion through modular deployment flexibility in commercial complexes. Light rail applications concentrate margin pools in integrated systems where signaling, platform screen doors, and vehicle supply bundle into single-source contracts.
The Federal Transit Administration administers capital investment grants requiring Buy America compliance for rolling stock and steel components, while the EU's F-Gas Regulation phases refrigerants in climate-controlled APM cabins. China's MIIT enforces GB standards for urban rail electromagnetic compatibility and fire safety in underground installations. Stakeholders must monitor divergence between regional certification regimes as modular vehicle platforms seek cross-border deployment.
Market Dynamics
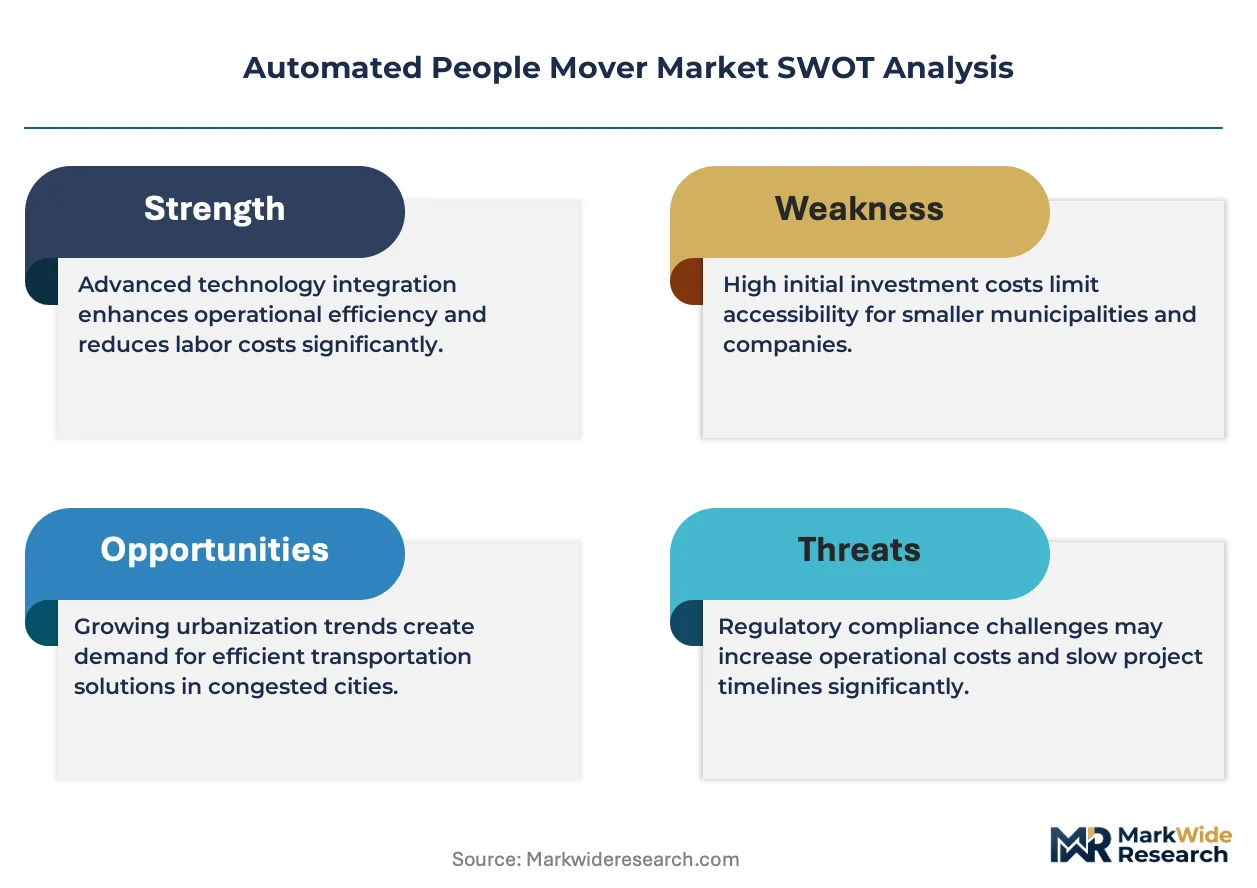
Federal Transit Administration capital investment grants are redirecting procurement criteria toward domestic manufacturing compliance, while EU Green Deal mandates force airport authorities to prioritize decarbonized transit architectures. This dual regulatory pressure is compressing vendor qualification timelines and elevating turnkey system integrators.
Growth Catalysts
- Airport Authority Modernization:United States transportation hubs under FAA oversight are replacing legacy bus circuits with automated guideway systems to reduce tarmac congestion and improve passenger throughput during peak boarding windows.
- REACH and F-Gas Phase-Down:European operators must retrofit climate-controlled cabins with low-global-warming-potential refrigerants, creating replacement demand for rolling stock and HVAC subsystems across Belgium, France, and Germany.
- Urban Rail Electrification Mandates:China's MIIT-enforced GB standards for electromagnetic compatibility and fire safety are accelerating underground APM deployments in Shenzhen and Chengdu metropolitan corridors.
Market Restraints
- Steel and Aluminum Input Volatility:Buy America compliance requirements for FTA-funded projects expose operators to domestic steel price swings that inflate rolling stock procurement budgets.
- Signaling System Concentration:Proprietary automatic train control architectures from a limited supplier base create vendor lock-in and complicate multi-source maintenance strategies.
- Guideway Infrastructure Capex Burden:Elevated concrete guideway construction demands specialized heavy civil contractors with scarce availability in secondary metropolitan markets.
Strategic Opportunities
- Entertainment and Commercial Complexes:Modular automated guided vehicle configurations are penetrating shopping districts and resort properties where fixed infrastructure investments face shorter payback thresholds.
- Digital Twin Integration:Convergence of predictive maintenance algorithms with real-time sensor networks enables performance-based service contracts that shift revenue from capital sales to recurring operational fees.
- India Urban Mobility Expansion:Metro rail corporations in Delhi, Mumbai, and Bangalore are evaluating APM feeder systems under central government smart city initiatives with dedicated transit-oriented development funding.
Industry Challenges
- Control Systems Engineering Talent Scarcity:Automatic train control software development requires specialized expertise in safety-critical embedded systems that outpaces university pipeline output.
- Multi-Standard Certification Complexity:Cross-border deployment of modular vehicle platforms demands simultaneous compliance with FTA Buy America, EU F-Gas, and Chinese GB electromagnetic standards, extending qualification timelines.
- Legacy Transit Interface Integration:APM installations must synchronize with existing platform screen doors, signaling networks, and passenger information systems that use incompatible communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated People Mover Market |
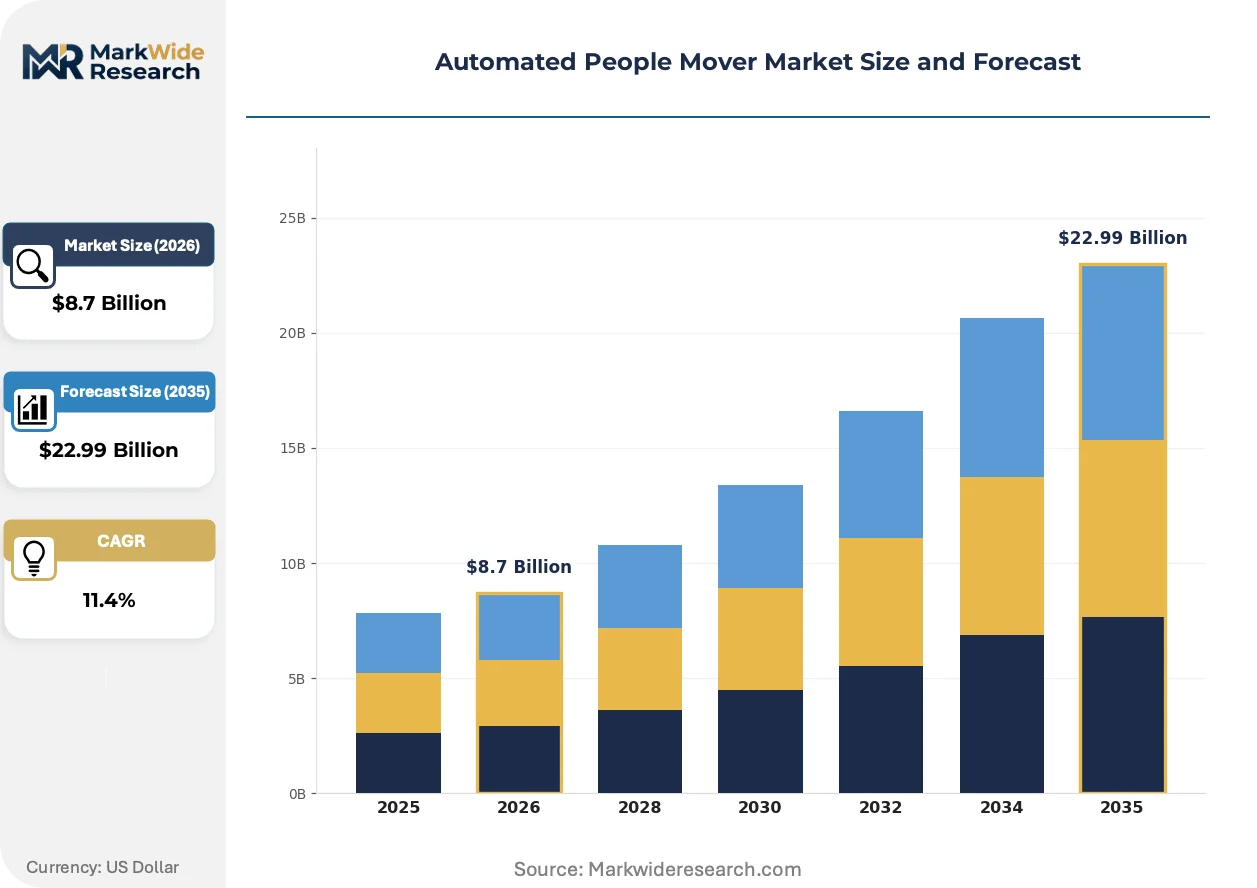
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Monorail, Light Rail, Heavy Rail, Automated Guided Vehicle Application: Airport Transportation, Urban Transit, Theme Parks, Commercial Complexes End User: Government, Private Enterprises, Municipalities, Transportation Authorities Installation: On-Site, Off-Site, Integrated Systems, Standalone Systems |
| Companies Covered | Kawasaki Heavy Industries Ltd., CRRC Corporation Limited, Alstom SA, Thales, Hyundai Rotem Company Ltd., Siemens AG, BYD Company Ltd., CAF SA, Mitsubishi Heavy Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated People Mover Market Emerging Trajectories
Battery-electric propulsion architectures are displacing traditional third-rail power collection across new installations, while digital twin platforms compress maintenance response intervals. Regulatory mandates on both sides of the Atlantic are forcing refrigerant and materials transitions that favor integrated system suppliers.
Lithium-titanate battery packs are electrifying onboard energy storage for automated guideway vehicles, eliminating exposed conductor rails in tunnel sections and reducing infrastructure capital intensity. Airport authorities in Denver and Orlando are specifying these configurations for terminal expansion phases. The technology is electrifying competitive differentiation among rolling stock vendors who can bundle battery management with regenerative braking systems.
The EU F-Gas Regulation mandates progressive phase-down of hydrofluorocarbon refrigerants in climate-controlled APM cabins, forcing HVAC subsystem redesigns before 2030 compliance deadlines. European airport operators in Paris and Amsterdam are accelerating procurement timelines to lock in compliant rolling stock ahead of supply bottlenecks. French and Belgian authorities are prioritizing turnkey contracts that bundle refrigerant-compliant climate systems with platform screen door installations.
Consolidated procurement frameworks are displacing fragmented vehicle-only purchasing across United States airport authorities, with FTA capital investment grants favoring single-source contracts spanning signaling, platforms, and rolling stock. Turnkey integrators capture margin pools that previously fragmented across subsystem vendors. This concentration is most visible in Dallas-Fort Worth and Atlanta hub expansions where multi-phase developments demand unified system architectures.
Automated People Mover Market Segmentation
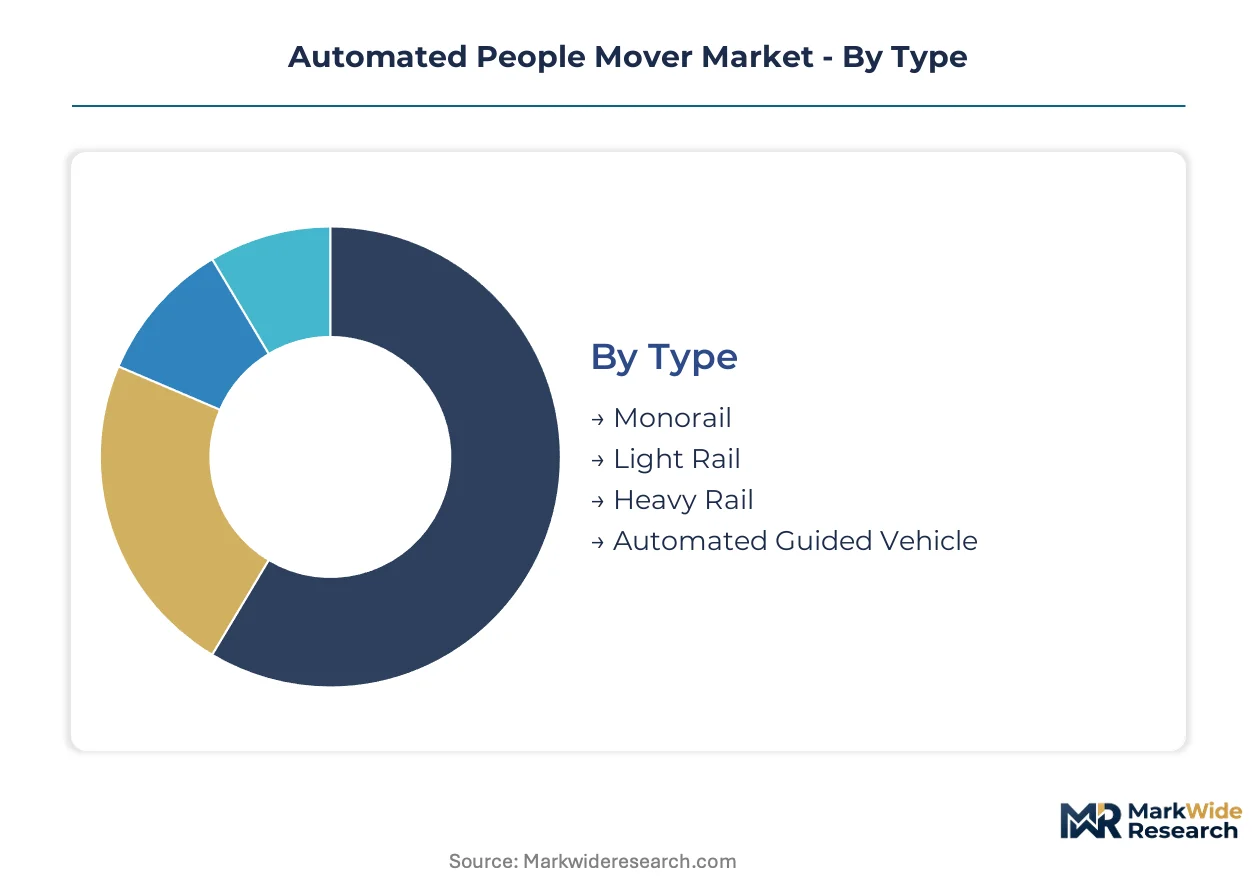
Automated people mover procurement varies sharply by deployment context, with airport authorities prioritizing throughput reliability while urban operators weigh guideway footprint against passenger volume. Segmentation reveals how technical specifications, institutional buyer types, and installation complexity create distinct margin pools across the value chain.
Type:
Buyers differentiate primarily by infrastructure constraints and passenger density requirements, with footprint limitations and tunnel clearances dictating vehicle configuration selection.
- Monorail:Single-beam guideway systems reduce structural mass for elevated corridors in dense urban cores. Demand concentrates in Chinese megacities where MIIT-enforced GB standards for electromagnetic compatibility favor proven beam-based architectures in Shenzhen and Chengdu underground networks.
- Automated Guided Vehicle:Modular, battery-electric configurations operate without fixed guideway infrastructure using optical or magnetic path following. Commercial complexes in Orlando and Denver are specifying these for terminal expansions where construction timelines preclude concrete elevated structures.
- Light Rail:Steel-wheel systems integrate with existing urban rail networks through compatible track gauges and signaling protocols.
- Heavy Rail:High-capacity metro-style vehicles serve passenger volumes exceeding 30,000 hourly in airport hub connections.
Monorail leads volumes today; automated guided vehicle configurations are gaining share fastest.
Application:
Revenue concentration tracks capital expenditure cycles, with FAA-supervised hub expansions and EU Green Deal transit mandates creating divergent procurement rhythms.
- Airport Transportation:Terminal-to-terminal circulation systems operate under FAA oversight with stringent availability requirements. United States transportation hubs are replacing legacy bus circuits with automated guideway systems to reduce tarmac congestion during peak boarding windows at Dallas-Fort Worth and Atlanta.
- Urban Transit:Municipal feeder networks connect metro stations to residential clusters. China's state-backed urban rail modernization programs anchor volume through centralized procurement in megacity corridors.
- Theme Parks:Controlled-environment installations prioritize experiential design integration over pure throughput metrics.
- Commercial Complexes:Shopping districts and resort properties deploy modular systems where fixed infrastructure faces shorter payback thresholds.
Urban transit commands the largest installed base; commercial complexes show the steepest expansion trajectory.
End User:
Contracting authority determines financing structure, with federal grant eligibility and turnkey integration requirements reshaping vendor qualification.
- Transportation Authorities:Airport and port districts with dedicated capital funding streams. FTA capital investment grants require Buy America compliance for rolling stock and steel components, compressing vendor timelines for domestic manufacturing verification.
- Government:National and state-level infrastructure agencies with multi-year appropriation cycles.
- Municipalities:City governments integrating APM feeders into smart city initiatives with transit-oriented development funding.
- Private Enterprises:Resort operators and commercial developers self-funding installations without federal grant dependencies.
Transportation authorities dominate procurement value; municipalities are expanding their share most rapidly.
Installation:
Delivery model selection hinges on site access constraints and the density of existing infrastructure interconnections.
- Integrated Systems:Unified contracts spanning signaling, platform screen doors, and rolling stock. Consolidated procurement frameworks are displacing fragmented vehicle-only purchasing across United States airport authorities, with FTA grants favoring single-source turnkey integrators.
- On-Site:Traditional construction with guideway assembly at final location.
- Off-Site:Prefabricated guideway segments transported to reduce construction duration.
- Standalone Systems:Isolated installations without interface requirements to legacy transit networks.
Integrated systems capture the majority of new contract value; off-site prefabrication is climbing fastest as contractors seek to mitigate heavy civil labor scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automated people mover systems originated in United States airport modernization programs during the 1970s, with Federal Transit Administration grant structures later spreading turnkey procurement models worldwide. Today's deployment geography reflects this institutional lineage alongside divergent regulatory frameworks.
United States
Airport authorities in Dallas-Fort Worth and Atlanta are consolidating procurement under Federal Transit Administration capital investment grants that mandate Buy America compliance for steel components and rolling stock. FAA oversight enforces stringent availability requirements for terminal-to-terminal circulation systems. Denver and Orlando hubs are specifying battery-electric configurations to eliminate exposed conductor rails in tunnel sections.
China
State-backed urban rail modernization programs concentrate demand in Shenzhen and Chengdu metropolitan corridors where underground APM deployments accelerate. The Ministry of Industry and Information Technology enforces GB standards for electromagnetic compatibility and fire safety in tunnel installations. Changzhou and Zhuzhou manufacturing clusters anchor volume production through captive rail manufacturing scale.
Germany
Industrial automation heritage positions German engineering firms to capture digital twin and predictive maintenance contracts for automated guideway systems. The EU F-Gas Regulation phases hydrofluorocarbon refrigerants in climate-controlled cabins, forcing HVAC subsystem redesigns before 2030 deadlines. Siemens AG extends its integrated signaling-platform portfolio across Belgian and French turnkey installations.
France
Paris and Amsterdam airport operators are accelerating procurement timelines to lock in F-Gas-compliant rolling stock ahead of supply bottlenecks. The EU Green Deal's decarbonization mandate repositions procurement criteria toward low-global-warming-potential refrigerant architectures. Alstom SA leverages its integrated signaling-platform portfolio to compete for turnkey APM installations in domestic and Belgian markets.
India
Metro rail corporations in Delhi, Mumbai, and Bangalore are evaluating APM feeder systems under central government smart city initiatives with dedicated transit-oriented development funding. The Bureau of Indian Standards and central electricity authority frameworks guide electromagnetic compatibility specifications for urban rail electrification. Municipal contracting authorities are expanding procurement share most rapidly among government buyer categories.
Automated People Mover Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the automated people mover value chain, with integrated system integrators capturing margin pools that previously fragmented across subsystem vendors. The vendor base concentrates around turnkey contractors capable of bundling signaling, platform screen doors, and rolling stock into single-source contracts. Three archetypes dominate: captive rail manufacturers with state-backed production scale, diversified industrial conglomerates with digital twin capabilities, and specialized airport system integrators with FAA certification experience. Competitive positioning hinges on strategic partnerships for battery-electric propulsion architectures and geographic expansion into Indian smart city corridors.
Among Asian industrial conglomerates, Kawasaki Heavy Industries Ltd. and Mitsubishi Heavy Industries Ltd. occupy positions shaped by Japanese precision manufacturing heritage and airport system integration expertise. CRRC Corporation Limited anchors the state-backed manufacturing archetype through volume production scale in Changzhou and Zhuzhou. Siemens AG and Alstom SA exemplify the European integrated systems model, with the former extending digital twin capabilities into predictive maintenance contracts and the latter competing for turnkey installations under EU Green Deal procurement criteria.
| Leading Market Players |
|---|
| Kawasaki Heavy Industries Ltd. |
| CRRC Corporation Limited |
| Alstom SA |
| Thales |
| Hyundai Rotem Company Ltd. |
| Siemens AG |
| BYD Company Ltd. |
| CAF SA |
| Mitsubishi Heavy Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
Control systems engineering talent scarcity in Germany's safety-critical embedded systems sector widens pricing-tier spreads between integrated turnkey contracts and fragmented subsystem procurement, as labor-cost differentials compound with FTA Buy America compliance premiums in United States airport authority tenders.
Pricing Analysis
Project-based long-term contracting dominates automated people mover procurement, with pricing stratifying across premium turnkey integrators, standard vehicle-only suppliers, and economy retrofit specialists. Price differentiation rests on certification grade — FTA Buy America compliance versus EU F-Gas refrigerant mandates — and after-sales service bundling. Cost compression in standard-tier rolling stock is intensifying because steel and aluminum input volatility exposes operators to domestic price swings. Municipal buyers in India show highest price sensitivity; United States transportation authorities with dedicated FTA capital grants demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with proprietary automatic train control architectures from limited European and Japanese supplier bases. Geographic supply concentration draws from China for battery-electric propulsion components, Germany for digital twin platforms, and the United States for heavy civil guideway construction. Raw material dependencies center on lithium-titanate battery packs, specialized signaling semiconductors, and Buy America-compliant steel. Regulatory restriction risk looms as cross-border deployment demands simultaneous FTA, EU F-Gas, and Chinese GB certification. Distribution runs through turnkey system integrators capturing consolidated procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated people mover market functions as a geographic-arbitrage play: India's Bureau of Indian Standards frameworks impose lower electromagnetic compatibility certification costs than EU F-Gas refrigerant mandates, redirecting vendor qualification investments toward South Asian smart city corridors.
For Market Incumbents: Hedge against battery-electric propulsion disruption by securing lithium-titanate supply agreements and backward integration into regenerative braking software. Alstom and Siemens face emerging threat from CRRC's state-backed manufacturing scale in Changzhou; defensive capacity addition in India leverages lower certification timelines. Priority lever: predictive maintenance algorithm development to shift revenue toward recurring operational fees. For New Entrants and Emerging Players: Digital-channel route through municipal smart city procurement portals offers lowest barrier-to-entry path. White-space targets concentrate in Bangalore and Delhi feeder system evaluations, plus Orlando and Denver commercial complex modular deployments. Most penetrable segment: automated guided vehicle configurations for shopping districts where fixed infrastructure payback thresholds compress. Go-to-market angle: battery management system bundling with HVAC subsystem redesigns. For Investors and Strategic Acquirers: Industrial automation conglomerates with airport system integration expertise are the most active acquirer in this space. Long-term viability over a decade hinges on turnkey contract consolidation displacing fragmented vehicle-only purchasing. Acquisition target archetype: specialized automatic train control software developers with safety-critical embedded systems expertise. Signal to watch: FTA grant allocation acceleration toward single-source integrators versus subsystem vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Turnkey System Integration | Captures margin pools previously fragmented across signaling, platform, and rolling stock vendors under FTA grant structures. |
| Battery-Electric Propulsion Transition | Eliminates exposed conductor rails in Denver and Orlando tunnel sections while reducing infrastructure capital intensity. |
| Digital Twin Platform Deployment | Enables Siemens and Alstom to extend predictive maintenance contracts compressing response intervals for airport authorities. |
| Regulatory Compliance Pre-Positioning | Locks in F-Gas-compliant rolling stock ahead of 2030 deadlines for Paris and Amsterdam airport operators. |
| Geographic Manufacturing Footprint Expansion | CRRC anchors volume production in Changzhou and Zhuzhou to serve Shenzhen and Chengdu underground deployments. |
Methodological Framework
Multiple input streams — primary interviews with airport procurement directors, signaling system engineers, and FTA grant administrators; secondary validation through FAA oversight documentation, EU F-Gas Regulation filings, and Chinese MIIT GB standard publications — were reconciled through bottom-up and top-down triangulation across the analysis window.
Historical capital expenditure cycles were cross-referenced against expert panel inputs on procurement timeline compression. Segmentation dimensions modeled include vehicle configuration type, application context, end-user contracting authority, and installation delivery model. CAGRs were derived from reconciling vendor shipment data with infrastructure investment flows. Industry-specific forecast inputs incorporated battery-electric propulsion adoption curves and refrigerant phase-down compliance deadlines.
The model assumes a particular technology adoption path; alternative pathways for autonomous shuttle architectures without fixed guideway infrastructure would alter the outlook. Forecasts reflect assumptions on FTA grant continuity, EU Green Deal mandate enforcement, and Chinese state-backed urban rail program funding levels. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Road Weather Information Systems (RWIS) Market
Smart Transportation Solutions
France Ridesharing Market
Smart Transportation Solutions
Global IoT Fleet Management Market
Smart Transportation Solutions
Rail Internet of Things (IoT) Market
Smart Transportation Solutions
Shared Vehicles Market
Smart Transportation Solutions
Shared Mobility Market
Smart Transportation Solutions
Fleet Management Solution Market
Smart Transportation Solutions
Alternate Transportation Market
Smart Transportation Solutions
Europe Electronic Toll Collection Market
Smart Transportation Solutions
Semi Height Platform Screen Door Market
Smart Transportation Solutions
Intelligent Traffic Management Market
Smart Transportation Solutions
Automatic Identification Systems (AIS) Market
Smart Transportation Solutions
Automated Robotic Parking System Market
Smart Transportation Solutions
E-Scooter Sharing Market
Smart Transportation Solutions
Smart Mobility Market
Smart Transportation Solutions
North America IoT Transportation Market