
 Transportation Vehicle Automated Passenger Counting (APC) System Market | 2026-2036
Transportation Vehicle Automated Passenger Counting (APC) System Market Size, Share, and Industry Trends Forecast 2026-2036
Transportation Vehicle Automated Passenger Counting (APC) System Market Insights
Edge-based video analytics with onboard AI inference is rewriting how APC systems process passenger flow data without relying on constant cloud connectivity. Siemens leverages its industrial automation heritage to sustain engineering depth in rail-grade counting solutions. HELLA Aglaia Mobile Vision GmbH anchors its position through specialized automotive vision expertise adapted for transit environments.
Transportation Vehicle Automated Passenger Counting (APC) Systems comprise sensor arrays, edge processors, and analytics software that detect and log passenger boardings and alightings with accuracy rates typically exceeding 95 percent in standard conditions. These systems serve transit operators by generating real-time occupancy data that feeds into fleet management, revenue allocation, and service planning decisions. Video analytics solutions command attention due to their ability to distinguish individual passengers in dense crowds where infrared beam systems miscount. Machine learning technology underpins the fastest-improving performance tier, as neural network models trained on diverse demographic datasets reduce edge-case counting errors. IoT connectivity segments mature into commodity status, with cellular and Wi-Fi modules becoming standard rather than differentiating features.
The Federal Transit Administration in the United States mandates accurate ridership reporting for funding eligibility, compelling transit authorities to adopt certified APC technologies. The European Union's GDPR framework shapes how passenger flow data may be stored and shared, particularly for video-based systems that capture identifiable images. Stakeholders must weigh the trade-off between counting precision and privacy compliance as regulatory scrutiny of biometric-adjacent transit data intensifies.
Market Dynamics
Edge computing architectures are compressing latency requirements for real-time passenger analytics, forcing transit operators to reconfigure fleet IT infrastructure around distributed processing nodes rather than centralized cloud dependency.
Growth Catalysts
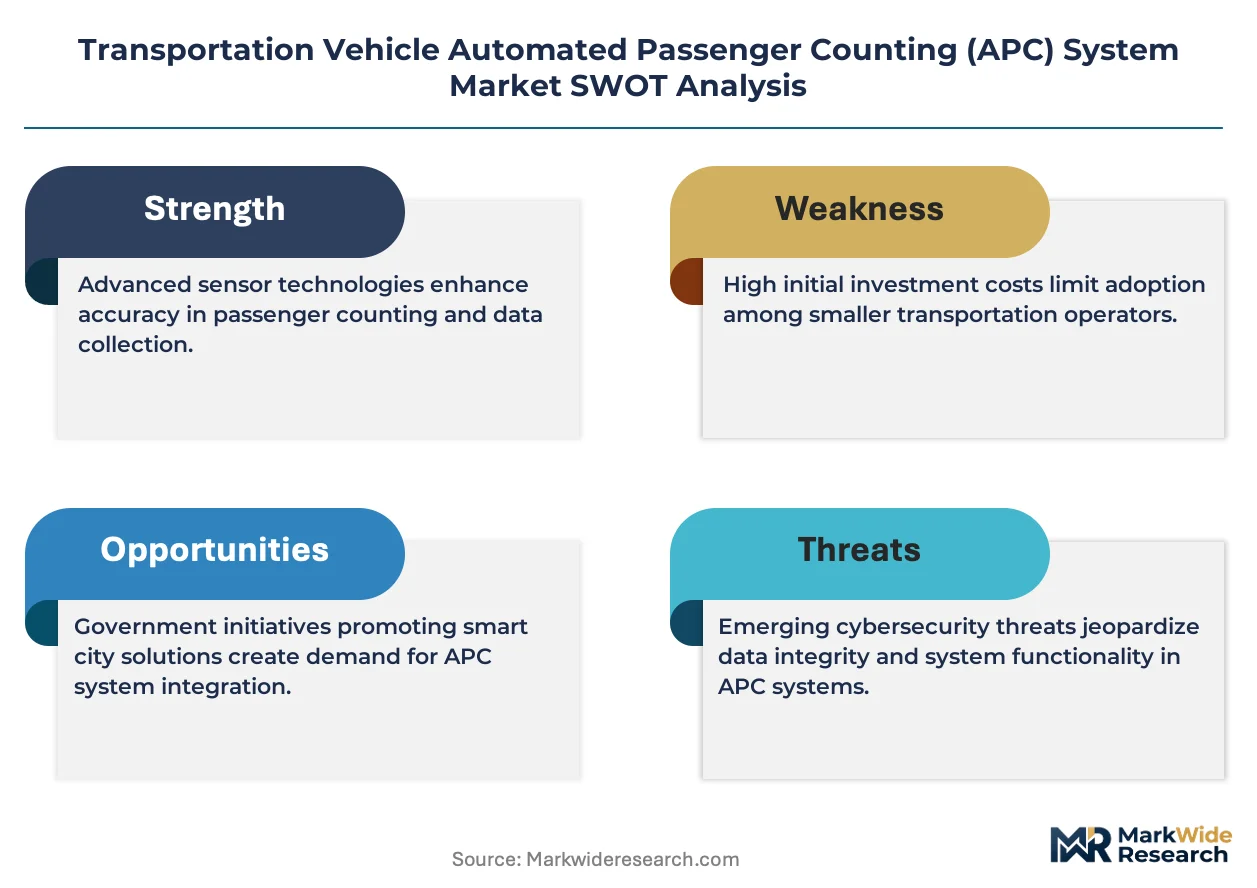
- GDPR-compliant data frameworks:European transit authorities accelerate APC deployments knowing anonymization protocols satisfy privacy mandates while enabling ridership optimization.
- Machine learning inference:Neural network models trained on diverse passenger demographics reduce counting errors in variable lighting conditions across underground metro environments.
- Germany:Municipal operators in Berlin, Munich, and Hamburg mandate real-time occupancy feeds for dynamic fleet scheduling, creating concentrated demand for video-based APC systems.
Market Restraints
- Semiconductor supply concentration:Edge processor availability depends on fabrication capacity concentrated in Taiwan and South Korea, exposing deployment timelines to foundry allocation decisions.
- Infrared beam legacy infrastructure:Existing hardware investments in older counting technologies create switching costs that delay full-system replacements despite accuracy limitations.
- GDPR enforcement variance:Interpretation of biometric-adjacent data rules differs across EU member states, complicating cross-border fleet standardization for multinational operators.
Strategic Opportunities
- India:Metro construction in Delhi, Mumbai, and Bangalore outpaces APC installation rates, leaving substantial white space for first-mover system integrators.
- 5G-V2X convergence:Integration of cellular vehicle-to-everything connectivity with passenger counting hardware enables predictive crowding alerts distributed directly to rider smartphones.
- California SB 1251:State-level transit equity mandates require granular ridership data by route and time-of-day, compelling agencies to upgrade from sampled counts to continuous APC coverage.
Industry Challenges
- Embedded vision engineering talent:Shortage of specialists capable of optimizing neural networks for resource-constrained edge processors extends development cycles for accuracy improvements.
- Legacy AVL integration:Automatic Vehicle Location systems deployed in the 2010s lack standardized APIs, forcing custom middleware development for APC data fusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transportation Vehicle Automated Passenger Counting (APC) System Market |
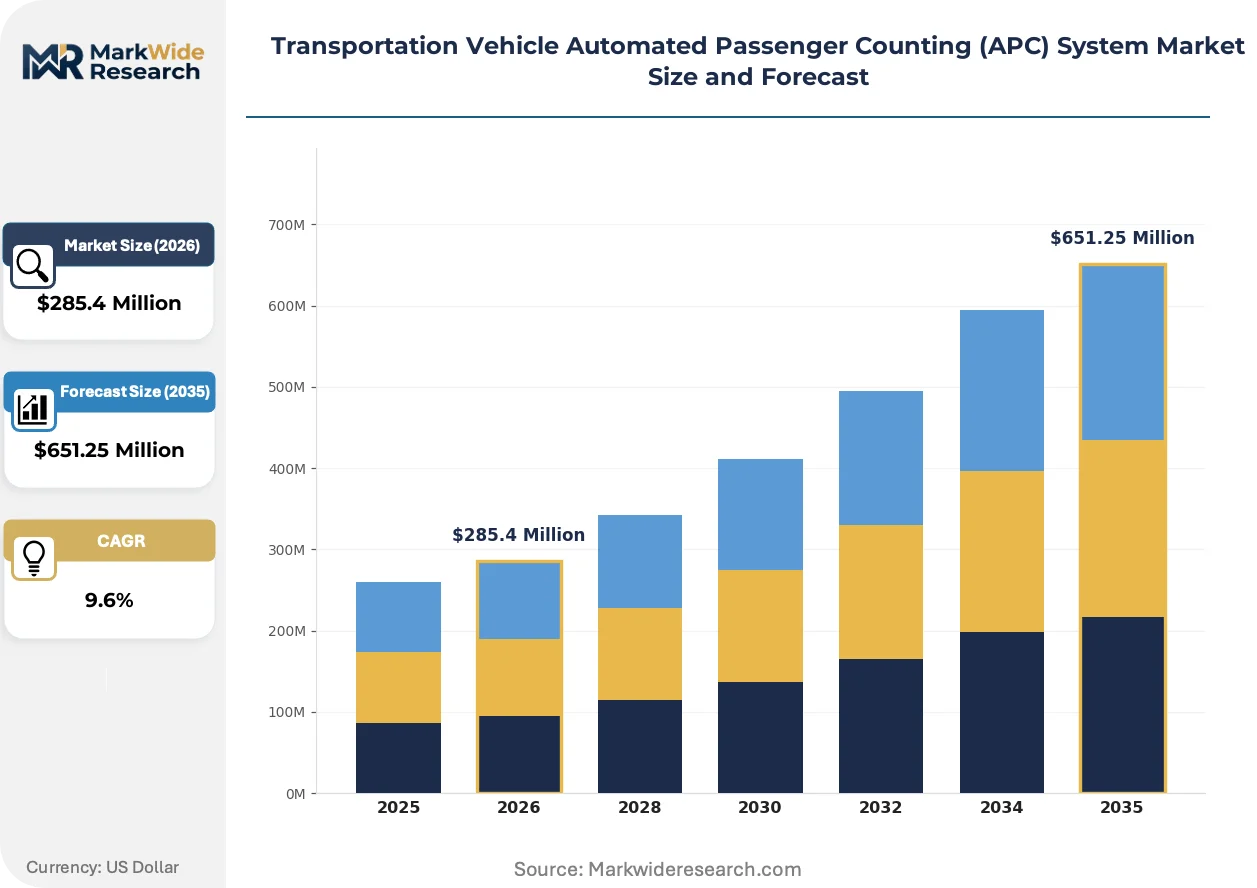
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $651.25 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Sensors, Video Analytics, Thermal Cameras, Pressure Sensors Application: Public Transport, Shuttle Services, School Buses, Railways Technology: Machine Learning, Data Analytics, IoT Connectivity, Cloud Computing End User: Transit Authorities, Private Operators, Educational Institutions, Research Organizations |
| Companies Covered | iris GmbH, HELLA Aglaia Mobile Vision GmbH, DILAX Intelcom GmbH, Infodev EDI, Siemens, Eurotech S.p.A., Init, Passio Technologies, Clever Devices Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transportation Vehicle Automated Passenger Counting (APC) System Market Trends and Innovations
Processing architectures for passenger analytics are redistributing computational load away from remote data centers, enabling real-time decision-making aboard vehicles even during tunnel-induced connectivity gaps.
Time-of-flight depth sensors are migrating from experimental pilot programs to standard equipment specifications for new bus procurements. Transit agencies in the Netherlands and Singapore now require sub-5cm depth resolution for accurate passenger separation in dense boarding scenarios. This migration from 2D imaging to volumetric sensing is compressing competitive differentiation around hardware precision rather than software-only analytics.
The European Union's AI Act establishes risk classification frameworks for automated decision systems processing passenger data. Transit operators must document algorithmic transparency for high-risk deployments, adding compliance overhead to video-based APC implementations. German and French authorities are responding by mandating third-party accuracy certification before system acceptance.
Buying patterns among municipal transit agencies are consolidating around framework agreements with pre-qualified system integrators. Single-source procurement is displacing open tender processes for APC upgrades, particularly in mid-sized European cities lacking internal technical evaluation capacity. This concentration is most visible in Scandinavia, where regional purchasing cooperatives negotiate multi-year supply contracts covering rolling stock and onboard analytics as bundled packages.
Transportation Vehicle Automated Passenger Counting (APC) System Market Segmentation
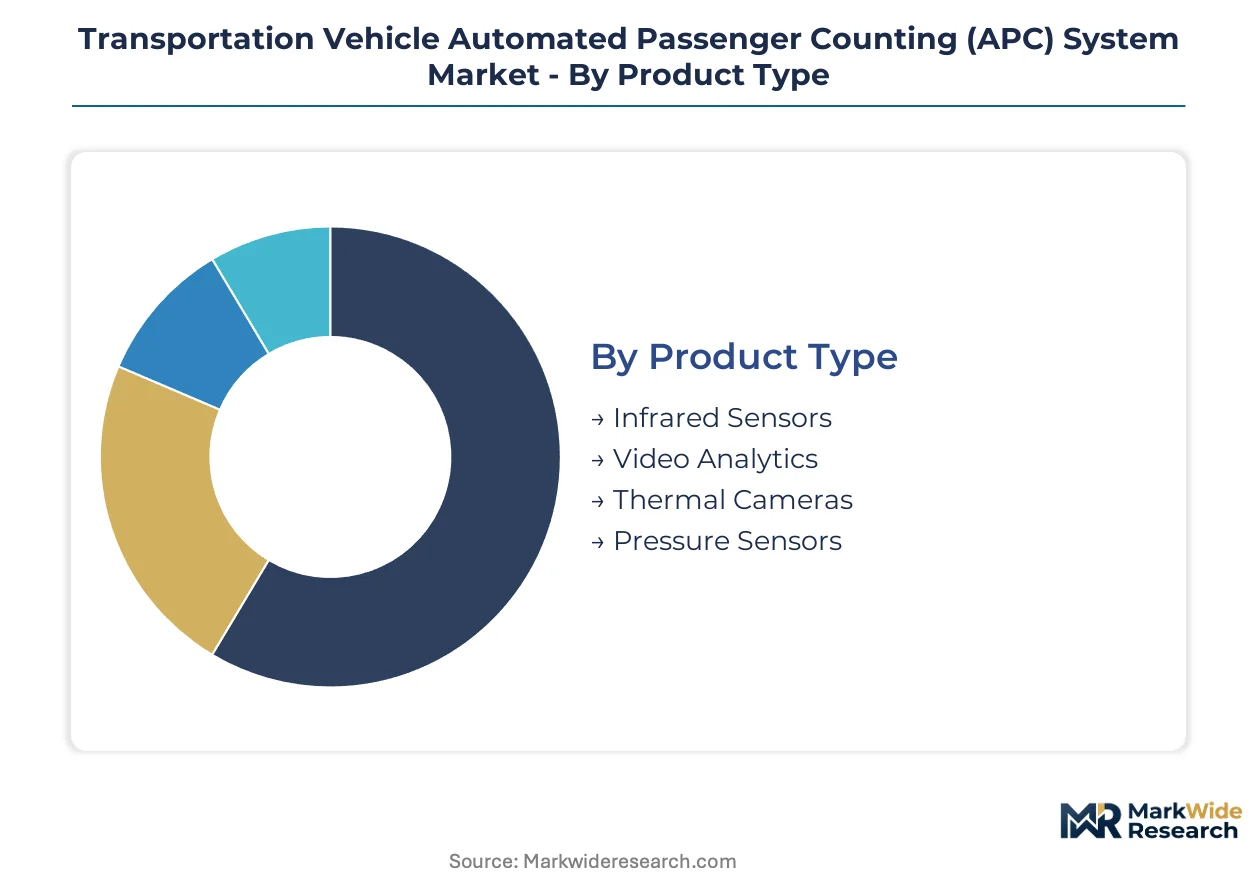
APC system procurement cycles vary dramatically by component type, with sensor hardware refreshing every 5-7 years while analytics software updates deploy continuously via over-the-air patches. Understanding these replacement rhythms helps vendors align R&D investment with predictable revenue windows.
Product Type:
Video analytics platforms turn over fastest as neural network architectures improve quarterly, while infrared sensors persist longest due to mechanical simplicity and transit agency capital planning cycles.
- Video Analytics:Camera arrays paired with onboard GPUs process passenger silhouettes through convolutional neural networks optimized for edge inference. Berlin's BVG and Munich's MVG mandate sub-2% error rates for crowding alerts, driving demand for 4K stereo vision configurations with depth estimation.
- Infrared Sensors:Beam-break arrays mounted at vehicle doorways detect passage interruptions using paired emitter-receiver modules. Legacy installations across German S-Bahn networks create switching cost barriers despite accuracy limitations in dense boarding scenarios.
- Thermal Cameras:Uncooled microbolometer sensors capture passenger heat signatures independent of ambient lighting, penetrating tinted glass and direct sunlight that blind visible-spectrum systems.
- Pressure Sensors:Floor-mounted load cells estimate occupancy through weight distribution mapping, deployed primarily in low-floor buses where mechanical durability exceeds precision requirements.
Infrared sensors dominate installed base. Video analytics is where expansion concentrates.
Application:
Cost tier separation shapes procurement patterns, with metro systems funding premium multi-sensor fusion while school districts prioritize basic beam counters meeting federal reporting minimums.
- Public Transport:Urban metro and bus networks demand real-time occupancy feeds integrated with CAD/AVL systems for dynamic headway adjustment. GDPR-compliant anonymization protocols enable ridership optimization without biometric data retention risks.
- Railways:High-capacity commuter rail requires platform-edge counting synchronized with train doors, where time-of-flight depth sensors resolve passenger separation in crush-loading conditions. Dutch NS and Singapore LTA now specify sub-5cm depth resolution in tender documents.
- Shuttle Services:On-demand microtransit operators deploy lightweight APC for route profitability analysis, with cellular backhaul replacing hardwired infrastructure.
- School Buses:Districts satisfy state reporting mandates through basic passenger tallies, with pressure mat systems dominating due to vandal resistance and minimal maintenance.
Public transport commands premium pricing. Railways is gaining share fastest as European operators modernize rolling stock.
Technology:
Volume concentration clusters around connectivity layers commoditizing fastest, while differentiation migrates toward inference engines requiring specialized engineering talent.
- Machine Learning:Neural network models trained on diverse demographic datasets reduce counting errors in variable lighting across underground environments. Edge processor shortages from Taiwan foundries constrain deployment timelines despite algorithmic readiness.
- IoT Connectivity:Cellular and Wi-Fi modules achieve commodity status as standard equipment, with 5G-V2X integration emerging as the next capability frontier for predictive crowding alerts.
- Data Analytics:Backend platforms aggregate fleet-wide occupancy patterns for service planning, with cloud-native architectures displacing on-premise deployments among mid-sized agencies.
- Cloud Computing:Hybrid architectures balance real-time edge inference with historical trend analysis, though tunnel connectivity gaps mandate onboard processing redundancy.
IoT connectivity saturates new installations. Machine learning is climbing the fastest as accuracy certification becomes mandatory.
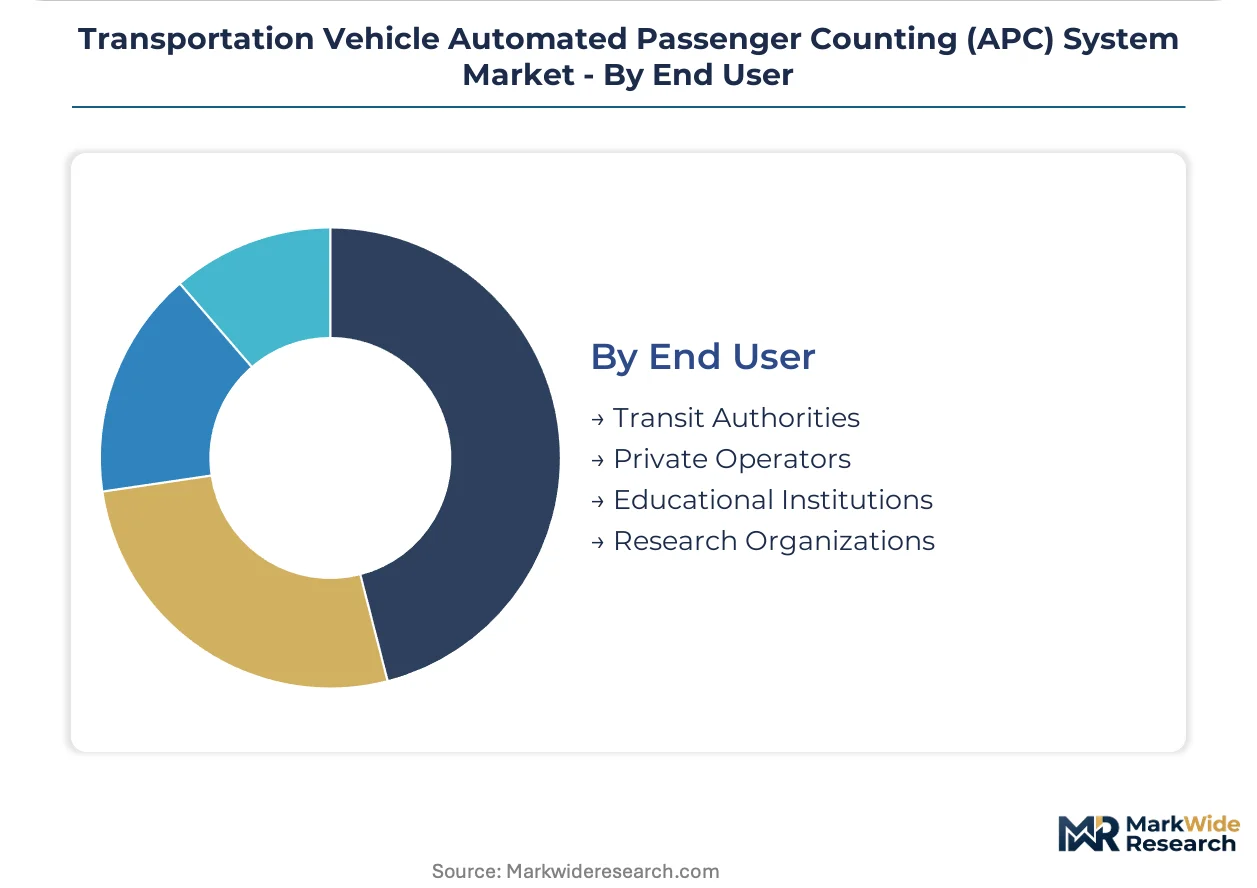
End User:
Customer type determines procurement sophistication, with transit authorities running competitive tenders while private operators favor bundled fleet management contracts.
- Transit Authorities:Municipal operators in Hamburg and Berlin mandate open APIs for CAD/AVL integration, with framework agreements consolidating vendor selection around pre-qualified system integrators.
- Private Operators:Contracted bus services prioritize total cost of ownership over acquisition price, accepting higher upfront investment for predictive maintenance compatibility.
- Educational Institutions:University shuttle systems deploy APC for demand-responsive service adjustments, with procurement decentralized across individual campus facilities.
- Research Organizations:Pilot programs test experimental sensing modalities including radar and lidar, though commercial scale remains limited by unit economics.
Transit authorities dominate contract value. Private operators are expanding most quickly as contracted service models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German APC system manufacturers export video analytics hardware to Dutch and Singaporean transit operators modernizing metro rolling stock. This trade corridor reflects Europe's concentration of rail-grade counting expertise serving Asian infrastructure expansion.
United States
The Federal Transit Administration mandates certified ridership reporting for funding eligibility, compelling municipal agencies to upgrade from manual sampling. California SB 1251 requires granular route-level data, driving demand in Los Angeles and San Francisco Bay Area transit districts. Chicago Transit Authority deploys edge-based systems for real-time crowding alerts across elevated rail corridors.
Germany
Berlin BVG and Munich MVG mandate sub-2% error rates for crowding management, creating concentrated demand for stereo vision configurations. KBA certification requirements shape procurement standards for rail-grade installations. Hamburg Hochbahn integrates real-time occupancy feeds with dynamic fleet scheduling algorithms across U-Bahn and bus networks.
Singapore
The Land Transport Authority specifies sub-5cm depth resolution for platform-edge counting in crush-loading conditions. National procurement frameworks prioritize accuracy certification before system acceptance. Jurong Region Line construction incorporates time-of-flight sensors as standard equipment in new metro rolling stock.
Netherlands
Nederlandse Spoorwegen tenders require volumetric sensing for passenger separation at high-capacity stations. National rail modernization programs displace legacy infrared beam installations. Amsterdam and Rotterdam metro operators deploy video analytics with GDPR-compliant anonymization protocols.
India
Metro construction in Delhi, Mumbai, and Bangalore outpaces APC installation rates, leaving substantial deployment white space. National urban transport missions prioritize real-time fleet management capabilities. Delhi Metro Rail Corporation tests edge-based inference systems for underground connectivity resilience.
Transportation Vehicle Automated Passenger Counting (APC) System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement segments. The vendor base clusters around three strategic archetypes: industrial automation conglomerates with rail heritage, automotive vision specialists adapting transit applications, and pure-play analytics software houses. Consolidation pressure intensifies as framework agreements displace open tenders in mid-sized European cities. Dominant competitive moves include strategic partnerships for CAD/AVL integration and geographic expansion through system integrator alliances.
Among German-based engineering groups, iris GmbH and HELLA Aglaia Mobile Vision GmbH exemplify the automotive-to-transit adaptation archetype, while Siemens occupies a position representing industrial automation heritage in rail-grade solutions. These three entities anchor the premium tier where accuracy certification and open API compliance determine vendor selection.
| Leading Market Players |
|---|
| iris GmbH |
| HELLA Aglaia Mobile Vision GmbH |
| DILAX Intelcom GmbH |
| Infodev EDI |
| Siemens |
| Eurotech S.p.A. |
| Init |
| Passio Technologies |
| Clever Devices Ltd |
| Others |
Pricing and Supply Chain Analysis
Undercapacity at Taiwan foundries is compressing edge processor availability and forcing APC vendors to allocate limited silicon to premium-tier contracts while standard-system deliveries face extended lead times. This utilization squeeze simultaneously elevates pricing power for qualified suppliers and accelerates buyer migration toward software-upgrade pathways that extend hardware lifecycles.
Pricing Analysis
Current-generation stereo vision configurations command substantial premiums over legacy infrared beam systems, while next-generation time-of-flight depth sensors carry additional certification-grade markups. Pricing stratifies across premium, standard, and economy tiers where sub-2% accuracy certification from German KBA or Singapore LTA determines tier placement. Cost compression in standard-tier video analytics is intensifying because commoditized IoT connectivity modules eliminate differentiation leverage. School bus operators exhibit highest price sensitivity, accepting pressure-mat systems with 5-7% error rates rather than funding precision upgrades.
Supply Chain Analysis
CMOS image sensors and edge AI processors draw from fabrication capacity concentrated in Taiwan, South Korea, and mainland China. Uncooled microbolometer arrays for thermal cameras rest on germanium and vanadium oxide supply chains anchored in Belgium and Japan. Single-source vulnerability around TSMC's 7nm automotive-grade node exposes deployment timelines to foundry allocation decisions. Distribution runs through system integrators holding framework agreements with municipal transit authorities, particularly in German-speaking markets where KBA certification creates qualified-supplier bottlenecks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Scandinavian regional purchasing cooperatives and German framework agreements displace open tenders, consolidating procurement leverage among fewer decision-makers. This consolidation elevates vendor qualification requirements while compressing margins for non-preferred suppliers.
For Market Incumbents: Insulate certification-grade positioning by deepening KBA and LTA accuracy validation pipelines before framework agreement renewal cycles. Secure captive supply of automotive-grade edge processors through direct foundry allocation commitments, neutralizing semiconductor shortage threats that delay competitor deliveries. Prioritize open API development for legacy CAD/AVL middleware integration, locking in switching-cost advantages against pure-play analytics entrants.
For New Entrants and Emerging Players: Pursue white-space deployment in Indian metro construction corridors where APC installation rates lag rolling stock delivery schedules. Target on-demand microtransit operators with lightweight cellular-backhaul systems bypassing hardwired infrastructure requirements. Anchor go-to-market strategy through system integrator alliances rather than direct municipal tender competition.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across video analytics software layers as neural network architectures achieve commodity status, while hardware precision tiers retain upstream value capture. Long-term viability favors automotive vision specialists with transit-adaptable IP and established accuracy certification relationships. Monitor 5G-V2X module integration timelines as inflection signal for predictive crowding alert monetization potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Accuracy Certification Investment | KBA and LTA validation opens framework agreement access in German and Singaporean transit markets. |
| Edge Processor Supply Agreement | Direct foundry allocation insulates delivery timelines against Taiwan capacity constraints. |
| CAD/AVL Platform Integration | Open API compatibility locks in switching-cost advantages with legacy transit infrastructure. |
| 5G-V2X Module Development | Predictive crowding alerts distributed to rider smartphones create new monetization pathways. |
| Indian System Integrator Alliance | First-mover positioning in Delhi, Mumbai, and Bangalore metro expansions captures white-space demand. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with transit authority procurement directors, APC system engineering leads, and fleet management software vendors; and secondary validation through Federal Transit Administration ridership reporting databases, EU GDPR implementation guidance documents, and tender documentation from BVG, MVG, and Singapore LTA. Bottom-up sizing of component-level shipments triangulated against top-down transit agency capital expenditure patterns.
Forecast inputs span sensor hardware refresh cycles, software update deployment velocities, and regulatory mandate timelines across the projection horizon. Segmentation dimensions modeled include product type, application tier, technology maturity, and end-user procurement sophistication. CAGRs were derived from fitted growth curves incorporating edge processor availability constraints and accuracy certification adoption rates as industry-specific inputs.
Sensitivities concentrate around foundry capacity allocation decisions, GDPR enforcement variance across EU member states, and 5G-V2X infrastructure rollout pacing. Forecasts reflect documented assumptions regarding semiconductor supply normalization and transit agency funding continuity. Cross-checking against Federal Transit Administration National Transit Database ridership reporting trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Global Smart Commute Market
Smart Transportation Solutions
Global Smart Highway Market
Smart Transportation Solutions
Micromobility Platform Market
Smart Transportation Solutions
Traffic Monitoring Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
Advanced Traffic Management System (ATMS) Market
Smart Transportation Solutions
Mexico Ride Hailing Market
Smart Transportation Solutions
Europe Smart Transportation Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Off-Street Parking Management System Market
Smart Transportation Solutions
Electric Kick Scooters Market
Smart Transportation Solutions
France Ridesharing Market
Smart Transportation Solutions
Smart Car Tracking Systems Market
Smart Transportation Solutions
Car Sharing Market