
 Global Smart Parking Solutions Market | 2026-2036
Global Smart Parking Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Parking Solutions Market Outlook
The smart parking industry is recalibrating around a widening gap between premium integrated platforms and commodity hardware-only installations. SKIDATA AG leverages its ski-resort heritage into controlled-access urban systems with high-margin recurring software layers. Siemens AG anchors European municipal contracts through deep automation expertise and captive service networks. Shenzhen Jieshun Science and Technology Industry Co Ltd dominates China's domestic deployment scale with cost-optimized barrier and payment terminal manufacturing.
Smart parking solutions encompass sensor networks, dynamic guidance systems, and automated payment platforms that reduce vehicle search time and curb emissions in dense urban environments. Core functionality relies on ultrasonic or camera-based occupancy detection with sub-ten-second latency, relayed to cloud dashboards for real-time space allocation. IoT Solutions and Cloud-based Systems lead current revenue pools as municipalities prioritize interoperable platforms over siloed hardware. Mobile Apps represent the fastest-expanding touchpoint layer, though margin concentration remains in Integrated Solutions bundles that combine hardware installation with decade-long software maintenance contracts.
The EU Green Deal and F-Gas Regulation shape European procurement by mandating low-emission urban logistics infrastructure, while China's MIIT issues GB standards for connected parking data interoperability. The US DOT and municipal authorities in Los Angeles, Singapore's LTA, and Germany's KBA collectively enforce diverging data localization and cybersecurity requirements that fragment vendor certification paths. Stakeholders must monitor which regulatory jurisdiction's compliance burden becomes the de facto global design floor.
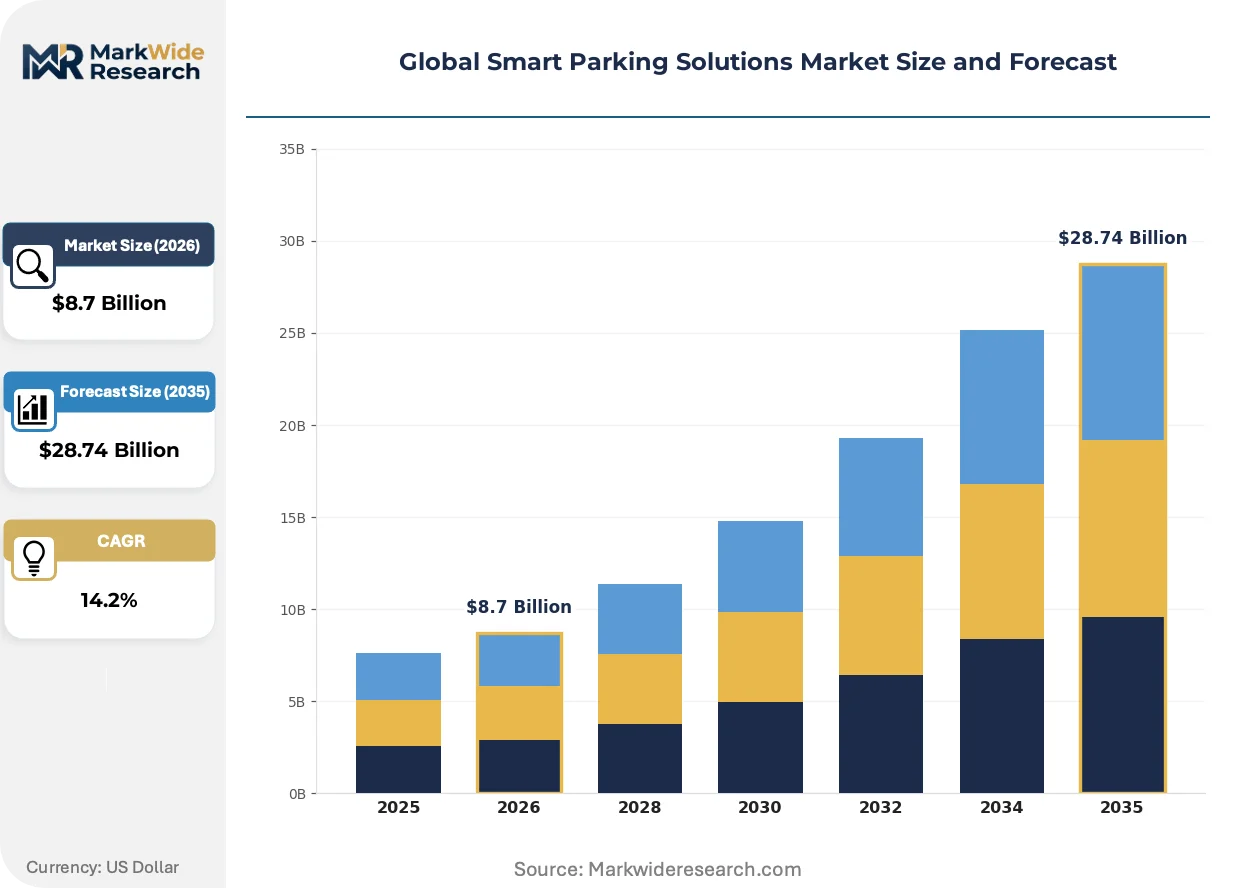
Market Dynamics
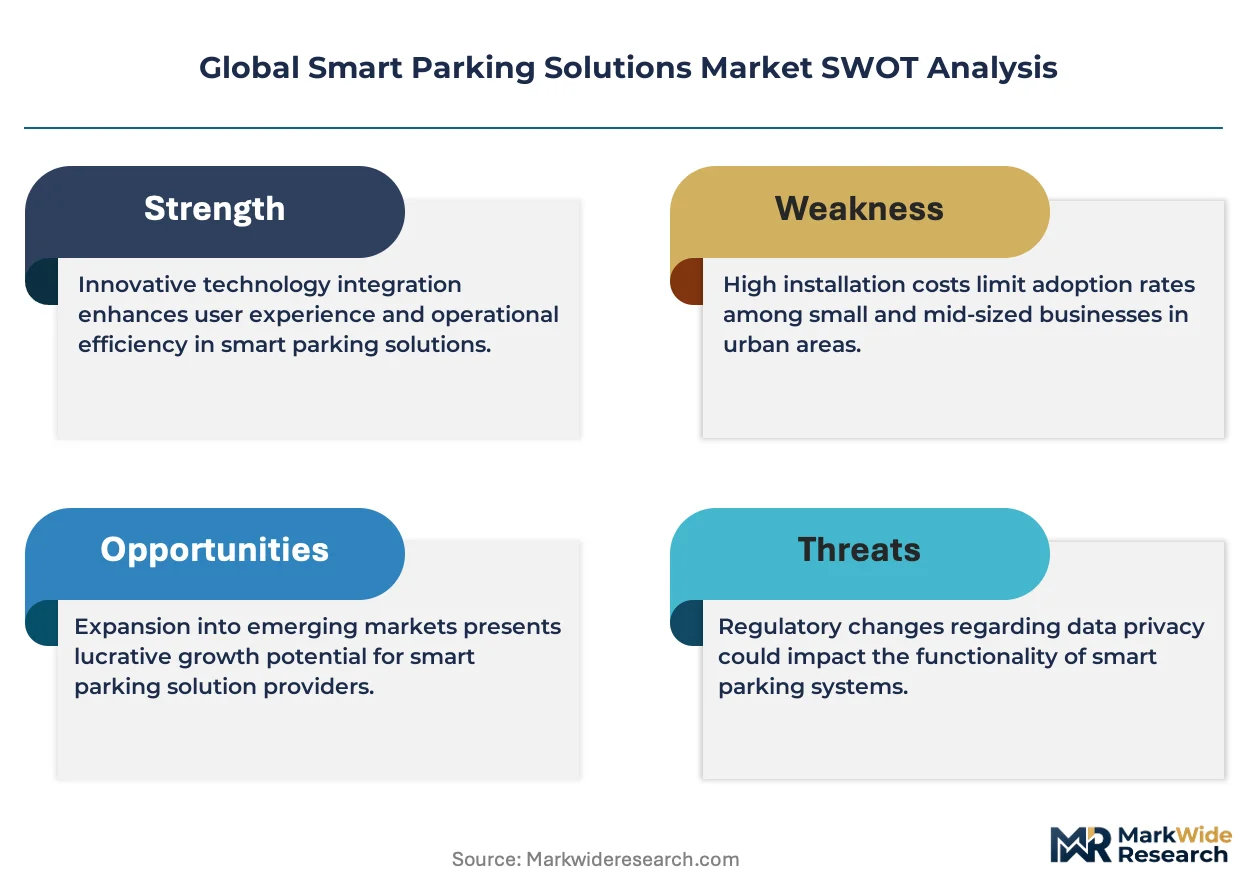
The smart parking market is bifurcating sharply between integrated platform providers and hardware-only vendors, as municipal buyers under EU Green Deal mandates demand interoperable systems with decade-long software maintenance commitments rather than standalone sensor installations.
Growth Catalysts
- EU Green Deal urban mobility mandates:German commercial parking operators are expanding sensor-based deployments to comply with low-emission logistics infrastructure requirements, creating recurring revenue pools for integrated solution vendors.
- NEV parking incentives in China:Municipal congestion pricing and new energy vehicle preferential parking policies in tier-one cities are accelerating smart infrastructure procurement at scale.
- Camera-based occupancy detection:Sub-ten-second latency systems are displacing ultrasonic alternatives as the default specification in dense urban environments where real-time space allocation determines system value.
Market Restraints
- Silicon and lithium battery input volatility:Sensor network hardware margins compress when commodity component costs spike, forcing vendors to absorb price swings or risk municipal contract losses.
- Cloud infrastructure supplier concentration:Dominance of hyperscale providers in Western Europe and North America creates single-point-of-failure risk for parking platform operators dependent on real-time data relay.
- Data localization fragmentation:Diverging cybersecurity and data storage requirements across US DOT, Singapore LTA, and Germany KBA jurisdictions multiply vendor certification burdens and extend sales cycles.
Strategic Opportunities
- India's smart city mission:Underpenetrated tier-two and tier-three urban centers present white space for cost-optimized barrier and payment terminal deployments as municipal budgets expand.
- AI-powered predictive parking analytics:Convergence of machine learning with legacy sensor networks enables dynamic pricing optimization that hardware-only vendors cannot replicate.
- Mobile app unbundling:New channel strategies separating payment interfaces from hardware installation create entry points for fintech and mobility-as-a-service platforms.
Industry Challenges
- Embedded systems engineering talent scarcity:Firmware development for ultra-low-power IoT sensors requires specialized skill sets concentrated in Shenzhen and Munich, limiting vendor scaling.
- Legacy parking meter integration complexity:Municipal procurement often mandates backward compatibility with decades-old mechanical infrastructure, inflating deployment costs and technical risk.
- GB standards compliance timelines:China's MIIT interoperability certification processes extend product launch schedules by six to twelve months for foreign platform providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Parking Solutions Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Solutions, Mobile Apps, Cloud-based Systems, RFID End User: Municipalities, Commercial Parking Operators, Residential Complexes, Transportation Hubs Offering: Hardware, Software, Integrated Solutions, Consulting Services Deployment: On-premise, Cloud-based, Hybrid, Managed Services |
| Companies Covered | SKIDATA AG, Amano Corporation, Siemens AG, Nedap N.V., Smart Parking Ltd, Robert Bosch GmbH, Cisco Systems, Inc., ParkMobile LLC, Shenzhen Jieshun Science and Technology Industry Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Parking Solutions Market Strategic Shifts
Edge computing architectures are absorbing real-time processing workloads that previously required continuous cloud connectivity, reshaping hardware design priorities and supplier value capture across the smart parking stack.
Computer vision systems with onboard inference chips are absorbing license-plate recognition and occupancy verification tasks at the camera node itself. Airport and hospital operators in the United States are deploying these units at scale to eliminate latency from centralized processing. This shift is absorbing margin from cloud-service providers while concentrating value in edge-hardware vendors with proprietary AI accelerators.
The EU F-Gas Regulation is phasing out high-global-warming-potential refrigerants in parking facility climate control systems, indirectly mandating sensor-network upgrades that monitor and optimize HVAC energy draw. Parking structure operators in France and the Netherlands are retrofitting guidance systems to meet combined emissions targets. Underground and multi-story garage segments face the steepest compliance costs and are accelerating procurement of integrated environmental monitoring platforms.
Subscription-based software licensing is displacing perpetual ownership models among municipal and commercial fleet buyers. German and Japanese parking operators are negotiating usage-based contracts that bundle maintenance, updates, and cybersecurity monitoring. This pattern is most visible in airport and railway station deployments where uptime guarantees outweigh capital expenditure preferences.
Global Smart Parking Solutions Market Segmentation
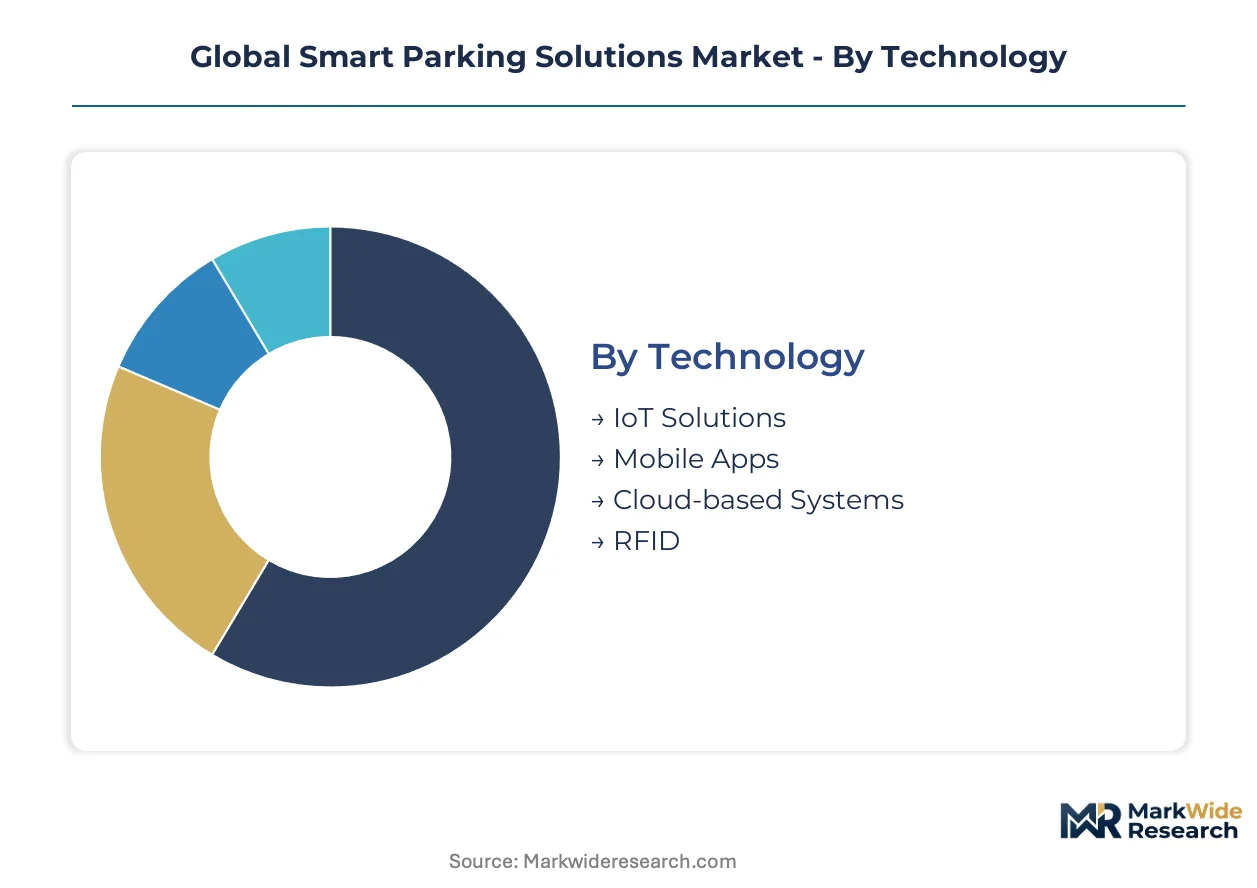
Smart parking procurement patterns diverge sharply between municipal buyers seeking decade-long interoperability and commercial operators prioritizing rapid deployment flexibility. Understanding these buyer-type distinctions across technology, end user, offering, and deployment dimensions clarifies where vendors capture margin versus volume.
Technology:
Cost tier separates buyers in this category, with premium integrated platforms commanding recurring software revenue against commodity hardware-only alternatives.
- IoT Solutions:Sensor networks combining ultrasonic or camera-based occupancy detection with sub-ten-second latency relay. Demand concentrates in Germany under EU Green Deal mandates where commercial parking operators expand sensor-based deployments for low-emission logistics compliance.
- Cloud-based Systems:Centralized dashboards for real-time space allocation and predictive analytics. China's tier-one cities drive procurement volume through municipal congestion pricing and NEV parking incentive programs that require interoperable data platforms.
- Mobile Apps:Payment interfaces and navigation layers expanding fastest as touchpoints.
- RFID:Legacy access control systems with declining share in new deployments.
Volume sits with IoT Solutions; growth tilts toward Cloud-based Systems.
End User:
Application context determines procurement complexity, from standardized municipal RFPs to customized commercial operator specifications.
- Commercial Parking Operators:Profit-driven buyers prioritizing dynamic pricing optimization and revenue maximization. German operators under KBA jurisdiction lead European deployment scale, integrating HVAC energy monitoring to meet EU F-Gas Regulation emissions targets in multi-story facilities.
- Municipalities:Public-sector procurement emphasizing interoperability standards and backward compatibility. China's MIIT GB standards certification requirements extend foreign vendor sales cycles by six to twelve months, favoring domestic platform providers.
- Transportation Hubs:Airports and railway stations demanding uptime guarantees over capital expenditure minimization.
- Residential Complexes:Cost-sensitive deployments with simpler integration requirements and shorter procurement timelines.
Commercial Parking Operators anchor current revenue; Transportation Hubs are climbing the fastest as subscription-based licensing displaces perpetual ownership.
Offering:
Margin concentration follows bundling depth, with pure hardware vendors facing compression against integrated solution providers capturing software maintenance streams.
- Integrated Solutions:Combined hardware installation with decade-long software maintenance contracts. German and Japanese parking operators negotiate usage-based agreements bundling updates and cybersecurity monitoring, particularly in airport deployments where uptime guarantees dominate.
- Software:Subscription licensing for parking management platforms and predictive analytics. AI-powered dynamic pricing modules create differentiation that hardware-only vendors cannot replicate, absorbing margin from commodity sensor suppliers.
- Hardware:Barrier systems, payment terminals, and sensor networks with compressed margins during silicon and lithium battery input volatility.
- Consulting Services:System design and legacy integration support for complex retrofit projects.
Hardware dominates unit shipments; Integrated Solutions capture expanding value share.
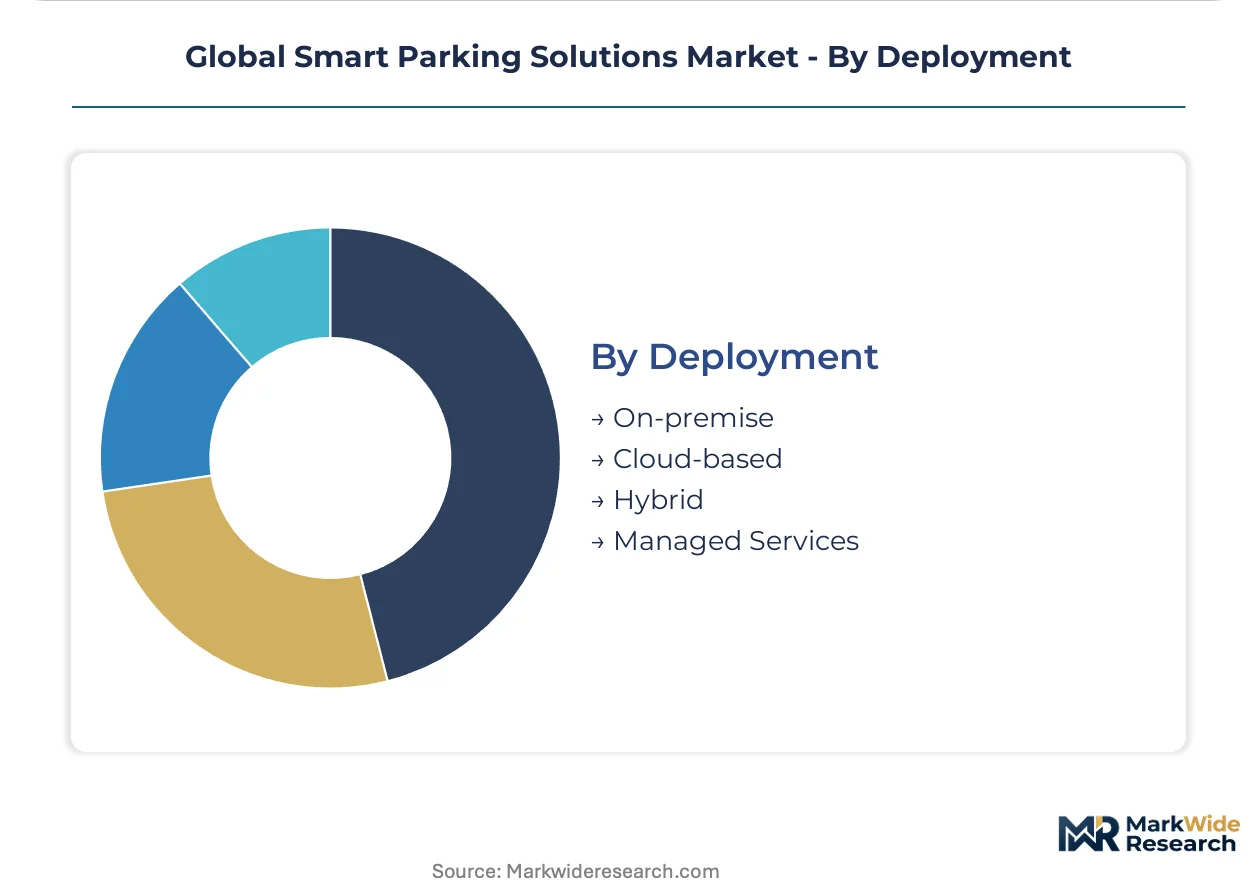
Deployment:
Customer technical maturity and data sovereignty requirements shape architecture preferences across on-premise, cloud, and hybrid alternatives.
- Cloud-based:Fully managed infrastructure eliminating capital expenditure for municipal buyers. Singapore's LTA and US DOT diverging data localization requirements fragment vendor certification paths, extending sales cycles for cross-border platform operators.
- Hybrid:Edge computing architectures absorbing real-time processing workloads at camera nodes. US airport and hospital operators deploy computer vision systems with onboard inference chips to eliminate latency from centralized processing.
- On-premise:Air-gapped systems for buyers with strict cybersecurity mandates or legacy infrastructure constraints.
- Managed Services:Outsourced operations and maintenance with uptime guarantees for transportation hub operators.
Cloud-based deployments lead current procurement; Hybrid architectures are gaining share fastest as edge computing reshapes hardware design priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors global smart parking hardware manufacturing, with its electronics corridor supplying sensor networks and payment terminals to municipal buyers across Asia, Europe, and North America.
United States
Airport and hospital operators in Los Angeles and Chicago deploy edge-computing camera systems with sub-ten-second latency for real-time space allocation. The US DOT enforces diverging data localization requirements that extend vendor certification timelines. Dallas-Fort Worth and Atlanta metropolitan clusters concentrate procurement of hybrid cloud-edge architectures for transportation hub deployments.
Germany
Commercial parking operators in Munich and Hamburg expand sensor-based deployments under EU Green Deal urban mobility mandates for low-emission logistics infrastructure. The KBA enforces cybersecurity and data storage requirements that favor integrated platform vendors with decade-long maintenance capabilities. The Ruhr industrial corridor and Frankfurt Rhine-Main region concentrate retrofit demand for multi-story garage environmental monitoring systems.
China
Municipal congestion pricing and NEV parking incentives in Beijing, Shanghai, and Shenzhen accelerate smart infrastructure procurement at scale. MIIT issues GB standards for connected parking data interoperability that extend foreign vendor sales cycles. The Pearl River Delta manufacturing cluster, centered on Shenzhen and Guangzhou, dominates domestic barrier and payment terminal production for cost-optimized deployments.
Japan
Railway station operators in Tokyo and Osaka negotiate subscription-based software licensing with uptime guarantees over capital expenditure minimization. METI standards shape procurement preferences for predictive analytics platforms. The Kansai and Chubu industrial regions concentrate demand for integrated solutions bundling maintenance, updates, and cybersecurity monitoring.
Singapore
The Land Transport Authority mandates interoperable data platforms for urban congestion management, driving procurement of cloud-based centralized dashboards. Strict data localization requirements fragment cross-border vendor certification paths. The city-state's limited land area concentrates high-density deployment of automated guidance systems in commercial and residential mixed-use developments.
Global Smart Parking Solutions Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the smart parking stack, as integrated platform vendors absorb margin from commodity hardware-only suppliers. The market structure bifurcates between premium bundled-solution providers capturing recurring software revenue and volume-driven sensor manufacturers facing silicon input volatility. Three archetypes dominate: European automation specialists with captive service networks, Chinese cost-optimized hardware fabricators, and North American cloud-native platform operators. Competitive moves concentrate on strategic partnerships for edge-AI chip integration and geographic expansion into India's underpenetrated tier-two cities.
Among European automation specialists, Siemens AG and SKIDATA AG exemplify the integrated-solution archetype combining hardware installation with long-term software maintenance contracts. Shenzhen Jieshun Science and Technology Industry Co Ltd occupies a position within the cost-optimized hardware tier, representing Chinese manufacturing scale in barrier systems and payment terminals. These three anchors illustrate the geographic and capability segmentation shaping vendor positioning across municipal, commercial, and transportation hub procurement channels.
| Leading Market Players |
|---|
| SKIDATA AG |
| Amano Corporation |
| Siemens AG |
| Nedap N.V. |
| Smart Parking Ltd |
| Robert Bosch GmbH |
| Cisco Systems, Inc. |
| ParkMobile LLC |
| Shenzhen Jieshun Science and Technology Industry Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Silicon wafer spot indices and lithium carbonate contract benchmarks cascade through smart parking hardware manufacturing into three distinct pricing tiers that separate premium integrated platform vendors from commodity sensor suppliers. German commercial parking operators under KBA jurisdiction absorb elevated costs for decade-long software maintenance bundles, while India's tier-two municipal buyers drive volume at stripped-down hardware price points.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for transportation hub operators, with airport and railway deployments commanding premium subscription tiers against standard municipal SaaS offerings. Price differentiation rests on cybersecurity certification grade and edge-AI inference capability, not sensor hardware alone. Cost compression in the hardware-only tier intensifies because silicon and lithium battery input volatility squeezes barrier system margins. Municipal buyers in China's tier-one cities exhibit lowest price sensitivity due to NEV incentive program funding, while Indian tier-three cities represent the most cost-constrained procurement segment.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Munich, and Dallas-Fort Worth orchestrate hub-and-spoke fulfillment patterns for sensor networks and payment terminals. Manufacturing concentrates in China for cost-optimized barrier hardware, Germany for precision automation components, and Taiwan for edge-AI inference chips. Component dependencies include CMOS image sensors, ARM-based microcontrollers, and lithium-ion power cells. Single-source vulnerability in hyperscale cloud infrastructure creates systemic risk for platform operators dependent on real-time data relay. Distribution runs through authorized system integrators for municipal contracts and direct OEM channels for commercial operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart parking vendor consolidation accelerates as EU Green Deal compliance costs and decade-long software maintenance obligations force sub-scale hardware-only players toward exit. Interoperability mandates and certification burdens favor integrated platform providers with captive service networks.
For Market Incumbents: To counter margin erosion from commodity sensor competition, Siemens AG and SKIDATA AG should deepen backward integration into edge-AI chip supply through strategic partnerships with Taiwan semiconductor fabricators. German automation specialists must expand captive maintenance capacity in India's underpenetrated tier-two cities before domestic cost-optimized vendors establish local service density.
For New Entrants and Emerging Players: AI-powered predictive parking analytics offers entry leverage against legacy hardware vendors unable to replicate dynamic pricing optimization modules. White space concentrates in India's smart city mission tier-two deployments and Japanese railway station subscription licensing negotiations. Fintech and mobility-as-a-service platforms should unbundle payment interfaces from hardware installation to bypass incumbent integrated solution bundles.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap integrated solution providers with established KBA cybersecurity certification and decade-long municipal maintenance contracts in Germany. Long-term viability hinges on software recurring revenue exceeding hardware shipment volatility. Watch for MIIT GB standards compliance acceleration as inflection signal favoring domestic Chinese platform providers over foreign vendors facing six-to-twelve-month certification delays.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Chip Integration Partnership | Onboard inference at camera nodes eliminates hyperscale cloud dependency for US airport operators. |
| Backward Integration into Sensor Manufacturing | Captive CMOS supply insulates German vendors from silicon wafer spot price volatility. |
| Subscription Licensing Platform Launch | Usage-based contracts with Japanese railway operators displace perpetual ownership models. |
| India Tier-Two Geographic Expansion | Cost-optimized barrier deployments capture smart city mission procurement before domestic competition consolidates. |
| EU F-Gas Regulation Compliance Certification | HVAC energy monitoring integration unlocks multi-story garage retrofit demand in France and Netherlands. |
Study Parameters
Document review covered EU Green Deal implementation guidance, MIIT GB standards documentation, and municipal RFP archives from Los Angeles, Singapore LTA, and Germany's KBA, complemented by interviews with parking platform CTOs, commercial operator procurement directors, and airport facility managers. Secondary validation drew from SEC filings of listed automation vendors, customs trade data for sensor network imports, and hyperscaler capex disclosures. Bottom-up unit deployment estimates across technology tiers triangulated against top-down municipal budget allocation projections.
Historical deployment trajectories in Germany, China, and the United States cross-referenced against expert panel inputs on regulatory timeline acceleration. Segmentation modeling spanned technology tier, end-user procurement complexity, deployment architecture, and regional regulatory cluster. CAGRs derived from slope analysis of annual procurement volumes adjusted for policy incentive phase-in schedules. Edge computing adoption curves and NEV parking incentive program budgets served as primary forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical trade restriction escalation, hyperscale cloud provider market exit, and abrupt EU F-Gas Regulation enforcement timeline shifts. Forecasts reflect documented assumptions on municipal budget continuity and certification process duration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Platform Screen Doors Market
Smart Transportation Solutions
Parking Management Solutions Market
Smart Transportation Solutions
Automatic Identification Systems (AIS) Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market
Smart Transportation Solutions
North America Vehicle Tolling System Market
Smart Transportation Solutions
Closed Platform Screen Doors Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Sustainable Last-Mile Delivery Network Design Services Market
Smart Transportation Solutions
Electric Kick Scooters Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Asia Pacific Hyperloop Technology Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Global IoT in Transportation Market
Smart Transportation Solutions
Global Parking Meter Apps Market
Smart Transportation Solutions
Alternate Transportation Market
Smart Transportation Solutions
Automated Robotic Parking System Market