
 Europe Bike Sharing Market | 2026-2036
Europe Bike Sharing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bike Sharing Market Foresight
A widening capital-intensity gap between heavy-asset operators and lean platform providers is bifurcating competitive dynamics across the Europe Bike Sharing Market. Voi Technology leverages integrated in-house maintenance networks to sustain operational density in Nordic cities. Donkey Republic competes through a decentralized franchise model that minimizes fixed-asset exposure. JCDecaux anchors long-term municipal concession contracts to dominate station-based deployments in French and Belgian urban centers.
Europe bike sharing constitutes short-term bicycle rental services enabling point-to-point urban mobility through docked or dockless systems, typically incorporating IoT-enabled locking mechanisms and GPS telemetry for fleet management and user authentication. The primary commercial purpose centers on reducing car dependency and last-mile transit gaps in congested metropolitan areas. Electric bikes command the fastest expansion trajectory within service type segmentation as battery costs decline and hill-climb performance demands intensify. Mobile apps anchor the technology dimension, though smart locks represent the critical hardware layer where margin pools concentrate due to replacement cycles and vandalism exposure. Tourist and commuter customer types split revenue seasonally, with commuters providing subscription stability against volatile visitor flows.
The EU Green Deal and F-Gas Regulation shape fleet electrification timelines, while GDPR constrains mobility data collection practices across platform operators. France's ANSM and Germany's KBA influence local safety certification requirements for e-bike components, creating compliance layering that favors established operators with dedicated regulatory affairs capacity. Stakeholders must monitor how the EU AI Act's risk classification framework applies to predictive rebalancing algorithms as automated fleet management deepens.
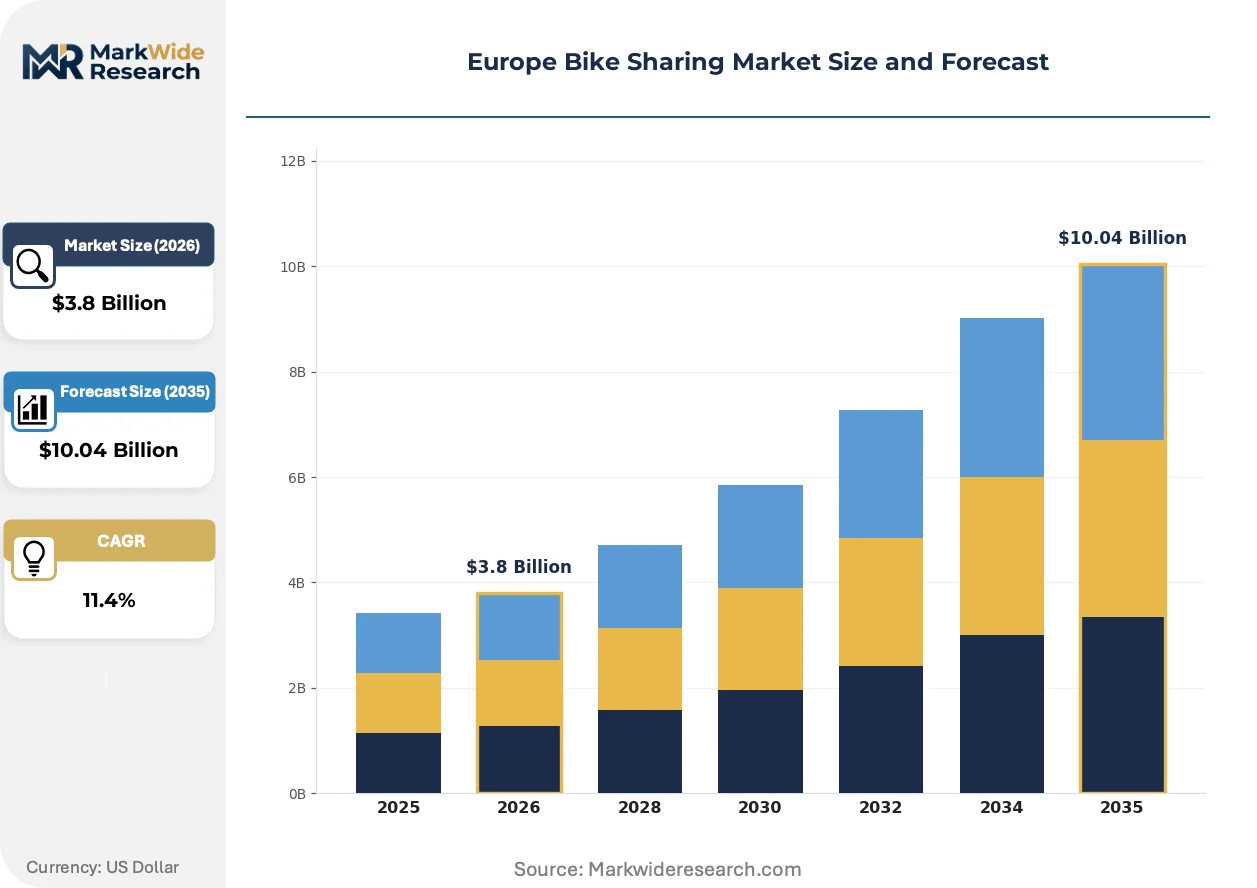
Market Dynamics
Fleet electrification mandates under the EU Green Deal are compressing operator margins while accelerating hardware refresh cycles across metropolitan deployments. Municipal procurement offices now weight carbon intensity metrics above unit economics in concession awards.
Growth Catalysts
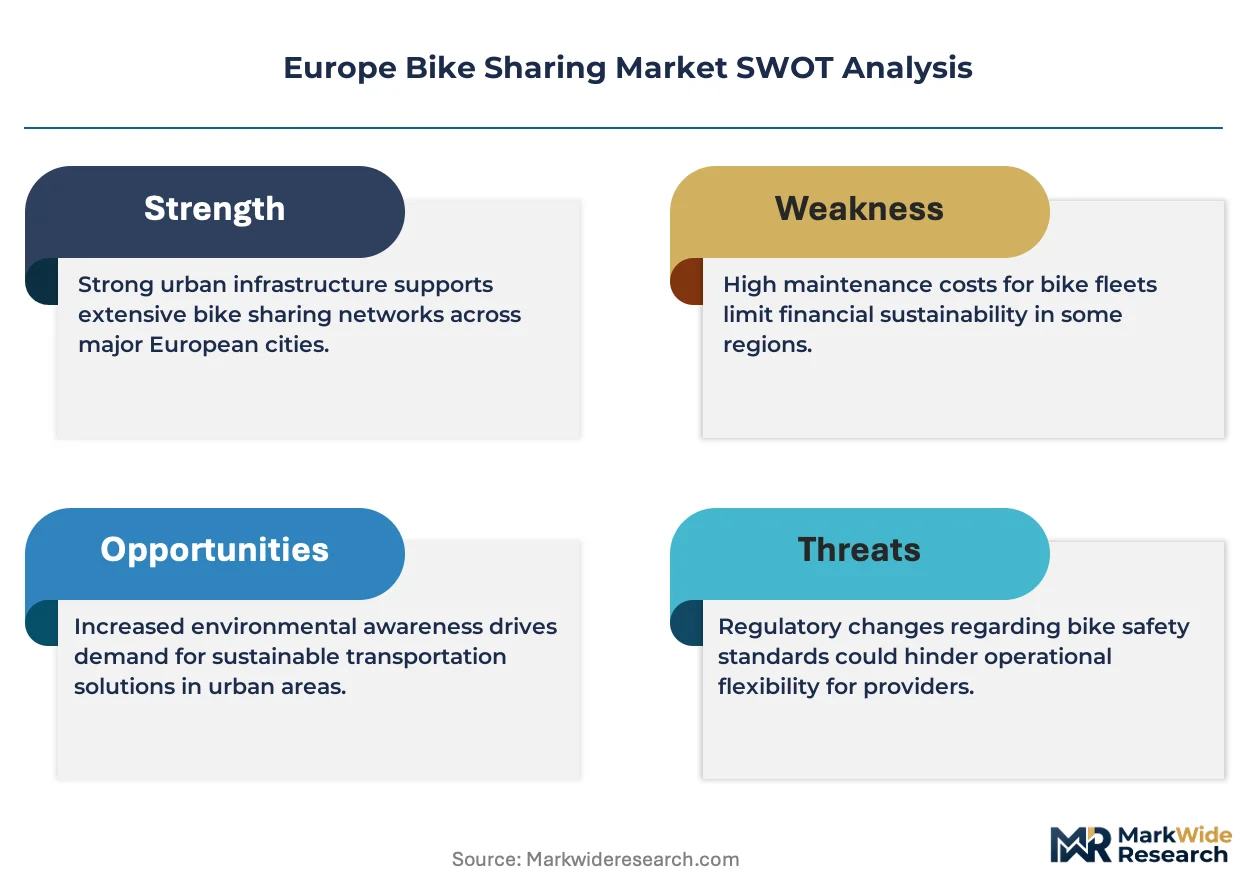
- EU Green Deal mobility targets:Binding emission reduction timelines force cities to expand zero-carbon last-mile infrastructure, directing public transit budgets toward docked and dockless bicycle networks.
- Lithium-ion battery cost curves:Declining cell prices enable e-bike fleet expansion without proportional fare increases, widening addressable trip distances for suburban commuters.
- France and Germany infrastructure intensification:Dedicated cycle lane construction in Paris, Berlin, and Amsterdam removes safety barriers that previously suppressed casual ridership adoption.
Market Restraints
- GDPR mobility data constraints:Strict geolocation tracking limitations under European privacy law impede predictive rebalancing algorithm accuracy and fleet optimization.
- Smart lock hardware concentration:Vandalism exposure and replacement cycle costs concentrate margin pressure on IoT-enabled locking mechanisms sourced from limited component suppliers.
- Station-based infrastructure capex:Municipal dock installation requires multi-year capital commitments that freeze fleet flexibility compared to dockless competitors.
Strategic Opportunities
- Netherlands intercity corridor expansion:Underpenetrated regional rail-bike integration outside Amsterdam and Rotterdam offers white space for subscription-based commuter products.
- AI Act predictive fleet management:Risk classification frameworks for automated rebalancing algorithms create first-mover advantage for operators with dedicated compliance capacity.
- Swappable battery standardization:Convergence between IoT telemetry and modular power systems enables service model unbundling between hardware ownership and energy provision.
Industry Challenges
- Maintenance technician scarcity:Electrified fleet complexity demands mechatronics skills that outpace vocational training pipeline output in Nordic and Baltic markets.
- ANSM and KBA certification layering:Divergent e-bike component safety requirements between France and Germany extend product homologation timelines and fragment procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bike Sharing Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Public Bikes, Electric Bikes, Cargo Bikes, Hybrid Bikes Customer Type: Tourists, Commuters, Students, Locals Technology: Mobile Apps, GPS Tracking, Smart Locks, Blockchain Distribution Channel: Mobile Platforms, Kiosks, Third-party Providers, Partnerships |
| Companies Covered | Voi Technology, Donkey Republic, Lime, JCDecaux, Dott, Tier Mobility, Bolt Technology, Bird Global, Nextbike Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bike Sharing Market Shifts & Advancements
Operational technology stacks are fragmenting as specialized vendors unbundle functions previously captive to integrated platform providers. This decomposition is redistributing margin pools across hardware, software, and service layers.
Swappable battery architectures are decomposing the traditional bundled service model where operators owned complete vehicle systems. Dutch and German fleet managers now pilot battery-as-a-service contracts that separate energy infrastructure from bicycle hardware, compressing upfront capital requirements while introducing new interoperability standards between competing networks.
The EU AI Act's risk classification framework is reshaping algorithmic fleet management as operators scramble to document automated decision-making in predictive rebalancing systems. Medium-risk categorization for mobility pattern prediction triggers conformity assessment obligations that favor established players with dedicated regulatory affairs functions over lean platform entrants.
Commuter subscription contracts are displacing per-ride tourist pricing as the dominant revenue architecture in Paris, Berlin, and Copenhagen. Transit authority procurement offices now mandate annual pass integration with metro and bus networks, unbundling the seasonal revenue volatility that previously characterized visitor-dependent operations.
Europe Bike Sharing Market Segmentation
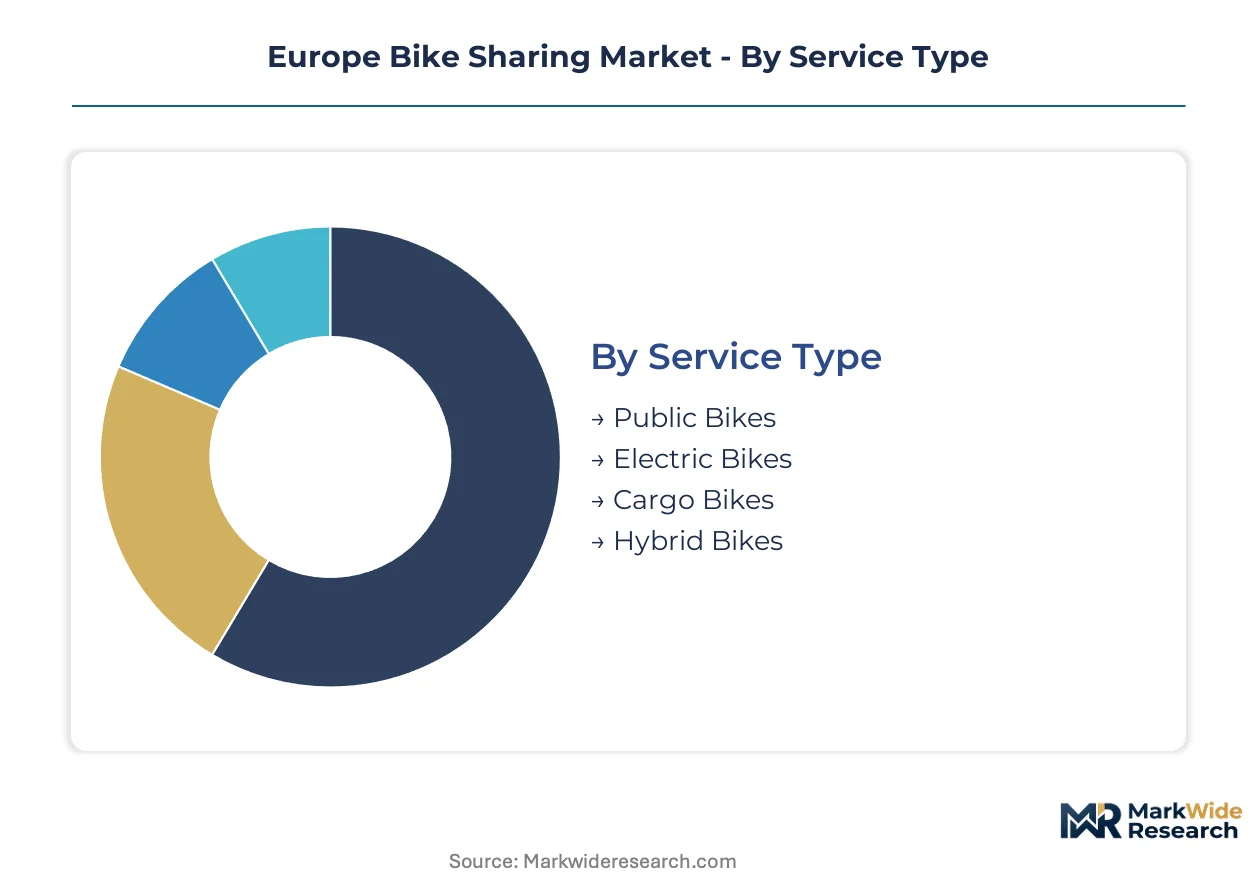
Segmentation in the Europe Bike Sharing Market reveals how operator business models align with divergent cost structures, regulatory exposure, and user behavioral patterns across metropolitan deployments. Understanding these splits illuminates where margin pools concentrate and which technology layers face the steepest substitution pressure from adjacent mobility modes.
Service Type:
Substitution pressure from e-scooters and micro-transit services hits traditional pedal fleets hardest, while electrified segments defend share through hill-climb performance and trip-distance extension.
- Electric Bikes:Lithium-ion powered two-wheelers with pedal-assist motors rated 250W under EU type-approval rules. Demand concentrates in Paris and Berlin hill districts where climb gradients previously suppressed casual ridership, with battery cost curves enabling fleet expansion without proportional fare hikes.
- Public Bikes:Conventional mechanical bicycles deployed through docked municipal concessions. Station-based infrastructure in Amsterdam and Copenhagen retains commuter loyalty through metro integration contracts, though trip volumes face erosion from dockless electrified competitors.
- Cargo Bikes:Three-wheeled or extended-frame vehicles rated for 100kg+ payloads. Last-mile delivery fleets in Dutch urban centers anchor commercial demand.
- Hybrid Bikes:Multi-terrain frames bridging road and path use cases. Weekend recreational riders in German lake districts drive seasonal utilization.
Public Bikes anchors the volume base while Electric Bikes gains share at the steepest rate.
Customer Type:
Revenue stability diverges sharply between subscription-locked commuters and weather-dependent tourist flows, with student segments offering acquisition cost advantages through university procurement partnerships.
- Commuters:Annual pass holders integrating bike-share with rail and metro networks. Paris Navigo and Berlin Deutschlandticket bundling drives 10+ trip monthly frequency.
- Tourists:Short-duration casual users generating peak summer revenue. Amsterdam canal district and Barcelona waterfront concentrate volatile visitor demand.
- Students:Campus-affiliated users accessing discounted semester passes. Dutch university cities leverage institutional procurement for fleet density.
- Locals:Resident casual riders without commuter subscription commitment. Weekend errand trips in French provincial cities sustain off-peak utilization.
Commuters provide the revenue foundation while Tourists exhibit the most pronounced seasonal amplitude.
Technology:
Margin concentration shifts toward hardware layers as software commoditizes, with smart lock replacement cycles and vandalism exposure creating persistent cost pressure.
- Smart Locks:IoT-enabled electromechanical locking mechanisms with cellular connectivity and accelerometer tamper detection. Fleet managers in Nordic cities face concentrated margin pressure from accelerated replacement cycles due to salt corrosion and physical attack exposure.
- Mobile Apps:User-facing reservation and payment interfaces with route optimization features. White-label platform providers erode differentiation as municipal procurement standardizes on functional parity.
- GPS Tracking:Telemetry systems enabling fleet visibility and theft recovery. GDPR geolocation constraints under CNIL and BfDI guidance limit predictive rebalancing accuracy.
- Blockchain:Distributed ledger pilots for usage verification and cross-operator interoperability. Dutch and German consortiums test tokenized access credentials.
Mobile Apps dominate user touchpoints while Smart Locks captures the hardware margin pool.
Distribution Channel:
Channel economics fragment as direct mobile platforms displace kiosk infrastructure, though third-party aggregators introduce commission compression and brand dilution risks.
- Mobile Platforms:Native iOS and Android applications with embedded payment processing. Direct channel control in Copenhagen and Stockholm preserves customer data ownership against GDPR constraints.
- Kiosks:Physical rental terminals at transit hubs and tourist landmarks. French and Belgian municipal concessions retain station-based infrastructure for unbanked user access.
- Third-party Providers:Mobility-as-a-Service aggregators bundling bike-share with ride-hail and transit. Whim and Citymapper integration expands reach at 15-20% commission cost.
- Partnerships:Corporate and institutional contracts with employers, universities, and hospitality chains. Berlin corporate wellness programs subsidize employee subscriptions.
Mobile Platforms commands the transaction volume while Partnerships delivers the most defensible customer acquisition economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe Bike Sharing Market trade flows remain intra-regional, with Dutch component suppliers exporting smart lock assemblies to German and French fleet operators while Nordic cities import complete e-bike systems from southern European assembly plants.
Germany
Berlin and Hamburg drive fleet electrification through Deutschlandticket bundling with bike-share subscriptions. The KBA enforces component safety certification for e-bike motors and battery enclosures, extending product homologation timelines. North Rhine-Westphalia's Ruhr corridor concentrates maintenance technician training programs at vocational institutes in Dortmund and Essen.
France
Paris Navigo integration commands the deepest transit-bike bundling in Europe, with annual pass holders generating ten-plus monthly trips. ANSM regulates e-bike battery safety standards alongside CNIL geolocation constraints under GDPR. Lyon and Bordeaux municipal concessions anchor station-based infrastructure investment in secondary urban centers.
Netherlands
Randstad rail-bike integration extends beyond Amsterdam into Rotterdam-The Hague corridor, creating intercity subscription demand. The EU Green Deal accelerates dedicated cycle lane construction through national infrastructure budgets. Eindhoven's high-tech campus clusters pilot swappable battery standardization between competing fleet networks.
Denmark
Copenhagen's metro-bike integration sets the benchmark for Nordic commuter subscription density. GDPR implementation through the Danish Data Protection Agency constrains predictive rebalancing algorithm training datasets. Aarhus and Odense replicate the capital's station-based concession model with municipal procurement favoring long-term operational contracts.
Sweden
Stockholm's archipelago geography favors dockless electrified fleets for island-hopping commuter routes. The EU AI Act risk classification framework triggers conformity assessment obligations for automated fleet management systems. Gothenburg's automotive supplier base pivots toward e-bike component manufacturing as original equipment diversification accelerates.
Europe Bike Sharing Market Competitive Landscape
Concentration sits with integrated platform operators and lean asset-light providers rather than pure hardware manufacturers. The vendor base splits between heavy-asset municipal concessionaires and scalable dockless entrants. Two strategic archetypes dominate: vertically integrated fleet managers with captive maintenance networks, and decentralized franchise platforms minimizing fixed-capital exposure. Competitive moves center on long-term municipal contract anchoring and predictive algorithm compliance positioning under emerging AI regulation.
Within the integrated platform tier, Voi Technology and JCDecaux exemplify divergent geographic anchoring strategies, while Donkey Republic occupies a position representing the decentralized franchise archetype. Voi Technology sits within the Nordic-focused fleet density model, JCDecaux anchors the station-based municipal concession approach in French and Belgian urban centers, and Donkey Republic exemplifies asset-light network expansion through local operator partnerships.
| Leading Market Players |
|---|
| Voi Technology |
| Donkey Republic |
| Lime |
| JCDecaux |
| Dott |
| Tier Mobility |
| Bolt Technology |
| Bird Global |
| Nextbike Group |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day smart lock procurement cycles concentrate margin pressure on fleet operators while amplifying pricing power for Dutch and German component suppliers who control IoT-enabled locking mechanism production. This lead-time band tightens further during municipal concession bidding windows, forcing operators to absorb inventory carrying costs or sacrifice fleet density targets.
Pricing Analysis
The customization-premium spread between standard dockless deployments and configured-to-order station-based systems widens as municipal procurement offices mandate metro integration specifications. Subscription-based commuter contracts anchor the dominant pricing structure, with price differentiation driven by battery range tiering and after-sales maintenance bundling. Cost compression in hardware procurement is intensifying because lithium-ion cell sourcing consolidates among South Korean and Chinese suppliers. Tourist segments exhibit the highest price sensitivity, while corporate partnership channels show the least due to wellness program subsidies.
Supply Chain Analysis
Taiwan Strait shipping lanes constitute a critical chokepoint for aluminum frame extrusions and precision-machined brake assemblies destined for European assembly plants. Manufacturing concentration rests on China for battery cell production, Taiwan for electronic control systems, and the Netherlands for final fleet integration and software calibration. Raw material dependencies span lithium carbonate, rare earth magnets, and high-grade aluminum alloys. Single-source vulnerability in semiconductor-based motor controllers threatens fleet electrification timelines. Distribution runs through Rotterdam port terminals into regional maintenance hubs serving Nordic and German metropolitan networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechatronics technician pipelines in Nordic vocational institutes cannot match electrified fleet complexity, creating a capability bottleneck that constrains operator expansion velocity and inflates labor cost structures.
For Market Incumbents: Fortify captive maintenance networks through apprenticeship partnerships with Dortmund and Essen technical colleges, securing technician supply against dockless entrants. Anchor long-term municipal concessions in Paris and Berlin before AI Act conformity assessment obligations favor established regulatory affairs capacity over lean platform competitors. For New Entrants and Emerging Players: Differentiate on swappable battery interoperability, targeting underpenetrated Netherlands intercity rail corridors where subscription-based commuter products remain nascent. Deploy franchise partnerships in secondary French and German urban centers to minimize fixed-asset exposure against heavy-asset incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU AI Act risk classification frameworks will consolidate algorithmic fleet management capabilities among operators with dedicated compliance functions. Target acquisition profiles emphasize predictive rebalancing software stacks and established CNIL or BfDI data governance protocols. Monitor swappable battery standardization pilots in Eindhoven as an inflection signal for service model unbundling.| Strategic Initiative | Industry Significance |
|---|---|
| Swappable Battery Standardization | Eindhoven pilots between competing Dutch networks signal interoperability convergence that fragments hardware ownership from energy provision. |
| AI Act Compliance Investment | Medium-risk algorithm classification triggers conformity assessment obligations favoring operators with dedicated regulatory affairs capacity. |
| Franchise Network Expansion | Decentralized local operator partnerships compress fixed-capital exposure compared to heavy-asset municipal concession models. |
| Transit Authority Bundling | Paris Navigo and Berlin Deutschlandticket integration locks in commuter subscription stability against seasonal tourist volatility. |
| Vocational Pipeline Partnerships | Dortmund and Essen technical college alliances secure mechatronics technician supply for electrified fleet maintenance networks. |
Research Methodology
A spread of perspectives from fleet operations directors, municipal procurement officers, IoT hardware engineers, and regulatory affairs specialists converged on the working assumptions governing fleet electrification timelines and subscription pricing elasticity. Primary fieldwork combined structured interviews with secondary validation against EU Green Deal policy documents, KBA and ANSM safety certification filings, and GDPR implementation guidance from CNIL and BfDI. Customs records tracking lithium-ion battery imports through Rotterdam terminals supplemented bottom-up operator capacity estimates, with top-down triangulation against national cycling infrastructure budget allocations.
Segmentation dimensions modeled span service type, customer archetype, technology layer, and distribution channel across the projection horizon. The analytical framework derives CAGRs from fleet deployment velocity, battery cost curve trajectories, and municipal concession award patterns. Forecast inputs incorporate lithium-ion cell price indices, dedicated cycle lane construction permits in Paris and Berlin, and GDPR geolocation constraint evolution under national data protection authority guidance.
Material uncertainties — abrupt lithium supply disruptions, AI Act enforcement variance between member states, and vandalism rate spikes in Nordic coastal cities — sit outside the modeled envelope. Forecasts reflect assumptions about battery chemistry stability and municipal procurement continuity that practitioners should keep alternative scenarios live as EU Green Deal mobility target revisions and F-Gas Regulation phase-out schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Smart Parking Systems Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
E-Bike Rental Market
Smart Transportation Solutions
Europe Electronic Toll Collection Market
Smart Transportation Solutions
Parking Space Management Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
B2C Mobility Sharing Market
Smart Transportation Solutions
Global Connected Mobility Solutions Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
Europe Hyperloop Technology Market
Smart Transportation Solutions
Automotive Digital Mapping Market
Smart Transportation Solutions
North America Passenger Information System Market
Smart Transportation Solutions
Smart Car Digital Key System Market
Smart Transportation Solutions
US Smart Highway Market