
 Global Integrated Traffic System Market | 2026-2036
Global Integrated Traffic System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Integrated Traffic System Market Foresight
The EU AI Act is rebalancing the cost-of-entry calculus for vendors selling automated incident detection and enforcement platforms into European municipal authorities. Kapsch TrafficCom leverages its end-to-end tolling heritage to anchor large-scale integrated corridor projects across Central Europe. Siemens Mobility sustains technology leadership in edge-computing traffic signal controllers, while Cubic Corporation competes aggressively on cloud-native transit coordination software in North American metropolitan markets.
An integrated traffic system fuses real-time sensor networks, centralized command platforms, and adaptive signal algorithms into unified urban mobility infrastructure, typically processing sub-100-millisecond latency requirements for collision avoidance and signal preemption. Its primary purpose is to synchronize multimodal flows—vehicular, transit, pedestrian, and emergency—across constrained right-of-way. Traffic Management systems dominate current municipal spending as cities retrofit legacy signal grids, while AI and Machine Learning represents the fastest-expanding technology layer as agencies demand predictive congestion modeling rather than reactive timing plans. Video Analytics maintains strong margin pools in highway monitoring applications where legacy camera infrastructure already exists.
The U.S. Department of Transportation, the European Commission through CE marking and the EU AI Act, and Japan's METI collectively shape product standards, data governance protocols, and cross-border procurement eligibility for integrated traffic platforms. China's MIIT and GB standards further constrain market access for foreign cloud-dependent architectures in domestic smart city tenders. Stakeholders must monitor whether algorithmic audit requirements proliferate from Brussels to other procurement jurisdictions, as compliance fragmentation would fragment vendor addressable markets.
Market Dynamics
Municipal authorities are replacing legacy signal controllers with edge-AI platforms that fuse camera, radar, and connected vehicle data streams into millisecond-responsive corridor orchestration. This hardware-to-software transition is compressing vendor margins on traditional signal hardware while expanding recurring revenue pools in cloud-based traffic analytics subscriptions.
Growth Catalysts
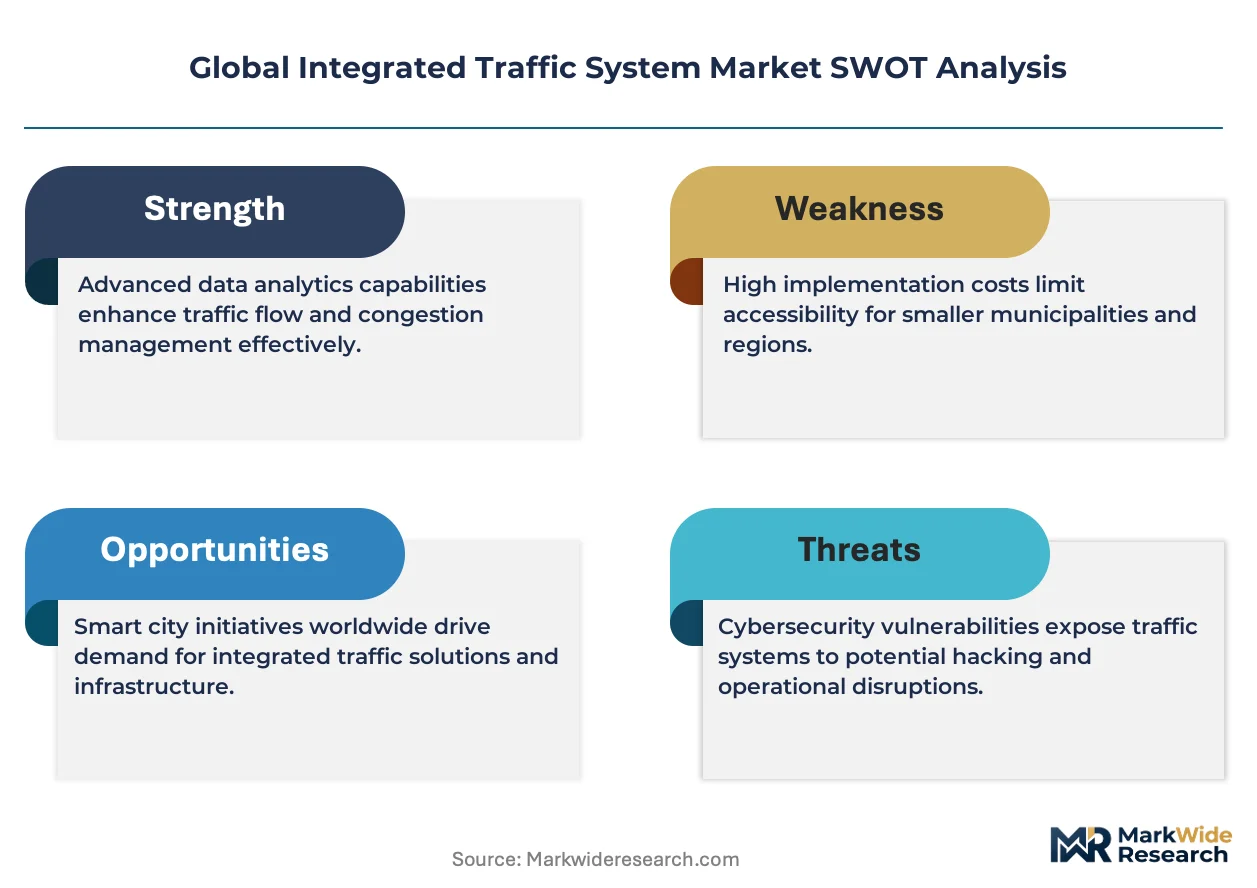
- EU AI Act algorithmic transparency mandates:European procurement authorities now require auditable decision logs for automated enforcement systems, creating upgrade cycles for legacy platforms that cannot generate explainable incident classifications.
- India Smart Cities Mission corridor unification:The Ministry of Road Transport is bundling signal control, transit priority, and emergency preemption into single-vendor integrated command contracts across 100 urban agglomerations.
- Edge computing latency thresholds:Sub-100-millisecond collision avoidance requirements are forcing municipalities to deploy localized processing nodes rather than cloud-dependent architectures for safety-critical applications.
Market Restraints
- Semiconductor supply concentration:Specialized FPGA and AI accelerator chips for traffic edge nodes source predominantly from Taiwan and South Korea foundries, exposing deployment timelines to geopolitical supply disruptions.
- Legacy copper-loop infrastructure:Underground fiber deployment costs in historic European city centers often exceed 40% of total project budgets, delaying sensor network densification.
- Cybersecurity certification fragmentation:Divergent national standards for critical infrastructure protection across Germany's BSI, France's ANSSI, and Italy's ACN create redundant compliance engineering for pan-European vendors.
Strategic Opportunities
- Vietnam and Indonesia urban corridor buildouts:Ho Chi Minh City and Jakarta are issuing bundled smart traffic tenders that combine signal control with congestion pricing infrastructure, rewarding vendors with tolling heritage.
- V2X communication module integration:DSRC and C-V2X roadside units are converging with existing video analytics platforms to enable pedestrian-bicycle-vehicle conflict prediction in dense Asian megacities.
- Japan METI autonomous mobility zones:Designated regulatory sandboxes in Tokyo and Osaka are permitting mixed-traffic pilot deployments that require real-time traffic system coordination with vehicle OEMs.
Industry Challenges
- Embedded systems firmware talent scarcity:Real-time operating system expertise for safety-certified signal controllers concentrates in Central European engineering clusters, constraining vendor expansion timelines.
- Multi-decade asset depreciation cycles:Municipal traffic signal infrastructure typically carries 15-20 year accounting lives, creating procurement committee resistance to mid-cycle technology refreshes.
- Interoperability with 1970s-era electromechanical controllers:Some US Sun Belt municipalities still operate relay-based signal systems that resist digital retrofit without complete cabinet replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Integrated Traffic System Market |
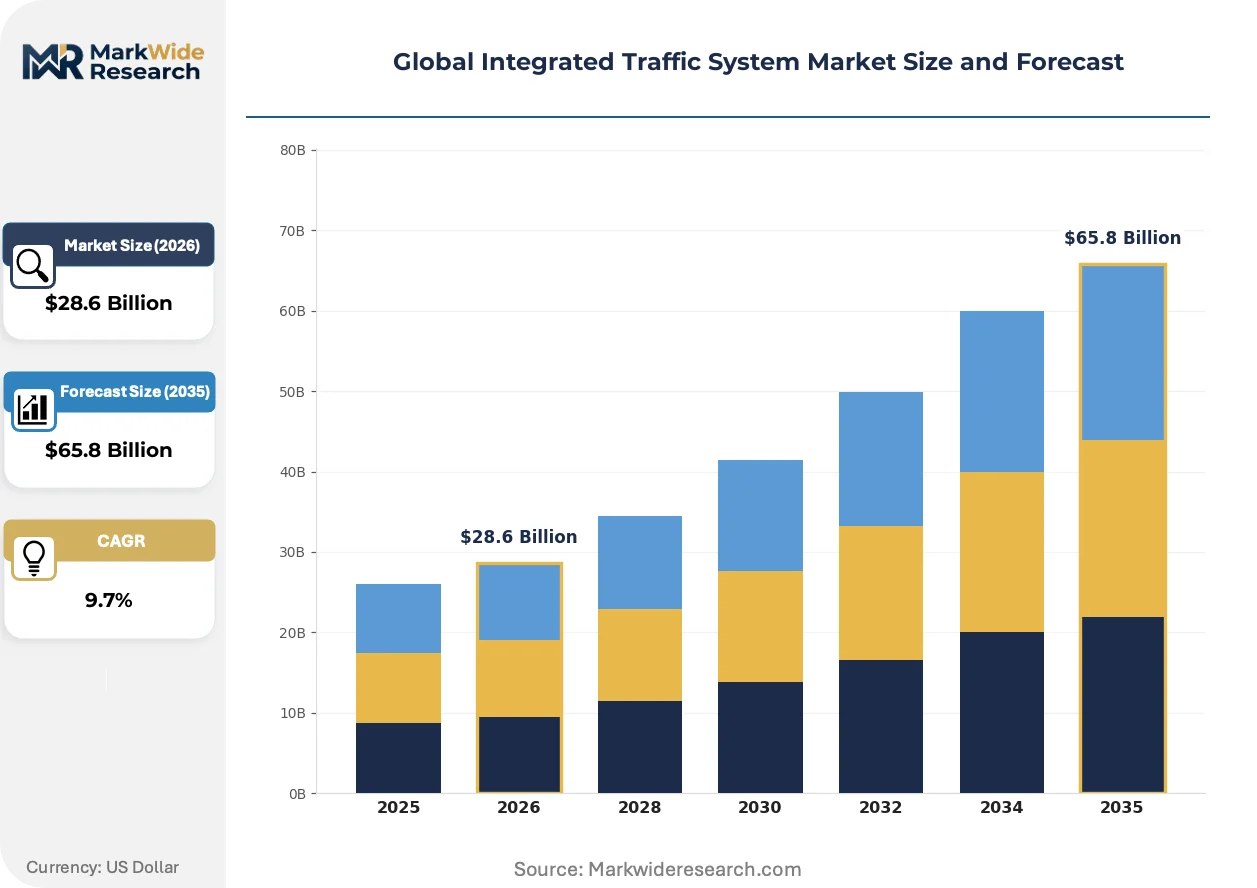
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $65.8 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Traffic Management, Incident Detection, Surveillance & Monitoring, Parking Management, Toll Collection Technology: AI & Machine Learning, Video Analytics, IoT Sensors, Wireless Communications, Cloud Computing Application: Urban Traffic Control, Highway Monitoring, Public Transit Coordination, Smart Parking, Emergency Response End User: Municipal Authorities, Transportation Operators, Infrastructure Providers, Traffic Control Centers |
| Companies Covered | Kapsch TrafficCom, Cubic Corporation, Swarco, Siemens Mobility, Sumitomo Electric Industries, Jenoptik AG, Iteris Inc., LG CNS, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Integrated Traffic System Market Shifts & Advancements
Traffic management architectures are pivoting from centralized SCADA-style command centers to distributed edge-AI meshes that process sensor fusion locally while feeding aggregate pattern data to municipal cloud platforms for strategic planning.
Computer vision inference engines are converging with thermal imaging and lidar point-cloud processing into unified perception stacks for intersection conflict detection. California DOT and Texas DOT are piloting these multimodal sensor fusions on high-fatality rural highway corridors where camera-only systems fail in fog and glare conditions. The technology is compressing vendor specialization boundaries, forcing pure-play camera analytics firms to acquire lidar processing capabilities or cede safety-critical bids to diversified sensing platforms.
The EU AI Act's risk-based classification system is reclassifying automated incident detection algorithms as high-risk AI systems subject to conformity assessment and post-market monitoring. European traffic authorities in the Netherlands and Denmark are now requiring CE-marked algorithmic audit trails before contract award, displacing vendors whose platforms generate black-box enforcement decisions. This regulatory pressure is accelerating open-architecture procurement specifications that mandate API-accessible decision logs.
Municipal buying committees are unbundling decade-long maintenance contracts from initial system deployment, opting instead for performance-based service agreements with 3-5 year renewal cycles. North American metropolitan planning organizations in Seattle, Vancouver, and Denver are leading this shift, using annual corridor-level mobility outcome metrics to determine vendor retention. The practice is most visible in transit signal priority deployments, where agencies withhold full payment until bus schedule adherence improvements meet contracted thresholds.
Global Integrated Traffic System Market Segmentation
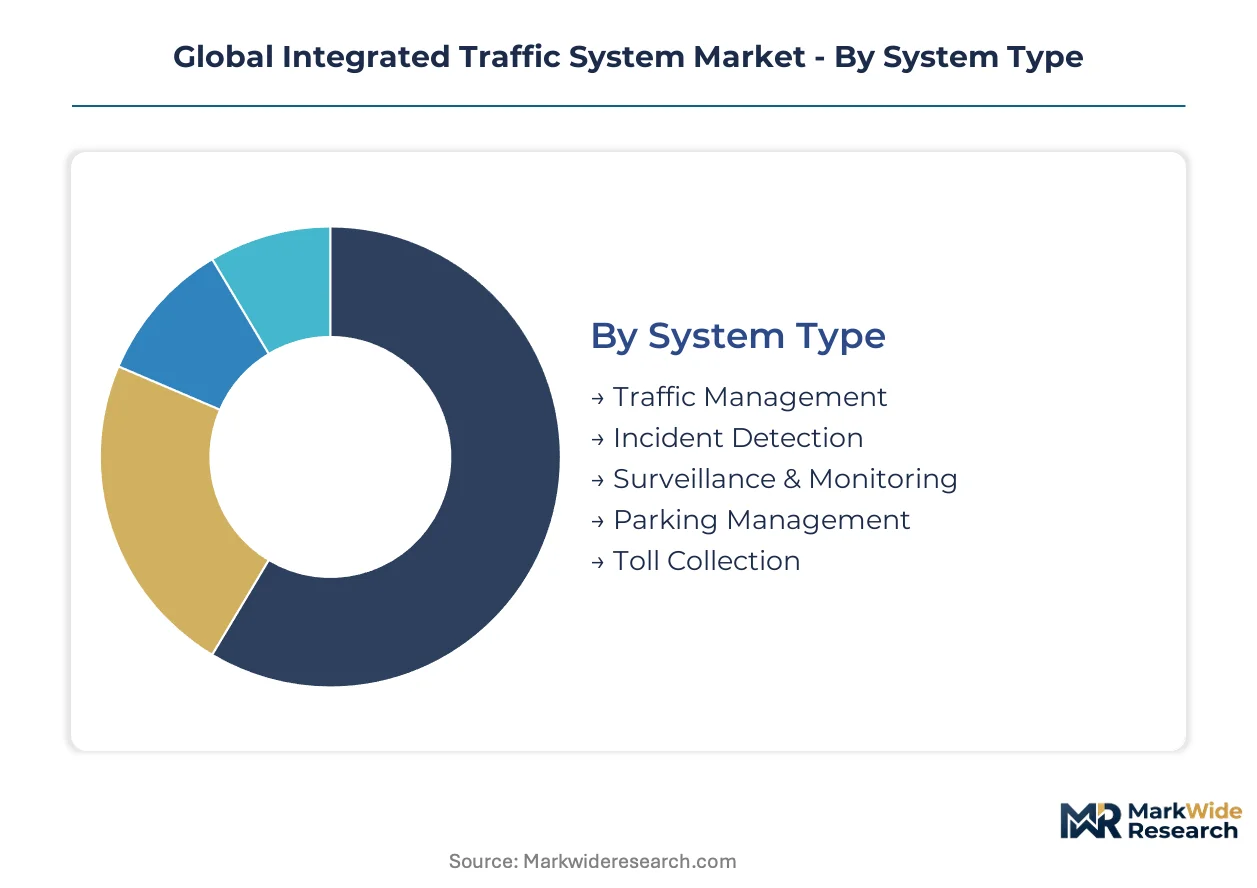
Procurement patterns in integrated traffic systems diverge sharply between retrofit-heavy municipal budgets and greenfield smart city deployments. Buyers prioritize system modularity when legacy infrastructure constraints dominate, while emerging markets favor bundled technology stacks that compress vendor selection cycles.
System Type:
Municipal procurement committees weight total cost of ownership against interoperability mandates when evaluating system categories.
- Traffic Management:Adaptive signal control platforms process real-time flow data from radar, camera, and connected vehicle feeds to adjust phase timings dynamically. Demand concentrates in India under the Smart Cities Mission corridor unification drive, where 100 urban agglomerations require unified command platforms. Volume sits with Traffic Management; growth tilts toward Incident Detection.
- Incident Detection:Automated collision and debris identification systems fuse edge-AI inference with thermal and lidar sensors for sub-100-millisecond alert generation. European authorities in the Netherlands and Denmark now mandate EU AI Act-compliant algorithmic audit trails, displacing black-box legacy platforms.
- Surveillance & Monitoring:Continuous video and sensor feeds for corridor-wide situational awareness, heavily deployed on California DOT and Texas DOT rural highway pilots where multimodal sensing replaces camera-only fog-vulnerable systems.
- Parking Management:Occupancy detection and dynamic pricing platforms integrating curb-space sensors with mobile payment gateways.
- Toll Collection:Multi-lane free-flow and congestion pricing infrastructure, bundling increasingly with smart traffic tenders in Ho Chi Minh City and Jakarta.
Retrofit economics favor Traffic Management; bundled greenfield tenders elevate Toll Collection.
Technology:
Technology selection tracks latency requirements, with safety-critical applications demanding localized processing while strategic planning leverages cloud aggregation.
- AI & Machine Learning:Predictive congestion modeling and adaptive signal optimization algorithms trained on multimodal historical flow patterns. Agencies across Southeast Asia are accelerating procurement of these platforms as municipal authorities replace reactive timing plans. AI & Machine Learning expands most quickly; Video Analytics retains the strongest margin pools.
- Video Analytics:Computer vision inference engines for vehicle classification, incident detection, and pedestrian-bicycle conflict prediction. Highway monitoring applications in North America and Europe leverage existing camera infrastructure for strong margin retention.
- IoT Sensors:Distributed radar, lidar, and environmental monitoring nodes feeding edge-computing meshes.
- Wireless Communications:DSRC and C-V2X roadside units enabling vehicle-to-infrastructure coordination in Tokyo and Osaka autonomous mobility zones.
- Cloud Computing:Centralized data aggregation and strategic planning platforms, constrained in China by MIIT and GB standards that limit foreign cloud-dependent architectures.
Edge deployment dominates safety-critical bids; cloud concentration rises in planning and analytics.
Application:
Application prioritization reflects fatality reduction mandates and transit recovery objectives post-pandemic.
- Urban Traffic Control:Intersection-level signal coordination and multimodal priority management across constrained right-of-way. European historic city centers face 40% fiber deployment cost overruns that delay sensor densification. Urban Traffic Control commands current spending; Smart Parking shows steepest expansion trajectory.
- Highway Monitoring:Corridor-wide incident detection and weather-responsive speed harmonization on high-fatality rural routes.
- Public Transit Coordination:Bus and rail signal priority systems with performance-based service agreements in Seattle, Vancouver, and Denver tying vendor retention to schedule adherence metrics.
- Smart Parking:Dynamic curb management and guidance systems, gaining traction as cities unbundle decade-long maintenance contracts for 3-5 year renewal cycles.
- Emergency Response:Preemption systems for fire, ambulance, and police corridor clearance with millisecond-responsive signal overrides.
Urban retrofit absorbs majority capex; parking digitization climbs fastest.
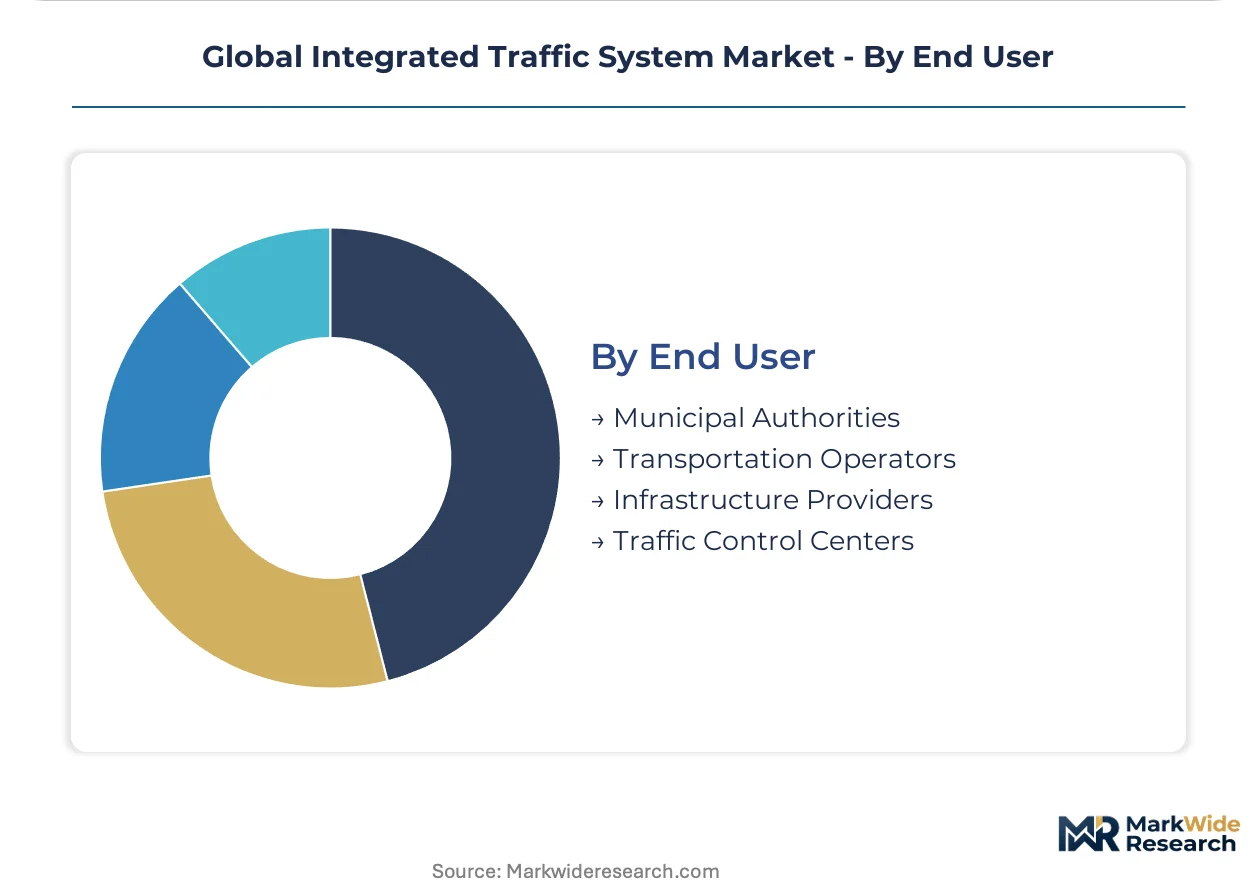
End User:
End-user segmentation reveals divergent procurement authority and technical sophistication.
- Municipal Authorities:City and regional governments managing signal grids, parking, and curb space with 15-20 year asset depreciation cycles creating resistance to mid-cycle refreshes. Municipal Authorities represent the dominant buyer class; Traffic Control Centers gain sophistication fastest.
- Transportation Operators:Transit agencies and toll road concessionaires prioritizing corridor throughput and revenue optimization.
- Infrastructure Providers:Private developers and public-private partnerships financing bundled smart city deployments.
- Traffic Control Centers:Centralized command facilities evolving from SCADA-style architectures to distributed edge-AI meshes with cloud-connected strategic layers.
Budget authority fragments across municipal committees; technical specification power centralizes in control centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates demand through corridor unification mandates under the Smart Cities Mission, while regulatory pressure from the EU AI Act and semiconductor supply risks in East Asia reshape deployment timelines across procurement jurisdictions.
United States
State DOTs in California and Texas pilot multimodal sensor fusion on high-fatality rural corridors where fog and glare disable camera-only systems. The Federal Highway Administration coordinates Connected Vehicle Pilot deployment guidelines. Metropolitan planning organizations in Seattle, Denver, and Vancouver drive performance-based procurement with 3-5 year renewal cycles tied to mobility outcomes.
Germany
Municipal authorities face 40% fiber deployment cost overruns in historic city centers that delay sensor network densification. The EU AI Act mandates auditable decision logs for automated enforcement, displacing black-box legacy platforms. Engineering clusters in Bavaria and Baden-Württemberg concentrate embedded systems firmware talent for safety-certified signal controllers.
India
The Ministry of Road Transport bundles signal control, transit priority, and emergency preemption into single-vendor integrated command contracts across 100 urban agglomerations. BIS standards and the Smart Cities Mission framework govern procurement specifications. Municipal authorities in Maharashtra and Karnataka accelerate retrofit spending on legacy signal grids.
Japan
METI designates regulatory sandboxes in Tokyo and Osaka permitting mixed-traffic pilot deployments requiring real-time coordination between traffic systems and vehicle OEMs. JIS standards shape edge-computing latency requirements for collision avoidance applications. The Kanto and Kansai regions anchor autonomous mobility zone development.
Vietnam
Ho Chi Minh City issues bundled smart traffic tenders combining signal control with congestion pricing infrastructure. Municipal authorities prioritize vendors with tolling heritage for urban corridor buildouts. The Mekong Delta economic zone drives procurement acceleration as infrastructure investment concentrates in southern metropolitan clusters.
Global Integrated Traffic System Market Competitive Landscape
European producers anchor the premium tier through tolling heritage and regulatory compliance depth; East Asian specialists hold scale advantages in semiconductor-integrated edge hardware. The vendor base organizes around three strategic archetypes: end-to-end corridor integrators, edge-computing signal specialists, and cloud-native transit coordination platforms. Competitive moves concentrate on M&A for sensor fusion capabilities and strategic partnerships with municipal authorities for performance-based service agreements.
Within the integrated corridor tier, Kapsch TrafficCom and Siemens Mobility occupy positions shaped by European regulatory alignment and hardware-to-software transition dynamics. Cubic Corporation sits within the North American cloud-native segment where transit coordination software procurement concentrates. Sumitomo Electric Industries exemplifies the East Asian specialist archetype with embedded systems integration depth for safety-critical applications.
| Leading Market Players |
|---|
| Kapsch TrafficCom |
| Cubic Corporation |
| Swarco |
| Siemens Mobility |
| Sumitomo Electric Industries |
| Jenoptik AG |
| Iteris Inc. |
| LG CNS |
| Thales Group |
| Others |
Supply & Pricing Matrix
EU AI Act algorithmic transparency mandates gate qualified supply and premium-tier pricing access for vendors selling automated enforcement platforms into European municipal authorities. Procurement committees now withhold contract awards from vendors whose platforms cannot generate auditable decision logs, compressing margins for legacy black-box systems while rewarding compliant architectures with pricing power.
Pricing Analysis
Short lead times for specialized FPGA and AI accelerator chips command substantial premiums from municipal buyers facing delayed deployment timelines. Project-based pricing dominates integrated corridor contracts, with differentiation driven by CE marking tier and after-sales service bundling. Cost compression in standard signal hardware is intensifying because edge-AI platforms displace legacy controller margins. Municipal authorities in India exhibit highest price sensitivity, while German traffic control centers prioritize certification depth over unit cost.
Supply Chain Analysis
CE marking and EU AI Act conformity assessment requirements gate vendor participation in European tenders, filtering supply to firms with regulatory engineering depth. Semiconductor manufacturing concentrates in Taiwan and South Korea, with edge-AI inference engines sourcing from Japanese foundries. Specialized radar modules and thermal imaging sensors feed from German and Israeli component specialists. Single-source vulnerability in Taiwan-based FPGA fabrication exposes deployment timelines to geopolitical disruption. Distribution runs through systems integrators with municipal procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with end-to-end corridor integration capabilities, as EU AI Act compliance costs force sub-scale players toward exit or acquisition.
For Market Incumbents: Deepen embedded systems firmware capabilities in Central European engineering clusters to defend against talent scarcity constraining safety-certified controller development. Acquire lidar processing specialists to capture multimodal sensor fusion bids displacing pure-play camera analytics firms. Vertical integration into semiconductor sourcing mitigates Taiwan foundry concentration risk. For New Entrants and Emerging Players: Mid-sized Vietnamese and Indonesian municipal authorities represent the most penetrable buyer archetype, as Ho Chi Minh City and Jakarta issue bundled smart traffic tenders rewarding tolling heritage. Target performance-based service agreements with 3-5 year renewal cycles in North American metropolitan planning organizations. Lead with cloud-native transit coordination software to bypass hardware margin compression. For Investors and Strategic Acquirers: First-municipal adoption of EU AI Act-compliant algorithmic audit trails is the leading indicator that consolidation momentum is accelerating toward end-to-end corridor integrators. Over a multi-year horizon, acquisition targets cluster around edge-computing signal specialists with JIS or BIS certification depth for Japan and India autonomous mobility zones. Watch for METI regulatory sandbox expansions beyond Tokyo and Osaka as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Sensor Fusion Specialist | California DOT and Texas DOT multimodal pilot requirements compress vendor specialization boundaries. |
| Performance-Based Service Agreement | Seattle and Denver metropolitan planning organizations tie vendor retention to bus schedule adherence thresholds. |
| EU AI Act Compliance Investment | Netherlands and Denmark procurement authorities now mandate CE-marked algorithmic audit trails pre-contract. |
| Edge-AI Platform Launch | Sub-100-millisecond collision avoidance requirements force localized processing node deployment. |
| Joint Venture with Tolling Heritage Firm | Ho Chi Minh City bundled tenders combine signal control with congestion pricing infrastructure. |
Research Methodology
SEC filings, municipal procurement databases, and connected vehicle pilot disclosure documents formed the secondary backbone, supplemented by customs records tracking FPGA and AI accelerator chip trade flows. Primary interviews with traffic control center operations directors, municipal procurement committee chairs, and embedded systems firmware engineering managers combined with secondary validation through bottom-up and top-down triangulation.
Bottom-up modeling aggregated individual corridor deployment values across system type, technology layer, and application segments, while top-down analysis cross-checked aggregate municipal infrastructure spending patterns. Modeled dimensions spanned traffic management versus incident detection systems, AI and machine learning versus video analytics technologies, and urban traffic control versus highway monitoring applications. CAGRs derived from deployment timeline phasing and technology refresh cycle assumptions, with edge-computing latency requirements and EU AI Act compliance deadlines as key forecast inputs.
Revisions become necessary when semiconductor supply disruptions, EU AI Act enforcement interpretations, or India Smart Cities Mission procurement delays materialize beyond modeled assumptions. Forecasts reflect documented expectations regarding municipal budget authority fragmentation and control center technical specification centralization. A model refresh is warranted upon material change in METI autonomous mobility zone regulatory sandbox expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Smart Parking Technologies Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Smart Car Digital Key System Market
Smart Transportation Solutions
E-Scooter Sharing Market
Smart Transportation Solutions
B2C Mobility Sharing Market
Smart Transportation Solutions
Fleet Management Software Market
Smart Transportation Solutions
Shared Vehicles Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market
Smart Transportation Solutions
Intelligent Airways Transportation Market
Smart Transportation Solutions
Global Intelligent Traffic Management System Market
Smart Transportation Solutions
Smart Chassis Market
Smart Transportation Solutions
Cellular Vehicle-To-Everything (C-V2X) Market
Smart Transportation Solutions
Parking Management Solutions Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
Closed Platform Screen Doors Market
Smart Transportation Solutions
Global Smart Highway Market