
 Global Ridesharing Market | 2026-2036
Global Ridesharing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ridesharing Market Outlook
Commercial driver's license certification and local vehicle-for-hire permitting is collapsing the pool of eligible operators in major metropolitan markets. Uber Technologies Inc. leverages its dual-sided network density to sustain pricing power across North American urban corridors. DiDi Global Inc. anchors its competitive position through in-house mapping and autonomous vehicle R&D pipelines in Chinese megacities. Lyft, Inc. differentiates by concentrating driver incentives and loyalty programs in U.S. coastal markets where supply constraints bite hardest.
Ridesharing denotes the digital matching of private vehicle operators with fare-paying passengers through algorithmic dispatch platforms, typically requiring real-time GPS telemetry, dynamic pricing engines, and integrated mobile payment rails to coordinate supply and demand across dispersed geographies. Ride-hailing commands the dominant revenue share among service type categories, while carpooling captures the fastest user growth as fuel costs and congestion charges push commuters toward shared occupancy models. Corporate users within the customer type dimension generate disproportionate trip frequency and yield per account, though individual consumers still constitute the absolute volume base.
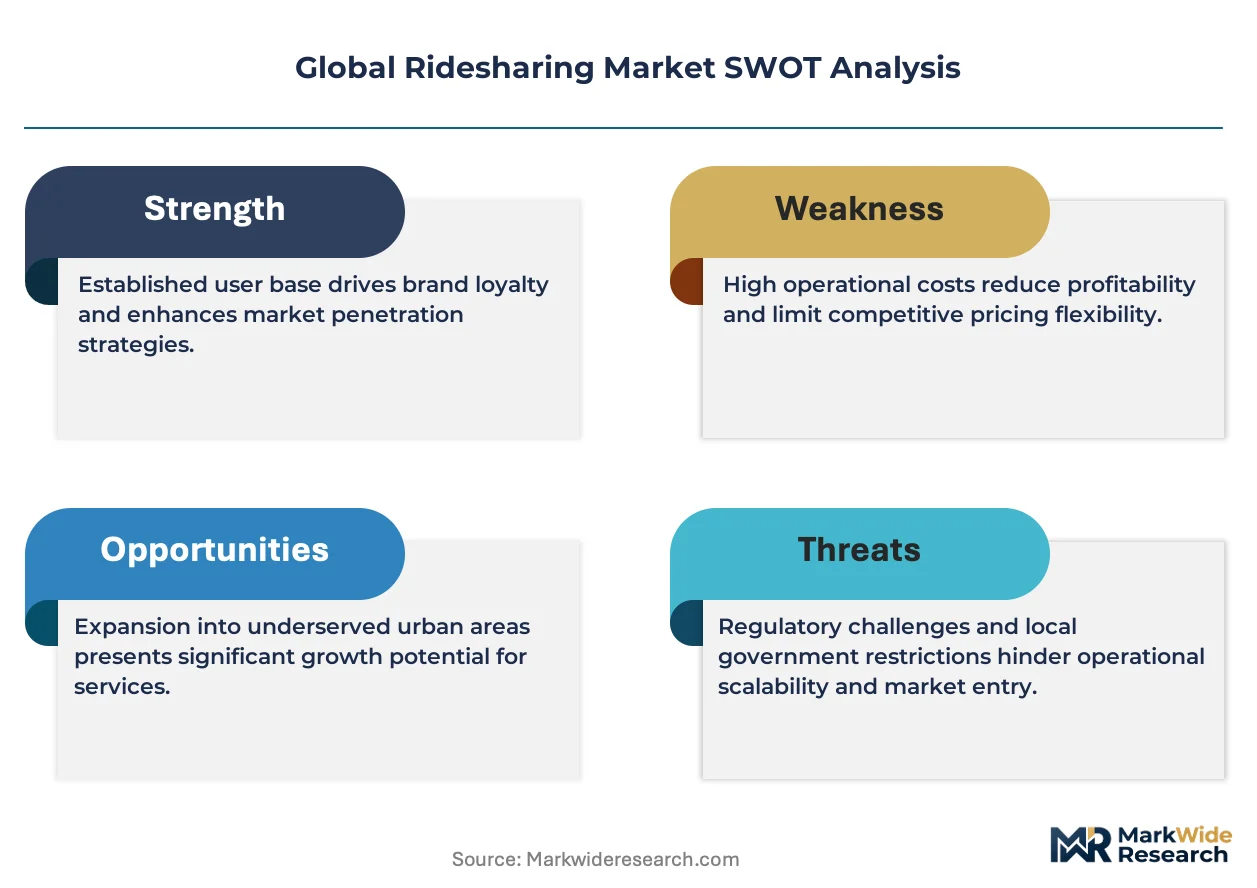
The U.S. Department of Transportation, the EU's Platform Work Directive framework, and India's Ministry of Road Transport and Highways each impose distinct compliance burdens on cross-border operators ranging from driver background verification to data localization and fare transparency mandates. India's Motor Vehicle Aggregator Guidelines and the EU's GDPR data-handling standards directly shape platform architecture and market entry sequencing for new competitors. Stakeholders must monitor evolving employment classification rulings across multiple jurisdictions to anticipate cost structure disruptions before they compress unit economics.
Market Dynamics
The European Commission's Platform Work Directive is recalibrating labor cost structures across continental operations, compelling platform operators to absorb employment benefits previously externalized onto driver-contractors. This regulatory inflection cascades through pricing models and network density economics in every jurisdiction where gig-worker reclassification gains traction.
Growth Catalysts
- Urban congestion pricing:London's Ultra Low Emission Zone and Singapore's Electronic Road Pricing system push private vehicle owners toward shared mobility alternatives, expanding addressable demand in metropolitan cores.
- Integrated payment infrastructure:Real-time mobile payment rails and embedded wallet ecosystems reduce transaction friction for unbanked populations in emerging economies, lowering barriers to platform adoption.
- Corporate mobility budgets:Enterprise travel managers consolidate ground transportation spend under centralized platform contracts, generating predictable trip volume and higher per-account yields than individual consumer segments.
Market Restraints
- Driver supply certification chokepoints:Commercial licensing requirements and vehicle-for-hire permitting create regulatory friction that collapses eligible operator pools in dense metropolitan markets.
- Fuel cost volatility:Diesel and gasoline price swings transmit directly to driver earnings and platform subsidy burdens, compressing unit economics during energy price spikes.
- Public transit substitution:Heavy rail and bus network expansions in Chinese and Indian megacities capture price-sensitive commuters who would otherwise select shared mobility.
Strategic Opportunities
- Autonomous vehicle integration:The convergence of lidar sensor miniaturization and edge-computing inference engines enables driverless fleet pilots in geofenced urban corridors.
- Two-wheeler expansion:Motorcycle and scooter-based services address last-mile connectivity gaps in Southeast Asian and Latin American urban agglomerations where four-wheel penetration remains limited.
- India's Motor Vehicle Aggregator Guidelines:National-level regulatory clarity on data localization and fare transparency creates a template for compliant market entry that reduces jurisdictional uncertainty.
Industry Challenges
- Algorithmic wage transparency mandates:The EU's Platform Work Directive requires explainable dispatch and pricing logic, forcing engineering teams to rearchitect proprietary matching systems.
- Cross-border data governance fragmentation:Divergent localization requirements between India's Ministry of Road Transport and the EU's GDPR create compliance architecture complexity for operators spanning both jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ridesharing Market |
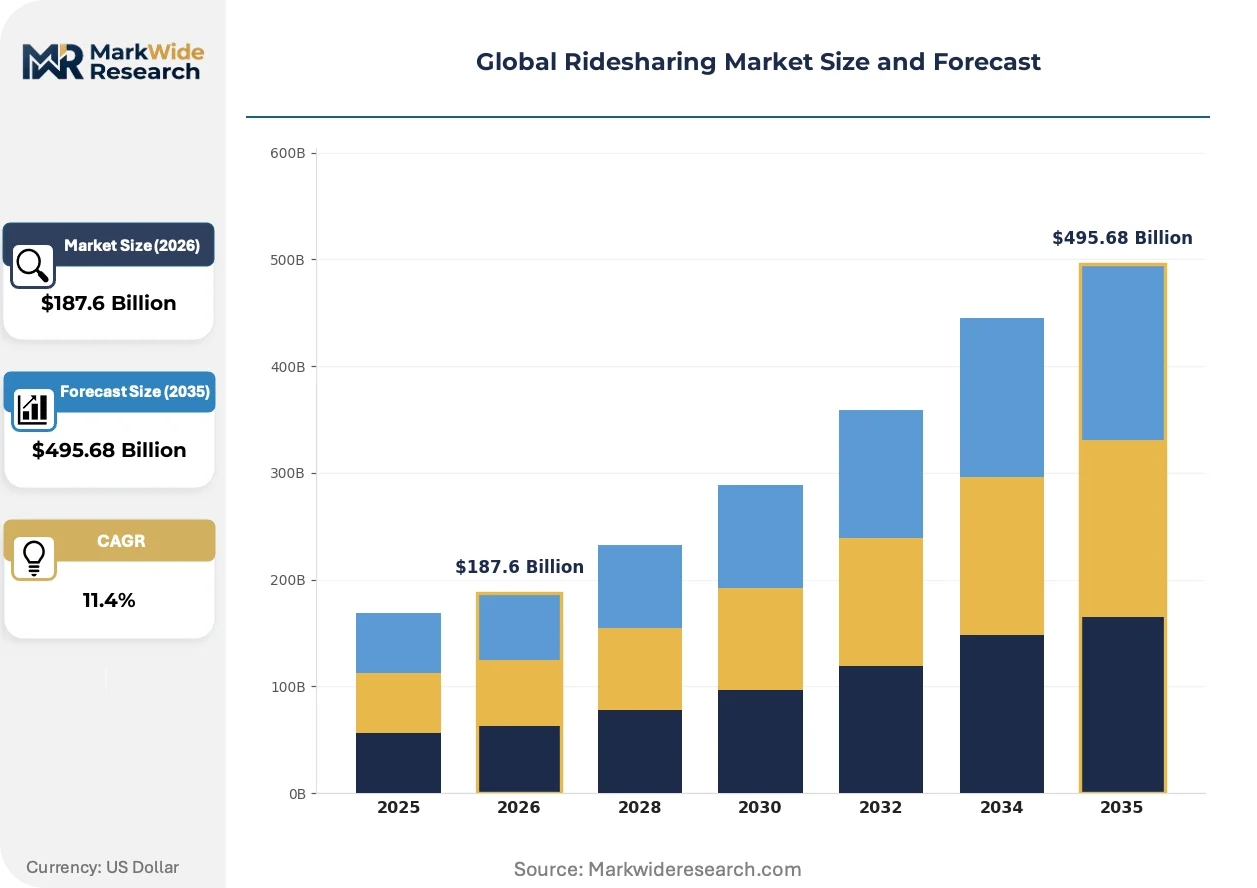
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ride-Hailing, Carpooling, Shuttle Services, Luxurious Rides Customer Type: Corporate Users, Individual Consumers, Tourists, Elderly Users Technology: Mobile Apps, Web Platforms, GPS Navigation, Payment Integration Operating Model: Peer-to-Peer, Fleet Management, Subscription Services, On-Demand |
| Companies Covered | Uber Technologies Inc., DiDi Global Inc., Lyft, Inc., Grab Holdings Inc., ANI Technologies Pvt. Ltd. (Ola Cabs), Bolt Technology OÜ, Careem, Cabify Spain SLU, BlaBlaCar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ridesharing Market Strategic Shifts
Telematics hardware and edge-computing inference engines are compressing the cost curve for real-time vehicle monitoring, enabling granular driver behavior scoring and predictive maintenance integration that reshapes fleet insurance economics.
Sensor fusion technology for autonomous navigation is miniaturizing from rooftop-mounted arrays to windshield-integrated modules, reducing per-vehicle retrofit costs. Ride-hailing operators in Phoenix and San Francisco are piloting these streamlined configurations for limited driverless service zones. The structural consequence is a compression of the timeline for regulatory approval of expanded autonomous operating areas.
The EU's Platform Work Directive mandates algorithmic transparency and employment reclassification for gig workers, forcing platform operators to restructure labor cost models. This regulatory shift most acutely affects cross-border operators with significant European driver networks, who are responding by segmenting fleet ownership structures and introducing guaranteed minimum earning floors.
Corporate procurement of ground transportation is consolidating under centralized mobility-as-a-service platforms that unbundle traditional fleet ownership. Travel managers at multinational enterprises are replacing employee reimbursement models with direct platform billing relationships, a pattern most visible in German and British corporate travel programs where sustainability reporting requirements favor shared mobility over rental vehicles.
Global Ridesharing Market Segmentation
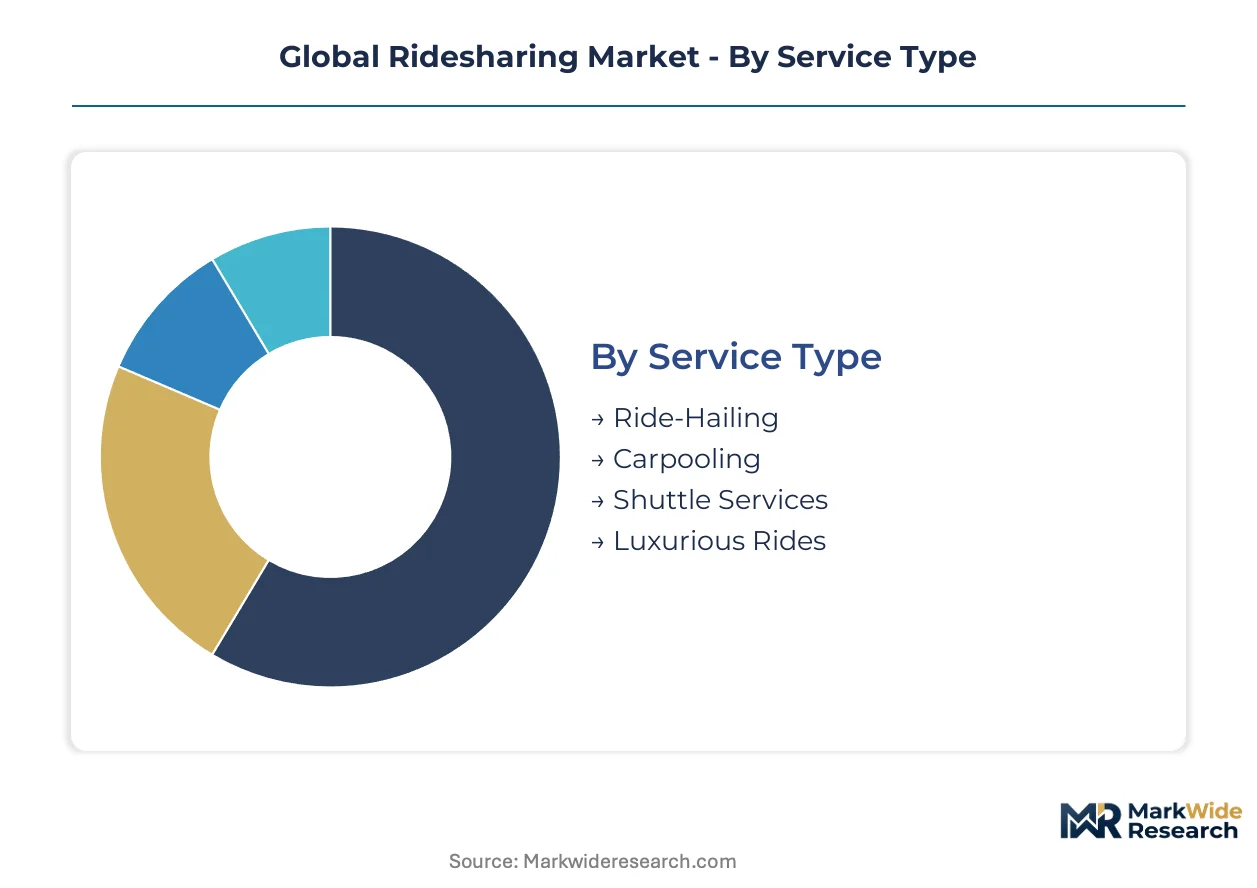
Ridesharing platforms coordinate supply and demand through distinct service configurations that match vehicle capacity to trip purpose. Each segmentation dimension reveals divergent margin structures and regulatory exposure across operator business models.
Service Type:
Ride-hailing and carpooling dominate mobile app distribution channels, while shuttle services and luxury segments concentrate through corporate procurement portals and premium booking interfaces.
- Ride-Hailing:On-demand dispatch of dedicated vehicles for single-party trips generates the highest per-trip revenue and driver utilization rates. Demand concentrates in Indian and Brazilian metropolitan corridors where two-wheeler alternatives supplement four-wheel coverage gaps.
- Carpooling:Algorithmic matching of co-directional passengers into shared vehicle occupancy reduces per-passenger fare burden while improving driver earnings per kilometer. This segment is expanding most quickly in European cities with congestion pricing zones and corporate sustainability mandates.
- Shuttle Services:Fixed-route, scheduled-availability operations serve airport corridors and intercity connectors through pre-booked capacity.
- Luxurious Rides:Premium vehicle classes with certified professional drivers target executive travel and hospitality sector procurement.
Ride-hailing dominates installed base. Carpooling is where expansion concentrates.
Customer Type:
Cost tier stratification separates enterprise accounts with negotiated rate cards from retail consumers facing dynamic surge pricing.
- Corporate Users:Centralized mobility budgets and direct platform billing relationships generate predictable trip volume with lower customer acquisition costs. Procurement concentrates in German and British enterprise travel programs where sustainability reporting requirements favor shared mobility.
- Individual Consumers:Price-sensitive retail demand responds acutely to subsidy levels and competitor promotional intensity. This segment anchors network density in Indian tier-two cities where first-time smartphone adoption expands addressable population.
- Tourists:Cross-border payment compatibility and multilingual interface requirements distinguish this demand pool.
- Elderly Users:Accessibility features and phone-based booking alternatives address digital literacy barriers.
Individual consumers anchor trip volume. Corporate users concentrate margin expansion.
Technology:
Application layer maturity separates established markets with embedded wallet ecosystems from emerging corridors requiring cash-equivalent payment bridges.
- Mobile Apps:Native iOS and Android applications with real-time GPS telemetry and push-notification dispatch constitute the primary coordination layer. Demand concentrates in Southeast Asian markets where super-app integration bundles rides with food delivery and financial services.
- GPS Navigation:Proprietary mapping layers and real-time traffic inference engines reduce estimated time of arrival variance. This segment is climbing the fastest as operators in China and the United States deploy lidar-augmented localization for autonomous fleet preparation.
- Web Platforms:Browser-based booking interfaces serve corporate travel managers and accessibility-constrained users.
- Payment Integration:Embedded wallet, buy-now-pay-later, and cross-border remittance rails reduce transaction abandonment.
Mobile apps dominate active user interfaces. GPS navigation is where R&D investment concentrates.
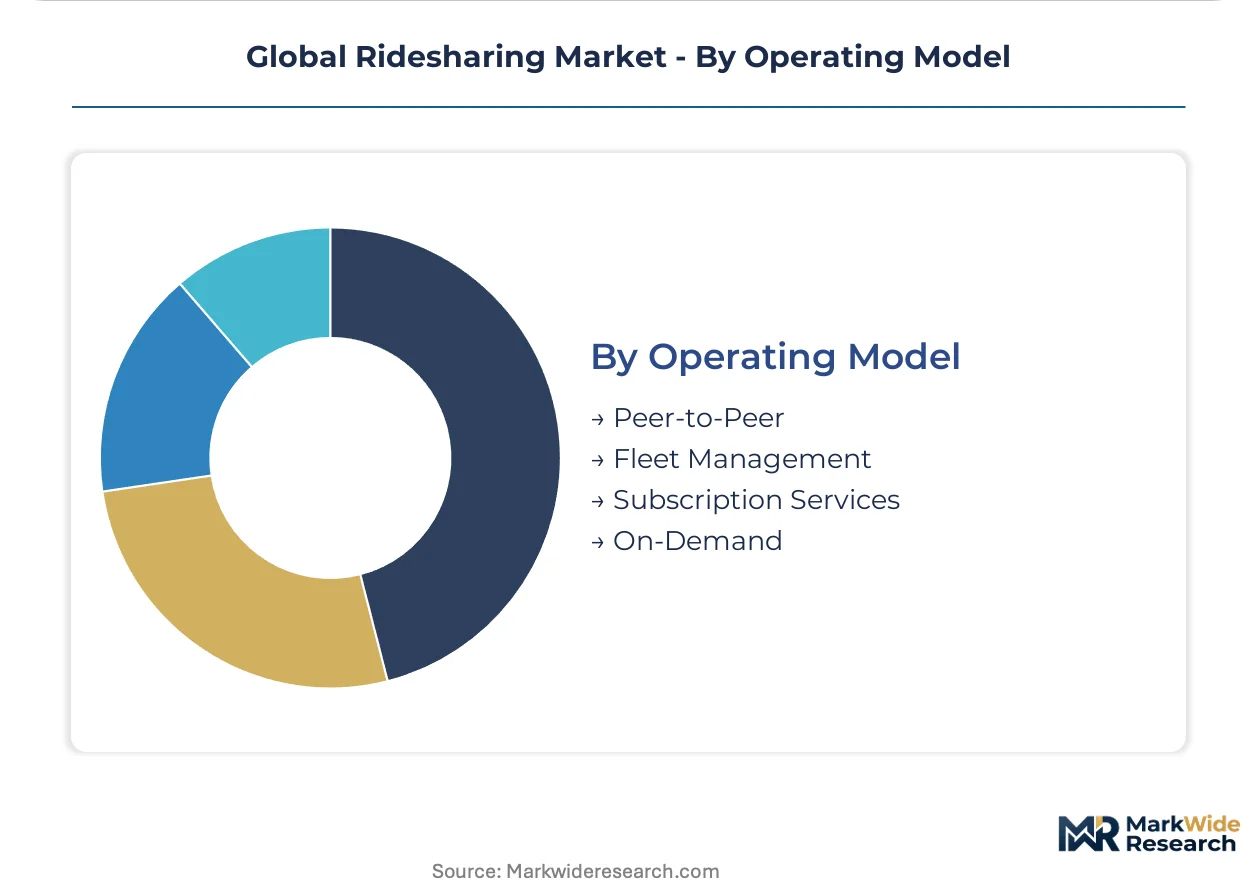
Operating Model:
Asset ownership structure determines regulatory classification and balance sheet intensity across jurisdictions with divergent employment reclassification risk.
- Peer-to-Peer:Driver-owned vehicles matched through platform dispatch minimize capital deployment while maximizing network coverage elasticity. Demand concentrates in Latin American markets where vehicle ownership rates exceed formal employment density.
- Fleet Management:Platform-operated or leased vehicle pools enable quality standardization and electrification mandates. This configuration is gaining share fastest in European cities with zero-emission zone requirements and driver supply certification chokepoints.
- Subscription Services:Recurring flat-fee access models bundle fixed trip allowances for predictable commuter expenditure.
- On-Demand:Instant-availability dispatch without advance reservation dominates time-sensitive use cases.
Peer-to-peer dominates active driver supply. Fleet management is where regulatory compliance investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Motor Vehicle Aggregator Guidelines and the EU's Platform Work Directive are recalibrating compliance costs for operators entering these jurisdictions. Brazil's ANTT regulations and Singapore's LTA frameworks similarly reshape market entry sequencing. Demand clusters concentrate where urban congestion pricing and smartphone penetration intersect.
United States
Corporate mobility budgets and airport corridor density drive trip volume in metropolitan clusters. The Department of Transportation enforces driver background verification through the FMCSA Drug and Alcohol Clearinghouse. Phoenix and San Francisco anchor autonomous vehicle pilot zones where sensor-fusion fleets operate within geofenced service areas.
Germany
Enterprise sustainability reporting requirements and zero-emission zone mandates accelerate fleet electrification commitments. The KBA administers commercial licensing standards that constrain eligible operator pools in Berlin and Munich. Corporate procurement consolidation under mobility-as-a-service platforms concentrates in Frankfurt and Hamburg financial corridors.
India
Smartphone-first user adoption and tier-two city expansion generate the fastest passenger growth globally. The Ministry of Road Transport and Highways enforces data localization and fare transparency through Motor Vehicle Aggregator Guidelines. Bengaluru and Hyderabad compete for platform R&D investment while Delhi-NCR and Mumbai anchor revenue concentration.
Brazil
Peer-to-peer vehicle ownership rates and informal employment density sustain network elasticity in São Paulo and Rio de Janeiro. ANTT oversight of interstate passenger transport creates compliance architecture for platform operators. The Southeast region concentrates trip frequency where motorcycle-based last-mile services supplement four-wheel coverage.
Singapore
Electronic Road Pricing and Ultra Low Emission Zone equivalents push private vehicle owners toward shared alternatives. The Land Transport Authority imposes fleet electrification timelines and driver vocational licensing standards. The city-state functions as a regulatory template for Southeast Asian market entry sequencing.
Global Ridesharing Market Competitive Environment
Player mix skews toward integrated platform operators with dual-sided network density. Market structure concentrates around three to five dominant coordinators in each metropolitan corridor, with long-tail regional specialists occupying secondary cities. Strategic archetypes include algorithmic dispatch specialists, fleet-owning platform operators, and super-app integrators bundling mobility with financial services. Competitive moves center on autonomous vehicle R&D partnerships and driver incentive restructuring to absorb employment reclassification costs.
Within the integrated platform tier, Uber Technologies Inc. and DiDi Global Inc. occupy positions reflecting divergent geographic emphases, while ANI Technologies Pvt. Ltd. anchors the Indian subcontinent competitive dynamic. These entities exemplify the capital-intensive network density model where real-time matching algorithms and embedded payment rails constitute core infrastructure. Regional specialists such as Grab Holdings Inc. and Bolt Technology OÜ represent alternative scaling paths through two-wheeler service expansion and emerging market penetration strategies.
| Leading Market Players |
|---|
| Uber Technologies Inc. |
| DiDi Global Inc. |
| Lyft, Inc. |
| Grab Holdings Inc. |
| ANI Technologies Pvt. Ltd. (Ola Cabs) |
| Bolt Technology OÜ |
| Careem |
| Cabify Spain SLU |
| BlaBlaCar |
| Others |
Value Chain & Pricing Dynamics
Driver onboarding lead-times stretching to 14-21 days in congested metropolitan corridors compress platform pricing power by constraining supply elasticity when surge demand spikes. This inventory-like bottleneck in certified operator pools forces dynamic pricing algorithms to absorb higher subsidy burdens during peak periods, directly coupling supply-chain certification chokepoints to margin compression.
Pricing Analysis
Certification level (commercial driver's license plus vehicle-for-hire permitting) creates the primary spread between peer-to-peer and fleet-managed service tiers. Three-tier pricing structure across premium, standard, and economy levels segments corporate accounts with negotiated rate cards from individual consumers facing real-time surge multipliers. Pricing pressure stems from fuel cost volatility transmitting directly to driver earnings and platform subsidy requirements. Individual consumers in Indian tier-two cities exhibit highest price sensitivity, while German enterprise travel managers with sustainability mandates show lowest elasticity.
Supply Chain Analysis
Commercial licensing bottlenecks in Berlin, Mumbai, and São Paulo constrain eligible operator pools and fragment supply concentration across regulatory jurisdictions. The ridesharing ecosystem draws from smartphone manufacturing in China, telematics hardware in Taiwan, and payment processing infrastructure in the United States. Single-source vulnerability concentrates in proprietary mapping and dispatch algorithm providers. Distribution runs through mobile app stores and embedded super-app integrations rather than traditional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where super-app bundling of mobility with financial services and food delivery is displacing standalone ride-hailing applications. Interoperability between autonomous vehicle sensor stacks and legacy dispatch infrastructure will determine competitive survival.
For Market Incumbents: Secure driver supply certification pipelines through partnerships with vocational training institutes in Indian and Brazilian metropolitan corridors. Lock in fleet electrification commitments ahead of zero-emission zone mandates in German and British urban centers. Absorb employment reclassification costs through guaranteed minimum earning floors rather than per-trip subsidies. For New Entrants and Emerging Players: Anchor in two-wheeler service gaps across Southeast Asian and Latin American urban agglomerations where four-wheel penetration remains limited. Target corporate mobility procurement in Frankfurt and Hamburg financial corridors where sustainability reporting requirements favor shared mobility over rental vehicles. Pursue super-app integration partnerships rather than standalone app launches. For Investors and Strategic Acquirers: Carve-out targets emerge from automotive OEMs spinning off autonomous vehicle divisions and telematics hardware specialists. Long-term viability hinges on regulatory approval timelines for expanded driverless operating areas and employment classification stability across European jurisdictions. Monitor EU Platform Work Directive implementation as the critical inflection signal for labor cost model restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Vehicle Fleet Pilot | Sensor-fusion deployments in Phoenix and San Francisco compress regulatory approval timelines for driverless expansion. |
| Two-Wheeler Service Expansion | Motorcycle and scooter platforms address last-mile gaps in Jakarta and São Paulo where car ownership lags. |
| Super-App Integration Partnership | Embedding ride-hailing within Grab and Gojek ecosystems reduces customer acquisition costs through cross-service bundling. |
| Corporate Mobility Contract Consolidation | Direct billing relationships with German and British enterprise travel managers generate predictable trip volume. |
| Fleet Electrification Commitment | Zero-emission vehicle mandates in London and Singapore compliance windows force capital redeployment ahead of deadlines. |
Study Parameters
Cross-validation between primary interviews with platform operations executives and secondary validation through SEC filings and app store analytics anchors the qualitative findings. Conversations with fleet managers, driver supply coordinators, urban mobility planners, and corporate travel procurement officers generated ground-level operational data. Bottom-up driver supply modeling and top-down metropolitan trip volume estimates triangulate market sizing across service type and customer segments.
Sensitivity analysis around fuel price volatility and employment reclassification scenarios shapes the analytical framework across the projection horizon. Segmentation dimensions include service configuration, customer archetype, technology interface, and operating model ownership structure. CAGRs derive from driver supply elasticity curves and smartphone penetration trajectories in emerging metropolitan corridors.
Underlying assumptions cover regulatory stability in Indian and European jurisdictions, with deviation risk concentrated in EU Platform Work Directive enforcement intensity and autonomous vehicle permitting timelines. Practitioners should keep alternative scenarios live as employment classification rulings and zero-emission zone mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Cellular Vehicle-To-Everything (C-V2X) Market
Smart Transportation Solutions
Traffic Monitoring Market
Smart Transportation Solutions
Rail Internet of Things (IoT) Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Automated Parking Systems Market
Smart Transportation Solutions
Mexico Ride Hailing Market
Smart Transportation Solutions
Automated People Mover Market
Smart Transportation Solutions
Personal Transporter Market
Smart Transportation Solutions
Closed Platform Screen Doors Market
Smart Transportation Solutions
France Ridesharing Market
Smart Transportation Solutions
Transportation Predictive Analytics Market
Smart Transportation Solutions
Parking Space Management Market
Smart Transportation Solutions
Europe Connected Cars Market
Smart Transportation Solutions
Big Data Analytics in Transportation Market
Smart Transportation Solutions
Autonomous Warehouse Charging Infrastructure Market
Smart Transportation Solutions
Traffic Signal Controller Market