
 Reusable Plastic Water Bottles Market | 2026-2036
Reusable Plastic Water Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Plastic Water Bottles Market Outlook
LFGB food-contact certification is unwinding competitive access for Asian exporters unable to document migration testing for polycarbonate alternatives. Nalgene Outdoor Products sustains North American shelf presence through FDA-compliant Tritan copolyester formulations. SIGG Switzerland AG anchors European premium positioning with dual compliance under REACH and LFGB protocols. Contigo competes on sealed-lid engineering that addresses airline carry-on restrictions.
Reusable plastic water bottles are cylindrical or contoured vessels manufactured from food-grade thermoplastics—typically Tritan copolyester, polypropylene, or polyethylene—designed for repeated filling, cleaning, and transport of potable liquids. Wall thickness ranges from 0.8 mm for ultralight hiking models to 2.5 mm for insulated vacuum-assisted designs, with mouth diameters spanning 28 mm standard to 63 mm wide-mouth configurations for ice accommodation and brush access. BPA-Free and Tritan product categories command margin premiums due to consumer chemophobia and retail buyer mandates, while Polypropylene variants dominate institutional procurement for schools and corporate campuses where unit cost thresholds override material prestige. Folding feature designs represent the fastest-growing functional segment among travelers and ultralight backpackers prioritizing packability over thermal retention.
FDA food-contact notification requirements govern polymer selection and additive packages for US-bound production, while REACH substance restrictions and the EU Single-Use Plastics Directive collectively elevate reusable formats over disposable competitors in European retail. China's GB 4806.7 national food safety standard for plastics adds a third compliance layer for manufacturers sourcing base resins from domestic petrochemical suppliers. Stakeholders must monitor evolving state-level extended producer responsibility proposals in California and New York that could mandate recycled content minimums or standardized threading for cap-bottle compatibility.
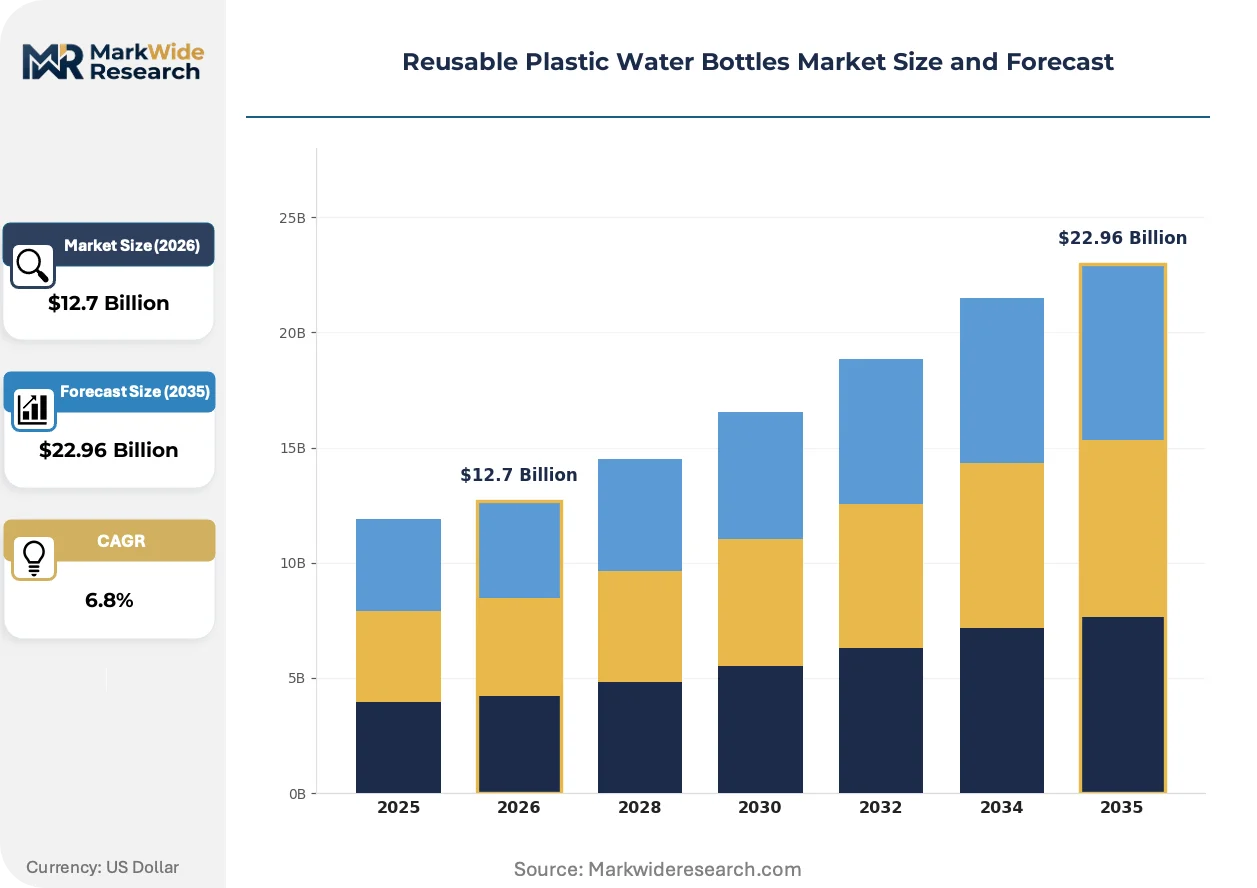
Market Dynamics
The EU Single-Use Plastics Directive is compressing demand for disposable alternatives and forcing retail shelf reallocation toward refillable formats across member states. Municipal refill station networks in Germany and deposit-return infrastructure are creating structural pull that locks in habitual reuse behavior among urban consumers.
Growth Catalysts
- Fitness culture normalization:Gym memberships and outdoor recreation participation are embedding bottle-carrying as standard equipment behavior among health-conscious consumers.
- REACH substance restrictions:ECHA protocols on polymer migration testing are elevating certified reusable formats above unverified imports in European retail channels.
- Tritan copolyester adoption:BPA-free polymer formulations are capturing premium shelf space as chemophobia drives material substitution in food-contact applications.
Market Restraints
- Petrochemical input volatility:Tritan and polypropylene resin prices fluctuate with crude oil derivatives, compressing margin stability for mid-tier manufacturers.
- Asian exporter documentation gaps:LFGB certification requirements exclude suppliers unable to complete migration testing protocols for polycarbonate alternatives.
- Stainless steel substitution:Metal bottles are capturing thermal retention segments where insulation performance outweighs weight considerations.
Strategic Opportunities
- Folding feature designs:Packable silicone and collapsible thermoplastic constructions are opening ultralight backpacker and digital nomad segments.
- Extended producer responsibility mandates:California and New York state proposals on recycled content minimums would advantage domestic producers with circular supply chains.
- Airline channel penetration:Sealed-lid engineering compatible with TSA liquid restrictions is creating duty-free and travel retail placement opportunities.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA, REACH, and GB 4806.7 compliance requires parallel testing tracks that extend product launch windows.
- Cap-bottle threading standardization:Proprietary mouth diameter designs fragment accessory ecosystems and complicate consumer replacement purchases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Plastic Water Bottles Market |
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $22.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BPA-Free, Tritan, Polyethylene, Polypropylene End User: Fitness Enthusiasts, Travelers, Students, Office Workers Feature: Insulated, Folding, Built-in Filter, Wide Mouth Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Nalgene Outdoor Products, Tupperware Brands Corporation, Contigo, CamelBak Products LLC, Klean Kanteen Inc., SIGG Switzerland AG, Thermos LLC, Elite S.r.l., Cascade Designs Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Plastic Water Bottles Market Strategic Shifts
Material science advances and regulatory pressure on single-use formats are converging to reshape competitive positioning around certification depth and functional differentiation rather than price alone.
Tritan copolyester formulations are displacing legacy polycarbonate in premium segments due to superior clarity and thermal stability without bisphenol-A content. Fitness enthusiasts and institutional procurement officers are accelerating adoption as retail buyers mandate BPA-free documentation. This material shift is compressing margins for uncertified Asian exporters while rewarding European and North American producers with existing FDA and LFGB dossiers.
REACH substance restrictions and the EU Single-Use Plastics Directive are collectively elevating reusable formats in continental retail assortments. ECHA protocols on polymer additives are forcing reformulation of colorants and stabilizers across the supply base. German and French mass-market retailers are responding by delisting non-compliant imports and sourcing exclusively from REACH-registered manufacturers.
Certification-driven preference shifts are restructuring B2B procurement patterns as corporate sustainability officers mandate vendor documentation. Schools and corporate campuses are replacing opaque supplier relationships with direct contracts to certified manufacturers. This behavior is most visible in Germany, where municipal sustainability frameworks require public institution compliance with EU Green Deal procurement guidelines.
Reusable Plastic Water Bottles Market Segmentation
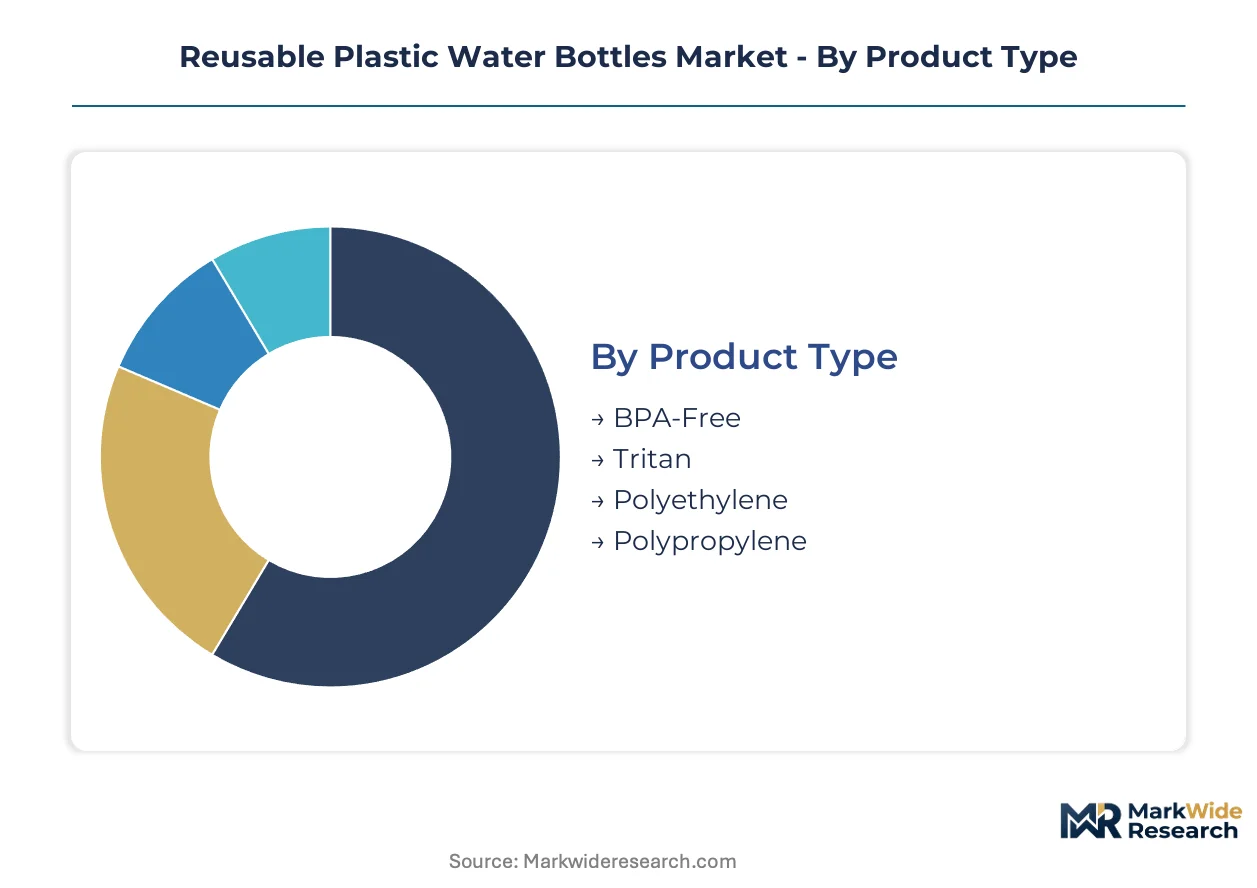
Segmentation in reusable plastic water bottles reveals how material certification, functional design, and channel access create distinct margin architectures. Each dimension shapes procurement patterns and competitive positioning differently across consumer and institutional demand pools.
Product Type:
Margin pools concentrate in certified polymer grades where regulatory documentation creates supply scarcity and pricing power.
- BPA-Free:Copolyester and polypropylene formulations exclude bisphenol-A through alternative catalyst systems. Demand clusters among parents purchasing for school-age children and corporate wellness programs where liability concerns override unit cost considerations.
- Tritan:Eastman Chemical's proprietary copolyester delivers optical clarity and dishwasher durability superior to commodity alternatives. German and French premium retailers source exclusively from FDA-registered manufacturers, locking out uncertified Asian suppliers.
- Polyethylene:Low-density grades dominate collapsible and ultralight constructions for hiking applications.
- Polypropylene:Institutional procurement favors this material for impact resistance and microwave reheat compatibility in campus and healthcare settings.
Tritan holds installed capacity. BPA-Free is rotating up the share rankings.
End User:
Volume concentration follows lifestyle patterns that normalize bottle-carrying as default equipment behavior.
- Fitness Enthusiasts:Gym culture and outdoor recreation participation embed hydration vessels as standard workout gear. Germany's municipal refill station networks reinforce habitual reuse among urban exercisers.
- Travelers:TSA-compatible sealed-lid engineering opens duty-free and airport retail placement. Digital nomads prioritize packable formats that compress for carry-on constraints.
- Students:School district procurement mandates BPA-free documentation, favoring certified domestic suppliers over opaque import channels.
- Office Workers:Corporate sustainability officers direct vendor selection toward REACH-registered manufacturers with circular supply chain credentials.
Fitness Enthusiasts command the steepest expansion trajectory. Travelers are gaining share fastest among premium-priced functional designs.
Feature:
Functional differentiation creates pricing tiers that separate thermal performance from packability priorities.
- Insulated:Double-wall vacuum-assisted constructions with 2.5 mm wall thickness retain temperature for extended periods. Stainless steel substitutes capture this segment where thermal performance outweighs weight considerations.
- Folding:Silicone and collapsible thermoplastic constructions compress to pocket size for ultralight backpackers. This segment is climbing the fastest as digital nomad mobility patterns spread.
- Built-in Filter:Activated carbon and hollow-fiber membrane integrations address emerging market portable water quality concerns.
- Wide Mouth:63 mm diameter openings accommodate ice cubes and brush access for cleaning compliance in institutional settings.
Insulated holds installed capacity. Folding is rotating up the share rankings.
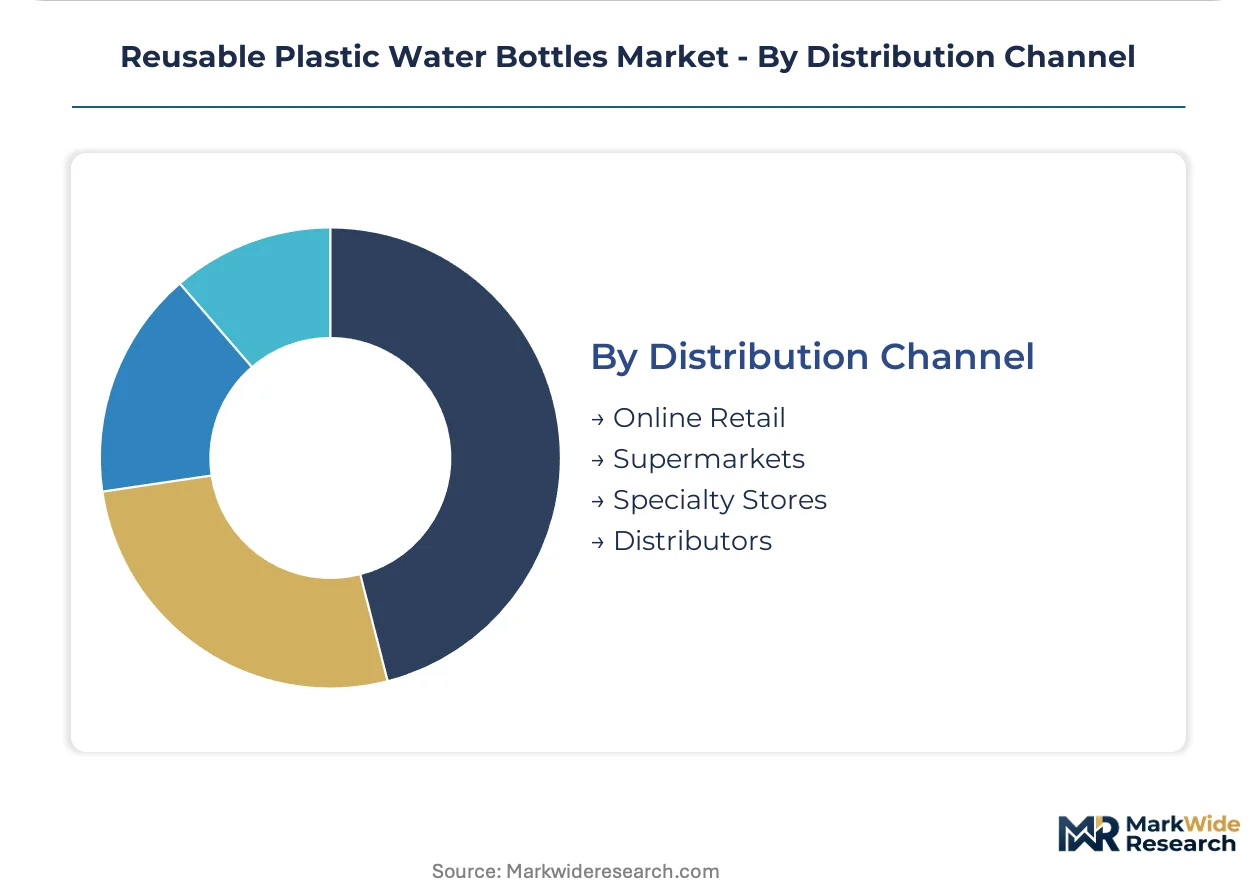
Distribution Channel:
Channel economics diverge between certification-heavy retail and direct-to-consumer speed-to-market advantages.
- Online Retail:E-commerce platforms enable rapid product iteration and consumer education on material specifications. California and New York state extended producer responsibility proposals would advantage domestic sellers with recycled content documentation.
- Supermarkets:Mass-market shelf placement requires REACH or FDA dossier completion that excludes uncertified import suppliers. German retailers lead in delisting non-compliant products.
- Specialty Stores:Outdoor and fitness retailers emphasize technical performance metrics and brand storytelling for enthusiast segments.
- Distributors:B2B procurement consolidation favors manufacturers with multi-jurisdiction certification depth and institutional contract experience.
Supermarkets hold installed capacity. Online Retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness enthusiasts and institutional procurement officers concentrate demand in Germany, the United States, China, and Japan, where regulatory infrastructure and consumer chemophobia create distinct market access conditions. Each geography presents unique certification barriers and channel dynamics that reshape competitive positioning.
Germany
Municipal refill station networks in Berlin, Hamburg, and Munich normalize habitual bottle-carrying among urban exercisers. The EU Single-Use Plastics Directive and REACH substance restrictions under ECHA protocols exclude uncertified imports from mass-market retail. Bavaria's outdoor manufacturing cluster around Rosenheim supplies premium Tritan formulations to REWE and Edeka chains.
United States
Gym culture penetration and corporate wellness programs embed hydration vessels as standard equipment across fitness chains and office campuses. FDA food-contact notification requirements govern polymer selection for domestic production. California's extended producer responsibility proposals on recycled content minimums would advantage West Coast manufacturers with circular supply chains.
China
Domestic petrochemical suppliers feed Guangdong and Zhejiang molding clusters serving both export and emerging middle-class consumption. GB 4806.7 national food safety standards add compliance complexity for manufacturers sourcing base resins locally. Shenzhen's e-commerce logistics hubs enable rapid product iteration for direct-to-consumer brands.
Japan
Health-conscious consumers and outdoor recreation participants drive premium positioning for BPA-free and Tritan formulations. METI guidelines on food-contact materials align with international standards while maintaining additional domestic testing protocols. Osaka's chemical processing district hosts specialized additive compounding for colorant and stabilizer reformulation.
Switzerland
Outdoor tourism and alpine sports culture sustain demand for ultralight and insulated constructions among hiking and skiing enthusiasts. Dual LFGB and REACH compliance requirements position Swiss manufacturers as premium suppliers to EU retail channels. The Zurich-Geneva corridor concentrates design-engineering capabilities for sealed-lid innovations addressing airline carry-on restrictions.
Reusable Plastic Water Bottles Market Competitive Environment
Player mix skews toward specialty outdoor brands and diversified housewares conglomerates with certification depth. The vendor base separates into three tiers: premium-positioned European specialists with dual REACH-LFGB dossiers, North American brands leveraging FDA-compliant Tritan formulations for retail shelf access, and Asian contract manufacturers facing documentation barriers to European mass-market entry. Dominant competitive moves include geographic expansion through distributor partnerships and portfolio diversification into adjacent hydration categories.
Within the premium-tier vector, SIGG Switzerland AG anchors European positioning through dual regulatory compliance, while Nalgene Outdoor Products exemplifies North American market access through FDA-registered Tritan supply chains. Contigo occupies a position on functional differentiation, with sealed-lid engineering addressing TSA-compatible travel retail placement.
| Leading Market Players |
|---|
| Nalgene Outdoor Products |
| Tupperware Brands Corporation |
| Contigo |
| CamelBak Products LLC |
| Klean Kanteen Inc. |
| SIGG Switzerland AG |
| Thermos LLC |
| Elite S.r.l. |
| Cascade Designs Inc. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day resin inventory cycles at Guangdong molding clusters tether pricing power to petrochemical index movements, compressing margins for mid-tier manufacturers while rewarding vertically integrated players with captive copolyester supply. Certification documentation costs for FDA and REACH dossiers create fixed-cost barriers that stratify pricing tiers between documented exporters and uncertified regional suppliers.
Pricing Analysis
Cost-plus contracts indexed to Eastman Chemical's Tritan resin quotations dominate premium tier procurement, with price differentiation anchored in LFGB certification grade and volume scale commitments. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered European manufacturers from FDA-compliant North American suppliers and uncertified Asian exporters. Pricing pressure stems from polypropylene resin volatility tied to crude derivatives, with institutional buyers in German municipal procurement showing least price sensitivity due to sustainability mandate compliance requirements.
Supply Chain Analysis
Sixty-day order-to-delivery lead times from Zhejiang molding hubs to European retail channels reflect geographic supply concentration across China, Germany, and the United States. Base resin supply draws from Eastman Chemical's Tennessee copolyester production, SABIC's European polypropylene complexes, and domestic Chinese petrochemical suppliers under GB 4806.7 standards. Single-source vulnerability concentrates in specialized colorant and stabilizer additives subject to ECHA REACH reformulation mandates. Distribution runs through REWE and Edeka supermarket chains in Germany, Amazon and direct-to-consumer platforms in North America, and Shenzhen e-commerce logistics hubs serving Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among German municipal procurement officers and North American corporate sustainability directors, fragmenting vendor access into certified and uncertified supplier tiers with diverging margin outcomes.
For Market Incumbents: Shield installed shelf positions at REWE, Edeka, and REI by accelerating dual REACH-LFGB certification for Tritan copolyester formulations before California extended producer responsibility mandates take effect. Deepen backward integration into colorant compounding to reduce ECHA-driven reformulation exposure. Prioritize sealed-lid engineering R&D for TSA-compatible airline channel penetration. For New Entrants and Emerging Players: FDA food-contact notification fast-track procedures offer the lowest barrier to North American mass-market entry, opening white-space at Target and Walmart against established outdoor brands. Digital nomad segments present penetrable demand for folding silicone constructions with packable form factors. Pursue direct-to-consumer launch through Amazon and Shopify to bypass supermarket certification requirements. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-arbitrage play because certification depth determines market access more than manufacturing scale. Target acquisition archetypes include mid-cap European specialists with existing REACH dossiers and dormant FDA registrations. Watch for California recycled content mandate threshold crossings as inflection signal for domestic circular supply chain valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | REACH-LFGB dossier completion unlocks REWE and Edeka shelf placement against Asian competitors. |
| Folding Feature R&D | Silicone compressible designs capture digital nomad segments underserved by rigid Tritan incumbents. |
| Airline Channel Penetration | TSA-compatible sealed-lid engineering opens duty-free placement at Frankfurt and Dubai airports. |
| Backward Integration into Additives | In-house colorant compounding reduces ECHA reformulation risk and protects margin stability. |
| Direct-to-Consumer Pivot | Amazon and Shopify routes bypass supermarket certification barriers for emerging Asian manufacturers. |
Study Parameters
Initial hypotheses were tested against primary input from brand managers at outdoor equipment manufacturers, category buyers at German supermarket chains, supply planners at copolyester resin distributors, and regulatory affairs leads at food-contact packaging firms, then refined through secondary validation against FDA food-contact notifications, ECHA REACH registration dossiers, German customs trade data, and Nielsen retail audit records. Bottom-up demand modeling triangulated with top-down petrochemical consumption indicators.
Variance decomposition across material type, end-user segment, functional feature, and distribution channel dimensions structured the analytical framework throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against aggregate resin consumption projections. Industry-specific inputs included municipal refill station deployment schedules in Berlin and Hamburg, and California extended producer responsibility proposal tracking.
The analysis sits within stated boundaries; outcomes outside FDA, REACH, and GB 4806.7 regulatory stability would require recalibration. Forecasts reflect assumptions on petrochemical input cost trajectories and certification timeline continuity. Revision becomes warranted when ECHA substance restriction list expansions or California recycled content mandate implementations cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Brazil Plastic Bottles Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
Polyethylene Mailers Market
Plastic Packaging
Plastic Bottles and Containers Market
Plastic Packaging
Nigeria Plastic Bottles Market
Plastic Packaging
Egypt Plastic Packaging Market
Plastic Packaging
Plastic Medicine Bottles Market
Plastic Packaging
PET Jars Market
Plastic Packaging
Japan Plastic Packaging Market
Plastic Packaging
Europe Plastic Packaging Films Market
Plastic Packaging
Brazil Plastic Packaging Market
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
Plastic Aerosol Packaging Market
Plastic Packaging
Asia Pacific Single-Use Plastic Packaging Market
Plastic Packaging
Plastic Cans Market
Plastic Packaging
United States Plastic Packaging Films Market