
 France Plastic Caps and Closures Market | 2026-2036
France Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
France Plastic Caps and Closures Market Insights
Pharmaceutical-grade closure specifications is unwinding legacy commodity positioning across the French supply base. Berry Global, Inc. leverages its multi-material platform to serve sterile drug packaging requirements. Aptar Group differentiates through precision dosing closure technology for nasal and ophthalmic applications. Silgan Holdings Inc. anchors North American-to-European supply coordination for multinational pharmaceutical clients.
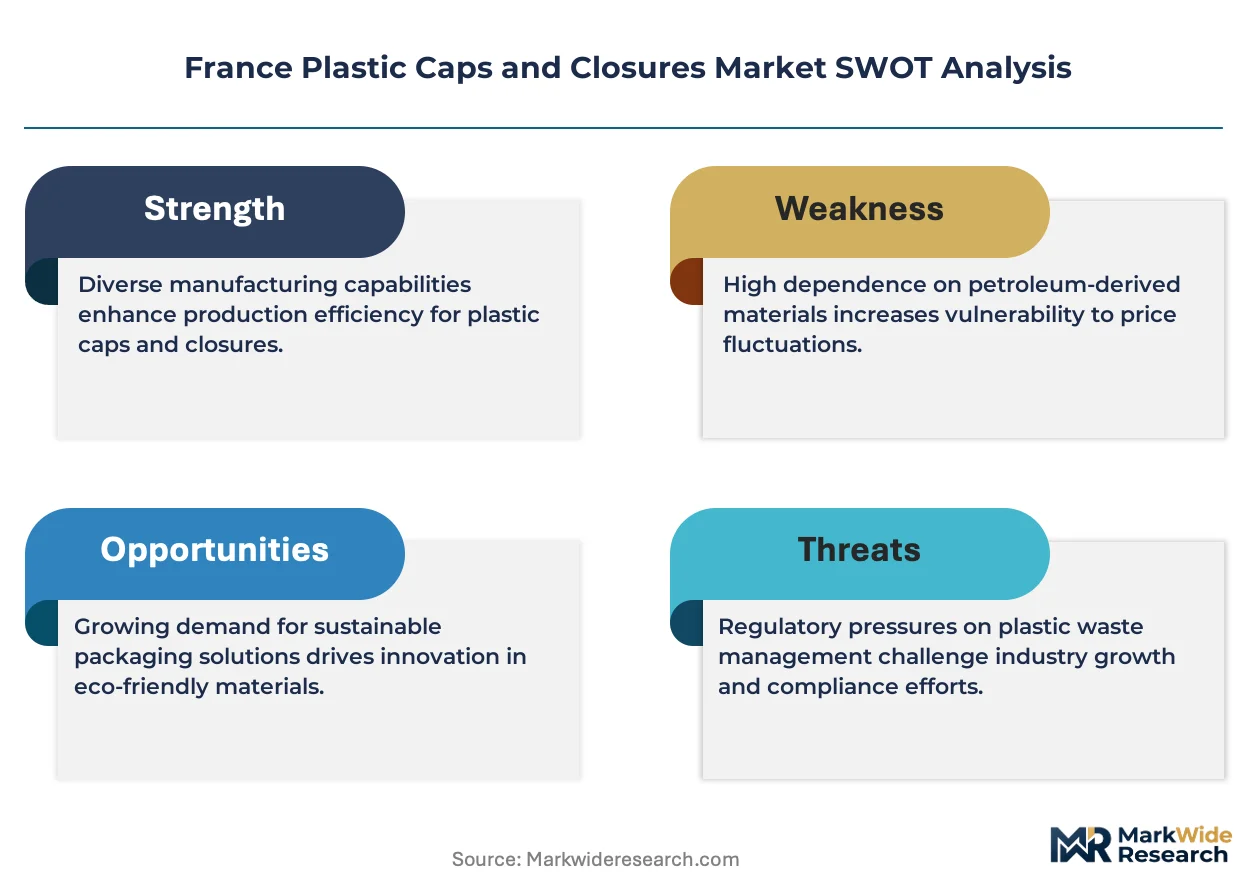
Plastic caps and closures are injection-molded or compression-molded thermoplastic components, typically manufactured from polyethylene or polypropylene with thread geometries measured in millimeter pitch standards, designed to seal containers against leakage, contamination, and tampering while enabling controlled dispensing. Screw caps occupy the mature volume core of the French market, serving still water and edible oil applications where cost efficiency dominates procurement criteria. Dispensing caps represent the fastest-growing product configuration, driven by concentrated detergent and personal care formulations requiring measured dosing functionality. Biodegradable plastics within the material matrix capture emerging margin pools as French retailers enforce shelf-ready sustainability credentials under corporate environmental commitments.
France's national environmental regulator enforces AGEC circular economy requirements mandating minimum recycled plastic content thresholds in consumer packaging, directly elevating rPET and rPP compound qualification costs for closure manufacturers. ANSM pharmaceutical standards govern child-resistant and senior-friendly closure designs, constraining mold modification cycles for suppliers serving prescription drug markets. ECHA REACH chemical registration obligations restrict certain additive chemistries in food-contact closures, compelling reformulation investments across the supplier tier. Stakeholders must monitor evolving French decree implementation timelines for recycled content mandates and position compound qualification capabilities ahead of enforceable compliance deadlines.
Market Dynamics
France's AGEC circular economy law is forcing closure manufacturers to requalify entire compound portfolios around minimum recycled content thresholds, compressing legacy virgin-resin supply relationships while elevating rPET and rPP processing capabilities.
Growth Catalysts
- AGEC Law Mandates:France's extended producer responsibility framework imposes binding recycled plastic quotas on consumer packaging, compelling brand owners to source certified post-industrial and post-consumer compounds for closure applications.
- Pharmaceutical Dosing Precision:Nasal and ophthalmic drug delivery systems require measured-dispensing closure architectures, expanding specification complexity beyond commodity screw-cap functionality.
- Île-de-France Packaging Cluster:Concentrated demand from Paris-region food, beverage, and cosmetics headquarters creates localized procurement gravity for specialized closure suppliers.
Market Restraints
- rPP/rPET Compound Volatility:Post-consumer resin availability fluctuates with French collection infrastructure maturity, creating input cost instability for recycled-content closure production.
- ANSM Certification Cycles:France's national pharmaceutical regulator enforces extended validation protocols for child-resistant and senior-friendly closure designs, extending mold modification timelines.
- Aluminum Closure Substitution:Premium wine producers in Bordeaux and Champagne test lightweight metal alternatives for sparkling and still wine segments, threatening plastic's established position.
Strategic Opportunities
- Biodegradable Compound Qualification:PLA and PHA-based closures certified under French retail sustainability protocols capture emerging shelf-ready positioning as Carrefour and E.Leclerc enforce corporate environmental commitments.
- Concentrated Detergent Dispensing:Refill-format household cleaning products require precision-dose closures, opening specification windows beyond traditional beverage and edible oil applications.
- AGEC Compliance Services:Closure suppliers bundling recycled-content certification, traceability documentation, and EPR fee management create differentiated value for mid-size French brand owners lacking in-house regulatory capacity.
Industry Challenges
- Multi-Material Mold Engineering Talent:France's specialized tooling workforce lacks depth in bi-injection and sequential molding techniques required for recycled-core/virgin-skin closure architectures.
- REACH Reformulation Timelines:ECHA chemical registration obligations force additive replacement in food-contact closures, compressing product requalification windows against fixed customer launch schedules.
- Legacy Equipment Retrofit Costs:Existing injection molding assets require substantial capital modification to process high-contamination recycled streams without quality degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Plastic Caps and Closures Market |
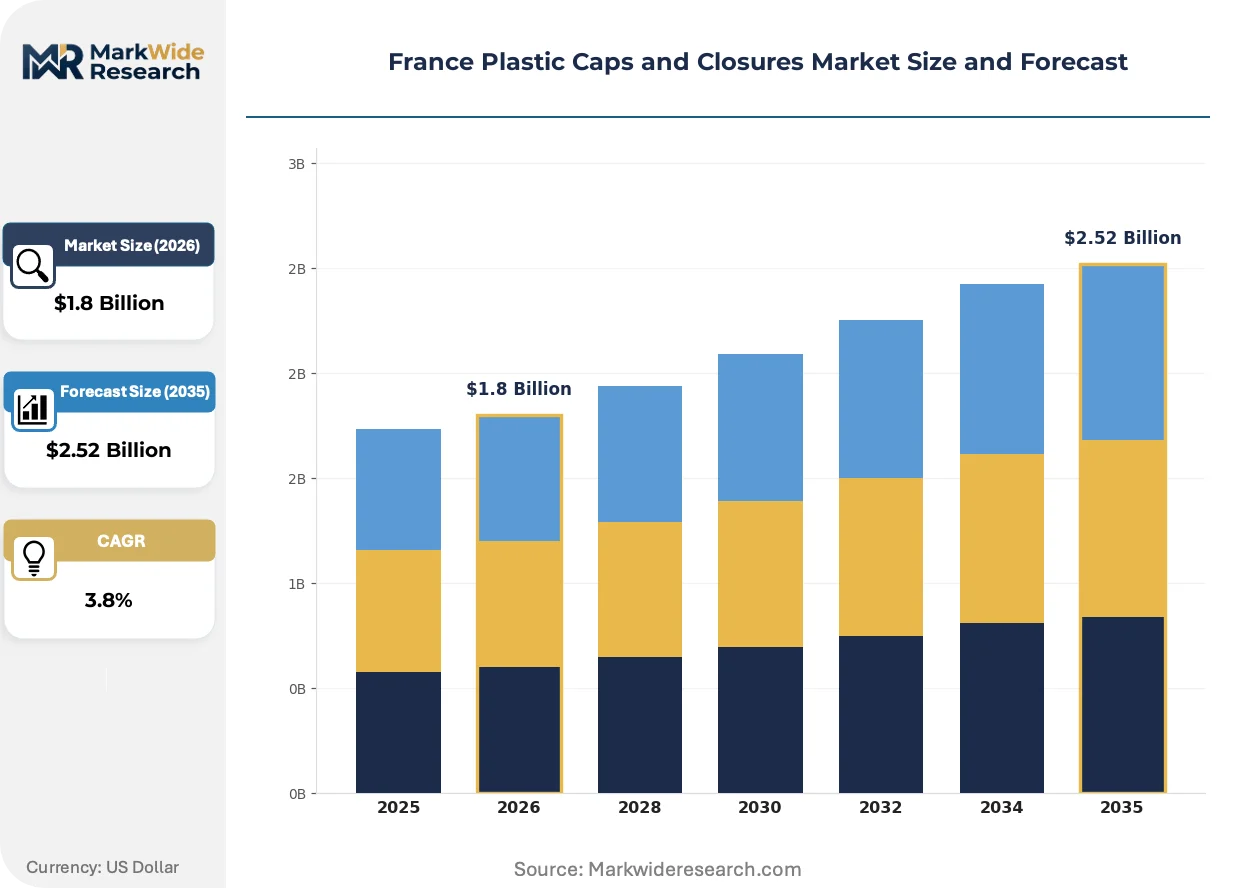
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.52 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Top Caps, Screw Caps, Dispensing Caps, Tamper Evident Caps Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Biodegradable Plastics End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Packaging Type: Bottles, Jars, Cans, Pouches |
| Companies Covered | Retal Industries Ltd, Bericap Holding GmbH, Berry Global, Inc., Silgan Holdings Inc., United Caps, Aptar Group, Jokey Group, Berlin Packaging, Guala Closures S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Plastic Caps and Closures Market Trends and Innovations
Material science advances and regulatory precision requirements are converging to transform closure architecture from passive sealing components into active dispensing and compliance-enabling systems.
Compression-molded HDPE closures with integrated tamper-evident bands are supplanting traditional injection-molded PP screw caps in French bottled water applications. Danone and Nestlé Waters France have accelerated adoption timelines to meet AGEC lightweighting targets. This transition is compressing energy consumption per unit while demanding new high-speed capping line investments across the supply base.
France's AGEC law implementation timeline tightens recycled-content thresholds progressively through enforceable decree deadlines. Closure manufacturers must front-load compound qualification investments ahead of compliance windows or face disqualification from major retail supply chains. The still water and edible oil segments face the most immediate reformulation pressure given their high volume and standardized specifications.
Brand owners now bundle closure specification decisions with EPR fee optimization and shelf-ready sustainability scoring. Procurement teams at L'Oréal and LVMH evaluate suppliers on traceability documentation depth, not unit cost alone. This behavioral shift concentrates contract awards among compounders with integrated recycling partnerships and certified mass-balance accounting systems.
France Plastic Caps and Closures Market Segmentation
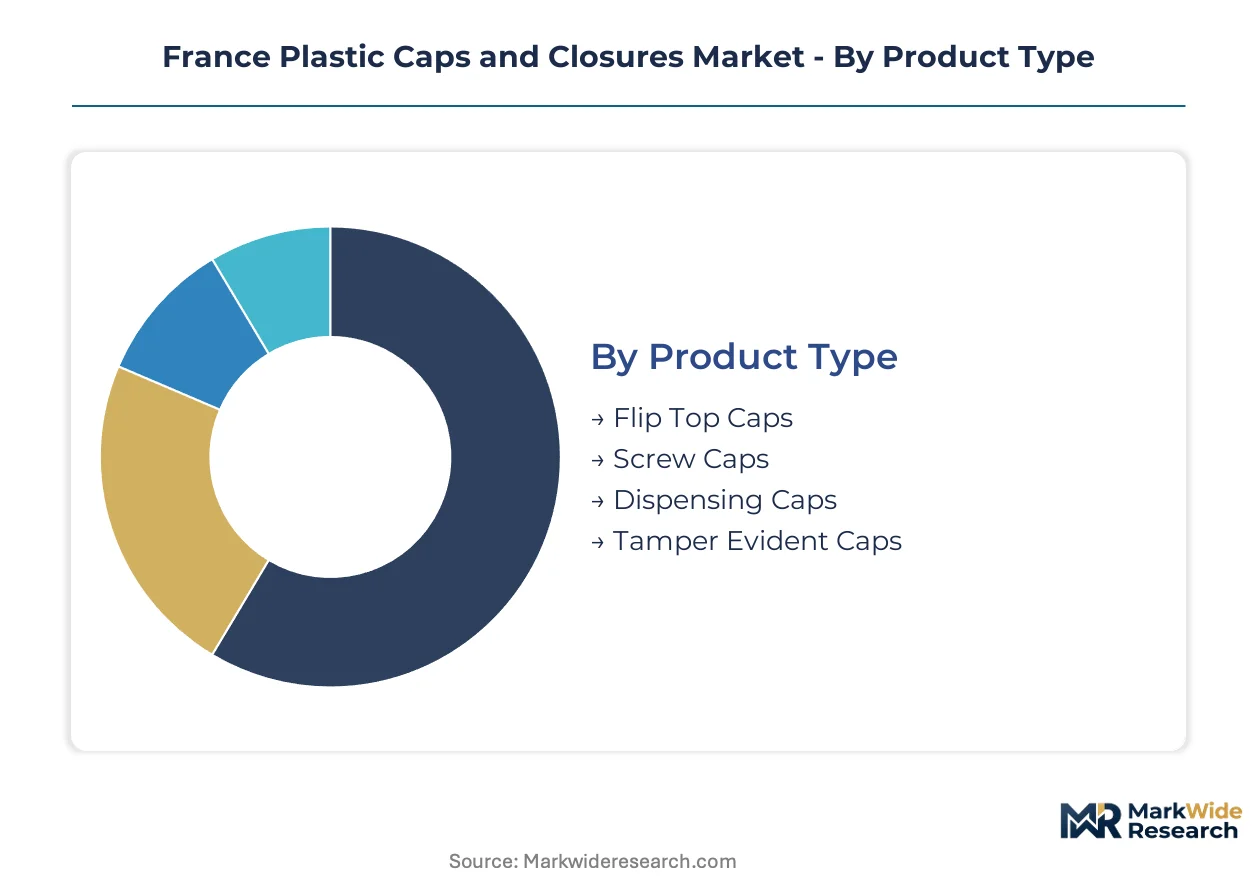
Segmentation in the France Plastic Caps and Closures Market reveals distinct pressure points where aluminum substitution, AGEC compliance costs, and precision dosing requirements reshape competitive positioning. Understanding these segment boundaries enables suppliers to allocate qualification investments toward the highest-margin specification windows.
Product Type:
Screw caps face the most acute substitution pressure from aluminum alternatives in premium wine applications, while dispensing architectures command technology premiums that insulate against material switching.
- Screw Caps:Compression-molded HDPE or injection-molded PP threaded closures with standardized pitch geometries dominate still water and edible oil packaging. Danone and Nestlé Waters France procurement teams prioritize these formats for AGEC lightweighting compliance, though Bordeaux and Champagne producers increasingly trial aluminum for premium positioning.
- Dispensing Caps:Precision-dose mechanisms with calibrated orifice control serve concentrated detergent and nasal pharmaceutical formulations. L'Oréal and LVMH specification teams value measured-flow architectures for personal care applications where dosing accuracy commands shelf price premiums.
- Flip Top Caps:Hinged polypropylene closures with living-hinge durability suit shampoo and conditioner bottles across mass-market cosmetics.
- Tamper Evident Caps:Break-band or shrink-sleeve integrated designs satisfy ANSM pharmaceutical integrity requirements and FSSAI-aligned food safety protocols.
Screw caps anchor the volume base while dispensing caps gain share at the steepest rate.
Material:
Cost tier stratification separates virgin commodity resins from certified recycled compounds that carry AGEC compliance premiums and biodegradable alternatives targeting retailer sustainability scorecards.
- Polypropylene:Homopolymer and copolymer grades deliver chemical resistance and living-hinge fatigue performance for flip-top personal care applications. Île-de-France compounders qualify rPP streams for Carrefour and E.Leclerc supply chains ahead of enforceable recycled-content deadlines.
- Polyethylene:HDPE compression-molding grades enable thin-wall tamper-evident band integration at reduced unit weight versus injection-molded alternatives. Berry Global and Silgan Holdings prioritize PE formulations for bottled water lightweighting roadmaps.
- Biodegradable Plastics:PLA and PHA certified under French retail protocols capture emerging positioning in single-use food service and premium organic product lines.
- Polyvinyl Chloride:Specialized grades persist in pharmaceutical blister lidding and certain chemical-resistant industrial closures despite environmental pressure.
Polypropylene captures the widest application breadth while biodegradable plastics expand most quickly from a smaller base.
End User:
Application-specific regulatory intensity creates divergent margin profiles, with pharmaceutical dosing precision commanding qualification premiums versus commodity food and beverage procurement.
- Food & Beverage:Still water, edible oil, and wine applications drive screw-cap volume with cost-dominated procurement. EPR fee optimization and AGEC recycled-content thresholds now influence supplier selection alongside unit economics.
- Pharmaceuticals:ANSM child-resistant and senior-friendly closure mandates extend mold validation timelines. Aptar Group precision-dose technology serves nasal and ophthalmic segments where measured dispensing is specified as drug-device combination.
- Cosmetics:L'Oréal and LVMH procurement teams bundle closure specification with shelf-ready sustainability scoring and traceability documentation depth.
- Household Products:Concentrated detergent refill formats require precision-dose closures that reduce packaging volume per use cycle.
Food and beverage anchors the volume base while pharmaceuticals gains share at the steepest rate.
Packaging Type:
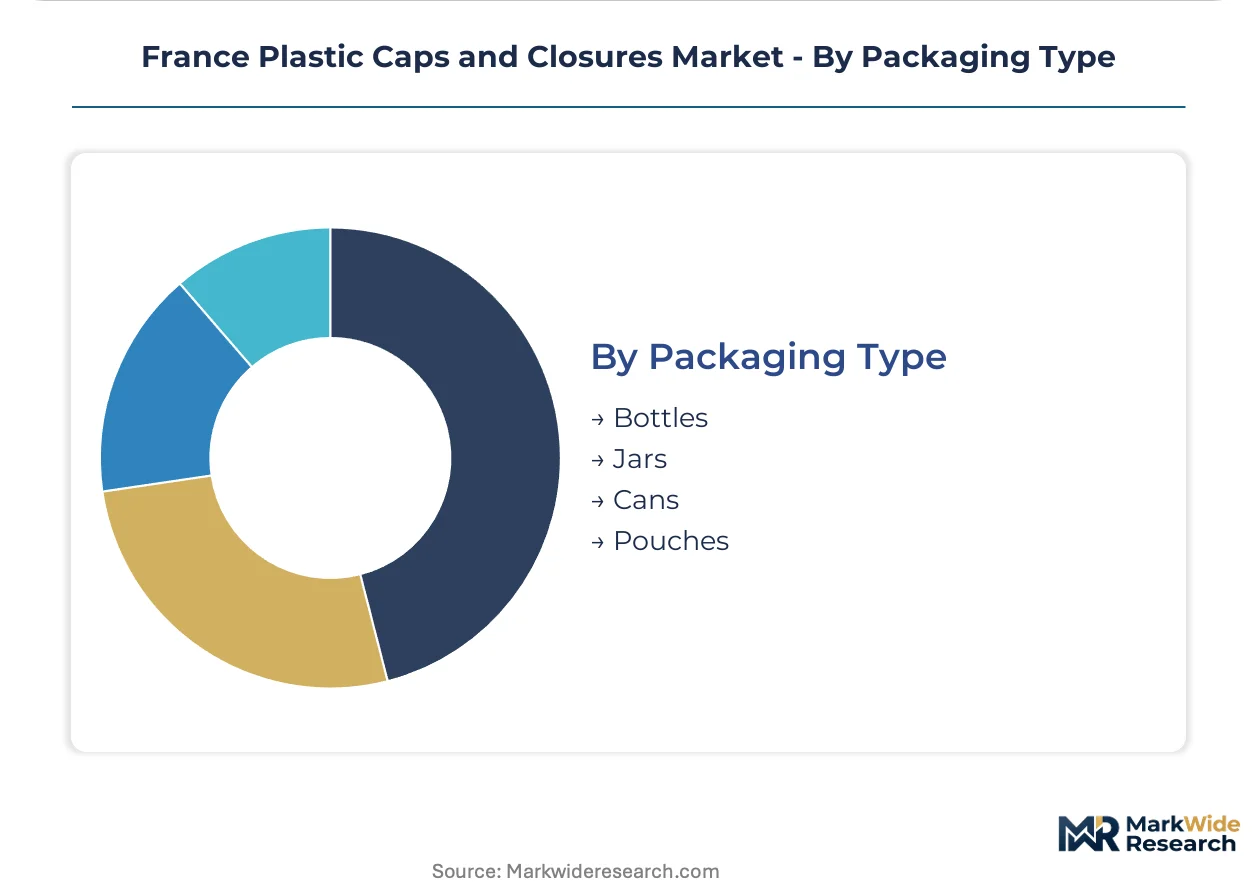
Container geometry dictates closure thread standard and torque specification, with bottle-neck finish standardization enabling scale economies that jar and pouch formats cannot replicate.
- Bottles:PCO 28 and 1881 neck finishes dominate French bottled water and carbonated soft drink lines. High-speed capping equipment investments lock in supplier relationships across Danone and Nestlé Waters France production networks.
- Jars:Wide-mouth polypropylene closures serve condiment and cosmetic cream applications where spoon or finger access is required.
- Cans:Plastic over-caps for aluminum beverage cans provide resealability in energy drink and ready-to-drink coffee segments.
- Pouches:Spout-fitment closures for flexible refill and food service formats represent a lower-volume, higher-complexity specification niche.
Bottles anchor the volume base while pouches gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Closure manufacturing concentrates in France's northern industrial corridor, where polymer compounding infrastructure and beverage bottling networks create procurement gravity for specialized suppliers.
Île-de-France
The Paris-region packaging cluster anchors French demand, with L'Oréal and LVMH headquarters driving premium cosmetic closure specifications. ANSM pharmaceutical standards govern child-resistant designs for prescription drug packaging. The Plaine Saint-Denis industrial zone hosts multiple injection molding facilities serving high-volume personal care applications.
Auvergne-Rhône-Alpes
Lyon's chemical engineering base supports rPP and rPET compound development for AGEC compliance. The region's polymer research institutes collaborate with closure manufacturers on recycled-content formulations. Saint-Étienne tooling shops supply precision molds for pharmaceutical dosing applications.
Provence-Alpes-Côte d'Azur
Nice and Marseille cosmetics laboratories demand precision-dispensing closures for premium skincare lines. The region's fragrance industry requires specialized orifice control for volatile formulations. Sophia Antipolis technology park hosts material science startups developing biodegradable alternatives.
Hauts-de-France
The Lille metropolitan area processes post-consumer plastic streams for rPET closure feedstock. AGEC collection infrastructure investments expand resin availability for packaging manufacturers. Dunkirk port facilities enable imported virgin resin distribution to northern compounding plants.
Nouvelle-Aquitaine
Bordeaux wine producers trial aluminum alternatives for premium bottling, pressuring plastic closure suppliers to demonstrate sustainability credentials. The region's agricultural packaging sector demands cost-optimized screw caps for edible oil applications. Biarritz-based startups pilot PLA-based closures for organic product lines.
France Plastic Caps and Closures Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where precision-dosing specialists command specification premiums against scale-driven commodity producers. The French market consolidates around multinational material science platforms with integrated recycling partnerships and mid-size regional compounders serving agile brand owners. Three archetypes dominate: multi-material platform operators, precision-dosing technology specialists, and recycled-content certification bundlers. Capacity expansion and strategic partnerships represent the dominant competitive moves, as suppliers secure compound qualification ahead of AGEC enforcement deadlines.
Among multi-material platform operators, Berry Global, Inc. and Silgan Holdings Inc. exemplify the integrated supply coordination archetype serving multinational pharmaceutical and beverage clients. Aptar Group occupies a distinct position within the precision-dosing specialist tier, anchoring technology-driven specification windows for nasal and ophthalmic drug delivery applications.
| Leading Market Players |
|---|
| Retal Industries Ltd |
| Bericap Holding GmbH |
| Berry Global, Inc. |
| Silgan Holdings Inc. |
| United Caps |
| Aptar Group |
| Jokey Group |
| Berlin Packaging |
| Guala Closures S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day compound qualification cycles concentrate pricing power among rPET and rPP suppliers with pre-qualified AGEC certification, while virgin-resin closure manufacturers absorb margin compression from recycled-content mandates. Inventory velocity at Île-de-France bottling facilities shapes procurement contract structures, locking in volume commitments ahead of enforceable decree deadlines.
Pricing Analysis
AGEC law dictates the pricing tier structure across the French closure market, separating certified recycled-content compounds from virgin-resin alternatives. Three-tier pricing stratifies by certification grade, volume scale, and traceability documentation depth. Cost compression in commodity screw caps intensifies because aluminum substitution trials in Bordeaux and Champagne redirect premium volume. Food and beverage procurement teams exhibit highest price sensitivity, while pharmaceutical dosing specialists accept technology premiums for ANSM-validated designs.
Supply Chain Analysis
Strategic stockpile preferences dominate rPP and rPET sourcing as post-consumer resin availability fluctuates with French collection infrastructure maturity. Supply concentrates in Germany, Belgium, and domestic Hauts-de-France compounding facilities. Raw material dependencies center on virgin polypropylene feedstock, post-consumer PET flake streams, and specialty additive packages for food-contact compliance. Single-source vulnerability runs through limited qualified rPP compounders serving Carrefour and E.Leclerc supply chains. Distribution feeds from northern industrial corridor polymer plants through Île-de-France packaging clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense imperative as aluminum closure trials in premium wine segments threaten plastic's established position. The structural response requires requalifying compound portfolios ahead of AGEC enforcement windows while demonstrating sustainability credentials that metal alternatives cannot match.
For Market Incumbents: Secure pre-qualified rPP and rPET compound supply through backward integration into Hauts-de-France recycling infrastructure or exclusive offtake agreements with certified compounders. Anchor pharmaceutical relationships by accelerating ANSM validation cycles for child-resistant designs before aluminum substitution pressure extends into drug packaging segments. For New Entrants and Emerging Players: AGEC compliance service gaps among mid-size French brand owners present white-space entry points where incumbents under-serve regulatory documentation and EPR fee management needs. Concentrated detergent refill formats offer the most penetrable application window, with precision-dose closure specifications exceeding commodity screw-cap capabilities. A bundled certification-and-traceability go-to-market angle differentiates against scale-driven commodity producers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because AGEC decree timelines will progressively tighten recycled-content thresholds, concentrating contract awards among compounders with integrated recycling partnerships and certified mass-balance accounting systems. Acquisition targets should display multi-material platform capabilities spanning virgin, recycled, and biodegradable compounds. The signal to watch is aluminum closure adoption rates in Champagne and Bordeaux premium segments crossing material-switching inflection thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| rPP/rPET Compound Qualification | Pre-positions suppliers ahead of AGEC enforceable deadlines for recycled-content mandates. |
| ANSM Certification Acceleration | Shortens mold validation timelines for child-resistant pharmaceutical closure designs. |
| Backward Integration into Recycling | Captures post-consumer resin supply through Hauts-de-France collection infrastructure investments. |
| Precision-Dose Technology Development | Opens specification windows in concentrated detergent and nasal pharmaceutical applications. |
| Biodegradable Compound Certification | Qualifies PLA and PHA alternatives under Carrefour and E.Leclerc sustainability protocols. |
Research Methodology
A standing panel of closure manufacturing plant managers, L'Oréal and LVMH procurement leads, ANSM regulatory affairs specialists, and Saint-Étienne tooling engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA REACH registration databases, French customs trade statistics, AGEC decree implementation timelines, and SEC filings of listed packaging multinationals. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled product type, material grade, end-use industry, and regional production hub dimensions. CAGRs were derived from segment-level growth trajectory analysis. Forecast inputs incorporated AGEC compliance cost curves, aluminum substitution elasticity in wine applications, and pharmaceutical dosing precision specification trends.
Forecasts assume regulatory continuity in AGEC circular economy implementation and ECHA REACH chemical registration regimes; material policy shifts would require re-modeling. Specific risk factors include rPP/rPET compound availability disruptions, aluminum closure technology breakthroughs, and ANSM validation protocol changes. Revision becomes warranted when aluminum substitution rates in premium wine segments cross material-switching thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Bag Closures Market
Caps and Closures
Smooth Hinge Caps and Closure Market
Caps and Closures
Screw Closure Market
Caps and Closures
Latin America Plastic Caps and Closure Market
Caps and Closures
Disc Top Caps Market
Caps and Closures
Colombia Plastic Caps and Closures Market
Caps and Closures
Resealable Closures and Spouts Packaging Market
Caps and Closures
Dispensing Spouts Market
Caps and Closures
China Plastic Caps and Closures Market
Caps and Closures
Molded Fiber Pulp Cap Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Germany Plastic Caps and Closures Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
Bar Top Corks Market
Caps and Closures
Cap Seals Market
Caps and Closures
PVC-Free Cap Liners Market