
 Global Hospital Supplies Market | 2026-2036
Global Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hospital Supplies Market Analysis
Ambulatory surgical centers is expanding as a procurement channel for single-use surgical drapes, sterilization wraps, and procedure kits. Johnson & Johnson leverages its Ethicon franchise to dominate advanced sutures and stapling systems across outpatient settings. Becton, Dickinson and Company anchors hospital medication delivery through its vascular access and infusion therapy portfolios. Cardinal Health, Inc. competes on distribution scale, controlling direct-to-hospital logistics networks that reduce inventory carrying costs for acute care facilities.
Hospital supplies encompass the disposable and reusable instruments, devices, and consumables required for patient diagnosis, treatment, and facility operations, typically manufactured from medical-grade polymers, stainless steel, or textile composites and subject to biocompatibility ISO 10993 and sterility assurance level SAL 10^-6 validation. Their primary purpose is to enable safe, standardized clinical workflows while minimizing cross-contamination risk across care settings. Surgical instruments and wound care supplies represent mature, high-volume segments where margin pools have compressed under group purchasing organization pressure. Infusion pumps and diagnostic equipment concentrate technology leadership premiums, with software-integrated models capturing higher service attach rates.
FDA 510(k) clearance pathways and EMA Medical Device Regulation conformity assessments shape product development timelines and market access costs for manufacturers seeking multi-jurisdiction placement. ISO 13485 quality management systems and WHO prequalification standards further filter supplier eligibility for institutional procurement tenders. Stakeholders must monitor how FDA's proposed reclassification of certain surgical gloves and evolving EU F-Gas Regulation phase-down schedules for sterilization gases reshape material substitution strategies and capital planning.
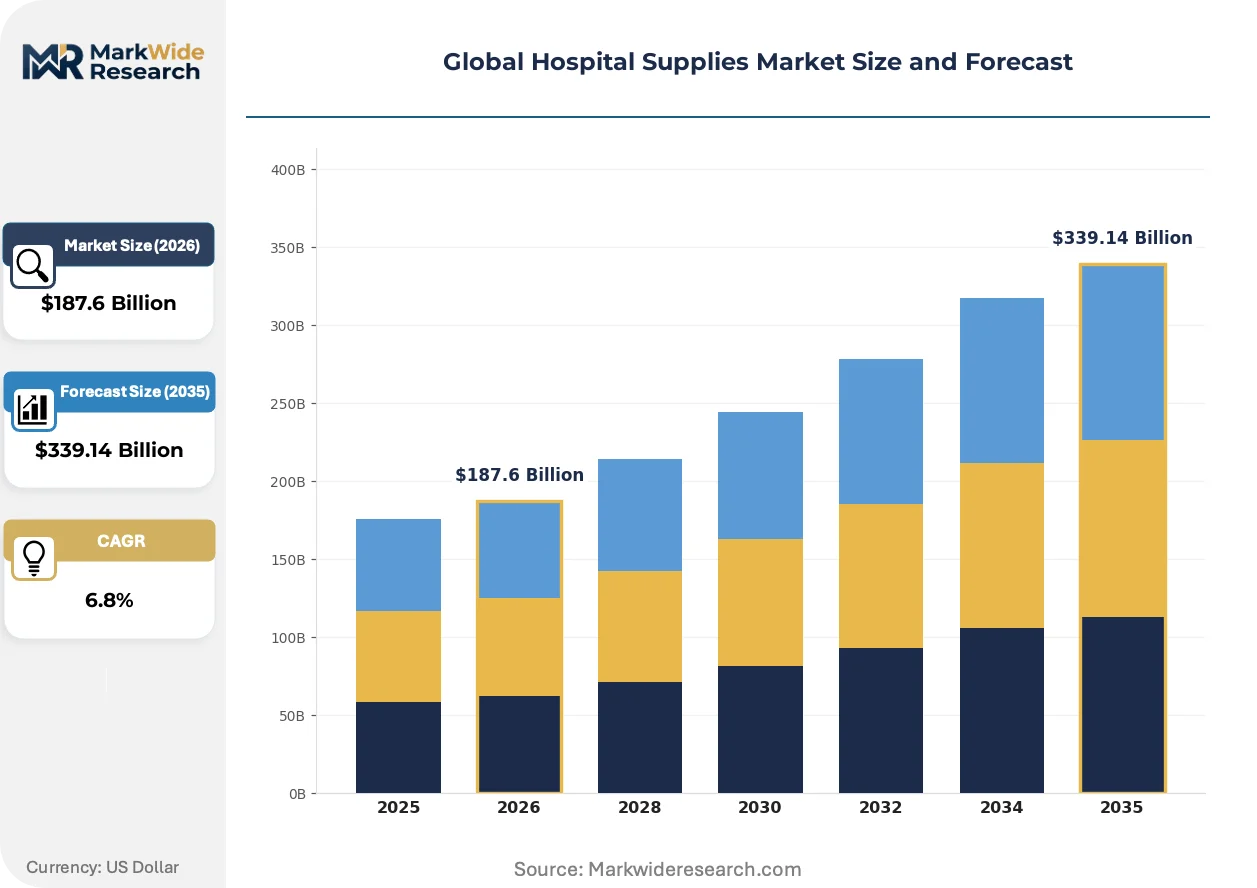
Market Dynamics
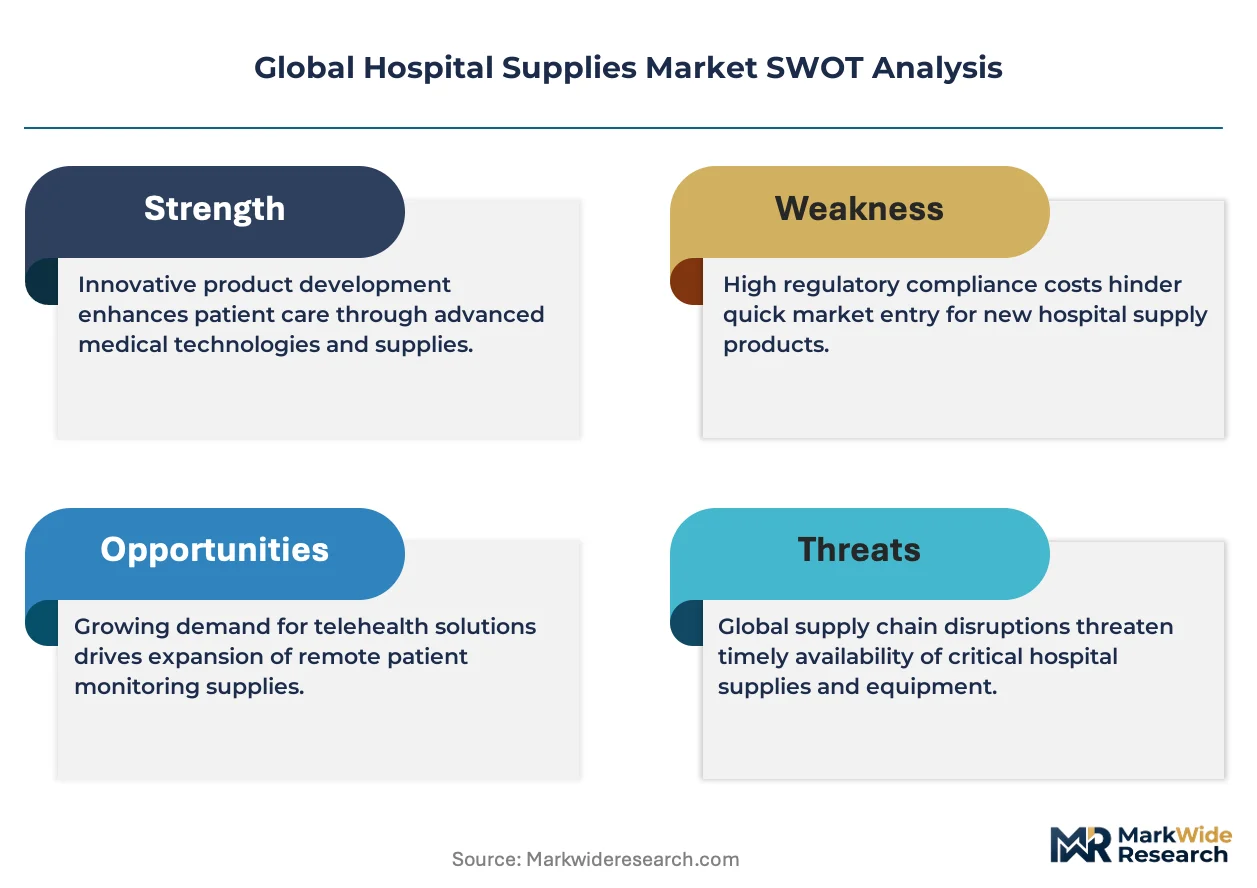
Group purchasing organizations are compressing margin pools across surgical consumables and standard instruments, forcing manufacturers to defend position through SKU rationalization and direct-to-hospital distribution investments rather than price competition alone.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient facilities in the United States are accelerating procurement of disposable procedure kits and sterilization wraps to support same-day discharge protocols.
- India's PLI scheme for medical devices:Production-linked incentives are attracting domestic manufacturing investment for syringes, catheters, and surgical gloves to reduce import dependency.
- FDA 510(k) pathway streamlining:Predicate device clearance mechanisms are shortening time-to-market for Class II infusion pumps and vascular access devices.
Market Restraints
- Ethylene oxide sterilization constraints:EPA emission regulations and EU F-Gas Regulation phase-down schedules are limiting capacity for medical-grade sterilization services.
- Polymer feedstock volatility:Medical-grade polypropylene and PVC resin prices fluctuate with petrochemical supply disruptions, squeezing converter margins on disposable products.
- Concentrated glove manufacturing:Malaysia and Thailand dominate nitrile and latex glove production, creating geographic single-point-of-failure exposure for hospital supply chains.
Strategic Opportunities
- Reusable instrument reprocessing:Central sterile processing departments in Germany and France are investing in automated washer-disinfector systems to offset single-use cost inflation.
- Software-integrated infusion systems:Smart pumps with dose error reduction software are unifying medication delivery with electronic health record interoperability.
- Brazil's SUS hospital modernization:Federal procurement tenders for public hospital infrastructure are opening volume contracts for diagnostic consumables and wound care products.
Industry Challenges
- ISO 13485 quality management certification:Small and mid-sized instrument manufacturers face 12-18 month audit timelines and documentation burdens to maintain EU MDR conformity.
- Sterile barrier packaging validation:Demonstrating SAL 10^-6 assurance across accelerated aging protocols requires specialized microbiology capabilities that concentrate among contract testing laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hospital Supplies Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $339.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Diagnostic Equipment, Wound Care Supplies, Infusion Pumps End User: Clinics, Rehabilitation Centers, Ambulatory Surgical Centers, Home Healthcare Delivery Mode: Direct Sales, Online Sales, Distributors, Wholesalers Application: Patient Monitoring, Infection Control, Surgery Assistance, Medical Training |
| Companies Covered | Medtronic plc, Johnson & Johnson, Boston Scientific Corporation, Stryker Corporation, Cardinal Health, Inc., Becton, Dickinson and Company, B. Braun Melsungen AG, 3M Company, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hospital Supplies Market Emerging Trajectories
Digital integration and material substitution are converging to redefine how hospitals source, track, and deploy clinical consumables across acute and ambulatory settings.
Smart inventory management systems embedding RFID and IoT sensors are unifying supply chain visibility with point-of-use consumption tracking. Academic medical centers in the United States are deploying these platforms to automate par-level replenishment and reduce nursing time spent on supply searches. The structural consequence is compressing distributor margins as hospitals gain direct negotiating leverage with manufacturers.
The EU Medical Device Regulation's enhanced clinical evidence requirements are extending technical documentation obligations for Class IIa and IIb surgical instruments. Manufacturers must now submit post-market surveillance data and periodic safety update reports that previously applied only to implantable devices. Wound closure and laparoscopic instrument portfolios face the steepest compliance cost increases, with some suppliers withdrawing lower-volume SKUs from the European market entirely.
Consolidated service agreements are replacing transactional purchase orders as the dominant contracting mechanism for diagnostic and therapeutic consumables. Integrated delivery networks in the United States are bundling device procurement with preventive maintenance and staff training under multi-year partnerships. This shift is most pronounced in cardiovascular catheterization and interventional radiology suites, where procedure volume guarantees anchor contract value.
Global Hospital Supplies Market Segmentation
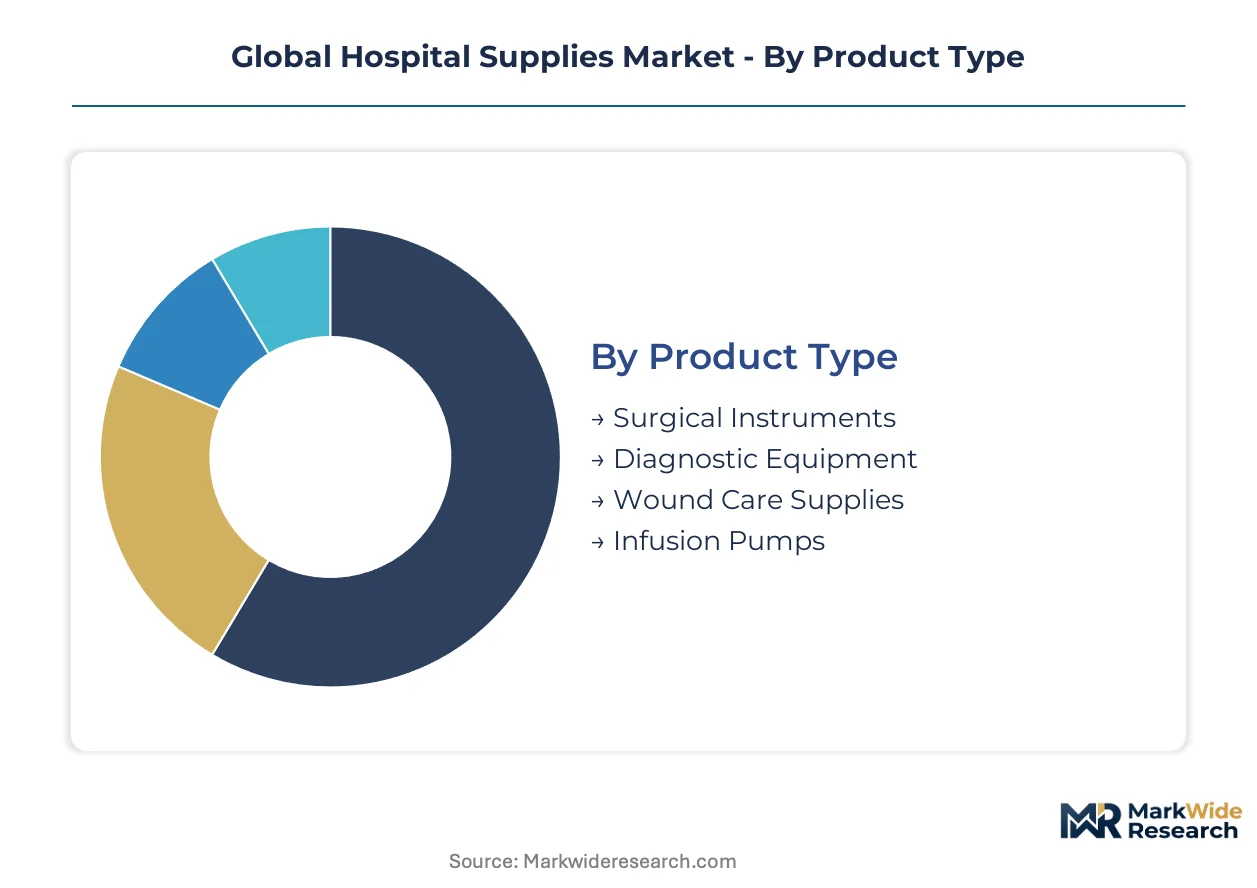
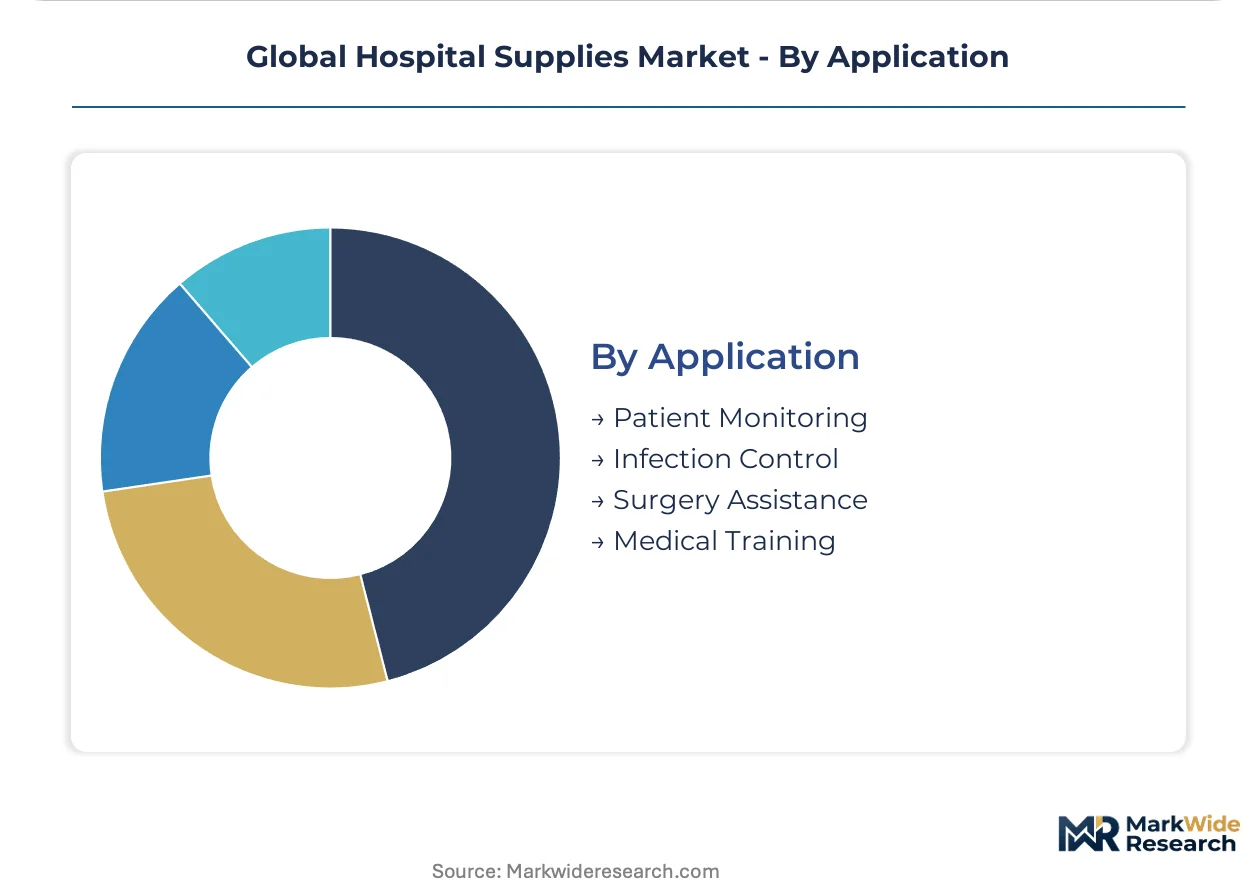
Hospital supplies segmentation reveals how regulatory pathways, procurement channels, and clinical settings fragment demand across distinct compliance and margin profiles. Manufacturers must align product portfolios with the specific certification tiers and distribution economics governing each category.
Product Type:
FDA 510(k) clearance dominates Class II surgical instruments and infusion pumps, while diagnostic equipment requiring premarket approval concentrates investment timelines among capital-intensive manufacturers.
- Surgical Instruments:Stainless steel and polymer-composite tools subject to ISO 13485 quality management and SAL 10^-6 sterility validation. Demand concentrates in ambulatory surgical centers across the United States, where same-day discharge protocols accelerate disposable kit procurement.
- Diagnostic Equipment:Software-integrated monitors and imaging peripherals requiring FDA premarket notification and EMA MDR technical documentation. Germany's university hospitals anchor European volume for advanced patient monitoring systems with EHR interoperability.
- Wound Care Supplies:Advanced dressings and negative pressure therapy devices meeting biocompatibility ISO 10993 standards.
- Infusion Pumps:Smart delivery systems with dose error reduction software facing tightened FDA cybersecurity guidance.
Leading the category by volume: Surgical Instruments. Growing fastest: Diagnostic Equipment.
End User:
Procurement authority varies sharply across settings, with group purchasing organizations dominating hospital networks while home healthcare relies on durable medical equipment suppliers and direct-to-patient channels.
- Ambulatory Surgical Centers:Outpatient facilities in India and the United States driving disposable procedure kit volumes through streamlined procurement workflows. India's PLI scheme for medical devices is attracting domestic manufacturing investment to serve this channel.
- Home Healthcare:Post-acute settings requiring portable infusion pumps and wound care systems with simplified sterilization protocols. Japan's aging population is expanding reimbursement for home-based monitoring equipment through METI-coordinated insurance frameworks.
- Clinics:Primary care facilities prioritizing cost-optimized diagnostic consumables.
- Rehabilitation Centers:Long-term care settings with extended device utilization cycles.
Volume concentrates with: Ambulatory Surgical Centers. Steepest expansion trajectory: Home Healthcare.
Delivery Mode:
Channel economics reflect inventory carrying cost trade-offs, with direct sales capturing high-value capital equipment and distributors defending position through last-mile logistics density.
- Distributors:Regional logistics networks controlling hospital inventory replenishment through vendor-managed inventory programs. Cardinal Health's direct-to-hospital infrastructure in the United States exemplifies scale advantages in acute care penetration.
- Direct Sales:Manufacturer-led contracting for infusion pumps and diagnostic suites with attached service agreements. Brazil's SUS hospital modernization tenders favor direct manufacturer engagement for volume diagnostic contracts.
- Online Sales:E-procurement platforms gaining traction among smaller clinics.
- Wholesalers:Bulk aggregation points for standard consumables with compressed margins.
Dominant by throughput: Distributors. Gaining share fastest: Direct Sales.
Application:
Clinical use cases determine sterility assurance requirements and software validation burdens, with infection control facing the steepest regulatory escalation across jurisdictions.
- Infection Control:Sterilization wraps, barrier garments, and surface disinfectants subject to EPA emission regulations and EU F-Gas phase-down constraints. Ethylene oxide sterilization capacity limitations in the United States are forcing material substitution toward hydrogen peroxide vapor alternatives.
- Surgery Assistance:Procedure-specific kits combining drapes, instruments, and suction systems. France's central sterile processing departments are investing in automated reprocessing to offset single-use cost inflation.
- Patient Monitoring:Continuous vital signs surveillance with interoperability mandates.
- Medical Training:Simulation supplies with reduced regulatory clearance requirements.
Fastest-growing application: Infection Control. Largest installed base: Surgery Assistance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of hospital supplies concentrates in Malaysia and Thailand for nitrile gloves, while consumption gravity shifts toward India and the United States where infrastructure investment and outpatient expansion accelerate procurement volumes.
United States
Ambulatory surgical centers in Texas and Florida are driving disposable procedure kit procurement as same-day discharge protocols expand. FDA 510(k) clearance pathways for Class II infusion pumps streamline market access for vascular access device manufacturers. The Minneapolis medical device cluster anchors domestic production of advanced surgical instruments and sterilization equipment.
Germany
University hospitals in Bavaria and North Rhine-Westphalia anchor European demand for patient monitoring systems with EHR interoperability requirements. EU MDR technical documentation obligations and ISO 13485 quality management certifications filter supplier eligibility for institutional tenders. The Tuttlingen surgical instrument cluster maintains specialized manufacturing capacity for precision stainless steel tools.
India
Government hospital infrastructure upgrades under the Ayushman Bharat scheme and medical tourism expansion in Chennai and Hyderabad accelerate volume procurement of syringes, catheters, and surgical gloves. CDSCO medical device rules and the PLI scheme for domestic manufacturing attract investment to reduce import dependency. The Tamil Nadu medical devices park near Chennai concentrates new production capacity for consumables.
Brazil
Federal procurement tenders through SUS hospital modernization programs open volume contracts for diagnostic consumables and wound care products in São Paulo and Minas Gerais. ANVISA medical device registration requirements shape product development timelines for manufacturers seeking market access. The São Paulo metropolitan cluster serves as the distribution hub for Latin American hospital supply chains.
Japan
Aging population demographics expand reimbursement for home-based monitoring equipment and portable infusion pumps through METI-coordinated insurance frameworks. PMDA quality management system requirements and JIS standards govern domestic procurement specifications. The Kanto region around Tokyo concentrates demand for advanced diagnostic equipment in academic medical centers.
Global Hospital Supplies Market Vendor Landscape
Top-tier vendors anchor premium technology segments, while mid-scale distributors and regional manufacturers compete on logistics density and cost-optimized consumables. The vendor base stratifies across three tiers: diversified healthcare conglomerates with full portfolio coverage, specialized instrument manufacturers with ISO 13485 certification depth, and distribution-focused intermediaries controlling hospital inventory replenishment. Consolidated service agreements and direct-to-hospital logistics investments represent the dominant competitive moves, displacing traditional transactional purchasing.
Among diversified healthcare conglomerates, Johnson & Johnson and Medtronic plc exemplify the integrated portfolio archetype spanning surgical instruments, wound closure, and advanced sterilization systems. Cardinal Health, Inc. occupies a position within the distribution-centric tier, leveraging direct-to-hospital infrastructure to reduce inventory carrying costs for acute care facilities. These three entities represent distinct strategic postures: technology leadership through R&D-intensive franchises, scale advantages in logistics networks, and hybrid models combining manufacturing with distribution control.
| Leading Market Players |
|---|
| Medtronic plc |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Stryker Corporation |
| Cardinal Health, Inc. |
| Becton, Dickinson and Company |
| B. Braun Melsungen AG |
| 3M Company |
| GE Healthcare |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up distributors controlling hospital logistics networks have consolidated procurement leverage, compressing manufacturer margins while concentrating pricing power among intermediaries with direct-to-facility inventory programs. This ownership pattern tightens payment terms on small instrument suppliers and accelerates SKU rationalization as scale-dependent players defend position through volume guarantees rather than product differentiation.
Pricing Analysis
Margin tightening in standard surgical consumables reflects group purchasing organization consolidation and ethylene oxide sterilization capacity constraints. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared devices with software integration from basic stainless steel instruments and unbranded disposable kits. Cost compression accelerates because Malaysian and Thai glove manufacturers face EPA emission compliance costs passed through to hospital buyers. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement rates, while academic medical centers prioritize interoperability premiums over unit cost.
Supply Chain Analysis
India's PLI scheme for medical devices and Brazil's local-content requirements in SUS tenders are reshaping sourcing patterns toward domestic manufacturing zones. Supply concentrates in Malaysia and Thailand for nitrile gloves, Germany for precision surgical instruments, and India for syringes and catheters. Raw material dependencies rest on medical-grade polypropylene resin, stainless steel surgical grades, and ethylene oxide sterilization gases. Single-source vulnerability runs through concentrated glove production regions exposed to climate disruption. Distribution runs through Cardinal Health and regional logistics networks with vendor-managed inventory programs anchoring hospital replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital supplies is becoming a vertical-integration race as manufacturers pursue backward control over sterilization capacity to offset ethylene oxide regulatory constraints and secure supply continuity.
For Market Incumbents: Anticipate FDA cybersecurity guidance tightening on infusion pumps by accelerating software companion development and dose error reduction system validation. Defend position through captive sterilization facility investments in hydrogen peroxide vapor alternatives, offsetting ethylene oxide capacity shortages. Reinforce GPO contract anchoring with multi-year service bundling that attaches preventive maintenance to device procurement. For New Entrants and Emerging Players: Enter via India's PLI scheme manufacturing zones to serve domestic hospital infrastructure upgrades and medical tourism corridors in Chennai and Hyderabad. Target diagnostic consumables for Brazil's SUS modernization tenders where ANVISA registration requirements filter out established competitors lacking local presence. Pursue direct-to-hospital logistics partnerships bypassing distributor margin layers. For Investors and Strategic Acquirers: FDA's proposed reclassification of surgical gloves is the leading indicator that sterility assurance validation capabilities will concentrate among contract testing laboratories with specialized microbiology infrastructure. Five-to-ten year viability favors mid-scale instrument manufacturers with ISO 13485 certification depth and automated reprocessing technology portfolios. Watch for EU MDR technical documentation withdrawal events signaling SKU rationalization opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessments filter supplier eligibility for institutional tenders in Germany and France. |
| Hospital System Partnership | Integrated delivery networks bundle device procurement with staff training under multi-year service agreements. |
| Software Companion Development | Smart pumps with EHR interoperability capture higher service attach rates in academic medical centers. |
| Reimbursement Strategy | METI-coordinated insurance frameworks in Japan expand home healthcare equipment coverage for aging populations. |
| Backward Integration into Sterilization | Automated washer-disinfector investments offset single-use cost inflation in German central sterile processing departments. |
Methodological Framework
Document review covered FDA 510(k) clearance databases, EMA MDR technical documentation filings, and hospital procurement contract registries, complemented by interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and sterilization service operators. Secondary validation drew from CDSCO medical device rules, ANVISA registration filings, and CMS Medicare reimbursement schedules. Bottom-up demand modeling triangulated against top-down market sizing across product categories.
Market value outputs were derived through segmentation across surgical instruments, diagnostic equipment, wound care supplies, and infusion pumps, with end-user splits between ambulatory surgical centers, home healthcare, clinics, and rehabilitation settings. CAGRs were calculated from installed base growth, replacement cycles, and procedure volume expansion across the analysis window. Forecast inputs incorporated ethylene oxide sterilization capacity constraints, polymer feedstock price volatility, and regulatory pathway streamlining effects.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EPA emission regulation acceleration or EU F-Gas phase-down schedule advancement. Projections reflect assumptions on outpatient migration rates, domestic manufacturing incentive effectiveness, and sterility assurance technology substitution timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
External Nasal Dilator and Nasal Strip Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Global Hot and Cold Therapy Packs Market
Medical Supplies
UAE Hospital Supplies Market
Medical Supplies
Global Adhesive Bandages Market
Medical Supplies
Disposable Masks Market
Medical Supplies
North America Healthcare Packaging Market
Medical Supplies
Port Access Needles Market
Medical Supplies
US Ostomy Care and Accessories Market
Medical Supplies
Europe Surgical Glue Market
Medical Supplies
Venipuncture Needles and Syringes Market
Medical Supplies
GCC Intravenous Solutions Market
Medical Supplies
Nasal Oxygen Cannula Market
Medical Supplies
Scintillation Vials Market
Medical Supplies
Medical Disposables Market
Medical Supplies
Europe Custom Procedure Kits Market