
 Evidence Collection Tubes Market | 2026-2036
Evidence Collection Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Evidence Collection Tubes Market Foresight
REACH compliance and the EU Green Deal are restructuring material specifications for evidence collection tubes across European procurement channels. BD sustains dominant manufacturing scale in glass and plastic tube categories through backward integration into resin and borosilicate supply chains. Thermo Fisher Scientific leverages forensic-specific R&D intensity to differentiate its specialty tube portfolios for DNA preservation applications. Greiner Bio-One International GmbH anchors European distribution through direct hospital and laboratory contracts in Germany and Austria.
Evidence collection tubes are sterile, tamper-evident containers manufactured from borosilicate glass or medical-grade polymers such as polypropylene and polyethylene, designed to preserve biological and chemical specimens under controlled temperature and contamination barriers for forensic admissibility. Product type segmentation shows plastic tubes occupying the volume lead due to cost efficiency and breakage resistance, while specialty tubes command margin pools through additive coatings and temperature-stabilizing substrates. End-user segmentation reveals forensic laboratories as the fastest-growing category, driven by backlog reduction mandates and federal infrastructure grants in multiple jurisdictions.
FDA quality system regulations, ISO 18385 forensic DNA contamination control standards, and CE marking under the EU Medical Device Regulation collectively govern product approval, manufacturing traceability, and cross-border market access for evidence tube suppliers. The EPA and OSHA intersect with this market through biohazard handling and worker exposure protocols during tube fabrication and field deployment. Stakeholders must monitor evolving chain-of-custody digitization requirements and material sustainability mandates as procurement criteria harden across public forensic agencies.
Market Dynamics
Forensic laboratories across Germany, the United States, and Japan are modernizing infrastructure under federal backlog reduction mandates, creating concentrated procurement pull for tamper-evident tube systems that satisfy chain-of-custody digitization requirements.
Growth Catalysts
- EU AI Act compliance:Automated evidence tracking mandates are accelerating replacement cycles for legacy tube inventories in European forensic agencies.
- Borosilicate glass substitution:Medical-grade polypropylene formulations are capturing volume from breakage-prone glass in field collection applications.
- Federal infrastructure grants:United States Department of Justice funding streams are expanding certified laboratory capacity in state and municipal jurisdictions.
Market Restraints
- Resin price volatility:Polypropylene feedstock costs fluctuate with crude oil benchmarks, compressing margin predictability for plastic tube manufacturers.
- German supply concentration:Borosilicate glass production clusters in Saxony and Thuringia create geographic single-point vulnerability for premium tube sourcing.
- ISO 18385 certification friction:Forensic DNA contamination control standards impose 18-24 month validation timelines for new production lines.
Strategic Opportunities
- Japan cold-chain expansion:Temperature-stabilized substrates for DNA preservation remain underdeployed in prefectural police laboratories outside Tokyo and Osaka.
- EU Green Deal material mandates:Bio-based polymer specifications in public procurement tenders favor suppliers with renewable feedstock certifications.
- Blockchain-integrated custody systems:Convergence of RFID tagging with distributed ledger verification opens premium pricing for tamper-evident tube vendors.
Industry Challenges
- Forensic technician certification gaps:Proper handling of additive-coated specialty tubes requires training programs that lag behind product rollout schedules.
- Legacy LIMS integration:Digitized chain-of-custody protocols face interoperability failures with 1990s-era laboratory information management systems in underfunded agencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Evidence Collection Tubes Market |
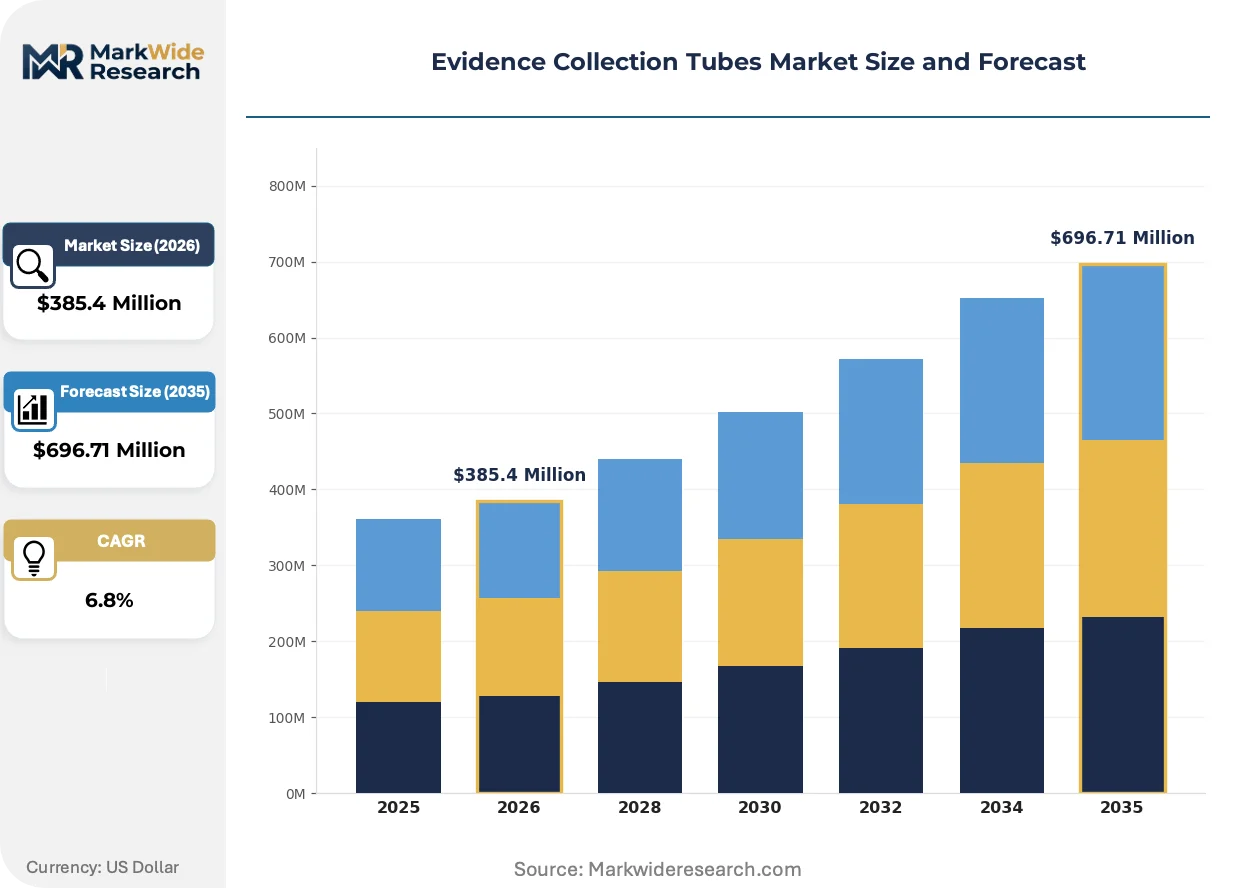
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Tubes, Glass Tubes, Tube Kits, Specialty Tubes End User: Law Enforcement, Forensic Laboratories, Hospitals, Private Investigators Application: Biological Samples, Chemical Analyzers, Crime Scene Investigations, Chain of Custody Distribution Channel: Online Sales, Direct Sales, Medical Supply Stores, Distributors |
| Companies Covered | Thermo Fisher Scientific Inc., BD (Becton, Dickinson and Company), Greiner Bio-One International GmbH, Cardinal Health, VWR International LLC, Medtronic PLC, LabCorp, SteriPack, Kangjian Medic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Evidence Collection Tubes Market Shifts & Advancements
Active digitization of evidence custody records is compressing replacement cycles for analog-compatible tube systems while reshaping supplier qualification criteria across public procurement channels.
RFID-embedded tamper-evident seals are consolidating field-to-laboratory traceability into unified data architectures. State police departments in the United States are piloting these systems at scale. The technology is consolidating previously fragmented custody documentation into single-source audit trails that satisfy judicial scrutiny standards.
REACH substance restrictions are eliminating certain phthalate plasticizers from European-sourced polymer formulations. Manufacturers must reformulate medical-grade polyethylene compounds to maintain flexibility without restricted additives. Forensic laboratories in Germany and Austria are accelerating supplier audits to verify compliance ahead of enforcement deadlines.
Consolidated purchasing cooperatives are displacing individual agency procurement for high-volume tube categories. Multi-jurisdictional contracts in the United States aggregate demand from county and state laboratories into single tender processes. This concentration favors suppliers with FDA quality system documentation and ISO 18385 certification already on file.
Evidence Collection Tubes Market Segmentation
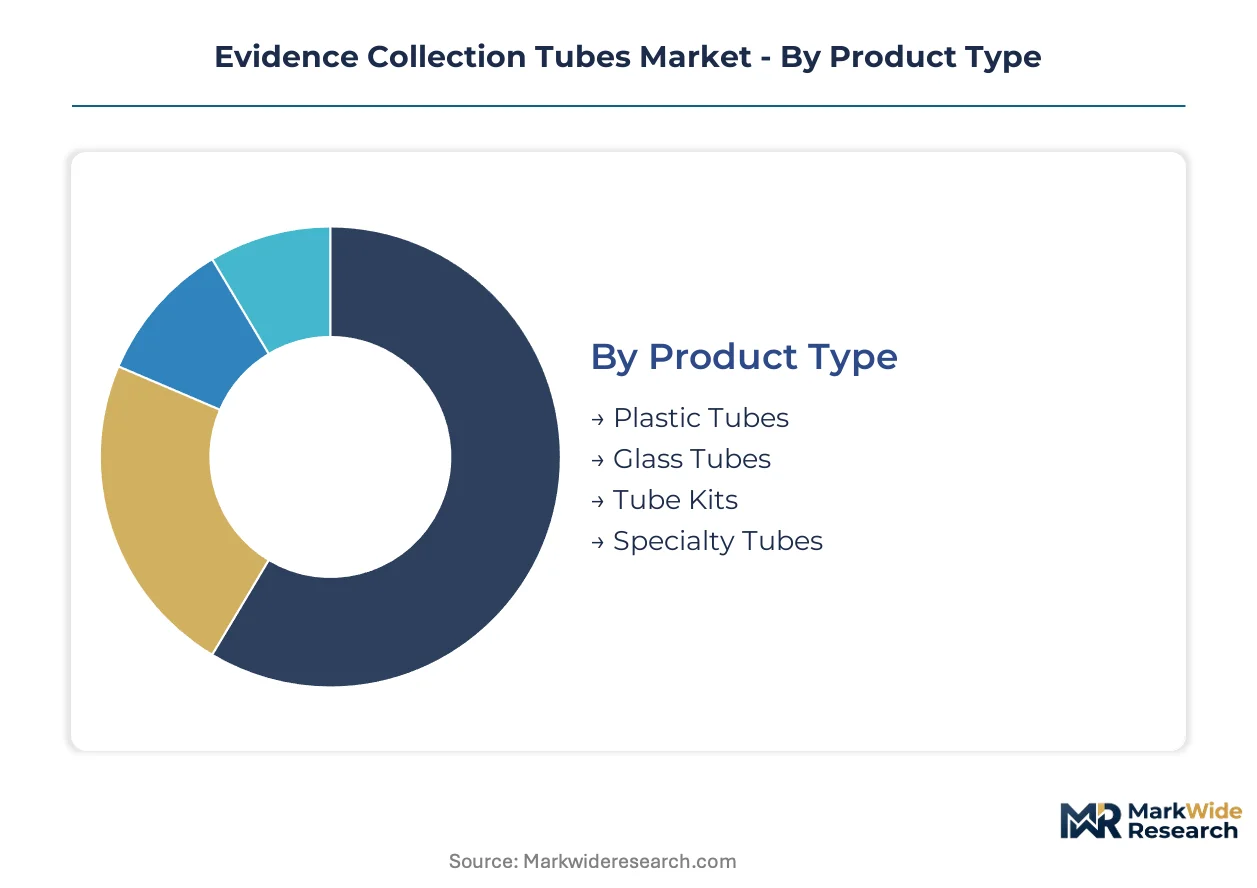
Procurement patterns for evidence collection tubes diverge sharply across institutional buyers, with forensic laboratories prioritizing certification depth while law enforcement agencies optimize for field durability and unit economics. Understanding these segment-specific purchasing logics enables suppliers to align R&D investment with the highest-margin demand pools.
Product Type:
Material selection separates buyers by breakage tolerance, temperature stability requirements, and chain-of-custody digitization readiness.
- Plastic Tubes:Medical-grade polypropylene and polyethylene formulations dominate field collection due to shatter resistance and lighter logistics burden. Demand concentrates in municipal police departments across the United States where officer safety protocols mandate breakage-proof containers for roadside evidence gathering.
- Glass Tubes:Borosilicate construction preserves chemical inertness for volatile compound analysis and long-term DNA archival. German federal forensic institutes specify glass for sexual assault kit backlogs where judicial admissibility standards require demonstrable contamination barriers.
- Tube Kits:Pre-configured collections with swabs, labels, and temperature indicators accelerate training for agencies with high technician turnover.
- Specialty Tubes:Additive-coated substrates with stabilizing matrices serve toxicology reference laboratories requiring metabolite preservation across extended storage windows.
Volume sits with plastic tubes; growth tilts toward specialty tubes.
End User:
Institutional sophistication determines specification stringency and contract consolidation patterns.
- Forensic Laboratories:ISO 18385-certified facilities drive premium tube adoption through federal backlog reduction grants in the United States and Japan. These buyers aggregate multi-year supply agreements that lock in pricing against resin volatility.
- Law Enforcement:Patrol divisions and detective bureaus prioritize tamper-evident seals and RFID compatibility over chemical specifications. Japanese prefectural police outside major metropolitan areas represent underdeployed demand for cold-chain integrated systems.
- Hospitals:Emergency departments and sexual assault nurse examiner programs require tubes bridging clinical sterility standards with forensic chain-of-custody protocols.
- Private Investigators:Individual practitioners and small agencies purchase through retail medical supply channels with minimal volume concentration.
Forensic laboratories command margin; law enforcement delivers volume scale.
Application:
Specimen chemistry dictates barrier properties, temperature regimes, and documentation rigor.
- Biological Samples:DNA, blood, and tissue preservation demands sterile interior surfaces and nucleic acid stabilizers. United States Department of Justice infrastructure grants are expanding certified laboratory capacity for sexual assault kit processing.
- Chain of Custody:Tamper-evident engineering and digitized tracking interfaces satisfy judicial scrutiny standards. EU AI Act compliance mandates are accelerating replacement cycles for analog-compatible tube inventories across European forensic agencies.
- Crime Scene Investigations:Field-deployable tubes balance contamination control with rapid sealing mechanisms for trace evidence collection.
- Chemical Analyzers:Volatile organic compound preservation requires inert gas flushing and specialized septum closures for arson and toxicology applications.
Biological samples anchor procurement volumes; chain-of-custody digitization is climbing fastest.
Distribution Channel:
Channel selection reflects buyer scale, urgency requirements, and technical specification complexity.
- Direct Sales:National forensic institutes and consolidated purchasing cooperatives negotiate multi-jurisdictional contracts with embedded certification documentation. United States county laboratory aggregations favor suppliers with FDA quality system and ISO 18385 files already established.
- Distributors:Regional medical supply networks serve mid-sized police departments and hospital systems requiring mixed-product procurement efficiency.
- Online Sales:E-commerce platforms capture small agency and individual practitioner demand with standardized SKUs and rapid fulfillment.
- Medical Supply Stores:Brick-and-mortar retail serves emergency replenishment and training program procurement with minimal technical consultation.
Direct sales capture value; distributors extend geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of borosilicate glass and medical-grade polymers clusters in Germany and the United States, while procurement demand concentrates in forensic modernization programs across Japan and European federal agencies. This geographic split shapes logistics networks and certification requirements for tube suppliers.
United States
Department of Justice infrastructure grants are expanding certified laboratory capacity in state and municipal jurisdictions, creating concentrated procurement pull for tamper-evident systems. FDA quality system regulations and ISO 18385 forensic DNA contamination standards govern product approval and manufacturing traceability. Federal backlog reduction mandates in Texas and California are accelerating replacement cycles for legacy tube inventories.
Germany
German federal forensic institutes specify borosilicate glass for sexual assault kit backlogs where judicial admissibility standards require demonstrable contamination barriers. REACH compliance and the EU Green Deal are restructuring material specifications across European procurement channels. Production clusters in Saxony and Thuringia supply premium glass tubes, though this concentration creates geographic single-point vulnerability.
Japan
Prefectural police laboratories outside Tokyo and Osaka represent underdeployed demand for cold-chain integrated systems and temperature-stabilized substrates. METI standards and forensic infrastructure modernization programs are driving digitization requirements. Kansai region laboratories are piloting RFID-embedded tamper-evident seals for field-to-laboratory traceability.
United Kingdom
Consolidated purchasing cooperatives are displacing individual agency procurement for high-volume tube categories across county forensic services. CE marking under the EU Medical Device Regulation and post-Brexit UKCA marking requirements create dual compliance pathways. London and Southeast England anchor demand from national forensic institutes and hospital-based sexual assault examiner programs.
France
ANSM oversight intersects with forensic evidence handling protocols through biohazard containment and sterility validation requirements. EU AI Act compliance mandates are accelerating replacement cycles for analog-compatible tube inventories in national forensic agencies. Paris-region laboratories are scaling procurement of digitized chain-of-custody systems under federal modernization budgets.
Evidence Collection Tubes Market Competitive Landscape
The competitive structure tilts toward diversified life science conglomerates with backward integration into resin and glass supply chains. Three to four manufacturers capture the majority of institutional contracts through FDA quality system documentation and ISO 18385 certification files. Strategic archetypes include scale-driven resin compounders, forensic-specialist R&D houses, and European distribution anchors with direct laboratory contracts. Dominant competitive moves encompass multi-jurisdictional tender aggregation and specialty coating technology licensing.
Among diversified laboratory supply conglomerates, Thermo Fisher Scientific Inc. and BD (Becton, Dickinson and Company) exemplify the scale-driven archetype through captive control over borosilicate and polymer feedstocks. Greiner Bio-One International GmbH occupies a position within the European distribution-focused tier, anchoring hospital and laboratory contracts in German-speaking markets. These three entities represent the concentration of manufacturing scale and certification depth that public procurement channels favor for multi-year supply agreements.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| BD (Becton, Dickinson and Company) |
| Greiner Bio-One International GmbH |
| Cardinal Health |
| VWR International LLC |
| Medtronic PLC |
| LabCorp |
| SteriPack |
| Kangjian Medic |
| Others |
Supply & Pricing Matrix
Consolidated purchasing cooperatives in the United States and European federal forensic agencies command contract-based long-term offtake pricing that compresses margin pools for mid-tier suppliers lacking ISO 18385 certification depth. This buyer concentration forces pricing stratification across premium certified, standard compliant, and economy uncoated tiers.
Pricing Analysis
Margin tightening in standard-grade plastic tubes reflects polypropylene feedstock volatility tied to crude oil benchmarks. Three-tier pricing structure across premium certified, standard compliant, and economy field-grade levels separates buyers by contamination control requirements and chain-of-custody digitization readiness. Price differentiation traces to ISO 18385 certification depth and FDA quality system documentation status. Municipal police departments exhibit highest price sensitivity; German federal forensic institutes demonstrate lowest sensitivity due to judicial admissibility mandates.
Supply Chain Analysis
Single-source vulnerability sits with borosilicate glass production clusters in Saxony and Thuringia, Germany. Manufacturing draws from medical-grade polypropylene feedstocks in the United States, borosilicate glass in Germany, and specialty additive coatings in Japan. Supply chain risk centers on geographic concentration of premium glass tube sourcing. Distribution runs through direct sales to national forensic institutes, regional medical supply distributors, and consolidated purchasing cooperatives aggregating multi-jurisdictional demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over resin and borosilicate supply chains determines procurement qualification for multi-year federal contracts.
For Market Incumbents: Deploy certification depth as a moat by accelerating ISO 18385 validation timelines for additive-coated specialty tube lines before EU AI Act enforcement hardens. Lock in multi-jurisdictional tender aggregation through pre-established FDA quality system files that underfunded agencies cannot replicate. Consolidate position against emerging bio-based polymer specialists by backward integration into renewable feedstock certifications ahead of EU Green Deal procurement mandates. For New Entrants and Emerging Players: The price-point gap between RFID-embedded premium systems and analog-compatible economy tubes offers entry traction for mid-tier digitization vendors. Prefectural police laboratories in Japan outside Tokyo and Osaka represent the most penetrable geography for temperature-stabilized substrate deployment. Pursue white-label partnerships with existing distributors serving hospital-based sexual assault nurse examiner programs to bypass direct certification barriers. For Investors and Strategic Acquirers: The window for entry favors forensic-specialist R&D houses with captive coating technology and established CE marking files. Long-term viability hinges on convergence with blockchain-integrated custody systems and cold-chain logistics platforms. Watch for inflection when federal backlog reduction grants in the United States and Japan accelerate replacement cycles for legacy tube inventories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | BD's captive polypropylene production secures margin stability against oil-linked feedstock volatility. |
| ISO 18385 Certification Acceleration | Thermo Fisher Scientific's forensic DNA contamination control depth locks in German federal institute contracts. |
| RFID-Embedded Seal Development | State police departments in Texas and California pilot unified field-to-laboratory traceability architectures. |
| Bio-Based Polymer Reformulation | REACH compliance and EU Green Deal mandates force elimination of restricted phthalate plasticizers by enforcement deadlines. |
| Multi-Jurisdictional Tender Aggregation | United States county laboratory cooperatives concentrate demand with suppliers holding pre-filed FDA documentation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with forensic laboratory directors, procurement officers at consolidated purchasing cooperatives, regulatory affairs specialists, and distribution channel managers combined with secondary validation from FDA 510(k) filings, EPA biohazard handling protocols, and EU Medical Device Regulation submission databases. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from production capacity disclosures.
Granularity-level modeling operated at product type, end-user institution, and application chemistry dimensions across the analysis window. Segmentation by material substrate, certification tier, and chain-of-custody digitization readiness shaped volume and value outputs. CAGRs derived from trend extrapolation of federal infrastructure grant disbursements, backlog reduction mandate timelines, and replacement cycle compression from EU AI Act compliance requirements.
Underlying measurement precision varies by segment; forensic laboratory procurement carries tighter precision than private investigator retail channels due to contract visibility. Forecasts reflect assumptions about grant continuity, regulatory enforcement timing, and resin price stabilization that could shift materially. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Hemodialysis Consumables Market
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
Global Syringe Market
Medical Supplies
Cosmetic Pipette Market
Medical Supplies
Disposable Hospital Supplies Market
Medical Supplies
Safety Needles Market
Medical Supplies
Cerumen Removal Market
Medical Supplies
Global Medical Waste Containers Market
Medical Supplies
Disposable Lead Wires Market
Medical Supplies
Italy Hospital Supplies Market
Medical Supplies
Asia-Pacific Human Fibrin Glue Market
Medical Supplies
Global Surgical Kits Market
Medical Supplies
Pressure Monitoring Extension Tubing Sets Market
Medical Supplies
Measured Volume Burette Set Market
Medical Supplies
India Hospital Supplies Market
Medical Supplies
Histology and Cytology Consumables Supplies Market