
 Cryoboxes Market | 2026-2036
Cryoboxes Market Size, Share, and Industry Trends Forecast 2026-2036
Cryoboxes Market Outlook
Modular cryobox bundling with color-coded cap inserts and rack-compatible footprints is expanding buyer choice in biobanking procurement. Thermo Fisher Scientific leverages its cold-chain logistics heritage to dominate integrated storage workflows. Greiner Bio-One anchors European supply through ISO-compliant polycarbonate manufacturing. Eppendorf differentiates via precision-molded grid systems that reduce sample retrieval errors.
Cryoboxes are rigid, thermally insulated containers engineered from polycarbonate, aluminum, or composite materials to maintain ultra-low temperatures between minus 150 and minus 196 degrees Celsius for biological specimen preservation. Their primary purpose is to organize vials within liquid nitrogen dewars or mechanical freezers while preventing thermal shock during retrieval. Storage cryoboxes represent the mature revenue base, while transport cryoboxes are gaining share as cell-and-gene therapy logistics expand beyond fixed-site biobanks. Polycarbonate material grades command premium positioning due to transparency and autoclave resilience, whereas aluminum variants compete on thermal conductivity in liquid nitrogen immersion protocols.
The FDA enforces cGMP and 21 CFR Part 11 standards that mandate lot traceability and validation documentation for cryogenic storage accessories used in clinical trials. ISO 20387 biobanking standards and the EU MDR framework are converging to require documented thermal performance and material biocompatibility for cryoboxes entering regulated European workflows. Stakeholders must monitor evolving cell-therapy logistics requirements and preemptive compliance investments ahead of anticipated harmonization between FDA and EMA cold-chain guidance.
Market Dynamics
The convergence of cell-and-gene therapy commercialization with FDA 21 CFR Part 11 traceability mandates is compressing procurement cycles for validated cryogenic storage systems. Biobanks and CDMOs now demand pre-qualified cryobox configurations that integrate directly with laboratory information management systems.
Growth Catalysts
- Biobanking infrastructure expansion:Federal initiatives in the United States and national precision medicine programs are funding ultra-low temperature storage capacity at research medical centers.
- ISO 20387 standardization:Biobanks pursuing accreditation are replacing legacy containers with thermally validated, barcode-ready cryobox systems to satisfy audit requirements.
- Cell therapy logistics scaling:Autologous and allogeneic therapy developers require transport-grade cryoboxes that maintain chain-of-custody documentation across multi-site manufacturing networks.
Market Restraints
- Polycarbonate resin cost volatility:Medical-grade polymer feedstock prices fluctuate with petrochemical markets, squeezing margins for transparent cryobox manufacturers.
- Supply concentration in German precision molding:A limited base of ISO-certified polycarbonate processors creates bottleneck risk for European biobank procurement.
- Liquid nitrogen infrastructure dependency:Mechanical freezer alternatives cannot replicate minus 196 degrees Celsius immersion protocols required for long-term stem cell viability.
Strategic Opportunities
- Indian biobanking buildout:The CDSCO's expanding clinical trial oversight and the Department of Biotechnology's biorepository investments are creating demand for validated cold-chain accessories.
- RFID-integrated traceability:Converging wireless sensing with cryogenic-compatible substrates enables real-time location and temperature logging without manual barcode scanning.
- Direct-to-lab distribution:Manufacturers are bypassing general laboratory distributors to establish validated supply agreements with cell therapy CDMOs.
Industry Challenges
- Cryogenic materials engineering talent scarcity:Few polymer scientists possess expertise in minus 150 degrees Celsius substrate behavior and autoclave sterilization compatibility.
- FDA validation documentation burden:21 CFR Part 11 compliance requires extensive IQ/OQ/PQ protocols that extend sales cycles by 6-12 months for new cryobox configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryoboxes Market |
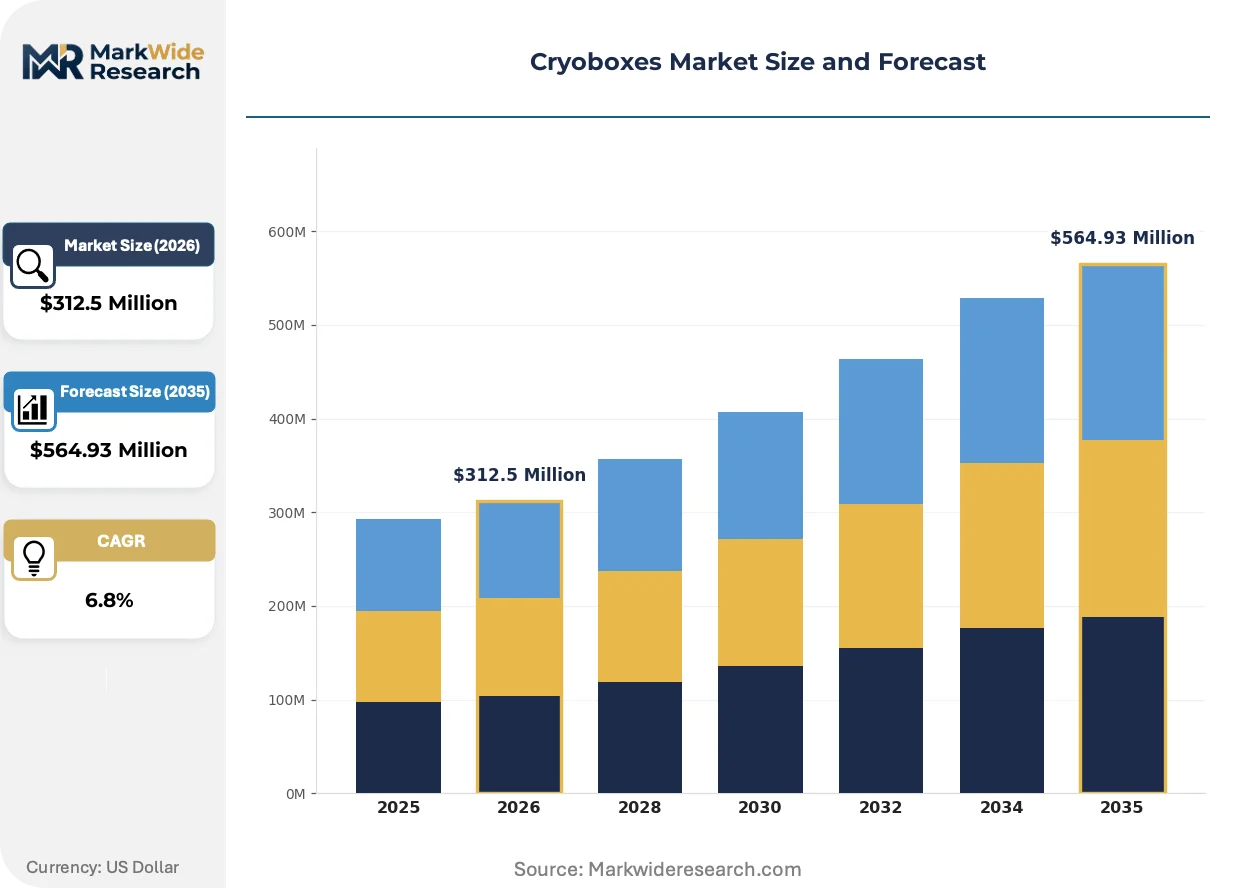
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage Cryoboxes, Transport Cryoboxes, Liquid Nitrogen Cryoboxes, Custom Cryoboxes Material: Polycarbonate, Aluminum, Steel, Composite Materials Capacity: Small, Medium, Large, Extra Large End User: Biobanks, Pharmaceutical Companies, Research Laboratories, Healthcare Institutions |
| Companies Covered | VWR International, Greiner Bio-One, Thermo Fisher Scientific, Micronic, Argos Technologies, Eppendorf, Biologix Group, DWK Life Sciences, Corning Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryoboxes Market Strategic Shifts
Digital traceability and modular storage architectures are displacing static, single-purpose cryobox designs across regulated biobanking workflows. Manufacturers are embedding sensing layers and reconfigurable grid geometries to satisfy divergent end-use requirements.
Grid-adaptable polycarbonate cryoboxes with removable dividers are modularizing storage system design. Cell therapy manufacturers are adopting these configurations to accommodate varying vial diameters across autologous patient batches. This flexibility is modularizing procurement decisions, allowing facilities to standardize on fewer SKUs while supporting diverse sample types.
The FDA's 21 CFR Part 11 electronic records requirements are mandating machine-readable traceability for temperature-sensitive storage accessories. Biobanks must now demonstrate lot-level audit trails for cryoboxes used in clinical trial specimen storage. Pre-validated, barcode-integrated cryobox systems are capturing preference share in United States academic medical centers and contract research organizations.
Consolidated procurement through group purchasing organizations is compressing vendor access for specialized cryobox manufacturers. Hospital systems and research consortia are centralizing cold-chain accessory purchasing to leverage volume pricing and standardized validation packages. This concentration is most pronounced in United States biobanking networks affiliated with the National Cancer Institute's biospecimen research programs.
Cryoboxes Market Segmentation
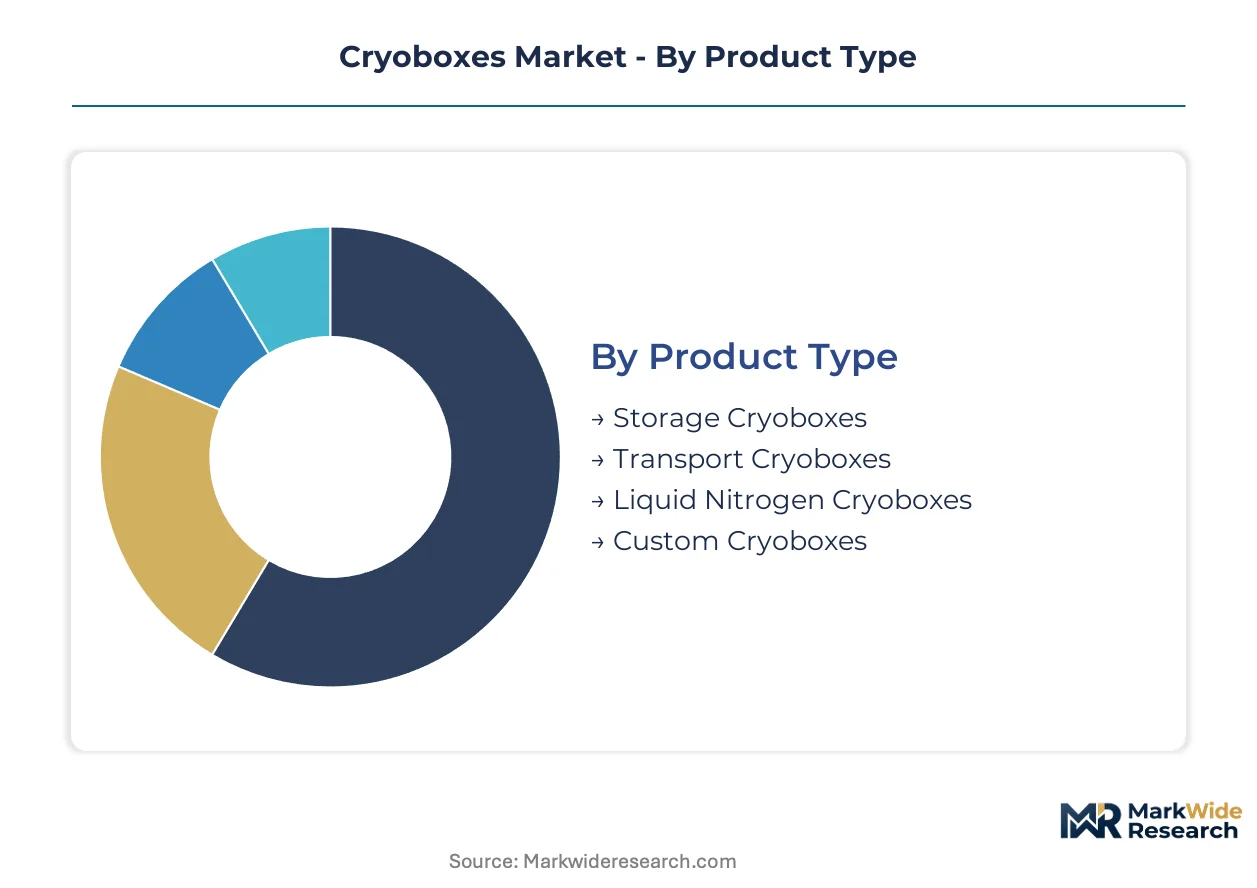
Cryobox segmentation reflects divergent thermal protocols across fixed-site biobanking and distributed cell therapy logistics. Procurement priorities split between validated storage configurations for longitudinal specimen archives and transport-grade systems maintaining chain-of-custody across multi-site manufacturing networks.
Product Type:
Buyers differentiate by thermal stability requirements and mobility constraints in their cold-chain workflows.
- Storage Cryoboxes:Rigid polycarbonate or aluminum containers engineered for static ultra-low temperature preservation within mechanical freezers or liquid nitrogen dewars. Academic medical centers and biobanks in the United States prioritize these for longitudinal specimen archives under FDA 21 CFR Part 11 traceability mandates.
- Transport Cryoboxes:Insulated, shock-resistant configurations maintaining minus 150 to minus 196 degrees Celsius during inter-facility shipment. Cell therapy CDMOs in Germany and Switzerland are scaling procurement as autologous therapy logistics expand beyond single-site manufacturing.
- Liquid Nitrogen Cryoboxes:Specialized immersion-grade designs with vented constructions preventing pressure buildup during direct liquid nitrogen contact.
- Custom Cryoboxes:Bespoke dimensions and grid patterns matching proprietary vial formats or automated retrieval systems.
Storage cryoboxes lead volumes today; transport cryoboxes are gaining share fastest.
Material:
Material selection trades optical clarity and sterilization resilience against thermal conductivity and mechanical durability.
- Polycarbonate:Medical-grade transparent polymer offering autoclave compatibility and visual sample verification without thermal exposure. ISO 20387-accredited biobanks in France and the Netherlands specify these for audit-compliant specimen management.
- Aluminum:High thermal conductivity metal variants optimizing heat transfer in liquid nitrogen immersion protocols. Research laboratories in Japan favor these for rapid cooldown applications in stem cell cryopreservation workflows.
- Steel:Reinforced structural grade for heavy-duty rack systems and automated storage retrieval environments.
- Composite Materials:Hybrid constructions combining polymer insulation with metallic reinforcement for specialized transport applications.
Polycarbonate dominates procurement value; aluminum climbs fastest in liquid nitrogen-dependent segments.
Capacity:
Facility scale and sample throughput density determine dimensional requirements across procurement decisions.
- Small:Compact 25-81 vial configurations for boutique research laboratories and early-stage cell therapy developers with limited batch sizes.
- Medium:Standard 100-vial footprints compatible with universal rack systems. Pharmaceutical companies in India deploy these for CDSCO-oversight clinical trial specimen management.
- Large:High-density 144-vial designs maximizing cubic efficiency in centralized biobank infrastructure.
- Extra Large:Bulk 256-plus vial systems for national precision medicine repositories and high-throughput screening facilities.
Medium capacity anchors standard procurement; extra large configurations expand most quickly in federal biobanking initiatives.
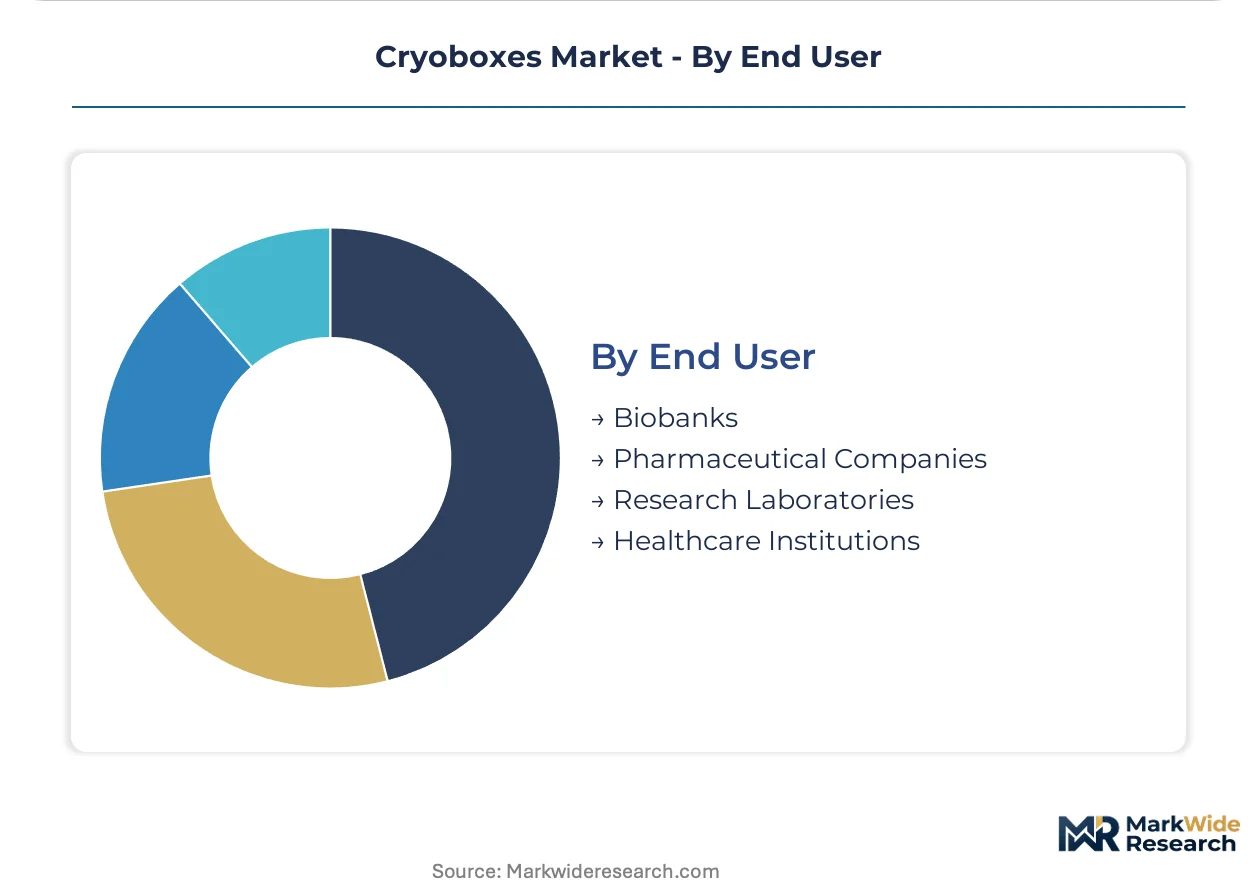
End User:
Regulatory exposure and sample custody requirements shape specification rigor across customer categories.
- Biobanks:Accredited specimen repositories requiring ISO 20387-compliant thermal validation and barcode-integrated traceability. The United States National Cancer Institute's biospecimen research programs drive standardization for pre-qualified cryobox systems.
- Pharmaceutical Companies:Cell therapy developers and clinical trial sponsors needing transport-grade configurations with documented chain-of-custody. Swiss and German manufacturers prioritize these for EMA-aligned cold-chain compliance.
- Research Laboratories:Academic and institutional investigators with flexible specifications and cost-sensitive procurement patterns.
- Healthcare Institutions:Hospital-based tissue banks and transplant centers with intermediate regulatory exposure and routine clinical sample volumes.
Biobanks command premium specification adoption; pharmaceutical companies represent the steepest expansion trajectory as cell therapy commercialization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cryogenic storage infrastructure originated in United States academic medical centers during the 1960s biobanking movement, then diffused to European pharmaceutical clusters and Asian precision medicine initiatives. Procurement patterns now reflect divergent regulatory maturity across three continents.
United States
The National Cancer Institute's biospecimen research programs fund ultra-low temperature capacity at research medical centers in Boston and Houston. FDA 21 CFR Part 11 mandates compress procurement cycles for validated cryobox systems with barcode-integrated traceability. Philadelphia's cell therapy corridor drives transport-grade configuration demand as autologous therapy logistics expand.
Germany
ISO 20387-accredited biobanks in Heidelberg and Berlin replace legacy containers with thermally validated polycarbonate systems. The EU MDR framework requires documented thermal performance for cryogenic accessories entering regulated workflows. Baden-Württemberg's precision molding cluster anchors European supply for medical-grade polymer processing.
Switzerland
Cell therapy CDMOs in Basel and Zurich scale procurement of transport cryoboxes maintaining chain-of-custody across multi-site manufacturing networks. Swissmedic oversight aligns cold-chain documentation with EMA guidance for commercial therapy distribution. The country's pharmaceutical logistics heritage shapes specification rigor for cryogenic transport validation.
India
The Department of Biotechnology's biorepository investments create demand for validated cold-chain accessories in Hyderabad and Bangalore. CDSCO expanding clinical trial oversight mandates temperature documentation for specimen containers in regulatory submissions. Maharashtra's pharmaceutical manufacturing belt adopts medium-capacity polycarbonate configurations for contract research operations.
Japan
Stem cell cryopreservation workflows in Tokyo and Osaka favor aluminum cryobox variants for rapid cooldown applications in liquid nitrogen immersion protocols. PMDA guidelines for regenerative medicine products specify thermal validation requirements for storage accessories. METI-funded precision medicine initiatives expand centralized biobank infrastructure in the Kanto region.
Cryoboxes Market Competitive Environment
The competitive structure tilts toward diversified laboratory supply conglomerates with cold-chain logistics heritage. Tiered positioning separates integrated workflow providers from specialized precision molders and regional polymer processors. Three archetypes dominate: full-service laboratory distributors with validated supply networks, ISO-certified polycarbonate specialists with autoclave-compatible manufacturing, and precision-molded grid system innovators. Capacity expansion and direct-to-lab distribution agreements constitute the dominant competitive moves as manufacturers bypass general distributors to secure cell therapy CDMO relationships.
Among diversified laboratory supply conglomerates, Thermo Fisher Scientific and VWR International represent integrated workflow providers leveraging broad cold-chain infrastructure. Greiner Bio-One and Eppendorf exemplify the European precision molding archetype, with the former anchoring ISO-compliant polycarbonate supply and the latter occupying a position in precision-molded grid system design. Biologix Group sits within the Asia-Pacific manufacturing tier, reflecting regional capacity buildout for validated cryogenic accessories.
| Leading Market Players |
|---|
| VWR International |
| Greiner Bio-One |
| Thermo Fisher Scientific |
| Micronic |
| Argos Technologies |
| Eppendorf |
| Biologix Group |
| DWK Life Sciences |
| Corning Incorporated |
| Others |
Value Chain & Pricing Dynamics
FDA 21 CFR Part 11 validation requirements are forcing biobanks and CDMOs toward pre-qualified cryobox configurations, compelling polycarbonate processors to absorb certification costs and compressing margins on standard-grade products while elevating premiums for documented thermal performance.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with ISO 20387 certification grade and autoclave compatibility serving as the primary price differentiation drivers. Cost compression in standard polycarbonate tiers is intensifying because petrochemical feedstock volatility squeezes transparent-grade manufacturers. Academic medical centers exhibit the highest price sensitivity due to consolidated purchasing through National Cancer Institute-affiliated group purchasing organizations, while cell therapy CDMOs prioritize thermal validation over unit cost.
Supply Chain Analysis
ISO 20387 and EU MDR qualification gating restricts viable supply to a narrow base of certified processors in Germany, Switzerland, and the United States. Medical-grade polycarbonate resin, precision-molded grid components, and cryogenic-compatible RFID substrates constitute critical input dependencies. Single-source vulnerability concentrates in Baden-Württemberg's precision molding cluster, where a limited cohort of ISO-certified processors serves European biobank demand. Distribution runs through validated laboratory supply networks that bypass general distributors for direct-to-CDMO agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA 21 CFR Part 11 electronic records mandates and converging EMA cold-chain guidance continuously escalate specification thresholds and replacement cycles.
For Market Incumbents: Extend validation documentation capabilities to compress 6-12 month IQ/OQ/PQ sales cycles, and anchor supply agreements with Philadelphia and Boston cell therapy corridors before emerging polymer processors achieve ISO certification. Threat concentration sits with Indian and Chinese manufacturers scaling medical-grade polycarbonate capacity; defensive leverage rests on backward integration into cryogenic materials engineering talent pools. For New Entrants and Emerging Players: The price-point gap between premium validated systems and economy-grade research configurations offers white-space entry for mid-tier thermal validation offerings. India's CDSCO-expanding clinical trial oversight presents the most penetrable geography, with Maharashtra's pharmaceutical manufacturing belt seeking medium-capacity polycarbonate systems. A go-to-market angle targeting contract research organizations with bundled barcode-traceability packages bypasses entrenched GPO relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-molded grid system specialists possessing autoclave-compatible manufacturing and existing FDA master file documentation. Long-term viability over a multi-year horizon favors acquisition targets with captive cryogenic materials engineering capabilities and established CDMO relationships. The signal to watch is harmonization timing between FDA and EMA cold-chain guidance, which would trigger accelerated replacement cycles for non-validated legacy inventory.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 21 CFR Part 11 Pre-Validation | Reduces sales cycles for academic medical centers and CROs by embedding IQ/OQ/PQ documentation. |
| RFID-Integrated Traceability Development | Enables real-time temperature logging without manual barcode scanning for cell therapy logistics. |
| Direct-to-CDMO Distribution Agreements | Bypasses general laboratory distributors to secure validated supply relationships with Basel and Zurich manufacturers. |
| ISO 20387 Accreditation Investment | Unlocks procurement from European biobanks in Heidelberg and Berlin replacing legacy containers. |
| Cryogenic Materials Engineering Talent Acquisition | Addresses scarcity in polymer scientists with minus 150 degrees Celsius substrate expertise. |
Study Parameters
Multiple input streams — primary interviews with biobank operations directors, cell therapy supply chain managers, and cryogenic materials engineers; secondary validation through FDA 510(k) filings, ISO 20387 accreditation databases, and CDSCO clinical trial registries; plus customs and trade data on medical-grade polymer imports — were reconciled through bottom-up and top-down triangulation.
Historical shipment patterns were cross-referenced against expert panel inputs to model volume and value outputs across the projection horizon. Segmentation dimensions included product type, material grade, capacity tier, end-user category, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating cell therapy commercialization timelines and biobanking infrastructure buildout trajectories. Industry-specific forecast inputs encompassed liquid nitrogen infrastructure expansion rates and precision molding capacity utilization.
The model assumes a particular technology adoption path; alternative pathways for RFID-integrated cryogenic sensing would alter the outlook if wireless substrate durability at minus 196 degrees Celsius advances faster than projected. Deviation in FDA-EMA cold-chain guidance harmonization timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Hemodialysis Consumables Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Global Chromatography Syringes Market
Medical Supplies
Veterinary Suture Kit Market
Medical Supplies
Bleeding Control Kit Market
Medical Supplies
Nucleic Acid Isolation and Purification Kits Market
Medical Supplies
Plastic Syringes Market
Medical Supplies
IV Infusion Gravity Bags Market
Medical Supplies
Nursing Breast Pads Market
Medical Supplies
Face Mask Market
Medical Supplies
Nasal Splints Market
Medical Supplies
Medical Disposables Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Italy Hospital Supplies Market
Medical Supplies
Measured Volume Burette Set Market
Medical Supplies
United Kingdom Hospital Supplies Market