
 France Home Appliances Market | 2026-2036
France Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
France Home Appliances Market Foresight
The EU Green Deal and France's AGEC anti-waste law is pivoting manufacturer priorities toward repairability and recycled material integration. Groupe SEB leverages its deep domestic manufacturing base to control premium small appliance supply chains. Whirlpool Corporation anchors its European R&D operations in France to align with evolving ecodesign rules. BSH Hausgeräte GmbH specializes in energy-efficient built-in kitchen systems that meet stricter French building codes.
France home appliances encompass electrically powered devices for domestic food preservation, textile care, cooking, and cleaning, typically operating at 230V/50Hz with energy efficiency ratings scaled from A to G under EU frameworks. Their primary purpose is reducing household labor time while minimizing electricity and water consumption per cycle. Refrigerators and washing machines dominate volume sales, though smart appliances represent the fastest-expanding margin pool as connectivity premiums justify higher price points. Energy efficient technology retains structural importance due to French utility rebate programs and mandatory EU labeling, while IoT enabled systems attract urban buyers seeking remote monitoring and predictive maintenance.
ANSM oversees product safety compliance for appliances with health-relevant functions, while ADEME administers national ecodesign subsidies and circular economy incentives that directly shape manufacturer cost structures. France's repairability index, enforced by DGCCRF market surveillance, now mandates disassembly scoring that influences both consumer choice and retailer stocking decisions. Stakeholders must monitor how upcoming EU Ecodesign for Sustainable Products Regulation amendments will redefine material disclosure requirements and extended producer responsibility fees across the French market.
Market Dynamics
France's AGEC anti-waste law and repairability index mandates are forcing manufacturers to redesign products around modularity and extended lifespan, compressing traditional replacement cycles while creating new service revenue streams.
Growth Catalysts
- Île-de-France Urban Density:Paris and Lyon apartment dwellers are upgrading to connected kitchen ecosystems, driving premium smart appliance penetration above national averages.
- ADEME Ecodesign Subsidies:National circular economy incentives directly reduce manufacturer redesign costs for recycled material integration and modular component architectures.
- EU Green Deal Alignment:Extended producer responsibility frameworks are accelerating retailer stocking shifts toward repairability-scored products.
Market Restraints
- Copper and Rare Earth Input Volatility:Motor and sensor production faces cost pressure from concentrated mining supply chains outside Europe.
- DGCCRF Enforcement Complexity:Repairability index compliance creates documentation burdens that slow product launch timelines for smaller manufacturers.
- Technical Skill Shortage:Modular repair architectures require technicians trained in component-level diagnostics, a capability pool concentrated in established service networks.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur Underpenetration:Secondary urban centers outside Paris show lagging smart appliance adoption, creating whitespace for connectivity-first market entry.
- IoT-Predictive Maintenance Convergence:Remote monitoring capabilities are enabling subscription-based service models that decouple revenue from unit sales.
- ANSM Safety Certification Pathways:Health-relevant appliance functions create premium positioning through medical-grade compliance differentiation.
Industry Challenges
- CE Marking Transition Timelines:Upcoming EU Ecodesign for Sustainable Products Regulation amendments demand material disclosure systems that most manufacturers lack.
- Legacy Inventory Obsolescence:Existing stock with poor repairability scores faces accelerated devaluation as retailer stocking decisions pivot to index-compliant alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Home Appliances Market |
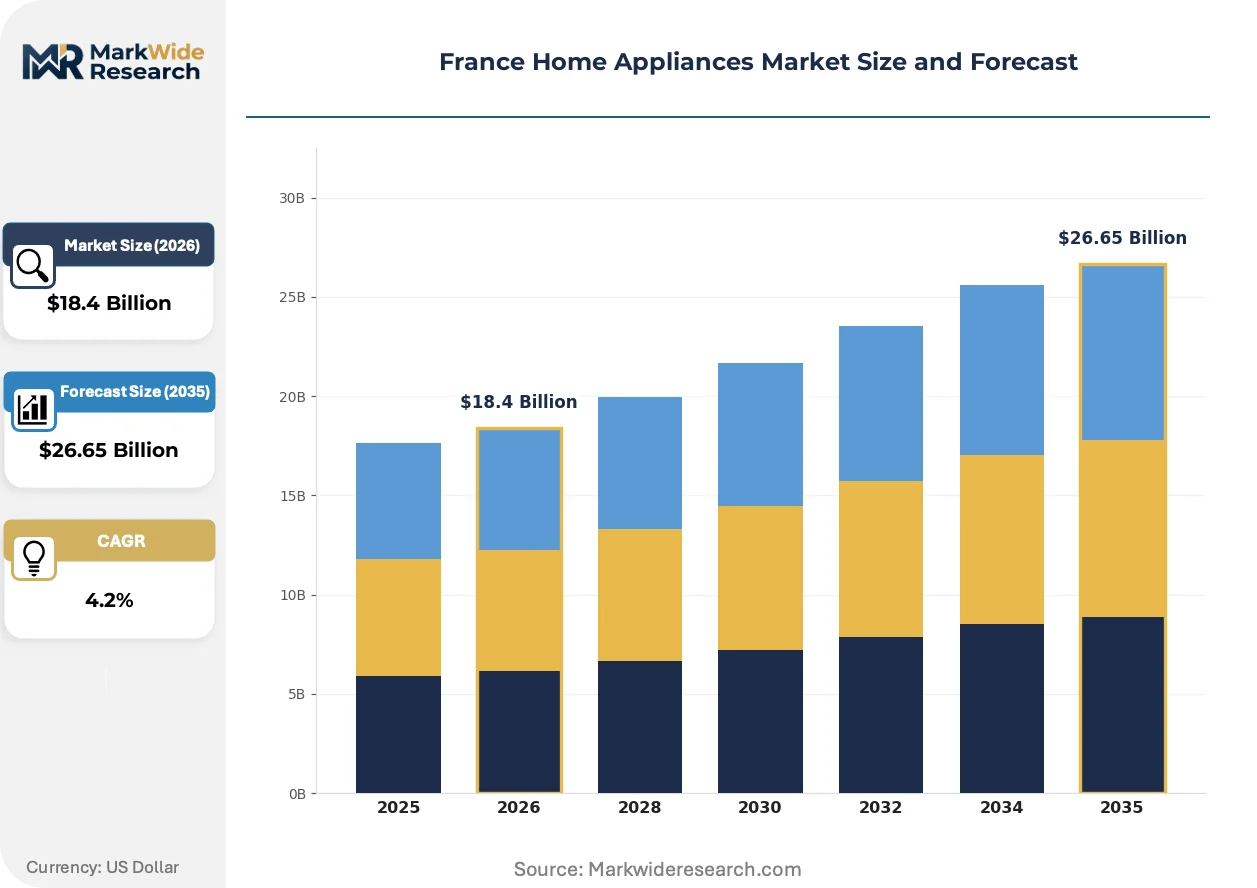
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $26.65 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Ovens, Dishwashers Technology: Smart Appliances, Energy Efficient, Traditional, IoT Enabled End User: Residential, Hospitality, Retail, Commercial Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Whirlpool Corporation, GROUPE BRANDT, Groupe SEB, LG Electronics, Robert Bosch GmbH, BSH Hausgeräte GmbH, Haier Europe, Samsung Electronics Co. Ltd., Electrolux AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Home Appliances Market Shifts & Advancements
Connectivity premiums and circular economy mandates are restructuring how appliances are designed, sold, and serviced across French households, with technology convergence and regulatory compliance emerging as the primary axes of competition.
Edge computing modules embedded in refrigeration and laundry systems are enabling real-time energy optimization and fault prediction without cloud dependency. Urban buyers in Paris and Lyon are adopting these capabilities fastest, paying connectivity premiums that justify hardware cost increases. Predictive maintenance algorithms are converging with utility demand-response programs, creating appliance ecosystems that automatically shift cycles to off-peak pricing windows.
France's repairability index enforcement by DGCCRF now mandates standardized disassembly scoring displayed at point of sale. Manufacturers must submit technical documentation proving component accessibility, directly influencing R&D allocation toward modular architectures. Premium built-in kitchen systems face the steepest compliance costs, while freestanding small appliances adapt more rapidly to scoring requirements.
Buyers are unbundling after-sales service from initial purchase, selecting third-party maintenance providers based on repairability score transparency. Retailers in Île-de-France are responding with in-store diagnostic hubs that extend product lifespan through component swaps rather than full replacement. This behavioral shift compresses manufacturer service revenue while expanding independent repair network participation.
France Home Appliances Market Segmentation
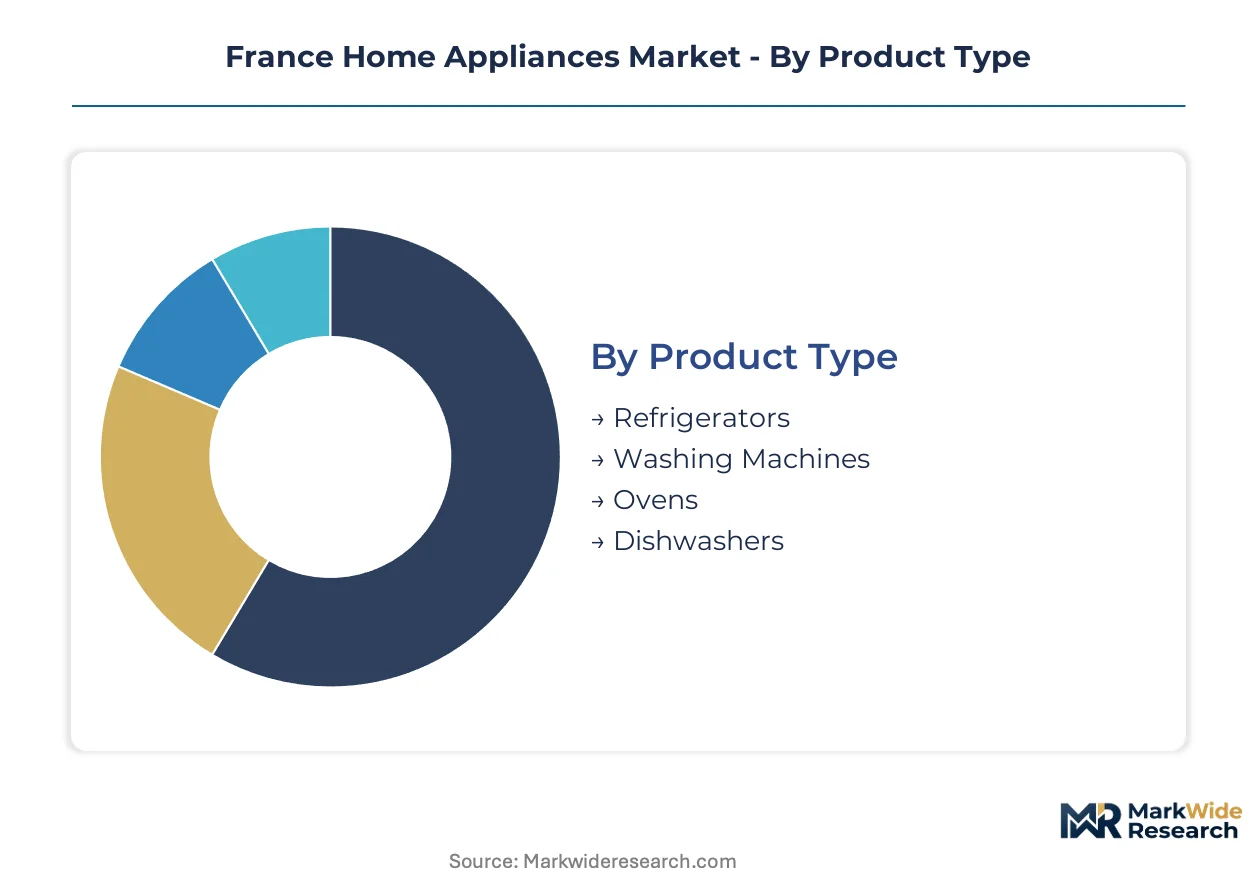
Segmentation in the France home appliances market reveals how AGEC compliance costs and connectivity premiums distribute unevenly across product categories and buyer types. Understanding these fault lines helps explain why Île-de-France households absorb price increases faster than secondary markets.
Product Type:
Upgrade cycles vary dramatically by product category, with replacement timelines compressing for connected models while extending for modular repair-friendly designs.
- Refrigerators:French-door and bottom-freezer configurations dominate premium placements in Parisian apartments, where space constraints favor vertical storage optimization. Île-de-France buyers prioritize connected inventory management systems that reduce food waste, aligning with AGEC anti-waste objectives while justifying higher price points through utility rebate eligibility.
- Washing Machines:Front-loading drum systems with heat pump drying integration command the steepest premiums in urban households, where combined wash-dry cycles address space limitations. ADEME ecodesign subsidies accelerate adoption of water-recirculating models in Lyon and Marseille, though technical skill shortages slow repair network expansion for modular motor replacements.
- Ovens:Built-in pyrolytic and steam-assisted cooking systems serve renovation-driven demand in Île-de-France housing upgrades.
- Dishwashers:Slimline 45cm widths address Parisian kitchen constraints, with water consumption ratings driving purchase decisions under French utility scoring frameworks.
Volume placements concentrate in Refrigerators; the faster expansion belongs to Washing Machines with heat pump integration.
Technology:
Cost tier stratification separates buyers who prioritize upfront acquisition price from those capturing lifetime operating cost savings through efficiency premiums.
- Smart Appliances:Edge computing modules embedded in refrigeration and laundry systems enable real-time energy optimization without cloud dependency. Paris and Lyon apartment dwellers adopt these capabilities fastest, paying connectivity premiums that manufacturers use to offset AGEC compliance investments.
- Energy Efficient:A+++ rated models under EU frameworks dominate ADEME subsidy qualification, with recycled material integration becoming mandatory for ecodesign certification. French building codes for new construction increasingly mandate minimum efficiency thresholds that exclude traditional technology from permitted installations.
- Traditional:Non-connected, non-modular appliances face accelerated devaluation as DGCCRF repairability index enforcement shifts retailer stocking decisions toward scored alternatives.
- IoT Enabled:Predictive maintenance algorithms converging with utility demand-response programs create automatic cycle-shifting capabilities that reduce peak-hour electricity costs.
Volume placements concentrate in Energy Efficient models; the faster expansion belongs to Smart Appliances with embedded edge computing.
End User:
Application context determines whether appliances operate in owner-controlled environments with long-term efficiency incentives or rental settings with capital-constrained purchasing patterns.
- Residential:Owner-occupied apartments in Île-de-France drive premium smart appliance penetration, where households capture full lifecycle savings from efficiency investments. AGEC repairability mandates align with homeowner preferences for extended product lifespan through modular component replacement.
- Hospitality:Boutique hotels in Provence-Alpes-Côte d'Azur prioritize design-forward kitchen ecosystems that differentiate guest experiences, accepting higher capital costs for connected inventory management that reduces operational labor.
- Retail:Appliance showrooms and demonstration environments require commercial-grade durability ratings that exceed residential specifications.
- Commercial:Shared laundry facilities and corporate cafeteria kitchens face compressed replacement cycles due to intensive utilization patterns.
Volume placements concentrate in Residential; the faster expansion belongs to Hospitality with experience-differentiation requirements.
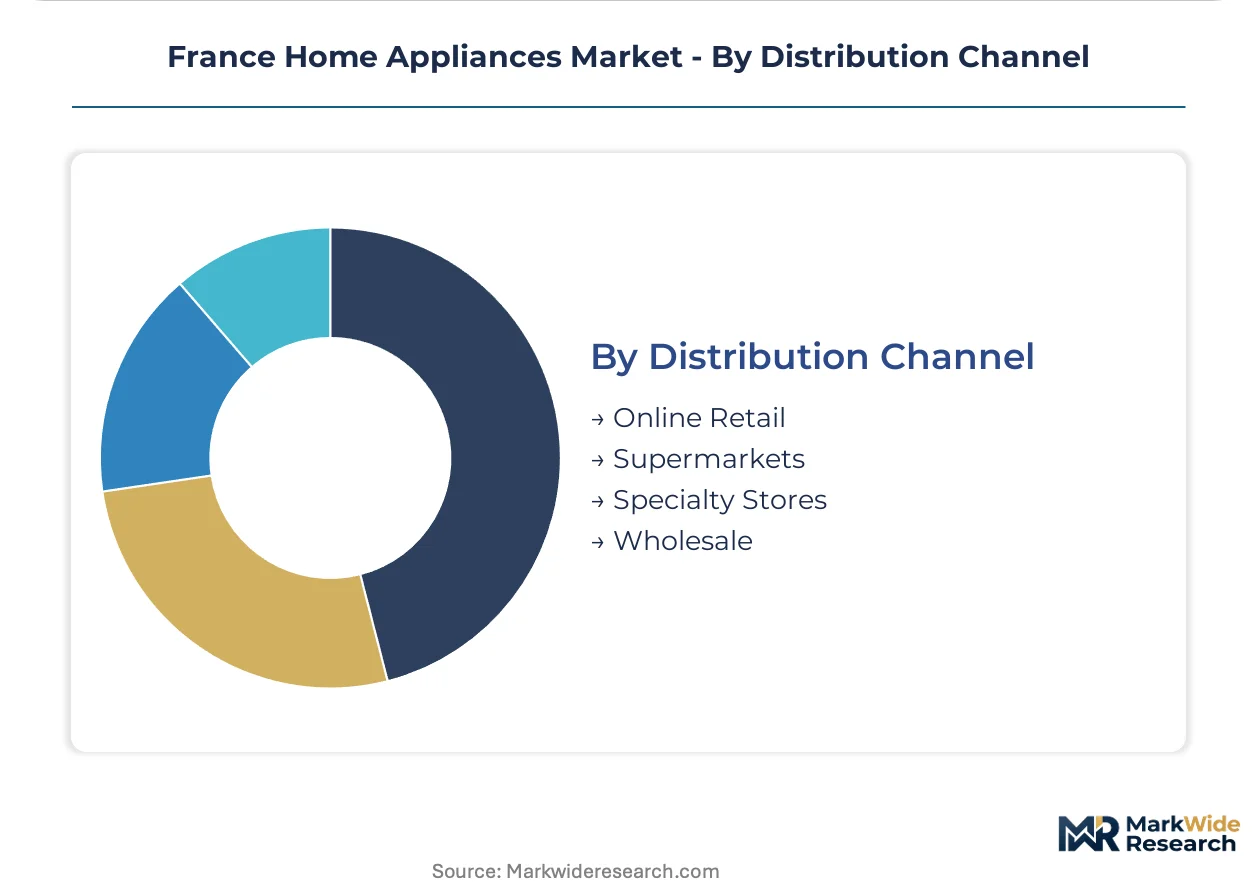
Distribution Channel:
Customer type and purchase journey complexity shape channel selection, with informed buyers seeking repairability transparency and convenience-driven purchasers prioritizing immediate availability.
- Online Retail:E-commerce platforms enable detailed repairability score comparison and subscription-based service bundling that decouples revenue from unit sales. DGCCRF-mandated documentation requirements favor established online retailers with technical content management capabilities.
- Supermarkets:Hypermarket chains leverage volume placement of freestanding small appliances, where lower compliance costs enable aggressive pricing on entry-tier products with minimal smart functionality.
- Specialty Stores:Kitchen design studios in Paris and Lyon provide in-store diagnostic hubs that extend product lifespan through component-level service.
- Wholesale:Builder and contractor channels supply new construction projects subject to French building code efficiency mandates.
Volume placements concentrate in Supermarkets; the faster expansion belongs to Online Retail with subscription service integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris anchors France's home appliances demand concentration, with Île-de-France households absorbing premium smart appliance price increases faster than secondary markets. Regional variation reflects urban density gradients and repairability index enforcement intensity.
Île-de-France
Paris and its metropolitan periphery drive connected kitchen ecosystem upgrades, where apartment space constraints favor vertical storage optimization and combined wash-dry cycles. ADEME ecodesign subsidies accelerate adoption of A+++ rated models in owner-occupied housing. The capital's specialty kitchen design studios operate in-store diagnostic hubs that extend product lifespan through modular component replacement.
Auvergne-Rhône-Alpes
Lyon households replicate Parisian smart appliance penetration patterns, though at moderated price points reflecting lower housing costs per square meter. The region's industrial heritage supports a concentrated technician pool for component-level diagnostics, mitigating skill shortages that slow repair network expansion elsewhere. Whirlpool Corporation anchors its European R&D operations here to align with evolving French ecodesign rules.
Provence-Alpes-Côte d'Azur
Boutique hospitality operators in Nice and Marseille prioritize design-forward kitchen ecosystems that differentiate guest experiences, accepting higher capital costs for connected inventory management. Smart appliance adoption lags residential markets in Paris and Lyon, creating whitespace for connectivity-first market entry. Regional utility rebate programs remain less generous than ADEME's national circular economy incentives.
Hauts-de-France
Lille and surrounding industrial centers exhibit price-sensitive purchasing patterns concentrated in supermarket channels and entry-tier freestanding appliances. DGCCRF repairability index enforcement penetrates retail stocking decisions more slowly here than in Île-de-France. The region's housing stock renovation cycles drive periodic replacement demand for built-in pyrolytic cooking systems.
Nouvelle-Aquitaine
Bordeaux households balance efficiency investments with upfront acquisition price sensitivity, favoring energy-efficient technology that qualifies for utility rebate programs over connectivity premiums. The region's dispersed settlement patterns reduce the density required for third-party maintenance network viability. Water-recirculating washing machine adoption accelerates where local utility scoring frameworks provide explicit consumption incentives.
France Home Appliances Market Competitive Landscape
Premium-margin players sit above commodity-margin players across repairability score transparency and IoT integration depth, with tier separation widening as DGCCRF enforcement intensifies. The vendor base clusters around three strategic archetypes: domestic manufacturers with captive supply chains, European R&D-anchored multinationals, and Asian scale players with modular platform architectures. Consolidation pressure concentrates among mid-tier traditional technology specialists facing inventory obsolescence. Dominant competitive moves include strategic partnerships with utility demand-response programs and backward integration into recycled material sourcing.
Within the domestic manufacturing tier, Groupe SEB exemplifies premium small appliance supply chain control through its deep French production base. Whirlpool Corporation and BSH Hausgeräte GmbH anchor the European R&D-anchored multinational segment, with the former aligning operations to ecodesign rules and the latter specializing in energy-efficient built-in kitchen systems. These three occupy positions that reflect divergent responses to AGEC anti-waste law compliance costs.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| GROUPE BRANDT |
| Groupe SEB |
| LG Electronics |
| Robert Bosch GmbH |
| BSH Hausgeräte GmbH |
| Haier Europe |
| Samsung Electronics Co. Ltd. |
| Electrolux AB |
| Others |
Supply & Pricing Matrix
AGEC-mandated repairability index compliance costs are forcing manufacturers to absorb modular redesign expenses while defending margin positions through connectivity premiums. Supply chain responses concentrate on recycled material sourcing and component standardization to offset documentation burdens imposed by DGCCRF enforcement.
Pricing Analysis
Value-based pricing anchored to lifetime operating cost savings dominates premium tier positioning, with A+++ efficiency ratings and predictive maintenance capabilities justifying connectivity premiums. Three-tier pricing structure across premium smart, standard efficient, and economy traditional levels reflects repairability score transparency and ADEME subsidy eligibility. Cost compression in entry-tier segments is intensifying because supermarket channels prioritize volume placement of minimally compliant freestanding appliances. Hospitality buyers in Provence-Alpes-Côte d'Azur show least price sensitivity, absorbing capital costs for design-forward kitchen ecosystems that differentiate guest experiences.
Supply Chain Analysis
Direct-to-specialty-retail channels handle premium built-in system demand, while supermarket chains manage high-volume freestanding appliance distribution. Manufacturing concentration rests on China for motor and control module production, Germany for precision engineering components, and domestic French facilities for final assembly serving AGEC compliance requirements. Copper and rare earth dependencies for sensor and motor production create single-source vulnerability from concentrated mining supply chains outside Europe. Distribution runs through Île-de-France specialty kitchen studios with in-store diagnostic capabilities, supplemented by online platforms enabling repairability score comparison.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's home appliances market functions as a cost-of-compliance story where AGEC anti-waste law mandates create barrier-to-entry moats favoring manufacturers with established modular platform architectures and captive domestic production.
For Market Incumbents: Extend service revenue streams through subscription-based predictive maintenance models that decouple income from unit sales. Invest in backward integration into recycled material sourcing to control ecodesign certification costs. Consolidate position by acquiring regional technician training networks to address skill shortages slowing modular repair network expansion. Defend against Asian scale players by leveraging DGCCRF documentation capabilities as competitive differentiation. For New Entrants and Emerging Players: Edge computing-enabled inventory management systems offer a technology-first wedge into underpenetrated Provence-Alpes-Côte d'Azur hospitality markets. Target boutique hotel operators in Nice and Marseille seeking design-forward differentiation without Parisian price premiums. White-space exists in third-party maintenance network provision for component-level diagnostics in secondary urban centers. Go-to-market should emphasize repairability score transparency and utility demand-response integration. For Investors and Strategic Acquirers: The window for entry favors domestic manufacturers with established AGEC compliance infrastructure and captive supply chain control. Mid-tier traditional technology specialists face inventory obsolescence pressure, creating consolidation targets for players seeking modular platform capabilities. Long-term viability hinges on circular economy positioning and extended producer responsibility fee management. Watch for DGCCRF enforcement intensity shifts as inflection indicator for repairability score valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Standardization | Reduces AGEC compliance costs through component interchangeability across product lines. |
| Recycled Material Sourcing Integration | Secures ADEME ecodesign subsidy eligibility while hedging virgin commodity volatility. |
| Predictive Maintenance Subscription Launch | Creates recurring revenue streams independent of replacement cycle compression. |
| Specialty Retail Diagnostic Hub Expansion | Captures service margins from component-level repair demand in Île-de-France. |
| Utility Demand-Response Partnership | Positions connected appliances for automatic peak-hour cycle shifting and rebate capture. |
Research Methodology
Multi-period observation of ADEME subsidy disbursement patterns, DGCCRF enforcement actions, and retailer stocking shifts anchored the trend analysis, supplemented by interviews with appliance category buyers at hypermarket chains, procurement directors at hospitality groups, technical service managers at specialty retailers, and sustainability officers at domestic manufacturers. Secondary validation drew from ANSM product safety filings, ADEME circular economy program documentation, EU Ecodesign regulatory amendments, and customs records of component imports. Bottom-up demand modeling triangulated against top-down manufacturer shipment data.
Segment-weighting applied product type, technology tier, end-user application, and distribution channel dimensions across the projection horizon. CAGRs were derived from fitted trend extrapolation adjusted for regulatory inflection points and subsidy program phase-outs. Industry-specific forecast inputs included repairability index scoring trajectories, copper price volatility assumptions, and technician training pipeline expansion rates.
Several conditions sit outside the modeled scope, including potential EU Ecodesign for Sustainable Products Regulation amendments, geopolitical disruptions to rare earth supply chains, and abrupt shifts in French utility rebate program generosity. Forecasts reflect documented assumptions about compliance cost pass-through rates and connectivity premium sustainability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Japan Small Home Appliances Market
Home Appliances
United States Major Home Appliances Market
Home Appliances
Bahrain Major Home Appliances Market
Home Appliances
United States Laundry Appliances Market
Home Appliances
Europe Home Appliances Market
Home Appliances
Mexico Home Appliances Market
Home Appliances
Germany Washing Machine Market
Home Appliances
Electric Fireplace Market
Home Appliances
Smart Small Home Appliances Market
Home Appliances
Argentina Home Appliances Market
Home Appliances
India Small Home Appliances Market
Home Appliances
Home Laundry Appliances Market
Home Appliances
China Laundry Appliances Market
Home Appliances
Russia Home Appliances Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
Japan Home Appliances Market