
 Smart Small Home Appliances Market | 2026-2036
Smart Small Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Small Home Appliances Market Analytics
Embedded systems engineering talent is rotating toward consumer IoT from industrial automation, tightening the labor pool for smart appliance firmware development. Samsung Electronics leverages its semiconductor foundry relationships to sustain chip supply security for connected cooking devices. Haier Smart Home anchors its position through U+ smart home platform integration across multiple appliance categories. Midea Group competes on manufacturing scale, operating some of the largest small appliance production facilities in Guangdong province.
Smart small home appliances encompass compact, network-connected domestic devices with embedded sensors, microcontrollers, and wireless communication modules enabling remote operation, automated scheduling, and data-driven performance optimization. These products typically operate on 110-240V AC power, incorporate IEEE 802.11 b/g/n Wi-Fi or Bluetooth 5.0 protocols, and serve the primary purpose of reducing manual intervention in routine household tasks while generating usage analytics for energy management and predictive maintenance. Smart ovens with integrated AI features command premium positioning due to computer vision-enabled cooking recognition and automatic temperature adjustment algorithms. Smart plugs represent the volume anchor within product type segmentation, benefiting from low entry price points and universal compatibility with existing non-connected appliances. The hospitality sector end user segment is concentrating demand for unified fleet management platforms that centralize control across distributed property portfolios.
The Federal Communications Commission enforces electromagnetic emissions standards that dictate wireless module certification timelines for US-bound products, while the EU Ecodesign Directive mandates standby power thresholds below 0.5W for networked appliances sold in member states. China's GB standards for household electrical safety, administered by the Standardization Administration, create parallel compliance pathways that manufacturers must navigate for domestic market access. Stakeholders must monitor evolving interoperability protocols and energy efficiency thresholds as these regulatory dimensions increasingly determine which product architectures achieve commercial viability across major sales channels.
Market Dynamics
Interoperability protocol fragmentation is forcing manufacturers to engineer multiple wireless stack variants simultaneously, inflating firmware development costs and certification timelines for connected kitchen and cleaning devices.
Growth Catalysts
- EU Ecodesign Directive standby power mandates:Networked appliances must demonstrate sub-0.5W idle consumption, accelerating replacement cycles for legacy products that fail efficiency thresholds.
- Urban millennial household formation:Compact housing in Shenzhen, Hangzhou, and Shanghai generates concentrated demand for space-efficient connected cooking devices with app-controlled scheduling.
- Matter protocol standardization:Cross-platform interoperability is reducing consumer friction in multi-brand smart home ecosystems, lifting attachment rates for complementary small appliances.
Market Restraints
- Semiconductor supply concentration:Wi-Fi and Bluetooth module fabrication clusters in Taiwan and South Korea expose manufacturers to single-source disruption risks during geopolitical tension.
- FCC electromagnetic emissions certification:US-bound products face 12-16 week approval timelines that compress launch windows and delay revenue recognition.
- Copper and rare earth magnet cost volatility:Motor assemblies in smart vacuums and blenders absorb input price swings that OEMs struggle to pass through in mass-market segments.
Strategic Opportunities
- India BIS certification alignment:Harmonized safety standards with IEC frameworks are reducing duplicate testing costs for manufacturers entering the subcontinent's underserved smart appliance channel.
- Hospitality fleet management platforms:Distributed property portfolios require centralized device monitoring, creating attach-rate potential for subscription-based maintenance and energy analytics.
- Computer vision and thermal sensor convergence:AI-enabled cooking recognition is opening premium positioning for ovens that automatically adjust temperature curves based on food state detection.
Industry Challenges
- Embedded systems talent scarcity:Firmware engineers with consumer IoT experience command compensation premiums that strain R&D budgets at mid-tier manufacturers.
- Multi-protocol certification stacking:Products supporting Zigbee, Thread, and Wi-Fi simultaneously face compounded testing timelines from IEEE, CSA, and Wi-Fi Alliance bodies.
- Legacy appliance integration complexity:Smart plugs and retrofit controllers must accommodate decades-old electrical standards without compromising safety margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Small Home Appliances Market |
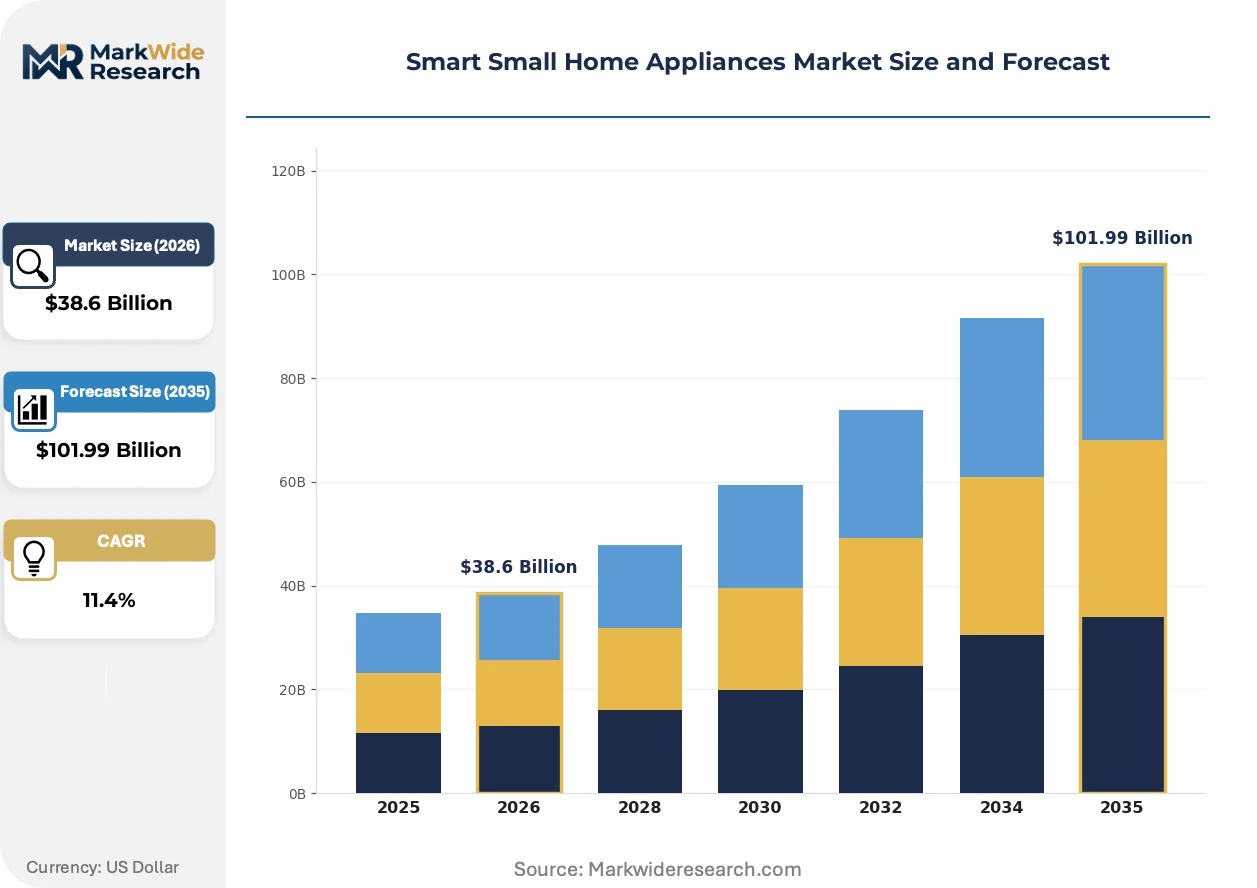
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Plugs, Smart Ovens, Smart Toasters, Smart Kettles Feature: Voice Control, Remote Monitoring, Energy Efficiency, Integrated AI End User: Homeowners, Renters, Hospitality Sector, Students Distribution Channel: Online Retail, Specialty Stores, Home Improvement, Mass Merchants |
| Companies Covered | Samsung Electronics, LG Electronics, Haier Smart Home, Whirlpool Corporation, BSH Hausgeräte GmbH, Panasonic Corporation, Midea Group, Electrolux AB, GE Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Small Home Appliances Market Evolving Landscape
Edge computing architectures are migrating cooking recognition algorithms from cloud servers to device-local processors, reducing latency and addressing consumer privacy concerns about kitchen data transmission.
Generative AI recipe engines are fragmenting competitive differentiation in connected cooking appliances. Haier and Midea embed large language models that interpret ingredient inventories and suggest preparation sequences. Early adoption concentrates among tech-forward households in Guangdong province. This capability is fragmenting the premium tier into AI-enabled and non-AI product lines with diverging margin structures.
The EU AI Act risk classification framework is imposing documentation burdens on appliances with automated decision-making capabilities. Cooking algorithms that adjust parameters without human confirmation face conformity assessment requirements. Smart oven manufacturers with computer vision features are most affected, with product teams restructuring technical files for notified body review.
Direct-to-consumer subscription models are displacing traditional retail attachment for consumable-linked appliances. Coffee machine manufacturers pilot bean-delivery programs that lock in recurring revenue. This pattern is most visible in Germany and the Netherlands, where sustainability-conscious buyers prioritize packaging reduction over shelf convenience.
Smart Small Home Appliances Market Segmentation
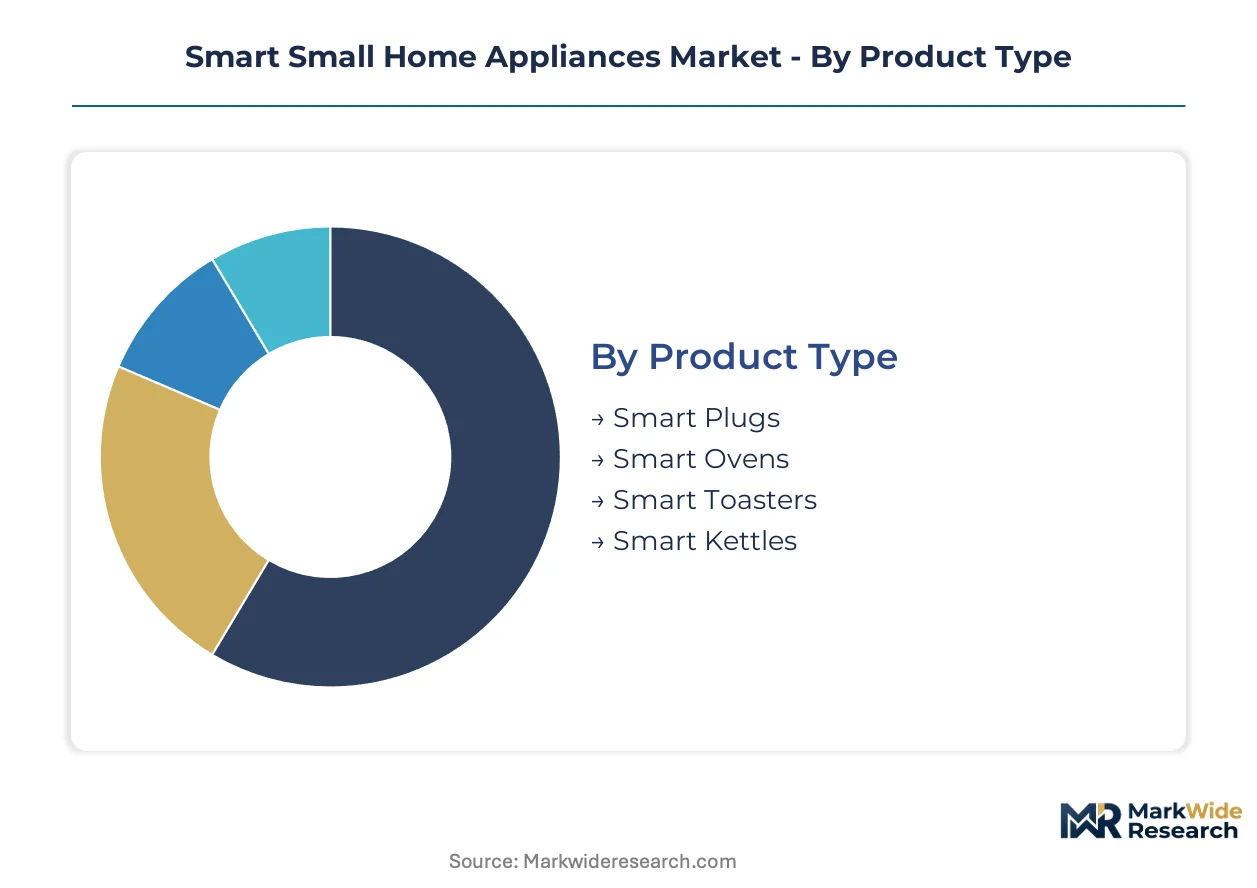
Segmentation in smart small home appliances reveals distinct demand profiles across product architectures, connectivity features, and procurement channels. Manufacturers calibrate R&D allocation and certification strategies based on which segments concentrate volume versus margin.
Product Type:
Domestic markets in China absorb the majority of smart kettles and toasters from Guangdong-based OEMs, while smart ovens and plugs ship disproportionately to North American and European distribution channels.
- Smart Plugs:Universal-form-factor devices with 110-240V AC compatibility and IEEE 802.11 b/g/n modules. Mass-market adoption concentrates in North America where retrofitting legacy appliances drives volume, constrained by FCC electromagnetic emissions certification timelines.
- Smart Ovens:Computer vision-enabled cooking chambers with thermal sensors and edge-deployed AI recognition algorithms. Premium positioning targets tech-forward households in Shenzhen and Hangzhou seeking automated temperature curve adjustment.
- Smart Toasters:Connected browning control units with app-based scheduling interfaces. European demand clusters under EU Ecodesign Directive standby power mandates below 0.5W.
- Smart Kettles:Wi-Fi-enabled water heating vessels with boil-dry protection and usage analytics. Domestic Chinese consumption dominates through Haier and Midea smart home platform integration.
Smart plugs command the established base. The steepest expansion runs through smart ovens.
Feature:
Cost tier stratification separates premium AI-enabled products from mass-market efficiency-focused SKUs, with voice control bridging both tiers through Matter protocol standardization.
- Voice Control:Natural language interfaces compatible with Amazon Alexa, Google Assistant, and Apple Siri. Hospitality sector deployment in distributed property portfolios drives commercial-grade demand for unified command architectures.
- Remote Monitoring:Cloud-connected status feedback and push notification systems. Rental housing applications in urban millennial markets generate concentrated adoption for landlord-tenant coordination use cases.
- Energy Efficiency:Consumption optimization algorithms and real-time wattage display. EU regulatory compliance under Ecodesign Directive thresholds shapes product development roadmaps for export-bound manufacturers.
- Integrated AI:Generative recipe engines and ingredient inventory interpretation. Early deployment concentrates among Guangdong province households through Haier and Midea large language model integration.
Remote monitoring commands the established base. The steepest expansion runs through integrated AI.
End User:
Volume concentration tilts toward residential applications, while hospitality procurement patterns favor fleet-scale contracts with subscription-based maintenance attachments.
- Homeowners:Permanent residents investing in full smart home ecosystem integration. Shenzhen and Hangzhou urban districts show elevated attachment rates for multi-device platform consolidation.
- Renters:Transient households prioritizing portable, non-permanent installations. Smart plugs dominate this segment due to lease-friendly retrofit compatibility without electrical modification.
- Hospitality Sector:Hotels and serviced apartments requiring centralized device monitoring across distributed portfolios. Germany and Netherlands markets pilot subscription-based consumable delivery for coffee machine deployments.
- Students:Budget-constrained users in compact dormitory or shared housing. Entry-price-point smart kettles and basic remote monitoring features satisfy functional requirements without ecosystem lock-in.
Homeowners command the established base. The steepest expansion runs through hospitality sector.
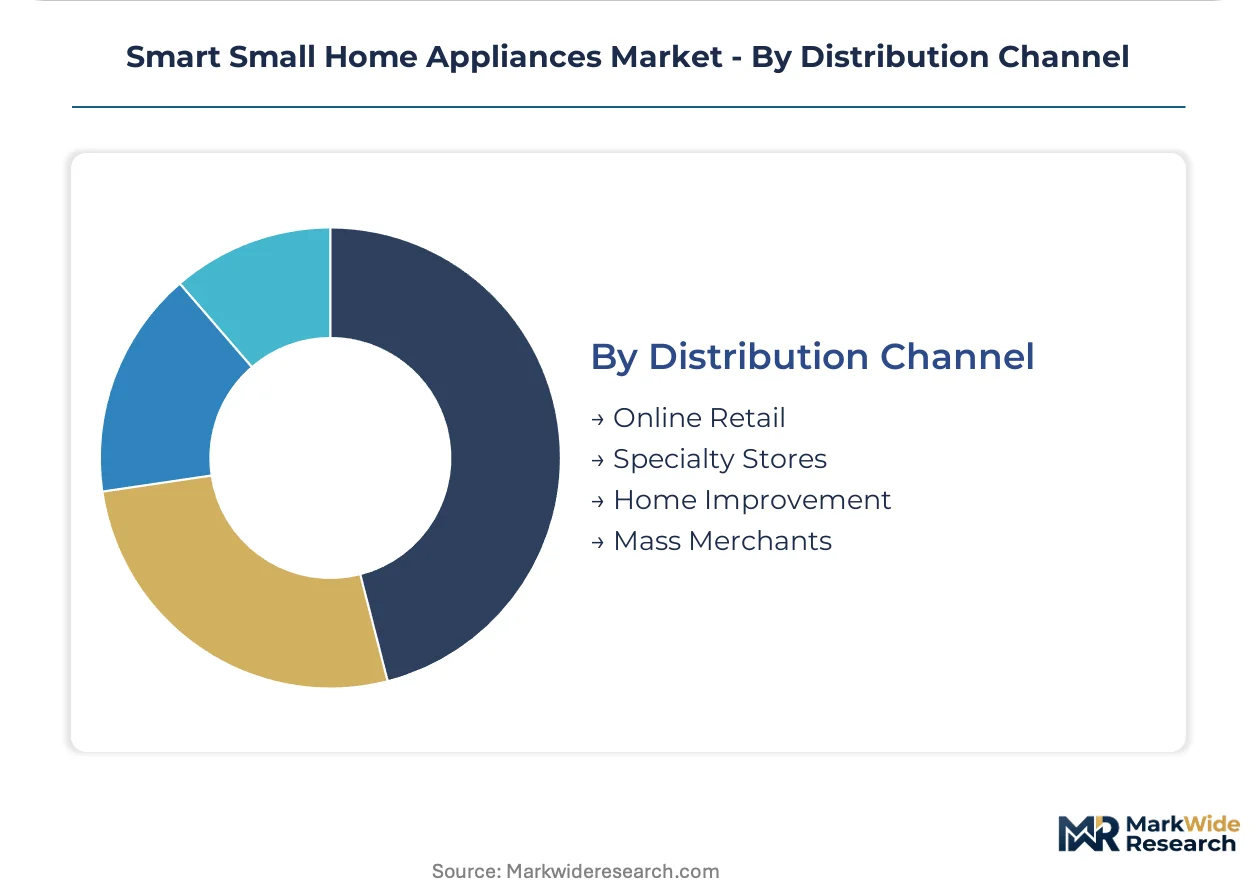
Distribution Channel:
Supply concentration varies by channel control—direct-to-consumer platforms capture subscription-linked appliances while mass merchants move high-volume plug and kettle SKUs.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators. Coffee machine bean-delivery subscription pilots in Germany and Netherlands displace traditional retail for sustainability-conscious buyers.
- Specialty Stores:Curated showrooms with in-person demonstration capabilities. Smart ovens with computer vision features require tactile consumer education to justify premium positioning.
- Home Improvement:Big-box retailers serving renovation and new construction projects. Electrical contractor relationships influence smart plug specification in North American residential builds.
- Mass Merchants:High-volume discount and club retailers. Midea Group manufacturing scale enables cost-competitive positioning for basic smart kettles and toasters in this channel.
Mass merchants command the established base. The steepest expansion runs through online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese households deploy smart small appliances as ecosystem-integrated nodes within platform-centric smart homes, while US and European consumers treat these devices as standalone retrofit upgrades to existing kitchens.
United States
FCC electromagnetic emissions certification mandates 12-16 week approval timelines that compress product launch windows for Wi-Fi-enabled cooking devices. The IRA's energy efficiency incentives accelerate replacement cycles for legacy appliances in high-electricity-cost states. Silicon Valley and Austin hardware startups concentrate R&D investment in edge-computing cooking recognition systems.
China
Urban millennial household formation in Shenzhen, Hangzhou, and Shanghai drives concentrated demand for space-efficient connected devices with app-controlled scheduling. GB standards administered by the Standardization Administration create parallel compliance pathways for domestic market access. Guangdong province manufacturing clusters from Haier and Midea anchor global supply for smart kettles and platform-integrated appliances.
Germany
EU Ecodesign Directive standby power thresholds below 0.5W reshape product architectures for networked appliances sold across member states. The country's national energy regulator enforces consumption disclosure requirements that favor efficiency-optimized SKUs. Berlin and Munich smart home integrators pilot subscription-based consumable delivery for coffee machine deployments.
India
BIS certification alignment with IEC frameworks reduces duplicate testing costs for manufacturers entering the subcontinent's underserved smart appliance channel. The country's central electricity authority promotes demand-side management programs that elevate consumer awareness of connected energy monitoring. Bangalore and Hyderabad technology corridors concentrate firmware engineering talent for consumer IoT development.
Japan
METI appliance efficiency standards exceed global baselines, creating premium positioning for AI-enabled cooking devices with computer vision features. The country's national telecommunications regulator coordinates Wi-Fi spectrum allocation for dense urban smart home deployments. Osaka and Nagoya industrial zones maintain precision manufacturing capabilities for thermal sensor modules in smart ovens.
Smart Small Home Appliances Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in smart small home appliances, with platform-scale manufacturers commanding supply security advantages through captive semiconductor relationships. The middle tier fragments across regional OEMs competing on manufacturing velocity and certification agility. Two strategic archetypes dominate: ecosystem-integrated conglomerates leveraging cross-category platform lock-in, and component-specialist contract manufacturers optimizing unit economics at volume. Competitive moves concentrate on backward integration into Wi-Fi module supply and geographic expansion through harmonized certification strategies.
Among Asia-Pacific-based conglomerates, Samsung Electronics and Haier Smart Home exemplify the ecosystem-integrated archetype, each anchoring platform-centric smart home strategies that reduce consumer friction across multi-device deployments. Midea Group occupies a position within the manufacturing-scale tier, representing Guangdong province's production concentration. BSH Hausgeräte GmbH sits within the European premium specialist segment. These three anchors illustrate how competitive positioning stratifies across platform integration, manufacturing scale, and regional brand equity.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Haier Smart Home |
| Whirlpool Corporation |
| BSH Hausgeräte GmbH |
| Panasonic Corporation |
| Midea Group |
| Electrolux AB |
| GE Appliances |
| Others |
Value Network & Pricing Analysis
FCC electromagnetic emissions certification gates both supply qualification and price differentiation simultaneously, as manufacturers absorbing 12-16 week approval timelines must recoup compliance costs through premium positioning while mass-market SKUs compete on manufacturing velocity from Guangdong province.
Pricing Analysis
Contract-based long-term offtake agreements with hospitality fleet operators anchor volume pricing, while spot-market transactions through online retail channels serve price-sensitive renters and students. Price differentiation separates Matter-certified multi-protocol products from basic Wi-Fi-only units, with brand premiums widening between ecosystem-integrated conglomerates and regional OEMs. Cost compression in entry-tier smart plugs intensifies because Midea Group's manufacturing scale enables aggressive unit economics. Students and transient renters exhibit highest price sensitivity; hospitality procurement committees with subscription attach-rate targets show lowest.
Supply Chain Analysis
Taiwan and South Korea anchor Wi-Fi and Bluetooth module fabrication, while Guangdong province in China concentrates final assembly for smart kettles, toasters, and plugs. Motor assemblies draw from copper windings and rare earth magnet supplies whose price volatility strains mass-market vacuum and blender margins. Single-source vulnerability in semiconductor module supply exposes manufacturers to geopolitical disruption risks during Taiwan Strait tensions. Distribution runs through mass merchants for high-volume SKUs, with specialty stores and direct-to-consumer platforms capturing premium computer vision-enabled ovens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment, where FCC and EU Ecodesign certification timelines create structural barriers that compound with each protocol generation and efficiency standard revision.
For Market Incumbents: Consolidate backward integration into Wi-Fi module supply through captive semiconductor relationships, mirroring Samsung Electronics' foundry strategy. Deepen certification agility by pre-positioning technical files for EU AI Act conformity assessments before computer vision features trigger notified body review. These moves defend against emerging contract manufacturers from India leveraging BIS-IEC harmonization to compress compliance timelines.
For New Entrants and Emerging Players: Hospitality fleet management platform under-service creates white-space opportunity where unified device monitoring contracts concentrate procurement decisions. Target Germany and Netherlands coffee machine subscription pilots with direct-to-consumer bean-delivery models that displace traditional retail attachment. Go-to-market through sustainability-conscious urban millennial segments prioritizing packaging reduction over shelf convenience.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-enabled cooking recognition systems as edge-computing architectures require thermal sensor and computer vision module integration. Long-term viability favors acquisition of firmware engineering specialists with consumer IoT experience, given talent scarcity premiums straining mid-tier R&D budgets. Watch Matter protocol adoption rates as inflection indicator for ecosystem lock-in durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wi-Fi Modules | Samsung Electronics' foundry relationships reduce single-source exposure from Taiwan and South Korea concentration. |
| EU AI Act Conformity Pre-Positioning | Smart oven manufacturers with computer vision features restructure technical files ahead of notified body requirements. |
| Hospitality Fleet Platform Development | Centralized monitoring contracts in Germany and Netherlands create subscription attach-rate potential for maintenance analytics. |
| Edge Computing Architecture Migration | Cooking recognition algorithms on device-local processors reduce latency and address privacy concerns in Shenzhen households. |
| Direct-to-Consumer Subscription Launch | Coffee machine bean-delivery pilots displace retail attachment for sustainability-conscious buyers in urban European markets. |
Research Methodology
Desk research of customs records, FCC equipment authorization databases, and EU Ecodesign implementing measures preceded structured interviews with smart appliance product managers, firmware engineering directors, hospitality procurement officers, and semiconductor supply chain specialists. Primary fieldwork combined with secondary validation from SEC filings, GB standards administration notices, and BIS certification alignment circulars. Bottom-up unit shipment modeling across product type and feature tiers triangulated against top-down market value estimates from manufacturing cluster output data.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within each segmentation dimension: product architecture, connectivity protocol, end-user application, and distribution channel. CAGRs derive from logistic diffusion curves fitted to smart home ecosystem penetration rates, with inflection parameters calibrated against urban millennial household formation data from Shenzhen, Hangzhou, and Shanghai. Forecast inputs incorporate standby power threshold compliance costs and Matter protocol certification timeline compression.
Forecasts assume regulatory continuity in FCC electromagnetic emissions standards and EU Ecodesign Directive thresholds; material policy shifts in standby power mandates or AI Act risk classifications would require re-modeling. Specific risks include semiconductor supply disruption from geopolitical tension and copper price volatility affecting motor assembly costs. Recalibration cycles align with material shifts in interoperability protocol adoption and energy efficiency threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
United Kingdom Home Appliances Market
Home Appliances
India Home Appliances Market
Home Appliances
Japan Household Appliance Market
Home Appliances
United States Major Home Appliances Market
Home Appliances
Global Residential Water Heaters Market
Home Appliances
Italy Small Home Appliances Market
Home Appliances
Germany Washing Machine Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
GCC Major Home Appliances Market
Home Appliances
Americas Range Hood Market
Home Appliances
Bahrain Home Appliances Market
Home Appliances
Asia-Pacific Home Appliances Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
Kuwait Home Appliances Market
Home Appliances
Electrical Appliances Market
Home Appliances
Israel Home Needs Appliances Market