
 Russia Home Appliances Market | 2026-2036
Russia Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Home Appliances Market Analytics
The premium and commodity tiers in Russia's home appliances sector is decoupling along energy efficiency and smart connectivity lines. Haier Group leverages its localized manufacturing footprint to sustain competitive delivery timelines. LG Electronics differentiates through inverter technology leadership in climate-intensive applications. Samsung Electronics dominates the premium segment with connected kitchen ecosystems.
Home appliances encompass electrically powered mechanical devices designed for domestic tasks, typically operating on 220-230V at 50Hz with energy efficiency ratings from A+++ to D under EAEU technical regulation TR CU 004/2011. Their primary commercial purpose centers on reducing household labor burden while optimizing water and electricity consumption. Refrigerators anchor the product type segment due to universal household necessity and replacement cycles driven by compressor longevity. The price tier structure concentrates margin pools in premium and luxury bands where import substitution incentives favor domestic assembly. Online retail channels represent the fastest-growing distribution pathway as logistics networks penetrate secondary cities.
Russia's Federal Agency on Technical Regulating and Metrology (Rosstandart) enforces EAEU conformity assessment procedures that govern electromagnetic compatibility and low-voltage safety for all imported appliances. The Federal Service for Surveillance in Consumer Rights Protection and Human Wellbeing (Rospotrebnadzor) supplements these with sanitary-epidemiological requirements that shape material specifications for food-contact surfaces. Stakeholders must monitor evolving EAEU tariff realignments and localization quota thresholds to determine sourcing and assembly strategies.
Market Dynamics
Rosstandart's enforcement of EAEU technical regulation TR CU 004/2011 is compressing import timelines and forcing manufacturers to localize testing and certification infrastructure within Russia's borders.
Growth Catalysts
- TR CU 004/2011 compliance mandates:Mandatory energy efficiency labeling is accelerating replacement cycles among Moscow and St. Petersburg households seeking A+++ rated appliances.
- Housing completions in the Central Federal District:Residential construction clusters around Moscow are generating concentrated demand for full-suite appliance installations.
- Inverter compressor technology:Climate-adaptive cooling systems are penetrating Russian regions with extreme temperature differentials, expanding addressable market for refrigeration and climate control equipment.
Market Restraints
- Component import dependency:Semiconductor and compressor sourcing concentrates in East Asian supply chains, exposing assemblers to tariff volatility and logistics bottlenecks.
- Rospotrebnadzor material specifications:Sanitary-epidemiological requirements for food-contact surfaces restrict polymer and coating formulations, limiting supplier pools.
- Substitution by repair services:Extended compressor lifecycles and third-party refurbishment networks delay replacement purchases in secondary cities.
Strategic Opportunities
- Volga Federal District penetration:Underdeveloped retail infrastructure in Nizhny Novgorod and Kazan creates first-mover advantage for direct-to-installer distribution models.
- Smart grid integration:Convergence of appliance connectivity with regional utility demand-response programs enables premium positioning for networked home ecosystems.
- Localization quota thresholds:EAEU tariff realignments incentivize domestic assembly, rewarding capital deployment to Russian manufacturing zones.
Industry Challenges
- EAEU conformity assessment timelines:Extended certification procedures for electromagnetic compatibility testing delay product launches by multiple quarters.
- Legacy 220-230V infrastructure integration:Voltage stability variations across Russia's grid require hardened power management designs, complicating SKU rationalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Home Appliances Market |
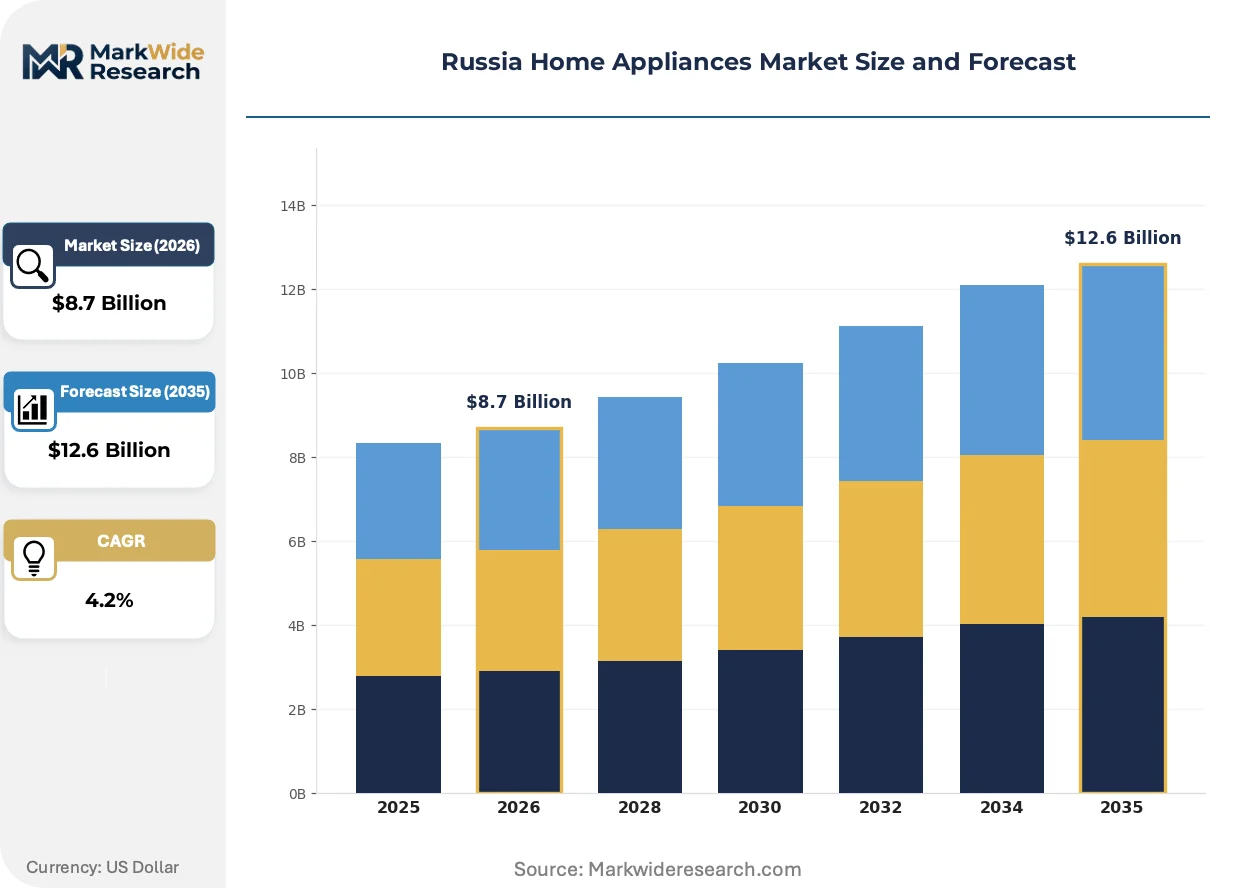
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Ovens, Dishwashers Price Tier: Economy, Mid-Range, Premium, Luxury Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Residential, Commercial, Industrial, Institutional |
| Companies Covered | Haier Group, Gorenje, LG Electronics, Midea Group, Arçelik, Samsung Electronics, Whirlpool (Indesit), Electrolux, BSH Hausgeräte (Bosch–Siemens), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Home Appliances Market Evolving Landscape
Inverter-driven climate adaptation and connected kitchen ecosystems are redefining competitive differentiation, while regulatory pressure on material safety is reshaping supplier qualification protocols.
Variable-speed compressor technology is integrating adaptive thermal management into residential refrigeration and air conditioning units. Urban buyers in Moscow and St. Petersburg are specifying inverter-equipped models for energy cost containment. This convergence is integrating climate resilience as a baseline specification, compressing margins on fixed-speed legacy platforms.
Rosstandart's phased implementation of stricter electromagnetic compatibility testing under TR CU 020/2011 is extending pre-market approval timelines. Manufacturers must maintain dual certification tracks for EAEU and residual national standards. Climate-intensive appliance categories face the steepest compliance burden, accelerating consolidation among testing-capable assemblers.
Channel disintermediation is fragmenting traditional retail concentration in Russia's home appliances sector. Secondary city buyers are bypassing distributor networks for manufacturer-direct platforms and installer-integrated purchasing. This behavioral shift is most pronounced in the Siberian Federal District, where logistics maturation enables fulfillment parity with Moscow-based retail.
Russia Home Appliances Market Segmentation
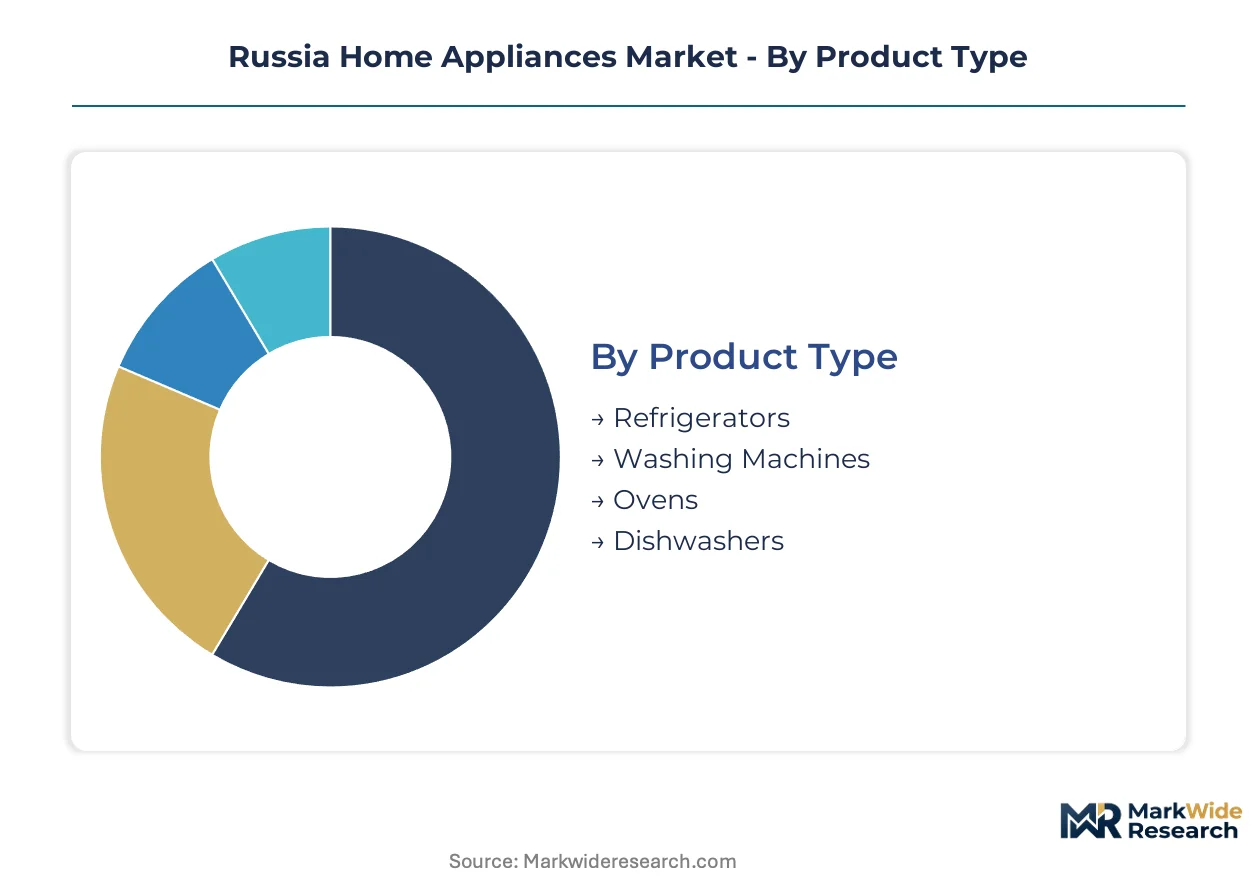
Segmentation in Russia's home appliances market exposes how EAEU regulatory pressure and regional purchasing power disparities fragment demand across technical specifications and channel preferences. Understanding these fault lines enables targeted positioning against Moscow's premium replacement cycles versus secondary cities' price-sensitive first-time purchases.
Product Type:
Volume concentrates in refrigeration and laundry equipment where universal household penetration meets compressor-driven replacement cycles, while premium margin pools concentrate in built-in kitchen systems.
- Refrigerators:Compressor longevity and frost-free technology specifications dominate purchasing criteria. Moscow and St. Petersburg households drive demand for inverter-equipped models with A+++ energy ratings under TR CU 004/2011 mandates.
- Washing Machines:Front-loading designs with variable-speed drum motors are displacing top-loading units in urban centers. Water efficiency regulations from Rospotrebnadzor constrain detergent formulation compatibility, narrowing supplier pools for drum seal materials.
- Ovens:Built-in electric models with pyrolytic cleaning functions command premium positioning in new Central Federal District residential developments.
- Dishwashers:Compact 45cm width units penetrate smaller Moscow apartments where kitchen square footage constraints dominate specification requirements.
Mature deployment sits with Refrigerators. Newer deployment is concentrated in Dishwashers.
Price Tier:
Margin distribution follows EAEU localization thresholds, with domestic assembly conferring tariff advantages that compress economy-tier pricing while import-dependent luxury segments absorb currency volatility.
- Economy:Basic functionality without inverter technology or smart connectivity. Demand clusters in secondary cities of the Volga and Siberian Federal Districts where repair service substitution delays replacement cycles.
- Mid-Range:Energy efficiency ratings between A+ and A+++ with partial smart features. This tier captures volume in St. Petersburg's residential upgrade market where housing completions outpace Moscow's pipeline.
- Premium:Full inverter technology suites and connected appliance ecosystems. Moscow's Central Federal District concentrates purchasing power here, with buyers specifying integrated kitchen systems from single-brand portfolios.
- Luxury:Bespoke finishes and professional-grade specifications for high-net-worth residential segments. Import dependency exposes this tier to EAEU tariff realignment volatility and extended Rosstandart certification timelines.
Volume leadership sits with Mid-Range. Margin expansion is climbing the fastest in Premium.
Distribution Channel:
Channel economics reflect logistics infrastructure maturity, with online fulfillment reaching parity in Moscow while specialty retail retains specification-intensive categories.
- Online Retail:Marketplace platforms and manufacturer-direct sites penetrate secondary cities where physical retail infrastructure remains underdeveloped. Logistics network maturation in the Siberian Federal District enables delivery timelines competitive with Moscow-based fulfillment.
- Supermarkets:Mass-market economy-tier appliances with impulse-purchase price points. Limited to compact refrigeration and small cooking appliances where specification complexity remains low.
- Specialty Stores:Consultative selling environments for premium built-in kitchen systems. Moscow and St. Petersburg concentrate showroom investment where installation services integrate with product specification.
- Wholesale:Developer-direct procurement for multi-unit residential projects in the Central Federal District. Bulk purchasing agreements align with housing completion timelines and EAEU conformity batch certification.
Established volume flows through Wholesale for new construction. Channel share is expanding most quickly in Online Retail.
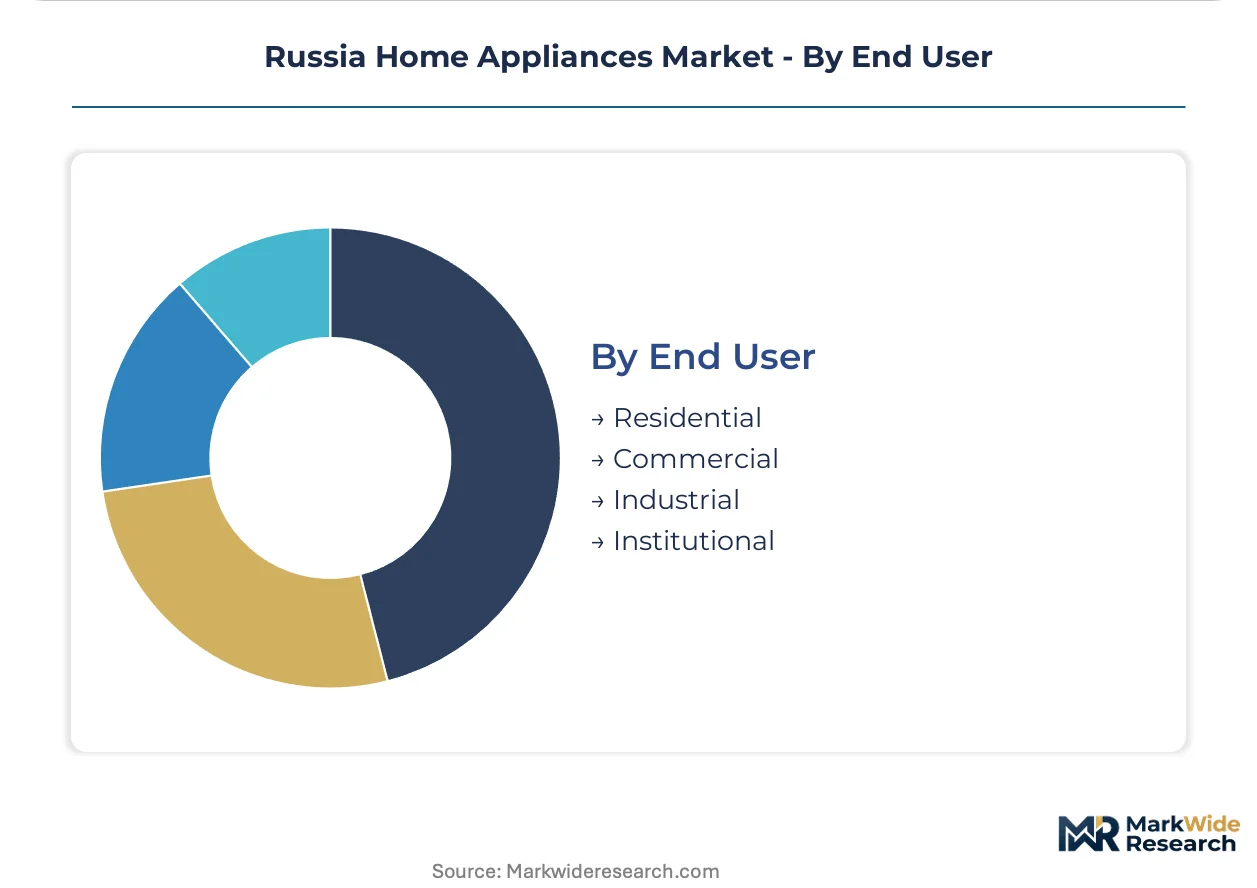
End User:
Demand composition splits between replacement-driven residential segments and project-based commercial procurement with diverging specification authority structures.
- Residential:Individual household purchasing decisions driven by energy cost containment and smart home integration preferences. Moscow's urban buyers specify connected ecosystems while secondary city demand prioritizes durability and repair service availability.
- Commercial:Hospitality and food service operations requiring commercial-grade refrigeration and dishwashing capacity. Rospotrebnadzor sanitary-epidemiological requirements constrain material specifications for food-contact surfaces.
- Industrial:Canteen and processing facility procurement with volume scale and maintenance contract requirements. Procurement authority typically resides with facility management rather than specialized kitchen equipment buyers.
- Institutional:Educational and healthcare facility purchasing subject to public procurement regulations. Extended tender timelines and localization quota requirements favor domestic assembly sources.
Volume concentration sits with Residential. Specification complexity is deepening fastest in Commercial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moscow anchors Russia's home appliances demand through concentrated housing completions and premium replacement cycles. The Central Federal District generates disproportionate volume against secondary cities where logistics maturity and purchasing power lag. EAEU regulatory harmonization shapes procurement patterns differently across Russia's federal districts.
Central Federal District
Moscow's residential construction pipeline and energy efficiency mandates under TR CU 004/2011 drive A+++ rated refrigerator and inverter-equipped washing machine demand. Rosstandart certification infrastructure concentrates testing capacity in this district. The Moscow-Tver-Vladimir corridor hosts the bulk of specialized retail showroom investment for premium built-in kitchen systems.
Northwestern Federal District
St. Petersburg's housing completion rates outpace Moscow's pipeline, generating mid-range tier volume for front-loading washing machines and frost-free refrigeration. The city's port infrastructure facilitates component import for domestic assembly operations. St. Petersburg's retail upgrade market captures energy-conscious buyers seeking partial smart connectivity features.
Volga Federal District
Nizhny Novgorod and Kazan present underdeveloped retail infrastructure where direct-to-installer distribution models gain traction. Economy-tier appliances dominate as repair service substitution delays replacement cycles. The region's industrial base supports emerging domestic assembly zones benefiting from EAEU localization quota thresholds.
Siberian Federal District
Logistics network maturation enables online retail fulfillment parity with Moscow timelines across Novosibirsk and Krasnoyarsk. Channel disintermediation fragments traditional distributor concentration as buyers adopt manufacturer-direct platforms. Extreme temperature differentials expand addressable market for climate-adaptive inverter compressor technology in refrigeration and climate control.
Southern Federal District
Rostov-on-Don anchors demand in a region where voltage stability variations require hardened power management designs. Wholesale procurement for multi-unit residential projects aligns with public procurement regulations and localization requirements. The district's agricultural processing facilities generate commercial-grade refrigeration demand subject to Rospotrebnadzor sanitary-epidemiological constraints.
Russia Home Appliances Market Competitive Landscape
Premium-margin players sit above commodity-margin players across energy efficiency certification and smart connectivity integration. The vendor base stratifies between localized assemblers with EAEU tariff advantages and import-dependent luxury specialists absorbing currency volatility. Three archetypes dominate: multinational platform brands with regional manufacturing footprints, European heritage manufacturers with premium positioning, and scale-driven Chinese producers optimizing cost structures. Competitive moves concentrate on domestic assembly capacity expansion and strategic partnerships with regional logistics operators.
Among the multinational platform brands, Haier Group, LG Electronics, and Samsung Electronics exemplify divergent strategic positioning. Haier's localized manufacturing footprint sustains competitive delivery timelines against EAEU compliance pressures. LG Electronics occupies a position emphasizing inverter technology leadership in climate-intensive applications. Samsung Electronics anchors the premium segment archetype through connected kitchen ecosystem integration. These three represent distinct responses to Rosstandart's TR CU 004/2011 enforcement and Rospotrebnadzor material specification requirements.
| Leading Market Players |
|---|
| Haier Group |
| Gorenje |
| LG Electronics |
| Midea Group |
| Arçelik |
| Samsung Electronics |
| Whirlpool (Indesit) |
| Electrolux |
| BSH Hausgeräte (Bosch–Siemens) |
| Others |
Value Network & Pricing Analysis
TR CU 004/2011 energy efficiency mandates gate qualified supply and premium-tier pricing access, compressing margins for non-compliant assemblers while rewarding certified domestic manufacturers with tariff-advantaged positioning in Moscow's replacement-driven demand.
Pricing Analysis
Value-based pricing anchored to energy cost savings dominates Moscow and St. Petersburg markets, with A+++ rated refrigerators and inverter-equipped washing machines commanding substantial premiums over fixed-speed alternatives. Price differentiation rests on certification tier under EAEU technical regulations and localized assembly status, with domestic production conferring tariff insulation that economy-tier imports cannot match. Cost compression in the economy tier is intensifying as repair service substitution delays replacement cycles in secondary cities. Developer-direct procurement for Central Federal District housing completions exhibits lowest price sensitivity, while Volga Federal District household buyers demonstrate highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with East Asian semiconductor and compressor suppliers, exposing Russian assemblers to logistics bottlenecks and currency volatility. Component sourcing draws from China, South Korea, and Japan for critical inputs including inverter modules, variable-speed motors, and polymer formulations for food-contact surfaces. Supply chain risk centers on extended Rosstandart electromagnetic compatibility certification timelines that delay product launches. Distribution runs through manufacturer-direct platforms penetrating secondary cities alongside traditional wholesale channels serving multi-unit residential developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's home appliances market functions as a cost-of-compliance story, where TR CU 004/2011 certification requirements create a barrier-to-entry moat that protects capitalized domestic assemblers from import-dependent competitors.
For Market Incumbents: Acquire testing and certification infrastructure within Russia's borders to compress EAEU conformity assessment timelines against emerging Chinese competitors. Expand inverter compressor assembly capacity in the Central Federal District to capture Moscow's premium replacement cycles before LG Electronics and Samsung Electronics consolidate connected kitchen ecosystems. Defensive positioning requires backward integration into polymer formulation capabilities that satisfy Rospotrebnadzor sanitary-epidemiological specifications.
For New Entrants and Emerging Players: EAEU localization quota thresholds in Russia open a window for domestic assembly partnerships that bypass tariff exposure on fully-imported units. Target the Volga Federal District's underdeveloped retail infrastructure with direct-to-installer distribution models, where economy-tier demand concentrates and first-mover advantage remains available. Penetrate through smart grid integration offerings aligned with regional utility demand-response programs, enabling premium positioning without competing head-to-head with established connected kitchen ecosystems.
For Investors and Strategic Acquirers: Housing completion permits in the Central Federal District are the leading indicator that wholesale procurement volume will concentrate among domestic assembly sources over the medium-term horizon. Acquisition targets should emphasize assemblers with captive EAEU certification capabilities and established relationships with Moscow-based developers. Monitor Rosstandart's phased TR CU 020/2011 electromagnetic compatibility implementation timeline as the signal for consolidation pressure among testing-capable players.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Capacity Expansion | Captures EAEU tariff advantages while compressing delivery timelines to Moscow developers. |
| Inverter Technology Licensing | Enables climate-adaptive product positioning in Siberian Federal District extreme temperature markets. |
| Direct-to-Installer Distribution | Bypasses fragmented retail infrastructure in Nizhny Novgorod and Kazan for first-mover penetration. |
| Smart Grid Integration Partnership | Aligns premium appliance ecosystems with regional utility demand-response programs. |
| Backward Integration into Polymer Formulation | Satisfies Rospotrebnadzor material specifications while reducing supplier pool constraints. |
Research Methodology
Multi-period observation of housing completion permits, EAEU certification timelines, and regional logistics infrastructure maturation anchored the trend analysis, supplemented by interviews with appliance category managers at retail chains, procurement directors at residential developers, Rosstandart compliance officers, and compressor technology engineers. Secondary validation drew from EAEU technical regulation filings, customs import records, regional utility demand-response program disclosures, and Federal State Statistics Service construction data. Bottom-up segment sizing triangulated against top-down macroeconomic projections.
Segment-weighting across product type, price tier, distribution channel, and end-user categories structured the analytical framework, with regional purchasing power indices and housing completion pipelines incorporated throughout the forecast period. CAGRs were derived from replacement cycle modeling and new construction absorption rates, with inverter technology penetration curves and EAEU localization quota compliance trajectories serving as primary industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for smart grid integration and connected appliance ecosystems would alter the outlook for premium-tier margin expansion. Forecasts reflect assumptions regarding regulatory enforcement continuity, currency stability, and logistics infrastructure development that external shocks could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
North America Electric Fireplace Market
Home Appliances
Argentina Home Appliances Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
Europe Small Home Appliances Market
Home Appliances
Undercounter Refrigerators Market
Home Appliances
Israel Home Needs Appliances Market
Home Appliances
Household Fridge Market
Home Appliances
South Korea Home Appliances Market
Home Appliances
Built-In Hobs Market
Home Appliances
Range Hood Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
Germany Small Home Appliance Market
Home Appliances
Brazil Home Appliances Market
Home Appliances
Europe Washing Machine Market
Home Appliances
Europe Laundry Appliances Market
Home Appliances
Italy Home Appliances Market