
 Europe Home Appliances Market | 2026-2036
Europe Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Home Appliances Market Foresight
Subscription-based appliance leasing is rewriting competitive dynamics in Europe by lowering upfront barriers for younger households and property managers. BSH Hausgeräte GmbH leverages its extensive service network to bundle maintenance into recurring contracts. Miele & Cie. KG anchors premium positioning through exceptional durability ratings and direct channel control. Haier Europe competes aggressively on connected-device integration and localized manufacturing footprint.
Europe home appliances encompass electrically powered devices for domestic food preservation, textile care, cooking, and cleaning, typically operating at 220-240V/50Hz with energy efficiency ratings scaled from A to G under EU standardized labeling. Their primary commercial purpose centers on reducing household labor time while minimizing electricity and water consumption against rising utility tariffs. Refrigerators dominate installed base value across the region, though robotic solutions represent the fastest-expanding technology segment as autonomous floor-care devices penetrate Southern and Eastern European markets. Energy-efficient models command the deepest margin pools as Ecodesign requirements and consumer electricity cost sensitivity converge.
The EU Ecodesign for Sustainable Products Regulation and REACH chemical compliance frameworks are mandating repairability scoring, recycled content minimums, and restricted substance lists that reshape product development cycles and supply chain qualification. ECHA substance evaluations further pressure manufacturers to reformulate coatings, plastics, and electronic components. Stakeholders must monitor how right-to-repair enforcement and digital product passport requirements will alter warranty structures, spare parts pricing, and the competitive viability of import-dependent brands.
Market Dynamics
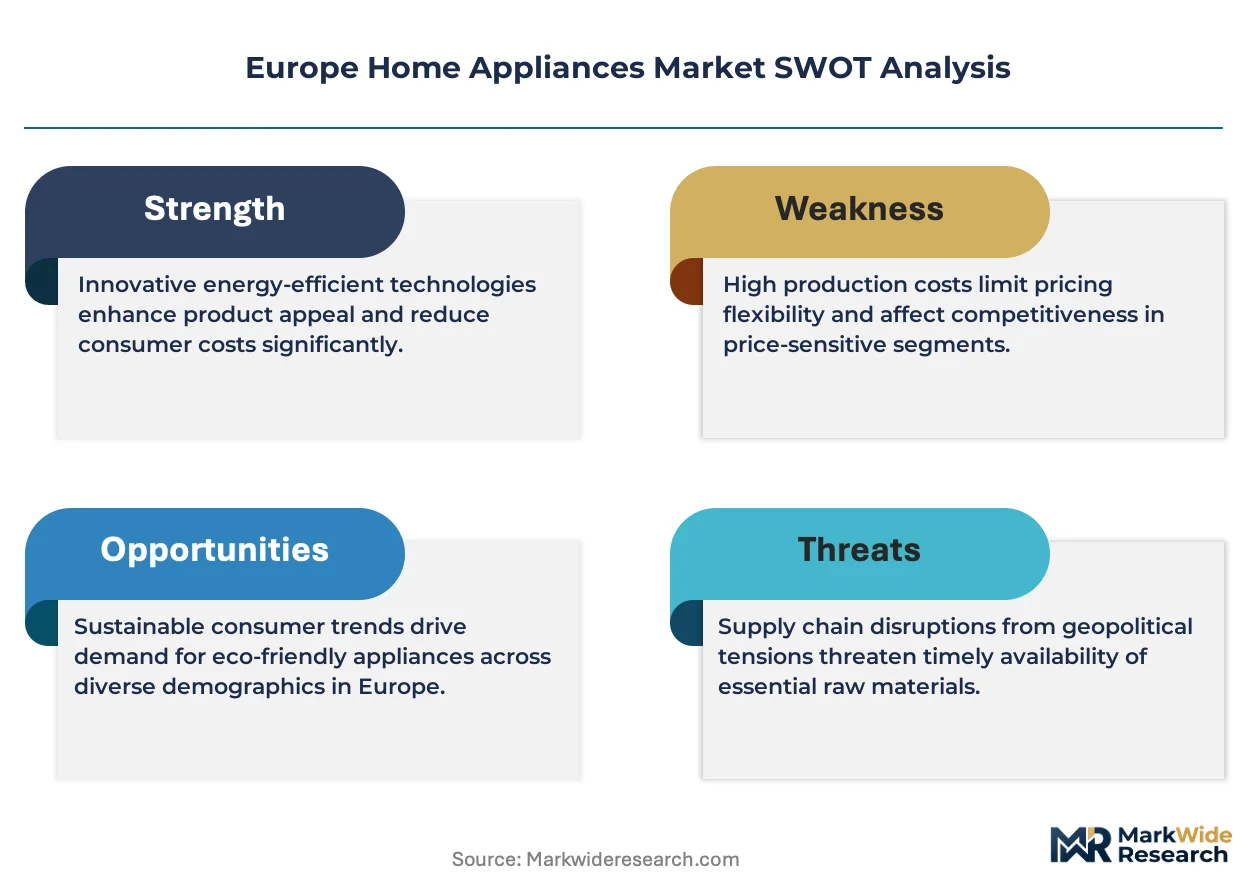
The EU Ecodesign for Sustainable Products Regulation is compressing product development timelines while forcing manufacturers to redesign supply chains around repairability scoring and recycled content mandates.
Growth Catalysts
- REACH chemical compliance:Reformulation requirements for coatings and plastics are accelerating R&D investment in bio-based alternatives, creating first-mover advantages for compliant suppliers.
- Hospitality sector upgrades:Hotel chains across Spain and Portugal are replacing aging laundry and refrigeration equipment with connected, energy-efficient models to meet corporate sustainability targets.
- Right-to-repair enforcement:Mandated spare parts availability and standardized disassembly protocols are extending product lifecycles and opening aftermarket revenue streams for service networks.
Market Restraints
- Copper and rare earth price volatility:Electric motor and compressor manufacturers face margin compression from concentrated Chilean and Chinese supply.
- Technical limitation in solid-state cooling:Thermoelectric refrigeration remains thermally inefficient for household-scale food preservation, blocking mass-market penetration.
- CE marking friction:Divergent national interpretations of electromagnetic compatibility testing create duplicate certification costs for cross-border distribution.
Strategic Opportunities
- Eastern European underpenetration:Robotic floor-care devices hold sub-15% household penetration in Poland and Romania versus Western European averages.
- EU Green Deal incentives:National rebate programs for A-rated appliance replacements are accelerating replacement cycles in Italy and France.
- Channel innovation via property management platforms:Build-to-rent operators in Germany are bundling appliance subscriptions into tenant service packages.
Industry Challenges
- Skill gap in refrigerant handling:F-Gas Regulation phase-down demands technicians certified in flammable A2L and A3 refrigerant systems that remain scarce across Southern Europe.
- Digital product passport integration:Manufacturers must rebuild ERP systems to capture component-level traceability data for regulatory disclosure by 2027.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Home Appliances Market |
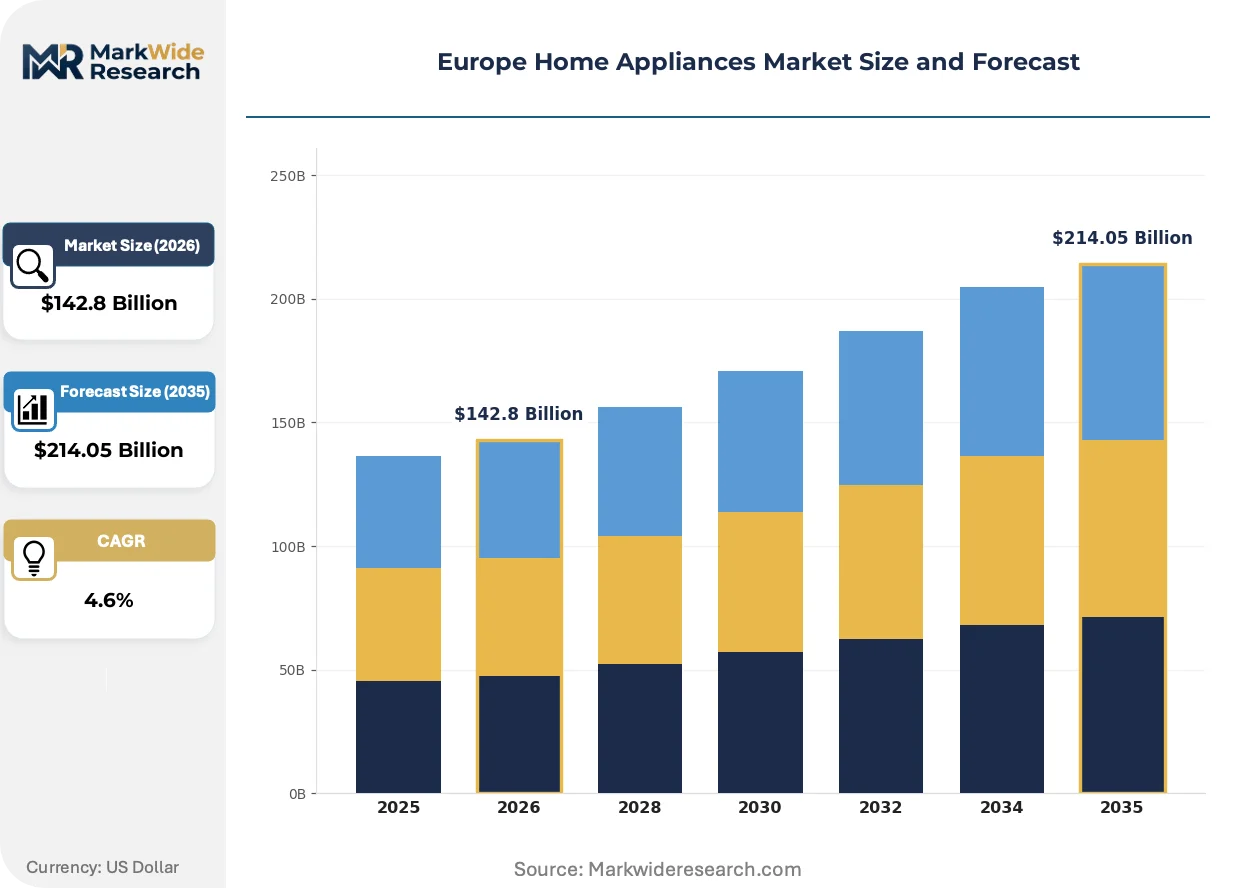
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $214.05 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washers, Ovens, Microwaves End User: Households, Hotels, Restaurants, Care Facilities Distribution Channel: Online Retail, Direct Sales, Department Stores, Specialty Outlets Technology: Smart Appliances, Energy-Efficient, Connected Devices, Robotic Solutions |
| Companies Covered | Arçelik A.Ş., Miele & Cie. KG, BSH Hausgeräte GmbH, Samsung Electronics, LG Electronics, Electrolux AB, Haier Europe, Gorenje Hisense, Whirlpool Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Home Appliances Market Shifts & Advancements
Connected appliance ecosystems are shifting value capture from hardware sales to recurring software and service revenue, while regulatory pressure on material circularity accelerates design-for-disassembly investments.
AI-enabled predictive maintenance is digitizing service delivery models across the European installed base. Mid-market dishwasher and laundry OEMs are embedding vibration and current-draw sensors to anticipate component failures before warranty claims materialize. This capability is digitizing traditional break-fix service relationships into subscription-based uptime guarantees that lock in multi-year customer contracts.
The EU F-Gas Regulation is banning refrigerants with global warming potential above 150 in new household refrigeration from 2025. Compressor manufacturers are retooling production lines for propane and isobutane alternatives that demand redesigned safety systems and technician retraining. Southern European markets with higher ambient temperatures face the steepest compliance costs as heat pump performance thresholds tighten simultaneously.
Younger households in urban France and Germany are rejecting ownership in favor of flexible-use appliance subscriptions. Property technology platforms are disintermediating traditional retail by offering bundled kitchen packages with embedded maintenance and upgrade rights. This behavior is most visible in Berlin and Munich, where rental housing stock dominates and tenant turnover drives regular equipment refresh cycles.
Europe Home Appliances Market Segmentation
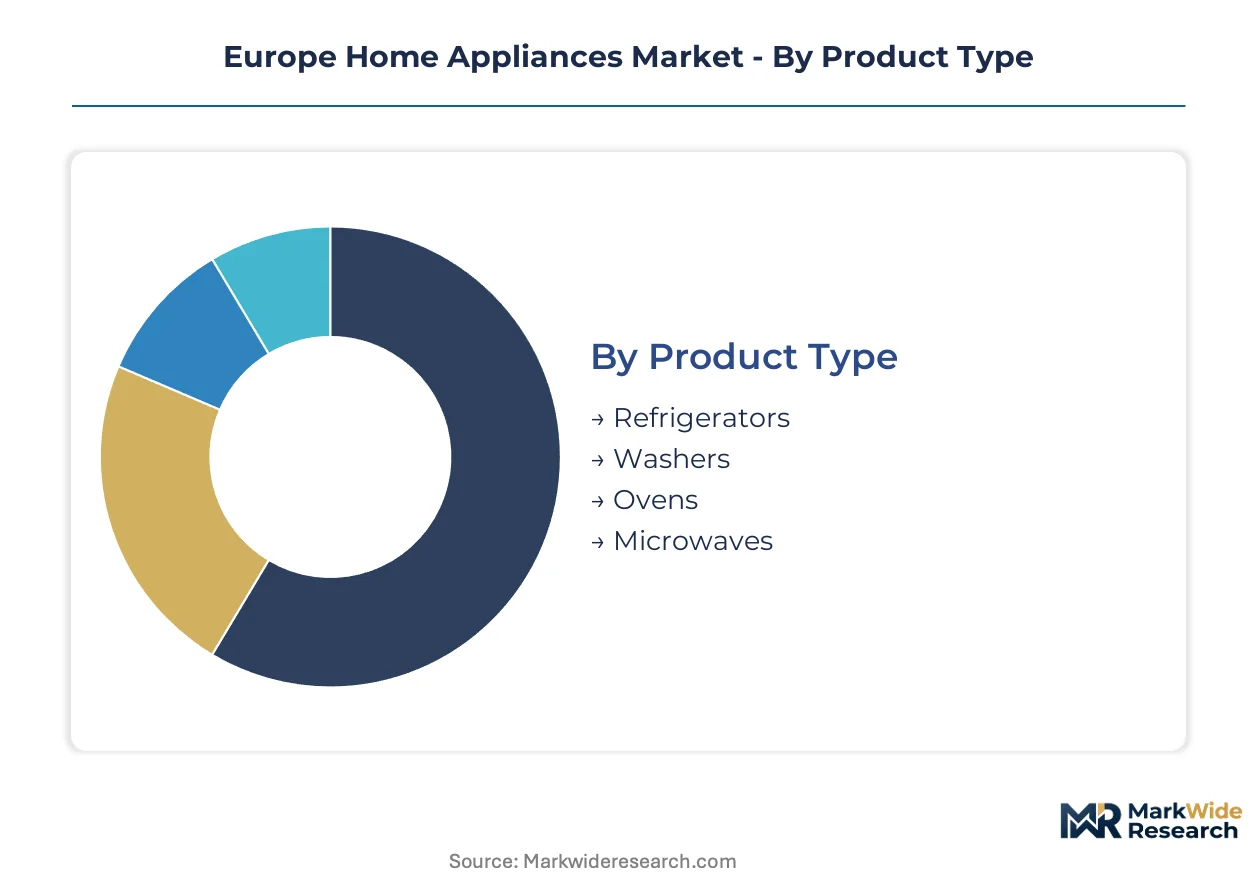
Segmentation in the Europe Home Appliances Market reveals how regulatory pressure and channel innovation reshape value capture across distinct buyer profiles. Understanding these divides exposes where Ecodesign compliance costs concentrate and where subscription models unlock new revenue pools.
Product Type:
Domestic labor reduction needs span from food preservation to textile care, with each category carrying different energy intensity and replacement cycle profiles.
- Refrigerators:Compression-based cooling systems operating at 220-240V dominate installed base value across Germany, France, and Italy. EU F-Gas Regulation mandates are forcing compressor retooling for flammable refrigerants, elevating compliance costs for manufacturers serving Southern European markets with higher ambient temperatures.
- Washers:Front-loading drum systems with variable-speed direct drive motors deliver A-rated efficiency under standardized EU labeling. German households and Spanish hotel chains are accelerating replacement cycles as water tariffs rise and corporate sustainability targets tighten.
- Ovens:Convection and pyrolytic self-cleaning configurations serve baking-intensive Mediterranean cuisines. Italian and French demand concentrates in built-in formats for kitchen-integrated renovations.
- Microwaves:Magnetron-based rapid heating appliances occupy compact urban kitchens across Paris and Berlin rental stock. Lower replacement barriers make this segment most vulnerable to subscription-based disintermediation.
The dominant share belongs to Refrigerators, while Robotic Solutions from adjacent categories are closing the gap fastest.
End User:
Procurement authority fragments between individual consumers and institutional buyers with diverging total-cost-of-ownership calculations.
- Households:Individual purchasers operating on 10-15 year replacement cycles in owned housing versus flexible subscription preferences in German and French rental markets. Electricity cost sensitivity drives A-rated model premiums as utility tariffs climb.
- Hotels:Corporate procurement departments in Spanish and Portuguese chains replacing laundry and refrigeration fleets to meet sustainability disclosures under CSRD. Connected asset monitoring reduces downtime costs in high-turnover properties.
- Restaurants:Commercial kitchen operators requiring certified food safety compliance and rapid recovery cycles. Italian trattoria and French bistro segments favor robust mechanical simplicity over connected features.
- Care Facilities:Elderly residential homes across Italy and Germany prioritizing accessibility interfaces and hygiene-automation. Public procurement frameworks extend sales cycles but lock in multi-year service contracts.
Households command the volume base, though Hotels are expanding their share most aggressively through fleet electrification mandates.
Distribution Channel:
Channel power is shifting from retail floor space to digital platforms and property-integrated bundling.
- Online Retail:Pure-play e-commerce and omnichannel platforms capturing urban millennial demand with comparison tools and subscription financing. Last-mile logistics networks determine competitive viability across Polish and Romanian expansion markets.
- Direct Sales:Manufacturer-controlled channels enabling premium positioning and service bundling. Miele and BSH leverage this route to anchor maintenance-inclusive contracts in affluent German suburbs.
- Department Stores:Declining foot traffic in French and Italian urban centers reduces this channel to clearance and promotional event dependency. Surviving formats integrate kitchen design consultation to justify physical presence.
- Specialty Outlets:Independent retailers with installation and repair capabilities retaining loyalty in older demographics and rural geographies. REACH compliance documentation requirements favor established distributors with qualified technical staff.
Online Retail has seized the volume lead, while Direct Sales is climbing the fastest through subscription attach rates.
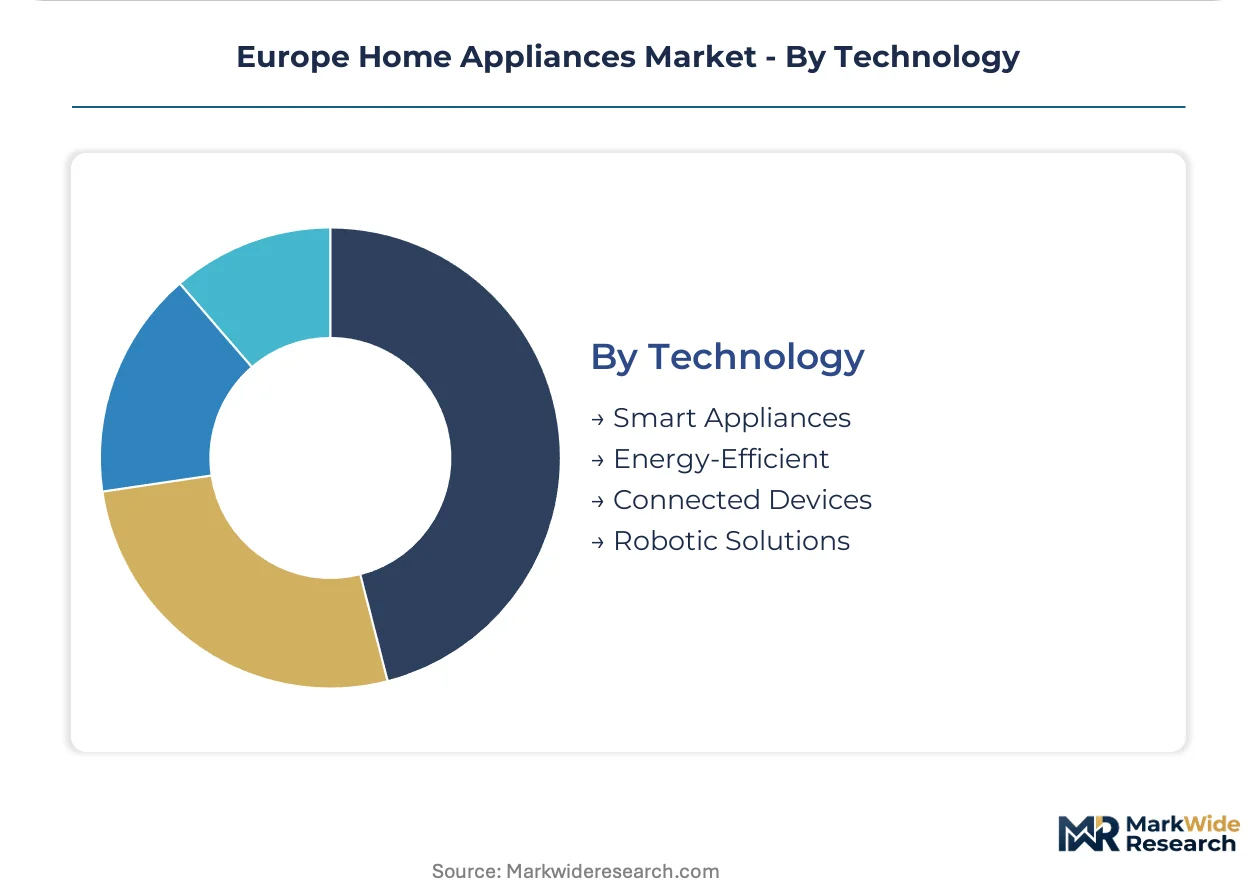
Technology:
Intelligence and efficiency layers are redefining product architecture and margin structure simultaneously.
- Smart Appliances:Wi-Fi-enabled units with app-based control and usage analytics. Data privacy constraints under GDPR limit cloud functionality scope in German and French deployments.
- Energy-Efficient:A-rated and above models qualifying for national rebate programs under EU Green Deal implementation. Italian Superbonus incentives have accelerated heat pump dryer adoption in Northern regions.
- Connected Devices:Ecosystem-integrated products communicating across HVAC, lighting, and security platforms. Interoperability standards fragmentation between proprietary protocols constrains mass-market penetration.
- Robotic Solutions:Autonomous navigation systems for floor care penetrating Southern and Eastern European markets from Western installed base saturation. Sub-15% household penetration in Poland and Romania against 40%+ in Germany creates expansion runway.
Energy-Efficient models hold the deepest installed base, with Robotic Solutions gaining share fastest through Eastern European penetration acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal incentives and national rebate programs are accelerating replacement cycles across the region, with member states deploying differentiated subsidy schemes tied to energy efficiency ratings. Urban rental markets and hospitality fleet upgrades concentrate demand in Western European metropolitan corridors.
Germany
Build-to-rent operators in Berlin and Munich bundle appliance subscriptions into tenant service packages, driving flexible-use adoption among younger households. The Federal Office for Economic Affairs and Export Control administers BAFA rebates for A-rated replacements. BSH Hausgeräte GmbH anchors its direct sales network in affluent suburban corridors around Stuttgart and Munich.
France
Parisian rental stock dominates microwave and compact appliance demand as tenant turnover drives regular refresh cycles. The Agence de la Transition Écologique channels MaPrimeRénov incentives toward heat pump dryer adoption in Île-de-France. Miele & Cie. KG maintains premium positioning through manufacturer-controlled channels in high-income Paris suburbs.
Italy
Built-in oven demand concentrates in kitchen-integrated renovations across Lombardy and Emilia-Romagna, serving baking-intensive Mediterranean cuisines. The Superbonus 110% program has accelerated heat pump appliance penetration in Northern regions. Electrolux AB leverages Italian manufacturing footprint to serve Southern European hospitality upgrades.
Spain
Hotel chains in Barcelona and Madrid replace aging laundry fleets with connected, energy-efficient models to meet CSRD sustainability disclosures. The Instituto para la Diversificación y Ahorro de la Energía administers regional rebate programs for commercial efficiency upgrades. Haier Europe competes on localized production serving Iberian Peninsula distribution.
Poland
Robotic floor-care devices hold sub-15% household penetration against 40%+ German averages, creating expansion runway for autonomous navigation systems. The National Fund for Environmental Protection and Water Management funds efficiency retrofits in multifamily housing. Arçelik A.Ş. targets emerging middle-class demand through value-tier positioning in Warsaw and Kraków metropolitan areas.
Europe Home Appliances Market Competitive Landscape
On the supply side, the industry is consolidating around integrated manufacturers with captive service networks and subscription-capable distribution infrastructure. Tiered competitive positioning separates premium durability specialists, mass-market connected-device platforms, and value-oriented regional assemblers. Dominant competitive moves include vertical integration into maintenance services and strategic partnerships with property technology platforms.
Within the premium-tier vector, Miele & Cie. KG and BSH Hausgeräte GmbH exemplify manufacturer-controlled channel strategies that embed long-term service relationships into hardware transactions. Haier Europe occupies a position at the connected-device intersection, leveraging scale advantages in smart home ecosystem integration. Samsung Electronics and LG Electronics represent the Korean conglomerate archetype, competing through vertical integration in component supply and display technology.
| Leading Market Players |
|---|
| Arçelik A.Ş. |
| Miele & Cie. KG |
| BSH Hausgeräte GmbH |
| Samsung Electronics |
| LG Electronics |
| Electrolux AB |
| Haier Europe |
| Gorenje Hisense |
| Whirlpool Corporation |
| Others |
Supply & Pricing Matrix
Copper and rare earth price volatility from concentrated Chilean and Chinese supply determines both the spread between A-rated premium tiers and entry-level economy positioning and the geographic retooling decisions compressor manufacturers face under EU F-Gas Regulation mandates.
Pricing Analysis
Certification level under EU energy labeling creates the primary spread between A-rated heat pump dryers commanding rebate-eligible premiums and G-rated legacy models facing channel exclusion. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling intensity and connected-device feature depth. Cost compression in entry-level refrigeration is intensifying because flammable refrigerant safety system redesigns elevate compliance costs disproportionately for lower-margin producers. Property management platforms exhibit lowest price sensitivity due to total-cost-of-ownership subscription models, while individual Polish and Romanian households remain most responsive to point-of-sale discounting.
Supply Chain Analysis
Steel and copper feedstock supply concentrates in Germany, Italy, and China, with compressor motor laminations and electronic control modules drawing from Taiwanese and South Korean semiconductor fabrication. Rare earth magnet dependencies for high-efficiency direct drive motors rest on Chinese processing capacity, while polymer formulations for interior liners hinge on REACH-compliant European compounders. Single-source vulnerability in A2L refrigerant chemical supply creates bottleneck risk as the F-Gas Regulation phase-down accelerates. Distribution runs through omnichannel platforms capturing urban demand, with direct manufacturer channels penetrating affluent suburban corridors for premium service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based appliance access models threaten traditional hardware margin capture, forcing incumbents to defend against disintermediation by property technology platforms bundling maintenance into tenant service packages.
For Market Incumbents: Harden service network exclusivity through captive technician certification programs addressing the Southern European skill gap in flammable refrigerant handling. Deepen backward integration into compressor remanufacturing to capture circular economy value pools as right-to-repair mandates extend product lifecycles. Lock in multi-year uptime guarantee contracts before predictive maintenance capabilities commoditize across mid-market competitors. For New Entrants and Emerging Players: Polish and Romanian robotic floor-care underpenetration offers white-space expansion at sub-15% household penetration against Western European saturation. Target hospitality fleet procurement in Spanish and Portuguese hotel chains replacing aging laundry equipment under CSRD sustainability disclosures. Deploy last-mile logistics partnerships with existing consumer electronics distributors to bypass established appliance retail gatekeeping. For Investors and Strategic Acquirers: The market sits at a regulatory compression phase that favors service-integrated manufacturers with ERP systems capable of digital product passport compliance by the 2027 disclosure deadline. Long-term viability hinges on repairability scoring competence and spare parts logistics infrastructure rather than pure manufacturing scale. Monitor technician certification program enrollment rates across Italy and Spain as early signal of compliance cost absorption capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Integration | BSH Hausgeräte bundles maintenance into recurring contracts, locking in tenant turnover-driven refresh cycles. |
| Refrigerant Safety System Redesign | Compressor OEMs retool for propane alternatives as EU F-Gas Regulation bans high-GWP refrigerants from 2025. |
| Predictive Maintenance Capability | AI-enabled vibration sensors digitize break-fix relationships into subscription-based uptime guarantees. |
| Digital Product Passport Compliance | ERP system rebuilds capture component-level traceability data for regulatory disclosure requirements. |
| Eastern European Distribution Expansion | Last-mile logistics networks determine competitive viability in Polish and Romanian robotic floor-care markets. |
Research Methodology
A spread of perspectives from product development executives at major OEMs, regulatory affairs specialists tracking Ecodesign implementation, hospitality procurement directors managing fleet replacements, and aftermarket service network managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against EU ECHA substance evaluation databases, national customs records for compressor and motor trade flows, and SEC filings from listed appliance manufacturers. Bottom-up shipment data triangulated against top-down energy efficiency rebate program disbursement records.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, end user archetype, distribution channel power, and technology intelligence layer. CAGRs derived from replacement cycle modeling against efficiency upgrade incentive program budgets and hospitality sector capital expenditure patterns. Forecast inputs incorporated F-Gas Regulation phase-down timelines and REACH chemical compliance cost pass-through assumptions.
Practitioners should monitor refrigerant handling technician certification program enrollment rates and digital product passport pilot program disclosures for early signals of compliance cost trajectory shifts. Forecasts reflect assumptions about subsidy program continuity and raw material price normalization that could revise materially. Cross-checking against national energy efficiency rebate disbursement databases and ECHA substance restriction proposal timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Smart Small Home Appliances Market
Home Appliances
US Household Appliances Market
Home Appliances
India Home Appliances Market
Home Appliances
Qatar Major Home Appliances Market
Home Appliances
China Small Home Appliances Market
Home Appliances
Built-In Hobs Market
Home Appliances
Refrigerator Market
Home Appliances
Electric Fireplace Market
Home Appliances
Americas Range Hood Market
Home Appliances
South Africa Home Appliances Market
Home Appliances
North America Built-In Home Appliances Market
Home Appliances
Europe Personal Care Appliances Market
Home Appliances
Japan Small Home Appliances Market
Home Appliances
Italy Home Appliances Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
South Korea Major Home Appliances Market