
 Home Appliance (Wet and Cold) Market | 2026-2036
Home Appliance (Wet and Cold) Market Size, Share, and Industry Trends Forecast 2026-2036
Home Appliance (Wet and Cold) Market Foresight
Chinese white-goods manufacturing capacity is restructuring around inverter-compressor platforms and modular refrigeration architectures. Samsung Electronics leverages its semiconductor supply chain to embed AI-driven temperature management across its wet and cold portfolios. Haier Group anchors its position through backward integration into compressor production and captive control of distribution networks in domestic and Southeast Asian markets.
Home Appliance (Wet and Cold) encompasses electrically powered equipment designed for thermal regulation of perishables and textile cleaning, typically operating between minus twenty-five and plus ten degrees Celsius for cold appliances and utilizing centrifugal forces above four hundred RPM for wet-cycle systems. Refrigerators and washing machines constitute the volume core, with inverter technology commanding margin premiums due to compressor efficiency gains and variable-speed control. Smart Technology integration is expanding fastest among urban households, while standalone installation formats retain dominant share in retrofit-oriented replacement cycles across mature housing stocks.
The US Department of Energy enforces minimum efficiency standards that reset product cost structures every three to seven years, while Europe's Ecodesign framework and F-Gas Regulation mandate phasedown of hydrofluorocarbon refrigerants with explicit GWP thresholds. China's GB standards and NEEQ labeling program impose parallel efficiency tiers that manufacturers must navigate for market access. Stakeholders must monitor regulatory divergence between efficiency metrics and refrigerant chemistries when allocating R&D budgets across regional product lines.
Market Dynamics
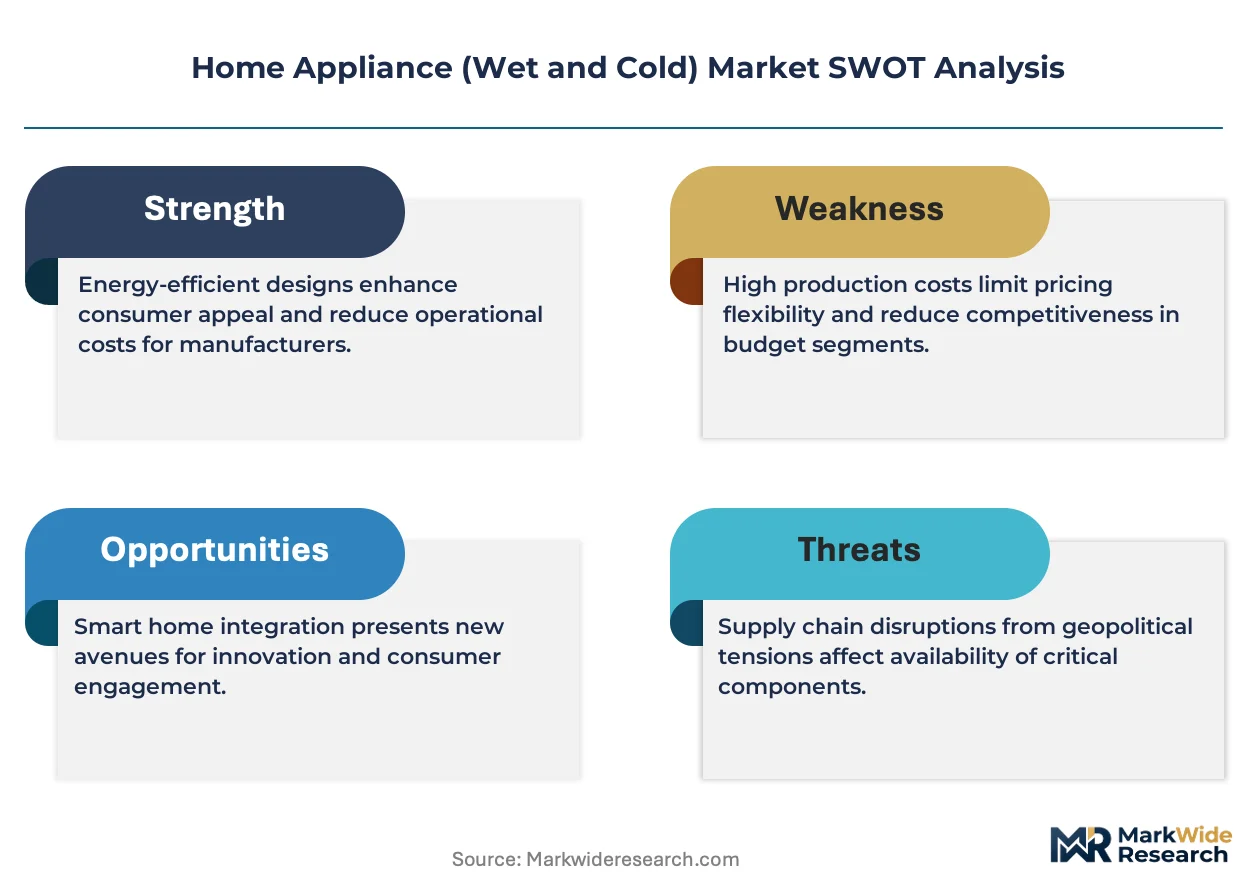
Europe's F-Gas Regulation is forcing refrigerant chemistry transitions across compressor architectures, while inverter-motor platforms absorb R&D budgets previously allocated to standalone mechanical designs.
Growth Catalysts
- Urban hospitality cluster expansion:Commercial kitchens in dense metropolitan zones are scaling wet and cold appliance fleets to meet tightening food safety protocols and HACCP-aligned inspection regimes.
- Inverter-compressor efficiency mandates:China's GB standards and NEEQ labeling tiers reward variable-speed refrigeration systems with preferential market access and procurement eligibility.
- Smart home integration pull:Residential renovation cycles in China's tier-one cities are accelerating replacement purchases through IoT-enabled appliance ecosystems and centralized home energy management.
Market Restraints
- Refrigerant input cost volatility:Hydrofluorocarbon phase-down timelines under Europe's F-Gas Regulation are compressing supply availability for legacy compressor architectures before lower-GWP alternatives achieve scale economics.
- Semiconductor supply concentration:Inverter control boards and power modules depend on fabrication capacity concentrated in East Asian foundry clusters, exposing finished goods producers to allocation rationing.
- Copper and steel price transmission:Sheet metal enclosures and refrigerant tubing absorb commodity swings that manufacturers cannot fully pass through in price-sensitive replacement cycles.
Strategic Opportunities
- Modular refrigeration architectures:Flexible cabinet platforms that accommodate multiple refrigerant circuits and door configurations are capturing specification share from fixed-format legacy designs.
- Rural electrification corridors:India's village-level grid extension and appliance ownership programs are opening first-time buyer segments previously excluded by infrastructure gaps.
- Appliance-as-service models:Subscription-based washing machine and refrigeration access is penetrating European multi-unit housing through property management channel partnerships.
Industry Challenges
- Refrigerant handling certification gaps:Technician training pipelines for lower-GWP chemistries lag deployment timelines, delaying service network readiness for next-generation systems.
- Legacy control system integration:Smart appliance connectivity protocols must bridge proprietary home automation ecosystems without fragmenting firmware development across incompatible standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Appliance (Wet and Cold) Market |
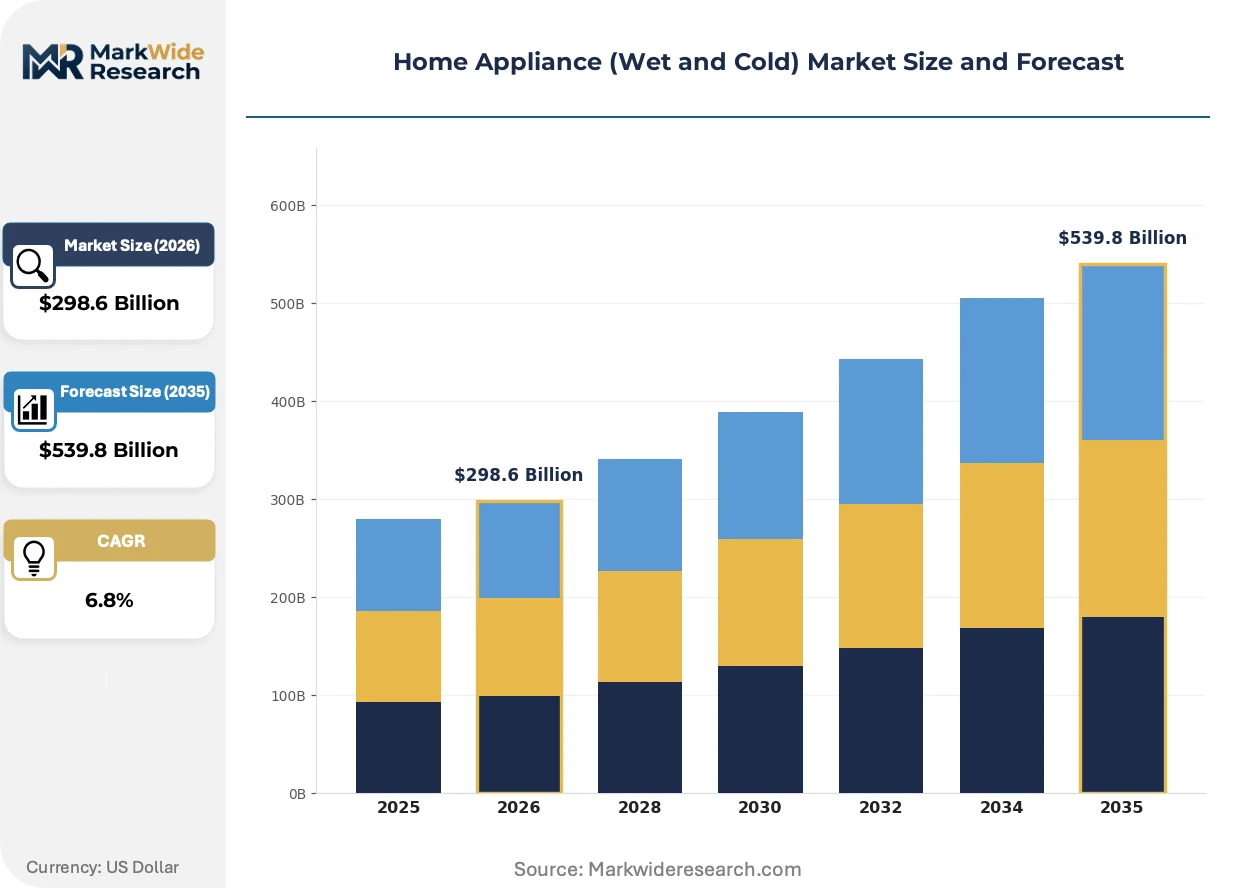
| Market Size in 2026 | $298.6 Billion |
| Market Size in 2035 | $539.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Freezers, Ice Makers, Washing Machines Technology: Smart Technology, Energy Efficient, Traditional, Inverter End User: Households, Commercial Kitchens, Hotels, Laundries Installation: Built-in, Standalone, Under-counter, Portable |
| Companies Covered | Whirlpool Corporation, Samsung Electronics, LG Electronics, Electrolux AB, Haier Group, Robert Bosch GmbH, Midea Group, Panasonic Corporation, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Appliance (Wet and Cold) Market Shifts & Advancements
Refrigeration and washing platforms are converging around semiconductor-enabled variable-speed control, while regulatory chemistry mandates and procurement model experiments reshape how value migrates through distribution channels.
AI-driven temperature management is unifying compressor operation with predictive load balancing across multi-zone refrigeration cabinets. Urban households with integrated smart home infrastructure are adopting these systems at replacement-cycle velocity. This convergence is compressing the performance gap between premium inverter platforms and mid-tier mechanical alternatives.
Europe's Ecodesign framework and F-Gas Regulation are mandating explicit global warming potential thresholds for refrigerant selection and system leakage rates. Manufacturers must now maintain parallel product lines with different compressor architectures and chemistries for regional compliance. Cold-chain commercial applications face the steepest re-engineering burden as they balance food safety redundancy with refrigerant charge minimization.
After-sales service unbundling is disrupting traditional dealer-margin structures in mature replacement markets. Independent technicians and platform-coordinated repair networks are capturing maintenance revenue previously retained by original equipment distribution channels. This pattern is most visible in Germany's dense urban housing stock where appliance ownership duration exceeds manufacturer warranty periods by significant margins.
Home Appliance (Wet and Cold) Market Segmentation
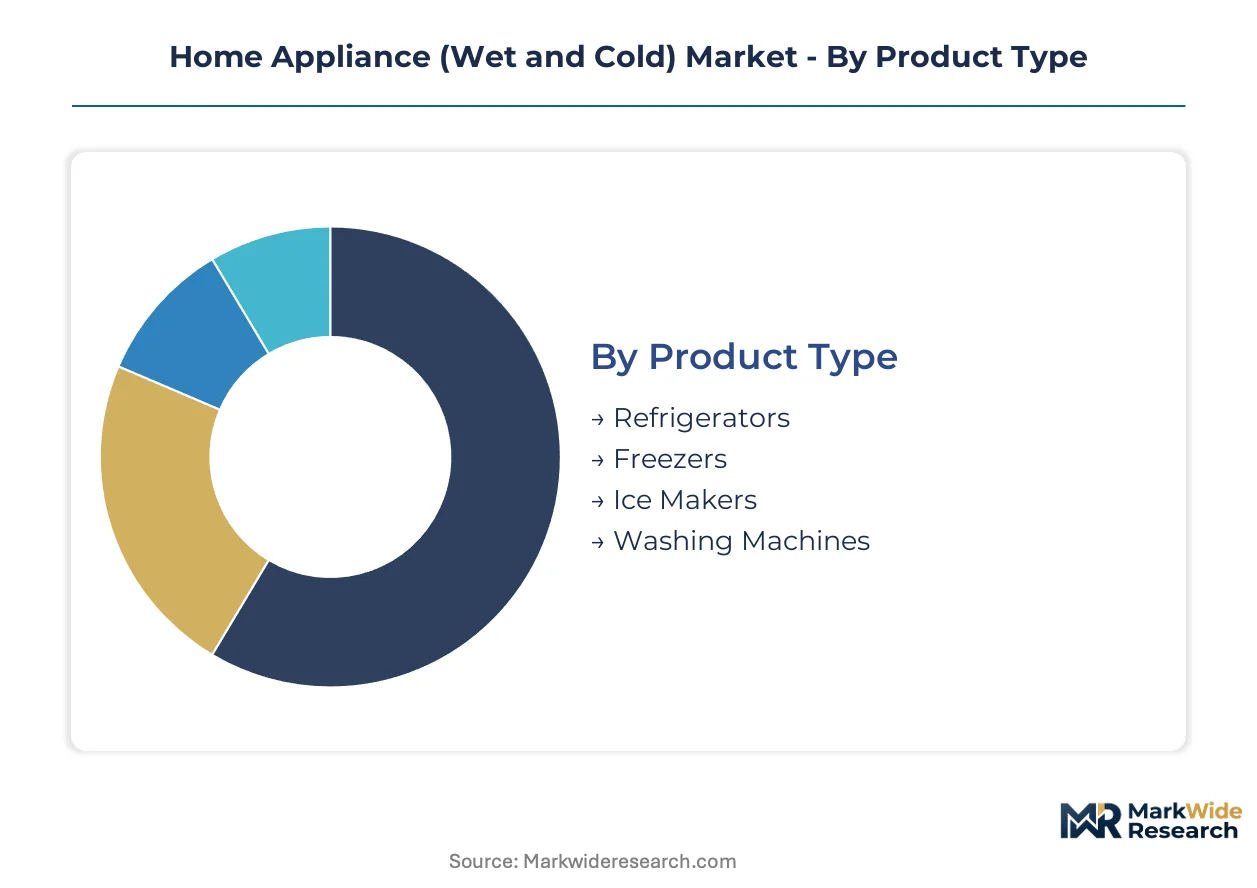
Segmentation in wet and cold appliances reveals how upgrade cycles, regulatory thresholds, and installation constraints partition purchasing behavior. Manufacturers configure platform architectures around these divides to capture replacement velocity versus first-time penetration.
Product Type:
Replacement cycles vary dramatically by thermal mass and mechanical complexity, with compressor-based systems commanding longer depreciation schedules than ice production or textile cleaning units.
- Refrigerators:Multi-compartment cabinets with forced-air or static cooling architectures dominate residential energy budgets. China's tier-one cities and Germany's dense urban housing stocks are driving demand for variable-speed inverter systems as renovation cycles accelerate.
- Washing Machines:Front-load and top-load configurations utilizing direct-drive or belt-driven drum mechanisms. European multi-unit housing and India's electrifying rural corridors represent divergent demand poles—subscription models in the former, first-time ownership in the latter.
- Freezers:Chest and upright formats with static cooling or frost-free operation. Cold-chain commercial applications absorb volume as food safety protocols tighten.
- Ice Makers:Modular under-counter and standalone units with integrated water filtration. Urban hospitality clusters specify these for HACCP-aligned beverage service.
Volume placements concentrate in Refrigerators; the faster expansion belongs to Ice Makers.
Technology:
Cost tier stratification separates premium semiconductor-enabled systems from mechanical alternatives, with regulatory efficiency mandates compressing the mid-market.
- Inverter:Variable-speed compressor and motor control through pulse-width modulation reduces energy consumption by matching output to thermal load. China's NEEQ labeling program and US DOE minimum efficiency standards are accelerating displacement of fixed-speed alternatives in replacement cycles.
- Smart Technology:IoT-connected appliances with AI-driven temperature management and predictive maintenance algorithms. Urban households with centralized home energy management infrastructure are adopting these platforms fastest.
- Energy Efficient:Static designs optimized for insulation performance and compressor duty cycling without variable-speed electronics. Price-sensitive replacement markets retain specification share.
- Traditional:Fixed-speed mechanical systems with electromechanical thermostats. Emerging market first-time buyers and rural electrification corridors sustain residual demand.
Traditional units retain volume dominance in emerging markets; Inverter platforms are climbing the fastest as efficiency mandates harden.
End User:
Application-specific durability requirements and utilization intensity create divergent margin structures across residential and commercial specifications.
- Households:Residential units designed for intermittent duty cycles and aesthetic integration with kitchen cabinetry. China's renovation-driven tier-one cities and India's appliance ownership programs represent opposite ends of the penetration spectrum.
- Commercial Kitchens:Heavy-duty refrigeration and washing platforms with stainless steel enclosures and redundant compressor configurations. Urban hospitality clusters in dense metropolitan zones are scaling fleets to meet tightening food safety inspection regimes.
- Hotels:In-room minibar units and back-of-house laundry systems with brand-standardized specifications. Property management channel partnerships are enabling appliance-as-service penetration in European multi-unit housing.
- Laundries:Coin-operated and industrial-scale washing platforms with high-RPM extraction and programmable cycle architectures. Germany's dense rental housing stock supports independent technician networks for after-market service.
Households absorb the greatest unit volume; Commercial Kitchens are gaining share fastest as food safety protocols proliferate.
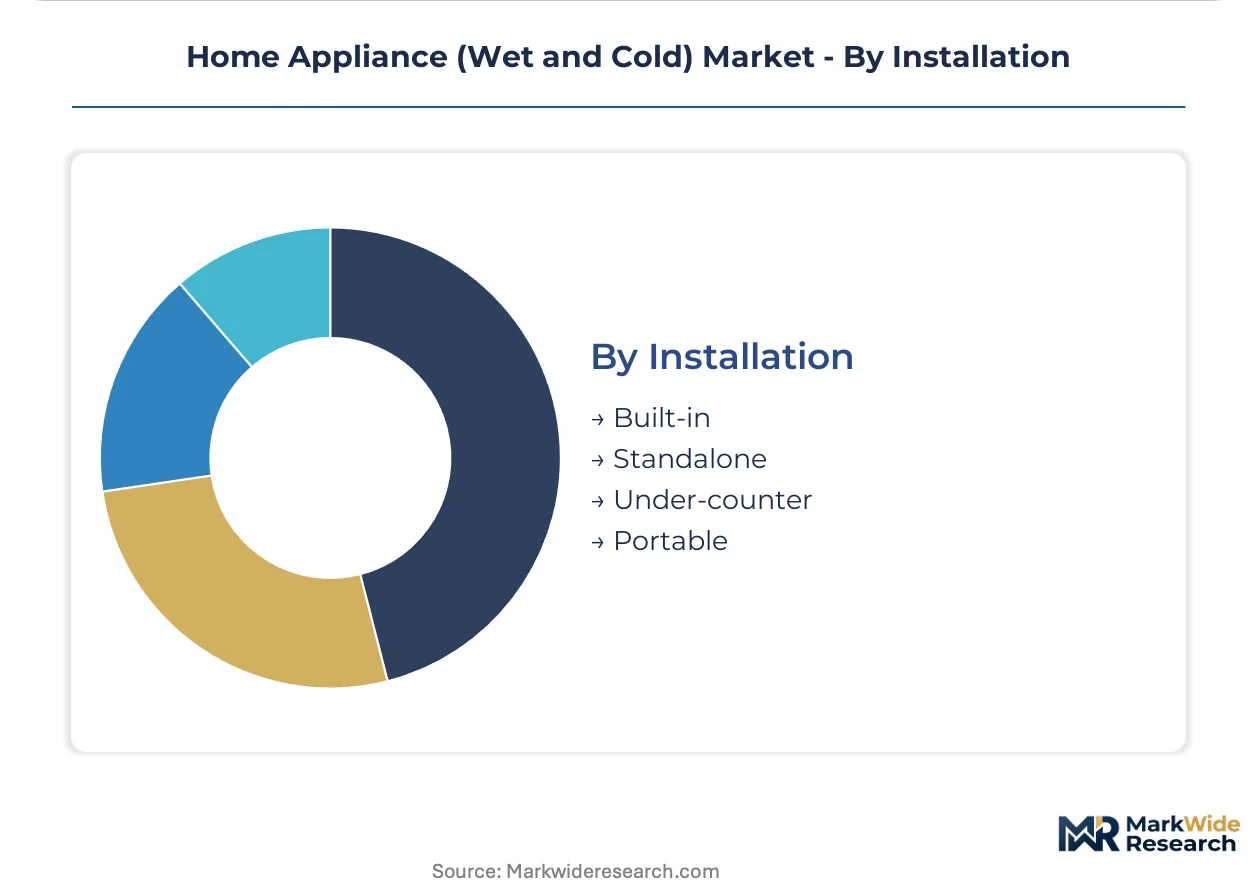
Installation:
Maturity of housing stock and retrofit feasibility determine format specification, with built-in systems requiring coordinated renovation timing.
- Standalone:Freestanding cabinets with finished enclosures requiring no cabinetry modification. Mature replacement cycles across aging housing stocks in the US and Europe sustain dominant share.
- Built-in:Panel-ready or fully integrated systems designed for flush mounting within kitchen millwork. China's tier-one residential renovation cycles and German kitchen replacement markets concentrate demand.
- Under-counter:Compact refrigeration and ice production units sized for bar and utility room installation. Urban hospitality clusters specify these for space-constrained commercial kitchens.
- Portable:Miniaturized washing and cooling units with castor mounting and temporary utility connection. India's village-level grid extension and rental housing transitions in dense Asian cities support niche demand.
Standalone formats retain volume concentration; Built-in systems show the steepest expansion trajectory as renovation cycles synchronize appliance replacement with kitchen remodeling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel feedstock availability in China's Shandong Province anchors compressor manufacturing clusters that supply wet and cold appliance assembly lines worldwide. Regional demand patterns diverge sharply between mature replacement markets and electrification-driven first-time purchases. Regulatory frameworks in the European Union, China, and the United States are forcing parallel refrigerant chemistry transitions that fragment product architectures.
China
Residential renovation cycles in Shanghai, Beijing, and Shenzhen are accelerating built-in refrigerator replacements as smart home integration becomes standard. GB standards and NEEQ labeling tiers reward inverter-compressor platforms with preferential procurement eligibility. Haier Group anchors its position through backward integration into compressor production and captive distribution control across the Yangtze River Delta manufacturing corridor.
Germany
Dense urban housing stocks in Berlin and Munich sustain standalone format dominance in price-sensitive replacement cycles. The F-Gas Regulation mandates explicit GWP thresholds for refrigerant selection, forcing chemistry transitions across compressor architectures. After-sales service unbundling is disrupting traditional dealer-margin structures as independent technician networks capture maintenance revenue.
United States
The Department of Energy resets minimum efficiency standards every three to seven years, compressing product cost structures and accelerating inverter platform displacement. Southeast and Midwest housing stocks with aging infrastructure favor standalone installation formats. Copper and steel price volatility transmits through sheet metal enclosures and refrigerant tubing that manufacturers cannot fully pass through.
India
Village-level grid extension under national electrification programs is opening first-time buyer segments in Maharashtra and Gujarat previously excluded by infrastructure gaps. BIS efficiency labeling and state-level appliance ownership subsidies are stimulating demand for entry-tier mechanical systems. Midea Group and domestic assemblers are configuring simplified control architectures for voltage-fluctuating rural distribution networks.
Japan
METI efficiency standards and shrinking household sizes are driving compact, high-RPM washing platform specifications in Tokyo and Osaka metropolitan zones. Semiconductor-enabled variable-speed control dominates residential replacement cycles. Panasonic Corporation occupies positioning around AI-driven temperature management integration with proprietary home automation ecosystems.
Home Appliance (Wet and Cold) Market Competitive Landscape
Global majors compete with regional champions across refrigerant chemistry compliance and inverter platform scale economics. The vendor base stratifies into three tiers: integrated conglomerates with captive compressor supply, mid-scale specialists in modular refrigeration architectures, and emerging-market assemblers serving price-sensitive electrification corridors. Dominant competitive moves include backward integration into power electronics fabrication and geographic expansion through property management channel partnerships for appliance-as-service models.
Within the integrated conglomerate tier, Whirlpool Corporation and Samsung Electronics exemplify scale-driven positioning through semiconductor supply chain leverage and AI-enabled control system development. LG Electronics anchors the Korean industrial cluster's presence alongside Panasonic Corporation, which occupies specialist positioning around compact urban formats. Robert Bosch GmbH and Siemens AG represent German engineering-centric archetypes navigating Ecodesign framework compliance. Haier Group and Midea Group exemplify Chinese champions with backward integration into compressor manufacturing and distribution network captivity across domestic and Southeast Asian markets. Electrolux AB occupies Nordic-European positioning around modular platform architectures.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Samsung Electronics |
| LG Electronics |
| Electrolux AB |
| Haier Group |
| Robert Bosch GmbH |
| Midea Group |
| Panasonic Corporation |
| Siemens AG |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists across Italy's Emilia-Romagna appliance belt anchor regional pricing discipline through captive service networks and generational technician training pipelines. Their ownership structure resists quarterly margin pressure, allowing sustained investment in refrigerant-handling certification that underwrites premium warranty bundles. China's state-backed producers meanwhile compress entry-tier pricing through subsidized steel feedstock access and vertically integrated compressor foundries.
Pricing Analysis
Warranty and after-sales bundling separates premium inverter platforms from unbundled mechanical alternatives in replacement markets. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and smart-home integration depth. Cost compression in entry-tier mechanical systems is intensifying because India's BIS efficiency mandates force component upgrades without corresponding brand premium capture. Price-sensitive first-time buyers in rural electrification corridors absorb the greatest volume, while German urban households with extended appliance ownership horizons show lowest sensitivity.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's NEEQ procurement rules are reshaping sourcing toward captive compressor production and regional steel finishing. Manufacturing gravity centers on China, South Korea, and Germany for finished goods assembly, with component fabrication drawing from Taiwan's semiconductor foundries and Thailand's motor winding facilities. Supply chain risk concentrates in single-source vulnerability for inverter control modules, where East Asian fabrication capacity feeds global finished goods production. Distribution runs through manufacturer-captive retail networks in China, independent dealer channels in Germany, and platform-coordinated subscription models in European multi-unit housing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where refrigerant chemistry transition costs and inverter R&D scale requirements force weaker mechanical-platform specialists toward exit or acquisition.
For Market Incumbents: To counter semiconductor supply concentration exposing finished goods producers to allocation rationing, secure captive power electronics fabrication capacity or long-term foundry offtake agreements with Taiwan's TSMC or Samsung's System LSI division. Deepen backward integration into compressor manufacturing to defend margin position against China's state-backed integrated producers. For New Entrants and Emerging Players: Begin with modular refrigeration architectures targeting European commercial kitchen retrofit cycles, where F-Gas Regulation compliance gaps create specification windows for lower-GWP alternative systems. India's village-level electrification corridors offer first-time penetration white space through simplified mechanical platforms configured for voltage-fluctuating rural distribution networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale German engineering-centric specialists with Ecodesign compliance certification and established technician training pipelines, positioned for acquisition by Asian conglomerates seeking European brand equity. Watch refrigerant input cost volatility as inflection indicator—sustained hydrofluorocarbon supply compression signals accelerated consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Haier Group's captive Shandong foundry supply secures margin control against commodity steel swings. |
| Smart Home Platform Integration | Samsung Electronics leverages semiconductor supply chain to embed AI-driven temperature management across portfolios. |
| Appliance-as-Service Model Launch | Property management channel partnerships in Berlin and Munich capture recurring revenue from extended ownership cycles. |
| Lower-GWP Refrigerant Transition | Europe's F-Gas Regulation mandates force parallel product line maintenance for regional compliance. |
| Rural Electrification Corridor Expansion | Midea Group configures simplified control architectures for Maharashtra and Gujarat first-time buyer segments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with appliance manufacturing executives, compressor procurement leads, commercial kitchen fleet managers, and independent service technician network coordinators. Bottom-up triangulation cross-checked against top-down macroeconomic indicators and energy efficiency standard implementation timelines across the analysis window.
Granularity-level modeling distinguished product type, technology tier, end-user application, and installation format dimensions at country-level resolution. CAGRs derived from replacement cycle velocity analysis, regulatory mandate phase-in schedules, and smart home penetration curves. Forecast inputs incorporated inverter platform displacement rates, refrigerant chemistry transition timelines, and rural electrification program implementation pace.
Underlying measurement precision varies by segment; China's tier-one renovation-driven replacement cycles and Germany's dense urban housing stocks carry tighter precision than India's emerging rural corridors. Forecasts reflect assumptions around regulatory implementation consistency and commodity price transmission elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Sweden Laundry Appliances Market
Home Appliances
Smart Home Appliances Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
Kuwait Small Home Appliances Market
Home Appliances
Portable Dehumidifier Market
Home Appliances
Japan Major Home Appliances Market
Home Appliances
India Small Home Appliances Market
Home Appliances
Global Residential Water Heaters Market
Home Appliances
United States Small Home Appliances Market
Home Appliances
Europe Small Home Appliances Market
Home Appliances
North America Home Appliances Market
Home Appliances
Mexico Small Home Appliances Market
Home Appliances
Germany Small Home Appliance Market
Home Appliances
Europe Portable Washing Machine Market
Home Appliances
Oman Home Appliances Market
Home Appliances
China Small Home Appliances Market