
 Argentina Home Appliances Market | 2026-2036
Argentina Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Home Appliances Market Outlook
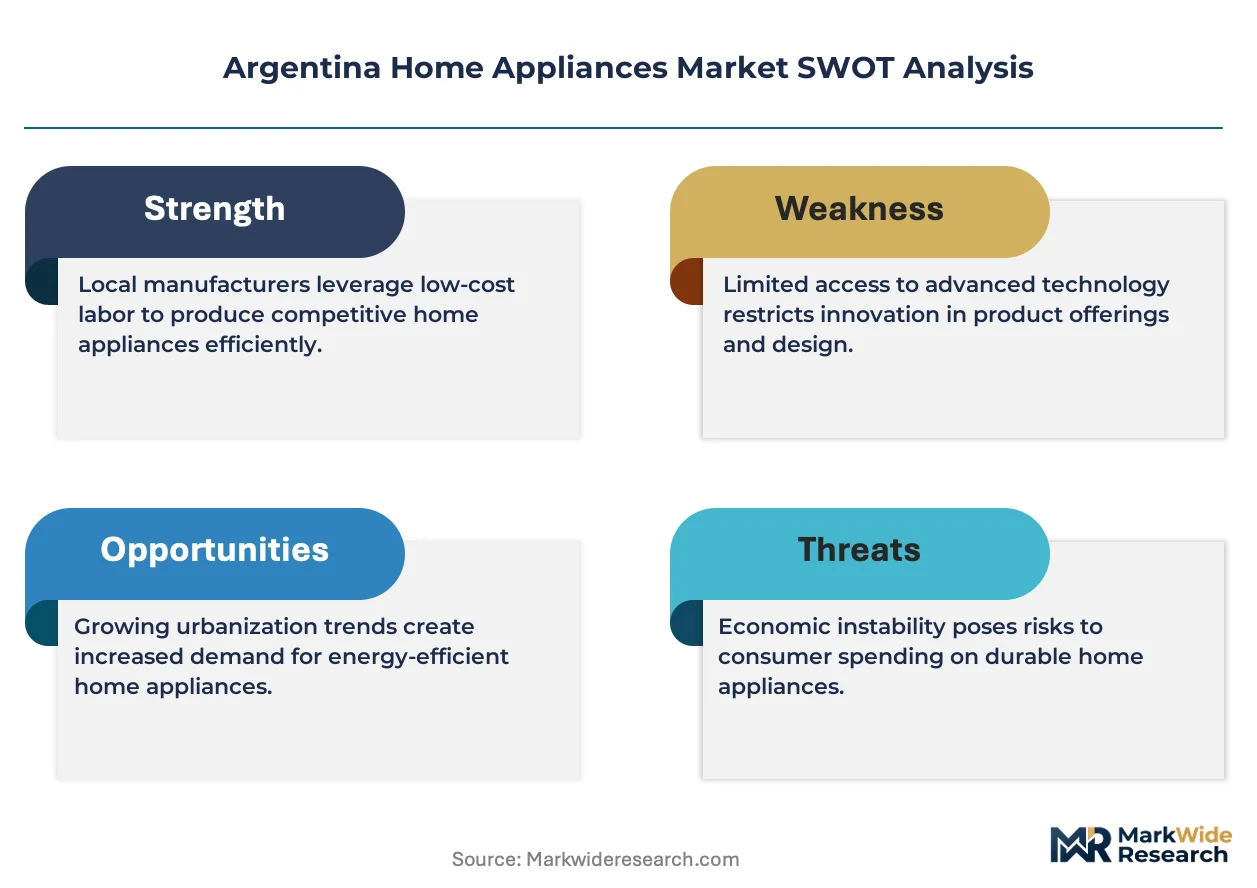
Bundle pricing across refrigerator-washer combinations is consolidating purchasing patterns among Argentine households seeking value in inflationary conditions. Whirlpool Corp. leverages its regional manufacturing footprint to sustain competitive delivery timelines. BGH S.A. anchors its position through deep distribution networks in interior provinces. Electrolux AB differentiates via premium energy-efficient positioning in Greater Buenos Aires.
Home appliances encompass electrically powered mechanical devices designed for domestic tasks, typically operating at 220V/50Hz with energy consumption ratings measured under IRAM standards. Refrigerators command the largest product-type share due to universal household penetration and replacement cycles driven by compressor technology upgrades. Smart appliances represent the fastest-expanding technology segment as Wi-Fi-enabled diagnostics and remote monitoring gain traction among urban households. Energy-efficient models capture margin concentration as electricity tariff structures incentivize lower-consumption units.
Argentina's Secretariat of Energy enforces mandatory energy labeling under IRAM standards, compressing demand toward certified efficient products. The country's national consumer protection authority monitors warranty compliance and after-sales service standards, elevating operational requirements for importers and domestic assemblers. BIS-equivalent conformity assessment procedures for electrical safety shape market access pathways for foreign manufacturers. Stakeholders must track regulatory alignment between domestic efficiency mandates and MERCOSUR technical harmonization protocols to anticipate compliance cost trajectories.
Market Dynamics
Argentina's mandatory IRAM energy efficiency labeling program is compressing demand toward inverter-compressor refrigeration technologies, forcing manufacturers to reconfigure product portfolios around certified efficient models or exit the market.
Growth Catalysts
- IRAM Labeling Mandate:Argentina's Secretariat of Energy enforces mandatory energy consumption disclosure, redirecting household purchasing toward certified efficient units and accelerating replacement cycles in Buenos Aires and Córdoba.
- Urban Electrification:Grid reliability improvements in central provinces expand addressable market for electrically intensive appliances, particularly among first-time refrigerator buyers in secondary cities.
- Wi-Fi Module Integration:Smart appliance connectivity is penetrating urban households as remote diagnostics and usage monitoring gain traction among tech-adopting consumer segments.
Market Restraints
- Imported Component Dependency:Compressor and electronic control module supply concentrates in Asian manufacturing hubs, exposing assemblers to currency volatility and extended lead times.
- Electricity Tariff Compression:Subsidized utility rates in interior provinces dilute the payback calculus for premium efficient models, slowing adoption outside regulated urban centers.
- Repair Infrastructure Scarcity:Inverter-compressor servicing requires specialized technical training that remains concentrated in Greater Buenos Aires, limiting rural market penetration.
Strategic Opportunities
- Interior Province Distribution:Underpenetrated markets in Mendoza, Tucumán, and Salta present whitespace for regional logistics networks capable of delivering certified units with local warranty support.
- Refrigerator-Washer Bundling:Inflation-conscious households seek value through combination purchasing, creating margin protection for suppliers with cross-category manufacturing flexibility.
- MERCOSUR Harmonization:Alignment between Argentine IRAM standards and regional technical protocols would streamline compliance costs for manufacturers serving multiple South American markets.
Industry Challenges
- Inverter-Compressor Technical Training:The shift from conventional to variable-speed refrigeration systems demands re-skilling of service technician networks, with certification lagging behind product rollout.
- Conformity Assessment Bottlenecks:BIS-equivalent electrical safety testing capacity constrains import velocity, delaying market access for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Home Appliances Market |
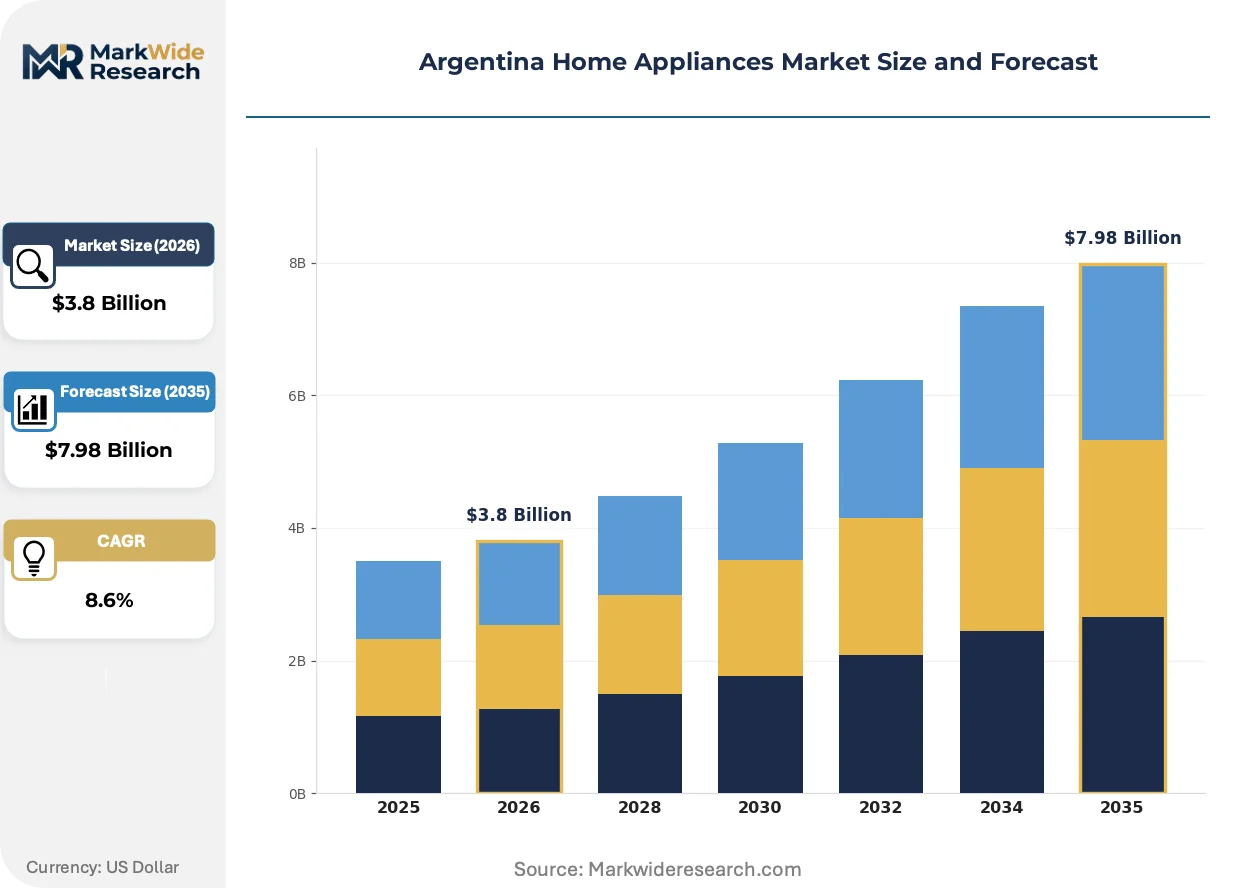
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washers, Ovens, Microwaves Technology: Smart Appliances, Energy-Efficient, Traditional, Hybrid End User: Households, Businesses, Institutions, Rental Properties Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Electrolux AB, BGH S.A., Whirlpool Corp., Alladio, Gafa, Samsung Electronics, Mabe, BSH Home Appliances Group, LG Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Home Appliances Market Strategic Shifts
Digital connectivity and energy efficiency certification are converging to reshape competitive positioning in Argentina's appliance sector, with regulatory pressure and consumer behavior shifting in parallel toward measurable performance standards.
Inverter-compressor technology is consolidating its position as the dominant refrigeration platform, replacing conventional fixed-speed units through variable-speed operation that matches cooling output to thermal load. Buenos Aires and Córdoba households are adopting these systems at accelerated rates as electricity tariffs in regulated urban zones amplify lifecycle cost advantages. This technology shift is consolidating manufacturer portfolios around certified efficient platforms while marginalizing non-compliant legacy models.
Argentina's Secretariat of Energy maintains mandatory IRAM energy labeling with efficiency tiers displayed at point of sale, creating transparent comparison criteria that reshape purchasing decisions. Domestic assemblers and importers must pre-certify units through accredited laboratories, elevating compliance costs but protecting market position for prepared participants. The household refrigeration segment bears the strongest compliance pressure, with urban retailers reorganizing floor space to feature certified models prominently.
Bundle purchasing patterns are emerging as inflation-adjusted households seek transaction efficiency through combined refrigerator-washer acquisitions. Traditional single-product retail channels face disruption from appliance chains offering packaged financing and coordinated delivery, particularly in Greater Buenos Aires where credit access supports larger basket sizes. This behavioral shift concentrates volume with suppliers possessing cross-category manufacturing depth and integrated logistics capabilities.
Argentina Home Appliances Market Segmentation
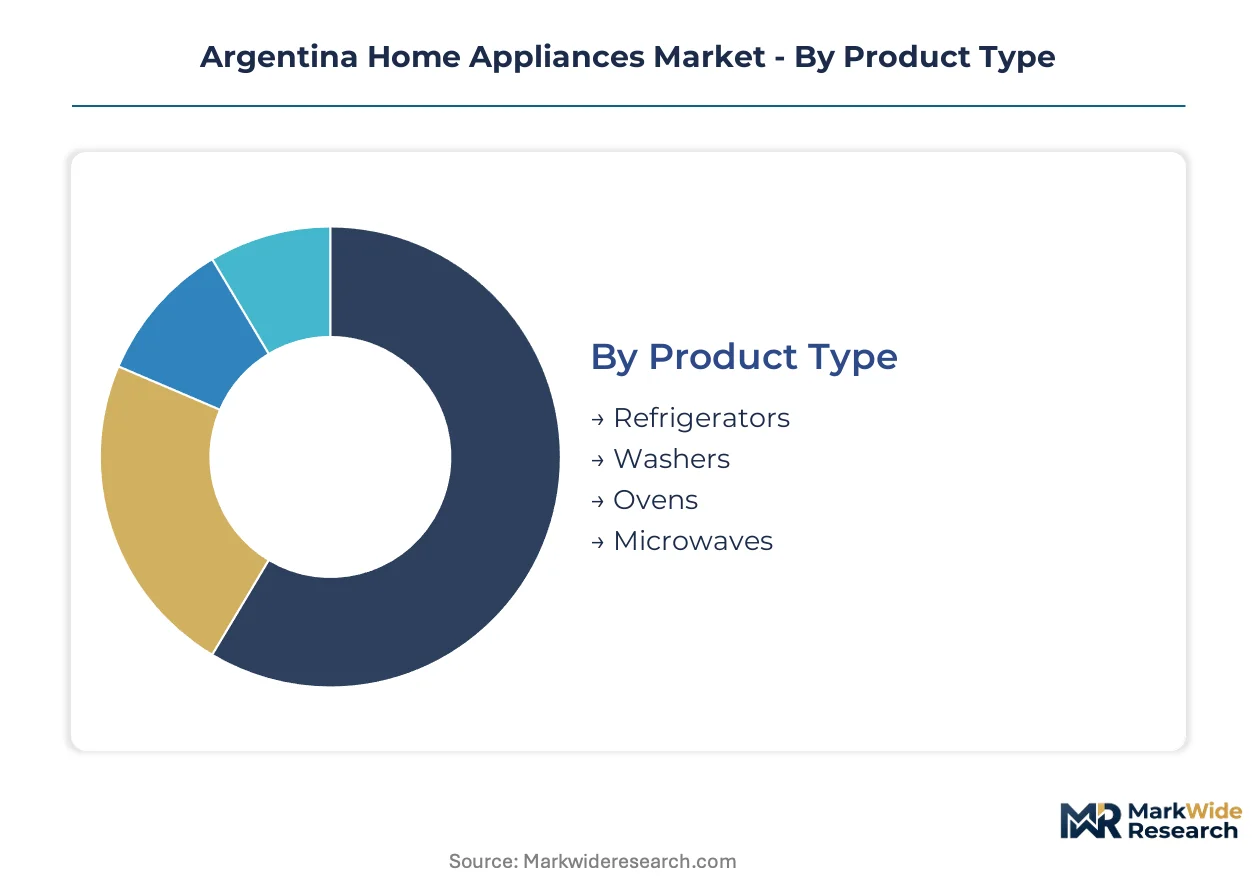
Segmentation in Argentina's home appliances market reveals how regulatory pressure and purchasing behavior fragment across technical specifications and channel access. Understanding these divisions exposes where inverter-compressor adoption concentrates and which customer groups bundle purchases under inflationary stress.
Product Type:
Standalone appliances dominate residential installations, while embedded or built-in systems serve renovation projects and new construction in Buenos Aires developments.
- Refrigerators:These units operate on 220V/50Hz with compressor efficiency ratings measured under IRAM standards. Demand clusters in Buenos Aires and Córdoba households replacing fixed-speed units with inverter-compressor models to meet tightening utility regulations.
- Washers:Front-loading and top-loading configurations serve distinct water-pressure and space-constrained environments. Bundle purchasing with refrigerators is accelerating among inflation-conscious households seeking transaction efficiency through combined financing.
- Ovens:Gas and electric variants address divergent fuel access across Argentina's central provinces. These appliances see replacement cycles tied to kitchen renovation timelines rather than standalone failure events.
- Microwaves:Countertop units dominate rental property and student housing segments where installation flexibility outweighs built-in aesthetics.
Volume placements concentrate in refrigerators; the faster expansion belongs to washers through bundle-purchasing dynamics.
Technology:
Cost-tier stratification separates premium certified units from economy models, with mid-tier products capturing households balancing upfront price against lifecycle electricity costs.
- Smart Appliances:Wi-Fi-enabled diagnostics and remote monitoring functionality penetrate urban Buenos Aires households where tech adoption rates exceed national averages. These units command premium positioning through connected service ecosystems.
- Energy-Efficient:Inverter-compressor refrigeration and variable motor washing systems reduce electricity consumption under IRAM certification tiers. Regulatory mandates from Argentina's Secretariat of Energy compress demand toward these certified platforms.
- Traditional:Fixed-speed compressors and mechanical controls serve price-sensitive segments in interior provinces where electricity subsidies dilute efficiency payback calculations.
- Hybrid:Partial connectivity with manual override options bridges adoption gaps for households transitioning toward smart functionality without full dependency on network reliability.
Volume placements concentrate in energy-efficient models; the steepest expansion trajectory belongs to smart appliances through urban connectivity adoption.
End User:
Customer-type segmentation distinguishes between owner-occupied decision-making and procurement patterns where third parties specify appliance standards.
- Households:Owner-occupiers in Greater Buenos Aires and Córdoba drive replacement cycles for certified efficient units. These buyers respond directly to IRAM labeling at point of sale and bundle financing incentives.
- Businesses:Restaurants, hotels, and laundromats prioritize commercial-grade durability and service response times over residential efficiency certifications. Procurement concentrates through wholesale channels with negotiated maintenance contracts.
- Institutions:Schools, hospitals, and government facilities follow public procurement protocols that increasingly incorporate IRAM efficiency mandates. Bulk purchasing timelines lag consumer market adoption by replacement-cycle offsets.
- Rental Properties:Landlords in Buenos Aires and secondary cities balance acquisition cost against tenant electricity complaints. This segment shows resistance to premium efficient models where tenants bear utility costs.
Volume placements concentrate in households; rental properties are climbing the fastest as urban tenancy rates rise.
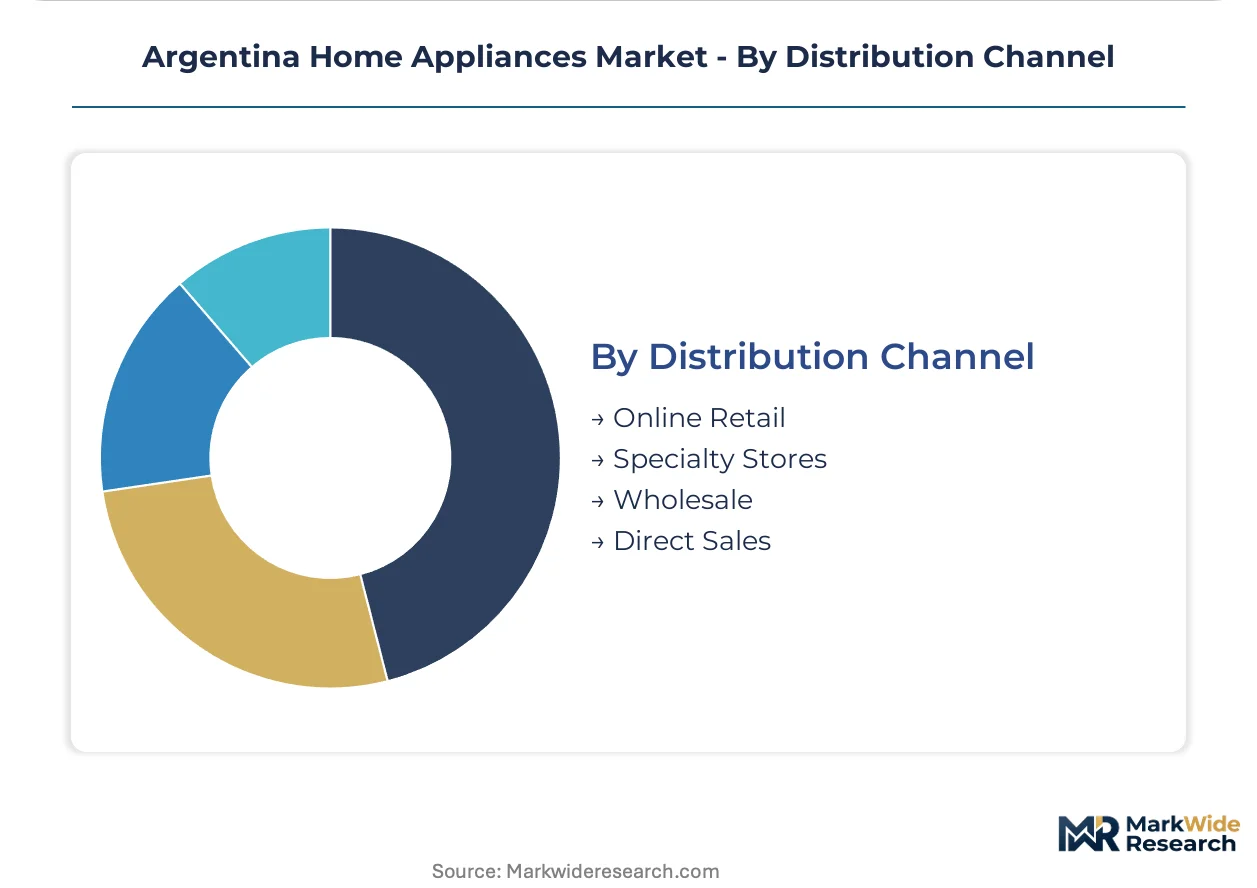
Distribution Channel:
Geographic reach and technical service capability determine channel viability across Argentina's concentrated urban markets and dispersed interior provinces.
- Online Retail:E-commerce platforms with integrated financing and delivery coordination gain share in Greater Buenos Aires. These channels leverage credit access and bundle-purchasing interfaces to capture inflation-adjusted household spending.
- Specialty Stores:Dedicated appliance retailers with floor space for IRAM-certified displays and trained sales staff dominate high-consideration purchases. Physical presence remains essential for inverter-compressor education and warranty explanation.
- Wholesale:Bulk supply to developers, institutions, and commercial operators runs through regional distributors with inventory depth in Mendoza, Tucumán, and Salta. These channels prioritize delivery reliability over consumer-facing certification display.
- Direct Sales:Manufacturer-owned outlets and commissioned sales networks serve interior provinces where third-party retail infrastructure remains underdeveloped. Whirlpool Corp. and BGH S.A. maintain direct presence to secure rural market access.
Volume placements concentrate in specialty stores; online retail is gaining share fastest through credit-integrated bundle transactions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tierra del Fuego's special economic zone for electronics manufacturing concentrates import-substitution incentives, drawing assembly operations away from traditional coastal entry points. Provincial tax abatements and duty exemptions on components reshape logistics networks across Argentina's interior.
Greater Buenos Aires
Household replacement cycles for inverter-compressor refrigerators accelerate as IRAM labeling mandates tighten enforcement. The Secretariat of Energy's efficiency disclosure requirements compress demand toward certified models in capital zone retail channels. Electrolux AB and BGH S.A. maintain flagship presence in Palermo and Belgrano commercial corridors.
Córdoba Province
Secondary city electrification expands addressable market for energy-intensive appliances among first-time buyers. Provincial utility regulators align tariff structures with national efficiency programs, amplifying payback calculations for premium certified units. Whirlpool Corp. operates regional distribution hubs serving the Córdoba-Rosario corridor.
Mendoza
Wine industry prosperity supports household appliance upgrade cycles in Greater Mendoza metropolitan area. Local consumer protection offices enforce warranty compliance standards that elevate operational requirements for direct-sales networks. Samsung Electronics and LG Electronics penetrate through specialized retail partnerships in the city's commercial district.
Tucumán
Sugar processing and citrus export revenues stabilize purchasing power for durable goods in San Miguel de Tucumán. Federal energy subsidy programs dilute efficiency incentives in this interior market, preserving demand for conventional compressor technologies. Mabe and Gafa compete through wholesale channels with inventory depth in regional distributor warehouses.
Salta
Tourism and mining investment flows expand middle-class appliance demand in Argentina's northwestern gateway. Direct sales networks from Buenos Aires-based assemblers face logistics cost penalties serving this dispersed geography. Alladio and BSH Home Appliances Group establish presence through commissioned agent arrangements with local commercial representatives.
Argentina Home Appliances Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Argentina's appliance sector, creating a tiered structure where cross-category manufacturing depth determines bundle-pricing leverage. The market consolidates around manufacturers with captive compressor supply or regional assembly footprints, while import-dependent assemblers face margin compression from currency volatility. Three archetypes dominate: integrated regional manufacturers with distribution control, global brand licensors with local assembly partnerships, and domestic distributors with private-label sourcing flexibility. Capacity rationalization and warranty network expansion represent the primary competitive moves, as service infrastructure scarcity in interior provinces creates defensive moats.
Among European-origin multinationals, Electrolux AB exemplifies premium-tier positioning through energy-efficient product architectures, while BSH Home Appliances Group occupies the mid-premium intersection of design and certification compliance. Whirlpool Corp. anchors the diversified-manufacturer archetype with cross-category breadth enabling refrigerator-washer bundling. BGH S.A. represents the domestic-integrated model with deep interior distribution networks. These three companies illustrate how geographic manufacturing footprint, regulatory certification depth, and channel control combine to determine competitive position under Argentina's IRAM mandate environment.
| Leading Market Players |
|---|
| Electrolux AB |
| BGH S.A. |
| Whirlpool Corp. |
| Alladio |
| Gafa |
| Samsung Electronics |
| Mabe |
| BSH Home Appliances Group |
| LG Electronics |
| Others |
Value Chain & Pricing Dynamics
Compressor and electronic control module costs flow from Asian manufacturing hubs through Buenos Aires assembly plants, stratifying final appliance pricing across premium inverter-compressor models and conventional fixed-speed alternatives. Currency volatility in component sourcing amplifies margin compression for import-dependent assemblers serving Argentina's interior provinces.
Pricing Analysis
Cost-down pressure on economy-tier units accelerates because electricity tariff subsidies in Tucumán and Salta dilute efficiency payback calculations, preserving demand for conventional compressors. Three-tier pricing structure across premium certified, standard mid-efficiency, and economy fixed-speed levels dominates the market. Price differentiation rests on IRAM certification grade and after-sales service bundling. Buenos Aires households show lowest price sensitivity due to credit access, while interior province buyers prioritize upfront acquisition cost.
Supply Chain Analysis
Regional distribution centers in Greater Buenos Aires and Córdoba anchor hub-and-spoke patterns reaching Mendoza, Tucumán, and Salta through commissioned agent networks. Component supply concentrates in China, South Korea, and Thailand for compressors, electronic modules, and precision motors. Raw material dependencies span copper wiring, refrigerant gases, and cold-rolled steel. Single-source vulnerability in inverter-compressor technology creates procurement risk. Distribution runs through specialty retail channels with certified display requirements in urban centers and direct-sales networks in underpenetrated interior markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's home appliances sector is consolidating around manufacturers with captive regional assembly and IRAM certification depth, forcing import-dependent assemblers toward exit or acquisition.
For Market Incumbents: Lock in service technician certification networks ahead of inverter-compressor rollout saturation, as repair infrastructure scarcity in interior provinces creates defensive moats against emerging entrants lacking warranty depth. Deepen backward integration into compressor supply or secure long-term offtake agreements with Asian component suppliers to hedge currency exposure. For New Entrants and Emerging Players: Wholesale distributors in Mendoza and Salta present the most penetrable channel gap, as direct-sales networks from Buenos Aires-based assemblers face logistics cost penalties serving these dispersed geographies. Target first-time refrigerator buyers in secondary cities through bundled financing with regional banks and localized warranty partnerships. For Investors and Strategic Acquirers: IRAM certification backlog clearance rates at accredited laboratories are the leading indicator that compliance-ready manufacturing assets will command scarcity premiums. Position for 5-10 year viability through acquisition of domestic-integrated assemblers with interior distribution control rather than import-dependent distributors exposed to currency volatility.| Strategic Initiative | Industry Significance |
|---|---|
| IRAM Certification Investment | Pre-certification through Buenos Aires laboratories protects market access under Secretariat of Energy mandates. |
| Interior Province Distribution Expansion | Regional logistics networks in Mendoza and Tucumán capture whitespace beyond concentrated coastal markets. |
| Refrigerator-Washer Bundle Launch | Cross-category manufacturing flexibility captures inflation-conscious household spending through transaction efficiency. |
| Technician Certification Program | Inverter-compressor service training networks defend rural market penetration against repair infrastructure scarcity. |
| MERCOSUR Harmonization Alignment | Regional technical protocol convergence streamlines compliance costs for multi-country South American manufacturing. |
Study Parameters
Trade customs records, Secretariat of Energy regulatory filings, and IRAM certification databases formed the secondary backbone, cross-referenced with primary interviews across appliance manufacturing executives, regional distribution managers, and retail channel heads. Bottom-up unit shipment estimates triangulated against top-down household penetration models derived from national electrification data and replacement cycle analysis.
Historical trendline analysis of compressor technology transitions and efficiency mandate compliance patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, technology tier, end-user category, and distribution channel. CAGRs were derived from slope analysis of technology adoption curves and regulatory phase-in timelines, incorporating electricity tariff trajectory assumptions and currency volatility inputs.
Caveats apply where MERCOSUR harmonization delays, compressor supply disruptions, or subsidy program modifications could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Household Induction Cooktops Market
Home Appliances
United States Laundry Appliances Market
Home Appliances
Germany Washing Machine Market
Home Appliances
Bahrain Major Home Appliances Market
Home Appliances
Built-In Hobs Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
India Home Appliances Market
Home Appliances
Household Electric Steamer Cooker Market
Home Appliances
China Major Home Appliances Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
White Goods Market
Home Appliances
India Small Home Appliances Market
Home Appliances
UAE Home Appliances Market
Home Appliances
Canada Laundry Appliances Market
Home Appliances
Household Refrigerators and Freezers Market
Home Appliances
European Built-In Refrigerator Market