
 Surgical Drainage Devices Market | 2026-2036
Surgical Drainage Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Drainage Devices Market Intelligence
The EU Medical Device Regulation is repositioning compliance requirements for surgical drainage devices sold across European member states. Medtronic leverages its broad geographic footprint to sustain market presence amid evolving certification timelines. Cardinal Health anchors its competitive stance through extensive distribution networks spanning acute and ambulatory channels. B. Braun Melsungen AG differentiates via specialized manufacturing capabilities in silicone and polyurethane catheter formulations.
Surgical drainage devices comprise implantable or external conduits—typically fabricated from medical-grade silicone, PVC, or polyurethane with lumen diameters ranging from 7 Fr to 32 Fr—engineered to evacuate blood, serous fluid, or purulent material from operative sites or body cavities to prevent hematoma, seroma, or infection. Closed drainage systems dominate hospital procurement due to reduced contamination risk and standardized connection interfaces with vacuum canisters. Active drainage systems represent the fastest-expanding category as negative-pressure mechanisms improve fluid evacuation efficiency in complex thoracic and abdominal procedures. Material selection increasingly favors silicone over PVC in extended-duration applications where tissue biocompatibility and kink resistance determine clinical outcomes.
The FDA maintains stringent biocompatibility and sterility standards under 21 CFR Part 820 quality system regulations, while the EU MDR requires notified body involvement for Class IIa and above surgical drains. Japan's PMDA enforces JIS T 0601 electrical safety standards for active suction units, creating layered compliance obligations for multinational manufacturers. Stakeholders must monitor evolving post-market surveillance requirements in major jurisdictions to align R&D investment with shifting evidence-generation demands.
Market Dynamics
Closed drainage systems are displacing open-suction alternatives as ambulatory surgical centers consolidate procurement around infection-prevention protocols and standardized vacuum-canister interfaces.
Growth Catalysts
- Outpatient Procedure Volume:Ambulatory surgical centers in the United States are expanding catheter procurement for same-day discharge protocols, driving closed-system adoption.
- FDA 510(k) Streamlining:The FDA's updated clearance pathways for Class II medical devices are accelerating silicone-based innovation timelines for manufacturers.
- Negative-Pressure Mechanisms:Active drainage systems with vacuum-assisted closure are penetrating complex thoracic and abdominal procedures previously managed by passive gravity drains.
Market Restraints
- Medical-Grade Silicone Supply:Concentrated silicone resin production in Northeast Asian chemical clusters creates input cost volatility for catheter fabricators.
- EU MDR Certification Friction:Notified body bottlenecks for Class IIa surgical drains are extending time-to-market for European distribution.
- Polyurethane Substitution Ceiling:Extended-duration applications favor silicone biocompatibility, limiting polyurethane catheter expansion in high-acuity settings.
Strategic Opportunities
- Integrated Health Network Standardization:Multi-hospital systems in the United States are unifying post-operative care protocols, creating bulk procurement contracts for compatible drainage systems.
- Silicone-Polyurethane Hybrid Formulations:Converging material technologies are enabling kink-resistant catheters with enhanced tissue compatibility for cardiac and neurosurgical applications.
- Japan PMDA Electrical Safety Alignment:Active suction unit manufacturers can leverage JIS T 0601 certification to access high-value thoracic surgery segments.
Industry Challenges
- Biocompatibility Testing Backlogs:ISO 10993 cytotoxicity and sensitization studies are creating bottlenecks for novel material introductions.
- Legacy System Integration:Vacuum canister interface standardization across hospital systems requires retrofitting incompatible suction pumps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Drainage Devices Market |
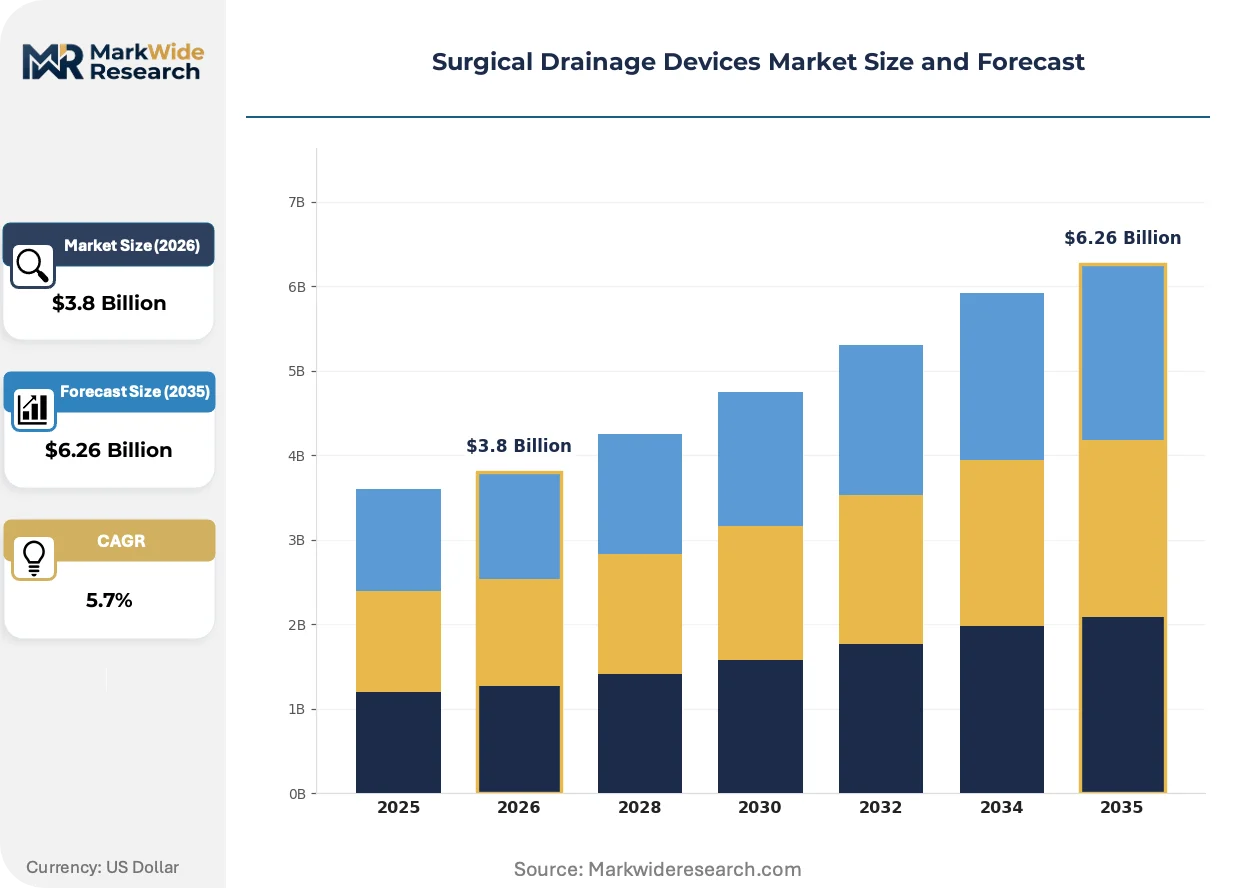
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Closed Drainage Systems, Open Drainage Systems, Gravity Drainage Systems, Active Drainage Systems Material: Silicone, PVC, Polyurethane, Latex End User: Hospitals, Clinics, Surgical Centers, Home Healthcare Application: Abdominal Surgery, Orthopedic Surgery, Plastic Surgery, Thoracic Surgery |
| Companies Covered | Medline Industries, Teleflex Incorporated, Cardinal Health, Stryker, Cook Medical, Medtronic, B. Braun Melsungen AG, Smith & Nephew, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Drainage Devices Market Strategic Shifts & Innovations
Material science advances and regulatory harmonization efforts are compressing product development cycles while elevating performance thresholds for extended-implantation applications.
Silicone elastomer formulations with platinum-cure chemistry are expanding into cardiac and neurosurgical drainage applications where tissue adhesion resistance determines clinical outcomes. Academic medical centers in Germany and the United States are piloting these catheters for post-sternotomy and cranial procedures. The technology is expanding into premium pricing tiers previously dominated by specialized thoracic drains.
The EU Medical Device Regulation's post-market surveillance requirements are forcing manufacturers to restructure clinical evidence portfolios for Class IIa surgical drains. Notified body capacity constraints in Germany and the Netherlands are redirecting certification submissions toward Baltic and Eastern European assessment entities. Smaller catheter specialists are responding by pooling clinical data through industry consortia to share surveillance costs.
Hospital procurement committees are unbundling after-sales service from device pricing, compressing vendor margins while demanding real-time inventory replenishment. Acute care networks in the United States are replacing distributor-mediated purchasing with direct manufacturer agreements tied to consumption-based replenishment. This behavioral shift is most visible in integrated delivery networks standardizing catheter specifications across 10-plus facility footprints.
Surgical Drainage Devices Market Segmentation
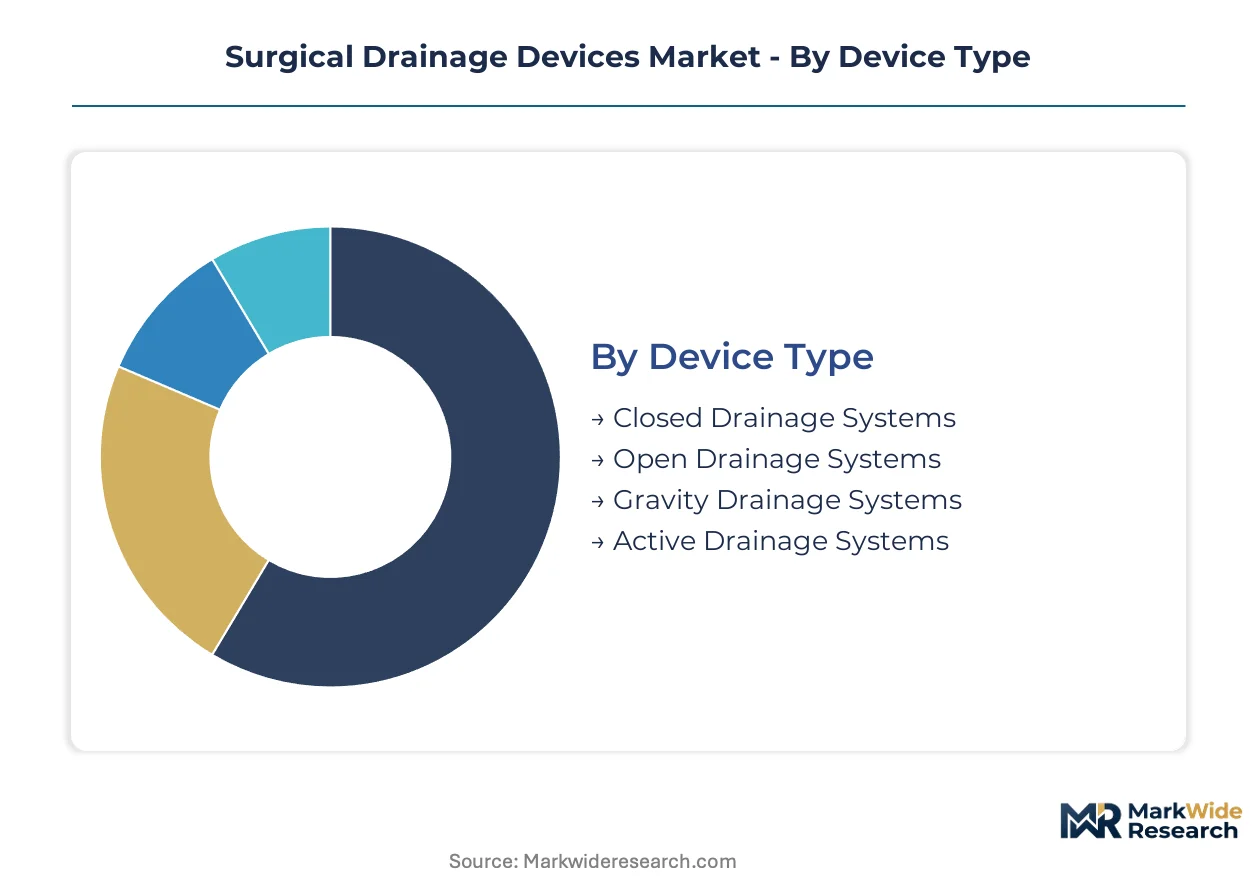
Surgical drainage devices segment across four critical dimensions that shape procurement decisions and clinical utility. Device type determines infection control capabilities and vacuum interface compatibility. Material selection governs biocompatibility profiles for extended implantation durations. End-user channel dictates pricing tolerance and service bundling requirements. Application specificity drives catheter diameter, lumen configuration, and suction pressure specifications.
Device Type:
Hospital procurement committees prioritize infection prevention and vacuum-canister interoperability when selecting drainage system architectures.
- Closed Drainage Systems:Sealed conduits with one-way valves and standardized vacuum-canister connections eliminate atmospheric contamination during fluid evacuation. United States ambulatory surgical centers are consolidating procurement around these systems for same-day discharge protocols, driven by CDC surgical site infection prevention guidelines.
- Active Drainage Systems:Negative-pressure mechanisms with adjustable suction controllers improve evacuation efficiency in high-output thoracic and abdominal procedures. German academic medical centers are piloting these units for post-sternotomy cardiac surgery, where gravity-dependent passive drainage proves inadequate.
- Open Drainage Systems:Passive gravity-dependent conduits without sealed interfaces persist in resource-constrained settings where vacuum infrastructure remains unavailable.
- Gravity Drainage Systems:Simple dependent drainage without active suction serves low-acuity postoperative monitoring in cost-sensitive clinical environments.
Closed Drainage Systems lead on scale; Active Drainage Systems lead on momentum.
Material:
Extended implantation duration and tissue contact sensitivity determine material selection priority in catheter specifications.
- Silicone:Platinum-cure elastomer formulations deliver superior biocompatibility and kink resistance for cardiac and neurosurgical applications. United States thoracic surgery units specify silicone catheters for post-operative durations exceeding seven days, where tissue adhesion resistance determines clinical outcomes.
- Polyurethane:Thermoplastic formulations balance mechanical strength with cost efficiency in intermediate-duration orthopedic and plastic surgery applications.
- PVC:Rigid polymer construction serves short-term drainage requirements where cost minimization outweighs biocompatibility concerns.
- Latex:Natural rubber formulations persist in emerging markets despite allergenicity limitations and regulatory migration toward synthetic alternatives.
Silicone commands premium positioning; Polyurethane captures volume expansion.
End User:
Channel-specific service requirements and consumption predictability shape manufacturer go-to-market strategies.
- Hospitals:Acute care networks with standardized post-operative protocols generate bulk procurement contracts spanning multi-facility footprints. United States integrated delivery networks are unifying catheter specifications across 10-plus hospital systems, compressing vendor margins while demanding real-time inventory replenishment.
- Surgical Centers:Ambulatory facilities with same-day discharge protocols favor closed-system compatibility and streamlined logistics over technical sophistication.
- Clinics:Outpatient settings with limited procedure volume prioritize distributor-mediated purchasing and minimal inventory carrying costs.
- Home Healthcare:Patient-managed drainage with remote monitoring capabilities is expanding into post-acute transition care, though reimbursement complexity constrains penetration.
Hospitals anchor revenue concentration; Surgical Centers drive volume acceleration.
Application:
Procedure-specific fluid characteristics and anatomical constraints dictate catheter diameter, lumen configuration, and suction pressure requirements.
- Thoracic Surgery:High-volume air and fluid evacuation from pleural spaces demands large-bore catheters with high-negative-pressure tolerance. German and United States cardiac surgery units specify active suction systems for post-sternotomy drainage, where retained hemothorax risks readmission.
- Abdominal Surgery:Purulent and serous fluid management across diverse operative sites requires flexible catheter configurations with multiple side-hole patterns.
- Orthopedic Surgery:Hematoma prevention in joint arthroplasty and trauma fixation utilizes smaller-diameter drains with moderate suction profiles.
- Plastic Surgery:Seroma prevention in flap procedures and liposuction sites favors low-profile drains with aesthetic concealment priorities.
Thoracic Surgery leads on technology intensity; Abdominal Surgery leads on procedure volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surgical drainage device manufacturing originated in post-war Germany and the United States, where polymer chemistry advances enabled medical-grade catheter production. The industry later dispersed across specialized chemical clusters in Northeast Asia and Western Europe. Today, procurement patterns concentrate in health systems with standardized post-operative protocols.
United States
Ambulatory surgical centers in Texas and Florida are consolidating closed-system procurement around CDC infection-prevention guidelines. The FDA's streamlined 510(k) pathways for Class II devices are accelerating silicone-based innovation timelines. Integrated delivery networks across the Southeast and Midwest are unifying catheter specifications across multi-hospital footprints exceeding ten facilities.
Germany
Academic medical centers in Bavaria and Baden-Württemberg are piloting platinum-cure silicone catheters for post-sternotomy cardiac procedures. The EU MDR's notified body requirements are redirecting certification submissions toward Baltic assessment entities amid capacity constraints in Germany and the Netherlands. Industrial chemical clusters along the Rhine maintain concentrated silicone resin production for catheter fabricators.
Japan
Thoracic surgery units in Tokyo and Osaka are specifying active suction systems with JIS T 0601 electrical safety certification. The PMDA enforces stringent post-market surveillance for active drainage units, creating compliance layering for multinational manufacturers. Medical device manufacturing concentrates in the Chubu region around Nagoya's precision engineering base.
China
Domestic hospital procurement committees in Shanghai and Beijing are migrating from PVC toward silicone catheters for extended-duration applications. The NMPA's updated medical device classification rules are reshaping registration pathways for Class II drainage systems. Yangtze River Delta chemical clusters supply medical-grade silicone resin to regional fabricators.
India
Corporate hospital chains in Maharashtra and Karnataka are standardizing closed drainage protocols for orthopedic and abdominal procedures. The CDSCO's medical device rules are aligning with ISO 13485 quality management standards for imported catheter systems. Manufacturing activity clusters around Ahmedabad's polymer processing corridor and Chennai's medical device special economic zone.
Surgical Drainage Devices Market Key Industry Players
Premium-margin players sit above commodity-margin players across material sophistication and regulatory certification depth. The vendor base stratifies between diversified medtech conglomerates with full-portfolio coverage and specialized catheter fabricators with concentrated silicone expertise. Three archetypes dominate: integrated health system suppliers with direct contracting relationships, regional specialists with notified body certification advantages, and chemical-integrated manufacturers with captive silicone supply. Competitive dynamics center on M&A activity consolidating distribution networks and strategic partnerships securing notified body capacity in Europe.
Among diversified medtech conglomerates, Medtronic, Cardinal Health, and B. Braun Melsungen AG exemplify the integrated health system supplier archetype. Medtronic leverages geographic footprint breadth to sustain presence amid evolving EU MDR certification timelines. Cardinal Health anchors positioning through distribution network density spanning acute and ambulatory channels. B. Braun Melsungen AG occupies a specialized manufacturing position in silicone and polyurethane catheter formulations. These three entities represent distinct strategic postures within the premium-tier competitive set.
| Leading Market Players |
|---|
| Medline Industries |
| Teleflex Incorporated |
| Cardinal Health |
| Stryker |
| Cook Medical |
| Medtronic |
| B. Braun Melsungen AG |
| Smith & Nephew |
| 3M Company |
| Others |
Cost & Logistics Intelligence
United States integrated delivery networks consolidating catheter specifications across multi-facility footprints are forcing supply chain reconfiguration toward direct manufacturer agreements, compressing distributor margins while elevating price transparency in bulk procurement negotiations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies catheter systems by material certification grade and after-sales service bundling. Premium silicone catheters with FDA 510(k) clearance and EU MDR certification command sustained margins, while economy PVC alternatives face cost compression from ambulatory surgical center procurement committees. Hospital systems with standardized protocols exhibit lowest price sensitivity; independent clinics demonstrate highest elasticity.
Supply Chain Analysis
Regional distribution centers in the United States Midwest and Southeast operate hub-and-spoke patterns feeding ambulatory surgical networks with consolidated inventory management. Medical-grade silicone resin production concentrates in Germany, China, and Japan, with catheter fabrication tethered to Northeast Asian chemical clusters and Rhine Valley industrial corridors. Single-source vulnerability in platinum-cure silicone chemistry creates exposure to input cost volatility. Distribution runs through manufacturer-direct contracts replacing traditional distributor mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical drainage devices market represents a late-cycle quality story where outpatient procedure migration toward ambulatory settings is elevating procurement standards for infection-prevention specifications and vacuum-canister interoperability.
For Market Incumbents: Deploy backward integration into medical-grade silicone resin production to defend margin position against Northeast Asian chemical cluster volatility. Consolidate notified body certification capacity through strategic partnerships with Baltic and Eastern European assessment entities to circumvent German and Dutch bottlenecks under EU MDR timelines. For New Entrants and Emerging Players: Begin with ambulatory surgical center closed-system procurement in the United States Southeast and Texas, where same-day discharge protocol standardization creates bulk contract opportunities without incumbent hospital network lock-in. Leverage JIS T 0601 electrical safety certification as differentiation wedge for active suction unit penetration. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized catheter fabricators possessing captive silicone formulation expertise and notified body certification momentum. Five-to-ten-year viability hinges on material science differentiation rather than commodity volume scale. Monitor EU MDR notified body capacity expansion as inflection signal for European market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Certification | Baltic assessment entity partnerships accelerate Class IIa surgical drain market entry timelines. |
| Silicone-Polyurethane Hybrid R&D | Platinum-cure chemistry advances enable cardiac and neurosurgical premium tier penetration. |
| Integrated Delivery Network Direct Contracting | Hospital system partnerships spanning 10-plus facilities displace distributor-mediated purchasing. |
| JIS T 0601 Electrical Safety Alignment | Japanese PMDA certification opens high-value thoracic surgery segments in Tokyo and Osaka. |
| Real-Time Inventory Replenishment Systems | Consumption-based logistics integration meets acute care network unbundled service demands. |
Research Approach
Bottom-up hospital procurement modeling reconciled against top-down silicone resin production tracking forms the analytical core. Primary interviews with biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and ambulatory surgical center administrators combined with secondary validation from FDA 510(k) filings, EU MDR notified body registries, hospital procurement databases, and CMS Medicare reimbursement schedules.
Input-output matrices segment volume and value across device type, material formulation, end-user channel, and application specificity throughout the projection horizon. CAGRs derive from procedure volume elasticity modeling, material substitution rate analysis, and regulatory pathway timeline assumptions. Forecast inputs incorporate ambulatory surgical center expansion trajectories and EU MDR notified body capacity constraints.
Caveats apply where FDA 510(k) pathway modifications, EU MDR implementation delays, or medical-grade silicone supply disruptions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Retractable Needles Market
Surgical Instruments
GCC Minimally Invasive Surgery Market
Surgical Instruments
Cardiac Surgery Instruments Market
Surgical Instruments
Global Gastroenterology Ambulatory Surgery Center Market
Surgical Instruments
Laparoscopic Sutures Market
Surgical Instruments
Global Powered Surgical Instruments Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Plastic Wound Retractor Market
Surgical Instruments
Americas Suture Needles Market
Surgical Instruments
Global Surgical Case Carts Market
Surgical Instruments
Operating Room Smoke Aspirators Market
Surgical Instruments
Dermal Curettes Market
Surgical Instruments
US Integrated Operating Rooms Market
Surgical Instruments
Global Arthroscopy Instruments Market
Surgical Instruments
Hand-Held Surgical Instruments Market
Surgical Instruments
Global Surgical Scalpel Market