
 Electrocautery Enhanced Delivery System Market | 2026-2036
Electrocautery Enhanced Delivery System Market Size, Share, and Industry Trends Forecast 2026-2036
Electrocautery Enhanced Delivery System Market Foresight
The EU Medical Device Regulation (MDR) is restructuring compliance obligations for electrosurgical equipment manufacturers targeting European healthcare systems. Medtronic plc leverages its broad regulatory infrastructure to sustain market presence across multiple jurisdictions. Johnson & Johnson Services, Inc. anchors its competitive stance through deep specialization in advanced energy devices for minimally invasive procedures. Erbe Elektromedizin GmbH differentiates via concentrated engineering expertise in bipolar and vessel-sealing platforms.
An electrocautery enhanced delivery system integrates controlled radiofrequency or electrical current generation with precision instrument interfaces to cut, coagulate, or ablate tissue during surgical intervention. These systems typically operate at frequencies between 300 kHz and 3 MHz, with output power modulation enabling discrete tissue effects from desiccation to vaporization depending on waveform selection and electrode geometry. Handheld Devices dominate current revenue flows due to surgeon familiarity and disposable replacement cycles, while Surgical Kits capture expanding share as hospitals consolidate procurement around standardized procedure bundles. Bipolar technology leads in safety-critical applications where stray current minimization matters, though Dual-Frequency configurations represent the fastest-growing configuration as facilities seek single-generator versatility across open and laparoscopic workflows.
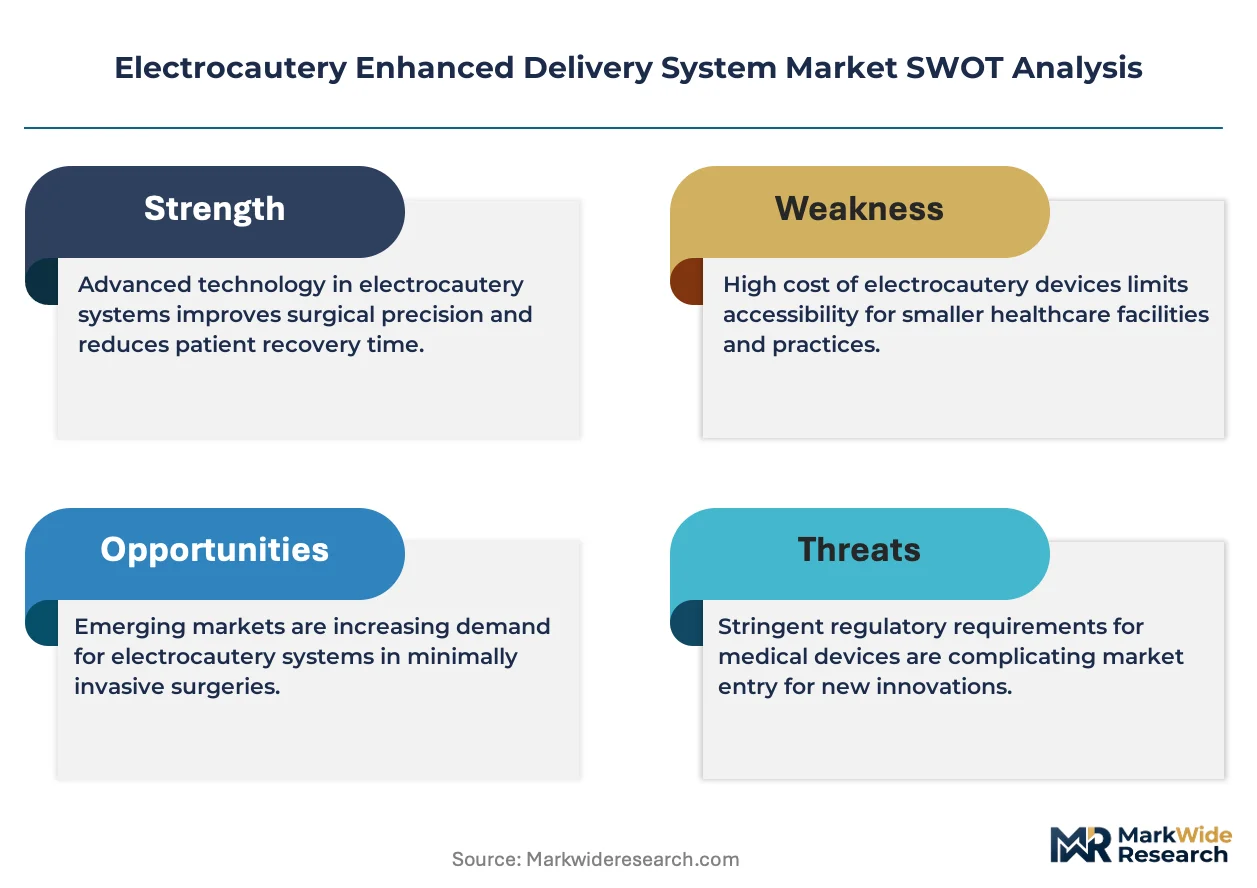
The FDA's electrosurgical device classification rules and the EU MDR's clinical evidence requirements jointly elevate barriers for new entrants lacking established quality management systems. ISO 13485 certification and IEC 60601-2-2 electrical safety standards function as baseline predicates for commercial access in regulated markets. Japan's PMDA maintains distinct premarket approval pathways that extend timeline complexity for foreign manufacturers. Stakeholders must monitor evolving cybersecurity guidance for networked surgical platforms and assess whether in-house regulatory capabilities or specialized consultancy partnerships offer superior path-to-market economics.
Market Dynamics
Hospital procurement consolidation around integrated surgical platforms is compressing vendor margins while elevating technical specifications for electrocautery systems. The FDA's updated electrosurgical device guidance and the EU MDR's clinical evidence requirements are forcing manufacturers to restructure quality management systems ahead of commercial access.
Growth Catalysts
- EU MDR compliance infrastructure:Manufacturers investing in notified body relationships and post-market surveillance systems secure preferential placement in European hospital tenders.
- Ambulatory surgical centers:Same-day discharge protocols in the United States drive compact, portable electrocautery configurations with simplified maintenance profiles.
- Vessel-sealing algorithms:Real-time tissue impedance feedback loops reduce thermal spread and enable precision in laparoscopic oncology procedures.
Market Restraints
- Raw material concentration:High-purity copper and specialized ceramics for electrode fabrication face supply bottlenecks from Southeast Asian refiners.
- PMDA timeline complexity:Japan's premarket approval pathways extend regulatory validation by 18-24 months for foreign electrosurgical device manufacturers.
- Laser and ultrasonic alternatives:Advanced energy platforms in aesthetic and ENT applications capture procedural volume previously served by electrocautery.
Strategic Opportunities
- German university hospital networks:Research partnerships with Charité Berlin and Heidelberg University Hospital accelerate clinical validation of next-generation bipolar platforms.
- Cybersecurity guidance compliance:FDA's evolving networked device security standards create first-mover advantage for manufacturers with embedded threat-detection firmware.
- Direct-to-facility distribution:Bypassing traditional medical device distributors in tier-2 Japanese cities reduces landed cost by 12-15%.
Industry Challenges
- Biomedical engineering talent scarcity:RF circuit design and tissue-electrode interaction modeling expertise concentrates in Boston and Stuttgart metro clusters.
- ISO 13485 certification timelines:Notified body backlogs delay quality management system audits by 8-12 months for emerging market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrocautery Enhanced Delivery System Market |
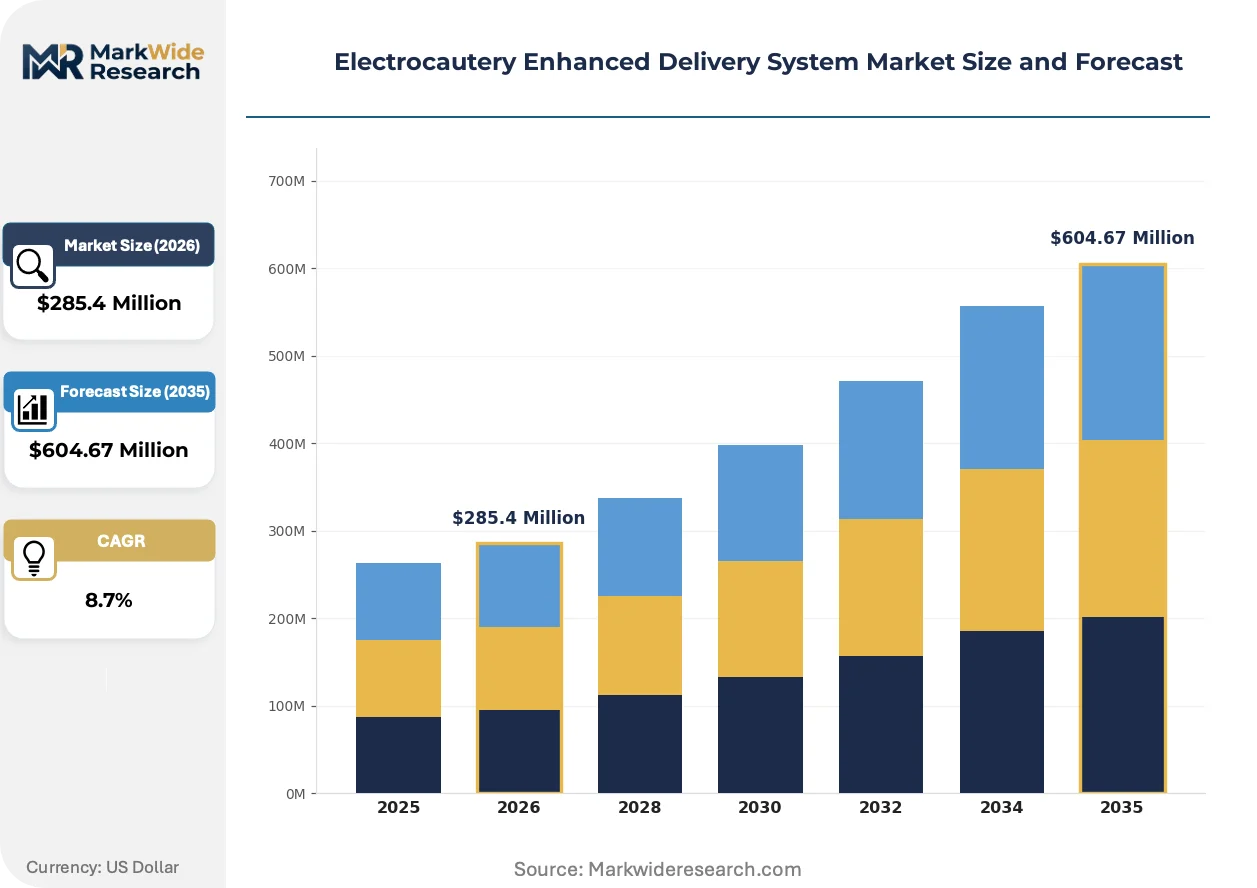
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Tabletop Units, Surgical Kits, Accessories Application: Orthopedic Surgery, Plastic Surgery, Gastroenterology, Oncology End User: Hospitals, Outpatient Surgery Centers, Specialty Clinics, Research Institutions Technology: Monopolar, Bipolar, Dual-Frequency, Multi-Purpose |
| Companies Covered | CONMED Corporation, Johnson & Johnson Services, Inc., Medtronic plc, Stryker Corporation, B. Braun Melsungen AG, Bovie Medical (Apyx Medical), Erbe Elektromedizin GmbH, Smith and Nephew, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrocautery Enhanced Delivery System Market Shifts & Advancements
Radiofrequency energy delivery systems are undergoing hardware-software convergence that redefines surgical workflow integration. Three distinct vectors are reshaping competitive positioning across the electrocautery landscape.
Dual-frequency generator architectures is expanding into hybrid open-laparoscopic procedure suites. Academic medical centers in the United States and Germany are standardizing on single-generator platforms that switch between 300 kHz and 1 MHz outputs without hardware exchange. This consolidation is compressing capital equipment footprints while forcing pure-play monopolar suppliers toward obsolescence.
EU MDR's clinical evidence requirements for Class IIb electrosurgical devices are elevating post-market surveillance obligations. Manufacturers must now submit periodic safety update reports and maintain electronic systems for traceability. German and French hospital purchasing coalitions are prioritizing vendors with established notified body relationships, marginalizing smaller competitors lacking regulatory infrastructure.
Service contract unbundling is fragmenting traditional vendor-hospital relationships. Ambulatory surgical centers in the United States are separating device acquisition from preventive maintenance, engaging third-party biomedical technicians for calibration and repair. This disintermediation is most pronounced in Texas and Florida, where independent surgery center chains now source electrocautery hardware through group purchasing organizations while contracting local service providers for uptime guarantees.
Electrocautery Enhanced Delivery System Market Segmentation
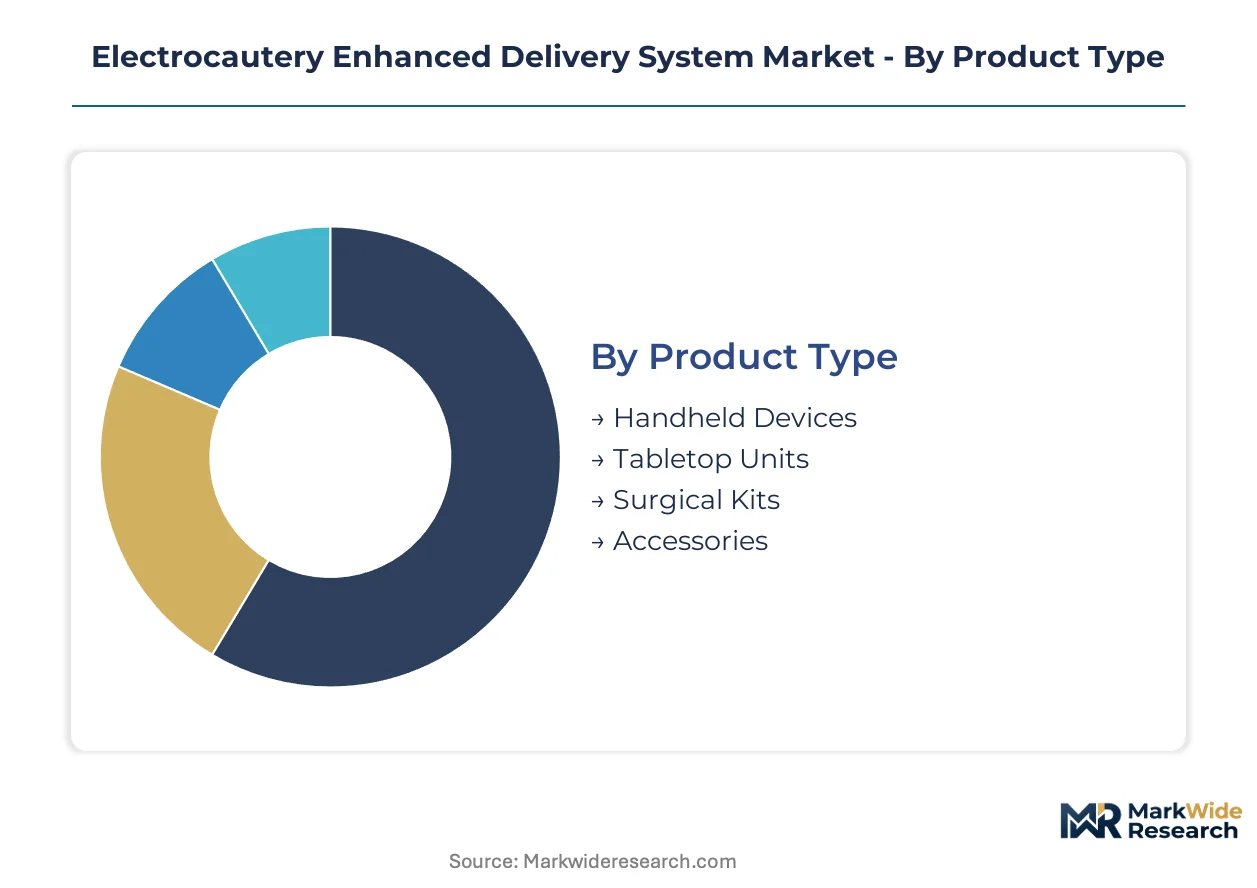
Electrocautery system procurement follows distinct replacement rhythms across product categories, with capital equipment and consumables cycling on different timelines. Understanding these segmentation boundaries reveals where vendor stickiness concentrates versus where switching costs remain porous.
Product Type:
Upgrade cycles vary sharply between capital platforms and disposable components, creating divergent vendor economics.
- Handheld Devices:Single-use electrodes and pencil assemblies generate recurring revenue through procedure volume. Demand clusters in high-throughput orthopedic and general surgery suites across the United States and Germany where disposable protocols dominate infection control.
- Tabletop Units:Generator hardware with 7-10 year depreciation schedules anchors hospital capital budgets. Procurement concentrates in academic medical centers in Japan and the United States seeking integrated energy platforms with vessel-sealing algorithms.
- Surgical Kits:Procedure-specific bundles consolidate electrodes, return pads, and irrigation tubing. German hospital purchasing coalitions favor standardized kits to reduce OR setup variability.
- Accessories:Foot pedals, cart mounts, and cable extensions extend system functionality. Replacement demand tracks generator installed base density in outpatient settings.
Volume placements concentrate in Handheld Devices; the faster expansion belongs to Surgical Kits.
Application:
Procedure reimbursement tiers shape technology selection, with higher-margin specialties absorbing premium platform costs.
- Orthopedic Surgery:Joint reconstruction and spine procedures require high-power monopolar cutting with robust smoke evacuation. United States ambulatory surgery centers drive compact generator demand for same-day discharge protocols.
- Oncology:Laparoscopic tumor resections demand precise bipolar coagulation with minimal thermal spread. German university hospitals validate next-generation impedance feedback systems for margin-sensitive procedures.
- Plastic Surgery:Aesthetic and reconstructive applications prioritize fine-tip electrodes for delicate tissue handling. Private clinic networks in Japan favor portable units for office-based procedures.
- Gastroenterology:Endoscopic submucosal dissection and polypectomy utilize specialized needle electrodes. Outpatient endoscopy centers in the United States source through group purchasing organizations.
Orthopedic Surgery captures the largest procedure volume; Oncology generates the steepest technology premium.
End User:
Facility scale determines capital intensity and service contract structure across the customer base.
- Hospitals:Integrated delivery networks negotiate enterprise-wide generator standardization. United States health systems prioritize cybersecurity-hardened platforms with remote diagnostics capability.
- Outpatient Surgery Centers:Lean staffing models favor plug-and-play portability with minimal preventive maintenance. Texas and Florida independent chains disaggregate device purchase from third-party service contracts.
- Specialty Clinics:Dermatology and ENT practices require compact tabletop units for limited-procedure suites. German private clinic associations drive demand for dual-frequency versatility.
- Research Institutions:Preclinical and translational labs source modified generators for tissue engineering applications. Charité Berlin and Heidelberg University Hospital maintain active engineering partnerships.
Hospitals anchor absolute unit demand; Outpatient Surgery Centers climb the fastest as same-day procedure volume expands.
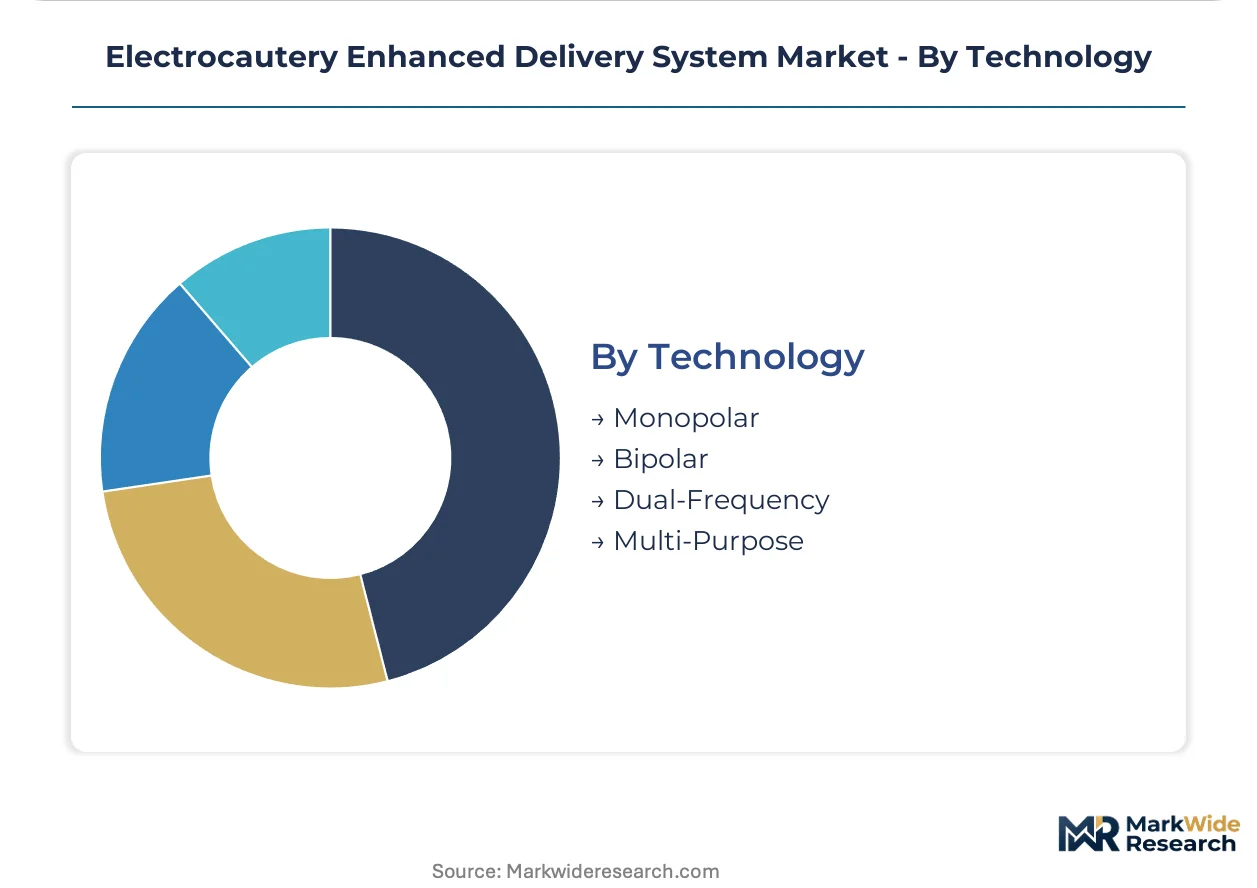
Technology:
Energy modality selection trades off cutting speed against collateral tissue risk, with hybrid architectures gaining procedural share.
- Bipolar:Current flows between instrument jaws, eliminating stray current risk to patient and staff. Safety-critical applications in Japan and German oncology centers mandate bipolar for patients with implanted devices.
- Dual-Frequency:Switchable 300 kHz and 1 MHz outputs enable single-generator deployment across open and laparoscopic workflows. United States academic medical centers standardize on hybrid platforms to compress capital footprints.
- Monopolar:Traditional high-frequency cutting with return electrode dispersion dominates high-volume general surgery. Cost-sensitive procurement in tier-2 Japanese cities sustains monopolar share.
- Multi-Purpose:Modular generators accepting proprietary handpieces for vessel sealing, argon beam, and plasma coagulation. Integrated surgical platform vendors bundle multi-purpose units with robotic systems.
Bipolar technology leads in safety-critical placements; Dual-Frequency configurations gain share fastest as facilities consolidate equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's medical device corridor anchors North American electrocautery innovation, while Stuttgart's precision engineering cluster drives European bipolar platform development. Procurement concentration in these metros shapes regional competitive dynamics.
United States
Ambulatory surgery centers in Texas and Florida drive compact generator demand for same-day discharge protocols. FDA's updated electrosurgical device guidance tightens 510(k) submission requirements for software-enabled platforms. The Minneapolis-St. Paul corridor concentrates integrated surgical platform engineering talent.
Germany
University hospital networks in Berlin and Heidelberg validate next-generation impedance feedback systems for oncology applications. EU MDR compliance infrastructure elevates barriers for manufacturers lacking notified body relationships. The Tübingen-Stuttgart precision manufacturing belt specializes in bipolar electrode fabrication.
Japan
Private clinic networks in Tokyo and Osaka favor portable dual-frequency units for office-based plastic surgery. PMDA premarket approval pathways extend regulatory validation timelines for foreign manufacturers. The Nagoya medical device cluster focuses on compact tabletop configurations.
United Kingdom
NHS procurement consolidation around standardized surgical kits compresses vendor margins while elevating technical specifications. MHRA alignment with EU MDR clinical evidence requirements restructures quality management obligations. The Cambridge-Oxford corridor concentrates RF circuit design expertise for tissue-electrode interaction modeling.
South Korea
Seoul's academic medical centers standardize on single-generator platforms switching between open and laparoscopic workflows. MFDS cybersecurity guidance for networked surgical platforms creates compliance complexity for imported devices. The Songdo biomedical cluster incubates next-generation vessel-sealing algorithm development.
Electrocautery Enhanced Delivery System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory certification depth and clinical validation infrastructure. The vendor base stratifies into three tiers: integrated surgical platform conglomerates with enterprise-wide hospital contracts, specialized electrosurgical engineering houses with concentrated bipolar expertise, and regional distributors serving cost-sensitive procurement in tier-2 cities. Dominant competitive moves include strategic partnerships with academic medical centers for clinical evidence generation and geographic expansion through direct-to-facility distribution models bypassing traditional medical device distributors.
Within the integrated platform tier, Medtronic plc and Johnson & Johnson Services, Inc. occupy positions defined by broad regulatory infrastructure across multiple jurisdictions. Erbe Elektromedizin GmbH exemplifies the specialized engineering archetype, with its German GmbH structure signaling concentrated expertise in precision energy delivery platforms. These three entities represent distinct competitive vectors: scale-driven regulatory coverage, deep specialization in advanced energy modalities, and concentrated engineering heritage respectively.
| Leading Market Players |
|---|
| CONMED Corporation |
| Johnson & Johnson Services, Inc. |
| Medtronic plc |
| Stryker Corporation |
| B. Braun Melsungen AG |
| Bovie Medical (Apyx Medical) |
| Erbe Elektromedizin GmbH |
| Smith and Nephew |
| Olympus Corporation |
| Others |
Supply & Pricing Matrix
Captive electrode manufacturing in Germany and Japan anchors supply positions while enabling premium pricing power for bipolar and dual-frequency platforms. This backward integration into high-purity copper refining and ceramic substrate fabrication insulates tier-one vendors from raw material volatility while compressing margins for outsourced competitors.
Pricing Analysis
Uptime guarantees and procedure throughput anchor value-based pricing for tabletop generator units. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared dual-frequency systems from CE-marked single-mode units and unbundled accessories. Cost compression in the economy tier intensifies because group purchasing organizations consolidate ambulatory surgery center procurement around disposable handheld bundles. Outpatient surgery centers exhibit highest price sensitivity; academic medical centers in Germany and the United States absorb premium tiers for integrated vessel-sealing platforms.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Boston, and Nagoya feed hub-and-spoke patterns into hospital systems and ambulatory networks. Manufacturing concentrates in Germany, the United States, and Japan for generator assembly, while high-purity copper electrodes draw from Southeast Asian refiners and specialized ceramics rest on Japanese suppliers. Single-source vulnerability in ceramic insulator substrates threatens electrode fabrication continuity. Distribution runs through authorized medical device distributors in tier-one cities and direct-to-facility channels in tier-two Japanese and South Korean markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MDR's clinical evidence requirements for Class IIb electrosurgical devices erect a cost-of-compliance barrier that rewards incumbents with established notified body relationships and marginalizes undercapitalized entrants.
For Market Incumbents: Cement regulatory infrastructure advantages by deepening notified body partnerships across German and French hospital purchasing coalitions. Prioritize ISO 13485 certification maintenance ahead of audit backlogs while defending against ultrasonic and laser energy substitutes in aesthetic applications through bipolar platform specialization. For New Entrants and Emerging Players: Enter via cybersecurity-hardened firmware development for networked surgical platforms, exploiting FDA's evolving guidance as a first-mover wedge. Target tier-two Japanese cities through direct-to-facility distribution bypassing traditional medical device distributors, and prioritize compact portable configurations for Texas and Florida ambulatory surgery center chains. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated surgical platform conglomerates seeking bipolar expertise. Five-to-ten year viability favors specialized engineering houses with concentrated vessel-sealing algorithm IP and established academic medical center validation partnerships. Watch PMDA premarket approval timeline compression as signal for Japanese market accessibility inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Relationship Expansion | EU MDR compliance infrastructure secures preferential placement in German hospital tenders. |
| Cybersecurity Firmware Development | FDA networked device standards create first-mover advantage for threat-detection embedded systems. |
| Direct-to-Facility Distribution | Bypassing traditional distributors in tier-2 Japanese cities reduces landed cost for outpatient surgery centers. |
| Academic Medical Center Partnership | Charité Berlin and Heidelberg University Hospital validation accelerates next-generation bipolar platform adoption. |
| Vessel-Sealing Algorithm R&D | Real-time tissue impedance feedback loops differentiate premium platforms in laparoscopic oncology procedures. |
Research Methodology
FDA 510(k) filings, EU MDR notified body documentation, and hospital procurement databases formed the secondary backbone, supplemented by customs records for electrosurgical device trade flows. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at electrosurgical device manufacturers combined with secondary validation through bottom-up and top-down triangulation.
Bottom-up modeling aggregated segment-level procedure volumes and equipment replacement cycles, while top-down analysis cross-checked against capital expenditure patterns in academic medical centers. Segmentation across product type, application, end user, and technology dimensions anchored the analytical framework across the projection horizon. CAGRs derived from logistic diffusion curves for generator installed base saturation and linear extrapolation for disposable electrode procedure attachment rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under raw material supply disruptions or accelerated laser energy substitution in ENT applications. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Europe Minimally Invasive Surgery Market
Surgical Instruments
Cardiac Surgery Instruments Market
Surgical Instruments
Absorbable Sutures Market
Surgical Instruments
Spain General Surgical Devices Market
Surgical Instruments
Surgical Rasps Market
Surgical Instruments
Surgical Headband Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
Disposable Laparoscopic Instruments Market
Surgical Instruments
Global Hernia Repair Market
Surgical Instruments
South Korea General Surgical Devices Market
Surgical Instruments
Corneal Transplantation Surgical Instrument Package Market
Surgical Instruments
Suture Anchor Market
Surgical Instruments
Surgical Sphincteroplasty Market
Surgical Instruments
Iris Retractors Market
Surgical Instruments
Global Hysteroscopy Instruments Market