
 Glass Veil Market | 2026-2036
Glass Veil Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Veil Market Analytics
Chinese fiberglass producers is broadening output capacity for thin-gauge industrial veils serving cross-border supply chains. Owens Corning leverages its North American mineral wool infrastructure to anchor regional distribution for building insulation applications. Saint-Gobain competes through specialized coated glass formulations targeting aerospace thermal protection systems. Jushi Group dominates bulk non-woven veil supply for Asian construction markets with integrated melt-spinning operations.
Glass veil denotes a thin, permeable sheet of continuous or chopped glass fibers bonded by chemical or thermal means, typically weighing between 30 and 100 grams per square meter, engineered to provide surfacing reinforcement, corrosion barriers, or thermal insulation in composite laminates. Non-woven fabric leads volume production due to lower manufacturing complexity and broader compatibility with resin infusion processes, while coated glass commands premium positioning in aerospace components where fire-retardant specifications are stringent. Building insulation anchors the largest application share as energy retrofit mandates intensify across mature construction markets.
EPA emissions standards and OSHA workplace exposure limits govern fiberglass particulate handling in United States manufacturing facilities, while REACH and RoHS frameworks in Europe restrict hazardous binder chemistries in imported veil products. China's GB standards and MIIT industrial guidelines set domestic benchmarks for glass fiber purity and tensile performance in construction-grade materials. Stakeholders must monitor divergence between regional chemical compliance regimes as cross-border certification costs reshape supplier selection criteria for multinational composite buyers.
Market Dynamics
Automotive electrification is forcing rapid recalibration of glass veil specifications as battery thermal management becomes the dominant performance criterion for composite suppliers.
Growth Catalysts
- EPA emissions standards:Tightened thermal efficiency mandates in United States building codes are accelerating specification of high-performance glass veil insulation in commercial retrofit projects.
- EV battery enclosures:Automotive OEMs are expanding procurement of lightweight glass veil composites to meet weight reduction targets for electric vehicle platforms.
- China construction volume:Jiangsu and Zhejiang provinces are driving domestic absorption of non-woven glass veil for infrastructure and residential energy efficiency programs.
Market Restraints
- Borosilicate raw material volatility:Energy-intensive glass melting operations face input cost pressure from natural gas and electricity price swings in European manufacturing zones.
- Supply concentration:Bulk chopped strand mat production clusters in Shandong Province create geographic vulnerability for international buyers dependent on Chinese export channels.
- Aramid fiber substitution:Aerospace thermal protection segments are partially migrating toward aramid-based alternatives where extreme temperature thresholds exceed glass veil performance envelopes.
Strategic Opportunities
- India building stock expansion:Urban residential construction in Maharashtra and Karnataka states presents underpenetrated demand for cost-optimized glass veil insulation systems.
- Hydrogen storage vessels:Composite pressure vessel manufacturers are evaluating glass veil surfacing layers for cryogenic containment applications in emerging hydrogen infrastructure.
- EU Green Deal renovation wave:Building retrofit mandates across Germany, France, and Poland are creating regulatory tailwinds for imported high-efficiency thermal barrier materials.
Industry Challenges
- Process engineering talent scarcity:Wet-laid non-woven production lines require specialized technicians familiar with slurry consistency control and binder chemistry optimization.
- Multi-jurisdiction certification timelines:REACH compliance documentation for European importation adds six-to-nine month lead times for Asian manufacturers seeking market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Veil Market |
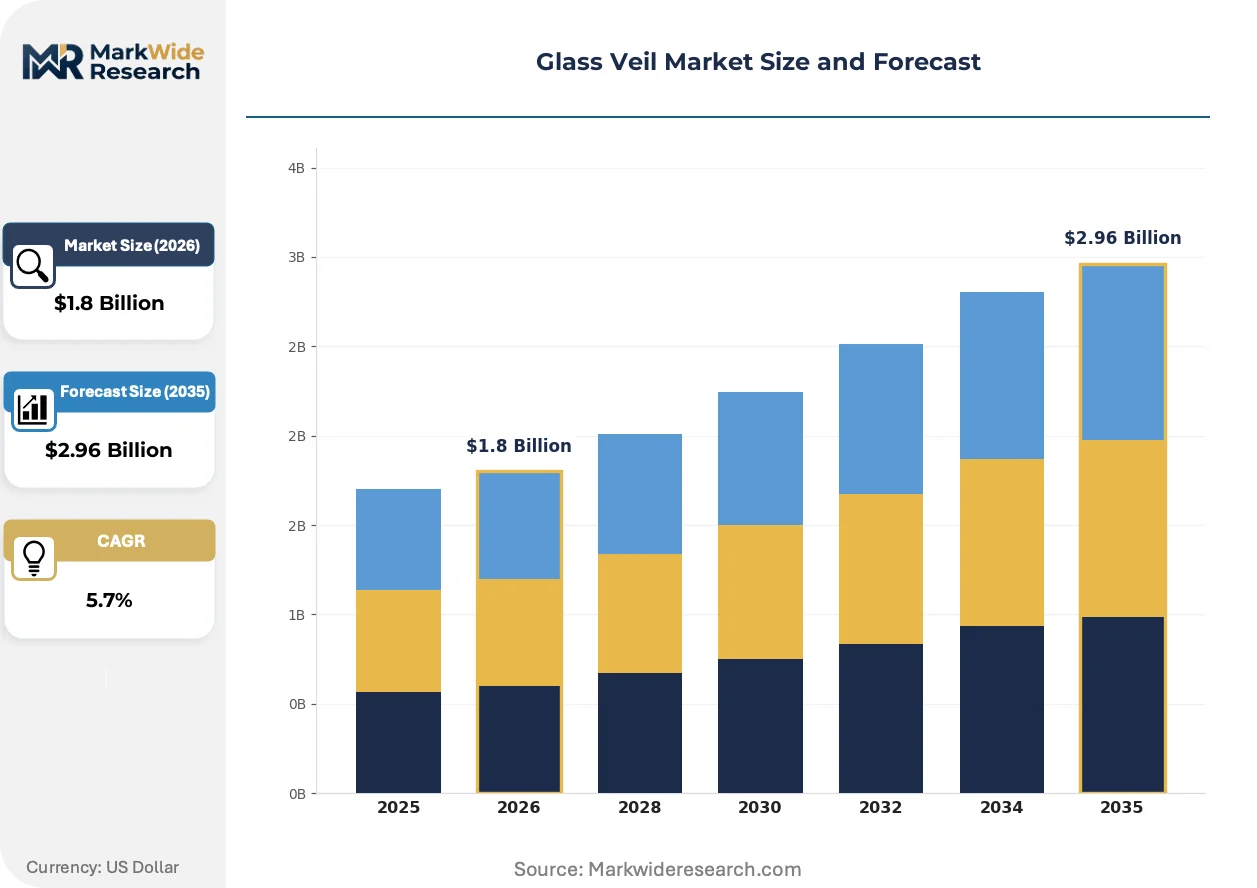
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabric, Non-Woven Fabric, Coated Glass, Laminated Glass Application: Automotive Interiors, Building Insulation, Aerospace Components, Consumer Electronics End User: Construction Industry, Automotive Manufacturers, Electronics Firms, Aerospace Companies Distribution Channel: Wholesale Distributors, Direct Sales, Online Retailers, Specialty Stores |
| Companies Covered | Johns Manville, Owens Corning, Saint-Gobain, Ahlstrom-Munksjö, Jiangsu Changhai Composite, Sinoma Jinjing Fiberglass, Shaanxi HuaTek Fiberglass Material, Jushi Group, Nippon Electric Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Veil Market Evolving Landscape
Material science convergence with digital manufacturing is compressing product development cycles and enabling mass customization of glass veil specifications for niche thermal management applications.
Coated glass veil formulations incorporating intumescent chemistries is expanding into aerospace fire protection segments as tier-one suppliers seek lighter alternatives to traditional ceramic blankets. Boeing and Airbus specification teams are accelerating qualification timelines for these materials. The technology is expanding into adjacent markets including high-speed rail interior panels where smoke toxicity standards are tightening.
REACH authorization requirements for formaldehyde-based binders are forcing European manufacturers toward bio-based acrylic alternatives with modified curing profiles. ECHA substance evaluation processes are extending reformulation timelines by twelve to eighteen months for incumbent suppliers. German and French composite laminators are absorbing premium pricing for compliant imported veils while domestic capacity retools.
Automotive battery pack engineers are consolidating supplier relationships around vertically integrated glass veil producers capable of delivering certified thermal runaway barriers with full traceability documentation. Tier-one suppliers are displacing fragmented distributor networks with direct mill relationships. This pattern is most visible in South Korean and German EV manufacturing clusters where OEM liability exposure drives specification stringency.
Glass Veil Market Segmentation
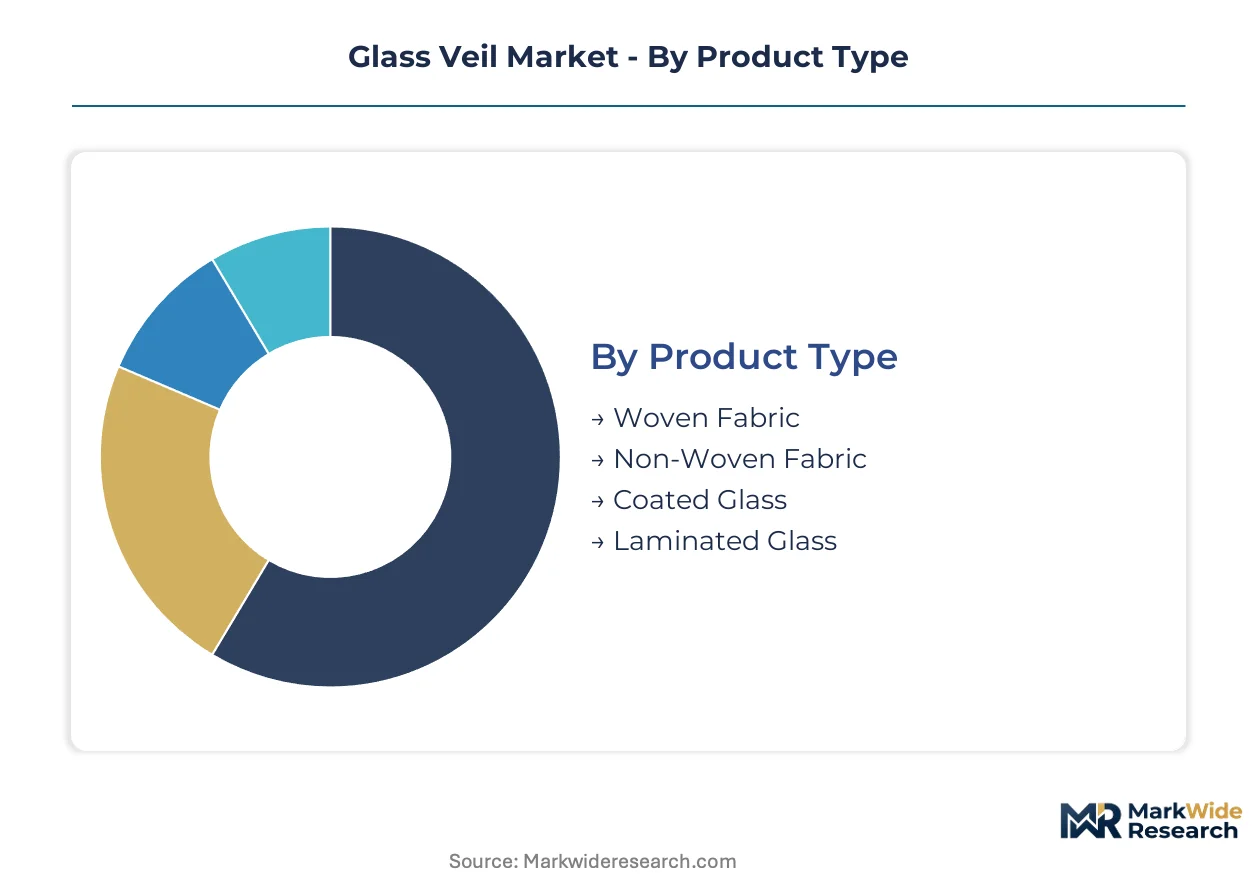
Glass veil specifications diverge sharply across end-use environments, with thermal performance thresholds and resin compatibility requirements dictating product selection. Procurement patterns in this market track closely to upgrade cycles in automotive electrification and building energy retrofit mandates.
Product Type:
Replacement demand in mature applications is tilting procurement toward lighter-weight alternatives that maintain mechanical integrity under reduced material loading.
- Non-Woven Fabric:Chopped or continuous glass fibers bonded thermally or chemically into permeable sheets weighing 30-100 gsm, engineered for resin infusion compatibility. Construction-grade specifications dominate procurement volumes in China’s Jiangsu and Zhejiang provinces, where infrastructure energy efficiency programs absorb bulk supply from integrated melt-spinning operations.
- Coated Glass:Specialized formulations incorporating intumescent or fire-retardant surface treatments for extreme thermal protection. Aerospace qualification timelines at Boeing and Airbus specification teams are accelerating for these materials as lighter alternatives to ceramic blankets, with secondary penetration into high-speed rail interior panels where smoke toxicity standards are tightening.
- Woven Fabric:Interlaced continuous filament constructions providing structural reinforcement in composite laminates.
- Laminated Glass:Multi-layer bonded assemblies combining glass veil with polymer interlayers for enhanced barrier properties.
Volume placements concentrate in Non-Woven Fabric; the faster expansion belongs to Coated Glass.
Application:
Cost-tier differentiation separates commodity thermal insulation from certified fire protection systems where regulatory compliance documentation commands substantial premiums.
- Building Insulation:Surfacing layers and thermal barriers in commercial and residential envelope systems. EPA emissions standards and tightened thermal efficiency mandates in United States building codes are accelerating specification in commercial retrofit projects across mature construction markets.
- Automotive Interiors:Battery thermal management barriers and lightweight structural reinforcements for electric vehicle platforms. OEM procurement is consolidating around vertically integrated producers capable of delivering certified thermal runaway barriers with full traceability documentation, particularly in South Korean and German EV manufacturing clusters.
- Aerospace Components:Fire protection and thermal insulation in aircraft and spacecraft systems.
- Consumer Electronics:Dielectric barriers and thermal management in device housings and battery compartments.
Building Insulation anchors current procurement tonnage; Automotive Interiors is climbing the fastest as electrification reshapes material specifications.
End User:
Customer-type fragmentation creates divergent procurement rhythms, with project-based construction demand contrasting against automotive program-cycle contracting.
- Construction Industry:Developers, contractors, and building envelope specialists specifying thermal insulation and reinforcement materials. EU Green Deal renovation wave mandates across Germany, France, and Poland are creating regulatory tailwinds for imported high-efficiency thermal barrier materials.
- Automotive Manufacturers:OEMs and tier-one suppliers integrating glass veil into battery enclosures and interior components. Direct mill relationships are displacing fragmented distributor networks as liability exposure drives specification stringency.
- Electronics Firms:Device manufacturers requiring dielectric and thermal management solutions.
- Aerospace Companies:Airframe and propulsion system integrators specifying certified fire protection materials.
Construction Industry holds the installed base; Automotive Manufacturers are gaining share fastest on electrification-driven specification changes.
Distribution Channel:
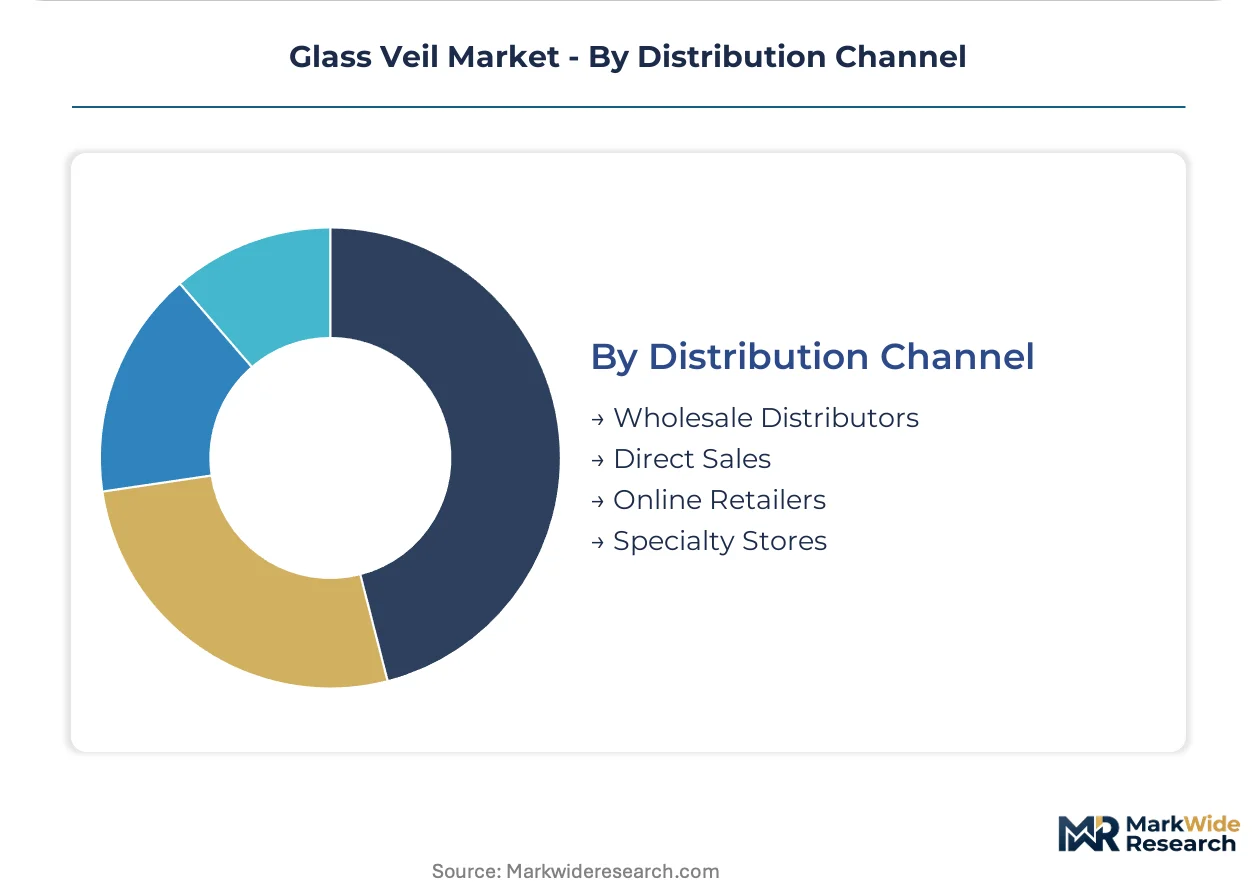
Supply concentration in Shandong Province and Jiangsu manufacturing clusters shapes channel economics, with bulk commodity flows favoring wholesale aggregation while certified grades migrate through direct relationships.
- Direct Sales:Mill-direct procurement relationships with tier-one automotive and aerospace OEMs. Tier-one suppliers are consolidating supplier relationships around vertically integrated producers capable of delivering certified thermal runaway barriers with full traceability documentation.
- Wholesale Distributors:Aggregated supply for construction and general industrial applications serving fragmented buyer bases.
- Online Retailers:Digital channels for standardized grades and small-volume procurement.
- Specialty Stores:Niche outlets serving repair, maintenance, and custom fabrication segments.
Wholesale Distributors still handle the heaviest volume flows; Direct Sales is expanding most quickly as automotive and aerospace procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Borosilicate sand deposits in Shandong Province and natural gas access in Sichuan Basin anchor Chinese production economics. German technical glass heritage clusters around Bavarian precision manufacturing zones. United States shale gas proximity benefits Texas and Louisiana melting operations.
China
MIIT industrial guidelines and GB standards govern glass fiber purity specifications for construction-grade veils. Jiangsu Changhai Composite and Sinoma Jinjing Fiberglass operate integrated melt-spinning facilities serving domestic energy retrofit programs and export channels. Shandong Province concentrates bulk chopped strand mat capacity, creating geographic concentration risk for international buyers.
Germany
EU Green Deal renovation wave mandates and REACH authorization requirements for formaldehyde-based binders are reshaping import sourcing. ECHA substance evaluation processes extend reformulation timelines for domestic manufacturers retooling toward bio-based acrylic alternatives. Bavarian composite laminators absorb premium pricing for compliant imported veils while regional capacity adapts.
United States
EPA emissions standards and tightened thermal efficiency mandates in commercial building codes accelerate specification of high-performance insulation. OSHA workplace exposure limits govern fiberglass particulate handling in manufacturing facilities. Owens Corning leverages mineral wool infrastructure across Midwestern states to anchor regional distribution networks.
Japan
METI energy efficiency targets and JIS standards for thermal barrier materials drive specification in commercial retrofit segments. Nippon Electric Glass maintains technical glass heritage operations serving aerospace and electronics applications. Kanto region manufacturing clusters specialize in thin-gauge industrial veils for precision composite laminates.
India
BIS standards for building envelope materials and state-level energy conservation building codes create compliance frameworks for imported thermal barriers. Maharashtra and Karnataka urban residential construction presents absorption capacity for cost-optimized insulation systems. Western region infrastructure programs drive procurement of non-woven glass veil for commercial envelope applications.
Glass Veil Market Competitive Landscape
Global majors compete with regional champions across certification capability and geographic proximity to automotive OEM clusters. Market structure tilts toward consolidation at the premium tier where full traceability documentation and multi-jurisdiction compliance separate qualified suppliers from commodity producers. Three archetypes dominate: integrated mineral wool conglomerates with backward control over melting operations, specialized non-woven fabricators with captive slurry-laid production lines, and coated glass specialists serving aerospace qualification timelines. Capacity expansion and direct mill relationships with tier-one automotive suppliers constitute the dominant competitive moves.
Among North American building materials conglomerates, Johns Manville and Owens Corning exemplify integrated mineral wool heritage applied to glass veil distribution networks. Saint-Gobain occupies a position within European technical glass specialists targeting aerospace thermal protection qualification. Jiangsu Changhai Composite and Sinoma Jinjing Fiberglass represent Chinese state-affiliated champions with concentrated capacity in Jiangsu and Shandong production zones. Jushi Group anchors the Asian non-woven bulk supply tier with integrated melt-spinning operations.
| Leading Market Players |
|---|
| Johns Manville |
| Owens Corning |
| Saint-Gobain |
| Ahlstrom-Munksjö |
| Jiangsu Changhai Composite |
| Sinoma Jinjing Fiberglass |
| Shaanxi HuaTek Fiberglass Material |
| Jushi Group |
| Nippon Electric Glass |
| Others |
Value Network & Pricing Analysis
Borosilicate sand procurement costs cascade through three distinct pricing tiers as raw material volatility from Shandong Province melting operations compresses margins for non-woven fabric grades while coated glass specialists in Bavaria capture premium positioning through aerospace qualification documentation.
Pricing Analysis
Warranty and traceability documentation bundling separates premium-tier suppliers from commodity producers as automotive OEMs mandate full certification packages for thermal runaway barriers. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by REACH compliance grade and volume scale. Pricing pressure stems from energy-intensive melting operations facing natural gas cost swings in European manufacturing zones. Construction procurement teams in Jiangsu province exhibit highest price sensitivity, while aerospace specification teams at Boeing and Airbus absorb substantial premiums for qualified intumescent formulations.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore anchor hub-and-spoke patterns for bulk non-woven shipments serving fragmented construction buyers. Supply concentrates in China, Germany, and the United States as borosilicate sand deposits in Shandong Province and natural gas access in Sichuan Basin anchor production economics. Raw material dependencies include borosilicate sand, soda ash, and natural gas for melting operations. Single-source vulnerability from Shandong Province bulk chopped strand mat clusters creates geographic concentration risk for international buyers. Distribution runs through direct mill relationships for automotive and aerospace tiers, with wholesale aggregation serving construction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coated glass veil formulations incorporating intumescent chemistries are displacing traditional ceramic blankets in aerospace thermal protection, compressing qualification timelines and consolidating procurement around vertically integrated producers capable of delivering certified fire protection with full traceability documentation.
For Market Incumbents: Cement backward integration into borosilicate sand processing and captive melting operations to defend against raw material volatility from Shandong Province supply clusters. Owens Corning and Saint-Gobain should accelerate certification investment for REACH-compliant bio-based acrylic binders as ECHA substance evaluation processes extend reformulation timelines for competitors. Channel control through direct mill relationships with South Korean and German EV manufacturing clusters insulates against distributor displacement.
For New Entrants and Emerging Players: Digital marketplace platforms for standardized construction-grade non-woven veils offer the lowest friction entry path. Maharashtra and Karnataka urban residential construction presents the most penetrable white-space as Indian state-level energy conservation building codes create compliance-driven demand for cost-optimized thermal barriers. Hydrogen storage vessel surfacing layers for cryogenic containment applications provide a technical differentiation angle with limited incumbent qualification.
For Investors and Strategic Acquirers: Automotive OEM consolidation of supplier relationships around vertically integrated producers is the leading indicator that mill-direct certification capability commands sustained premium multiples. The five-to-ten year viability window favors acquisition targets with captive slurry-laid production lines and existing aerospace qualification timelines at Boeing or Airbus specification teams. Watch for tier-one automotive procurement teams displacing fragmented distributor networks as the inflection signal for supplier consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Processing | Captive sand processing in Shandong Province insulates margin from raw material volatility. |
| REACH-Compliant Binder Reformulation | Bio-based acrylic alternatives command premium pricing while ECHA timelines delay competitor retooling. |
| Aerospace Qualification Acceleration | Boeing and Airbus specification team engagement positions coated glass as ceramic blanket replacement. |
| Direct Mill Relationship Consolidation | Tier-one automotive procurement teams favor full traceability documentation over distributor networks. |
| Hydrogen Vessel Surfacing Layer Development | Cryogenic containment qualification opens adjacent market beyond automotive and aerospace segments. |
Research Methodology
Multi-period observation of automotive electrification procurement patterns, building energy retrofit mandate implementation, and aerospace qualification timeline compression anchored the trend analysis, supplemented by interviews with glass veil plant managers, procurement leads at composite laminators, technical R&D directors at non-woven fabricators, and distribution channel partners serving construction and automotive segments. Secondary validation drew from MIIT industrial guidelines, ECHA substance evaluation databases, EPA emissions standard filings, customs and trade data for borosilicate sand and glass fiber imports, and SEC 10-K disclosures from integrated mineral wool conglomerates. Bottom-up volume modeling across product type and application segments triangulated against top-down macroeconomic drivers.
Segment-weighting approaches applied differential growth assumptions across non-woven fabric, coated glass, woven fabric, and laminated glass categories, with further disaggregation by building insulation, automotive interiors, aerospace components, and consumer electronics applications. CAGRs were derived through regression analysis of historical procurement volumes against regulatory mandate implementation schedules and OEM platform launch cycles. Forecast inputs included automotive battery pack thermal management specification evolution, EU Green Deal renovation wave mandate intensity, and hydrogen infrastructure deployment trajectories for composite pressure vessel demand.
The model holds under continued automotive electrification and building energy efficiency regulatory tightening; deviation in borosilicate raw material cost volatility, aramid fiber substitution acceleration in aerospace, or REACH authorization timeline extensions would shift volume and value trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Benelux Container Glass Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
Europe Cosmetic and Perfumery Glass Bottle Packaging Market
Glass Packaging
Africa Glass Bottles and Containers Market
Glass Packaging
Thailand Container Glass Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
United Kingdom (UK) Glass Bottles and Containers Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Mexico Glass Packaging Market
Glass Packaging
Glass Logistics Market
Glass Packaging
United Kingdom Glass Packaging Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
Oman Container Glass Market
Glass Packaging
Saudi Arabia Pharmaceutical Glass Packaging Market
Glass Packaging
Middle East and Africa Glass Packaging Market
Glass Packaging
Kenya Container Glass Market