
 France Automotive Pneumatic Actuators Market | 2026-2036
France Automotive Pneumatic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
France Automotive Pneumatic Actuators Market Foresight
Electric vehicle powertrain integration is hardening demand among Tier-1 suppliers for precision pneumatic actuation in battery thermal management and braking systems. AUTOMAX Sar leverages its specialization in compact actuator designs for hybrid architectures. Schaeffler Vehicle Lifetimes Solutions France SAS sustains R&D intensity around electromechanical-pneumatic hybrid systems. Bosch Rexroth AG anchors its position through channel control with major OEM assembly lines in Saint-Ouen-l'Aumône.
France automotive pneumatic actuators are force-converting devices utilizing compressed air at typical operating pressures of 6-10 bar to generate linear or rotary mechanical motion, primarily serving clutch engagement, gear selection, and brake actuation functions in vehicle powertrains. Double-acting actuators dominate installed volume due to their bidirectional force capability, while electro-pneumatic technology leads growth as automakers integrate smart valve control for predictive maintenance. Rack and pinion variants occupy the premium margin pool in steering assistance applications where positional accuracy requirements exceed standard scotch yoke tolerances.
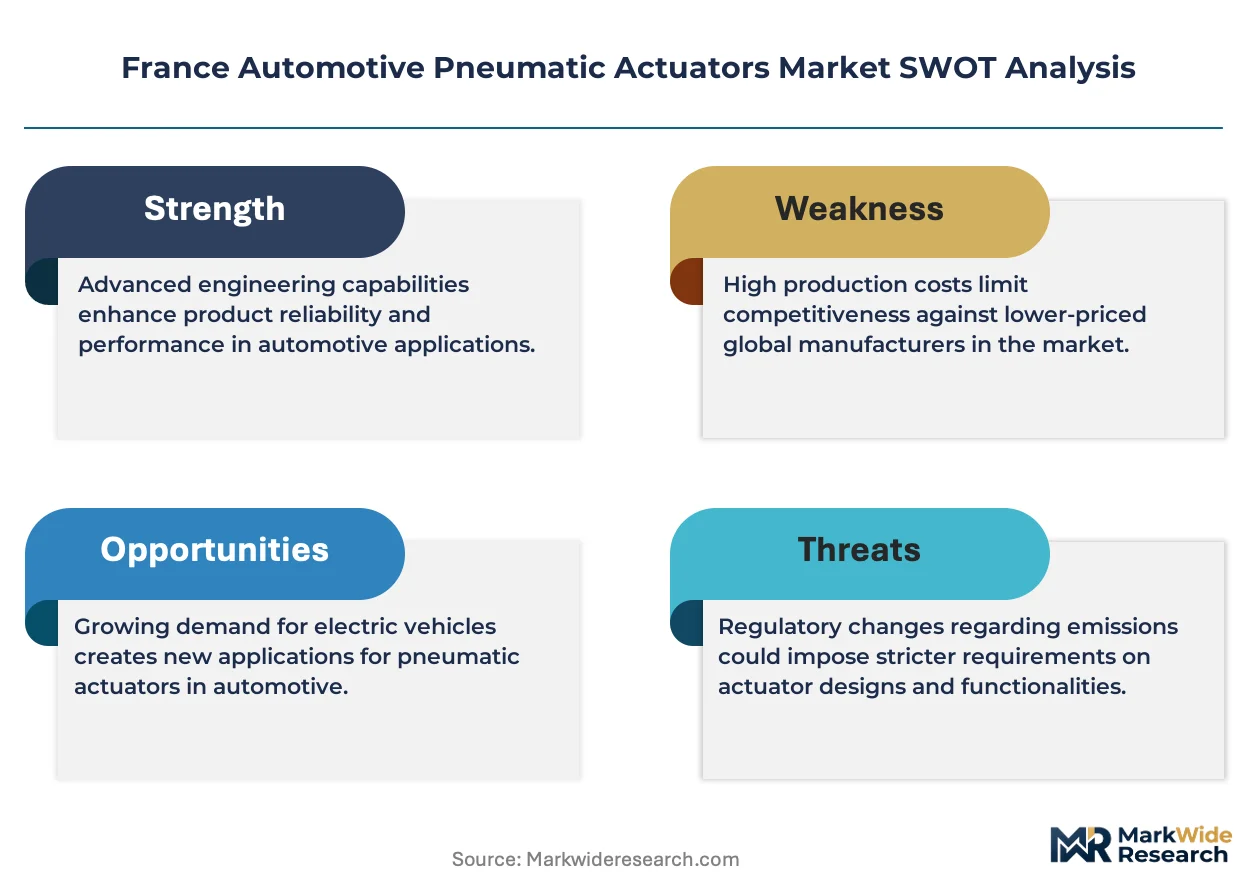
ANSM and CNIL shape France's regulatory landscape for automotive components, with EU REACH and RoHS frameworks restricting hazardous substance content in elastomer seals and lubricants used within pneumatic assemblies. The EU Green Deal's embedded carbon reporting requirements through CSRD disclosure rules are forcing Tier-1 suppliers to document lifecycle emissions across actuator supply chains. Stakeholders must monitor France's implementation timeline for Euro 7 emission standards and their ripple effects on pneumatic component specifications in internal combustion variants.
Market Dynamics
France's Loi de Transition Énergétique is compressing design cycles for pneumatic actuators as material efficiency mandates force Tier-1 suppliers to requalify elastomer seals and aluminum housings under stricter embodied carbon thresholds.
Growth Catalysts
- EU Green Deal CSRD disclosure rules:Embedded carbon reporting requirements are pulling lifecycle assessment capabilities into supplier qualification criteria, favoring actuators with documented supply chain emissions.
- Battery thermal management systems:Electric vehicle architectures require precision pneumatic actuation for coolant valve control, creating specification pull from hybrid powertrain programs.
- Île-de-France automotive cluster concentration:Proximity to Saint-Ouen-l'Aumône and Flins-sur-Seine assembly plants reduces logistics friction for just-in-sequence actuator delivery.
Market Restraints
- Aluminum alloy price volatility:Housing material costs fluctuate with LME pricing, compressing margin buffers for mid-volume actuator manufacturers serving second-tier OEMs.
- Electromechanical substitution:Servo-electric actuators are displacing pneumatic alternatives in steering assistance applications where positional feedback precision exceeds 0.1 degree tolerance.
- REACH compliance friction:ECHA substance restrictions on perfluorinated lubricants force reformulation of internal seal coatings, extending qualification timelines by 8-14 months.
Strategic Opportunities
- Auvergne-Rhône-Alpes supplier ecosystem:Lyon-Saint-Étienne manufacturing corridor offers untapped capacity for pneumatic component subassembly with lower labor cost differentials than Paris Basin.
- Predictive maintenance integration:Smart valve position sensors converging with edge computing enable condition-based actuator replacement, opening recurring revenue streams for sensor-integrated product lines.
- Euro 7 pre-compliance positioning:Anticipated emission standards for remaining internal combustion variants will tighten pneumatic exhaust valve response requirements, rewarding suppliers with pre-certified fast-actuation designs.
Industry Challenges
- Polymer compounding expertise scarcity:Formulation chemists capable of balancing compression set resistance with REACH-compliant plasticizers command premium compensation in Greater Paris labor markets.
- Electro-pneumatic integration complexity:Hybrid actuator architectures require simultaneous competence in pneumatic mechanics, solenoid control, and embedded firmware—capabilities rarely housed within single engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Automotive Pneumatic Actuators Market |
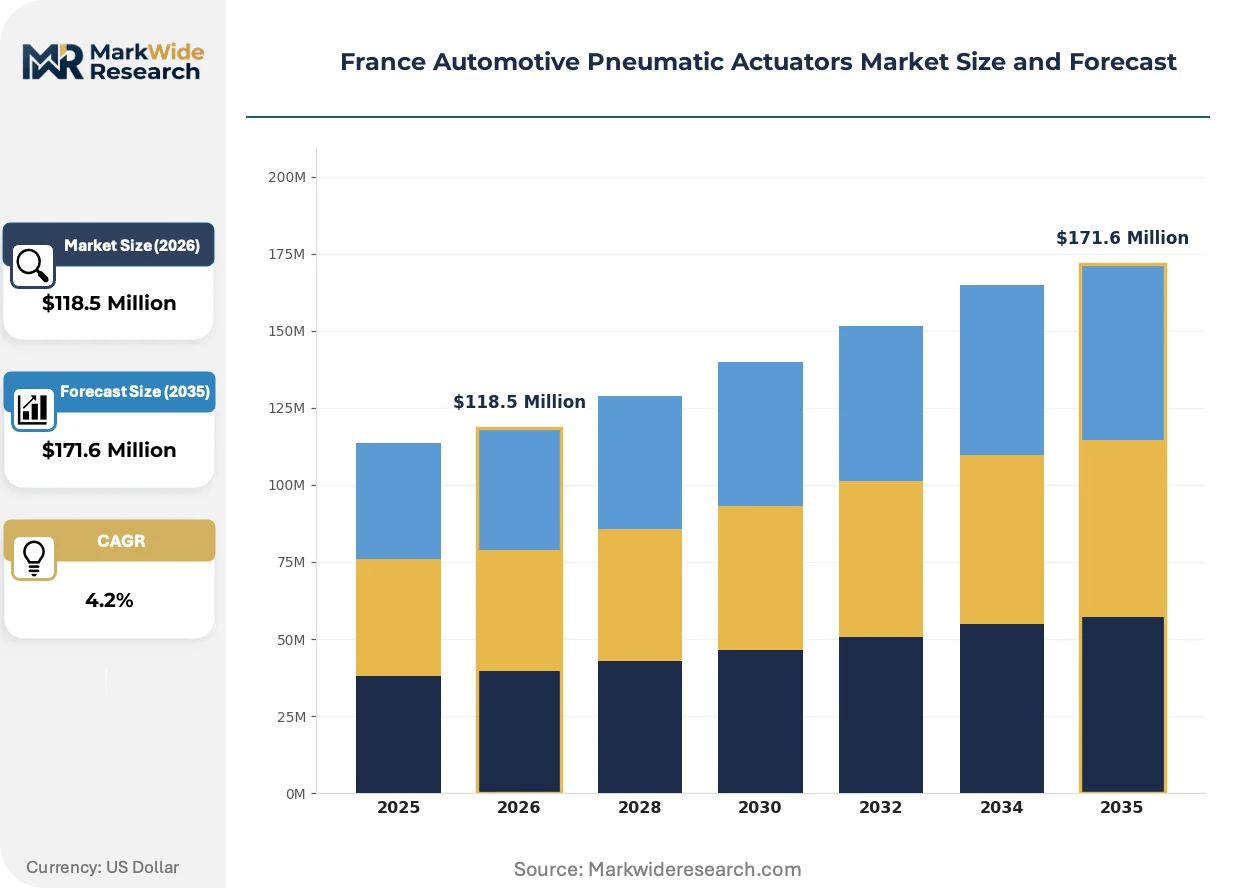
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $171.6 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Acting, Double-Acting, Rack and Pinion, Scotch Yoke Technology: Electro-Pneumatic, Pneumatic-Hydraulic, Direct Acting, Pilot Operated Application: Engine Control, Brake Systems, Suspension Systems, Transmission Systems End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Cai Actuators, Schaeffler Vehicle Lifetimes Solutions France SAS, AUTOMAX Sar, FTE automotive France, Nexteer Automotive France SAS, AUTEM Industrial Automation, Mubea France SaSu, Bosch Rexroth AG, Automatic Valve Réalisation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Automotive Pneumatic Actuators Market Shifts & Advancements
Smart pneumatics and predictive maintenance architectures are redefining value capture in French automotive actuator supply chains, compressing traditional hardware margins while opening software-enabled service revenue pools.
Electro-pneumatic hybrid actuators is unifying position feedback accuracy with pneumatic force density in a single housing, addressing battery thermal management applications where pure electric solutions overheat. Renault Group's ElectriCity manufacturing complex in northern France has adopted these hybrids for coolant routing valves. The technology is unifying previously separate pneumatic and electronic supplier tiers into integrated module competitions.
France's transposition of EU CSRD rules through the Autorité des Marchés Financiers is forcing Tier-1 suppliers to deploy product-level carbon footprinting tools by 2026. Pneumatic actuator manufacturers must now document Scope 3 emissions from aluminum smelting and seal polymer production. Suppliers serving Stellantis and Renault assembly lines are responding by qualifying low-carbon aluminum from Rio Tinto's Elysis joint venture.
Fleet operators and leasing companies are unbundling actuator maintenance from vehicle purchase contracts, creating direct procurement relationships with component suppliers. This disintermediation bypasses traditional OEM parts distribution channels in favor of outcome-based availability guarantees. The pattern is most visible in Île-de-France commercial vehicle fleets where uptime penalties exceed component replacement costs.
France Automotive Pneumatic Actuators Market Segmentation
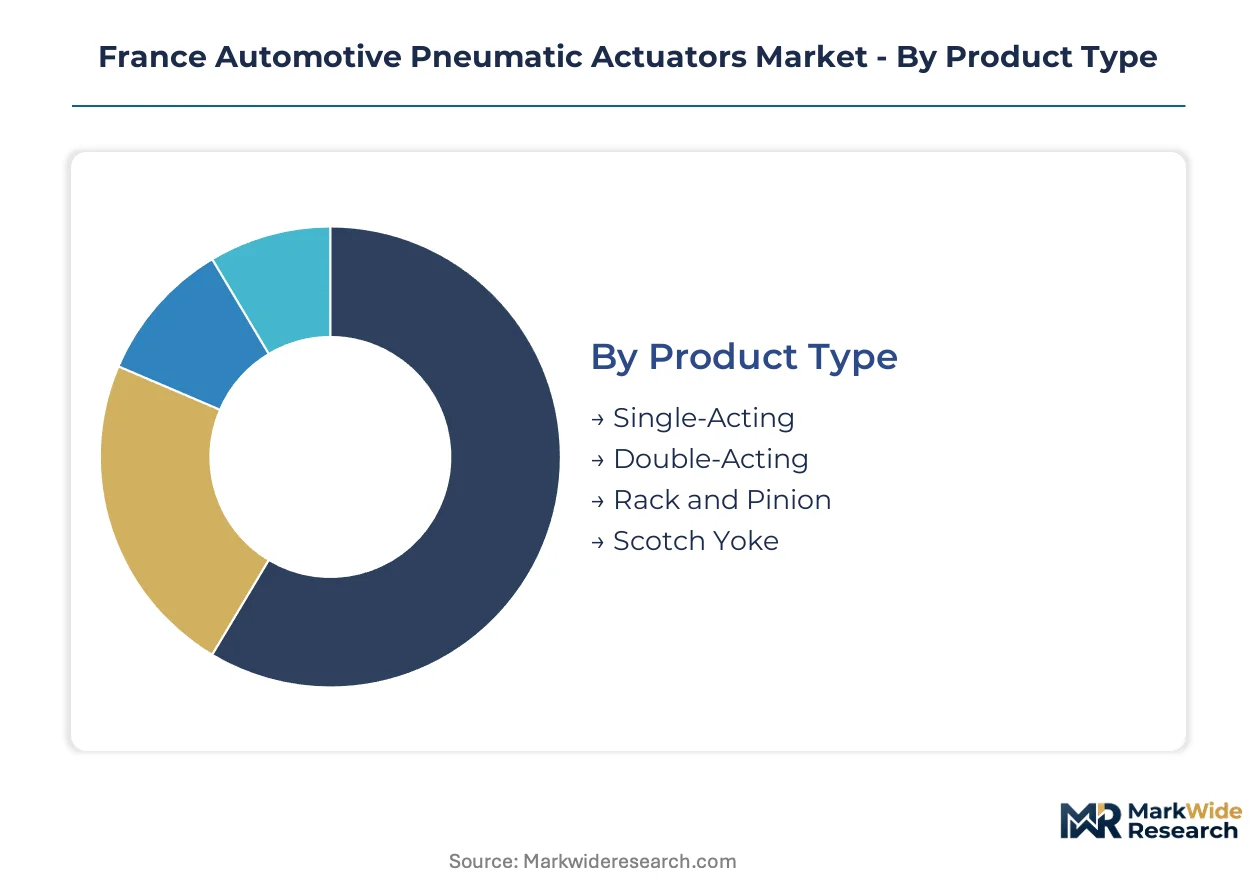
Segmentation in France's automotive pneumatic actuators market reveals how Tier-1 suppliers align product architectures with powertrain electrification timelines. Each dimension—product type, technology, application, and end user—exposes distinct margin structures and qualification barriers that reshape competitive positioning across the Île-de-France cluster and beyond.
Product Type:
Standardization dominates high-volume clutch and brake applications, while customization concentrates in steering assistance where positional tolerances tighten.
- Double-Acting:Bidirectional force capability suits gear selection and clutch engagement in hybrid powertrains. Demand concentrates among Stellantis and Renault transmission programs where actuator cycling exceeds 10 million operations over vehicle lifetime.
- Rack and Pinion:Precision rotary-to-linear conversion achieves positional accuracy below 0.05 degrees for steering assistance. Premium margins attach to variants serving Renault's ElectriCity complex where electro-pneumatic hybrids displace pure electric alternatives in thermal-sensitive battery coolant valves.
- Single-Acting:Spring-return designs serve parking brake and secondary clutch release functions with simpler control logic and lower per-unit cost.
- Scotch Yoke:Torque-efficient rotary output suits throttle body and wastegate control in remaining internal combustion variants, though Euro 7 pre-compliance is compressing specification windows.
Most installed capacity flows through Double-Acting designs. Expansion is steepest in Rack and Pinion as steering electrification demands tighter feedback integration.
Technology:
Cost tier stratification separates commodity pneumatic mechanics from sensor-integrated systems commanding software-enabled service revenues.
- Electro-Pneumatic:Solenoid valve integration with position feedback enables predictive maintenance architectures. AUTOMAX Sar and Schaeffler Vehicle Lifetimes Solutions France SAS compete here for battery thermal management contracts where smart valve control reduces warranty exposure.
- Pneumatic-Hydraulic:Force multiplication for heavy commercial vehicle brake systems. Auvergne-Rhône-Alpes suppliers exploit lower labor cost differentials against Paris Basin competition for this torque-dense segment.
- Direct Acting:Simplest architecture with fastest response times serves high-cycle clutch applications where control system complexity must minimize.
- Pilot Operated:Low-power signal actuation of high-flow valves suits engine control modules where electrical load reduction extends to every subsystem.
Volume concentrates in Direct Acting for legacy internal combustion programs. Value expansion is sharpest in Electro-Pneumatic as CSRD disclosure rules pull lifecycle assessment capabilities into supplier qualification criteria.
Application:
Application maturity varies with electrification penetration—brake and transmission systems retain pneumatic content longest while engine control faces displacement.
- Brake Systems:Pneumatic actuation persists in parking brake and emergency brake functions where fail-safe mechanical backup requirements outlast full electrification timelines. Bosch Rexroth AG anchors supply through Saint-Ouen-l'Aumône assembly line proximity.
- Transmission Systems:Dual-clutch and automated manual architectures sustain demand for precision clutch engagement actuators. The Île-de-France cluster's just-in-sequence delivery requirements favor suppliers with sub-50km logistics radius to Flins-sur-Seine.
- Engine Control:Throttle body and variable valve timing actuators face volume pressure as hybridization reduces internal combustion operating hours per vehicle.
- Suspension Systems:Pneumatic spring and damping control occupies niche premium vehicle segments where ride height adjustability justifies cost premium over electromechanical alternatives.
Transmission Systems carry the largest installed base. Brake Systems are gaining share fastest as safety-critical redundancy requirements extend pneumatic content into full electric architectures.
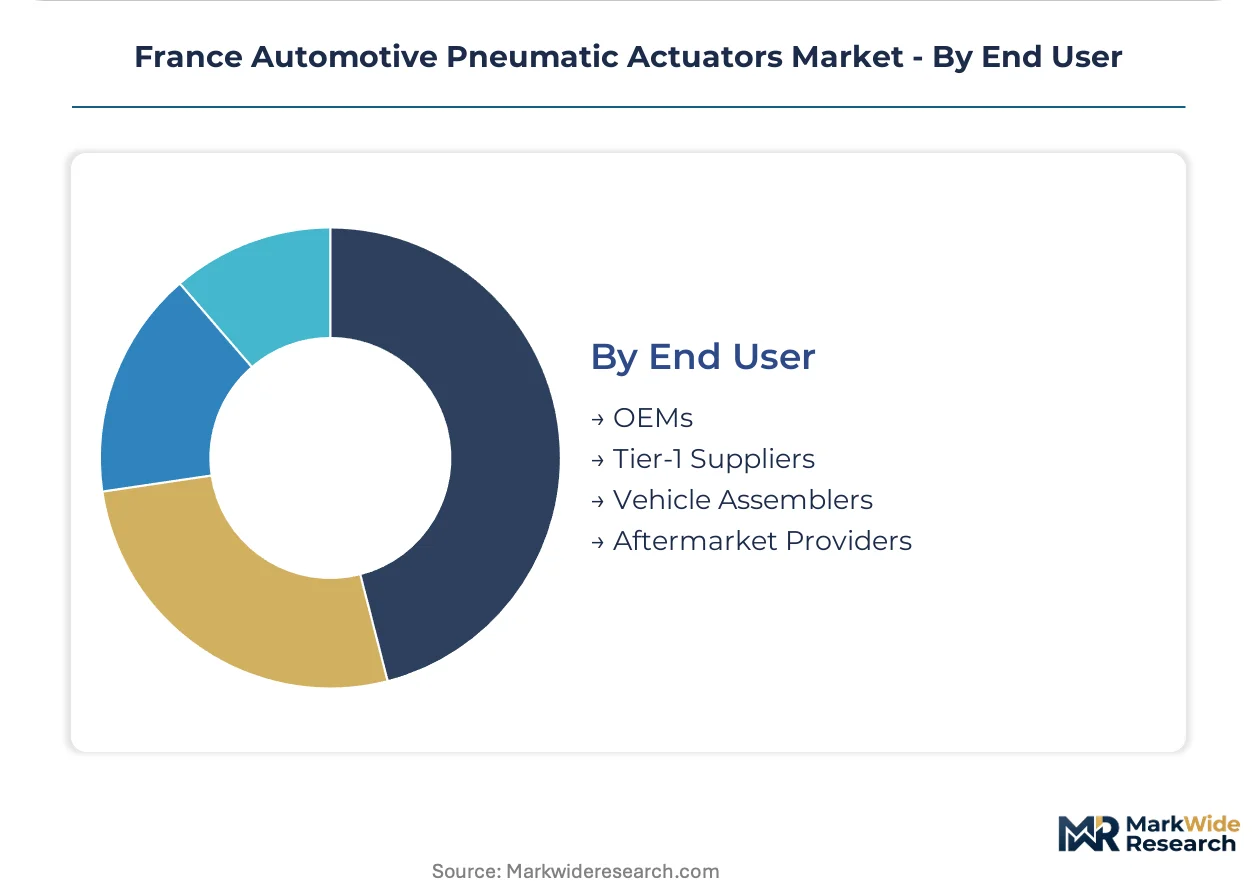
End User:
Customer type determines contract structure—OEM direct relationships demand systems integration competence while aftermarket procurement favors inventory velocity and interchangeability.
- Tier-1 Suppliers:Module-level integration responsibility for clutch, brake, and thermal management systems. ANSM and CNIL compliance documentation requirements concentrate procurement authority with suppliers possessing dedicated regulatory affairs functions in Greater Paris.
- OEMs:Direct actuator specification for proprietary powertrain architectures, particularly in Renault Group's vertical integration of ElectriCity manufacturing.
- Vehicle Assemblers:Contract manufacturing arrangements where actuator sourcing follows Tier-1 module supplier selection.
- Aftermarket Providers:Fleet operator disintermediation is creating direct procurement relationships for outcome-based availability guarantees, bypassing traditional OEM parts distribution in Île-de-France commercial vehicle segments.
Tier-1 Suppliers channel the majority of volume. Aftermarket Providers are expanding most quickly as uptime penalty clauses in leasing contracts shift maintenance risk to component suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Île-de-France automotive cluster surrounding Paris concentrates France's pneumatic actuator demand through proximity to Saint-Ouen-l'Aumône and Flins-sur-Seine assembly plants. Regional specialization varies across French manufacturing corridors as electrification timelines and supplier ecosystems diverge.
Île-de-France
Renault Group's ElectriCity complex and Stellantis assembly lines drive precision actuator demand for battery thermal management and dual-clutch transmission systems. ANSM compliance documentation requirements concentrate procurement authority with suppliers maintaining dedicated regulatory affairs functions in Greater Paris. Saint-Ouen-l'Aumône hosts Bosch Rexroth AG's channel control operations for just-in-sequence delivery to major OEM lines.
Auvergne-Rhône-Alpes
The Lyon-Saint-Étienne manufacturing corridor offers untapped subassembly capacity with labor cost differentials below Paris Basin levels. REACH compliance friction on perfluorinated lubricants extends qualification timelines, favoring established suppliers with existing ECHA substance authorization pathways. Local polymer compounding expertise supports seal formulation for pneumatic-hydraulic heavy commercial vehicle brake systems.
Hauts-de-France
Renault's Douai and Maubeuge plants anchor demand for clutch engagement actuators in hybrid powertrain programs. Euro 7 pre-compliance positioning rewards suppliers with fast-actuation designs certified for remaining internal combustion variants. The region's historical automotive density sustains Tier-1 supplier engineering presence despite electrification-driven employment shifts.
Provence-Alpes-Côte d'Azur
Specialized actuator testing and validation services cluster around Sophia Antipolis technology park. CNIL data governance requirements shape smart pneumatics development as predictive maintenance architectures integrate edge computing and position sensors. The region's aerospace heritage transfers precision motion control competence to automotive electro-pneumatic hybrid development.
France Automotive Pneumatic Actuators Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers consolidate electromechanical-pneumatic hybrid capabilities. The vendor base organizes around three tiers: integrated module suppliers with OEM direct relationships, specialized actuator fabricators serving Tier-1 transmission programs, and regional subassembly contractors. Two strategic archetypes predominate: precision motion specialists capturing steering assistance margins, and scale-driven manufacturers anchoring high-volume clutch and brake applications. M&A activity and technology licensing agreements represent the primary competitive vectors as electro-pneumatic integration complexity forces capability consolidation.
Among France-based specialists, Schaeffler Vehicle Lifetimes Solutions France SAS and AUTOMAX Sar exemplify the precision-motion archetype, occupying positions in electromechanical-pneumatic hybrid development. Bosch Rexroth AG anchors the scale-driven tier through its Saint-Ouen-l'Aumône proximity to major OEM assembly lines. These three entities represent distinct competitive positions: hybrid system integration, compact actuator specialization, and channel-controlled volume supply respectively.
| Leading Market Players |
|---|
| Cai Actuators |
| Schaeffler Vehicle Lifetimes Solutions France SAS |
| AUTOMAX Sar |
| FTE automotive France |
| Nexteer Automotive France SAS |
| AUTEM Industrial Automation |
| Mubea France SaSu |
| Bosch Rexroth AG |
| Automatic Valve Réalisation |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between ANSM-documented Tier-1 suppliers and undifferentiated subassembly contractors manifests in both margin capture and logistics configuration across the Île-de-France cluster. Premium pricing attaches to electro-pneumatic hybrids with embedded carbon disclosure under CSRD rules, while commodity pneumatic mechanics compete on aluminum input cost and Saint-Ouen-l'Aumône delivery radius.
Pricing Analysis
Aluminum alloy pass-through from LME pricing volatility compresses margin buffers for mid-volume manufacturers serving second-tier OEMs. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with ANSM compliance documentation and REACH-authorized seal formulations commanding spreads against generic alternatives. Cost compression in standard-tier clutch actuators intensifies because electromechanical substitution pressures pneumatic alternatives in steering assistance. Fleet operators in Île-de-France commercial segments exhibit highest price sensitivity where uptime penalty clauses shift maintenance risk to suppliers, while OEM direct specifications show lowest sensitivity due to systems integration requirements.
Supply Chain Analysis
Remanufacturing flows for rack and pinion steering actuators create reverse logistics value recovery from Sophia Antipolis validation facilities back to Lyon-Saint-Étienne subassembly corridors. Geographic supply concentration centers on Germany for precision valve components, China for aluminum alloy feedstock, and domestic Auvergne-Rhône-Alpes for polymer compounding. Raw material dependencies rest on low-carbon aluminum from Rio Tinto's Elysis joint venture, perfluorinated lubricant alternatives under ECHA restriction, and REACH-compliant elastomer formulations. Single-source vulnerability concentrates in smart valve position sensors where edge computing integration requires specialized firmware competence. Distribution runs through just-in-sequence channels anchored at Saint-Ouen-l'Aumône for Renault and Stellantis assembly line proximity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's automotive pneumatic actuators market functions as a geographic-arbitrage play where Auvergne-Rhône-Alpes labor cost differentials against Paris Basin levels enable margin recovery for suppliers serving heavy commercial vehicle brake systems.
For Market Incumbents: Lock in channel control through captive supply of electro-pneumatic hybrid modules to Renault Group's ElectriCity complex, insulating against servo-electric displacement in battery thermal management. Deepen backward integration into low-carbon aluminum qualification from Elysis joint venture feedstock, securing CSRD disclosure compliance before Tier-1 procurement mandates harden. Prioritize polymer compounding expertise retention in Greater Paris labor markets where formulation chemist scarcity threatens seal development timelines. For New Entrants and Emerging Players: EU Green Deal CSRD disclosure rules in France open a window for specialized lifecycle assessment service providers to embed carbon footprinting tools into actuator supply chains. Target the Auvergne-Rhône-Alpes manufacturing corridor where established suppliers face REACH compliance friction extending qualification timelines, creating white-space for pre-authorized seal formulations. Pursue direct procurement relationships with Île-de-France fleet operators seeking outcome-based availability guarantees bypassing traditional OEM parts distribution. For Investors and Strategic Acquirers: Consolidation pressure builds where electro-pneumatic integration complexity requires simultaneous competence in pneumatic mechanics, solenoid control, and embedded firmware rarely housed within single engineering teams. Long-term viability over the projection horizon favors acquisition targets with pre-certified fast-actuation designs for Euro 7 pre-compliance positioning in remaining internal combustion variants. Monitor Stellantis and Renault procurement mandate timelines for embedded carbon disclosure as the inflection signal for supplier qualification barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| CSRD Compliance Integration | Embedded carbon disclosure capabilities secure Tier-1 supplier qualification under EU Green Deal mandates. |
| Auvergne-Rhône-Alpes Capacity Expansion | Labor cost differentials against Paris Basin enable margin recovery in pneumatic-hydraulic heavy commercial vehicle systems. |
| Electro-Pneumatic Hybrid Development | Position feedback accuracy with pneumatic force density addresses battery thermal management where pure electric solutions overheat. |
| Predictive Maintenance Sensor Integration | Smart valve position sensors with edge computing open recurring revenue streams through condition-based replacement contracts. |
| Low-Carbon Aluminum Supply Agreement | Rio Tinto Elysis joint venture feedstock secures Scope 3 emissions documentation for Stellantis and Renault assembly lines. |
Research Methodology
Multiple input streams — primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, and aftermarket distributors; secondary validation through vehicle production databases, IHS Markit registration data, and SEC filings from listed automotive component manufacturers; plus customs records for aluminum alloy trade flows — were reconciled through bottom-up and top-down triangulation. Stakeholder engagement spanned regulatory affairs specialists at ANSM and CNIL, polymer compounding chemists in Greater Paris, and logistics coordinators at Saint-Ouen-l'Aumône assembly line facilities.
Data-stream reconciliation across product type, technology, application, and end user segmentation dimensions informed volume and value outputs over the projection horizon. CAGRs were derived from modeled interactions between electrification penetration timelines, Euro 7 pre-compliance positioning, and CSRD disclosure rule implementation. Industry-specific forecast inputs included hybrid powertrain program ramp schedules from Renault Group's ElectriCity complex and Stellantis transmission sourcing patterns.
Revisions become necessary when aluminum alloy price volatility exceeds historical bands, ECHA substance restrictions expand beyond perfluorinated lubricants, or electromechanical substitution accelerates in steering assistance applications. Forecasts reflect assumptions around REACH compliance timeline stability and Tier-1 supplier consolidation patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Timing Gear Market
Automotive Parts
Automotive Cooling Fan Market
Automotive Parts
Automotive Parts Aluminum Die Casting Market
Automotive Parts
Singapore Automotive Engine Oils Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
EV Reduction Gears Market
Automotive Parts
VVT Actuators Market
Automotive Parts
Undercarriage Systems Market
Automotive Parts
Global Car Engine Oil Market
Automotive Parts
India Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Morocco Passenger Vehicles Lubricants Market
Automotive Parts
Cabin Air Filter Housing Replacement Parts Market
Automotive Parts
North America Automotive Foams Market
Automotive Parts
Automotive Carbon Canister Market
Automotive Parts
Electromagnetic Clutches Market